
 Global Intranet Software Market | 2026-2036
Global Intranet Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intranet Software Market Foresight
Mid-market professional services firms are unwinding legacy SharePoint deployments in favor of modern employee experience platforms. Microsoft leverages its Entra identity fabric and Copilot integration to sustain dominance across enterprise accounts. Simpplr anchors its position through AI-powered content personalization that reduces internal communications overhead. Unily competes on global delivery capability, operating localized data residency nodes across fifteen countries to satisfy regional compliance mandates.
Intranet software comprises browser-based platforms that integrate content management systems, real-time communication protocols, and identity-aware access controls to centralize organizational knowledge and streamline workforce coordination. These systems typically deploy via REST APIs and SAML authentication to connect with HRIS, CRM, and productivity suites, serving the commercial purpose of reducing information silos and accelerating decision velocity. Cloud-Based deployment leads in net new bookings as CIOs prioritize elastic scaling and reduced data center capital, while Collaboration Tools within the Solution dimension captures expanding margin pools as vendors bundle synchronous editing, video conferencing, and project workspaces into unified licenses. Large Enterprises remain the anchor Customer Type segment, though Small & Medium Businesses represent the fastest-growing cohort as template-driven implementations lower implementation barriers.
The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements that reshape how European vendors architect recommendation engines and search ranking within intranet platforms. In the United States, HIPAA governs clinical intranet deployments for healthcare providers, while the SEC's cybersecurity disclosure rules pressure publicly traded adopters to document internal communication audit trails. Stakeholders must monitor how NIS2 implementation across EU member states will expand liability for platform operators managing critical infrastructure employee portals.
Market Dynamics
Consolidation of fragmented digital workplace tools is compressing procurement cycles and forcing vendors to bundle identity management, synchronous collaboration, and AI-powered search into unified platforms that displace standalone point solutions.
Growth Catalysts
- GDPR and EU AI Act:European privacy mandates accelerate replacement of legacy on-premise systems with cloud-native architectures that embed algorithmic transparency and data minimization by design.
- Healthcare workflow unification:Clinical and administrative staff demand single-pane access to EHR integration, shift scheduling, and HIPAA-compliant messaging within hospital intranets.
- Elastic cloud infrastructure:CIOs prioritize SaaS deployments that eliminate data center capital expenditure and enable rapid scaling during M&A integration or seasonal workforce fluctuations.
Market Restraints
- Identity fabric complexity:SAML and SCIM protocol fragmentation across HRIS, CRM, and productivity suites inflates integration costs and extends implementation timelines.
- Regional data residency mandates:Germany, France, and Switzerland require localized server nodes, forcing vendors to maintain redundant infrastructure that compresses gross margins.
- Generative AI hallucination risk:Enterprise legal teams block AI-powered intranet search until vendors demonstrate citation traceability and source attribution.
Strategic Opportunities
- Small and medium business template market:Pre-configured industry vertical packages reduce implementation from months to weeks, opening addressable market beyond Fortune 500 accounts.
- Frontline worker mobile access:Manufacturing and retail operations seek smartphone-optimized intranets that reach deskless employees previously excluded from digital workplace investments.
- CSRD disclosure automation:European sustainability reporting mandates create demand for intranet modules that aggregate ESG data and streamline stakeholder communication workflows.
Industry Challenges
- Legacy SharePoint migration complexity:Decades of document sprawl and custom workflows resist automated porting, requiring expensive manual curation and change management.
- AI/ML talent scarcity:Vendors struggle to hire engineers capable of building recommendation engines that satisfy both performance benchmarks and explainability requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intranet Software Market |
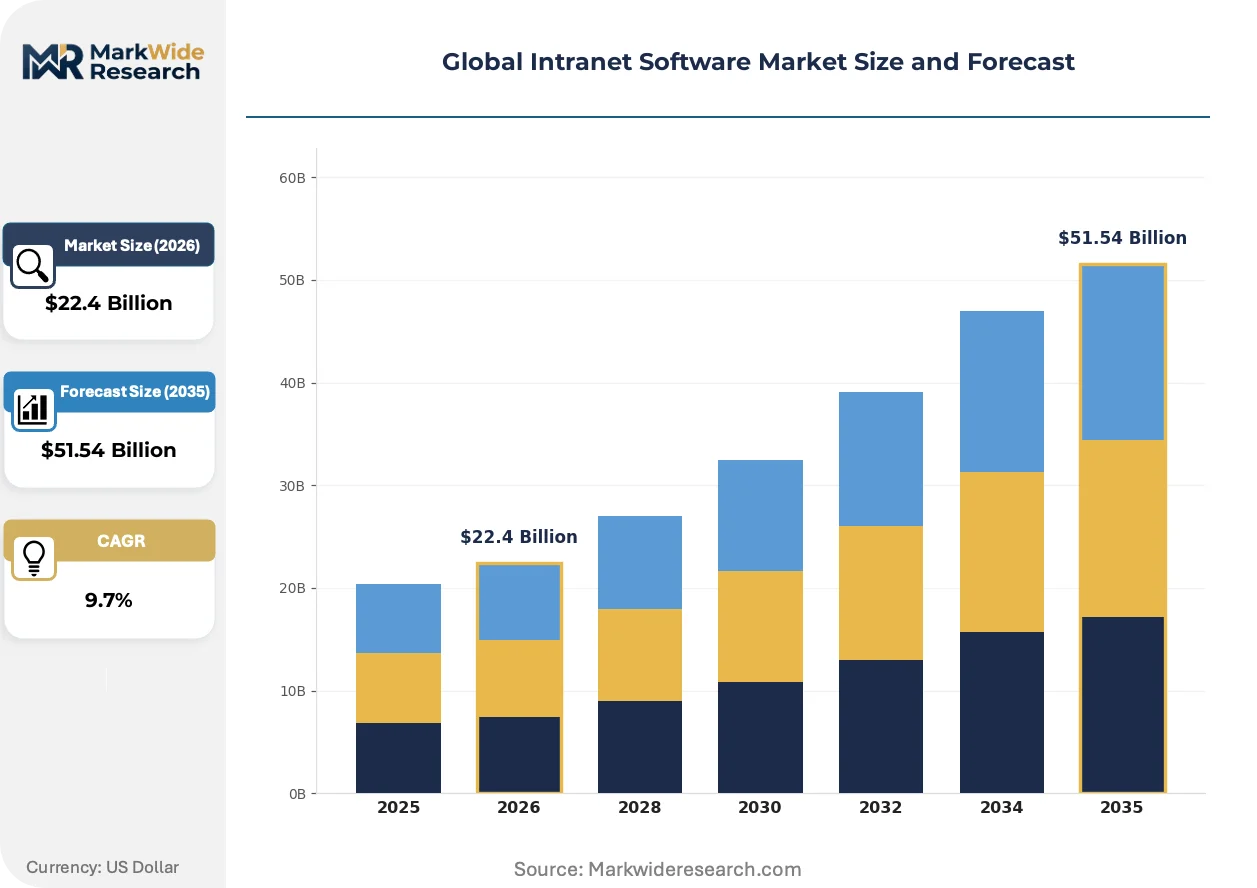
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $51.54 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Managed Services Solution: Content Management, Collaboration Tools, Communication Platforms, Workflow Automation, Document Management Use Case: Employee Engagement, Knowledge Sharing, Internal Communication, Process Optimization, Project Management Customer Type: Large Enterprises, Small & Medium Businesses, Non-Profit Organizations, Government Agencies, Educational Institutions |
| Companies Covered | Microsoft, Simpplr, Unily, Workvivo, Staffbase, LumApps, Interact, Claromentis, ThoughtFarmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intranet Software Market Shifts & Advancements
Agentic AI architectures are rewiring how knowledge workers interact with organizational information, shifting from passive document repositories toward systems that anticipate needs and execute multi-step workflows autonomously.
Retrieval-augmented generation is supplanting conventional keyword search in enterprise intranets. Natural language interfaces parse intent across fragmented content silos. Healthcare and professional services firms pilot these systems for clinical protocol lookup and client matter research. The technology is compressing time-to-information and reducing dependency on manual tagging taxonomies.
The EU AI Act's risk classification framework is reshaping vendor development roadmaps. High-risk applications—those affecting employment decisions or access to essential services—face mandatory conformity assessments and CE marking. Platform providers serving European multinational corporations are accelerating investment in algorithmic audit trails and human-in-the-loop override mechanisms to preempt regulatory blockage.
Subscription bundling is consolidating previously separate procurement decisions. CIOs negotiate single contracts covering intranet software, identity management, video conferencing, and project workspaces. This pattern concentrates spending power with integrated platform vendors and marginalizes standalone collaboration tool vendors, particularly visible in United States enterprise accounts where IT consolidation mandates have accelerated post-2022.
Global Intranet Software Market Segmentation
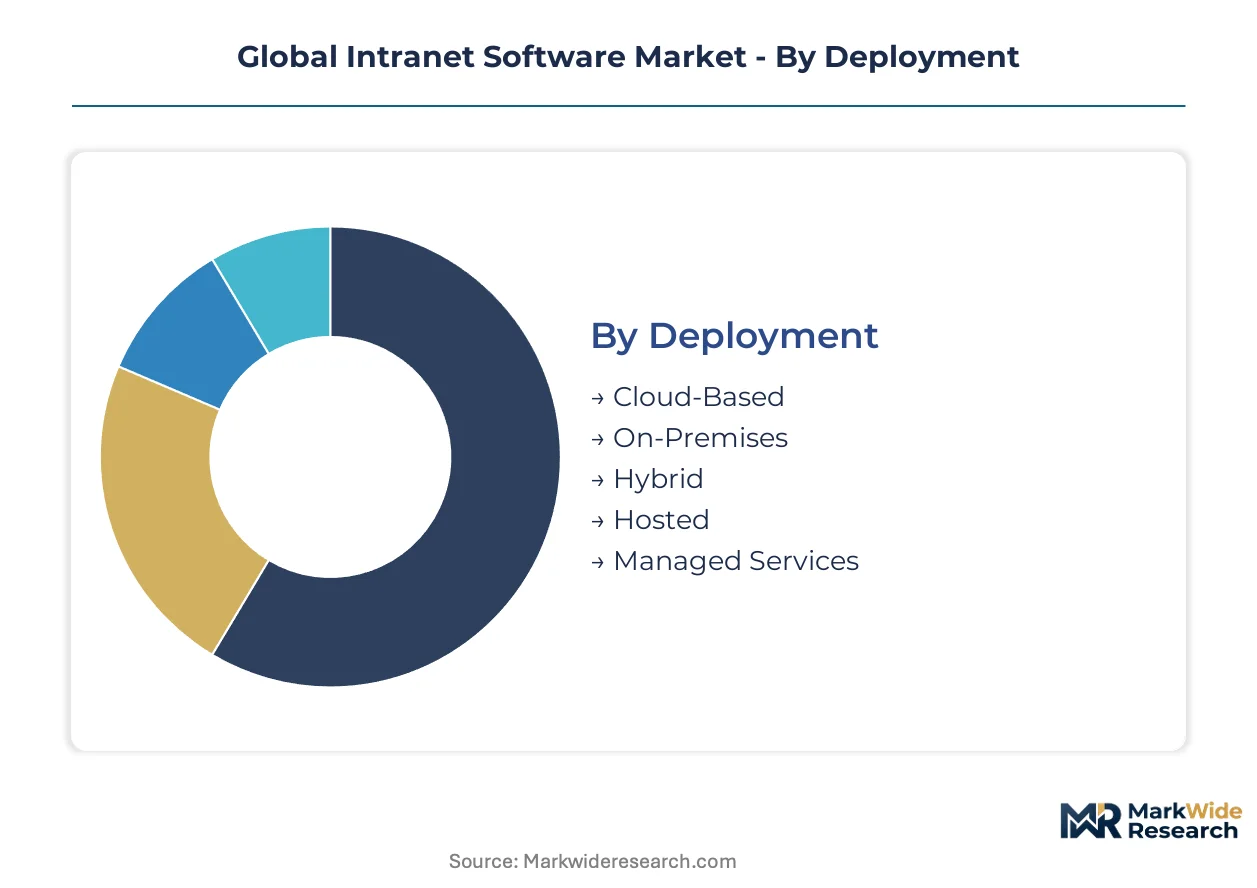
Intranet software vendors architect go-to-market strategies around deployment flexibility and solution bundling. Procurement patterns diverge sharply between CIOs prioritizing elastic infrastructure and compliance officers mandating data sovereignty controls.
Deployment:
Channel economics favor Cloud-Based and Hybrid deployments through direct vendor sales and systems integrators, while On-Premises and Managed Services flow through regional value-added resellers with compliance expertise.
- Cloud-Based:Multi-tenant SaaS architectures deploy via REST APIs with SAML authentication. United States enterprises consolidate fragmented digital workplace tools here, prioritizing reduced data center capital and rapid M&A integration scaling.
- Hybrid:Split architectures keep sensitive HR and financial data on-premises while exposing collaboration layers to public cloud. German and French manufacturers favor this model to satisfy works council agreements and GDPR data minimization mandates.
- On-Premises:Single-tenant installations in customer data centers serve defense contractors and Swiss banking regulators demanding air-gapped environments.
- Hosted:Vendor-managed dedicated instances provide compliance isolation without customer infrastructure burden, popular among mid-market healthcare providers navigating HIPAA technical safeguards.
- Managed Services:Fully outsourced operations including patching, backup, and tier-1 support, procured by Australian resource firms with limited internal IT capacity.
By volume, Cloud-Based leads. By growth pace, Hybrid is expanding most quickly.
Solution:
Margin concentration follows bundling intensity—vendors capture premium pricing when Collaboration Tools and Workflow Automation integrate into unified licenses rather than standalone procurement.
- Collaboration Tools:Synchronous editing, video conferencing, and project workspaces delivered through browser-based protocols. Healthcare organizations in the United States accelerate adoption here to unify clinical and administrative workflows within single-pane hospital intranets.
- Workflow Automation:Low-code process engines connecting HRIS, CRM, and productivity suites via SCIM and REST APIs. Professional services firms in the United Kingdom deploy these to compress client onboarding cycles and reduce manual handoffs.
- Content Management:Structured repositories with version control and metadata taxonomies, foundational for knowledge-intensive legal and consulting practices.
- Communication Platforms:Real-time messaging, executive broadcasting, and crisis alert systems reaching deskless manufacturing and retail workforces.
- Document Management:Lifecycle governance from creation through archival, critical for SEC-registered firms documenting audit trails under cybersecurity disclosure rules.
By installed base, Content Management dominates. By expansion trajectory, Workflow Automation is climbing the fastest.
Use Case:
Application depth determines pricing tier—Employee Engagement and Knowledge Sharing command standard SaaS rates while Process Optimization and Project Management unlock enterprise-wide platform commitments.
- Employee Engagement:Pulse surveys, recognition systems, and cultural analytics targeting retention metrics. United States mid-market professional services firms invest here to unwind legacy SharePoint deployments and reduce internal communications overhead.
- Process Optimization:Lean methodology digitization and Six Sigma workflow mapping. Japanese automotive suppliers embed these modules to synchronize just-in-time production schedules across supplier portals.
- Knowledge Sharing:Expert directories, wikis, and best-practice libraries preserving institutional memory during workforce transitions.
- Internal Communication:Leadership cascades, town hall streaming, and departmental newsletters reaching distributed workforces.
- Project Management:Gantt visualization, resource allocation, and milestone tracking integrated with external client collaboration spaces.
By deployment frequency, Internal Communication leads. By strategic priority, Process Optimization is gaining share fastest.
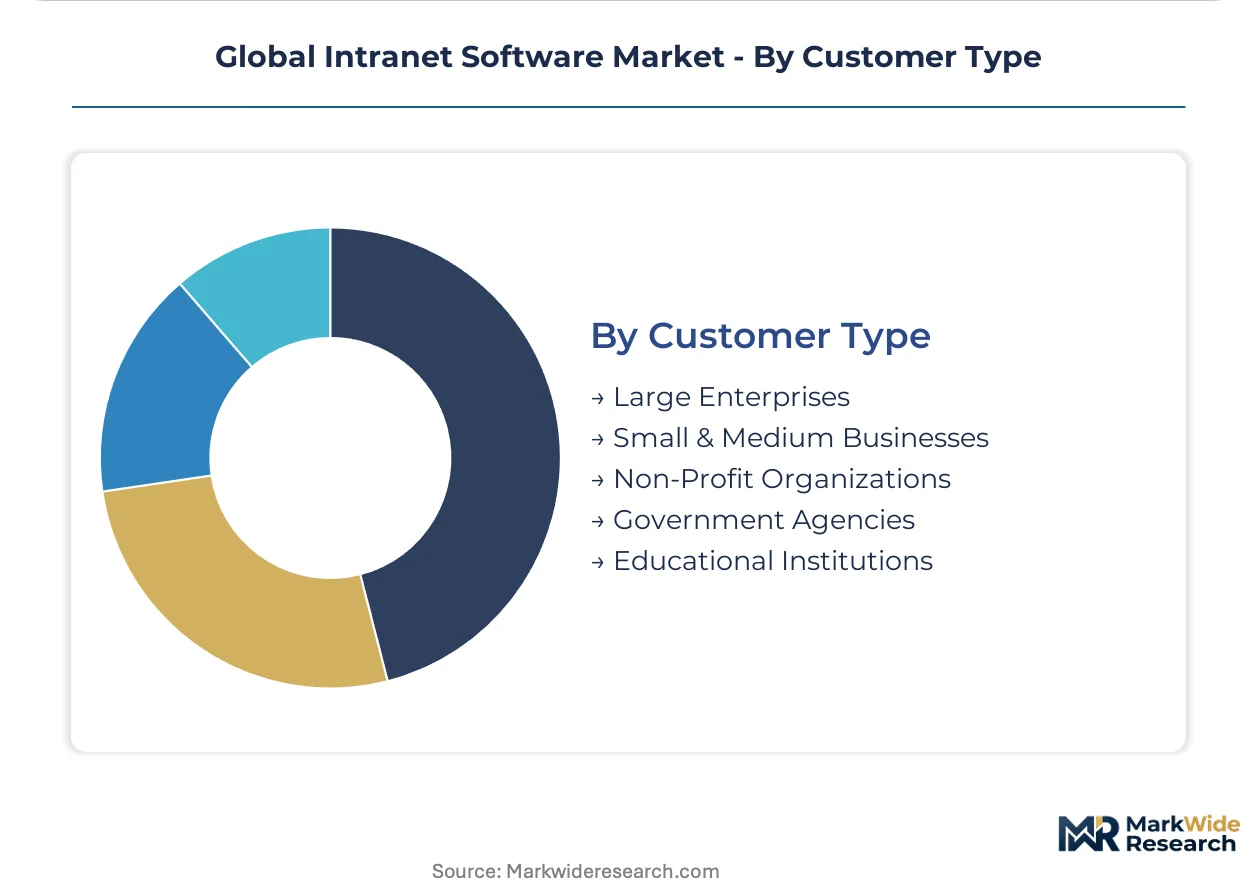
Customer Type:
Cost-to-serve ratios separate segments—Large Enterprises absorb complex implementation services while Small & Medium Businesses drive template standardization and self-service onboarding economics.
- Large Enterprises:Global deployments across 10,000+ seats with multi-language, multi-currency, and regional data residency requirements. EU-based multinationals here face EU AI Act algorithmic transparency mandates for high-risk employment decision applications.
- Small & Medium Businesses:Rapid template-driven implementations reducing deployment from months to weeks. These organizations represent the steepest expansion trajectory as pre-configured industry vertical packages lower adoption barriers.
- Government Agencies:FedRAMP and comparable national security certifications required, with procurement through formal RFP processes.
- Educational Institutions:Semester-based licensing aligned to academic calendars, with FERPA compliance for student record integration.
- Non-Profit Organizations:Discounted or donated licensing programs, often with volunteer coordination and donor management modules.
By revenue concentration, Large Enterprises anchor the market. By growth velocity, Small & Medium Businesses outpace all other segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investment concentrates in the United States, Germany, and United Kingdom, where enterprise IT consolidation and regulatory pressure are accelerating replacement cycles. Vendor data center footprints and compliance certifications determine competitive access across these markets.
United States
Healthcare systems and financial services drive SaaS intranet procurement, seeking HIPAA-compliant platforms that unify clinical workflows. The SEC's cybersecurity disclosure rules pressure publicly traded firms to document internal communication audit trails. Boston and New York metro areas host dense clusters of professional services firms unwinding legacy SharePoint deployments.
Germany
Manufacturing conglomerates and automotive suppliers favor hybrid architectures to satisfy works council agreements on data residency. GDPR and the EU AI Act mandate algorithmic transparency for employment-related intranet applications. Industrial clusters in Bavaria and Baden-Württemberg pilot AI-powered knowledge management for engineering documentation.
United Kingdom
Professional services firms in London deploy workflow automation to compress client onboarding cycles. Post-Brexit data protection frameworks maintain alignment with GDPR while adding UK-specific processing requirements. The Thames Valley corridor concentrates mid-market legal and consulting practices adopting template-driven intranet implementations.
France
Public sector and defense contractors require air-gapped or hosted deployments under national security guidelines. CNIL enforcement of data minimization principles shapes vendor product roadmaps. The Île-de-France region anchors demand from multinational headquarters consolidating European digital workplace tools.
Japan
Automotive and electronics manufacturers embed intranet modules for supplier portal coordination and just-in-time production scheduling. METI guidelines on operational technology security influence platform selection for industrial deployments. The Nagoya and Osaka industrial corridors drive process optimization use cases.
Global Intranet Software Market Competitive Landscape
Concentration sits with integrated platform vendors bundling identity, collaboration, and AI search into unified licenses. The vendor landscape tiers between hyperscale cloud providers, specialized employee experience platforms, and regional compliance-focused specialists. Two strategic archetypes dominate: horizontal suite extenders leveraging existing productivity fabric, and vertical-focused challengers competing on implementation speed and frontline worker reach. Competitive moves center on M&A to fill capability gaps and geographic expansion to satisfy data residency mandates.
Among the horizontal suite extenders, Microsoft anchors the enterprise tier through Entra identity integration and Copilot AI embedding. Simpplr and Unily occupy positions within the specialized tier, with Simpplr representing the AI-powered personalization archetype and Unily exemplifying global delivery capability through localized infrastructure nodes. These three companies illustrate how competitive positioning diverges between ecosystem leverage and standalone best-of-breed execution.
| Leading Market Players |
|---|
| Microsoft |
| Simpplr |
| Unily |
| Workvivo |
| Staffbase |
| LumApps |
| Interact |
| Claromentis |
| ThoughtFarmer |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts lock United States enterprises into multi-year SaaS commitments that guarantee data center node access while capping annual price escalation. German manufacturers negotiate hybrid deployment add-ons that inflate per-seat costs by mandating localized infrastructure redundancy under GDPR works council agreements.
Pricing Analysis
Volume-discount tiering structures separate enterprise anchor accounts from mid-market template buyers and frontline worker mobile-only licenses. Three-tier pricing structure across premium, standard, and economy levels reflects integration complexity, with HIPAA-compliant healthcare deployments commanding certification premiums. Cost compression in the standard tier is intensifying because Microsoft bundles Entra identity and Copilot into unified licenses that marginalize standalone vendors. Small and medium businesses exhibit highest price sensitivity, while large enterprises absorbing change management services show lowest elasticity.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes cloud infrastructure dependency on submarine cable routes linking United States, Ireland, and Singapore data centers. Software development concentrates in the United States, India, and Ireland, with AI/ML engineering talent scarcity in Germany and France inflating implementation costs. Supply chain risk centers on single-source vulnerability for GPU clusters powering generative AI search features. Distribution runs through direct vendor sales teams for enterprise accounts and systems integrators for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs tether enterprises to incumbent platforms through decades of document sprawl and custom workflow entrenchment.
For Market Incumbents: Fortify platform stickiness by embedding agentic AI architectures that automate multi-step workflows and reduce migration feasibility. Invest in algorithmic audit trails that preempt EU AI Act conformity assessments blocking European deployments. Acquire regional compliance specialists in Germany and France to satisfy CNIL and works council data residency mandates. For New Entrants and Emerging Players: FedRAMP certification fast-tracks access to United States government agency procurement pipelines currently underserved by hyperscale vendors. Target mid-market healthcare providers in the United States seeking HIPAA-compliant hosted deployments without enterprise implementation complexity. Lead with template-driven onboarding that compresses deployment timelines from months to weeks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical-focused challengers with frontline worker mobile capabilities over horizontal suite extenders. Long-term viability hinges on AI-powered personalization engines that reduce internal communications overhead. Watch for NIS2 implementation across EU member states as the inflection signal expanding liability for critical infrastructure employee portals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft's Entra-Copilot bundling displaces standalone identity vendors in United States enterprise accounts. |
| Geographic Expansion | Localized data residency nodes in fifteen countries satisfy GDPR and EU AI Act mandates for European multinationals. |
| Acquisition of Specialist Firm | Regional compliance specialists in Germany and France secure works council agreements and CNIL alignment. |
| Product Launch | Agentic AI architectures shift intranets from passive repositories toward autonomous workflow execution. |
| Strategic Partnership | EHR integration partnerships with United States hospital systems unify clinical and administrative workflows. |
Research Methodology
A standing panel of CIOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC cybersecurity disclosure filings, hyperscaler capex disclosures, hospital procurement databases, and EU regulatory implementation trackers. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across cloud, hybrid, and on-premises architectures.
Consistency checks validated outputs against external benchmarks including SaaS vendor revenue disclosures and systems integrator implementation pipeline data. The analytical framework segmented by deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs were derived from fitted growth curves incorporating M&A integration velocity, regulatory compliance deadline clustering, and AI feature adoption curves.
Underlying assumptions cover elastic cloud infrastructure availability, regulatory enforcement continuity, and AI talent pipeline expansion, with deviation risk concentrated in generative AI hallucination liability rulings and NIS2 liability expansion timing. Practitioners should keep alternative scenarios live as EU AI Act conformity assessment precedents and SEC disclosure rule enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
RIP Software Market
Software & Services
Global Customer Success Software Market
Software & Services
Estate Management Software Market
Software & Services
APAC Interior Design Software Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Real Estate Software Market
Software & Services
Global Document Control Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Global Mobile Middleware Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Global Audience Response Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Global Quoting Software Market
Software & Services
Team Collaboration Software Market
Software & Services
Managed Information Services Market