
 Global Digital Adoption Platform Software Market | 2026-2036
Global Digital Adoption Platform Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Adoption Platform Software Market Foresight
Embedded AI-driven contextual guidance is reconfiguring how enterprise software delivers user assistance, replacing static documentation with real-time behavioral prompts. WalkMe leverages extensive patent libraries to anchor its position in regulated industries. Pendo competes through product analytics integration that deepens user journey visibility. Whatfix differentiates by specializing in multilingual localization for multinational deployments.
Digital Adoption Platform Software comprises code-layer overlays that inject interactive walkthroughs, tooltips, and automation scripts into third-party applications without source modification, typically deployed via browser extensions or API connectors to reduce training overhead and support ticket volume. Cloud-based deployment leads the segment structure due to faster implementation cycles and lower infrastructure commitment, while employee onboarding solutions capture concentrated margin pools as enterprises prioritize retention economics. Financial services applications are expanding fastest as Basel III operational risk frameworks and SEC cybersecurity disclosure rules compel auditable training records.
FDA 21 CFR Part 11 validation requirements shape pharmaceutical deployment specifications, while EU GDPR Article 32 mandates drive data residency configurations for European implementations. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor risk. Stakeholders must monitor how NIST AI Risk Management Framework guidance will reshape algorithmic transparency requirements for automated guidance systems.
Market Dynamics
Cloud migration mandates from EU GDPR compliance and US HIPAA data localization rules are forcing platform upgrades, compressing implementation cycles and elevating procurement scrutiny around data residency configurations.
Growth Catalysts
- Basel III operational risk frameworks:Financial institutions in Germany and Japan require auditable training records, accelerating deployment of guided workflow tools for compliance documentation.
- Legacy system modernization budgets:Enterprise IT departments across financial services are channeling capital into interactive overlay platforms that reduce training overhead without source code modification.
- ISO 27001 certification requirements:Enterprise buyers now filter vendor selections through baseline security credentials, expanding addressable market for certified platform providers.
Market Restraints
- Implementation complexity with on-premise ERP:API connector limitations in SAP and Oracle environments create friction for hybrid deployment models.
- Data residency infrastructure costs:EU GDPR Article 32 mandates require localized server configurations, elevating total cost of ownership for multinational rollouts.
- Browser extension security policies:Enterprise IT lockdown policies in regulated industries restrict deployment vectors, constraining addressable user bases.
Strategic Opportunities
- FDA 21 CFR Part 11 validation gap:Pharmaceutical manufacturers seek compliant guidance platforms for electronic records, an underserved vertical with concentrated procurement budgets.
- Multilingual localization for emerging markets:Deployment support for Japanese and German regulatory documentation creates differentiation against English-centric competitors.
- NIST AI Risk Management Framework alignment:Automated guidance systems requiring algorithmic transparency certification will reshape vendor qualification criteria.
Industry Challenges
- Behavioral data science talent scarcity:Platform vendors struggle to hire specialists capable of designing predictive intervention workflows.
- Cross-application integration testing:Quality assurance across Salesforce, Workday, and ServiceNow environments extends release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Adoption Platform Software Market |
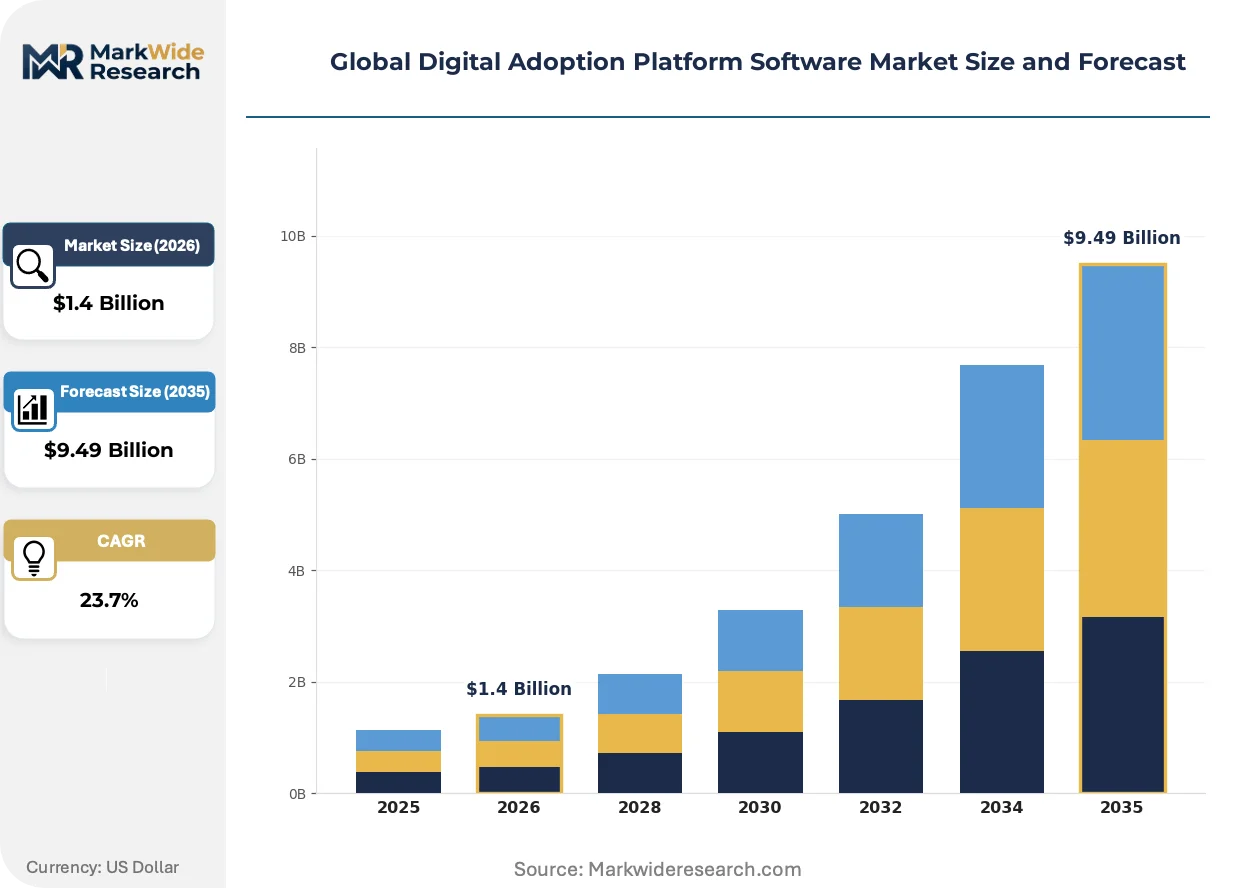
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $9.49 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Private Cloud Solution Type: Employee Onboarding, Customer Training, Product Adoption, Software Integration, Change Management Application: Financial Services, Education, Telecommunications, Government Agencies, Manufacturing End User: Enterprises, Small & Medium Businesses, Technology Providers, Consulting Firms, Educational Institutions |
| Companies Covered | Apty, Appcues, Pendo, UserGuiding, Userpilot, WalkMe, Userlane, Guideflow, Whatfix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Adoption Platform Software Market Shifts & Advancements
Embedded AI-driven contextual guidance is reconfiguring how enterprise software delivers user assistance, replacing static documentation with real-time behavioral prompts that compress onboarding duration and reduce support ticket volume.
Natural language processing engines are virtualizing the creation of interactive walkthroughs, enabling non-technical administrators to generate contextual guidance without scripting expertise. Mid-market SaaS vendors in the United States are adopting these tools fastest, compressing the traditional three-month implementation window into weeks. This capability is virtualizing competitive barriers between specialized DAP providers and adjacent analytics platforms.
EU AI Act risk classification requirements are reshaping procurement specifications for automated guidance systems, mandating human oversight mechanisms for high-risk workplace applications. German automotive manufacturers and French pharmaceutical groups now require algorithmic impact assessments before platform deployment. Financial services applications across the Netherlands and Italy are responding by demanding vendor documentation of decision logic transparency.
Subscription unbundling is fragmenting traditional platform packaging, with buyers separating analytics modules from core guidance functionality. Channel partners in Japan are displacing direct enterprise sales for mid-market accounts, offering localized implementation support that vendor direct teams cannot match. This pattern is most visible in healthcare and life sciences verticals where procurement committees prioritize regional service presence.
Global Digital Adoption Platform Software Market Segmentation
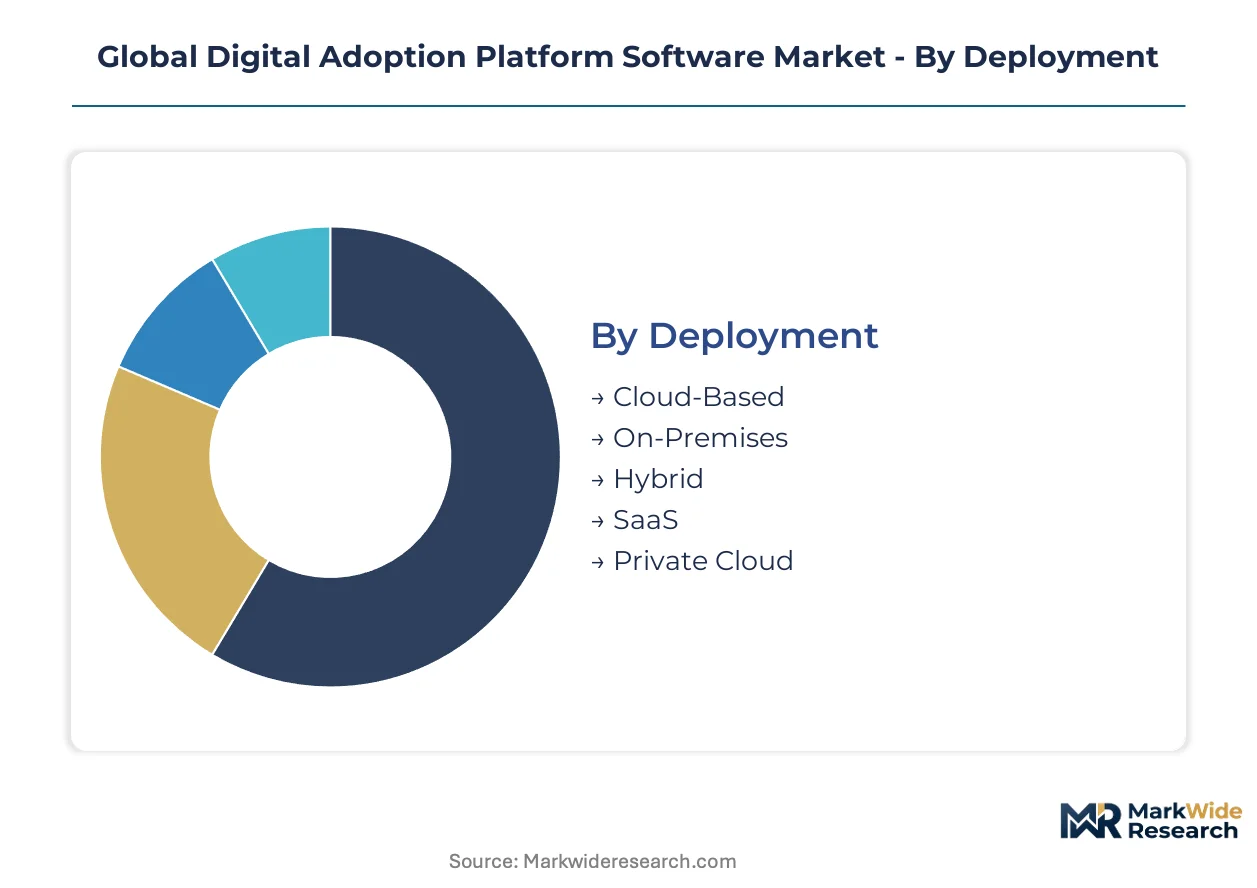
Deployment architecture and solution specialization determine how digital adoption platforms integrate with existing IT estates and compliance frameworks. Segmentation reveals where vendor capabilities align with buyer procurement criteria across regulated industries.
Deployment:
Cloud deployment models vary sharply in after-sales service intensity, with managed infrastructure demanding continuous vendor engagement versus self-hosted alternatives that shift operational burden to internal IT teams.
- Cloud-Based:Multi-tenant architectures with automatic updates reduce infrastructure overhead for mid-market buyers. Financial services firms in the United States and Germany concentrate procurement here, driven by HIPAA and GDPR data residency configurations that require localized server clusters.
- On-Premises:Dedicated hardware installations behind corporate firewalls satisfy air-gapped security requirements. Japanese automotive manufacturers and German pharmaceutical groups favor this model for IP protection, constrained by higher total cost of ownership and extended implementation cycles.
- Hybrid:Split workloads between cloud orchestration and on-site data retention balance flexibility with control.
- SaaS:Browser-delivered functionality with subscription pricing lowers entry barriers for rapid deployment.
- Private Cloud:Single-tenant virtualized environments offer customization without shared infrastructure exposure.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as enterprises navigate compliance complexity.
Solution Type:
Functional specialization maps directly to buyer organizational structure, with HR-aligned onboarding tools commanding different procurement committees than IT-centric integration modules.
- Employee Onboarding:Interactive walkthroughs and contextual guidance reduce time-to-productivity for new hires. Technology providers in the United States deploy these tools most aggressively, responding to retention economics and compressed hiring cycles in competitive labor markets.
- Customer Training:Self-service educational overlays embedded within SaaS products decrease support ticket volume. Telecommunications carriers across Japan and Germany prioritize these solutions for subscriber-facing portals, where multilingual localization drives differentiation requirements.
- Product Adoption:Feature discovery prompts and usage analytics accelerate value realization from software investments.
- Software Integration:Cross-application workflow automation connects disparate enterprise systems without API development.
- Change Management:Communication tools and progress tracking support organizational transformation initiatives.
By revenue concentration, Employee Onboarding dominates. By expansion trajectory, Customer Training shows steepest growth as product-led strategies proliferate.
Application:
Vertical-specific compliance requirements shape feature roadmaps, with regulated industries demanding audit trails and validation documentation that general-purpose platforms must retrofit.
- Financial Services:Basel III operational risk frameworks and SEC cybersecurity disclosure rules mandate auditable training records. Banks and insurers in Germany, Japan, and the United States channel the largest modernization budgets into guided workflow tools.
- Education:Learning management system overlays support hybrid instructional models. Universities across the United States deploy these for faculty technology adoption, constrained by procurement cycles tied to academic calendars.
- Telecommunications:Subscriber onboarding and self-service portal optimization reduce call center dependency.
- Government Agencies:FedRAMP and equivalent national security certifications filter vendor eligibility for public sector contracts.
- Manufacturing:Shop floor system training for ERP and quality management platforms addresses workforce turnover.
By implementation scale, Financial Services leads. By contract velocity, Education is climbing fastest as institutional digital transformation accelerates.
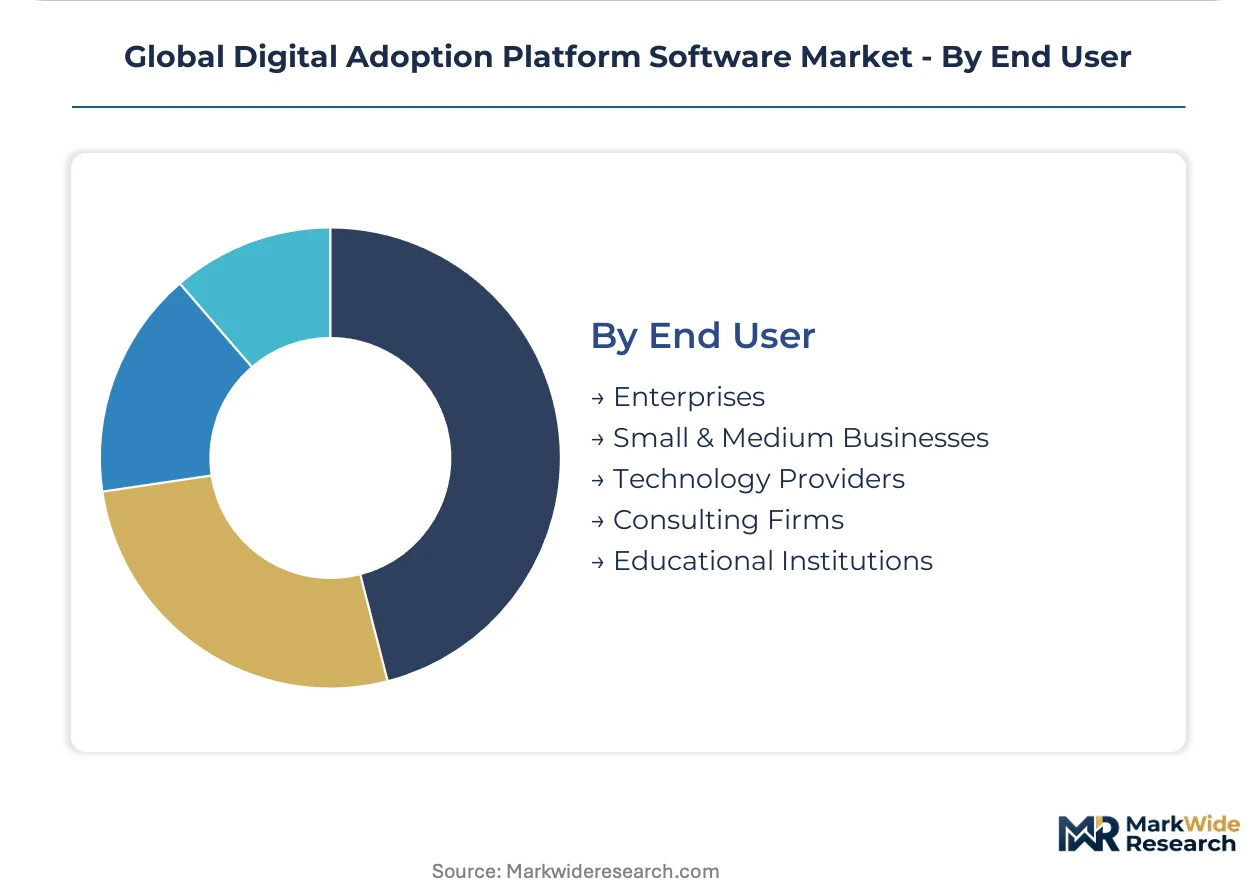
End User:
Organizational scale determines purchasing authority complexity, with enterprise procurement involving security, legal, and line-of-business stakeholders versus streamlined SMB decisions.
- Enterprises:Global deployments across multiple jurisdictions require multilingual support and regional data residency. Consulting firms in Germany and technology providers in Japan represent concentrated demand, driven by cross-border standardization mandates.
- Small & Medium Businesses:Department-level purchasing with shorter sales cycles favors self-service onboarding and transparent pricing. United States mid-market SaaS vendors adopt these tools fastest, compressing traditional implementation windows through natural language workflow generation.
- Technology Providers:Embedded guidance within own products reduces customer success overhead.
- Consulting Firms:Client-facing change management and training delivery tools extend service offerings.
- Educational Institutions:Faculty and student technology adoption support with limited IT resources.
By contract value, Enterprises dominate. By account growth rate, Small & Medium Businesses is expanding most quickly as vendor self-service capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of digital adoption platform software concentrate from US and Israeli development centers toward European and Asian enterprise buyers, while import dependency for localized implementation services runs in reverse. Germany and Japan maintain trade surpluses in systems integration expertise. Data residency mandates in multiple jurisdictions are fragmenting cloud infrastructure deployment patterns.
United States
Financial services modernization and HIPAA data localization rules drive procurement from New York and San Francisco enterprise clusters. SEC cybersecurity disclosure requirements mandate auditable training records. Silicon Valley SaaS vendors deploy natural language workflow generation tools fastest, compressing implementation windows for mid-market buyers.
Germany
Basel III operational risk frameworks and automotive ERP integration needs anchor demand in Frankfurt and Munich banking centers. GDPR Article 32 data residency configurations require localized server clusters. Bavarian manufacturing groups favor on-premises deployments for IP protection against cloud infrastructure exposure.
Japan
Legacy system modernization in Tokyo and Osaka financial districts accelerates guided workflow adoption. METI digital transformation incentives channel public-private investment into employee onboarding platforms. Automotive manufacturers in Nagoya maintain hybrid deployment preferences balancing cloud flexibility with air-gapped security requirements.
United Kingdom
FCA operational resilience rules and fintech scaling pressures drive London procurement of customer training overlays. Channel partners displace direct vendor sales for mid-market healthcare accounts. Edinburgh and Manchester consulting clusters expand regional implementation capacity beyond capital concentration.
India
IT services export hubs in Bangalore and Hyderabad generate demand for multilingual localization capabilities. RBI data localization guidelines for financial services elevate procurement scrutiny around server geography. Mumbai enterprise buyers prioritize subscription unbundling to separate analytics modules from core guidance functionality.
Global Digital Adoption Platform Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers. Patent-heavy incumbents anchor regulated verticals through compliance documentation capabilities. Analytics-integrated challengers compete on user journey visibility. Localization specialists capture multinational rollout contracts. Dominant competitive moves include API connector expansion and regional channel partner recruitment.
Within the patent-anchored tier, WalkMe exemplifies regulatory-focused positioning through extensive intellectual property libraries. Pendo occupies the analytics-integrated vector, deepening product usage visibility for SaaS vendors. Whatfix represents the localization specialist archetype, capturing multilingual deployment contracts across German and Japanese manufacturing clients.
| Leading Market Players |
|---|
| Apty |
| Appcues |
| Pendo |
| UserGuiding |
| Userpilot |
| WalkMe |
| Userlane |
| Guideflow |
| Whatfix |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber routes from San Jose to Tokyo anchor cloud infrastructure delivery costs for digital adoption platforms, compressing margins for vendors serving Japanese financial institutions while enabling tiered pricing differentiation between latency-optimized and standard SaaS deployments across German and US enterprise markets.
Pricing Analysis
Next-generation AI-native guidance engines command subscription premiums over legacy rule-based walkthrough tools, while prior-generation tooltip-only platforms face accelerated price erosion. Three-tier pricing structure across enterprise, professional, and self-serve levels segments buyer archetypes by implementation complexity and support intensity. Cost compression in the mid-market tier intensifies as natural language workflow generation commoditizes basic deployment capabilities. Small and medium businesses exhibit highest price sensitivity, driving vendors toward transparent self-service pricing and freemium conversion funnels.
Supply Chain Analysis
US export controls on advanced AI training infrastructure constrain how Israeli and Singaporean development centers access GPU clusters for behavioral model refinement. Cloud compute provisioning concentrates in the United States, Ireland, and Singapore, with German data residency requirements forcing localized server deployments that fragment infrastructure economics. Intellectual property licensing for embedded NLP engines draws from US patent holders and open-source repositories. Single-source vulnerability around hyperscaler API dependencies poses structural risk for vendors building on proprietary orchestration layers. Distribution runs through direct enterprise sales teams in regulated verticals and channel partners for mid-market localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable advantages: compliance documentation libraries and validated deployment templates generate switching costs that extend contract renewal rates and expand account values.
For Market Incumbents: Insulate core revenue streams by deepening ISO 27001 and FDA 21 CFR Part 11 certification moats against analytics-platform challengers entering from adjacent markets. Expand API connector coverage into SAP S/4HANA and Oracle Fusion environments to capture hybrid deployment demand from German manufacturing clients. Prioritize patent acquisition in predictive intervention algorithms to block natural-language workflow commoditization. For New Entrants and Emerging Players: Build out specialized compliance capabilities for pharmaceutical electronic records validation, an underserved vertical with concentrated procurement budgets and limited incumbent attention. Target Japanese automotive manufacturers seeking multilingual deployment support with localized implementation partnerships that established vendors lack bandwidth to replicate. Pursue channel-first go-to-market structures through regional systems integrators rather than direct sales buildout. For Investors and Strategic Acquirers: Patent-anchored specialists with validated regulatory documentation libraries represent the most defensible acquisition profile for long-term holding periods. Monitor NIST AI Risk Management Framework adoption velocity as an inflection signal: accelerated compliance mandates will reshape vendor qualification criteria and concentrate procurement among pre-certified providers. Watch for consolidation triggers when mid-market SaaS vendors begin bundling basic guidance functionality natively.| Strategic Initiative | Industry Significance |
|---|---|
| API Connector Expansion | Deepens SAP and Oracle integration coverage for hybrid deployment demand from German automotive manufacturers. |
| Regulatory Certification Investment | Accelerates FDA 21 CFR Part 11 validation for pharmaceutical electronic records compliance capture. |
| Channel Partner Recruitment | Displaces direct sales for Japanese mid-market accounts where localized implementation support drives procurement decisions. |
| Patent Portfolio Acquisition | Blocks natural-language workflow commoditization by securing predictive intervention algorithm intellectual property. |
| Data Residency Infrastructure Buildout | Enables GDPR Article 32 compliant deployments for EU financial services clients requiring localized server clusters. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Bottom-up deployment volume estimates triangulated against top-down enterprise software spending patterns.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling deployment architecture, organization size, vertical compliance intensity, and regional adoption pattern as core segmentation dimensions. CAGRs derived from fitted growth curves applied to validated baseline estimates, with inputs including cloud migration mandate timelines from GDPR and HIPAA enforcement patterns and Basel III operational risk framework adoption trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler platform vendors bundling native guidance functionality would shift outcomes. Material shifts in EU AI Act risk classification thresholds or NIST AI Risk Management Framework mandatory adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Restaurant Management Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Global Microscopy Software Market
Software & Services
Construction Software As A Service Market
Software & Services
North America Enterprise Resource Planning Market
Software & Services
Video Converter Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Global Electronic Data Capture Software Market