
 Europe Mobile Security Market | 2026-2036
Europe Mobile Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Security Market Analytics
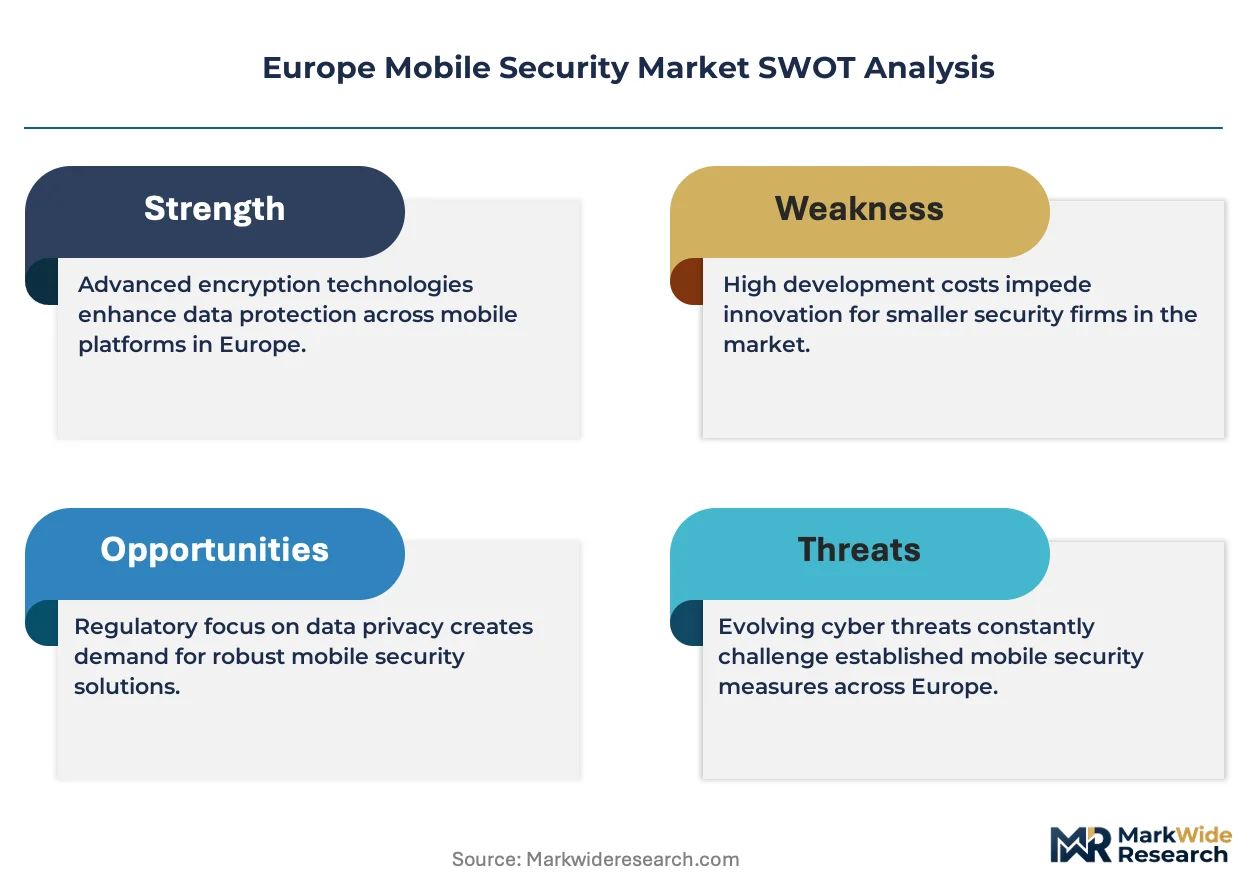
Cloud-native security architectures is rebalancing traditional on-premises mobile security economics across European enterprises. Sophos leverages its channel density in mid-market British and German accounts to sustain recurring revenue growth. Bitdefender anchors its competitive position through machine-learning threat detection pipelines purpose-built for Android and iOS attack surfaces. ESET, spol. s r.o. competes aggressively on price-performance in Central European public-sector tenders, while Check Point Software Technologies dominates large-enterprise mobile firewall deployments with unified perimeter-to-endpoint integration.
Europe Mobile Security encompasses software, services, and hardware layers that protect smartphones, tablets, and IoT endpoints from unauthorized access, malware injection, and data exfiltration through cryptographic protocols, behavioral analytics, and policy enforcement engines operating at OS kernel and network levels. The primary commercial purpose is preserving data confidentiality and regulatory compliance for organizations whose employees access corporate resources via personally owned or corporate-issued mobile devices. Anti-Malware product lines currently occupy the largest revenue share as ransomware campaigns targeting mobile banking apps intensify across Southern Europe. Cloud-Based deployment modes represent the fastest-expanding segment, with hybrid architectures gaining traction among French and Dutch enterprises navigating sovereign data requirements. Authentication solutions concentrate margin pools where FIDO2 and biometric implementations displace legacy password systems in regulated industries.
GDPR enforcement by national data protection authorities, the EU AI Act's risk-classification framework for automated decision systems, and the NIS2 Directive's expanded incident-reporting obligations collectively tighten compliance boundaries for mobile security vendors serving European organizations. EMA guidelines on data integrity for clinical trial applications and CE marking requirements for medical device companion apps further segment product certification pathways. Stakeholders must monitor how EU cybersecurity certification schemes for 5G-enabled IoT devices reshape vendor qualification criteria before procurement cycles accelerate.
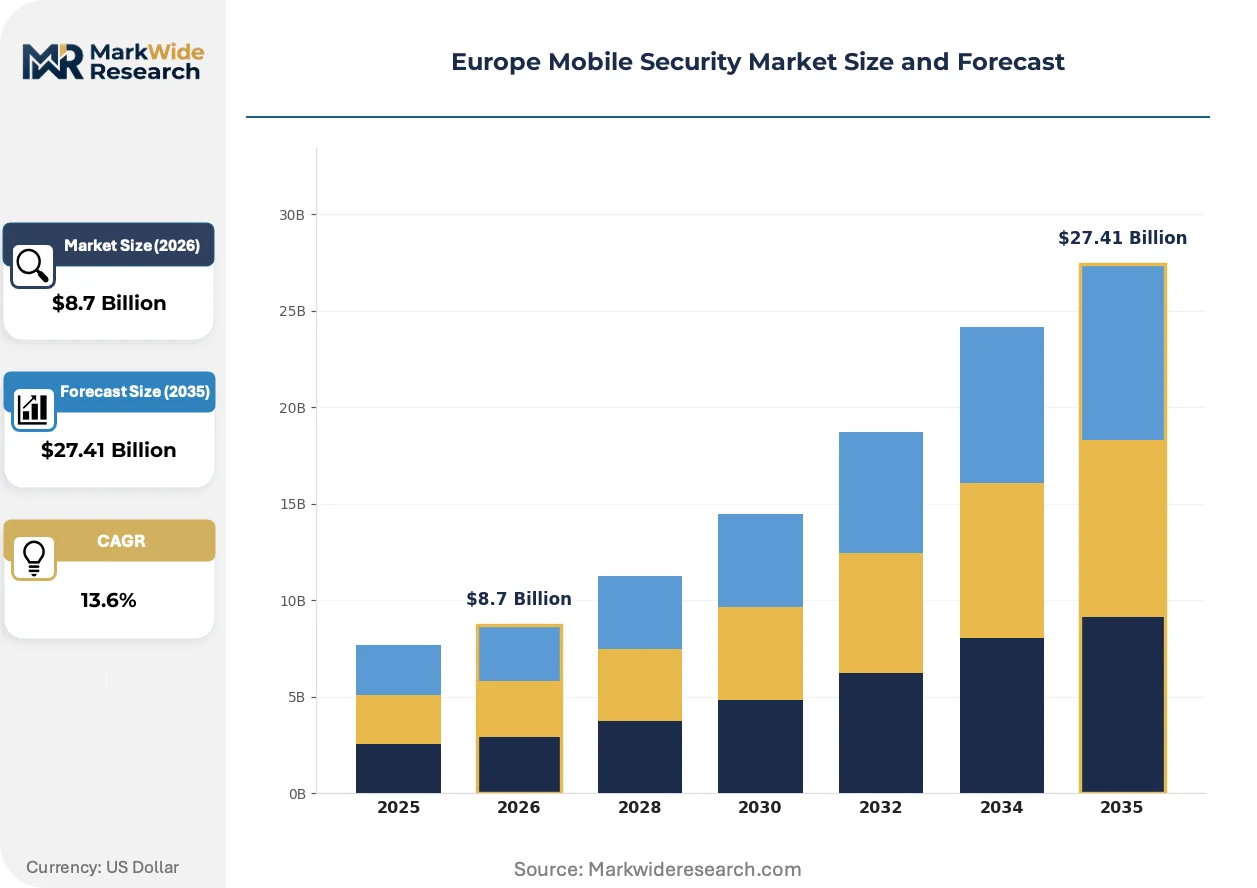
Market Dynamics
Zero-trust mobile architectures are restructuring procurement priorities across European enterprises as NIS2 Directive compliance deadlines approach. Financial services and automotive manufacturers now mandate continuous device verification, collapsing traditional perimeter-based security economics.
Growth Catalysts
- EU AI Act risk classification:Automated decision systems in mobile banking apps now face mandatory algorithmic auditing, forcing institutions to upgrade endpoint monitoring infrastructure.
- German automotive zero-trust mandates:Industrial conglomerates deploying connected vehicle fleets require kernel-level mobile threat detection for supplier ecosystem access.
- Biometric authentication convergence:FIDO2 standards adoption in French and Dutch regulated industries is displacing password-based corporate VPN access.
Market Restraints
- GDPR compliance fragmentation:National data protection authorities in Italy and Spain enforce divergent breach notification timelines, multiplying vendor certification costs.
- Sovereign cloud infrastructure gaps:French and Dutch enterprises face limited domestic hyperscale availability for mobile security telemetry storage.
- Legacy Android fragmentation:Extended support cycles for industrial handheld devices in Central European manufacturing block OS-level security patching.
Strategic Opportunities
- Polish and Romanian public-sector digitization:EU Recovery Fund allocations for e-government services create tender pipelines for mobile identity verification platforms.
- Medical device companion apps:EMA guidelines on clinical trial data integrity open specialized certification pathways for healthcare-focused endpoint protection.
- 5G private network integration:German automotive and logistics hubs require mobile security orchestration across network slices for industrial IoT deployments.
Industry Challenges
- Zero-trust architecture skill scarcity:European system integrators face recruitment bottlenecks for identity and access management specialists capable of cross-platform deployment.
- Cross-border data residency complexity:GDPR Schrems II rulings force vendors to rearchitect cloud backends for French and German sovereign data requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Security Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Device Management, Authentication, Encryption, Anti-Malware End User: Enterprises, Government, Individuals, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: Biometric Security, VPN, Security Information and Event Management, Firewall |
| Companies Covered | ESET, spol. s r.o., Sophos, F-Secure Corporation, McAfee, Check Point Software Technologies, Avast Software s.r.o., Bitdefender, Panda Security, Kaspersky Lab, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Security Market Evolving Landscape
Behavioral analytics engines are supplanting signature-based detection across European mobile security stacks. Vendors now embed on-device machine learning to reduce cloud telemetry dependency.
On-device federated learning models are electrifying threat detection latency for European banking applications. Santander and ING pilot implementations process anomaly signals locally rather than routing to centralized servers. This architecture is electrifying competitive positioning for vendors offering GDPR-compliant, low-latency mobile transaction security.
EU AI Act algorithmic transparency mandates now require mobile security vendors to document automated decision logic for biometric authentication failures. Industrial consequence includes mandatory technical documentation for machine-learning threat classifiers. German automotive suppliers face the strictest compliance burden, with TÜV certification now required for driver-monitoring mobile SDKs.
Consolidated security procurement through European managed service providers is compressing direct vendor relationships. Mid-market enterprises in Belgium and Austria now purchase mobile threat defense as bundled endpoint protection suites rather than standalone products. This pattern concentrates margin capture with distributors possessing multi-vendor integration capabilities.
Europe Mobile Security Market Segmentation
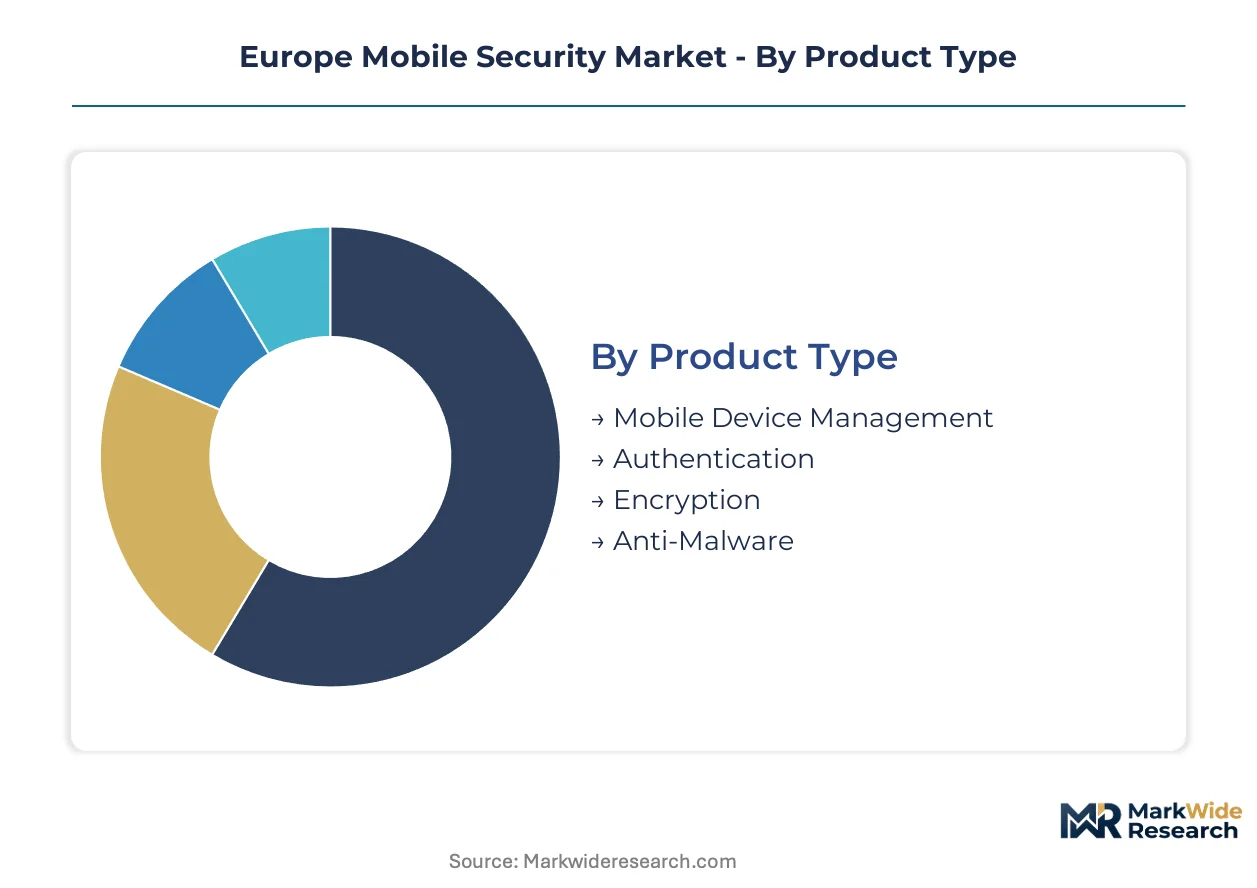
Segmentation in Europe Mobile Security reveals distinct procurement patterns across regulated industries. Buyer priorities diverge sharply between German automotive conglomerates requiring kernel-level threat detection and French public-sector tenders emphasizing sovereign cloud compliance.
Product Type:
Enterprise procurement teams weight total cost of ownership against integration complexity when selecting protection layers. German financial institutions prioritize authentication and encryption bundles, while Italian healthcare providers favor standalone anti-malware suites for legacy system compatibility.
- Anti-Malware:Signature and behavioral detection engines targeting mobile banking trojans and ransomware payloads. Southern European financial institutions drive volume as mobile payment fraud campaigns intensify across Spain and Italy. GDPR breach notification penalties amplify enterprise willingness to pay for real-time threat neutralization.
- Authentication:FIDO2-compliant biometric and token-based identity verification systems. French and Dutch regulated industries displace legacy password VPN access with hardware security key deployments. EU AI Act algorithmic auditing mandates now extend to biometric failure logging requirements.
- Mobile Device Management:Policy enforcement and containerization for corporate-issued and BYOD fleets. German automotive suppliers mandate MDM for supplier ecosystem network access.
- Encryption:Data-at-rest and in-transit cryptographic protocols. Central European manufacturing deploys field-level encryption for industrial handheld device fleets.
Anti-Malware leads on scale; Authentication leads on momentum as FIDO2 standards displace legacy credential systems.
End User:
Customer-type segmentation reflects divergent compliance burdens and procurement centralization. Government tenders emphasize price-performance and domestic data residency; enterprises prioritize integration with existing identity infrastructure.
- Enterprises:Corporate fleets spanning financial services, automotive, and industrial manufacturing. German conglomerates deploy zero-trust mobile frameworks at scale across connected vehicle and logistics operations. NIS2 Directive deadlines compress procurement cycles for continuous device verification platforms.
- Government:National and municipal public-sector agencies. Polish and Romanian e-government digitization creates tender pipelines for mobile identity verification under EU Recovery Fund allocations.
- Educational Institutions:Universities and research organizations managing mixed device populations. GDPR student data processing agreements constrain vendor selection.
- Individuals:Consumer-grade protection for personal banking and communication applications. Limited monetization outside bundled carrier offerings.
Government procurement concentrates volume in Central European markets; Enterprises capture margin through complex integration requirements.
Deployment:
Architecture choice hinges on data sovereignty requirements and telemetry latency tolerances. French and Dutch enterprises face limited domestic hyperscale availability, tilting selections toward hybrid configurations.
- Cloud-Based:Centralized security policy orchestration and threat intelligence feeds. Fastest-expanding mode as mid-market Belgian and Austrian enterprises adopt bundled endpoint protection suites through managed service providers. GDPR Schrems II rulings force backend rearchitecture for French and German sovereign data requirements.
- Hybrid:Split processing between on-device agents and cloud analytics. Gains traction among French and Dutch enterprises navigating sovereign data requirements while preserving real-time threat response.
- On-Premises:Air-gapped or self-hosted security infrastructure. German automotive and defense contractors mandate on-premise for supplier network access controls.
- Managed Services:Outsourced security operations through European MSPs. Consolidates procurement for mid-market accounts lacking internal zero-trust architecture expertise.
Cloud-Based deployment climbs the fastest; Hybrid architectures capture premium pricing in regulated verticals.
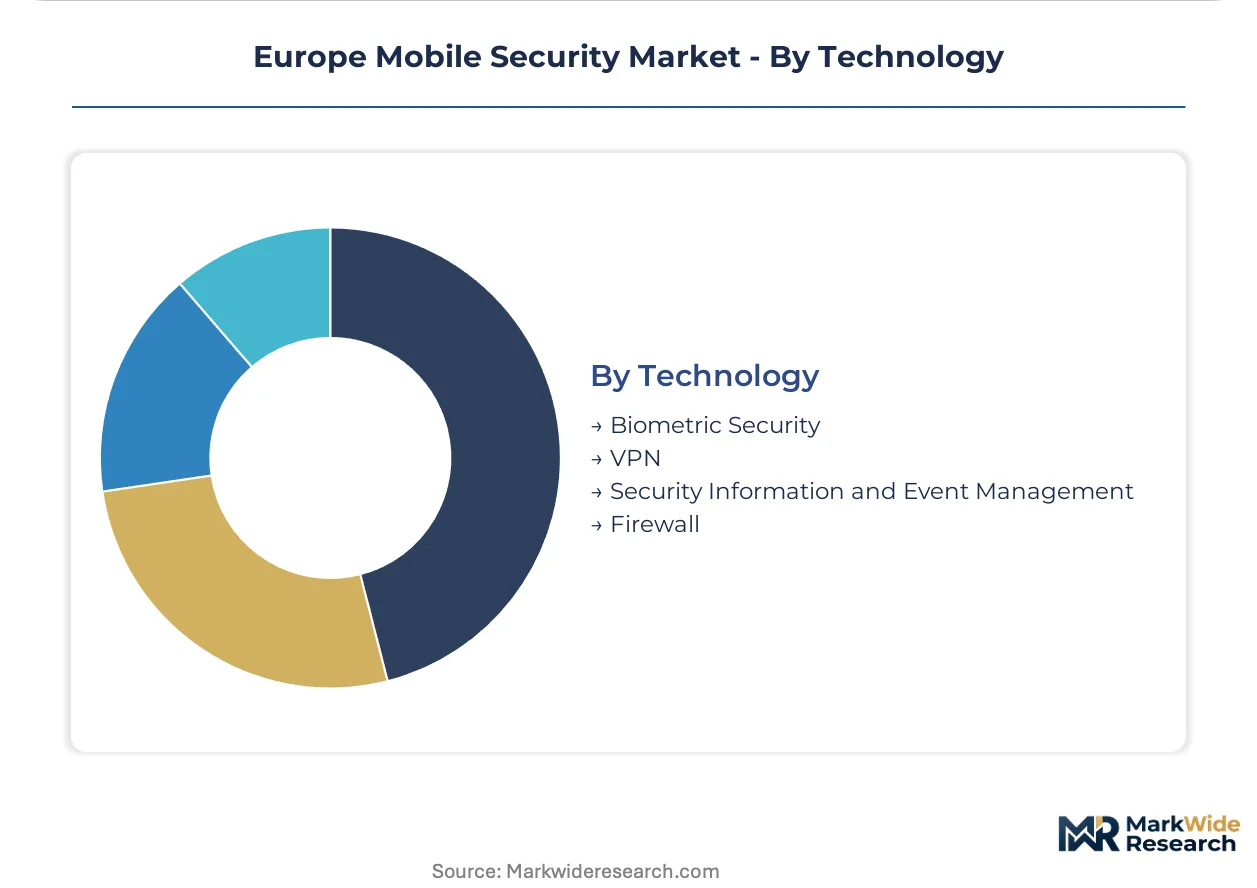
Technology:
Technology selection tracks attack surface expansion and regulatory certification requirements. Biometric implementations face EU AI Act documentation burdens; VPN demand shifts toward zero-trust network access architectures.
- Biometric Security:Fingerprint, facial recognition, and behavioral biometrics for device and application access. German automotive suppliers require TÜV certification for driver-monitoring mobile SDKs under strictest EU AI Act risk classification. On-device federated learning models reduce cloud telemetry dependency for GDPR compliance.
- Security Information and Event Management:Centralized logging and correlation across mobile endpoint telemetry. Financial services in Germany and France accelerate adoption for algorithmic auditing of automated decision systems.
- VPN:Encrypted tunneling for remote corporate resource access. Displacement by zero-trust network access in enterprise refresh cycles.
- Firewall:Network-layer traffic filtering and intrusion prevention. Large-enterprise mobile perimeter deployments favor unified perimeter-to-endpoint integration.
Biometric Security leads on margin concentration; SIEM gains share fastest from regulatory audit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and industrial conglomerates anchor European mobile security demand through zero-trust framework deployments. The EU AI Act and NIS2 Directive compress procurement timelines across member states. National data protection authorities enforce divergent compliance standards that reshape vendor qualification criteria.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg mandate kernel-level mobile threat detection for supplier ecosystem access. The NIS2 Directive imposes expanded incident-reporting obligations on critical infrastructure operators. Frankfurt's financial services cluster accelerates biometric authentication adoption for corporate VPN replacement.
France
French banking groups pilot on-device federated learning for GDPR-compliant transaction security. The CNIL enforces algorithmic transparency mandates under EU AI Act risk classifications. Paris-based regulated industries deploy hardware security keys displacing legacy password systems.
United Kingdom
Mid-market British enterprises purchase mobile threat defense through managed service provider bundles. Sophos leverages channel density across London and Manchester for recurring revenue capture. The Information Commissioner's Office tightens breach notification timelines for financial services mobile deployments.
Netherlands
Dutch enterprises navigate sovereign data requirements through hybrid cloud security architectures. Limited domestic hyperscale availability tilts selections toward split-processing configurations. Amsterdam's fintech cluster demands low-latency threat detection for mobile banking applications.
Poland
EU Recovery Fund allocations for e-government services create tender pipelines for mobile identity verification platforms. The national data protection authority enforces GDPR student data processing agreements constraining educational procurement. Warsaw's public-sector digitization programs concentrate volume for authentication solution vendors.
Europe Mobile Security Market Competitive Landscape
Global majors compete with regional champions across channel density and compliance specialization. The vendor base clusters around three strategic archetypes: cloud-native platform providers, endpoint protection incumbents, and price-performance challengers in public-sector tenders. Dominant competitive moves include portfolio diversification into zero-trust architectures and geographic expansion through managed service provider partnerships.
Within the endpoint protection tier, ESET, spol. s r.o. and Bitdefender exemplify divergent positioning strategies. ESET occupies a position as a price-performance challenger in Central European public-sector procurement. Bitdefender anchors the machine-learning threat detection segment for Android and iOS attack surfaces. Sophos represents the channel-driven archetype sustaining recurring revenue through mid-market British and German account density.
| Leading Market Players |
|---|
| ESET, spol. s r.o. |
| Sophos |
| F-Secure Corporation |
| McAfee |
| Check Point Software Technologies |
| Avast Software s.r.o. |
| Bitdefender |
| Panda Security |
| Kaspersky Lab |
| Others |
Value Network & Pricing Analysis
Horizontal integration across managed service provider networks anchors both supply positioning and pricing power in the European mobile security market. MSPs in Belgium and Austria consolidate procurement through bundled endpoint protection suites, compressing direct vendor relationships while capturing margin through multi-vendor integration capabilities. This consolidation pattern shifts pricing leverage toward distributors capable of orchestrating zero-trust deployments across heterogeneous device fleets.
Pricing Analysis
Input-cost pass-through from cloud infrastructure tariffs and compliance certification expenses shapes vendor margin structures. Subscription-based SaaS tiers dominate, with premium pricing tied to EU AI Act algorithmic audit documentation and GDPR sovereign data residency guarantees. Price differentiation hinges on certification grade—TÜV-validated biometric SDKs command substantial premiums over standard FIDO2 implementations—and vertical integration depth. Cost compression in mid-market tiers is intensifying because Polish and Romanian public-sector tenders emphasize price-performance metrics. Government procurement teams exhibit highest price sensitivity, while German automotive conglomerates prioritize integration reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Amsterdam, and London orchestrate hub-and-spoke fulfillment patterns for security software licenses and hardware security keys. Supply concentration centers on Estonia and Slovakia for cryptographic module manufacturing, Ireland for cloud infrastructure provisioning, and Israel for threat intelligence engine development. Raw material dependencies include semiconductor components for hardware security modules, specialized optical sensors for biometric implementations, and rare earth elements for tamper-resistant packaging. Single-source vulnerability in EU-certified cryptographic chip supply creates systemic exposure. Distribution runs through European MSP networks and direct enterprise sales forces, with channel partners handling localization and compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between German compliance-heavy deployments and Central European price-sensitive tenders creates margin optimization opportunities. Regulatory divergence—strict EU AI Act enforcement in Bavaria versus flexible GDPR interpretation in Warsaw—generates cost differentials exceeding standard logistics spreads.
For Market Incumbents: Cement channel control through exclusive MSP partnerships in British and German mid-market accounts. Deepen zero-trust architecture certification investments to defend against cloud-native platform providers encroaching on enterprise refresh cycles. Capture biometric authentication margin pools by acquiring FIDO2 specialist firms before EU AI Act documentation requirements harden competitive barriers.
For New Entrants and Emerging Players: Begin with Polish and Romanian e-government digitization pipelines where EU Recovery Fund allocations concentrate tender volume. Target medical device companion app certification as the most penetrable vertical, exploiting EMA guideline gaps that incumbent vendors have left underserved. Pursue go-to-market positioning through healthcare-focused system integrators possessing existing hospital procurement relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional MSPs because mid-market procurement consolidation concentrates recurring revenue streams with limited customer acquisition cost inflation. Five-to-ten year viability hinges on cloud-native platform transitions completing without margin collapse. Target acquisition archetypes: Belgian and Austrian MSPs with multi-vendor integration capabilities. Monitor 5G private network deployment velocity in German automotive hubs as the critical inflection signal for industrial IoT security demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | TÜV validation for German automotive supplier ecosystem access unlocks premium pricing tiers. |
| On-Device Federated Learning Deployment | Santander and ING pilot implementations demonstrate GDPR-compliant low-latency transaction security viability. |
| MSP Channel Partnership Expansion | Belgian and Austrian distributor consolidation captures mid-market procurement bundle economics. |
| Biometric SDK Regulatory Documentation | EU AI Act algorithmic transparency mandates create mandatory technical documentation revenue streams. |
| Hybrid Cloud Infrastructure Localization | French and Dutch sovereign data requirements drive split-processing architecture premium pricing. |
Research Methodology
Direct dialogue with CISOs at German automotive conglomerates, French banking group CTOs, Dutch fintech platform engineers, and Polish public-sector procurement directors grounded qualitative assessment. Secondary validation drew from EMA clinical trial guidance documents, EU AI Act implementation texts, NIS2 Directive transposition measures, and national data protection authority enforcement bulletins. Bottom-up triangulation across vendor revenue disclosures and top-down reconciliation against EU cybersecurity certification scheme adoption curves produced convergent estimates.
Segmentation outputs across product type, deployment architecture, end-user vertical, and technology layer fed into analytical framework construction over the projection horizon. CAGRs emerged from logistic adoption curves fitted to regulatory deadline compression effects and enterprise refresh cycle timing. Industry-specific forecast inputs included 5G private network deployment schedules in German industrial zones and EU Recovery Fund allocation trajectories for Central European e-government digitization.
Several conditions sit outside the modeled scope, including geopolitical disruptions to semiconductor supply chains, unilateral GDPR enforcement divergences by national data protection authorities, and breakthrough advances in quantum-resistant cryptography obsoleting current encryption standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Data Protection Market
Cybersecurity
Latin America Ransomware Protection Market
Cybersecurity
Operational Technology Security Market
Cybersecurity
IT and Telecom Cyber Security Market
Cybersecurity
Latin America IoT Security Market
Cybersecurity
Cloud-Based Email Security Market
Cybersecurity
India Cybersecurity Market
Cybersecurity
CDN Security Market
Cybersecurity
Global Cloud Security Posture Management Market
Cybersecurity
M2M Network Security Market
Cybersecurity
SOC As a Service Market
Cybersecurity
Global Cloud Encryption Market
Cybersecurity
United States Cybersecurity Market
Cybersecurity
Data Diode Solution Market
Cybersecurity
Colombia Cybersecurity Market
Cybersecurity
Greece Cybersecurity Market