
 Latin America IT Market | 2026-2036
Latin America IT Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America IT Market Outlook
Project finance for hyperscale data centers is tilting competitive dynamics toward asset-light operators with sovereign-backed guarantees. Nu Holdings leverages its digital-native infrastructure to sustain cost advantages across Brazilian retail banking. BairesDev anchors nearshore delivery capacity for North American enterprise clients. Telefônica Brasil competes through fiber backbone investments that dominate last-mile connectivity in southeastern states.
Latin America IT encompasses software applications, computing hardware, professional services, and telecommunications networking deployed to process, store, and transmit digital information across commercial and public sector environments. Cloud infrastructure operates at latency thresholds below 50 milliseconds to serve real-time financial transactions and telemedicine platforms. Services and cloud deployment categories command margin premiums as Brazilian and Mexican enterprises shift from capital-intensive on-premises estates to consumption-based models. Software segments specializing in regulatory compliance and open-source integration occupy the fastest-expanding demand pools.
Brazil's LGPD enforcement and Mexico's data localization mandates under its Federal Law on Protection of Personal Data shape vendor selection criteria and cross-border architecture decisions. ANATEL certification requirements in Brazil and IFETEL spectrum rules in Mexico constrain hardware import timelines and service launch velocities. Stakeholders must monitor evolving central bank digital currency frameworks and their interoperability demands on core banking infrastructure.
Market Dynamics
Cloud infrastructure migration across Brazilian and Mexican financial institutions is compressing traditional hardware procurement cycles while elevating compliance architecture to board-level investment priority. Sovereign data localization mandates are forcing architectural redesigns that favor regional hyperscale deployments over foreign public cloud reliance.
Growth Catalysts
- LGPD Enforcement Escalation:Brazil's data protection authority is accelerating audit frequencies across healthcare and banking sectors, compelling legacy system overhauls and dedicated compliance software procurement.
- Real-Time Payment Rails:Central bank instant payment infrastructure in Brazil and Mexico is forcing core banking modernization, creating demand for low-latency transaction processing platforms.
- São Paulo-Mexico City Corridor Concentration:Enterprise software demand clusters in these metropolitan technology corridors, attracting specialized vendor ecosystems and skilled engineering talent pools.
Market Restraints
- Import Hardware Lead Times:ANATEL certification requirements in Brazil extend server and networking equipment delivery windows by 4-8 months, constraining rapid infrastructure scaling.
- USD-Denominated Cloud Pricing:Latin American enterprise procurement faces foreign exchange volatility as major hyperscalers invoice in dollars, compressing IT budget predictability.
- Submarine Cable Concentration:Cross-border data traffic relies on limited fiber routes through Florida and California landing points, creating single-point-of-failure risk for regional connectivity.
Strategic Opportunities
- Colombian Andean Expansion:Bogotá and Medellín enterprise markets show underpenetrated cloud adoption relative to São Paulo, offering first-mover positioning for localized data center operators.
- Regulatory Technology Convergence:Open banking APIs and LGPD compliance requirements are creating integrated demand for platforms that unify transaction processing with automated audit trails.
- Edge Computing for Agribusiness:Precision agriculture IoT deployments in Brazil's Mato Grosso and Argentina's Pampas regions require sub-20 millisecond processing for autonomous equipment coordination.
Industry Challenges
- Certification Pipeline Bottlenecks:ANATEL and IFETEL testing queue backlogs delay product launches by 6-12 months, forcing vendors to sequence market entry around regulatory calendar capacity.
- Legacy Core Integration Complexity:Brazilian banks operate COBOL-based mainframe estates from the 1980s, creating API middleware development burdens that consume 40-60% of modernization project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America IT Market |
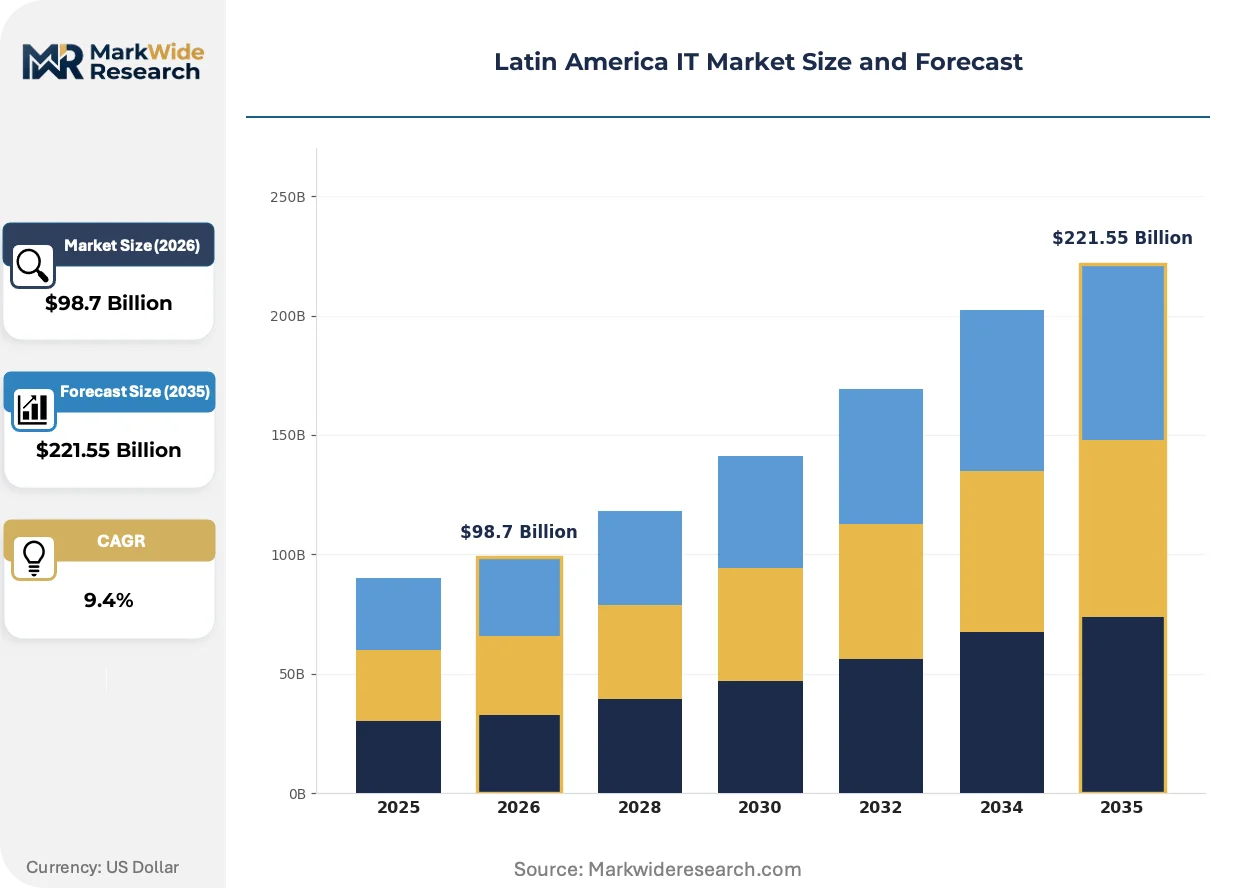
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $221.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Networking Deployment: On-Premises, Cloud, Hybrid, Edge End User: Government, IT & Telecom, Education, Healthcare Service Type: Consulting, Managed Services, Technical Support, Integration |
| Companies Covered | Nu Holdings (Nubank), BairesDev, América Móvil, 10Pearls, Gorilla Logic, Telefônica Brasil, N-iX, Sparq, Claro Telecom Participações, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America IT Market Strategic Shifts
Software-defined infrastructure is displacing purpose-built hardware across Latin American enterprise data centers, while regulatory technology stacks are converging with core operational platforms rather than operating as siloed audit tools.
Network function virtualization is virtualizing telecommunications infrastructure across Brazilian mobile operators. Telefônica Brasil and Claro are deploying virtualized radio access networks in São Paulo and Rio de Janeiro metropolitan zones to reduce base station hardware dependence. This architecture is virtualizing proprietary vendor lock-in, enabling multi-vendor equipment mixing that compresses capital intensity per subscriber.
Brazil's LGPD enforcement protocols are mandating data residency documentation and breach notification automation. The national data protection authority's penalty escalation—reaching 2% of Brazilian revenue—is compelling enterprise investment in compliance-as-code tooling. Financial services and healthcare verticals are responding fastest, embedding privacy-by-design into procurement specifications rather than retrofitting post-deployment.
Consumption-based infrastructure procurement is replacing capital-intensive server ownership among mid-market Mexican enterprises. Leasing and managed service arrangements now dominate Monterrey and Guadalajara manufacturing corridor IT spending. This preference shift is most visible in automotive supplier networks, where ERP and MES platform access is purchased as operational expenditure aligned with production volume fluctuations.
Latin America IT Market Segmentation
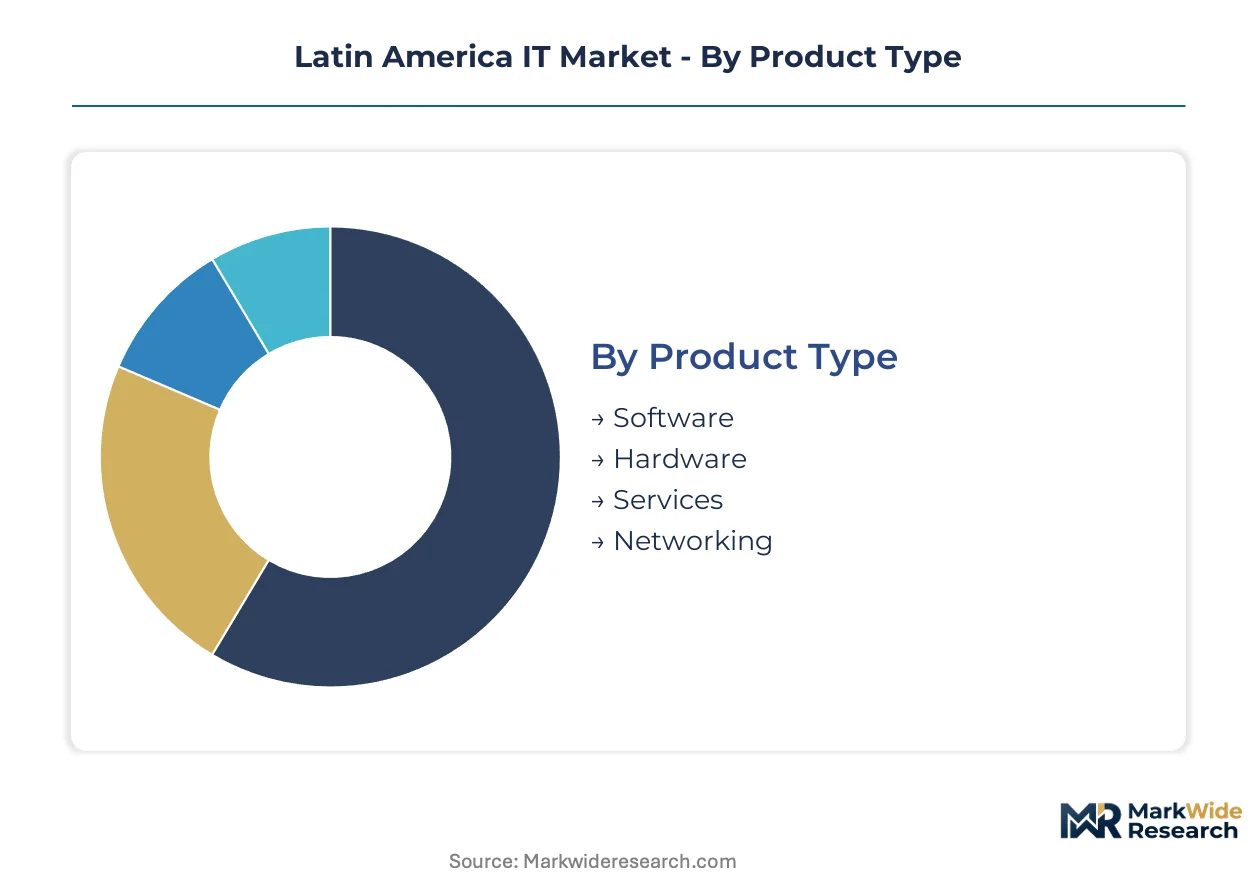
Segmentation reveals how compliance mandates and infrastructure modernization reshape procurement patterns across Brazilian and Mexican enterprises. Understanding these divisions exposes where margin concentrates and which architectural choices dominate capital allocation decisions.
Product Type:
After-sales service intensity varies sharply across product categories, with hardware demanding field maintenance networks while software relies on remote update channels.
- Software:Applications and platforms delivered through subscription or perpetual licensing models, spanning ERP systems to specialized compliance tooling. São Paulo financial institutions drive demand for regulatory technology stacks that embed LGPD audit automation directly into transaction workflows.
- Hardware:Physical computing infrastructure including servers, storage arrays, and networking equipment subject to ANATEL certification requirements. Import lead times of 4-8 months constrain rapid scaling for Mexican manufacturing corridors seeking on-premises capacity expansion.
- Services:Professional and managed service engagements covering implementation, optimization, and ongoing operational support.
- Networking:Telecommunications infrastructure spanning fiber backbone, wireless access, and submarine cable connectivity.
By volume, Hardware leads. By growth pace, Software is ahead.
Deployment:
Cost tier stratification separates capital-intensive ownership models from consumption-based alternatives, with hybrid architectures commanding premium pricing for flexibility.
- Cloud:Public and private cloud infrastructure delivered through hyperscale or regional provider networks. Brazilian banks accelerate migration to meet LGPD data residency requirements while avoiding dollar-denominated pricing volatility through local provider partnerships.
- Hybrid:Integrated environments combining on-premises assets with cloud burst capacity, favored by healthcare providers managing patient data sovereignty alongside analytics scalability.
- On-Premises:Traditional data center ownership models retaining full physical control over infrastructure.
- Edge:Distributed computing nodes positioned close to data generation points for latency-critical applications.
By volume, On-Premises leads. By expansion trajectory, Cloud is climbing the fastest.
End User:
Application criticality determines procurement sophistication, with financial services and healthcare verticals driving compliance-embedded specifications.
- IT & Telecom:Technology sector enterprises and telecommunications operators constituting both vendor and consumer roles. Telefônica Brasil and Claro deploy network function virtualization across São Paulo and Rio de Janeiro metro zones, reducing hardware dependency per subscriber.
- Government:Federal, state, and municipal public sector entities with procurement governed by transparency mandates and localization preferences. Brazil's central bank instant payment infrastructure modernization creates demand for low-latency transaction platforms.
- Healthcare:Hospitals, clinics, and health systems managing patient data under LGPD enforcement escalation.
- Education:Universities and K-12 institutions adopting learning management and administrative systems.
By volume, IT & Telecom leads. By policy tailwinds, Government is gaining share fastest.
Service Type:
Customer maturity separates transactional engagements from strategic partnerships, with managed services capturing long-term recurring revenue pools.
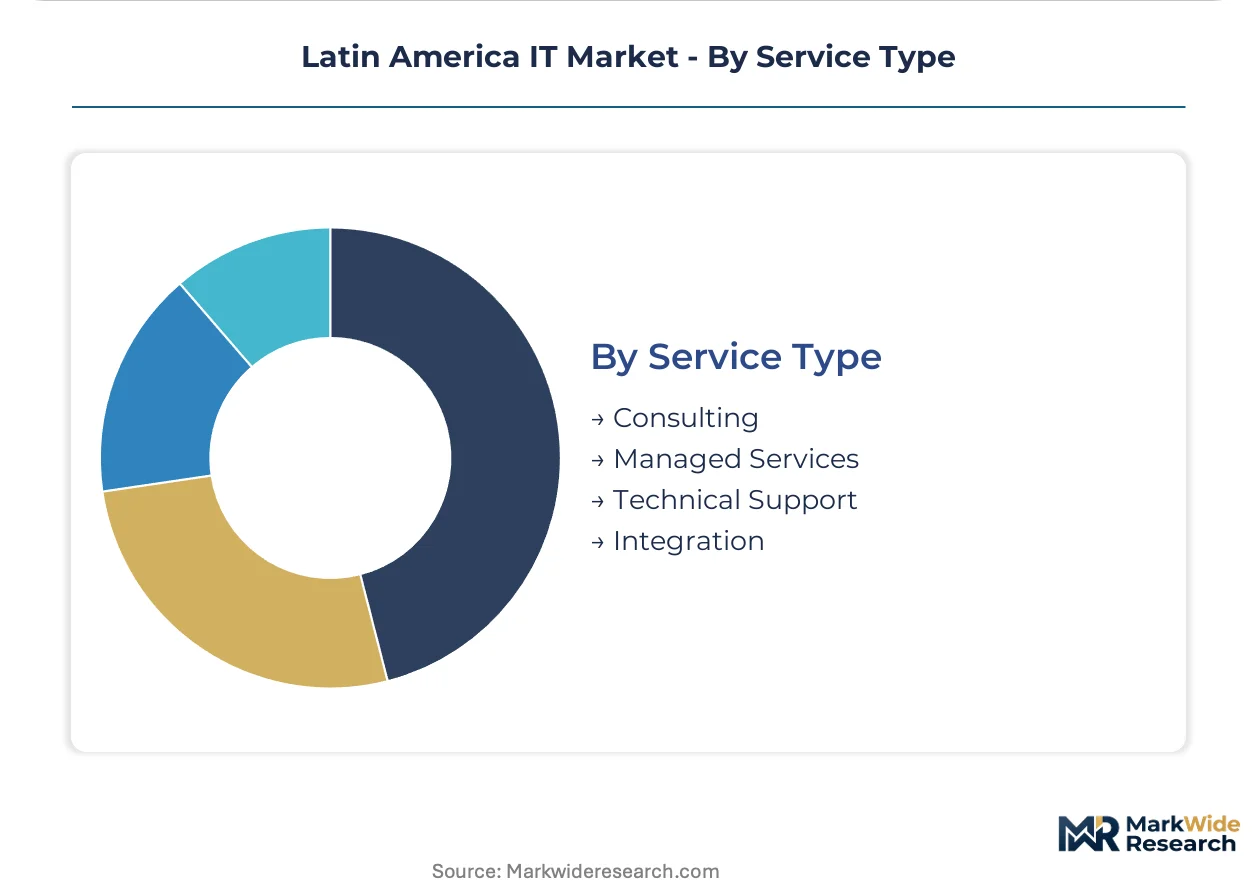
- Managed Services:Comprehensive outsourcing of IT operations including infrastructure monitoring, security management, and platform maintenance. Monterrey automotive suppliers favor operational expenditure models aligning IT spending with production volume fluctuations.
- Integration:System interoperability projects connecting legacy COBOL mainframes to modern API architectures. Brazilian banks dedicate 40-60% of modernization budgets to middleware development bridging 1980s core systems with open banking interfaces.
- Consulting:Advisory engagements spanning digital strategy, compliance roadmap development, and vendor selection.
- Technical Support:Break-fix and maintenance services for deployed infrastructure and applications.
By volume, Technical Support leads. By margin expansion, Managed Services is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise software procurement concentrates in São Paulo's technology corridor and Mexico City's enterprise cluster, with financial services and telecommunications verticals commanding premium IT spending across metropolitan technology hubs.
Brazil
LGPD enforcement escalation drives compliance software procurement across healthcare and banking verticals. ANATEL certification requirements extend hardware import timelines by 4-8 months, constraining rapid infrastructure scaling. São Paulo anchors demand concentration, with financial institutions accelerating cloud migration to meet data residency mandates.
Mexico
Central bank instant payment infrastructure modernization compels core banking platform upgrades. IFETEL spectrum regulations govern telecommunications service launch velocities and hardware deployment schedules. Mexico City's enterprise software cluster attracts specialized vendor ecosystems serving manufacturing and financial services verticals.
Colombia
Bogotá and Medellín enterprise markets demonstrate underpenetrated cloud adoption relative to regional peers, creating positioning opportunities for localized data center operators. The national data protection authority shapes vendor selection criteria for cross-border data architectures. Medellín's emerging technology corridor draws engineering talent for nearshore delivery operations.
Argentina
Precision agriculture IoT deployments in the Pampas region require sub-20 millisecond edge processing for autonomous equipment coordination. Central bank digital currency framework development creates interoperability demands on core banking infrastructure. Buenos Aires concentrates financial services IT spending amid currency volatility pressures on dollar-denominated cloud procurement.
Chile
Mining sector operational technology investments drive demand for industrial IoT platforms and edge computing nodes. The national telecommunications regulator governs spectrum allocation for private 5G networks serving remote extraction sites. Santiago's financial services sector modernizes payment rails to interoperate with regional instant settlement systems.
Latin America IT Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. Telecommunications operators leverage fiber backbone assets to dominate last-mile connectivity, while digital-native fintechs exploit cloud-native architectures to compress cost structures. Three archetypes define competitive positioning: infrastructure-owning incumbents, asset-light digital challengers, and nearshore delivery specialists. Dominant competitive moves include sovereign-backed project finance for hyperscale data centers and vertical integration into compliance-embedded software stacks.
Within the digital-native challenger tier, Nu Holdings exemplifies asset-light operational models that sustain cost advantages across retail banking. Among nearshore delivery specialists, BairesDev and 10Pearls occupy positions anchoring regional engineering capacity for North American enterprise clients. Telefônica Brasil represents infrastructure-owning incumbents competing through fiber backbone investments that dominate southeastern state connectivity.
| Leading Market Players |
|---|
| Nu Holdings (Nubank) |
| BairesDev |
| América Móvil |
| 10Pearls |
| Gorilla Logic |
| Telefônica Brasil |
| N-iX |
| Sparq |
| Claro Telecom Participações |
| Others |
Value Chain & Pricing Dynamics
Panama Canal transit cost volatility shapes Latin America IT hardware procurement economics, compressing margin structures for dollar-denominated cloud infrastructure while amplifying price differentiation between regional hyperscale deployments and foreign public cloud alternatives. Brazilian ANATEL certification timelines and Mexican IFETEL spectrum queues extend delivery windows, forcing buyers into premium expedited channels or delayed standard fulfillment tiers.
Pricing Analysis
Cost-plus contracts indexed to USD-BRL and USD-MXN exchange rate movements dominate hyperscale infrastructure procurement, transferring currency volatility risk to Latin American enterprise buyers. Price differentiation rests on ANATEL certification tier and data residency compliance level, with fully certified, LGPD-audited deployments commanding substantial premiums over uncertified alternatives. Pricing pressure stems from sovereign cloud mandates requiring architectural redesigns toward higher-cost local deployments. Mid-market manufacturing enterprises in Monterrey and Guadalajara exhibit highest price sensitivity, while São Paulo financial institutions prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates server and networking equipment procurement risk profiles, with ANATEL certification bottlenecks compounding import timeline uncertainty. Hardware supply concentrates in China, Taiwan, and South Korea for semiconductor components and server assembly. Raw material dependencies span advanced lithography equipment, high-purity silicon wafers, and specialized cooling systems. Distribution runs through Miami and Los Angeles submarine cable landing points, creating single-point-of-failure vulnerability for cross-border data traffic. Regional assembly partnerships in Mexico and Brazil are emerging to compress certification lead times and bypass direct import constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America IT market fragmentation creates niche positioning opportunities as LGPD enforcement and instant payment infrastructure modernization splinter demand across compliance-embedded software stacks, edge computing nodes, and sovereign cloud architectures. Sovereign data localization mandates are fragmenting previously consolidated procurement patterns toward specialized regional providers.
For Market Incumbents: Harden competitive moats through captive data center capacity in São Paulo and Mexico City technology corridors, securing ANATEL and IFETEL pre-certification for hardware portfolios to compress rival launch velocities. Threat exposure centers on digital-native challengers exploiting cloud-native cost structures and asset-light operational models. Priority levers include backward integration into fiber backbone assets and in-house production of compliance-as-code tooling. For New Entrants and Emerging Players: Colombian Andean enterprise markets in Bogotá and Medellín represent the most penetrable entry point, with cloud adoption gaps of 40-60% relative to São Paulo benchmarks creating first-mover positioning potential. Edge computing deployments for precision agriculture in Brazil's Mato Grosso and Argentina's Pampas regions offer specialized vertical entry. Go-to-market execution should anchor on regulatory technology convergence platforms unifying LGPD compliance with open banking API infrastructure. For Investors and Strategic Acquirers: Asset-light digital challengers with captive compliance engineering capabilities and established hyperscaler partnership networks constitute the highest-conviction acquisition archetype. Long-term viability hinges on sustained localization mandate enforcement and central bank digital currency interoperability demands across the projection horizon. The signal to watch is ANATEL certification queue compression timelines, which would erode expedited-channel pricing premiums and reshape competitive dynamics toward scale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscale Data Center Localization | Sovereign data residency mandates in Brazil and Mexico favor regional deployments over foreign public cloud reliance. |
| Compliance-as-Code Platform Development | LGPD penalty escalation to 2% of Brazilian revenue embeds audit automation into procurement specifications. |
| Network Function Virtualization Deployment | Telefônica Brasil and Claro reduce hardware dependency per subscriber through virtualized radio access networks. |
| Edge Computing Node Expansion | Sub-20 millisecond latency requirements for precision agriculture IoT in Mato Grosso and Pampas regions drive distributed infrastructure. |
| Nearshore Delivery Capacity Acquisition | BairesDev and 10Pearls anchor regional engineering talent for North American enterprise client retention. |
Study Parameters
Initial hypotheses were tested against primary input from cloud infrastructure procurement officers, data center operations directors, regulatory compliance leads, and telecommunications network planners, then refined through secondary validation against ANATEL certification databases, IFETEL spectrum allocation records, central bank instant payment infrastructure disclosures, and hyperscaler capital expenditure filings. Bottom-up demand modeling across deployment categories and top-down macroeconomic scenario analysis were triangulated to constrain forecast variance.
Demand-supply balance dynamics across the projection horizon were modeled through segmented adoption curves for cloud, hybrid, and edge deployment architectures, with organization size tiers and vertical-specific compliance intensity serving as cross-cutting segmentation dimensions. CAGRs were derived from installed base evolution and replacement cycle analysis. Industry-specific forecast inputs included LGPD enforcement penalty escalation trajectories and central bank digital currency interoperability specifications.
Stress conditions across BRL and MXN exchange rate bands, ANATEL certification timeline extensions, and submarine cable connectivity disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and infrastructure investment commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Route Optimization Software Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Ediscovery Solution Market
Digital Solutions
US Customer Communication Management (CCM) Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
Global Service Integration and Management Market