
 English Language Testing Market | 2026-2036
English Language Testing Market Size, Share, and Industry Trends Forecast 2026-2036
English Language Testing Market Intelligence
Modular test bundling is repositioning how institutions procure language credentials, unbundling single-exam packages into component skills assessments that buyers mix across providers. EF Education First leverages its vertically integrated language schools to anchor institutional contracts in Europe and Asia. Pearson ELT competes through its computer-based PTE Academic suite, while Educational Testing Service sustains brand dominance through the TOEFL iBT network and embedded university partnerships.
English language testing comprises standardized assessment instruments that measure reading, writing, listening, and speaking proficiency against calibrated frameworks such as the Common European Framework of Reference for Languages, with scores typically reported on 0-120 or 0-9 scales for visa and admissions decisions. Test type segmentation shows TOEFL and IELTS occupying mature, high-volume positions, while PTE gains share through faster score turnaround and AI scoring. Test format dynamics reveal online and hybrid modalities capturing growth as computer-based delivery displaces paper-based administration in major markets.
Regulatory frameworks including the UK's Home Office approved Secure English Language Test list, Australia's Department of Home Affairs skills assessment requirements, and ETS alignment with US institutional accreditors shape which credentials gain market access and visa eligibility. Immigration policy tightening in traditional destination countries is redirecting test-taker flows toward Canada and emerging European hubs. Stakeholders must monitor how credential recognition agreements between national regulators and test providers evolve to anticipate which assessment standards gain cross-border portability.
Market Dynamics
AI-proctored test delivery is compressing credential verification timelines from weeks to days, forcing incumbent providers to reengineer scoring infrastructure and security protocols around machine learning-based identity validation and response pattern analysis.
Growth Catalysts
- UK Home Office Secure English Language Test mandate:Immigration rules requiring approved providers for visa categories sustain institutional procurement volume and limit competitor entry.
- India's outbound student mobility:Test-taker concentration in metropolitan coaching clusters generates sustained demand for high-frequency test scheduling and localized preparation services.
- Computer-based delivery platforms:Faster score turnaround and flexible scheduling windows attract time-sensitive applicants facing admissions deadlines.
Market Restraints
- Development cost concentration:Calibrated item banks and psychometric validation require sustained investment that smaller providers cannot replicate.
- Regulatory fragmentation:Divergent approval requirements across the UK, Australia, and Canada force redundant compliance expenditure for multi-market credentials.
- Substitution from internal university assessments:Some institutions are developing in-house English proficiency screening to reduce dependency on external test fees.
Strategic Opportunities
- Canada's immigration intake expansion:Federal skilled worker and study permit volume growth creates demand for additional approved test center capacity.
- Skills-based modular assessment:Unbundled component testing allows employers to verify specific workplace communication competencies rather than general academic proficiency.
- Mobile-first test preparation:Smartphone-based adaptive learning modules penetrate price-sensitive segments unreachable through classroom coaching.
Industry Challenges
- AI security arms race:Deepfake-enabled impersonation and proxy testing require continuous algorithmic upgrade cycles that strain operational budgets.
- Legacy system integration:University admissions platforms with decades-old data architectures resist API-based score transmission without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | English Language Testing Market |
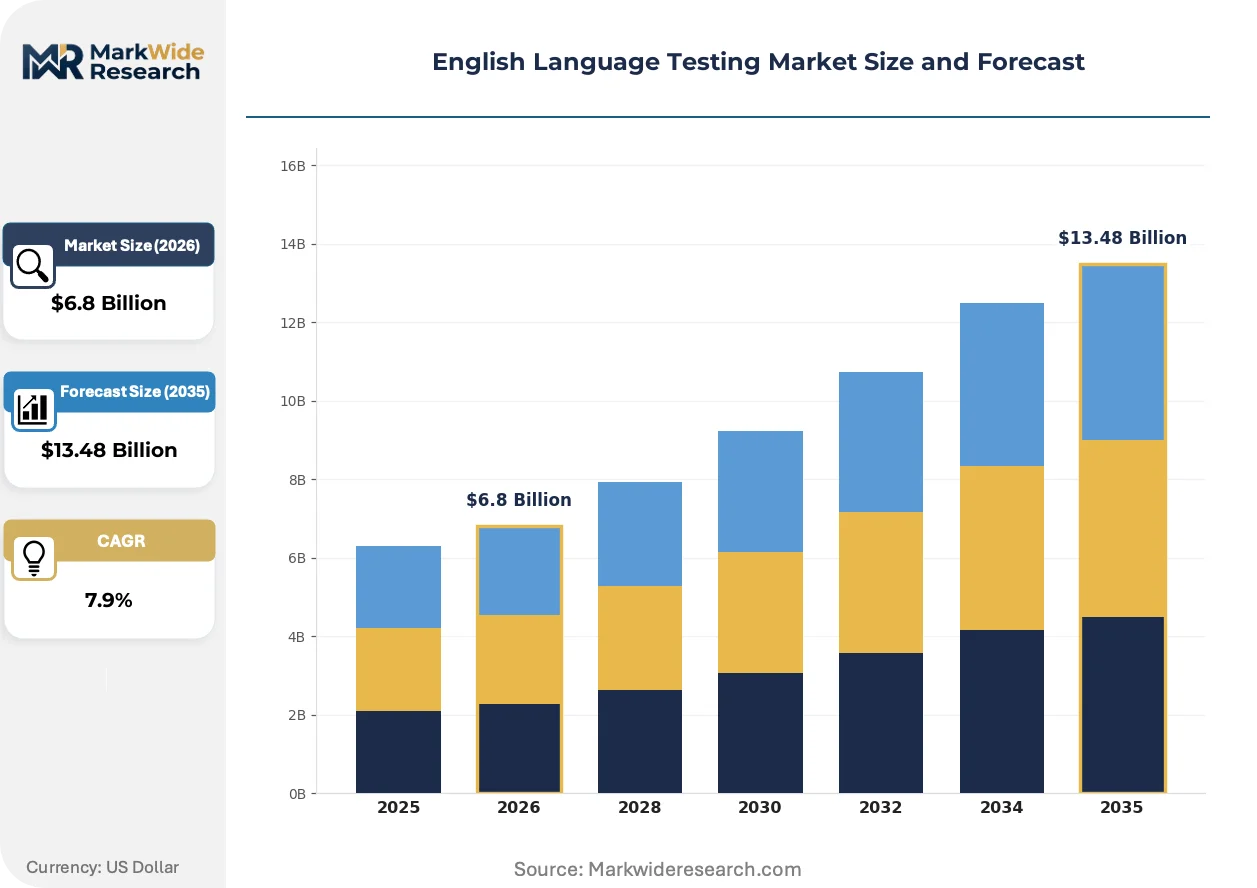
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: TOEFL, IELTS, CELPIP, PTE Purpose: Academic, Professional, Immigration, Employment Test Format: Online, Paper-Based, Hybrid, Computer-Based Target Audience: Students, Professionals, Immigrants, Institutions |
| Companies Covered | EF Education First, Berlitz Corporation, Educational Testing Service (ETS), New Oriental Education & Technology Group Inc., British Council, Pearson ELT, Language Testing International, McGraw Hill Education, Cambridge Assessment English, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
English Language Testing Market Strategic Shifts & Innovations
Adaptive testing algorithms and biometric identity verification are compressing the traditional test development cycle, enabling providers to release calibrated items faster while raising the technical bar for market entry.
Machine learning-based spoken response scoring is expanding into high-stakes admissions decisions previously reserved for human examiner evaluation. Top-tier business schools and engineering programs in the United States and United Kingdom are piloting these systems for applicant screening. The compression of scoring labor costs is enabling price competition against established human-scored alternatives.
Australia's Department of Home Affairs skills assessment requirements are tightening evidentiary standards for English proficiency in permanent residency pathways. The policy shift elevates credential recognition criteria and pressures providers to demonstrate test security rigor through independent audit. Regional test centers are responding with enhanced biometric capture and session monitoring investments.
Institutional procurement is fragmenting across multiple credential types rather than consolidating on single-provider contracts. Large university systems in India and Southeast Asia are negotiating volume discounts across TOEFL, IELTS, and PTE simultaneously. The unbundling trend is visible most acutely in metropolitan markets where test center density permits applicant choice.
English Language Testing Market Segmentation
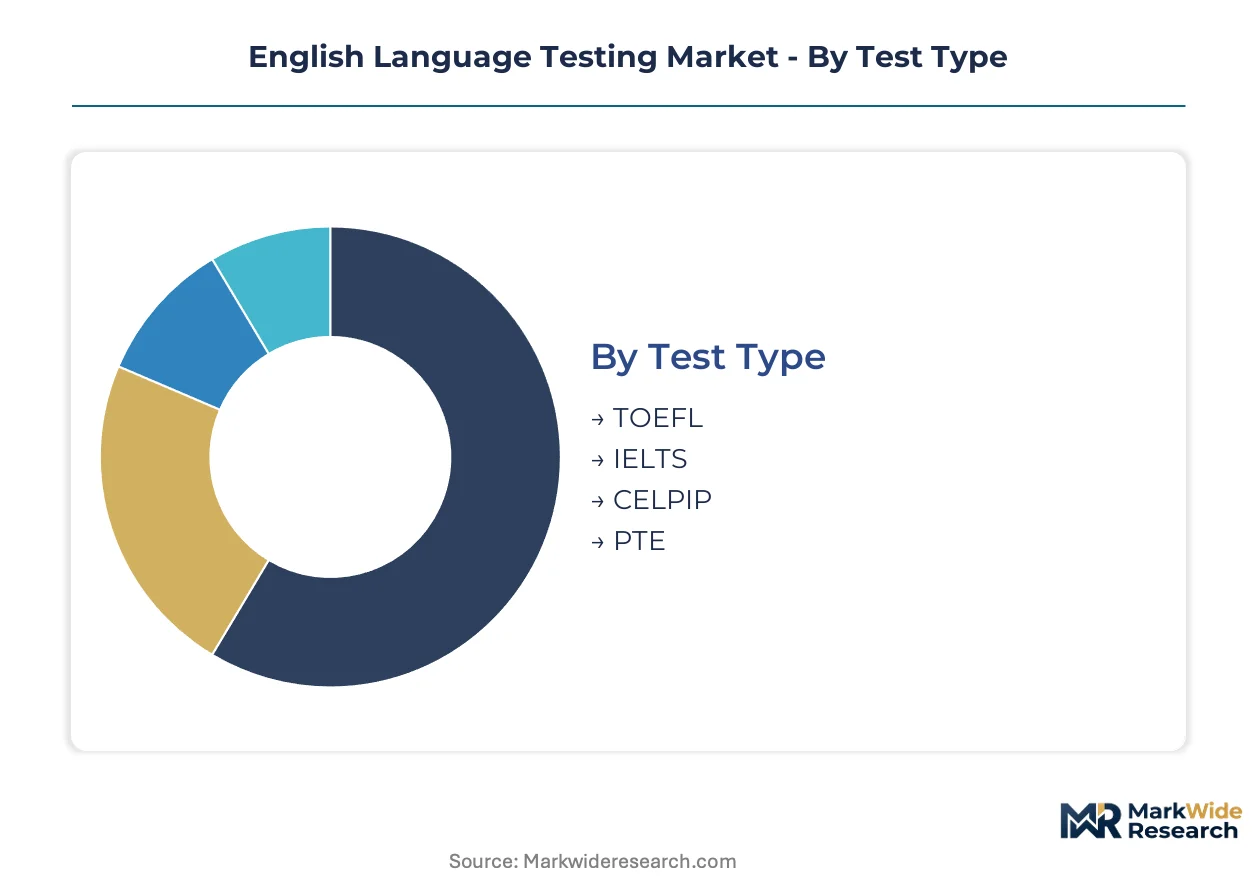
Segmentation in English language testing reveals how credential procurement fragments across delivery modalities, regulatory pathways, and applicant profiles. Test providers calibrate product architecture around distinct visa categories and institutional admissions workflows.
Test Type:
Test type classification follows the psychometric architecture and scoring methodology that each credential employs for proficiency measurement.
- TOEFL:Internet-based delivery with integrated academic English tasks scored on a 0-120 scale. Demand concentrates in United States university admissions pipelines, where institutional partnerships with ETS sustain procurement volume through embedded score reporting systems.
- IELTS:Dual Academic and General Training modules with human examiner evaluation of spoken responses. British, Australian, and Canadian visa categories drive concentrated demand, particularly through the UK's Home Office Secure English Language Test mandate that restricts eligible providers.
- CELPIP:Canadian English Language Proficiency Index Program optimized for Canadian immigration pathways. IRCC designation for permanent residency applications anchors its market position.
- PTE:Pearson Test of English employing AI scoring for all skill components with 48-hour result turnaround. Computer-native architecture attracts time-sensitive applicants facing tight admissions deadlines.
TOEFL leads on scale through decades of institutional embedding; PTE leads on momentum through AI-enabled speed advantages.
Purpose:
Purpose segmentation tracks how regulatory frameworks and institutional requirements shape which credential types applicants must procure.
- Academic:University and college admissions requiring proof of English proficiency for degree program entry. United States, United Kingdom, and Australian institutions sustain the highest volume concentration.
- Professional:Licensing bodies and certification authorities mandating language benchmarks for credential recognition. Medical councils and engineering accreditation boards dominate this pathway.
- Immigration:Visa categories specifying approved language tests for permanent residency and citizenship applications. Australia's Department of Home Affairs and Canada's IRCC maintain the most prescriptive approved-test lists.
- Employment:Corporate recruitment screening and intra-company transfer verification. Multinational employers in technology and finance sectors are expanding internal language assessment adoption.
Academic purpose dominates current volume; immigration purpose is climbing the fastest as policy pathways expand in Canada and Australia.
Test Format:
Format segmentation captures the infrastructure and delivery modality through which assessments reach test-takers.
- Online:Fully remote proctored delivery with AI-powered identity verification and session monitoring. Pandemic-era infrastructure investments accelerated provider capability in this modality.
- Paper-Based:Traditional in-person administration with physical test booklets and human-scored written responses. Declining share except in regions with limited digital infrastructure.
- Hybrid:Mixed delivery combining computer-based testing with human examiner evaluation for speaking components. IELTS employs this architecture to balance automation with human judgment.
- Computer-Based:Fixed-location digital delivery with on-screen input and automated scoring for most sections. Flexible scheduling windows attract applicants with tight deadlines.
Computer-based delivery holds installed base leadership; online proctored formats are gaining share fastest through convenience and accessibility expansion.
Target Audience:
Audience segmentation distinguishes how procurement authority and decision-making criteria vary across applicant categories.
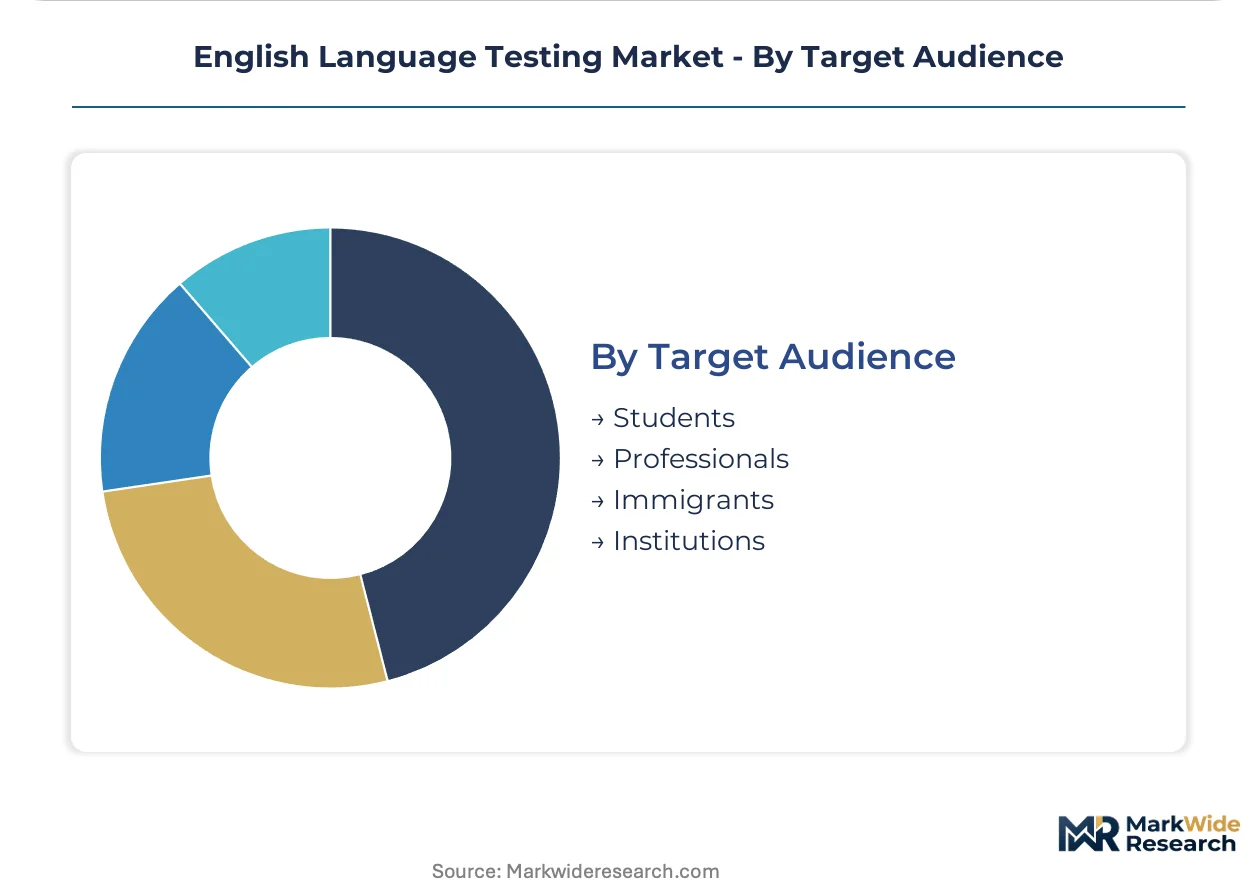
- Students:Undergraduate and graduate degree seekers navigating admissions requirements. India's metropolitan coaching clusters generate the highest concentration of test-taker volume globally.
- Professionals:Skilled workers seeking credential recognition or career mobility. Healthcare and information technology occupations show the steepest demand trajectory.
- Immigrants:Family reunification and economic migration applicants facing visa-mandated language thresholds. Canada's expanded immigration intake targets are redirecting flows from traditional destinations.
- Institutions:Universities, employers, and government agencies procuring assessments for screening or verification. Procurement is fragmenting across multiple credential types rather than consolidating on single-provider contracts.
Students anchor current scale; professionals are expanding most quickly through skills-based migration pathway growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The English language testing industry traces its modern commercial scale to post-war standardization efforts in the United Kingdom and the United States, where academic exchange programs first demanded calibrated proficiency benchmarks for visa screening and university admissions.
United States
University admissions pipelines and skilled worker visa categories sustain concentrated demand for TOEFL credentials. ETS alignment with US institutional accreditors shapes which assessments gain recognition across degree programs. Test center density peaks in metropolitan corridors spanning Boston, New York, and California's university clusters.
United Kingdom
The Home Office Secure English Language Test mandate restricts eligible providers for visa categories, anchoring procurement volume for approved credentials. British Council and Cambridge Assessment English maintain institutional relationships with universities and immigration authorities. London and Manchester coaching clusters generate sustained test-taker throughput.
India
Outbound student mobility and skilled migration applications concentrate global test-taker volume in metropolitan coaching hubs. DGFT and Ministry of External Affairs frameworks support credential recognition for emigration clearance. Delhi-NCR, Mumbai, and Bengaluru sustain the highest scheduling frequency for IELTS and PTE examinations.
Australia
Department of Home Affairs skills assessment requirements tighten evidentiary standards for permanent residency pathways. TGA and immigration authorities maintain prescriptive approved-test lists that elevate credential recognition criteria. Sydney and Melbourne test centers respond with enhanced biometric capture and session monitoring investments.
Canada
IRCC designation for permanent residency applications and expanded federal skilled worker targets redirect test-taker flows from traditional destinations. Immigration intake expansion creates demand for additional approved test center capacity. Toronto and Vancouver anchor credential procurement for economic migration and study permit pathways.
English Language Testing Market Key Industry Players
Premium-margin players sit above commodity-margin players across psychometric rigor and institutional embedding depth. The vendor base organizes into three tiers: established credential networks with decades of university partnerships, technology-native challengers leveraging AI scoring speed, and regional preparation services capturing coaching revenue. Consolidation pressure favors providers with calibrated item banks and multi-market regulatory approvals. Dominant competitive moves include strategic partnerships with immigration authorities and portfolio diversification into modular skills assessments.
Within the established credential network tier, Educational Testing Service and British Council exemplify institutional embedding through embedded score reporting systems and government-mandated visa eligibility. Pearson ELT occupies a position among technology-native challengers, representing the shift toward computer-native architecture and automated scoring turnaround. EF Education First anchors the vertical integration archetype, combining language school operations with assessment procurement to capture preparation-to-credential value chains.
| Leading Market Players |
|---|
| EF Education First |
| Berlitz Corporation |
| Educational Testing Service (ETS) |
| New Oriental Education & Technology Group Inc. |
| British Council |
| Pearson ELT |
| Language Testing International |
| McGraw Hill Education |
| Cambridge Assessment English |
| Others |
Cost & Logistics Intelligence
Family-owned coaching conglomerates across India and Southeast Asia anchor supply-side discipline through backward integration into test preparation, extracting margin from bundled credential-to-classroom value chains while exerting pricing pressure on standalone test providers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-proctored premium delivery from fixed-center standard slots and paper-based economy alternatives. Price differentiation rests on turnaround speed and biometric security tier, with fastest-score credentials commanding material premiums. Cost compression in the economy tier is intensifying because coaching centers bundle preparation with test registration. Students facing tight admissions deadlines show least price sensitivity; price-conscious repeat test-takers drive volume in economy segments.
Supply Chain Analysis
Test center equipment refresh cycles and biometric hardware refurbishment flows concentrate service revenue in India, the United Kingdom, and Australia. Raw material dependencies span secure browser software licenses, facial recognition SDKs, and server infrastructure for AI scoring. Single-source vulnerability in proctoring algorithm providers elevates operational risk. Distribution runs through university partnerships and immigration authority approved-center networks rather than open retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as institutional procurement shifts toward AI-scored credentials with demonstrable security audit trails over legacy human-scored alternatives.
For Market Incumbents: Deploy psychometric calibration investments to defend position against technology-native challengers. Deepen university score reporting system embedding to raise switching costs. Accelerate biometric security upgrades to counter deepfake-enabled proxy testing threats. For New Entrants and Emerging Players: Mobile-first test preparation apps represent the most penetrable white-space for reaching price-sensitive segments outside metropolitan coaching clusters. Target professionals seeking skills-based modular assessment for Canadian immigration pathways. Pursue direct-to-test-taker subscription models bypassing institutional procurement gatekeepers. For Investors and Strategic Acquirers: Education technology conglomerates are the most active acquirer in this space, rolling up regional preparation services to capture credential-to-classroom margins. Long-term viability favors providers with multi-market regulatory approvals and calibrated item banks. Monitor Home Office and IRCC credential recognition list changes as inflection indicators for competitive position shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Scoring Infrastructure Deployment | Pearson ELT's automated turnaround compresses competitor response times across admissions pipelines. |
| Biometric Security Certification | Independent audit trails satisfy Australia's Department of Home Affairs tightening evidentiary standards. |
| Modular Skills Assessment Launch | Unbundled component testing penetrates employer verification markets beyond academic admissions. |
| Mobile Preparation Platform Integration | Smartphone-based adaptive modules reach price-sensitive test-takers unreachable through classroom coaching. |
| Multi-Market Regulatory Approval | UK Home Office SELT and Canadian IRCC designations secure visa-mandated procurement volume. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Australia, with primary inputs from each region combining interviews with test center operations directors, university admissions officers, immigration authority policy leads, and coaching center franchise owners. Secondary validation draws from Home Office approved-test registers, IRCC designation records, university procurement disclosures, and skills assessment regulatory filings. Bottom-up test-taker volume estimates triangulate against top-down credential revenue analysis.
Granularity-level modeling disaggregates projections by test type, purpose category, delivery format, and target audience across the analysis window. CAGRs derive from trend extrapolation calibrated to policy pathway expansion rates and institutional procurement pattern shifts. Forecast inputs incorporate immigration intake targets, university international enrollment trajectories, and technology adoption curves for AI-proctored delivery.
The model assumes a particular technology adoption path; alternative pathways for deepfake detection algorithms would alter the outlook. Forecasts reflect assumptions regarding regulatory list stability and institutional procurement fragmentation. Practitioners should monitor Home Office SELT list revisions, IRCC designation updates, and university in-house assessment pilot programs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Asia Big Data Analytics in Education Market
Education & Training
US Child Care Market
Education & Training
Canada Outplacement Services Market
Education & Training
Children's Programming Education Market
Education & Training
Business Coaching Service Market
Education & Training
Global Alumni Management Software Market
Education & Training
Artificial Intelligence in the Education Sector Market
Education & Training
Corporate Training Software Market
Education & Training
Asia-Pacific Corporate Training Market
Education & Training
VR Education Market
Education & Training
Europe Executive Search (Headhunting) Market
Education & Training
Asia Pacific Strategic Consulting Services Market
Education & Training
Virtual Schools Market
Education & Training
Higher Education Student CRM Solutions Market
Education & Training
United States HR Professional Service Market
Education & Training
Blockchain in Edutech Market