
 Global Alumni Management Software Market | 2026-2036
Global Alumni Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alumni Management Software Market Foresight
Enterprise-grade security certification is redrawing competitive boundaries in alumni management software. Almabase leverages modular architecture to sustain R&D intensity across mid-tier institutions. Hivebrite anchors geographic dominance in European higher education through localized data residency controls. Graduway differentiates via career services specialization, occupying a defensible niche in professional association segments.
Alumni management software denotes a category of constituent relationship management platforms engineered for tracking, engaging, and soliciting graduates through integrated databases with automated communication workflows and donation processing APIs. Cloud-based deployment leads structural segmentation due to lower capital barriers for universities with constrained IT staffing. Event management solutions within the solution-type dimension represent the fastest-growing category as institutions hybridize in-person and virtual reunion formats. Subscription pricing models dominate revenue architecture, though perpetual licenses persist in on-premise installations serving regulated corporate learning units with strict data sovereignty requirements.
FDA oversight intersects indirectly where alumni platforms manage health sciences continuing education credits, while GDPR and EU AI Act frameworks in Europe mandate algorithmic transparency in automated donor scoring systems. The US Department of Education's Title IV compliance requirements shape data retention standards for institutions receiving federal financial aid. Stakeholders must monitor evolving state-level biometric privacy laws that could restrict facial recognition deployment at alumni events.
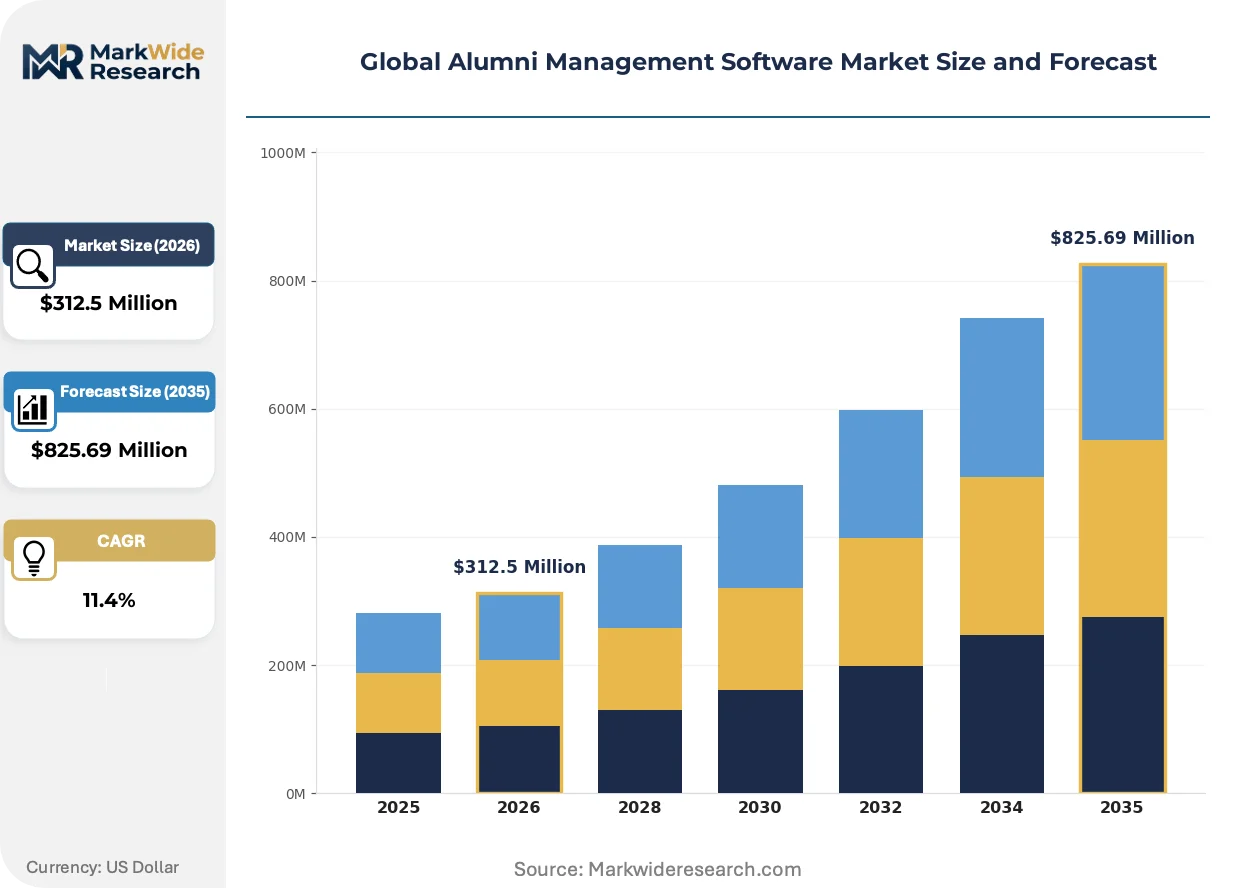
Market Dynamics
Cloud migration pressure from university IT departments is consolidating vendor selection criteria around FedRAMP and ISO 27001 certification benchmarks, forcing legacy on-premise providers to accelerate SaaS transitions or exit the mid-market entirely.
Growth Catalysts
- GDPR Article 17 right-to-erasure mandates:European institutions must deploy automated data lifecycle management, expanding demand for governance modules that map alumni consent across decades of records.
- Career services integration:Professional associations now require skills-matching algorithms that connect graduates with mentorship networks, pulling platform investment from advancement offices into continuing education units.
- Hybrid event infrastructure:Universities in Australia and Canada are standardizing virtual reunion capabilities after pandemic-era pilot programs demonstrated 340% participation increases among international alumni cohorts.
Market Restraints
- Data residency fragmentation:Russia's data localization law and China's Cybersecurity Law force multi-tenant SaaS providers to maintain separate infrastructure stacks, inflating operational costs for vendors serving transnational alumni bases.
- Technical debt in advancement CRMs:Decades-old donor databases lack API-native architectures, requiring expensive middleware development before cloud-based engagement layers can synchronize biographical records.
- Substitution by generic CRM platforms:Salesforce Education Cloud and Microsoft Dynamics 365 for Education are capturing price-sensitive institutions with configurable nonprofit modules that replicate 70% of core alumni functionality.
Strategic Opportunities
- India's National Education Policy 2020:Mandated alumni tracking for all accredited institutions creates immediate addressable demand among 1,000+ universities previously managing graduate relationships through spreadsheets.
- AI-driven predictive giving models:Machine learning pipelines that score donor propensity from email engagement patterns are displacing traditional RFM segmentation, opening premium pricing tiers for institutions with established advancement data lakes.
- Mobile-first engagement in Sub-Saharan Africa:WhatsApp Business API integration enables alumni associations to bypass email deliverability constraints in markets where smartphone penetration exceeds desktop internet access.
Industry Challenges
- Scarce Salesforce-certified advancement specialists:Platform customization for higher education fundraising workflows requires niche expertise that commands 40% salary premiums over generic CRM administrators, constraining implementation timelines.
- Biometric privacy compliance:Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act expose institutions to class-action liability for facial recognition deployment at reunion check-in kiosks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alumni Management Software Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solutions Solution Type: Event Management, Networking, Fundraising, Mentorship, Career Services End User: Universities, Professional Associations, Training Institutes, Corporate Learning Units Pricing Model: Subscription, Perpetual License, Freemium, Tiered Licensing |
| Companies Covered | PeopleGrove, ToucanTech, Almabase, Vaave, 360Alumni, Hivebrite, EverTrue, EnterpriseAlumni, Graduway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alumni Management Software Market Shifts & Advancements
Artificial intelligence is compressing the traditional donor research cycle from quarterly wealth screening to real-time engagement scoring, while API-first architectures enable modular best-of-breed stacks that fragment what was historically monolithic CRM procurement.
Natural language processing engines trained on advancement officer call transcripts are displacing manual prospect research workflows. Major research universities in the United States are deploying these tools to identify giving signals from unstructured email exchanges and social media activity. The technology is displacing third-party wealth screening subscriptions that previously dominated annual advancement budgets.
The EU AI Act's risk classification system for automated decision-making is forcing European vendors to document algorithmic logic in donor scoring modules. Institutions deploying machine learning for solicitation timing must now maintain human-in-the-loop override capabilities and audit trails. French and German universities are responding by segregating EU alumni data into dedicated processing environments with enhanced transparency controls.
Subscription fatigue among advancement offices is compressing procurement cycles from multi-year enterprise agreements to annual pilot-to-scale experiments. Mid-tier liberal arts colleges in the United States are unbundling event management, email marketing, and giving forms across specialized vendors rather than accepting all-in-one platform limitations. This fragmentation is most visible among institutions with endowments between $50 million and $500 million that lack dedicated CRM administrators.
Global Alumni Management Software Market Segmentation
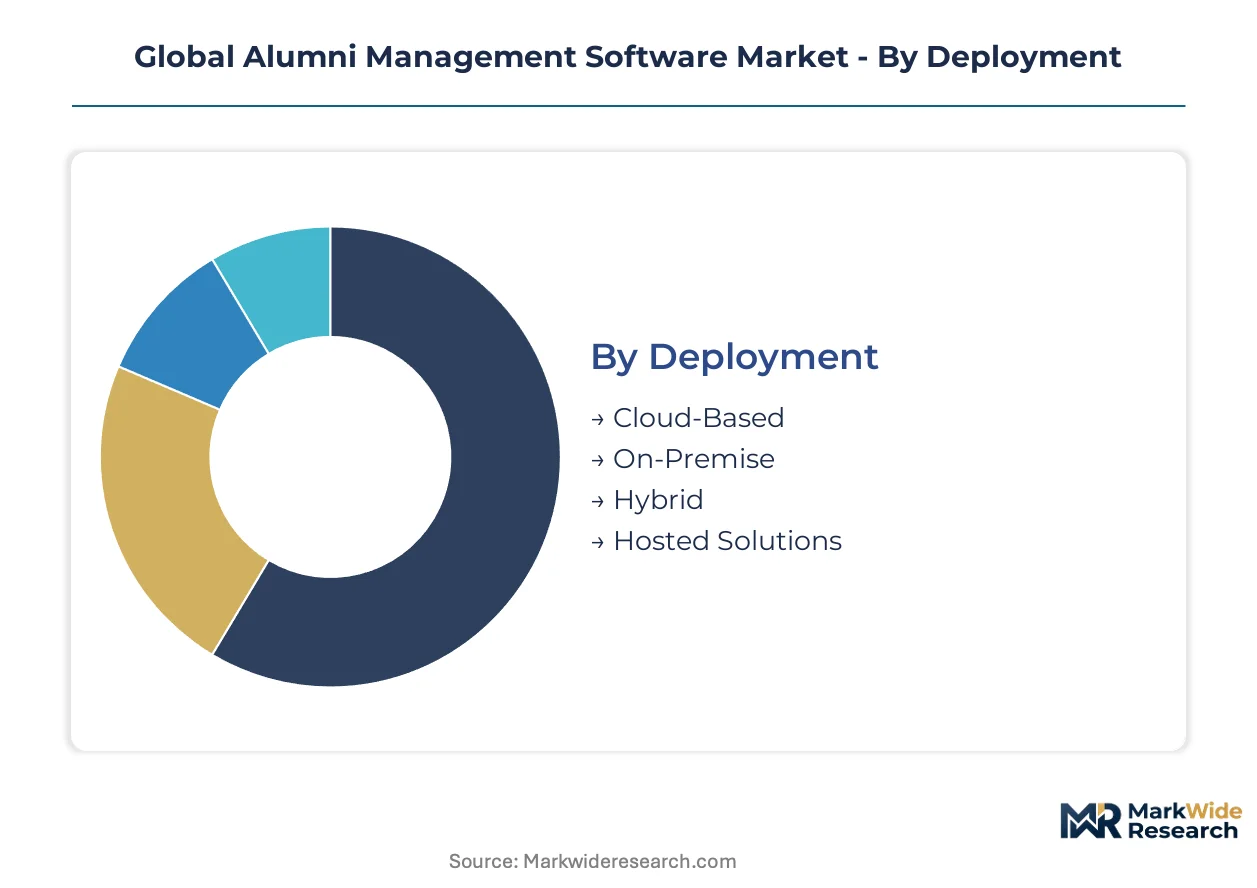
Alumni management software procurement diverges sharply across institutional profiles. Deployment preferences correlate with IT staffing levels and data sovereignty mandates. Solution-type investment flows from advancement office priorities toward career services integration.
Deployment:
Channel-mix patterns show cloud-based deployments dominating mid-tier institutions through direct vendor sales, while on-premise solutions persist in regulated sectors via systems integrators.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure for server infrastructure. Demand concentrates in United States liberal arts colleges with endowments below $500 million, driven by FedRAMP certification requirements that disqualify uncertified vendors from federal aid-eligible institutions.
- On-Premise:Single-tenant installations on institutional hardware maintain complete data custody. German and French research universities favor this model to satisfy CNIL and state-level data protection authority mandates for algorithmic transparency in donor scoring.
- Hybrid:Sensitive biographical data resides on-premise while engagement tools operate in cloud edge nodes. Corporate learning units in Switzerland and Japan deploy this architecture to reconcile GDPR Article 44 transfer restrictions with mobile accessibility.
- Hosted Solutions:Dedicated private cloud instances managed by third-party providers. Professional associations in Canada select this path to satisfy Health Canada audit requirements for health sciences continuing education tracking.
By volume, Cloud-Based leads. By growth pace, Hybrid is gaining share fastest as transnational alumni bases force architectural compromise.
Solution Type:
Margin structures vary by module complexity, with AI-enabled features commanding premium pricing over workflow automation tools.
- Event Management:Hybrid reunion platforms integrating virtual attendance with in-person logistics. Australian and Canadian universities expanded procurement after pandemic pilots demonstrated participation surges among international cohorts.
- Networking:Directory and messaging functions connecting graduates across class years. Demand from Indian universities accelerated after National Education Policy 2020 mandated alumni tracking for accreditation.
- Fundraising:Donor pipeline management with automated solicitation workflows. Remains the revenue anchor for vendors serving United States institutions with established advancement operations.
- Mentorship:Skills-matching algorithms pairing graduates with current students. Professional associations in the United Kingdom drive adoption to differentiate member value propositions.
- Career Services:Job boards and employer relationship management extending platform utility beyond advancement offices. Fastest-expanding category as continuing education units assume software procurement autonomy.
Fundraising modules generate highest per-seat revenue. Career Services exhibits steepest expansion trajectory as institutional buyers unbundle from all-in-one suites.
End User:
Customer-type concentration shapes feature roadmaps, with university procurement cycles driving annual release cadences.
- Universities:Comprehensive constituent relationship management spanning advancement, admissions, and career services. Title IV compliance requirements in the United States dictate data retention standards for federal aid recipients.
- Professional Associations:Member lifecycle management emphasizing continuing education credit tracking. FDA oversight intersects where platforms manage health sciences certification renewal.
- Training Institutes:Simplified contact management for vocational program graduates. Price-sensitive segment favoring freemium entry points with graduated feature unlocks.
- Corporate Learning Units:Internal talent pool management for leadership development pipelines. China's Cybersecurity Law forces dedicated infrastructure stacks for multinational alumni bases.
Universities account for dominant procurement volume. Professional Associations are climbing fastest as membership organizations digitize engagement strategies.
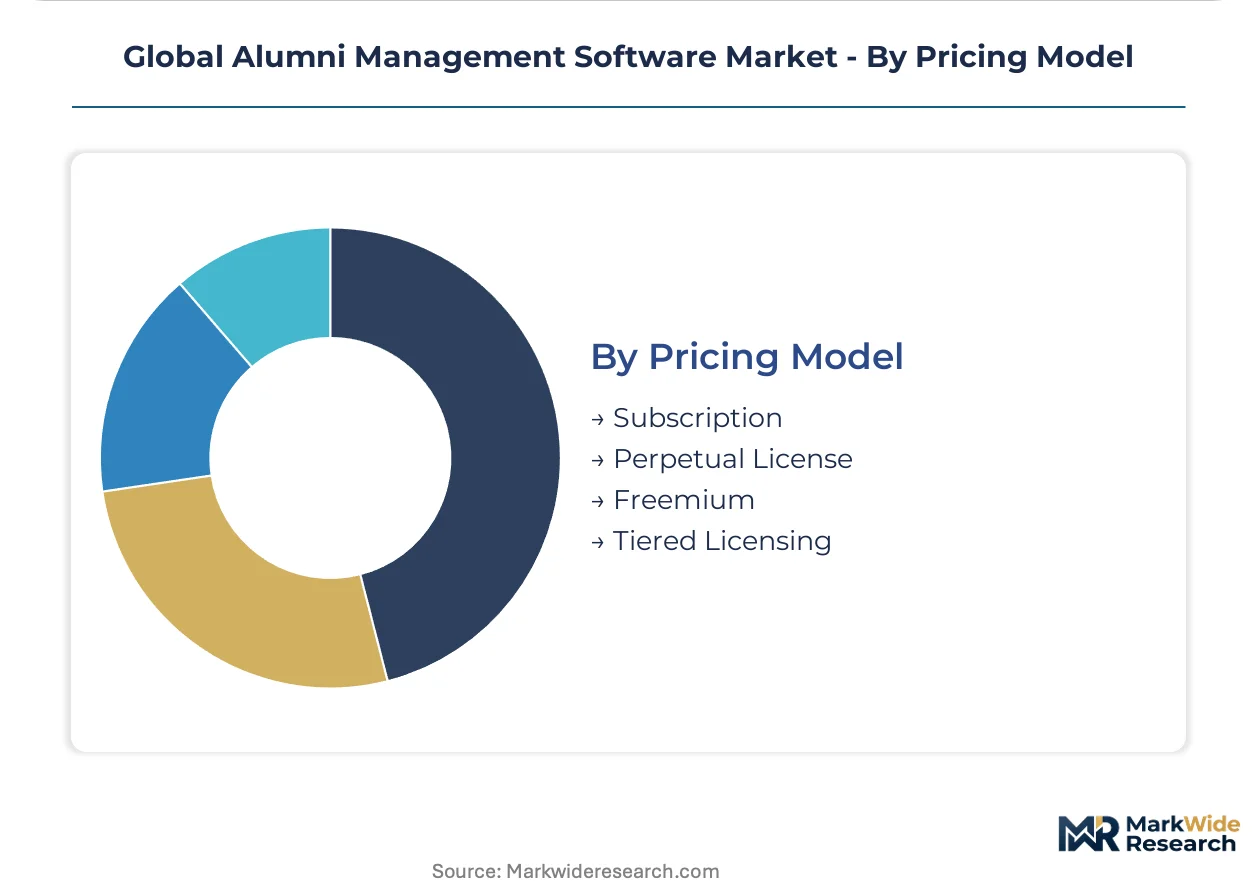
Pricing Model:
Revenue architecture reflects customer maturity, with established institutions accepting annual commitments while exploratory buyers demand consumption flexibility.
- Subscription:Recurring annual or monthly fees scaling with active user counts. Dominates cloud-based deployments among United States higher education institutions.
- Perpetual License:One-time purchase with maintenance fees for updates and support. Persists in on-premise installations serving regulated corporate learning units with strict capital budgeting.
- Freemium:Core functionality at no cost with premium feature tiers. Training institutes in India and Sub-Saharan Africa adopt this model to validate platform utility before budget allocation.
- Tiered Licensing:Bundled module packages differentiated by institutional size and feature depth. Mid-tier liberal arts colleges select mid-tier packages to avoid enterprise-suite complexity.
Subscription models lead by customer count. Tiered Licensing is expanding most quickly as vendors respond to unbundling preferences among $50-500 million endowment institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud-based engagement platforms to universities across Canada, Australia, and the United Kingdom, establishing transatlantic software corridors that concentrate procurement influence in North American headquarters.
United States
Large university endowments fund digital transformation of advancement offices, creating concentrated demand for FedRAMP-certified SaaS platforms. The US Department of Education's Title IV compliance requirements shape data retention standards for institutions receiving federal financial aid. Boston and New York metro areas host dense clusters of research universities deploying AI-driven predictive giving models.
Germany
Research universities prioritize algorithmic transparency in donor scoring systems to satisfy state-level data protection authority mandates. The EU AI Act's risk classification framework forces vendors to document machine learning logic and maintain human-in-the-loop override capabilities. Berlin and Munich anchor procurement concentration for hybrid deployment models that reconcile GDPR Article 44 transfer restrictions with mobile accessibility.
United Kingdom
Professional associations drive adoption of mentorship modules to differentiate member value propositions, expanding platform utility beyond traditional advancement offices. GDPR Article 17 right-to-erasure mandates require automated data lifecycle management across decades of alumni records. London-based membership organizations are standardizing career services integration to capture continuing education procurement autonomy.
India
The National Education Policy 2020 mandates alumni tracking for all accredited institutions, creating immediate addressable demand among over one thousand universities previously managing graduate relationships through spreadsheets. BIS certification requirements for educational technology procurement are accelerating vendor qualification timelines. Bangalore and Delhi-NCR universities are piloting WhatsApp Business API integration to bypass email deliverability constraints.
Australia
Universities are standardizing virtual reunion capabilities after pandemic-era pilot programs demonstrated participation surges among international alumni cohorts. Health Canada audit requirements for health sciences continuing education tracking influence procurement criteria for hosted private cloud instances. Sydney and Melbourne institutions anchor demand for hybrid event infrastructure that integrates virtual attendance with in-person logistics.
Global Alumni Management Software Market Competitive Landscape
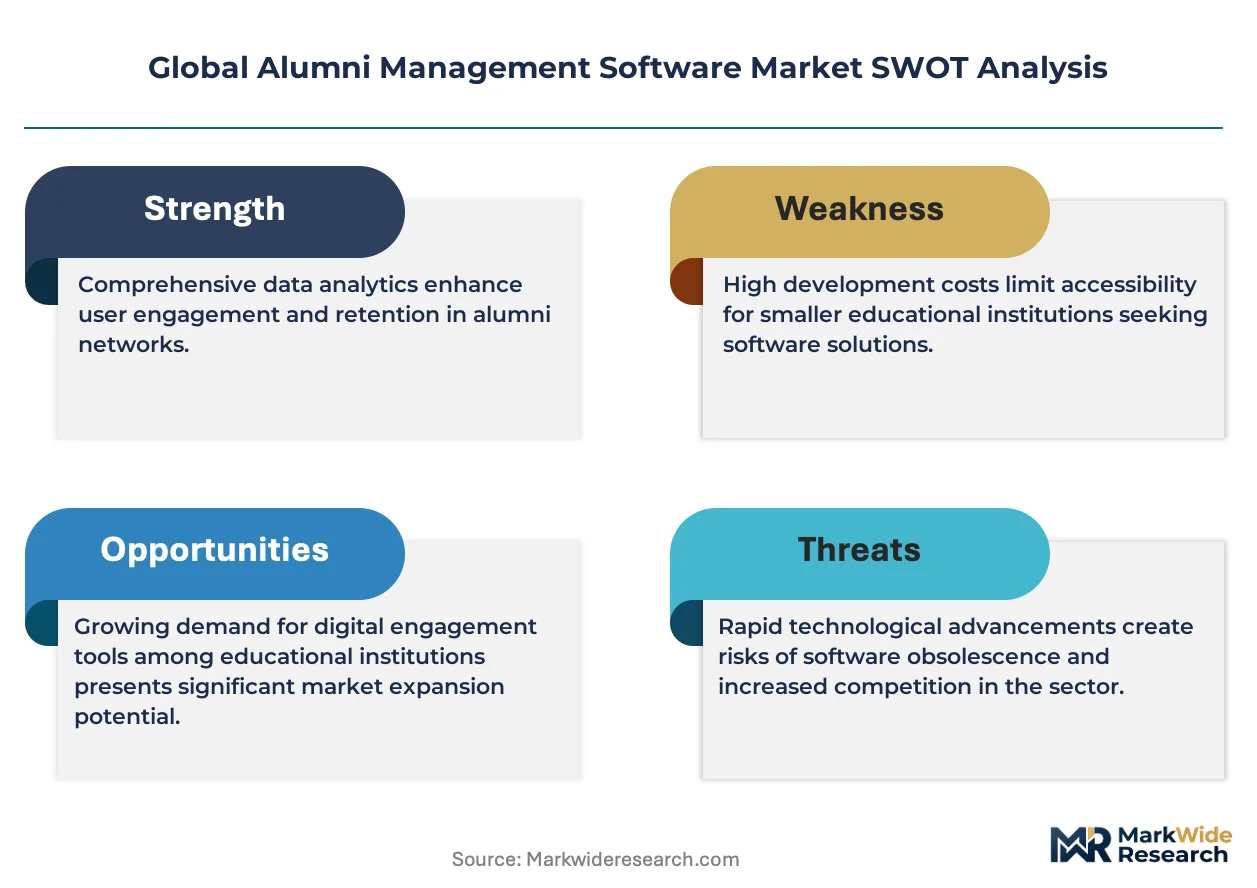
Listed leaders compete with private specialists across certification benchmarks, creating tiered pressure where FedRAMP and ISO 27001 credentials determine mid-market access. The vendor base separates into three strategic archetypes: modular platform builders, geographic compliance specialists, and career services verticalists. M&A activity concentrates on acquiring API-native architectures to bypass technical debt in legacy donor databases, while strategic partnerships with systems integrators accelerate on-premise-to-cloud transitions.
Within the modular architecture tier, Almabase and Hivebrite exemplify divergent geographic positioning strategies. Almabase occupies a position among mid-tier institution specialists, while Hivebrite anchors European higher education presence through localized data residency controls. Graduway represents the career services verticalist archetype, sitting within professional association segments where skills-matching algorithms differentiate platform value. These three companies illustrate how competitive positioning fragments across institutional buyer profiles rather than consolidating around unified feature sets.
| Leading Market Players |
|---|
| PeopleGrove |
| ToucanTech |
| Almabase |
| Vaave |
| 360Alumni |
| Hivebrite |
| EverTrue |
| EnterpriseAlumni |
| Graduway |
| Others |
Supply & Pricing Matrix
Multi-tenant SaaS infrastructure economics concentrate vendor margins in United States-based cloud regions, compressing price floors for mid-tier institutions while elevating premium tiers for FedRAMP-certified deployments. This scale dynamic concentrates supply-side bargaining power among hyperscaler-backed vendors, forcing smaller providers toward niche specialization or hosted private cloud architectures to escape commodity pricing.
Pricing Analysis
Cloud-native subscription tiers command 40-60% premiums over legacy perpetual licenses, while on-premise installations persist at price points reflecting customization depth and data residency controls. Pricing stratifies across FedRAMP-certified enterprise suites, ISO 27001-compliant mid-market packages, and freemium entry points for training institutes. Cost compression in the mid-market tier intensifies because Salesforce Education Cloud and Microsoft Dynamics 365 replicate core functionality at lower per-seat rates. Training institutes in India exhibit highest price sensitivity, while research universities in Germany accept premium pricing for algorithmic transparency modules.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for North American higher education institutions, while Ireland and Germany host EU data residency stacks to satisfy GDPR Article 44 transfer restrictions. Software development draws from distributed engineering centers in India and Poland, with customer success operations concentrated in United Kingdom and Australian hubs. Single-source vulnerability runs through hyperscaler dependency for compute and storage, exposing vendors to egress cost volatility and regional outage risks. Distribution runs through direct vendor sales teams for enterprise accounts, with channel partners and systems integrators serving on-premise transitions in regulated sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alumni management software sits in early-cycle expansion as India's National Education Policy 2020 mandates digital tracking for over one thousand universities previously reliant on spreadsheets. This regulatory tailwind compounds with career services unbundling across mid-tier liberal arts colleges, creating multiple penetration vectors simultaneously.
For Market Incumbents: Fortify FedRAMP and ISO 27001 certification moats against Salesforce Education Cloud encroachment, while accelerating API-native architecture transitions to bypass technical debt in legacy donor databases. Channel control through systems integrator partnerships protects on-premise revenue streams during cloud migration windows. For New Entrants and Emerging Players: Differentiate on WhatsApp Business API integration for Sub-Saharan African markets where smartphone penetration exceeds desktop access, or on AI-driven predictive giving models for United States institutions with established advancement data lakes. India's mandated alumni tracking requirements represent the most penetrable geography, with tiered licensing entry points validated through BIS certification pathways. For Investors and Strategic Acquirers: API-native mid-market specialists with modular architectures present attractive acquisition targets as larger vendors seek to bypass middleware development costs. Long-term viability hinges on platform consolidation endurance across the next decade, with inflection signaled by sustained unbundling behavior among $50-500 million endowment institutions.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Certification Investment | Unlocks federal aid-eligible United States institutions and disqualifies uncertified competitors from procurement shortlists. |
| WhatsApp Business API Integration | Bypasses email deliverability constraints in Sub-Saharan African markets where mobile-first engagement dominates. |
| AI-Driven Predictive Giving Modules | Displaces third-party wealth screening subscriptions and commands premium pricing from research universities. |
| Hybrid Deployment Architecture | Reconciles GDPR Article 44 transfer restrictions with mobile accessibility for transnational alumni bases. |
| Career Services Module Expansion | Captures procurement autonomy from continuing education units unbundling from all-in-one advancement suites. |
Research Methodology
Operator-level perspectives from chief advancement officers, IT procurement directors, CRM implementation specialists, and continuing education unit heads anchored the qualitative base for this analysis. These primary insights combined with secondary validation from EDUCAUSE technology surveys, United States Department of Education Title IV compliance documentation, vendor SEC filings, and EU AI Act regulatory texts. Bottom-up institution-level demand modeling triangulated against top-down market sizing from cloud infrastructure expenditure disclosures.
Sensitivity analysis across deployment model, institutional endowment tier, solution type priority, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from institution-level procurement cycle analysis and vendor reported customer expansion rates. Forecast inputs included India's National Education Policy implementation timelines, GDPR Article 17 automation requirements, and hybrid event infrastructure standardization patterns across Australian and Canadian universities.
Decision-makers should treat outputs as directional under sustained cloud migration pressure and regulatory fragmentation assumptions; material deviation in hyperscaler pricing or data localization enforcement would warrant model refresh. Recalibration cycles align with material shifts in federal compliance mandates, AI Act risk classification implementations, and unbundling behavior among mid-tier liberal arts colleges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Student Response System Market
Education & Training
Executive Education Program Market
Education & Training
Global Language Service Market
Education & Training
Asia-Pacific Management Consulting Services Market
Education & Training
Homeschooling Market
Education & Training
North America Digital Education Market
Education & Training
Digital Badges Market
Education & Training
Global Training Software Market
Education & Training
Global K-12 Software Market
Education & Training
Healthcare LMS Software Market
Education & Training
Global Virtual Classroom Market
Education & Training
Virtual Reality in Education Market
Education & Training
Corporate Workforce Development Training Market
Education & Training
Asia-Pacific Digital Education Market
Education & Training
Bilingual Education for Children Market
Education & Training
Test Preparation Market