
 United States HR Professional Service Market | 2026-2036
United States HR Professional Service Market Size, Share, and Industry Trends Forecast 2026-2036
United States HR Professional Service Market Insights
Workforce analytics and benefits administration revenue is reconfiguring margin pools away from traditional payroll processing toward integrated talent platforms. ADP leverages its data infrastructure to dominate multi-state payroll complexity. Workday sustains R&D intensity in cloud-native human capital management. Accenture competes through consulting-led digital HR transformation engagements.
United States HR Professional Service encompasses advisory, administrative, and technology-enabled functions that manage employee lifecycle operations from recruitment through separation, typically delivered through cloud platforms with API connectivity to enterprise resource planning systems. Payroll Processing and Compliance Management command mature, high-volume revenue streams with sticky client relationships. Talent Development and Software-as-a-Service delivery represent faster-expanding segments where margin pools deepen as employers prioritize retention analytics and self-service platforms.
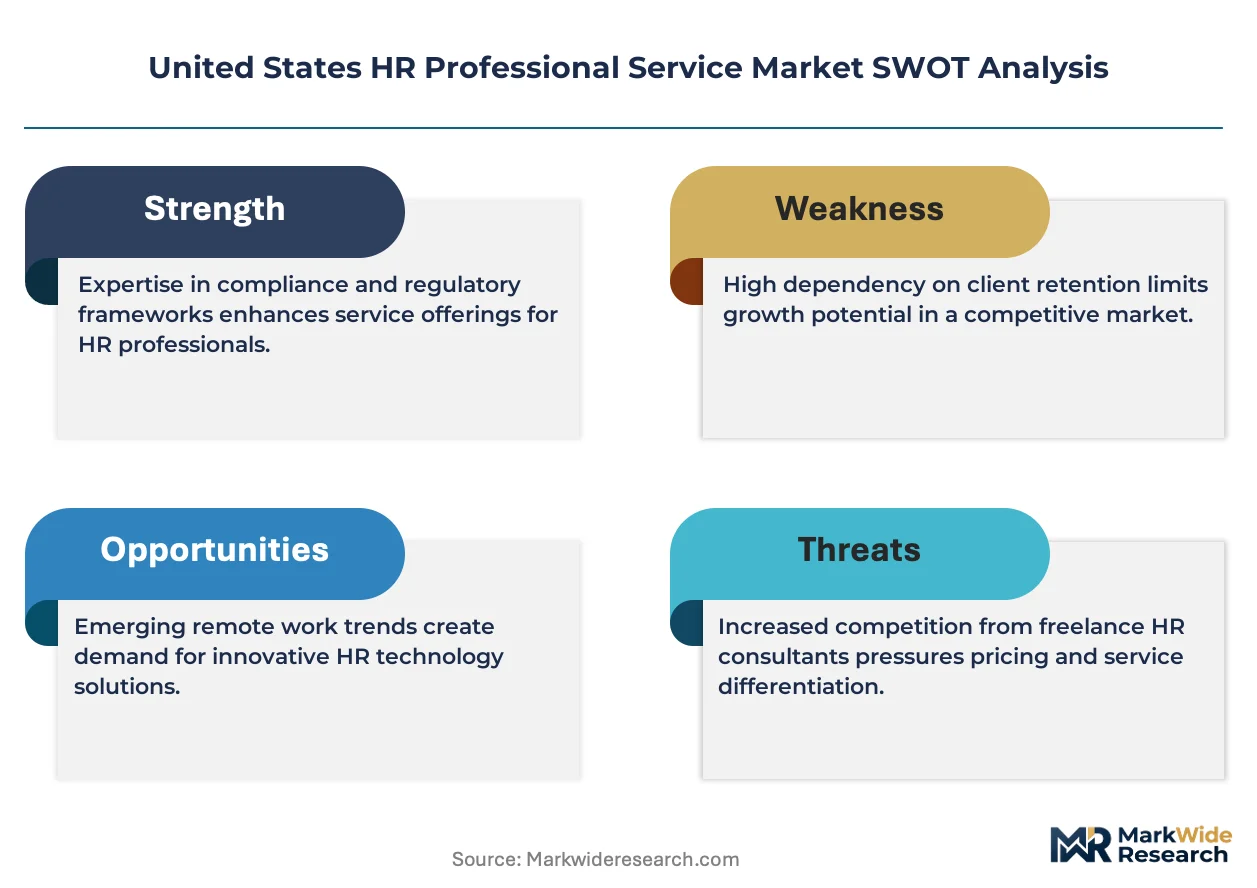
The Department of Labor enforces Fair Labor Standards Act provisions that shape employer demand for external wage-and-hour compliance support, while the Equal Employment Opportunity Commission's enforcement posture drives investment in audit-ready documentation systems. State-level regulators in California and New York impose additional paid leave and pay transparency mandates that fragment compliance requirements. Stakeholders must monitor how the NLRB's evolving joint-employer standard alters co-employment structures and PEO liability exposure.
Market Dynamics
The Department of Labor's evolving overtime threshold rules are compressing employer tolerance for internal compliance risk, accelerating the migration of wage-and-hour administration toward external specialists with dedicated legal infrastructure and multi-state filing capabilities.
Growth Catalysts
- Healthcare workforce expansion:Hospital systems and long-term care networks are outsourcing HR functions to manage clinical staffing complexity, credential tracking, and shift scheduling across dispersed facilities.
- California pay transparency mandates:State-level disclosure requirements are forcing mid-sized employers to adopt audit-ready compensation analytics platforms previously reserved for large enterprises.
- API-first platform architecture:Cloud-native HR systems with open integration frameworks are collapsing the technical barriers between payroll, benefits, and talent management modules.
Market Restraints
- Specialized talent scarcity:Shortages of certified HR technology architects and employment law specialists in Texas and California are inflating implementation costs and extending project timelines.
- Legacy system entrenchment:Decades-old on-premise payroll infrastructure in manufacturing and public sector verticals creates technical debt that resists cloud migration.
- Joint-employer liability uncertainty:The National Labor Relations Board's shifting standards on co-employment classification are freezing PEO contract renewals as legal teams reassess exposure.
Strategic Opportunities
- Mid-market penetration in Florida and Georgia:Employer density growth in Sun Belt metros is outpacing local HR service capacity, creating white space for platform providers with standardized implementation playbooks.
- Retention analytics convergence:Integration of workforce sentiment data with flight-risk algorithms is opening premium advisory tiers beyond transactional processing.
- State paid leave administration:New York and Washington mandates for family and medical leave insurance are generating demand for compliant absence management systems.
Industry Challenges
- Multi-state filing fragmentation:Employers operating across jurisdictions face divergent tax withholding rules, unemployment insurance rates, and reporting deadlines that strain centralized HR operations.
- Data interoperability gaps:Inconsistent API standards between enterprise resource planning systems and HR platforms force expensive custom integration work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States HR Professional Service Market |
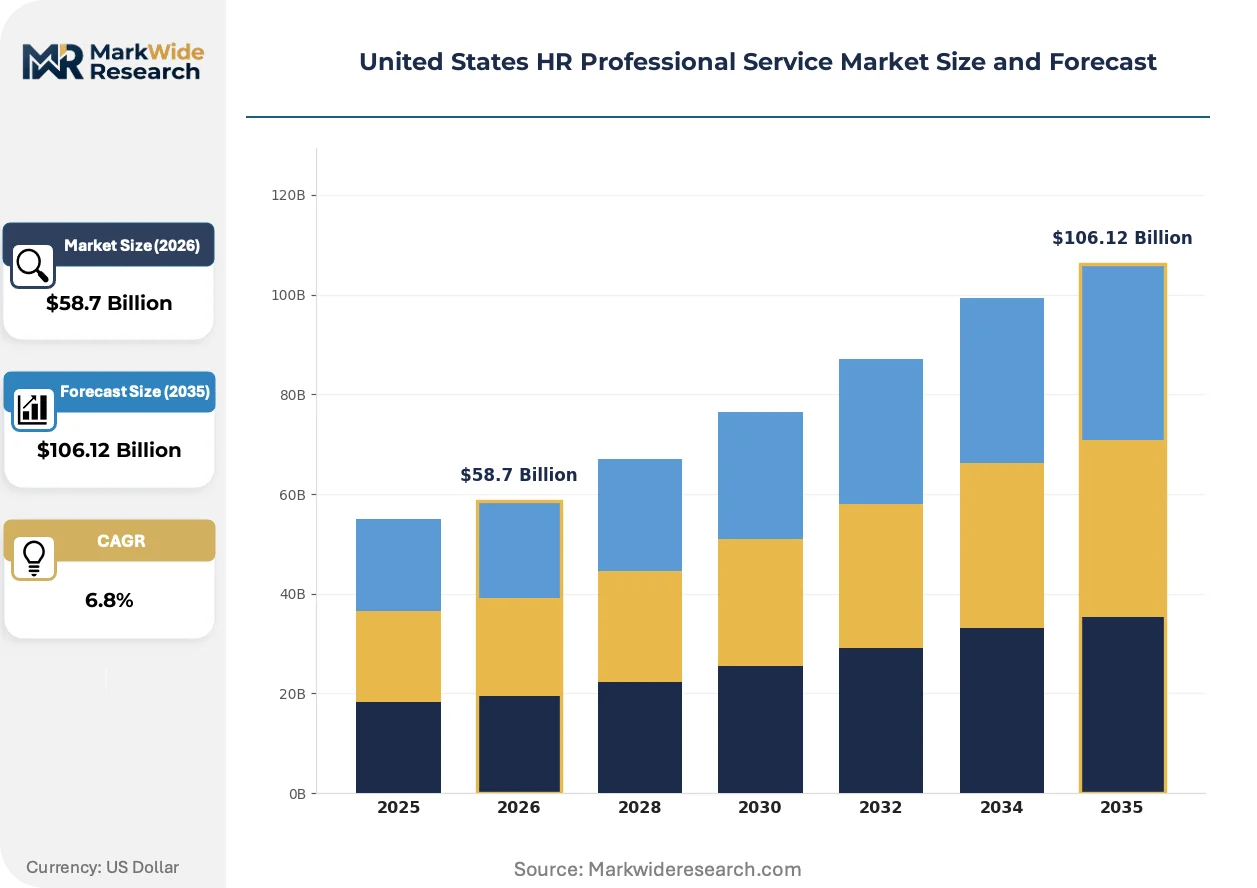
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recruitment, Payroll Processing, Compliance Management, Talent Development Client Type: Small Businesses, Large Enterprises, Government Agencies, Nonprofits Delivery Model: In-House Services, Outsourced Solutions, Software-as-a-Service, Hybrid Model Specialization Area: Employee Relations, Performance Management, HR Technology, Training Programs |
| Companies Covered | ADP, Workday, Paychex, Insperity, TriNet Group, ManpowerGroup, Deloitte, Accenture, UKG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States HR Professional Service Market Trends and Innovations
Artificial intelligence is collapsing traditional boundaries between administrative processing and strategic workforce planning, embedding predictive capabilities directly into transactional workflows that previously required separate consulting engagements.
Generative AI tools for policy drafting and employee inquiry response are collapsing the cost structure of tier-one HR support, enabling mid-market employers to automate routine interactions previously handled by dedicated staff. Healthcare and retail verticals with high seasonal turnover are deploying these systems fastest. The technology is collapsing the distinction between self-service portals and live advisory, compressing pricing power for basic administrative tiers.
The Department of Labor's pending overtime threshold adjustments are forcing employers to reclassify salaried positions and audit time-tracking systems. This regulatory pressure is accelerating demand for external compliance monitoring and automated classification tools. Organizations with distributed workforces across multiple states face the steepest reconfiguration burden.
Subscription pricing for integrated talent platforms is displacing per-paycheck transaction fees as the dominant commercial model, locking in multi-year relationships through embedded workflow dependencies. Large employers in California and Texas are negotiating enterprise licenses that bundle analytics, compliance, and administrative processing. This shift concentrates vendor selection authority with procurement functions rather than HR operations leadership.
United States HR Professional Service Market Segmentation
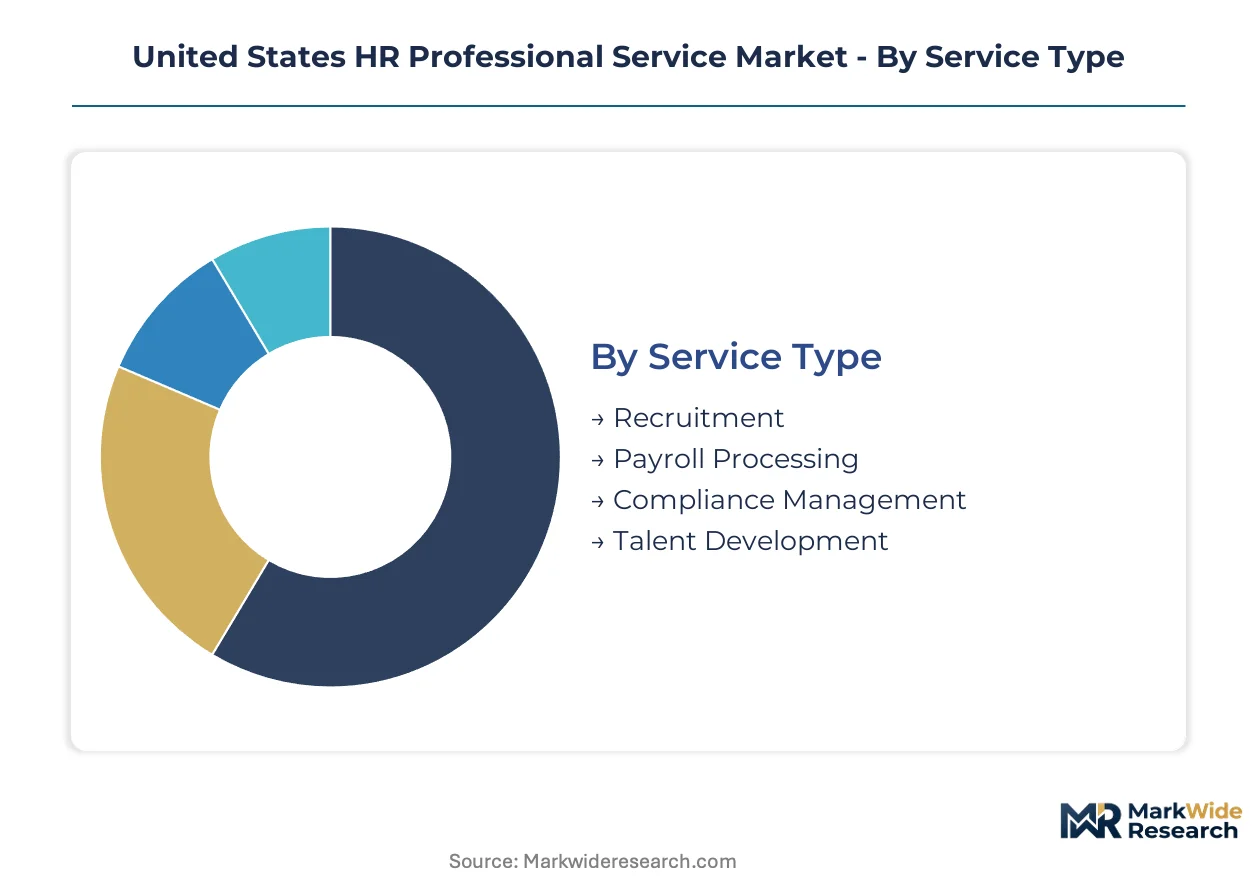
Employers in the United States select HR professional services through layered decision frameworks that weigh regulatory exposure against workforce scale. Segmentation reveals how delivery complexity fragments across service types, client profiles, and specialization depth.
Service Type:
Cost tier determines procurement authority and contract structure across administrative versus advisory functions.
- Recruitment:Talent acquisition services encompass sourcing infrastructure, applicant tracking systems, and employer branding execution. Healthcare systems in Texas and California deploy these services to manage clinical staffing pipelines and credential verification workflows.
- Payroll Processing:Wage calculation, tax withholding, and multi-state filing operations form the transactional backbone of HR outsourcing. Manufacturing employers with distributed facilities rely on external specialists to navigate divergent unemployment insurance rates and reporting deadlines across jurisdictions.
- Compliance Management:External monitoring of wage-and-hour regulations, EEOC documentation requirements, and state-level paid leave mandates.
- Talent Development:Retention analytics, leadership training, and succession planning advisory.
Payroll Processing commands the established base. The steepest expansion runs through Talent Development.
Client Type:
Customer scale shapes service configuration from standardized platforms to bespoke advisory engagements.
- Large Enterprises:Complex multi-state operations requiring integrated talent platforms with API connectivity to ERP systems. These employers negotiate enterprise licenses bundling analytics, compliance, and administrative processing across California and Texas headquarters clusters.
- Small Businesses:Resource-constrained employers purchasing transactional processing and basic compliance support through subscription models.
- Government Agencies:Public sector employers with legacy on-premise infrastructure and procurement-driven vendor selection.
- Nonprofits:Mission-driven organizations prioritizing cost containment in benefits administration and grant-compliant payroll reporting.
Large Enterprises anchor vendor revenue concentration. Small Businesses are gaining share fastest as platform economics democratize access.
Delivery Model:
Volume and technical architecture determine whether services reside internally, externally, or in blended configurations.
- Software-as-a-Service:Cloud-native platforms with self-service portals and embedded analytics. Mid-market employers in Florida and Georgia adopt these systems to bypass local HR service capacity constraints.
- Outsourced Solutions:Third-party administrators handling payroll, benefits, and compliance through co-employment or administrative services only arrangements.
- Hybrid Model:Combinations retaining strategic HR internally while outsourcing transactional processing and compliance monitoring.
- In-House Services:Fully internal HR operations typical of legacy manufacturing and public sector verticals with entrenched technical debt.
Outsourced Solutions retain the largest installed base. Software-as-a-Service shows the steepest adoption curve.
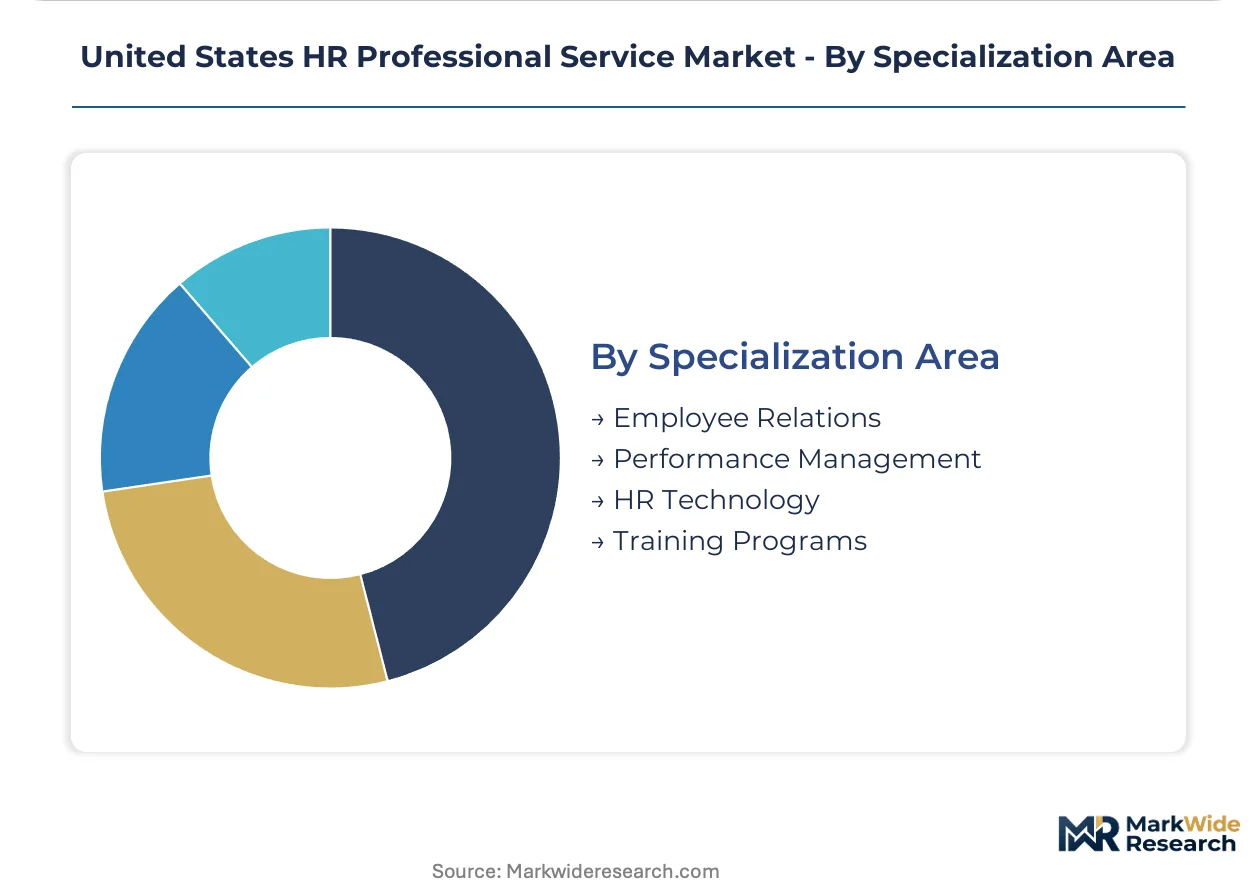
Specialization Area:
Application depth separates commodity processing from premium advisory tiers with measurable workforce outcomes.
- HR Technology:System selection, implementation, and integration of human capital management platforms. Demand concentrates where API-first architectures collapse barriers between payroll, benefits, and talent modules.
- Performance Management:Goal-setting frameworks, continuous feedback systems, and calibration processes.
- Employee Relations:Dispute resolution, policy enforcement, and NLRB-compliant documentation.
- Training Programs:Skills development, compliance certification, and leadership curriculum delivery.
HR Technology captures premium pricing. Performance Management is climbing the fastest as retention analytics converge with flight-risk algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor capacity concentrates in California and Texas metro clusters where employer density and regulatory complexity create premium service demand. The analysis examines five sub-regional markets driving United States HR Professional Service deployment patterns.
California
Healthcare systems and technology employers in the San Francisco Bay Area and Los Angeles metro deploy integrated talent platforms for clinical staffing and credential tracking. The state's pay transparency mandates and paid family leave insurance requirements force mid-sized employers toward audit-ready compensation analytics. Silicon Valley headquarters clusters negotiate enterprise licenses bundling compliance, payroll, and retention analytics.
Texas
Energy sector employers and hospital networks in Houston and Dallas-Fort Worth outsource HR functions to manage dispersed workforce operations across multiple facilities. The Texas Workforce Commission administers unemployment insurance and labor market information systems that shape vendor filing capabilities. Austin's technology corridor drives demand for cloud-native platforms with API connectivity to enterprise resource planning systems.
New York Metro
Financial services and healthcare employers in Manhattan and surrounding counties prioritize compliance management for wage-and-hour regulations and EEOC documentation. The New York State Department of Labor enforces paid family leave mandates that generate demand for absence management systems. The metro's density of large enterprises sustains premium advisory tiers for retention analytics and succession planning.
Florida
Mid-market employers in Miami, Tampa, and Orlando metro areas adopt software-as-a-service platforms to bypass local HR service capacity constraints. The state's business-friendly regulatory environment attracts relocating employers seeking standardized implementation playbooks. Healthcare networks with seasonal staffing fluctuations deploy automated classification tools for overtime compliance.
Illinois
Manufacturing employers and healthcare systems in Chicago and surrounding industrial corridors rely on external specialists for multi-state payroll complexity. The Illinois Department of Employment Security administers unemployment insurance systems that intersect with vendor filing operations. Legacy on-premise infrastructure in manufacturing verticals creates technical debt that resists cloud migration, sustaining hybrid outsourcing arrangements.
United States HR Professional Service Market Competitive Landscape
Payroll infrastructure specialists and cloud-native platform providers split the market between transactional processing scale and integrated talent management depth. Consolidation pressure concentrates revenue among vendors with multi-state filing capabilities and dedicated legal infrastructure. Three archetypes dominate: legacy payroll processors with sticky client relationships, enterprise software platforms with embedded analytics, and consulting-led transformation advisors. Competitive moves center on API-first architecture investments and mid-market penetration through standardized implementation playbooks.
Within the legacy processor tier, ADP and Paychex anchor established revenue streams through high-volume payroll operations and multi-state compliance infrastructure. Workday occupies a position exemplifying cloud-native platform architecture with embedded workforce analytics. Among consulting-led advisors, Accenture represents the digital HR transformation engagement model competing through advisory depth rather than transactional scale.
| Leading Market Players |
|---|
| ADP |
| Workday |
| Paychex |
| Insperity |
| TriNet Group |
| ManpowerGroup |
| Deloitte |
| Accenture |
| UKG |
| Others |
Pricing and Supply Chain Analysis
Dallas-Fort Worth and Austin technology corridors concentrate cloud-native HR platform development capacity, concentrating vendor pricing power among providers with multi-state compliance infrastructure and API-first architectures that lock in enterprise relationships through embedded workflow dependencies.
Pricing Analysis
After-sales revenue from retention analytics and compliance monitoring subscriptions now drives lifetime value beyond initial implementation fees. Three-tier pricing structure across premium advisory, standard platform, and economy processing levels stratifies by integration complexity and regulatory exposure depth. Cost compression in economy payroll tiers is intensifying because generative AI tools automate routine policy drafting and employee inquiry response. Small businesses in Florida and Georgia exhibit highest price sensitivity, while large enterprises in California negotiate enterprise licenses bundling analytics and compliance with least sensitivity to per-seat costs.
Supply Chain Analysis
Tariff exposure between the United States and India for software development talent dominates supply chain risk planning for HR technology vendors. Platform engineering capacity concentrates in the United States, India, and Ireland, with implementation consulting drawing from domestic employment law specialists in Texas and California. Raw material dependencies center on cloud computing infrastructure from hyperscalers, certified HR technology architect labor pools, and employment law compliance databases. Single-source vulnerability runs through specialized regulatory content providers for multi-state filing rules. Distribution runs through direct enterprise sales teams and channel partners serving mid-market employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity because recurring subscription revenue from integrated talent platforms expands faster than one-time implementation fees, embedding vendors deeply into client workflow dependencies.
For Market Incumbents: Pre-empt mid-market platform challengers by accelerating standardized implementation playbooks for Florida and Georgia metros where employer density growth outpaces local service capacity. Consolidate through acquisition of specialized compliance content providers addressing multi-state filing fragmentation. Joint-employer liability uncertainty from NLRB standards shifting represents immediate contract renewal risk requiring dedicated legal infrastructure investment as defensive moat. For New Entrants and Emerging Players: Pursue white space in mid-market SaaS penetration across Sun Belt metros where platform economics democratize access previously reserved for large enterprises. Target healthcare networks with seasonal staffing fluctuations needing automated overtime classification tools. Lead with API-first architecture messaging that collapses technical barriers between payroll, benefits, and talent management modules as core go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-utility play because regulatory fragmentation across state-level paid leave mandates and pay transparency requirements creates durable demand for external expertise regardless of economic cycle. Acquisition target archetype: specialized compliance monitoring vendors with California and New York regulatory content depth. Signal to watch is NLRB joint-employer standard finalization triggering PEO contract restructuring and vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Collapses technical barriers between payroll, benefits, and talent modules for mid-market employers. |
| Multi-State Compliance Content Expansion | Addresses DOL overtime threshold adjustments and California pay transparency mandates with automated monitoring. |
| Retention Analytics Convergence | Integrates workforce sentiment data with flight-risk algorithms opening premium advisory tiers. |
| Mid-Market Standardized Implementation | Captures employer density growth in Florida and Georgia metros outpacing local HR service capacity. |
| Generative AI Support Automation | Compresses cost structure of tier-one HR support collapsing pricing power for basic administrative tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DOL regulatory filings, state labor department rulemakings, and vendor SEC disclosures through structured interviews with HR technology executives, employment law specialists, enterprise HR operations directors, and mid-market platform procurement officers. Bottom-up triangulation validates service segment sizing against top-down macroeconomic employment trends and cloud software adoption patterns.
Forecast inputs include service type segmentation by delivery model complexity, client type scale tiers, and specialization depth across the analysis window. Modeled dimensions encompass administrative versus advisory function mix, platform deployment architecture, and geographic regulatory cluster intensity. CAGRs derive from employment growth projections, regulatory change velocity, and technology substitution rates for manual HR processes.
Sensitivities concentrate around NLRB joint-employer standard revisions, state-level paid leave mandate expansion timelines, and generative AI capability advancement disrupting tier-one support economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Private Tutoring Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
Global Outplacement Services Market
Corporate Training and Talent Development
Europe Consulting Services Market
Corporate Training and Talent Development
Integrated Talent Management Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market