
 Higher Education Student CRM Solutions Market | 2026-2036
Higher Education Student CRM Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Higher Education Student CRM Solutions Market Foresight
Subscription-based analytics modules are repositioning how institutions procure student relationship management capabilities. Salesforce Education Cloud leverages its platform ecosystem to anchor enterprise-wide deployments across large university systems. Anthology competes through deep integration with student information systems and legacy campus infrastructure. Slate by Technolutions specializes in highly configurable communication workflows that dominate selective undergraduate admissions.
Higher education student CRM solutions comprise software platforms that centralize prospect data, automate outreach sequences, and apply machine learning to predict enrollment yield with accuracy thresholds typically exceeding 80 percent. Cloud-based deployment leads installed capacity due to lower capital requirements and faster implementation cycles, while enrollment management features capture the largest margin pool because institutions prioritize tuition revenue protection over engagement tooling. Private cloud and single-tenant configurations are gaining traction among institutions with stringent data residency requirements.
The U.S. Department of Education enforces FERPA compliance that shapes how vendors architect data access controls and audit trails. State-level attorneys general in California and New York have expanded enforcement of student data privacy statutes, forcing CRM providers to localize storage and tighten breach notification protocols. Institutions must evaluate whether vendor roadmaps incorporate native AI governance features before committing to long-term platform contracts.
Market Dynamics
Predictive enrollment analytics are compressing decision cycles for admissions offices, forcing vendors to rearchitect platforms around real-time data ingestion and machine learning inference at scale.
Growth Catalysts
- FERPA Compliance Mandates:The U.S. Department of Education's enhanced audit requirements are compelling institutions to replace legacy systems with cloud-native CRMs offering immutable audit trails and role-based access controls.
- Multi-Campus Consolidation:Research-intensive university systems are standardizing on single-platform deployments to unify prospect data across decentralized recruitment operations.
- Yield Prediction Algorithms:Machine learning models achieving accuracy thresholds above 80 percent are converting skeptical enrollment managers into platform adopters.
Market Restraints
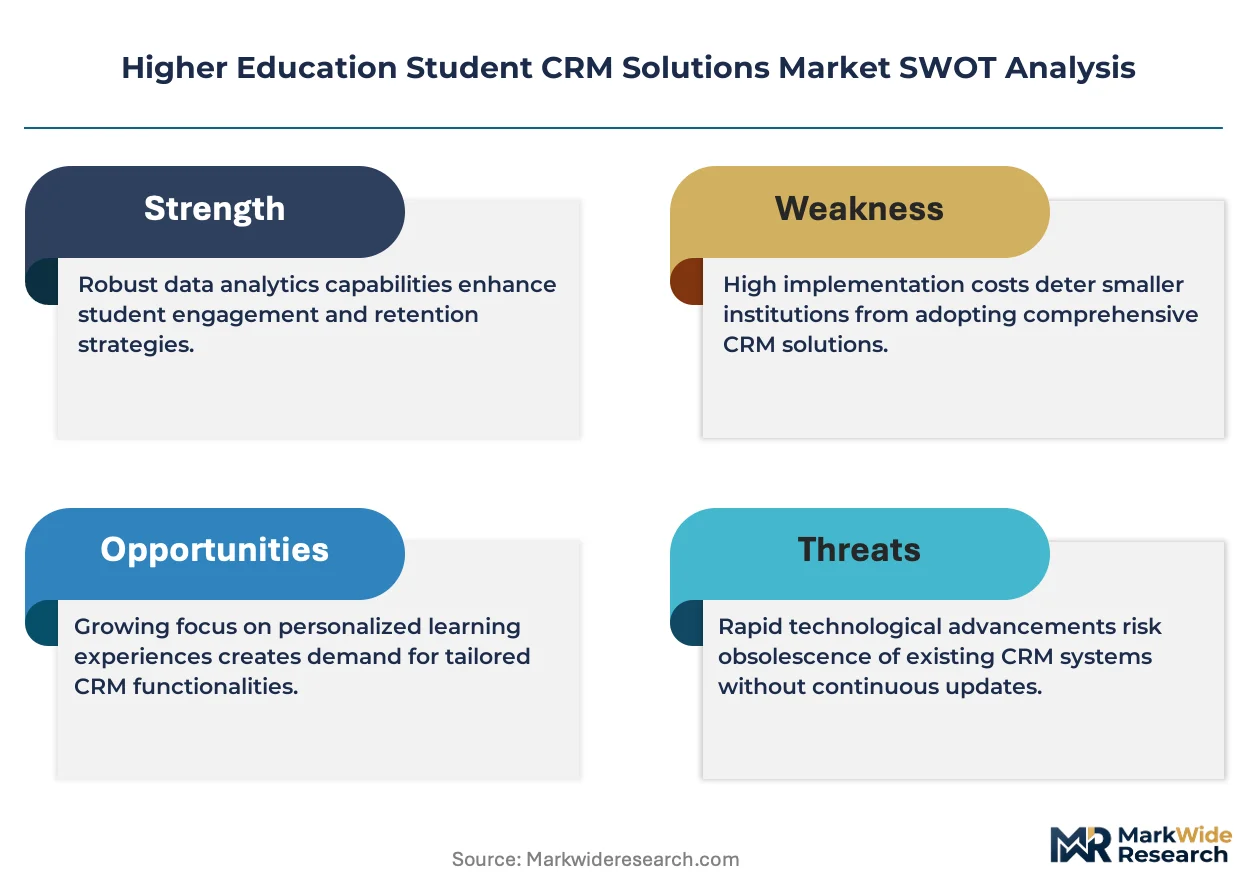
- Data Residency Requirements:State-level privacy statutes in California and New York are fragmenting vendor architectures, forcing costly single-tenant configurations for affected institutions.
- Integration Debt:Deep coupling with legacy student information systems creates switching costs that lock institutions into incumbent vendors despite superior alternatives.
- Specialized Labor Scarcity:Shortages of higher education data scientists and CRM administrators are extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- Community College Expansion:Two-year institutions with limited IT budgets represent an underpenetrated segment for scaled-down, preconfigured CRM modules.
- AI Governance Tooling:Native bias detection and explainability features are creating differentiation as institutions evaluate vendor roadmaps before long-term commitments.
- International Recruitment Pipelines:English-language program marketing automation for overseas prospects is opening new revenue streams for mid-tier universities.
Industry Challenges
- Interoperability Complexity:Synchronizing CRM platforms with learning management systems and financial aid databases requires custom API development that strains IT departments.
- Change Management Resistance:Admissions staff accustomed to relationship-based recruitment methods frequently underutilize automated outreach features, degrading platform ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Higher Education Student CRM Solutions Market |
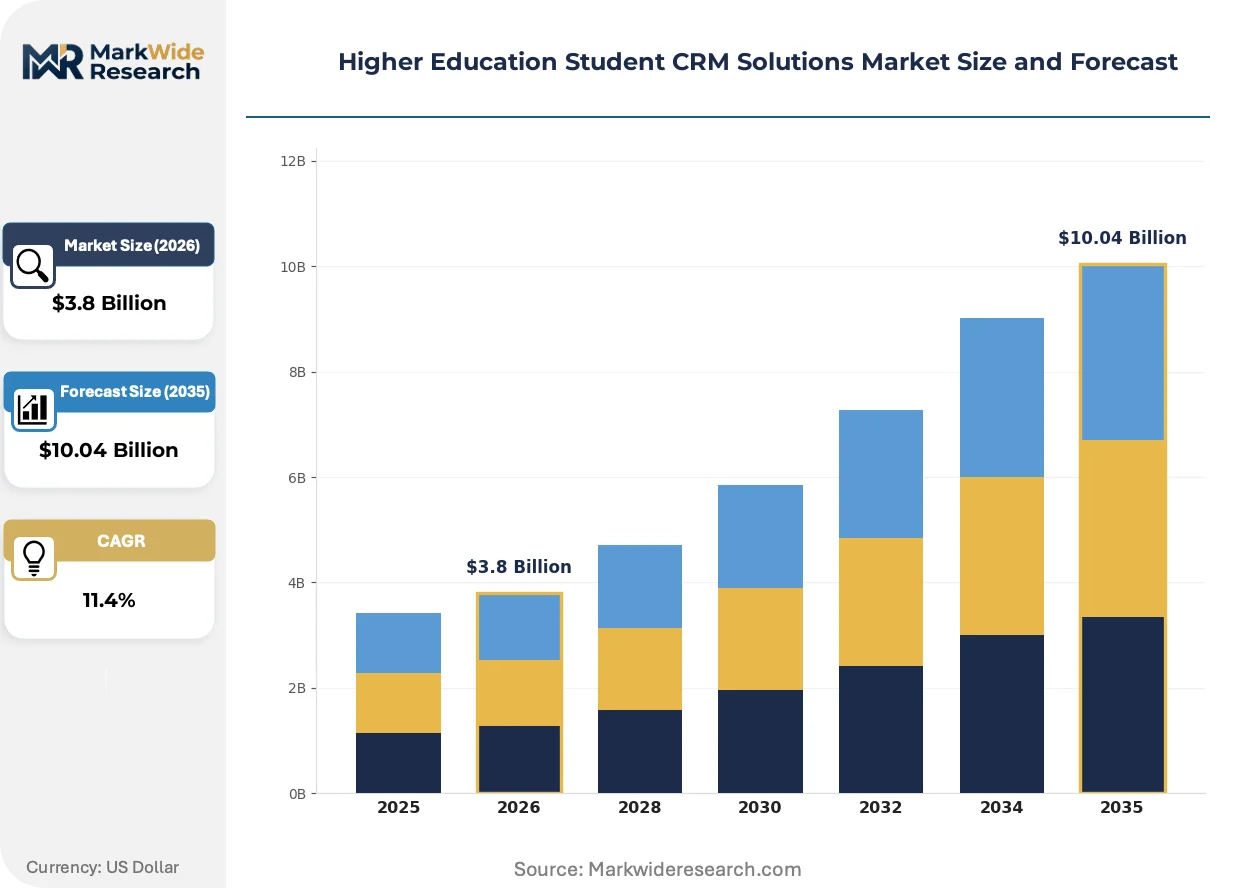
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Deployment: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant End User: Universities, Colleges, Online Educators, Training Institutes Feature: Enrollment Management, Student Engagement, Analytics, Customization |
| Companies Covered | Ellucian CRM, TargetX, Slate by Technolutions, Anthology, Blackbaud, Salesforce Education Cloud, ibl.ai, Jenzabar, Element451, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Higher Education Student CRM Solutions Market Shifts & Advancements
Platform architectures are fragmenting into composable services, enabling institutions to purchase enrollment management capabilities without absorbing full-suite complexity.
Microservices-based CRM architecture is modularizing how universities procure student relationship management. Large research institutions are adopting containerized enrollment modules that integrate with existing identity providers and data warehouses. This decomposition is compressing vendor lock-in by allowing institutions to swap individual services rather than replatform entirely.
The U.S. Department of Education's evolving FERPA guidance is forcing vendors to implement privacy-by-design data architectures. Providers must now demonstrate granular consent management and automated data deletion workflows before securing multi-year contracts. Graduate and professional programs with complex international applicant pools face the steepest compliance burdens.
Subscription-based procurement is displacing perpetual licensing in higher education technology acquisition. Chief information officers are negotiating annual renewals tied to active user counts rather than upfront capital commitments. This shift is most pronounced among public university systems with volatile state appropriations.
Higher Education Student CRM Solutions Market Segmentation
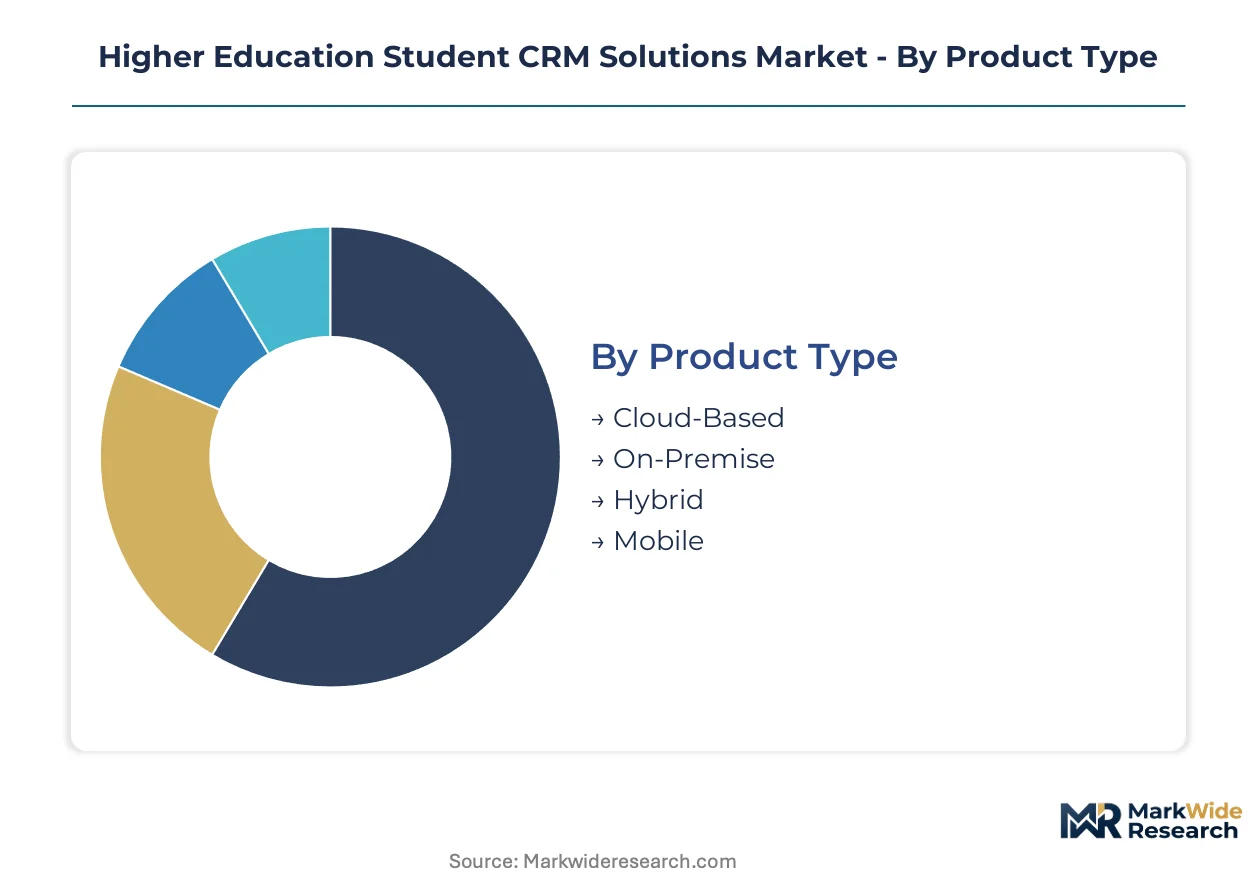
CRM procurement patterns diverge sharply between resource-constrained community colleges and research-intensive universities with dedicated IT budgets. Segmentation reveals how deployment complexity, compliance requirements, and feature sophistication create tiered market entry points for vendors.
Product Type:
Cloud-based platforms dominate transaction volume while on-premise installations command premium pricing from institutions with stringent data residency mandates.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling infrastructure reduce capital expenditure for public university systems. Demand concentrates among state flagship universities in California and Texas seeking rapid deployment across decentralized campuses without hardware procurement cycles.
- On-Premise:Single-tenant installations within institutional data centers satisfy FERPA audit requirements for immutable access logs. Military academies and federal research universities in Maryland and Virginia mandate these configurations for classified applicant processing.
- Hybrid:Split architectures keep sensitive prospect data on-premise while leveraging cloud analytics for enrollment forecasting.
- Mobile:Native iOS and Android applications extend recruiter access to field operations and campus events.
Mature deployment sits with Cloud-Based. Newer deployment is concentrated in Hybrid.
Deployment:
Public cloud configurations capture volume economics while single-tenant private clouds extract premiums from institutions facing state-level privacy enforcement.
- Public Cloud:Shared infrastructure pools drive per-seat costs below fifty dollars annually for large undergraduate programs. Regional state universities in the Midwest standardize here to maximize limited technology appropriations.
- Private Cloud:Dedicated virtual environments isolate prospect databases from co-tenant risks. Private liberal arts colleges in Massachusetts and Connecticut deploy these to satisfy attorney general scrutiny of cross-border data flows.
- Multi-Tenant:Logical separation within shared physical infrastructure balances cost and isolation for mid-tier institutions.
- Single-Tenant:Physically dedicated servers address the strictest interpretations of student data sovereignty laws.
Volume procurement clusters in Public Cloud. Compliance-driven replacement concentrates in Single-Tenant.
End User:
Universities with complex graduate pipelines purchase full-suite platforms while training institutes adopt stripped-down engagement modules.
- Universities:Doctoral-granting institutions require predictive yield algorithms across undergraduate, graduate, and professional divisions. Research-intensive systems in North Carolina and Michigan deploy enterprise-wide to unify prospect data from medical, law, and engineering admissions.
- Colleges:Baccalaureate-focused institutions prioritize communication automation over analytics depth. Small private colleges in Pennsylvania optimize these tools for relationship-based recruitment of first-generation applicants.
- Online Educators:Asynchronous program providers need scaled intake processing without campus visit scheduling.
- Training Institutes:Vocational and certificate programs demand rapid implementation with minimal customization.
Feature-rich adoption sits with Universities. Simplified deployment is expanding fastest among Online Educators.
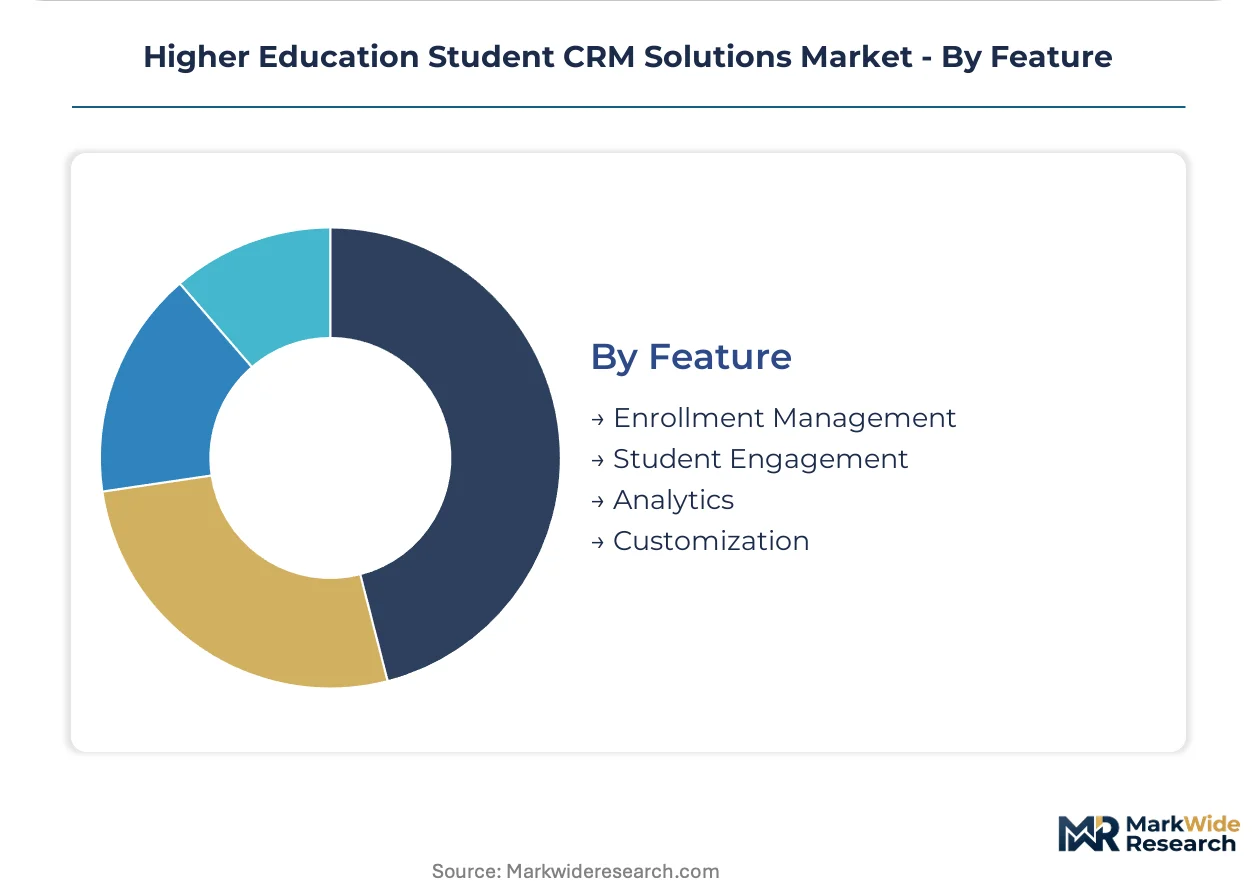
Feature:
Enrollment management modules generate the highest margins while analytics capabilities create switching costs that extend contract duration.
- Enrollment Management:Workflow automation for application processing, document collection, and decision release forms the core revenue base. Admissions offices at flagship public universities in Florida and Ohio treat these capabilities as tuition revenue protection infrastructure.
- Student Engagement:Multi-channel communication orchestration across email, SMS, and social platforms deepens prospect relationships. Enrollment marketers at selective private universities in California deploy these to personalize outreach at scale.
- Analytics:Machine learning inference on historical matriculation patterns improves yield forecasting accuracy.
- Customization:No-code configuration tools allow non-technical staff to adapt workflows without vendor professional services.
Mission-critical investment sits with Enrollment Management. Capability expansion is climbing the fastest in Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States while consumption spreads across English-speaking higher education markets. North American vendors supply deployment infrastructure that institutions in Canada, the United Kingdom, and Australia adopt for recruitment operations. Data residency requirements fragment cloud architectures across national boundaries.
United States
Research-intensive university systems drive enterprise CRM procurement across multi-campus networks. The U.S. Department of Education enforces FERPA audit requirements that compel institutions toward cloud-native platforms with immutable access logs. Boston's higher education cluster anchors selective undergraduate adoption of configurable communication workflows.
Canada
Provincial university systems standardize on shared service models for enrollment management technology. Health Canada and the Office of the Privacy Commissioner coordinate oversight of cross-border student data flows. Ontario's Greater Toronto Area concentrates demand from institutions with complex international recruitment pipelines.
United Kingdom
Russell Group universities invest in predictive analytics for postgraduate yield optimization. The UK Information Commissioner's Office applies GDPR enforcement to student prospect databases held by cloud providers. London's institutional cluster leads adoption of AI governance tooling for admissions decision transparency.
Australia
Group of Eight universities deploy CRM platforms to manage offshore agent networks and pathway partnerships. The Office of the Australian Information Commissioner mandates breach notification protocols for international student data. Sydney and Melbourne anchor competitive procurement among institutions with high international enrollment ratios.
Germany
Technical universities adopt enrollment management systems for English-taught master's programs targeting non-EU applicants. The Federal Commissioner for Data Protection and Freedom of Information enforces strict data localization for student records. Bavaria's Munich cluster represents emerging demand from institutions expanding international marketing automation.
Higher Education Student CRM Solutions Market Competitive Landscape
Capital-heavy platform developers compete with asset-light configuration specialists across deployment models. The vendor base organizes into three tiers: enterprise suite providers anchoring university-system contracts, mid-market specialists integrating with legacy student information systems, and niche workflow vendors dominating selective undergraduate admissions. Consolidation pressure intensifies as institutions demand unified data architectures across graduate, professional, and undergraduate divisions. Strategic moves center on API ecosystem expansion and vertical integration into analytics infrastructure.
Among platform-native providers, Salesforce Education Cloud and Anthology occupy positions anchoring enterprise-wide deployments, while Slate by Technolutions exemplifies the workflow-specialist archetype with deep configuration capabilities. These three vendors represent contrasting approaches to institutional lock-in: ecosystem breadth versus legacy integration depth versus admissions-specific customization.
| Leading Market Players |
|---|
| Ellucian CRM |
| TargetX |
| Slate by Technolutions |
| Anthology |
| Blackbaud |
| Salesforce Education Cloud |
| ibl.ai |
| Jenzabar |
| Element451 |
| Others |
Supply & Pricing Matrix
Federal data privacy mandates gate qualified supply and premium-tier pricing access in the higher education student CRM market. The U.S. Department of Education's FERPA audit requirements compel institutions toward cloud-native platforms with immutable access logs, forcing vendors to absorb compliance architecture costs that stratify pricing tiers.
Pricing Analysis
Cost compression in mid-tier SaaS offerings accelerates because public university systems negotiate volume discounts tied to active user counts. Subscription-based procurement dominates, with three-tier pricing structure across premium, standard, and economy levels differentiating by analytics depth and customization scope. State flagship universities in California and Texas drive pricing pressure through multi-campus standardization demands. Community colleges exhibit highest price sensitivity, while research-intensive university systems accept premium tiers for predictive yield algorithms.
Supply Chain Analysis
FERPA-compliant cloud infrastructure certification gates vendor participation and fragments supply concentration across the United States, Ireland, and Germany. Platform development draws from specialized machine learning engineering talent, API middleware providers, and identity management systems. Single-source vulnerability concentrates in hyperscaler compute contracts for multi-tenant deployments. Distribution runs through direct enterprise sales teams and higher education technology consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The higher education student CRM market operates as a vertical-integration race, with vendors pursuing downstream control over analytics infrastructure to capture enrollment forecasting value.
For Market Incumbents: Lock in institutional switching costs through deeper student information system integration and native AI governance tooling. Anthology and Salesforce Education Cloud should prioritize API ecosystem expansion to defend against modular competitors. Graduate program pipeline consolidation represents the priority defensive perimeter. For New Entrants and Emerging Players: Community college systems with constrained IT budgets represent the most penetrable buyer archetype for scaled-down, preconfigured CRM modules. Two-year institutions in the Midwest and Southeast lack dedicated data science staff, creating white-space for plug-and-play deployment. A channel partnership strategy through regional higher education technology cooperatives accelerates market entry. For Investors and Strategic Acquirers: State attorney general enforcement actions in California and New York are the leading indicator that single-tenant private cloud capabilities will command acquisition premiums. Target vendors with demonstrated FERPA audit trail architectures and localized data residency options. Long-term viability rests on AI explainability feature development.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified data architectures across graduate, professional, and undergraduate divisions reduce institutional switching costs. |
| Acquisition of Specialist Firm | Predictive analytics boutiques with 80-plus percent yield accuracy thresholds extend competitive moats. |
| Geographic Expansion | English-language program marketing automation for non-EU applicants opens German technical university demand. |
| Product Launch | Native bias detection and explainability features differentiate vendor roadmaps before long-term contract commitments. |
| Strategic Partnership | Hyperscaler alliances for auto-scaling infrastructure reduce capital expenditure barriers for public university systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with chief information officers, enrollment management directors, CRM administrators, and student information system integration specialists combined with U.S. Department of Education policy documents, FERPA audit guidelines, and state attorney general enforcement records. Bottom-up vendor revenue triangulation against top-down institutional technology expenditure estimates validated market sizing.
Segment-level modeling deployed deployment architecture, end-user institution type, feature module, and regional regulatory cluster as core dimensions across the projection horizon. CAGRs derived from enrollment trend extrapolation, technology replacement cycle analysis, and vendor pipeline visibility. Machine learning inference accuracy thresholds and compliance mandate implementation timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state-level privacy statute expansion and federal AI governance rulemaking. Model outputs reflect assumptions regarding public cloud adoption rates and professional services labor availability. A model refresh is warranted upon material change in FERPA enforcement intensity or hyperscaler contract restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Cognitive Assessment and Training Market
Education & Training
Corporate Training Software Market
Education & Training
Global Adaptive Learning Market
Education & Training
Remote Learning Technology Spending Market
Education & Training
GCC Massive Open Online Course (MOOC) Market
Education & Training
Global Social Learning Platforms Market
Education & Training
HSE Consulting Training Services Market
Education & Training
GCC E-Learning Market
Education & Training
M-Education Market
Education & Training
Personal Development Market
Education & Training
Europe Soft Skills Training Market
Education & Training
SETM Education Market
Education & Training
Executive Education Program Market
Education & Training
Back to School Market
Education & Training
Digital Classroom Market
Education & Training
Executive Coaching and Leadership Development Market