
 Children's Programming Education Market | 2026-2036
Children's Programming Education Market Size, Share, and Industry Trends Forecast 2026-2036
Children's Programming Education Market Insights
GDPR and the EU AI Act are recalibrating the cost-of-entry calculus for children's digital education platforms operating across European member states. Code.org leverages its nonprofit status and district partnerships to sustain free curriculum distribution at scale. Khan Academy anchors its competitive position through deep integration with public school systems and adaptive learning pathways. Hetao 101 dominates the Mandarin-language segment with localized pedagogy and parent-facing progress dashboards.
Children's programming education encompasses structured instructional systems that teach algorithmic thinking, syntax literacy, and software creation to learners under eighteen, typically delivered through block-based visual interfaces like Scratch or text-based environments with scaffolded difficulty progressions. The primary commercial purpose is building foundational computational skills that transfer to STEM careers while addressing parent demand for future-ready competencies. Online courses now lead delivery mode revenue as asynchronous formats reduce instructor marginal costs, though hybrid classes capture the fastest enrollment growth by combining live mentorship with self-paced modules. Game development content commands premium pricing due to immediate visual feedback loops that sustain learner engagement, while robotics instruction requires higher hardware investment but generates superior retention rates and recurring kit purchases.
FCC guidelines on children's online privacy, COPPA compliance requirements, and emerging state-level student data protection statutes in California and Illinois collectively shape platform architecture decisions and parental consent workflows. BIS certification requirements in India and China's GB standards for educational software add further jurisdictional complexity for multinational providers. Stakeholders must monitor evolving algorithmic transparency mandates and age-verification technical standards as regulatory fragmentation intensifies operational burdens.
Market Dynamics
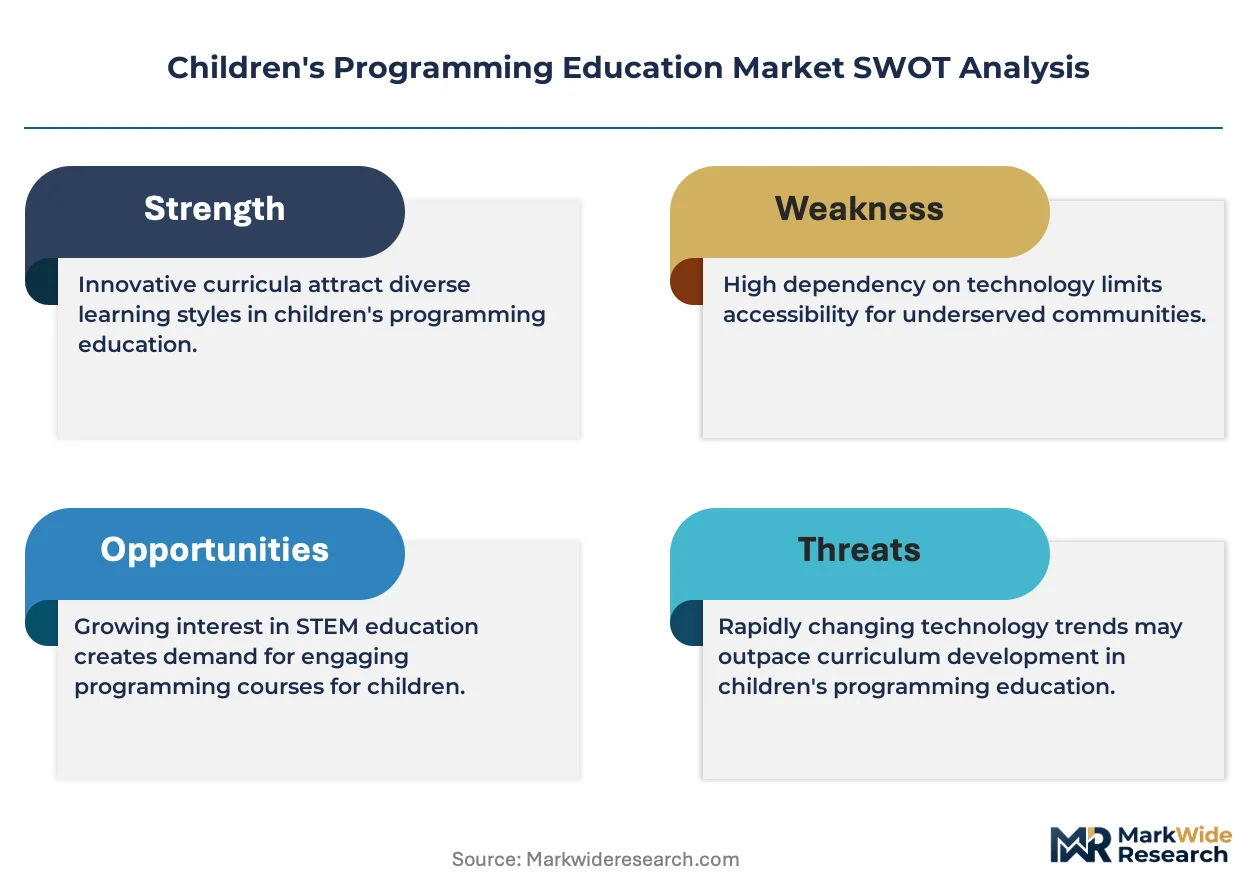
The children's programming education sector is restructuring around hardware-software convergence as robotics kits and cloud-based IDEs merge into unified learning stacks, compressing vendor margins while expanding addressable household spend.
Growth Catalysts
- Curriculum Mandates:China's Ministry of Education has embedded coding into compulsory national standards for primary grades, creating institutional demand that textbook publishers and edtech platforms must serve.
- Visual Feedback Loops:Game development content commands premium pricing due to immediate visual feedback that sustains learner engagement longer than abstract syntax exercises.
- GDPR:The EU AI Act and GDPR are recalibrating cost-of-entry calculus for platforms operating across European member states, favoring established compliance-heavy incumbents over lean entrants.
Market Restraints
- Hardware Cost Volatility:Robotics instruction requires higher semiconductor and sensor kit investment, exposing providers to Taiwan Strait supply concentration risks.
- COPPA Compliance Friction:FCC guidelines on children's online privacy and emerging state-level student data protection statutes in California and Illinois shape platform architecture decisions and inflate parental consent workflow costs.
- Block-to-Text Transition Dropout:Learner attrition spikes during the pedagogical shift from Scratch-style visual blocks to Python or JavaScript syntax, compressing lifetime value per cohort.
Strategic Opportunities
- Hybrid Delivery Models:Asynchronous online courses reduce instructor marginal costs while hybrid classes combining live mentorship with self-paced modules capture the fastest enrollment growth.
- Parent-Facing Dashboards:Mandarin-language platforms demonstrate that localized progress visualization for non-technical parents drives retention and word-of-mouth acquisition in East Asian markets.
- BIS Certification Pathways:India's BIS certification requirements for educational software create first-mover advantages for providers achieving compliance ahead of multinational entrants.
Industry Challenges
- Qualified Instructor Scarcity:Platforms face acute shortages of educators capable of teaching both computational thinking principles and age-appropriate classroom management.
- Cross-Border Data Architecture:China's GB standards for educational software and divergent age-verification technical standards force costly jurisdictional fragmentation of platform infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Children's Programming Education Market |
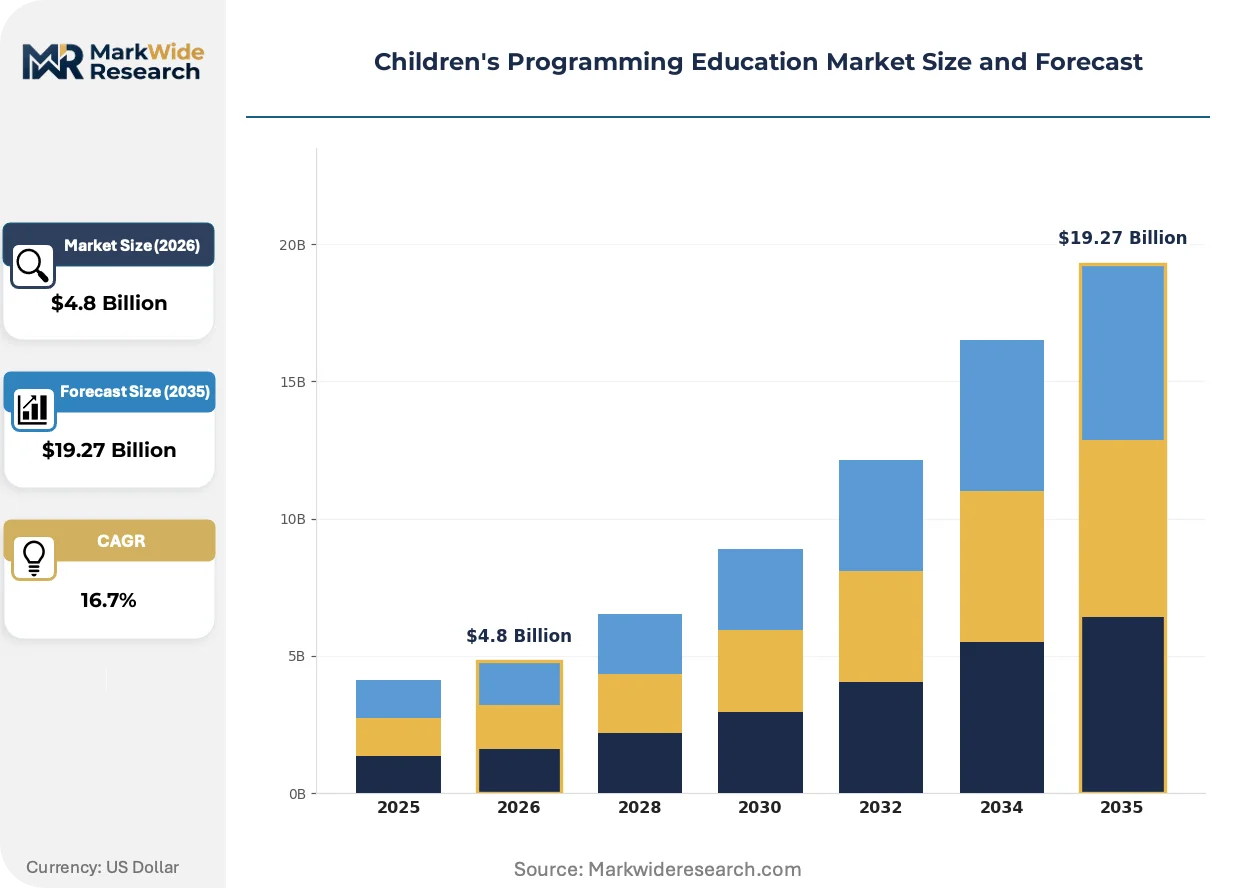
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Online Courses, In-Person Workshops, Hybrid Classes, Interactive Tutorials Age Group: Preschoolers, Elementary, Middle School, High School Content Type: Game Development, Robotics, Web Development, Mobile Apps Skill Level: Beginner, Intermediate, Advanced, Expert |
| Companies Covered | Hetao 101, AMAkids Education, Code.org, Codecademy, Scratch (MIT Media Lab), Khan Academy, Coursera, Udemy, Skillshare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Children's Programming Education Market Trends and Innovations
Generative AI tools are rewriting content production economics while regulatory pressure on child data protection intensifies technical compliance requirements across delivery platforms.
Edge-deployed AI tutors are decentralizing the traditional instructor-student relationship in coding education. Microcontroller manufacturers and regional telecoms are piloting localized inference chips that run personalized debugging assistance without cloud data transmission. K-12 districts with strict data residency requirements are adopting these systems fastest, compressing the addressable market for centralized SaaS platforms.
GDPR's Article 8 provisions on children's data and the EU AI Act's risk classification for educational applications are forcing architecture redesigns. Platform providers must now implement granular consent workflows and algorithmic transparency documentation that were previously optional. European operators are responding by segmenting product versions, with stripped-down feature sets for minors that reduce engagement metrics but satisfy regulator demands.
Parental purchasing committees are displacing individual subscription decisions in affluent districts. School-affiliated bulk purchasing consortia now negotiate enterprise licenses that bundle home access with classroom deployment, unbundling the direct-to-consumer channel that drove early market expansion. This pattern is most visible in suburban US school systems where parent-teacher organizations wield procurement influence.
Children's Programming Education Market Segmentation
Segmentation in children's programming education reveals how instructional design, learner development stages, and content formats intersect to determine platform economics and retention mechanics. Providers must align delivery infrastructure with age-appropriate pedagogy while managing hardware dependencies and regulatory compliance across jurisdictions.
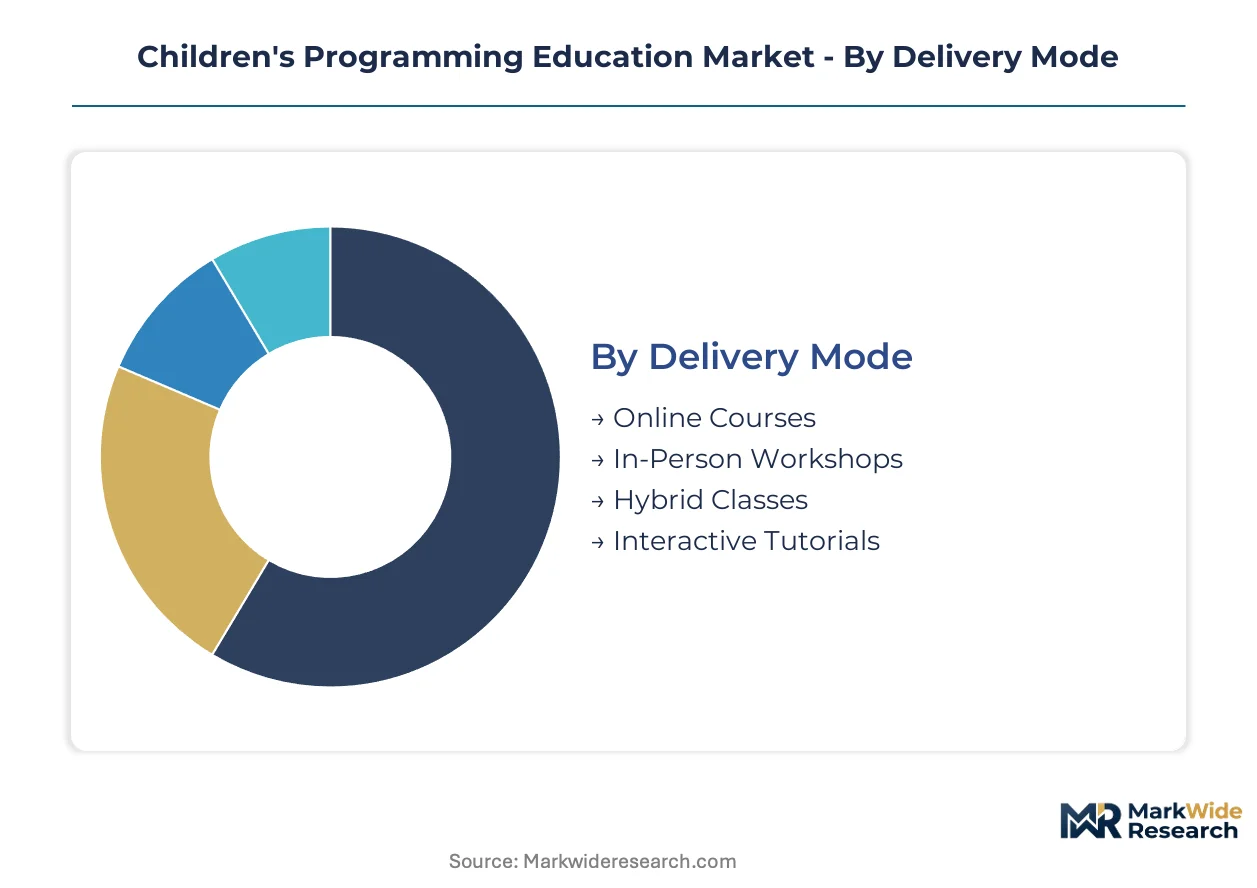
Delivery Mode:
Customization-to-standardization tension peaks in delivery architecture, where synchronous instruction demands localized staffing while asynchronous modules enable geographic arbitrage.
- Online Courses:Self-paced video modules with automated assessment engines dominate revenue contribution due to near-zero marginal cost per enrollment. Demand concentrates in suburban US districts where parent-teacher organizations negotiate bulk licenses combining classroom deployment with home access, though GDPR Article 8 consent workflows inflate European operational overhead.
- Hybrid Classes:Blended formats pairing live mentorship with asynchronous practice capture the steepest enrollment growth trajectory. Hardware-software convergence in robotics instruction favors this mode, as cloud-based IDEs require intermittent instructor intervention for debugging complex sensor integrations.
- In-Person Workshops:Location-constrained formats serving metropolitan clusters with qualified instructor density. BIS certification requirements in India and China's GB standards create jurisdictional fragmentation that favors regional specialists over multinational platform deployment.
- Interactive Tutorials:Gamified single-session experiences with immediate feedback loops. FCC COPPA compliance friction elevates parental consent workflow costs, compressing unit economics for under-13 audiences despite high engagement metrics.
Most installed capacity flows through Online Courses. Expansion is steepest in Hybrid Classes.
Age Group:
Developmental readiness dictates platform interface complexity and regulatory exposure tiering across learner cohorts.
- Elementary:Block-based visual programming environments like Scratch dominate, with curriculum mandates from China's Ministry of Education embedding coding into compulsory primary standards. Parent-facing progress dashboards in Mandarin-language platforms demonstrate retention mechanics transferable to other East Asian markets.
- Middle School:The block-to-text transition zone where learner attrition spikes during pedagogical shifts to Python or JavaScript syntax. California and Illinois state-level student data protection statutes shape platform architecture decisions for this cohort's rising digital independence.
- Preschoolers:Tangible computing interfaces with minimal screen time. EU AI Act risk classifications for educational applications force stripped-down feature sets that reduce engagement metrics but satisfy regulator demands for algorithmic transparency.
- High School:Industry-aligned certification preparation and portfolio development. Edge-deployed AI tutors with localized inference chips gain traction in K-12 districts with strict data residency requirements, compressing addressable market for centralized SaaS platforms.
Revenue concentration sits with Elementary. Portfolio value per learner peaks in High School.
Content Type:
Hardware intensity and visual feedback immediacy segment margin profiles and customer lifetime value.
- Game Development:Immediate visual feedback loops sustain learner engagement longer than abstract syntax exercises, commanding premium pricing. Parental purchasing committees in affluent US suburban districts prioritize tangible project outcomes that demonstrate skill acquisition.
- Robotics:Requires higher semiconductor and sensor kit investment with Taiwan Strait supply concentration risks, yet generates superior retention rates and recurring hardware purchases. Cloud-based IDE integration with microcontroller manufacturers compresses vendor margins while expanding addressable household spend.
- Web Development:Browser-based deployment minimizes hardware friction. GDPR and EU AI Act compliance recalibrations favor established incumbents with dedicated legal infrastructure over lean entrants targeting this lower-barrier segment.
- Mobile Apps:Platform-specific toolchain requirements (iOS/Android) fragment curriculum standardization. India's BIS certification pathways for educational software create first-mover advantages for providers achieving compliance ahead of multinational deployment.
Game Development anchors pricing power. Robotics commands the highest hardware attachment rates.
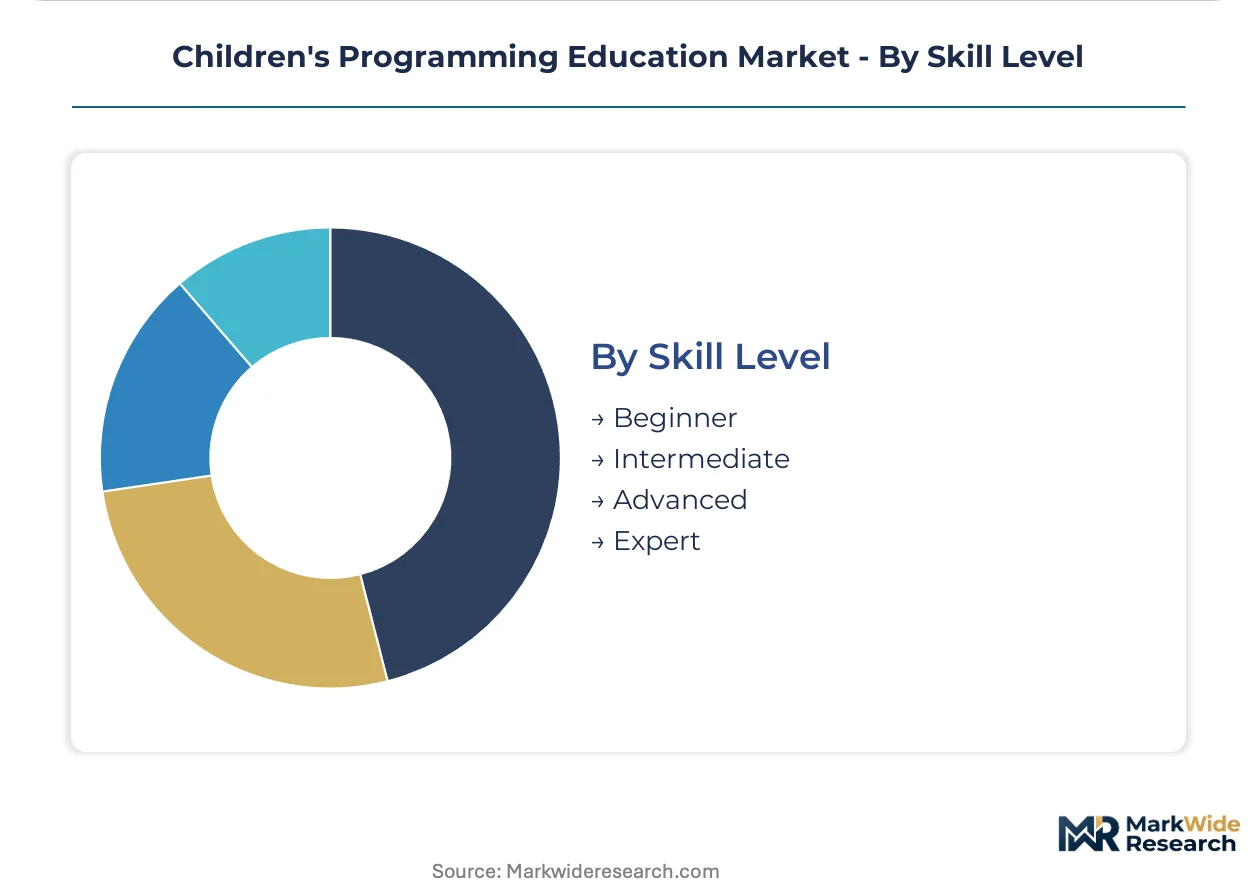
Skill Level:
Progression architecture determines cohort monetization depth and instructor qualification thresholds.
- Beginner:Visual block interfaces with scaffolded difficulty progressions. Free curriculum distribution at scale through nonprofit district partnerships sustains acquisition funnels despite low initial conversion.
- Intermediate:Syntax literacy development with personalized debugging assistance. Edge-deployed AI tutors are decentralizing traditional instructor-student relationships, with regional telecoms piloting localized inference chips that bypass cloud data transmission.
- Advanced:Project-based portfolio construction with industry mentorship. Acute shortages of educators capable of teaching both computational thinking principles and age-appropriate classroom management constrain supply expansion.
- Expert:Competitive programming and open-source contribution pathways. Minimal addressable population with highest instructor credential requirements and lowest platform scalability.
Beginner captures enrollment volume. Advanced generates per-learner margin peaks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The children's programming education industry traces its commercial roots to MIT Media Lab's 2007 release of Scratch, which scaled first through US after-school programs before China's 2014 national curriculum reforms institutionalized mass adoption.
United States
Suburban school districts in California and Texas drive enterprise licensing growth through parent-teacher organization procurement committees. FCC COPPA guidelines and emerging Illinois student data protection statutes elevate compliance architecture costs for platforms serving K-8 cohorts. The Greater Boston corridor hosts concentrated edtech development clusters where hardware-software convergence in robotics instruction advances fastest.
China
Ministry of Education mandates embedding coding into compulsory primary standards create institutional demand exceeding private household purchasing. GB standards for educational software and data residency requirements force jurisdictional platform fragmentation. The Yangtze River Delta metropolitan corridor concentrates domestic platform headquarters and parent-facing dashboard localization expertise.
Germany
Land-level education ministries in Bavaria and North Rhine-Westphalia pilot compulsory digital literacy modules that include block-based programming. GDPR Article 8 children's data provisions and EU AI Act risk classifications for educational applications recalibrate cost-of-entry for foreign platform entrants. Berlin-Brandenburg hosts regulatory compliance specialist clusters serving pan-European operators.
India
State government STEM initiatives in Karnataka and Maharashtra expand public school computer science adoption beyond elite urban academies. BIS certification requirements for educational software create first-mover structural advantages for early compliance achievers. The Delhi-NCR corridor concentrates regional platform development targeting Hindi-English bilingual instruction delivery.
United Kingdom
Department for Education computing curriculum mandates since 2014 sustain institutional demand through maintained school networks. ICO children's code provisions and emerging algorithmic transparency expectations shape platform consent workflow designs. London-Southeast clusters dominate English-language content export to Commonwealth education systems.
Children's Programming Education Market Competitive Landscape
The competitive structure tilts toward nonprofit-district partnership archetypes over pure commercial subscription models. Code.org anchors the free-curriculum segment through foundation-subsidized district relationships that constrain pricing power for paid entrants. Khan Academy occupies a parallel position in adaptive learning pathways. The market exhibits tiered concentration: global platforms with multilingual infrastructure, regional specialists with localized pedagogy, and hardware-integrated robotics providers. Dominant competitive moves include strategic partnerships with microcontroller manufacturers and geographic licensing of curriculum content to regional distributors.
Within the nonprofit-district partnership tier, Code.org and Khan Academy exemplify scale-through-access models that compress pricing elasticity for commercial entrants. Hetao 101 represents the regional specialist archetype, occupying a position within Mandarin-language instruction that demonstrates how parent-facing progress dashboards drive retention mechanics transferable to other East Asian markets. AMAkids Education sits within the premium-tier vector of franchise-delivered in-person instruction, anchoring a position that hardware-software convergence pressures most acutely.
| Leading Market Players |
|---|
| Hetao 101 |
| AMAkids Education |
| Code.org |
| Codecademy |
| Scratch (MIT Media Lab) |
| Khan Academy |
| Coursera |
| Udemy |
| Skillshare |
| Others |
Pricing and Supply Chain Analysis
Qualified coding instructor scarcity in Eastern European talent pools widens labor-cost differentials between premium live-mentorship tiers and self-paced economy modules. This workforce geography compresses mid-market pricing bands while elevating spreads between synchronous hybrid delivery and asynchronous subscription tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors platform revenue architecture. Premium tiers differentiate through live mentorship density and hardware kit bundling, while economy subscriptions compete on volume scale with automated assessment engines. Cost compression in the standard tier intensifies as cloud IDE providers consolidate debugging automation. Parent-teacher organization procurement committees exhibit lowest price sensitivity, whereas individual household subscribers in emerging markets drive economy-tier elasticity.
Supply Chain Analysis
Freight cost volatility for semiconductor sensor kits from Taiwan and South Korea elevates landed costs for robotics hardware bundles. Microcontroller manufacturing concentrates in Shenzhen, Dongguan, and Taipei, with curriculum content production anchored in Bangalore, Berlin, and Boston. Single-source vulnerability around Taiwan Strait logistics chokepoints threatens kit fulfillment timelines. Distribution runs through school district procurement consortia in affluent North American suburbs, bypassing direct-to-consumer channels for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in children's programming education rests on edge-AI tutor deployment collapsing live-instructor cost structures while premium robotics tiers capture hardware attachment premiums.
For Market Incumbents: Cement district partnership exclusivity through GB standards compliance in China and BIS certification in India before multinational entrants achieve jurisdictional parity. Deepen backward integration into microcontroller supply chains to buffer Taiwan Strait logistics exposure. Prioritize parent-facing dashboard localization as the retention lever against regional specialist encroachment. For New Entrants and Emerging Players: Edge-deployed AI debugging assistants offer a technology-first wedge into K-12 districts with strict data residency requirements. White-space concentration sits with preschool tangible computing interfaces underpenetrated by screen-based incumbents. Pursue franchise licensing of in-person workshop formats in Indian metropolitan corridors where qualified instructor scarcity constrains pure-platform scaling. For Investors and Strategic Acquirers: Regional telecoms piloting localized inference chips are the most active acquirer in this space, seeking curriculum content to bundle with edge hardware deployments. Long-term viability favors platforms with hybrid delivery infrastructure spanning synchronous mentorship and asynchronous automation. Watch for COPPA compliance cost spikes triggering consolidation among undercapitalized direct-to-consumer entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Tutor Deployment | Regional telecoms in Germany and Japan pilot localized inference chips that bypass cloud data transmission costs. |
| Hardware-Software Bundle Integration | Microcontroller manufacturers compress vendor margins while expanding addressable household spend per enrollment. |
| Parent-Facing Dashboard Localization | Mandarin-language platforms demonstrate retention mechanics transferable to Korean and Japanese markets. |
| District Partnership Exclusivity | Code.org's nonprofit foundation subsidies constrain pricing power for commercial entrants in North American K-12. |
| Regulatory Certification Pre-Positioning | EU AI Act risk classifications force architecture redesigns that favor established compliance-heavy incumbents. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with curriculum directors at K-12 districts, platform product executives, hardware kit procurement managers, and regulatory compliance officers. Secondary validation draws from Ministry of Education mandate documents, FCC COPPA guidance filings, EU AI Act regulatory texts, and BIS certification registries. Bottom-up enrollment data triangulates against top-down edtech spending estimates across the analysis window.
Granularity-level modeling segments by delivery mode, age cohort, content type, and skill progression tier. CAGRs derive from enrollment trajectory analysis and hardware attachment rate assumptions. Forecast inputs incorporate China's compulsory coding curriculum expansion, GDPR Article 8 consent workflow cost inflation, and Taiwan Strait logistics risk premiums.
The model holds under stable regulatory enforcement and semiconductor supply continuity; deviation in COPPA litigation trends or export control expansion would shift platform architecture investment requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Asia Big Data Analytics in Education Market
Education & Training
Global Admissions Software Market
Education & Training
Europe E-Learning Market
Education & Training
Global Digital English Language Learning Market
Education & Training
Smart Learning Systems Market
Education & Training
Research Publication Support Service Market
Education & Training
SETM Education Market
Education & Training
Higher Education Technology Market
Education & Training
Global AI in Education Market
Education & Training
Vocational English Course Counselling Solution Market
Education & Training
Artificial Intelligence in the Education Sector Market
Education & Training
Europe Consulting Services Market
Education & Training
Global Outplacement Services Market
Education & Training
Asia-Pacific Corporate Training Market
Education & Training
Early Childhood Education Market
Education & Training
Digital Educational Publishing Market