
 Asia-Pacific Corporate Training Market | 2026-2036
Asia-Pacific Corporate Training Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Corporate Training Market Analytics
Mid-market enterprises is rotating toward structured capability-building programs as the primary growth buyer archetype in the Asia-Pacific Corporate Training Market. Skillsoft Corp. leverages extensive digital content libraries to serve distributed workforces across Southeast Asia. NIIT Ltd. anchors instructor-led delivery networks throughout India and surrounding markets. Simplilearn competes through intensive certification bootcamps targeting cloud and data science competencies.
Corporate training encompasses structured workforce development programs delivered through instructor-led, self-paced, virtual instructor-led, and e-learning modalities to enhance employee productivity and organizational capability. The Asia-Pacific Corporate Training Market integrates online training platforms with classroom delivery to accommodate hybrid work arrangements prevalent across technology and finance sectors. Online training captures the fastest expansion trajectory as broadband infrastructure penetrates secondary cities across Indonesia and Vietnam. Classroom training retains durable share in manufacturing verticals where hands-on equipment certification remains mandatory. Blended learning occupies emerging margin pools as enterprises seek to balance engagement depth with scheduling flexibility.
India's PLI scheme and Australia's Skills Priority List directly shape enterprise reimbursement patterns and eligible training categories across the Asia-Pacific Corporate Training Market. TRAI digital infrastructure mandates and China's MIIT cybersecurity competency requirements further condition program content and delivery platform specifications. Stakeholders must monitor evolving national qualification frameworks as governments tighten alignment between subsidized training and verified labor market outcomes.
Market Dynamics
India's PLI scheme and Australia's Skills Priority List are compressing enterprise procurement cycles while forcing training providers to restructure certification content around verified labor market outcomes rather than generic competency frameworks.
Growth Catalysts
- TRAI Digital Infrastructure Mandates:India's broadband penetration requirements in secondary cities are expanding addressable enterprise bases for virtual instructor-led delivery models.
- Manufacturing Verticals:Hands-on equipment certification requirements in Indonesia's industrial zones sustain classroom training demand despite digital migration elsewhere.
- Hybrid Work Normalization:Technology and finance sectors across Singapore and Australia now require blended learning architectures that balance engagement depth with scheduling flexibility.
Market Restraints
- Content Localization Costs:Translation and cultural adaptation of standardized digital curricula creates margin pressure for providers serving Vietnam and Philippines markets simultaneously.
- Instructor Talent Concentration:Certified facilitators for cloud and data science bootcamps cluster in Bangalore and Sydney, creating supply bottlenecks for distributed delivery networks.
- Cybersecurity Competency Requirements:China's MIIT mandates force platform architecture modifications that fragment technical infrastructure investments across national boundaries.
Strategic Opportunities
- Vietnam's Secondary Cities:Broadband infrastructure expansion in Da Nang and Hai Phong creates first-mover advantages for localized e-learning platforms before competitor saturation.
- SkillsFuture Credit Integration:Singapore's individual learning accounts enable direct-to-learner revenue models that bypass traditional enterprise procurement bottlenecks.
- Micro-Credential Stacking:Modular certification pathways combining technical and soft skills respond to employer demands for verified competency portfolios rather than single-course completion.
Industry Challenges
- Certified Cloud Architect Scarcity:Qualified instructors for AWS and Azure bootcamps command premium compensation that compresses provider margins at scale.
- Legacy LMS Integration:Enterprise clients in Australia's financial services hubs require API compatibility with decades-old internal systems, extending implementation timelines.
- Outcome Verification Standards:National qualification frameworks across Indonesia and Philippines lack harmonization, complicating cross-border credential recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Corporate Training Market |
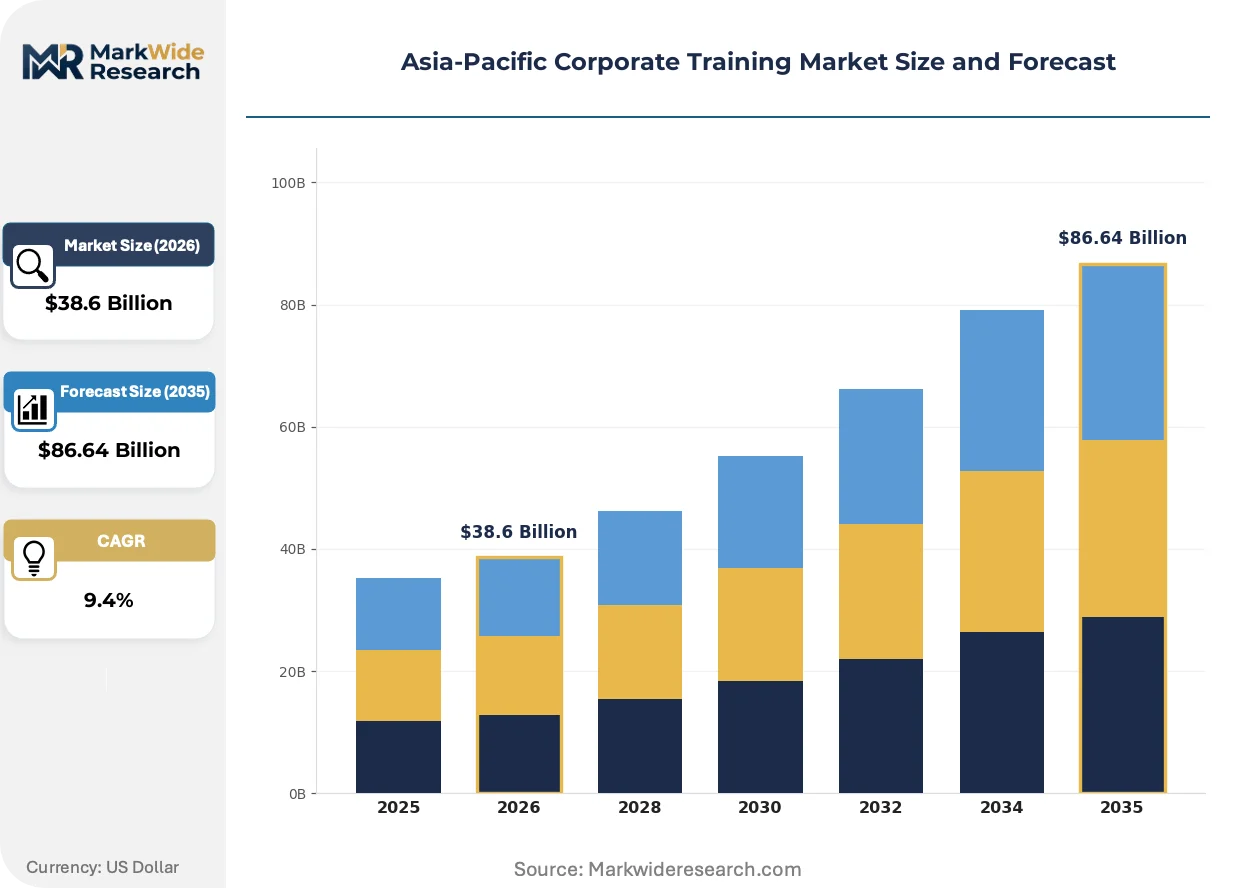
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Training Type: Online Training, Classroom Training, Blended Learning, Workshops Industry Vertical: Finance, Healthcare, Technology, Manufacturing Delivery Mode: Instructor-Led, Self-Paced, Virtual Instructor-Led, E-Learning End User: Corporates, SMEs, Educational Institutions, Government |
| Companies Covered | Cisco Systems Inc., Learning Technologies Group Plc, Skillsoft Corp., Korn Ferry, Simplilearn, GP Strategies Corporation, NIIT Ltd., BTS Group AB, Cornerstone, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Corporate Training Market Evolving Landscape
Artificial intelligence is restructuring content personalization and assessment validation across Asia-Pacific corporate training delivery models, forcing providers to reallocate development resources from production scale toward algorithmic adaptation.
Generative AI tutors are displacing standardized video modules as the primary self-paced delivery mechanism. Mid-market enterprises in India's technology corridor adopt these adaptive systems within six-month procurement cycles. The technology is displacing fixed-content libraries by enabling real-time curriculum adjustment based on individual learner performance patterns.
Australia's Skills Priority List now mandates direct alignment between subsidized training programs and verified occupational shortages, conditioning reimbursement eligibility on post-course employment tracking. Training providers must restructure program design around demonstrable job placement metrics rather than completion certificates alone. Financial services enterprises in Sydney and Melbourne face compressed compliance timelines to recertify workforces against updated priority occupations.
Enterprise buyers in Singapore and Hong Kong now demand consumption-based pricing tied to verified skill acquisition rather than seat-time contracts. Traditional annual licensing arrangements face displacement from per-competency billing models that transfer outcome risk to training vendors. Technology sector procurement teams lead this shift, using pilot programs with narrow cohorts before scaling commitments.
Asia-Pacific Corporate Training Market Segmentation
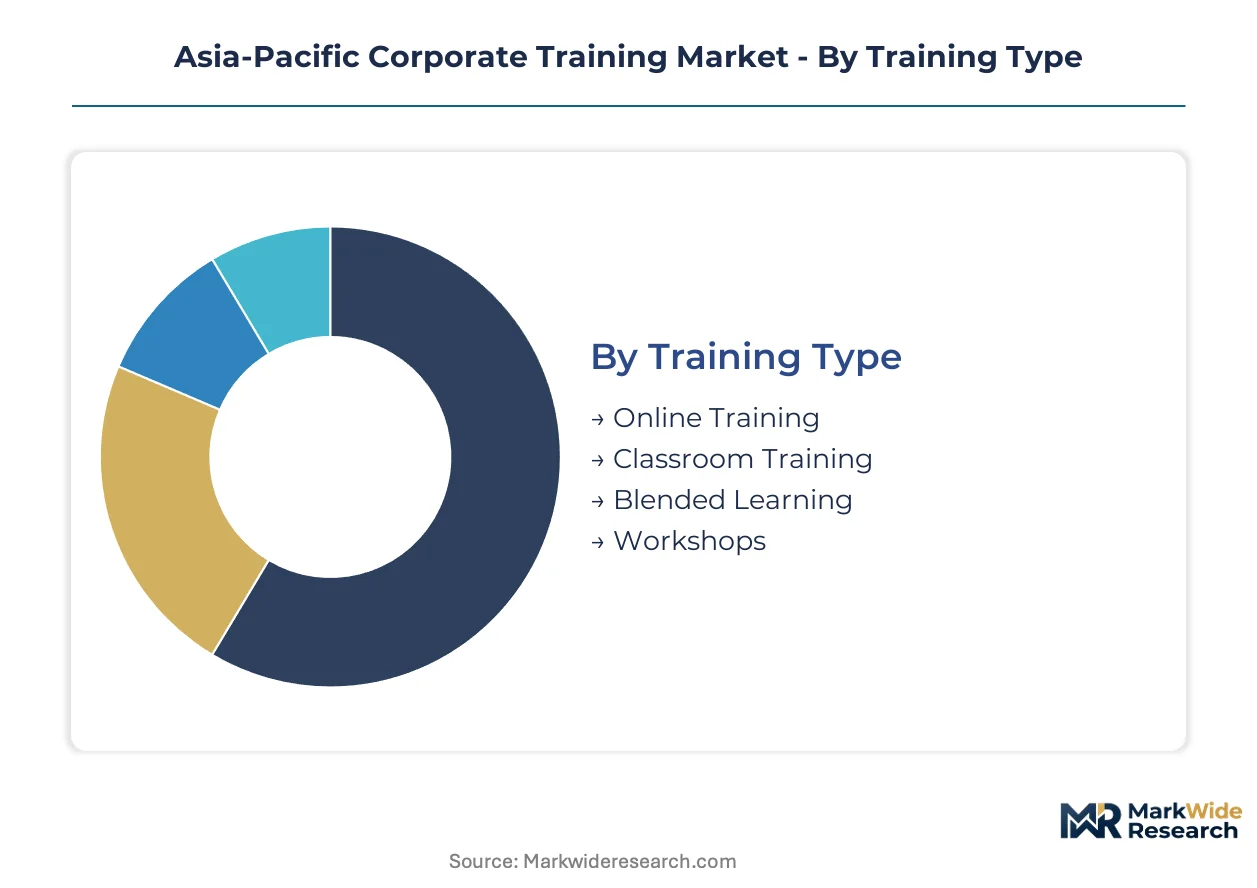
Training modality selection directly determines provider margin structure and capital intensity across Asia-Pacific markets. Procurement patterns diverge sharply between regulated industries requiring hands-on certification and technology sectors prioritizing scalable digital delivery.
Training Type:
Margin pools concentrate in delivery formats that balance engagement depth with geographic scalability across dispersed enterprise footprints.
- Online Training:Cloud-hosted modules enable asynchronous skill acquisition across Indonesia's expanding broadband infrastructure. India's PLI scheme beneficiaries in Bangalore and Hyderabad drive procurement volume for technical certification pathways.
- Blended Learning:Hybrid architectures combine synchronous virtual sessions with periodic in-person intensives. Singapore's financial services hubs and Sydney's enterprise clusters demand this format for compliance training requiring both flexibility and verified competency demonstration.
- Classroom Training:Instructor-led sessions dominate manufacturing verticals where equipment handling certification remains mandatory under occupational safety frameworks.
- Workshops:Intensive short-format programs address immediate skill gaps in leadership and project management competencies.
The dominant share belongs to Online Training, while Blended Learning is closing the gap fastest.
Industry Vertical:
Application intensity varies by regulatory burden and workforce turnover velocity across sectoral boundaries.
- Technology:Continuous upskilling mandates around cloud architecture and cybersecurity dominate procurement calendars. India's technology corridor enterprises under PLI scheme compliance drive volume for AWS and Azure certification pathways.
- Finance:Australia's Skills Priority List directly conditions reimbursement eligibility for risk management and regulatory compliance programs. Sydney and Melbourne banking clusters require frequent recertification cycles.
- Healthcare:Clinical competency updates and patient safety protocols sustain classroom delivery requirements despite digital migration elsewhere.
- Manufacturing:Indonesia's industrial zones sustain hands-on equipment certification demand under national occupational safety mandates.
Technology captures the steepest expansion trajectory, though Finance retains the highest per-learner contract values.
Delivery Mode:
Cost tier differentiation separates premium facilitated experiences from mass-market self-service platforms.
- Virtual Instructor-Led:Real-time remote facilitation enables synchronous engagement without travel overhead. TRAI broadband penetration mandates in India's secondary cities expand addressable bases for this format.
- Instructor-Led:Face-to-face delivery commands premium pricing for executive leadership and sensitive compliance content.
- Self-Paced:Asynchronous modules serve baseline competency requirements across distributed workforces with minimal marginal cost.
- E-Learning:Standardized digital libraries address evergreen skill domains through subscription licensing arrangements.
Virtual Instructor-Led holds the largest revenue base, while Self-Paced platforms are gaining share fastest among cost-conscious mid-market buyers.
End User:
Customer type determines procurement cycle length and contract structure complexity across the demand spectrum.
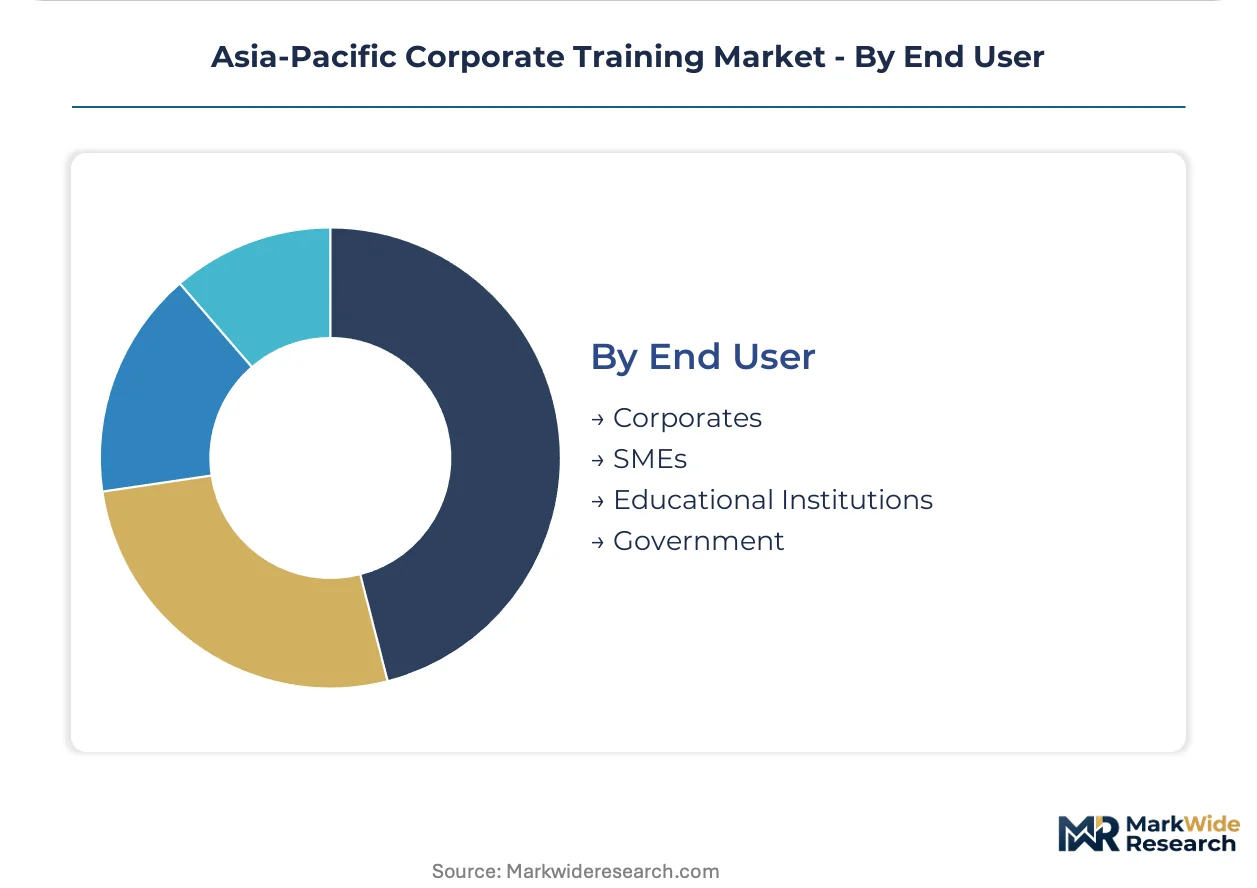
- Corporates:Large enterprises negotiate multi-year enterprise licensing with customized content integration requirements. Australia's financial services hubs and Singapore's technology clusters concentrate procurement volume.
- SMEs:Mid-market buyers rotate toward consumption-based pricing tied to verified skill acquisition rather than seat-time contracts.
- Government:Public sector procurement follows national qualification framework alignment requirements with extended vendor qualification timelines.
- Educational Institutions:Universities and vocational colleges serve as distribution channels for credential pathways bridging academic and enterprise competency standards.
Corporates command the dominant procurement value, while SMEs are expanding their share through direct-to-learner models bypassing traditional enterprise sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provider networks cluster in India's technology corridor and Australia's financial centers, with emerging infrastructure in Vietnam and Indonesia expanding addressable enterprise bases beyond traditional metropolitan hubs.
India
PLI scheme beneficiaries in Bangalore and Hyderabad drive procurement volume for cloud certification pathways. TRAI broadband mandates in secondary cities expand virtual instructor-led delivery reach. Karnataka and Telangana anchor instructor talent pools for data science bootcamps.
Australia
Sydney and Melbourne banking clusters require frequent recertification against Skills Priority List updates. TGA-aligned healthcare competency frameworks sustain classroom delivery requirements. Financial services procurement concentrates in New South Wales and Victoria.
Singapore
SkillsFuture Credit integration enables direct-to-learner revenue models bypassing enterprise sales cycles. Technology sector procurement teams demand consumption-based pricing tied to verified skill acquisition. Marina Bay and One-North districts concentrate fintech training demand.
Vietnam
Broadband infrastructure expansion in Da Nang and Hai Phong creates first-mover advantages for localized e-learning platforms. Manufacturing verticals in industrial zones sustain hands-on equipment certification demand. Northern and central provinces emerge as growth corridors.
Indonesia
Industrial zones in Java and Batam sustain classroom training requirements under national occupational safety mandates. Jakarta enterprise clusters drive blended learning adoption for compliance content. Secondary city broadband penetration expands asynchronous module reach.
Asia-Pacific Corporate Training Market Competitive Landscape
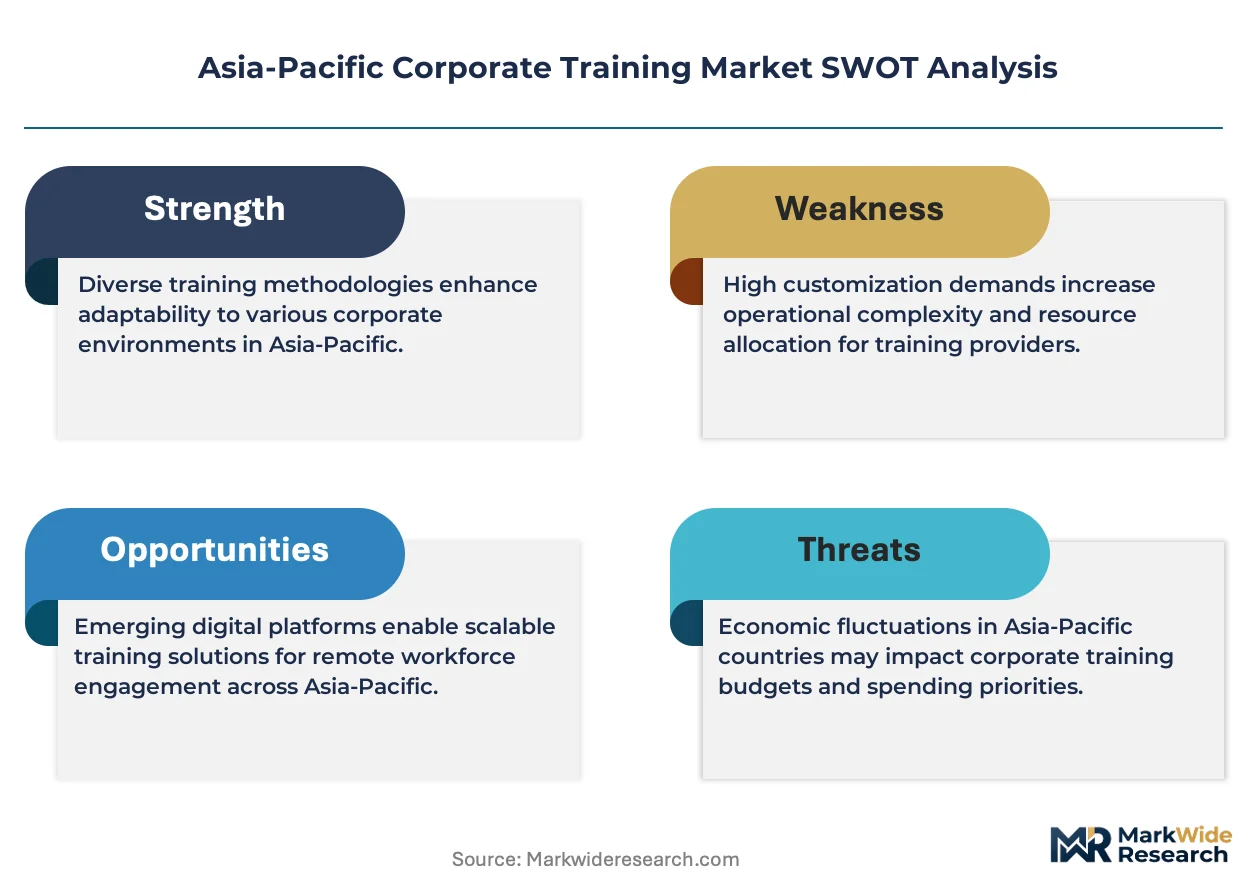
Concentration sits with diversified content libraries and instructor-led delivery networks serving distributed enterprise footprints. The vendor base spans global technology platforms, regional specialist providers, and localized certification bootcamp operators. Three archetypes dominate: integrated digital content platforms, instructor-network anchors, and intensive bootcamp specialists. Competitive moves center on AI-driven personalization investments and outcome-based pricing restructures.
Among integrated platform providers, Cisco Systems Inc. and Learning Technologies Group Plc occupy positions emphasizing scalable digital infrastructure. Skillsoft Corp. and NIIT Ltd. exemplify the instructor-network archetype with established delivery presence across multiple Asia-Pacific markets. Simplilearn represents the intensive bootcamp model targeting compressed certification timelines.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Learning Technologies Group Plc |
| Skillsoft Corp. |
| Korn Ferry |
| Simplilearn |
| GP Strategies Corporation |
| NIIT Ltd. |
| BTS Group AB |
| Cornerstone |
| Others |
Value Network & Pricing Analysis
Annual enterprise licensing contracts lock in multi-year supply access to instructor networks and digital content libraries across India's technology corridor and Australia's financial hubs. These arrangements provide price visibility for training providers while securing capacity commitments from certified facilitators concentrated in Bangalore and Sydney.
Pricing Analysis
Volume-discount tiering structures separate enterprise accounts purchasing 10,000+ seat licenses from mid-market buyers procuring sub-1,000 cohorts. Pricing stratifies across premium certification-grade content, standard competency modules, and economy self-paced libraries. Cost compression in the economy tier intensifies as generative AI tutors displace fixed-content subscriptions. Mid-market enterprises in Singapore exhibit the highest price sensitivity, while Australia's financial services procurement teams prioritize verified outcome metrics over per-seat cost.
Supply Chain Analysis
Certified cloud architect scarcity in Bangalore and Sydney creates a chokepoint that constrains scaling for AWS and Azure bootcamp delivery. Instructor talent draws from India's technology corridor, Australia's financial centers, and Singapore's fintech clusters. Raw material dependencies include broadband infrastructure, learning management system licenses, and assessment validation platforms. Single-source vulnerability concentrates in instructor-led delivery networks where qualified facilitators command premium compensation. Distribution runs through direct enterprise sales teams, channel partners, and SkillsFuture Credit-enabled direct-to-learner platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where established providers benefit from switching costs embedded in enterprise learning management system integrations and multi-year certification pathway commitments.
For Market Incumbents: Secure exclusive instructor network contracts in Bangalore and Sydney to lock out emerging bootcamp competitors from certified cloud architect talent pools. Deepen backward integration into proprietary AI-driven assessment engines to differentiate from commoditized content libraries facing generative AI displacement. For New Entrants and Emerging Players: Lead with micro-credential stacking platforms targeting Vietnam's secondary cities where broadband expansion outpaces incumbent platform localization. Capture first-mover positioning in Da Nang and Hai Phong through government-aligned competency frameworks before established providers restructure pricing for consumption-based models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors instructor-network anchors with proven placement metrics over pure-play digital content libraries. Long-term viability hinges on outcome-verification capabilities aligned with Australia's Skills Priority List employment tracking requirements. Monitor SkillsFuture Credit utilization rates as the inflection indicator for direct-to-learner model traction.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Personalization Investment | Generative AI tutors displace fixed-content libraries for India's PLI scheme beneficiaries. |
| Outcome-Based Pricing Restructure | Per-competency billing transfers employment risk to vendors serving Singapore fintech clusters. |
| Instructor Network Expansion | Certified cloud architect recruitment in Sydney alleviates supply bottlenecks for Azure pathways. |
| Micro-Credential Platform Launch | Modular certification stacking responds to employer demands for verified competency portfolios. |
| SkillsFuture Credit Integration | Direct-to-learner revenue models bypass traditional enterprise procurement cycles in Singapore. |
Research Methodology
A standing panel of chief learning officers, enterprise procurement directors, certified training facilitators, and regulatory affairs specialists provided ongoing calibration across primary fieldwork phases. Secondary validation drew from TRAI broadband penetration reports, Australia's Skills Priority List updates, Singapore SkillsFuture program disclosures, and PLI scheme beneficiary announcements. Bottom-up demand modeling triangulated against top-down market sizing from enterprise licensing disclosures and government training subsidy allocations.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler certification issuance data and national qualification framework enrollment statistics. The analytical framework modeled training modality, industry vertical, delivery mode, and end-user segmentation dimensions across the projection horizon. CAGRs were derived from regression analysis of historical procurement cycles and policy incentive trajectories, incorporating PLI scheme expansion timelines and broadband infrastructure deployment schedules as structural inputs.
Forecasts assume regulatory continuity in India's TRAI mandates, Australia's Skills Priority List alignment requirements, and Singapore's SkillsFuture Credit structures; material policy shifts would require re-modeling of reimbursement eligibility and procurement cycle assumptions. Practitioners should keep alternative scenarios live as cybersecurity competency requirements from China's MIIT and evolving national qualification frameworks across Indonesia and Philippines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
Corporate eLearning Market
Corporate Training and Talent Development
Frontline Workers Training Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Europe Consulting Services Market
Corporate Training and Talent Development
Europe Executive Search (Headhunting) Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
IT Training Market
Corporate Training and Talent Development
Private Tutoring Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market