
 Asia Pacific Strategic Consulting Services Market | 2026-2036
Asia Pacific Strategic Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Strategic Consulting Services Market Outlook
Mid-market private equity sponsors are collapsing the traditional dominance of Fortune 500 accounts as the fastest-growing buyer archetype across the region. Kearney anchors its competitive position through deep operational turnaround expertise in industrial portfolios throughout Southeast Asia. YCP Solidiance differentiates by embedding bilingual execution teams inside Japanese and Korean manufacturing clients. PwC Advisory extends its governance and risk consulting footprint through integrated audit-advisory bundling that large family offices find difficult to replicate.
Strategic consulting services encompass structured advisory engagements that diagnose competitive position, design operational improvements, and orchestrate organizational change through hypothesis-driven problem solving, primary research, and financial modeling. These engagements typically deploy partner-led teams working 12- to 24-week sprints to reduce cost bases, enter adjacent markets, or restructure capital allocation across business units. Management consulting occupies the largest fee pool as boards confront prolonged margin compression in consumer goods and manufacturing verticals. IT consulting registers the fastest expansion as cloud migration and AI governance mandates multiply across regulated industries. Project-based engagements still dominate revenue recognition, though retainer relationships with technology sector clients are deepening as product cycles compress and strategic planning horizons shorten.
Japan's METI issues industrial competitiveness roadmaps that directly shape advisory demand in automotive and semiconductor supply chain restructuring. India's SEBI and RBI frameworks on corporate governance and stressed asset resolution create recurring compliance-driven consulting procurement. Australia's TGA and prudential standards add healthcare and financial services regulatory complexity that foreign consultancies must navigate through local partnerships. Stakeholders must monitor how ASEAN member states harmonize cross-border data governance rules, as divergent digital compliance regimes will determine which advisory firms can scale regional delivery platforms without fragmenting practice economics.
Market Dynamics
Digital transformation mandates from Japan's METI and India's PLI scheme are compressing strategic planning cycles across Asia Pacific, forcing advisory firms to embed execution teams inside client operations rather than deliver episodic studies.
Growth Catalysts
- India's PLI scheme:Domestic conglomerates and multinational subsidiaries compete for top-tier advisory talent to structure incentive-compliant capital allocation and supply chain localization.
- Cloud migration mandates:Regulated industries across Southeast Asia require IT consulting for AI governance frameworks and multi-cloud architecture, expanding fee pools beyond traditional management consulting.
- Mid-market private equity:Sponsors are collapsing Fortune 500 account dominance as the fastest-growing buyer archetype, demanding operational turnaround expertise in industrial portfolios.
Market Restraints
- Talent scarcity:Bilingual execution capabilities in Japanese and Korean manufacturing clients concentrate in a narrow consultant pool, inflating compensation costs.
- Audit-advisory bundling:PwC Advisory's integrated governance and risk consulting footprint creates procurement friction for independent boutiques competing on specialized expertise.
- Regulatory fragmentation:Divergent ASEAN cross-border data governance rules fragment practice economics for firms attempting regional delivery platform scaling.
Strategic Opportunities
- Stressed asset resolution:India's SEBI and RBI frameworks on corporate governance create recurring compliance-driven consulting procurement from distressed industrial borrowers.
- Healthcare regulatory complexity:Australia's TGA standards and prudential requirements open advisory white space for local partnership models in pharmaceutical and medical device supply chains.
- Retainer relationship deepening:Technology sector clients are compressing strategic planning horizons, creating subscription-style advisory revenue as product cycles accelerate.
Industry Challenges
- Hypothesis-driven methodology retention:Partner-led team models struggle to preserve analytical rigor while compressing 24-week sprints into shorter client-mandated timelines.
- Primary research access:State-owned enterprise procurement processes in Southeast Asia restrict independent data gathering, degrading diagnostic quality for competitive positioning studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Strategic Consulting Services Market |
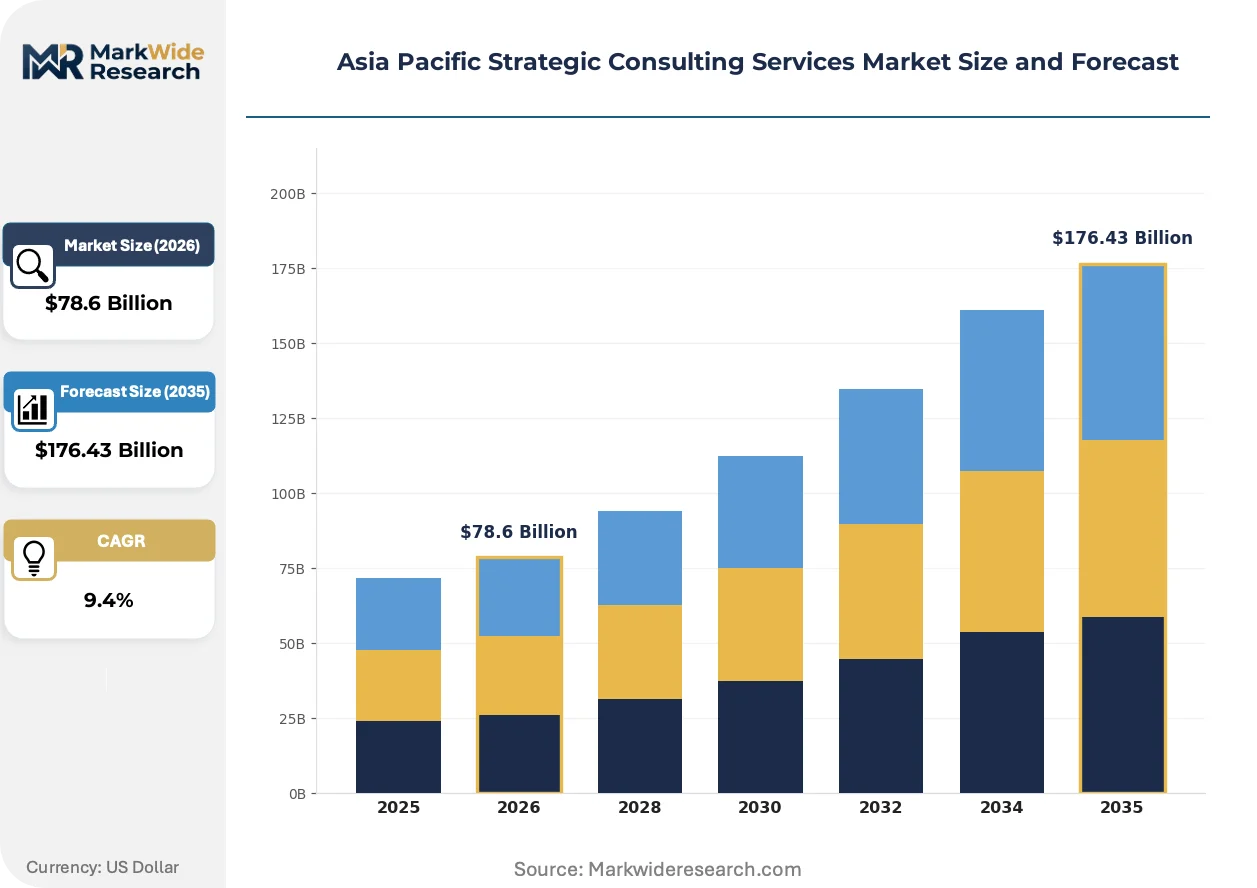
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $176.43 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Management Consulting, IT Consulting, HR Consulting, Financial Advisory Industry Vertical: Healthcare, Technology, Consumer Goods, Manufacturing Client Size: Small Enterprises, Medium Enterprises, Large Corporations, Startups Engagement Model: Project-Based, Retainer, Consulting Hours, Workshops |
| Companies Covered | Kearney, Accenture Strategy, McKinsey & Company, Roland Berger, Deloitte Consulting, Boston Consulting Group, YCP Solidiance, PwC Advisory, Bain & Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Strategic Consulting Services Market Strategic Shifts
Advisory delivery models are fragmenting as client organizations internalize diagnostic capabilities and demand embedded execution rather than PowerPoint-based recommendations.
Generative AI tooling is decomposing traditional financial modeling and primary research workflows. Mid-market private equity sponsors deploy these tools for rapid due diligence, compressing the value of junior consultant labor. Partner-level judgment remains scarce, but hypothesis generation and data synthesis are commoditizing faster than firms can retrain staff.
Japan's METI issues industrial competitiveness roadmaps that directly shape advisory demand in automotive and semiconductor supply chain restructuring. These mandates require consultancies to maintain Tokyo-based policy liaison capabilities, raising fixed cost structures. Korean manufacturing clients now expect simultaneous compliance with METI guidance and domestic MFDS standards.
Buyer concentration among technology sector clients is forcing advisory firms into continuous engagement models. Quarterly strategic sprints replace annual planning cycles in Singapore and Bangalore. Retainer structures deepen as product teams demand real-time competitive intelligence rather than episodic market entry studies.
Asia Pacific Strategic Consulting Services Market Segmentation
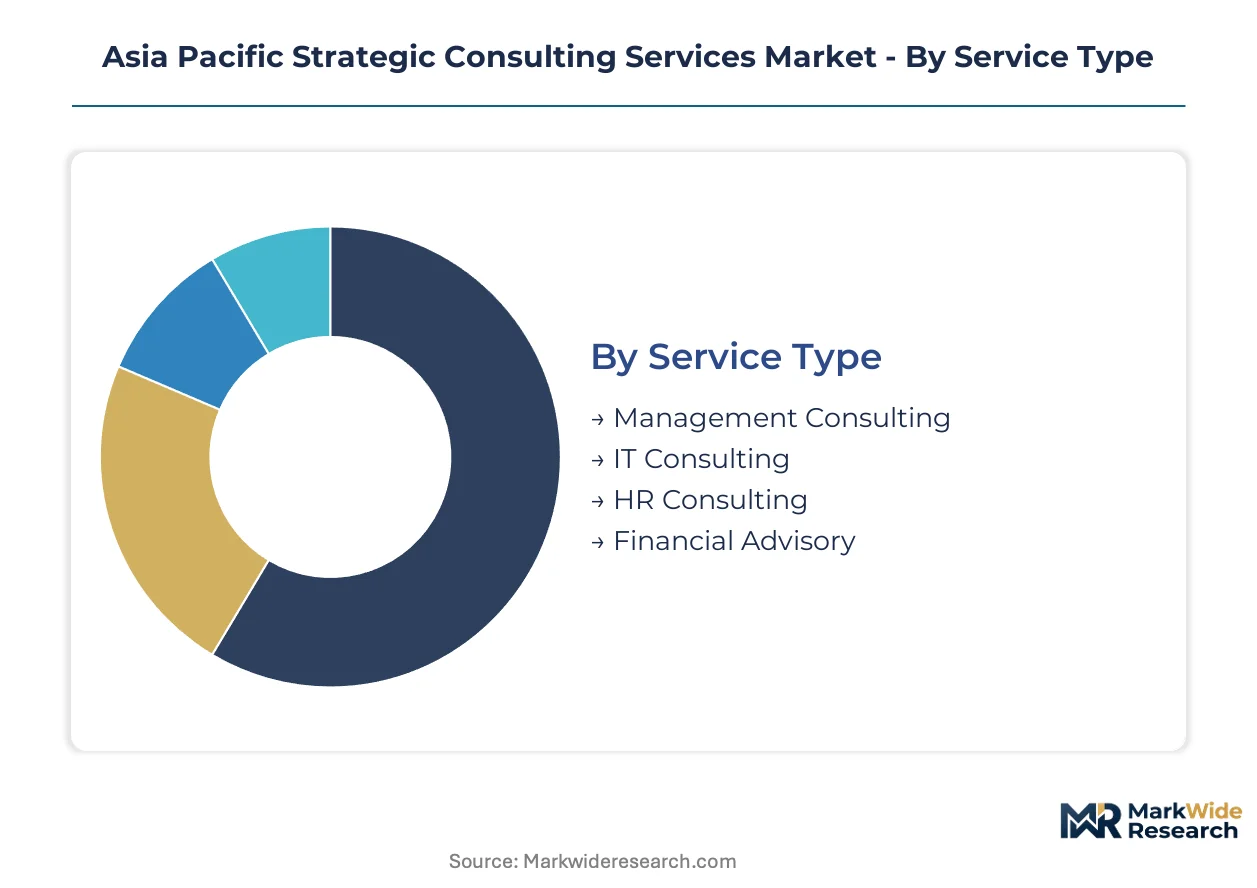
Strategic consulting procurement patterns diverge sharply across service archetypes and client maturity levels. Segmentation reveals where advisory firms must restructure delivery models versus where traditional partner-led engagements still command premium pricing.
Service Type:
Management consulting faces acute substitution pressure from in-house strategy functions at technology conglomerates, while IT consulting retains structural demand from compliance mandates.
- Management Consulting:Structured advisory engagements diagnose competitive position and orchestrate organizational change through hypothesis-driven problem solving. Boards at Indian conglomerates and Japanese automotive suppliers commission partner-led teams for 12- to 24-week cost reduction and market entry sprints.
- IT Consulting:Cloud migration and AI governance mandates multiply across regulated Southeast Asian industries, expanding fee pools beyond traditional advisory. Australia's TGA and India's RBI frameworks require multi-cloud architecture advisory that generalist boutiques cannot replicate.
- HR Consulting:Talent scarcity in bilingual Japanese and Korean manufacturing execution teams drives organizational design mandates.
- Financial Advisory:Stressed asset resolution under India's SEBI frameworks creates recurring procurement from distressed industrial borrowers.
Management consulting retains volume leadership; IT consulting holds the steepest expansion curve.
Industry Vertical:
Cost tier stratification separates verticals where advisory fees scale with regulatory complexity versus those where internal strategy teams absorb diagnostic functions.
- Healthcare:Australia's TGA standards and prudential requirements open advisory white space for local partnership models in pharmaceutical supply chains. Medical device manufacturers commission compliance-driven restructuring as product registration timelines compress.
- Technology:Quarterly strategic sprints replace annual planning cycles in Singapore and Bangalore as product teams demand real-time competitive intelligence. Retainer structures deepen with continuous engagement models supplanting episodic studies.
- Consumer Goods:Prolonged margin compression in Southeast Asian markets drives operational turnaround procurement from mid-market private equity sponsors.
- Manufacturing:Japan's METI industrial competitiveness roadmaps directly shape advisory demand in automotive and semiconductor supply chain restructuring.
Manufacturing commands the largest fee pool; technology verticals are climbing the fastest.
Client Size:
Customer type fragmentation concentrates premium advisory talent at scale extremes while mid-market procurement standardizes.
- Large Corporations:Fortune 500 subsidiaries compete for top-tier advisory talent to structure India PLI scheme-compliant capital allocation. Procurement processes restrict independent data gathering, degrading diagnostic quality for competitive positioning studies.
- Startups:Venture-backed technology ventures in Bangalore and Singapore compress strategic planning horizons, creating subscription-style advisory revenue as product cycles accelerate.
- Medium Enterprises:Mid-market private equity sponsors are collapsing traditional dominance of large corporate accounts as the fastest-growing buyer archetype.
- Small Enterprises:Limited procurement sophistication restricts advisory access to standardized workshop formats and templated diagnostic tools.
Large corporations retain volume leadership; startups hold the steepest expansion trajectory.
Engagement Model:
Margin compression varies by delivery structure, with embedded execution teams commanding premium pricing against commoditized workshop formats.
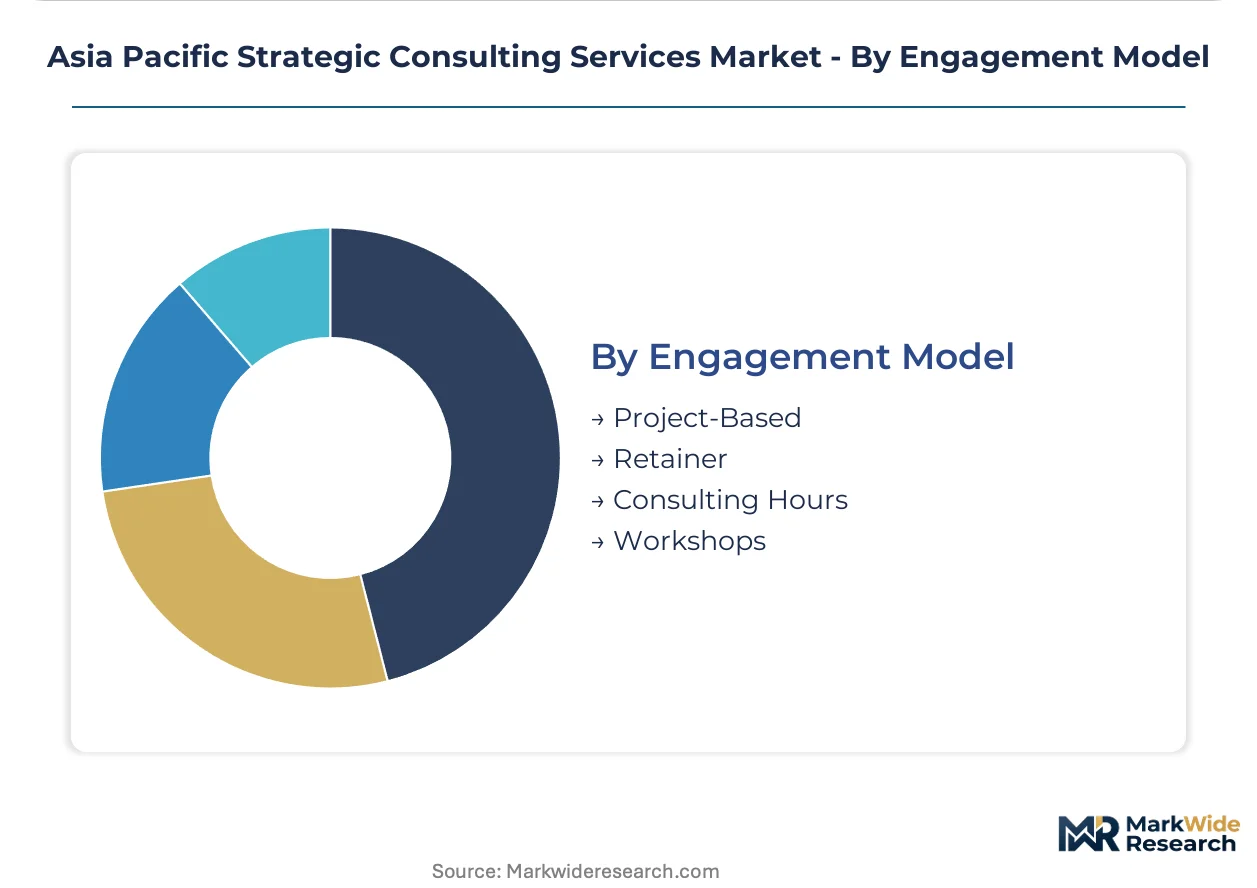
- Project-Based:Traditional 12- to 24-week sprints still dominate revenue recognition for operational turnaround and market entry mandates. Partner-led teams struggle to preserve analytical rigor while compressing timelines.
- Retainer:Technology sector clients demand real-time competitive intelligence rather than episodic studies, deepening continuous engagement models in Singapore and Bangalore.
- Consulting Hours:Time-based billing persists for compliance-driven advisory under India's RBI and SEBI frameworks where scope uncertainty prevents fixed pricing.
- Workshops:Standardized diagnostic sessions face substitution from generative AI tooling that decomposes traditional financial modeling workflows.
Project-based engagements retain volume leadership; retainer relationships are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advisory talent clusters in Tokyo, Singapore, and Bangalore, with each hub serving distinct regulatory and client archetypes across the region. METI roadmaps, SEBI frameworks, and PLI compliance mandates generate divergent procurement patterns that fragment delivery economics.
Japan
Automotive and semiconductor supply chain restructuring drives sustained demand for Tokyo-based policy liaison capabilities. METI industrial competitiveness roadmaps mandate consultancies to maintain fixed-cost policy intelligence functions. Osaka manufacturers now require simultaneous compliance with METI guidance and domestic standards, compressing advisory timelines.
India
Domestic conglomerates and multinational subsidiaries compete aggressively for partner-level talent to structure PLI scheme-compliant capital allocation. SEBI and RBI frameworks on corporate governance and stressed asset resolution create recurring compliance-driven procurement. Mumbai and Bangalore clusters concentrate distressed industrial borrower advisory and technology sector retainer relationships respectively.
Australia
Healthcare regulatory complexity opens advisory white space as TGA standards and prudential requirements intensify. Pharmaceutical and medical device manufacturers commission compliance-driven restructuring as product registration timelines compress. Sydney-based consultancies navigate these frameworks through local partnership models that foreign competitors struggle to replicate.
Singapore
Technology sector clients compress strategic planning horizons from annual to quarterly cycles, demanding real-time competitive intelligence. ASEAN headquarters for multinational corporations concentrate procurement of continuous engagement models. State-owned enterprise procurement processes restrict independent data gathering, degrading diagnostic quality for competitive positioning studies.
South Korea
Manufacturing clients expect simultaneous adherence to METI guidance and domestic MFDS standards, raising compliance advisory complexity. Bilingual execution capabilities concentrate in a narrow consultant pool, inflating compensation costs. Seoul-based advisory teams embed inside chaebol operations to deliver operational turnaround rather than episodic studies.
Asia Pacific Strategic Consulting Services Market Competitive Environment
Concentration sits with global strategy houses and integrated audit-advisory networks, while regional boutiques occupy specialized niches. The market structure tiers into three archetypes: hypothesis-driven generalists, operational turnaround specialists, and regulatory compliance bundlers. M&A activity targets bilingual execution capabilities, and portfolio diversification into embedded retainer models represents the dominant competitive move.
Within the operational turnaround tier, Kearney and YCP Solidiance exemplify divergent geographic anchoring strategies. Kearney maintains Southeast Asian industrial portfolio expertise, while YCP Solidiance embeds teams inside Japanese and Korean manufacturing clients. PwC Advisory occupies a distinct position through integrated audit-advisory bundling that large family offices find difficult to displace.
| Leading Market Players |
|---|
| Kearney |
| Accenture Strategy |
| McKinsey & Company |
| Roland Berger |
| Deloitte Consulting |
| Boston Consulting Group |
| YCP Solidiance |
| PwC Advisory |
| Bain & Company |
| Others |
Value Chain & Pricing Dynamics
Japan's METI industrial competitiveness roadmaps gate both advisory firm qualification and fee tier differentiation simultaneously, as Tokyo-based policy liaison capabilities become mandatory cost centers that only premium-tier consultancies can amortize across sufficient client volume.
Pricing Analysis
India's SEBI and RBI frameworks dictate the pricing tier structure across compliance-driven advisory segments, with three-tier pricing separating partner-led strategic mandates from manager-delivered implementation support and templated diagnostic workshops. Price differentiation rests on bilingual execution depth and METI policy intelligence access rather than generic brand premium. Cost compression in mid-market private equity procurement is intensifying because sponsors deploy generative AI tooling for rapid due diligence. Technology sector clients show least price sensitivity due to compressed product cycles demanding real-time competitive intelligence.
Supply Chain Analysis
Port congestion across the Shanghai-Singapore trade lane elevates inbound logistics costs for advisory firms flying execution teams into Southeast Asian manufacturing clients. Talent supply concentrates in India, Japan, and Singapore, with Mumbai and Bangalore clusters feeding distressed industrial borrower advisory and technology retainer relationships respectively. Raw material inputs draw from partner-level judgment, bilingual analyst pools, and regulatory database subscriptions. Single-source vulnerability sits with narrow consultant pools possessing simultaneous Japanese-Korean manufacturing fluency. Distribution runs through partner-led relationship networks rather than standardized channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where METI policy liaison capabilities and SEBI compliance expertise create switching costs that client organizations cannot replicate internally.
For Market Incumbents: Compound defensive positioning through deeper embedding of execution teams inside client operations and accelerated acquisition of bilingual Japanese-Korean talent pools. Generative AI tooling threatens junior consultant labor value, demanding retraining investment toward partner-level judgment preservation. Vertical integration into continuous retainer models with technology sector clients anchors revenue predictability against episodic project volatility. For New Entrants and Emerging Players: Anchor in Australia's healthcare regulatory white space, where TGA standards and prudential requirements exceed foreign consultancy navigation capabilities without local partnership structures. The most penetrable segment lies in pharmaceutical supply chain compliance advisory for medical device manufacturers facing compressed product registration timelines. A direct-to-hospital-system go-to-market angle bypasses entrenched audit-advisory bundling advantages. For Investors and Strategic Acquirers: India's PLI scheme maturation reshapes the acquisition landscape toward distressed industrial borrower advisory capabilities and PLI-compliant capital allocation structuring expertise. Long-term viability favors boutique firms possessing simultaneous METI policy intelligence and SEBI framework navigation depth. Monitor ASEAN cross-border data governance harmonization progress as the critical inflection signal for regional delivery platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Execution Team Expansion | Deepens client operational integration beyond PowerPoint-based deliverables in Japanese automotive supply chains. |
| Bilingual Talent Acquisition | Captures scarce Japanese-Korean manufacturing advisory capacity inflating compensation costs across Seoul and Osaka. |
| Retainer Model Conversion | Transforms episodic project revenue into subscription-style relationships with Bangalore technology sector clients. |
| Local Partnership Structuring | Unlocks TGA-compliant healthcare advisory access for foreign consultancies lacking Sydney-based regulatory navigation. |
| Policy Liaison Capability Buildout | Secures METI roadmap influence access mandatory for automotive and semiconductor supply chain restructuring mandates. |
Study Parameters
Desk research of regulatory filings, industry association reports, and consultancy capability disclosures preceded structured interviews with advisory firm partners, private equity operating partners, and corporate strategy directors. Primary fieldwork captured procurement decision criteria, pricing benchmark data, and talent competition dynamics across Tokyo, Singapore, Mumbai, and Bangalore clusters. Secondary validation drew from SEBI circulars, METI industrial policy documents, and ASEAN regulatory harmonization progress reports. Bottom-up engagement model sizing and top-down market value triangulation anchored quantitative outputs.
Variance decomposition across service type, industry vertical, client size, and engagement model dimensions shaped analytical framework construction over the projection horizon. CAGRs were derived from segment-level growth rate assumptions calibrated to regulatory mandate intensity and buyer archetype expansion patterns. Forecast inputs incorporated PLI scheme disbursement trajectories, cloud migration compliance timelines, and mid-market private equity dry powder deployment rates.
Underlying assumptions cover sustained regulatory complexity escalation and talent scarcity persistence, with deviation risk concentrated in ASEAN data governance harmonization acceleration or generative AI tooling adoption curves exceeding modeled parameters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Asia-Pacific Corporate Training Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
Talent As a Service Market
Corporate Training and Talent Development
Global Sales Training Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
Corporate Training Services Market
Corporate Training and Talent Development
Executive Coaching Certification Market
Corporate Training and Talent Development
Asia Pacific HR Professional Services Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Frontline Workers Training Market
Corporate Training and Talent Development
Europe Consulting Services Market
Corporate Training and Talent Development
Canada Outplacement Services Market
Corporate Training and Talent Development
United States HR Professional Service Market