
 Business Coaching Service Market | 2026-2036
Business Coaching Service Market Size, Share, and Industry Trends Forecast 2026-2036
Business Coaching Service Market Insights
Corporate training procurement is fragmenting as enterprises bypass traditional learning-and-development vendors to contract coaches directly. Ezra leverages its AI-matching platform to sustain premium placement with Fortune 500 HR departments. FranklinCovey anchors its position through licensed facilitator networks that control curriculum distribution across North America and Asia. CoachHub competes by extending its digital coaching marketplace into behavioral health and well-being adjacencies.
Business coaching services encompass structured, goal-oriented interventions delivered by credentialed professionals to improve managerial decision-making, team dynamics, and organizational performance, typically through recurring synchronous sessions with measurable outcome frameworks. Leadership development programming commands the largest revenue pool among service types due to C-suite succession pressures and board-level accountability mandates. Online coaching and hybrid programs are expanding fastest within delivery models as asynchronous scheduling and multi-time-zone deployment reduce per-session operational overhead. Subscription-based pricing is displacing hourly arrangements among mid-sized enterprise buyers seeking predictable talent development budgets.
ISO 30414 human capital reporting standards and the EU's Corporate Sustainability Reporting Directive shape disclosure requirements that elevate coaching outcomes to audit-relevant metrics in Europe. The US Occupational Safety and Health Administration and state-level workplace mental health regulations in California and New York drive employer investment in stress-management and resilience coaching modules. Stakeholders must monitor how credentialing bodies and regional labor classifications redefine coach practitioner status, as this boundary determines reimbursement eligibility and enterprise procurement compliance.
Market Dynamics
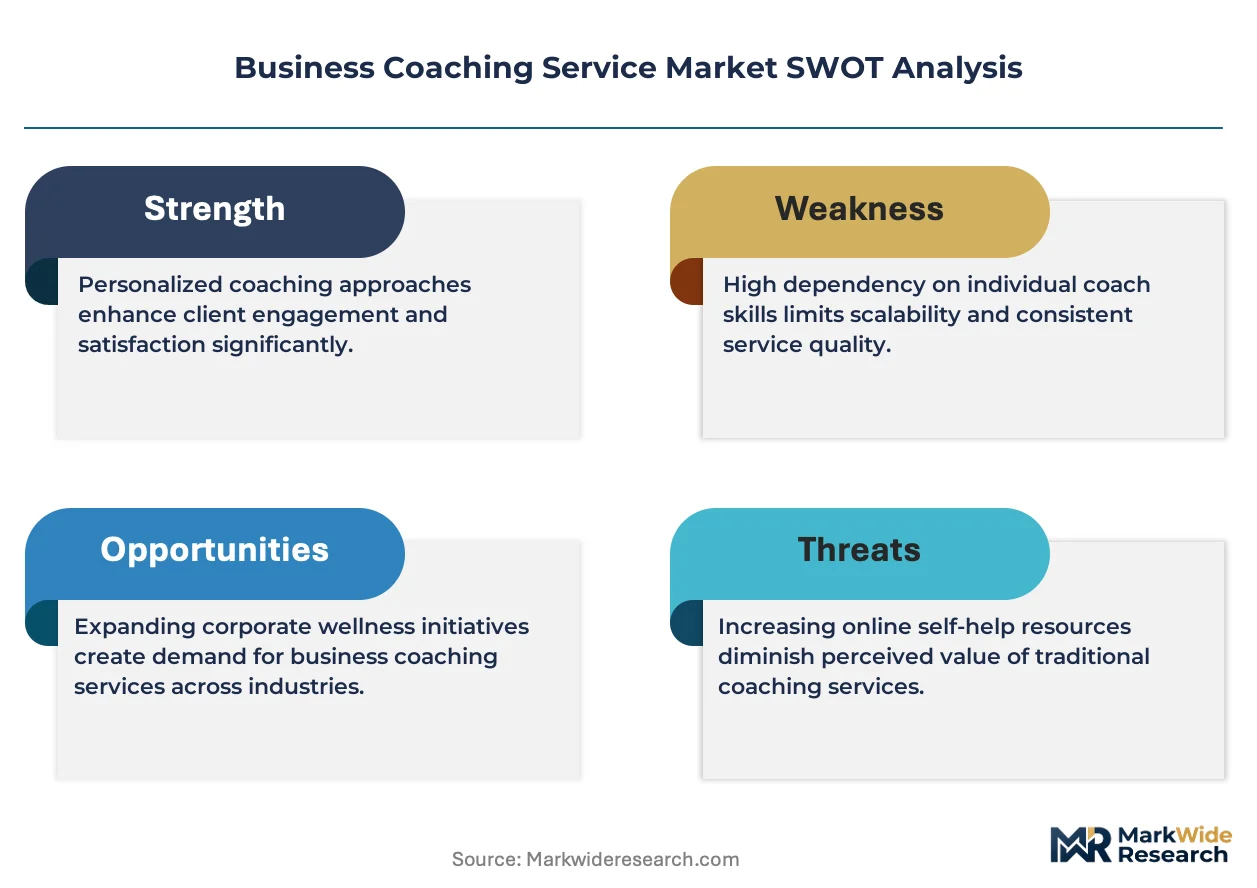
Human-centric leadership development is accelerating as algorithmic management regulations in Europe and workplace mental health mandates in the United States force enterprises to invest in credentialed coaching interventions rather than automated talent solutions.
Growth Catalysts
- EU AI Act compliance pressure:European organizations facing algorithmic accountability requirements are expanding budgets for human-led leadership development to demonstrate workforce investment alongside automation deployment.
- ISO 30414 disclosure mandates:Human capital reporting standards in Europe elevate coaching outcomes to audit-relevant metrics, converting talent development from discretionary spend to compliance-linked procurement.
- Mid-sized enterprise retention urgency:Succession pressures at firms with 500-5,000 employees are driving recurring subscription contracts for executive coaching as leadership pipeline insurance.
Market Restraints
- Credential fragmentation:The absence of unified international standards for coach practitioner status creates procurement friction and reimbursement uncertainty across multinational enterprise buyers.
- Practitioner supply concentration:Senior coaches with Fortune 500 placement track records cluster in metropolitan hubs in the United States, United Kingdom, and Germany, constraining deployment in secondary markets.
- Hourly rate compression:Digital marketplace platforms are commoditizing entry-level coaching engagements, pressuring margin structures for individual practitioners and boutique firms.
Strategic Opportunities
- Behavioral health convergence:Integration of resilience and stress-management modules into leadership coaching packages addresses OSHA and state-level workplace mental health regulations in California and New York.
- Asynchronous platform expansion:Multi-time-zone deployment capabilities open enterprise accounts in Australia, Singapore, and the United Arab Emirates without proportional operational overhead.
- Hybrid delivery standardization:Blended synchronous-asynchronous program structures reduce per-session costs while maintaining premium positioning with HR departments.
Industry Challenges
- Outcome measurement standardization:Enterprise procurement teams demand quantified return-on-investment metrics that coaching providers struggle to validate across diverse organizational contexts and time horizons.
- Practitioner classification ambiguity:Regional labor classifications and tax treatment of independent coaches vary across jurisdictions, complicating compliance for cross-border service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Coaching Service Market |
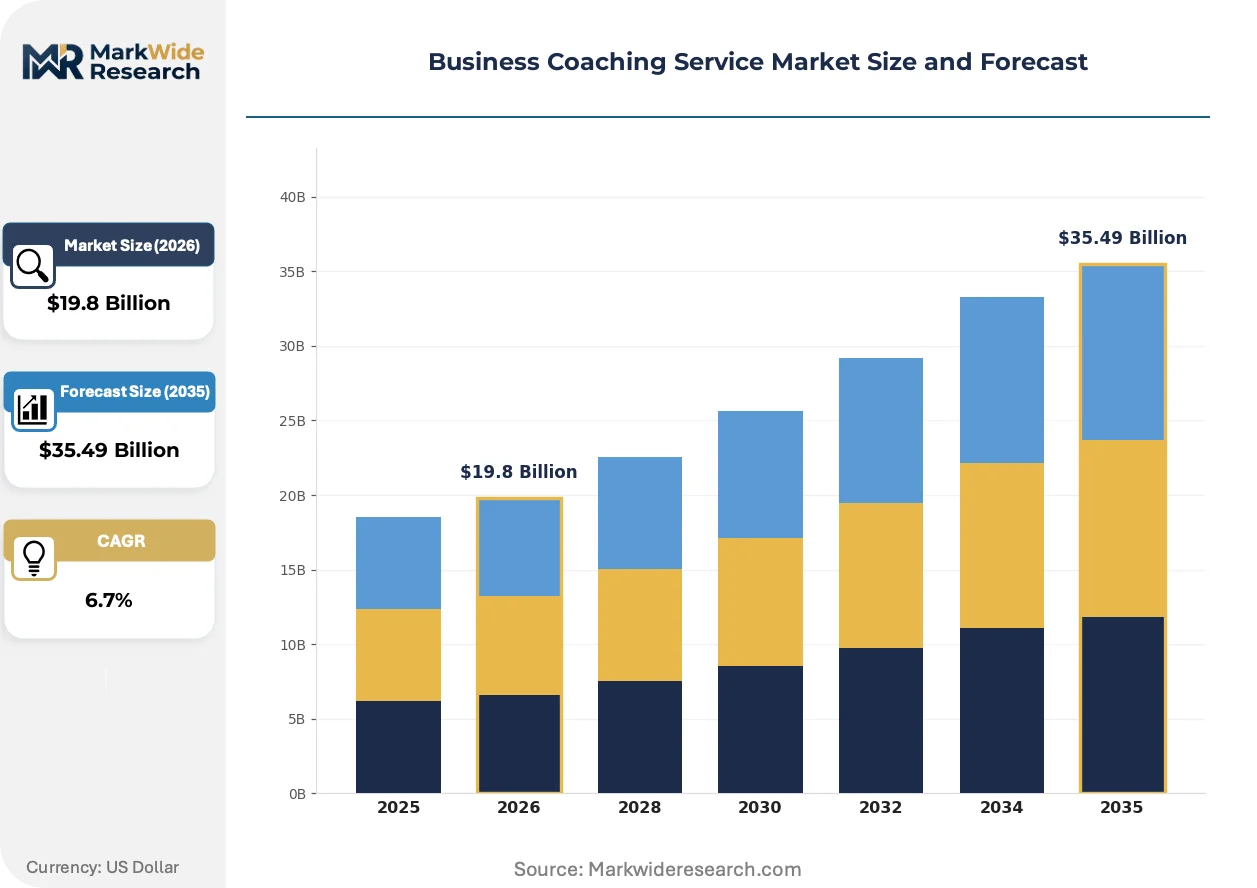
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $35.49 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Leadership Development, Executive Coaching, Team Building, Career Transition, Performance Improvement Client Type: Entrepreneurs, Startups, Small Businesses, Mid-sized Enterprises, Family-owned Firms Delivery Model: One-on-One Sessions, Group Workshops, Online Coaching, Hybrid Programs, Self-paced Modules Pricing Model: Hourly Rate, Fixed Package, Subscription-Based, Pay-per-Session, Retainer Agreements |
| Companies Covered | Ezra, AceUp, BetterUp, Dale Carnegie Training, FranklinCovey, CoachHub, Bravely, Blanchard, GrowthSpace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Coaching Service Market Trends and Innovations
Digital infrastructure is reconfiguring how coaching engagements are matched, delivered, and measured, compressing the traditional relationship between practitioner credential and enterprise access while expanding addressable buyer segments.
AI-powered coach-matching platforms are virtualizing the discovery and placement layer that historically relied on personal networks and referral chains. Mid-sized enterprises without dedicated talent development staff now access vetted practitioner pools previously gated by procurement minimums and relationship capital. The technology is virtualizing geographic and network barriers that once concentrated premium coaching within Fortune 500 corridors.
CSRD and ISO 30414 implementation timelines in Europe are mandating auditable human capital disclosures. Coaching outcomes must now integrate with sustainability reporting frameworks, converting qualitative development interventions into quantified ESG metrics. European-headquartered multinationals are responding by restructuring vendor contracts to include standardized measurement protocols and third-party verification clauses.
Subscription pricing models are displacing legacy hourly arrangements among budget-conscious enterprise buyers. Procurement departments favor predictable annual talent development expenditures over variable project-based invoicing. This pattern is most visible in United States-based technology and professional services sectors where finance teams have standardized recurring software-as-a-service contracting templates across non-software vendor categories.
Business Coaching Service Market Segmentation
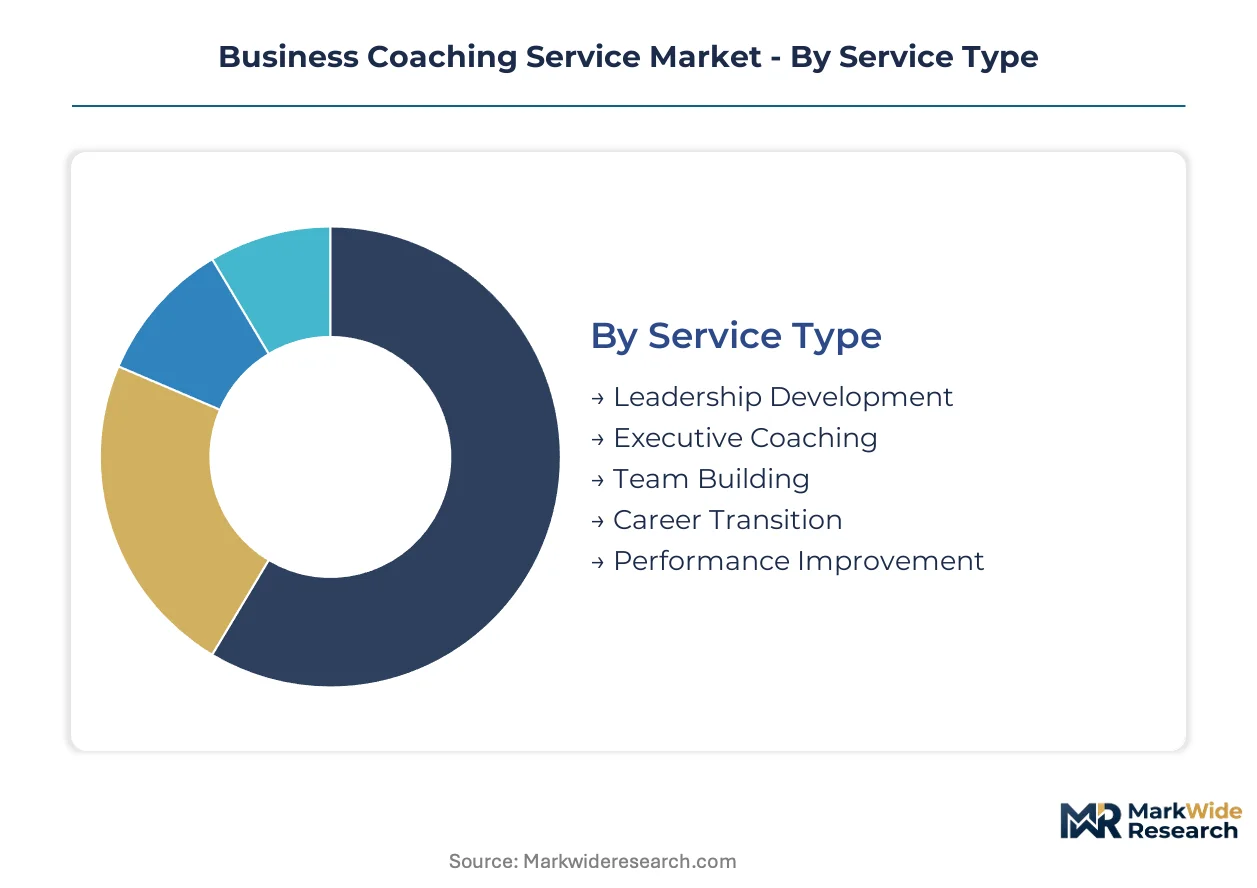
Business coaching services fragment across four structural dimensions that determine procurement patterns, margin architecture, and competitive positioning. Service type and delivery model capture the core value proposition variation, while client type and pricing model govern go-to-market economics and sales cycle length.
Service Type:
Application focus distinguishes coaching interventions by organizational hierarchy and performance objective.
- Leadership Development:Structured programming targeting C-suite succession readiness and board-level accountability mandates. Mid-sized enterprises in the United States deploy this most heavily as leadership pipeline insurance against retention volatility.
- Executive Coaching:Intensive one-to-one engagements with senior managers, characterized by psychometric assessment integration and 360-degree feedback loops. Demand concentrates among Fortune 500 HR departments seeking measurable behavioral outcomes for audit disclosure.
- Team Building:Facilitated group interventions addressing cross-functional collaboration and conflict resolution protocols.
- Career Transition:Outplacement and onboarding support for executive mobility, including role-specific skill bridging.
- Performance Improvement:Targeted behavioral correction for underperforming managers with defined remediation timelines.
Leadership Development holds installed capacity. Executive Coaching is rotating up the share rankings.
Client Type:
Customer scale determines contract value, sales complexity, and renewal predictability across the buyer base.
- Mid-sized Enterprises:Organizations with 500-5,000 employees represent the fastest-expanding contract category, driven by succession pressures and ISO 30414 disclosure requirements in Europe. Finance teams here favor subscription pricing for budget predictability.
- Entrepreneurs:Founder-led ventures purchasing coaching for personal leadership capacity and investor-facing communication skills. Demand clusters in technology corridors where venture capital due diligence includes leadership team assessment.
- Startups:Early-stage companies with institutional funding seeking scalable management frameworks before formal HR infrastructure.
- Small Businesses:Owner-operated firms with limited procurement staff, typically accessing coaching through digital marketplaces rather than direct practitioner relationships.
- Family-owned Firms:Multi-generational enterprises addressing succession planning and governance structure formalization.
Mid-sized Enterprises command procurement volume. Entrepreneurs are climbing the fastest.
Delivery Model:
Channel configuration shapes operational overhead, geographic reach, and per-session margin structure.
- Online Coaching:Synchronous video-based sessions with asynchronous scheduling flexibility. Multi-time-zone deployment opens enterprise accounts in Australia, Singapore, and the United Arab Emirates without proportional operational overhead.
- Hybrid Programs:Blended synchronous-asynchronous structures combining live sessions with digital coursework. HR departments favor this for premium positioning at reduced per-contact cost versus pure in-person delivery.
- One-on-One Sessions:Traditional high-touch practitioner-client relationships with maximum customization and relationship capital intensity.
- Group Workshops:Cohort-based facilitation for skill standardization across managerial populations.
- Self-paced Modules:Pre-recorded content libraries with minimal practitioner involvement, deployed for foundational knowledge transfer.
One-on-One Sessions retains premium positioning. Online Coaching is gaining share fastest.
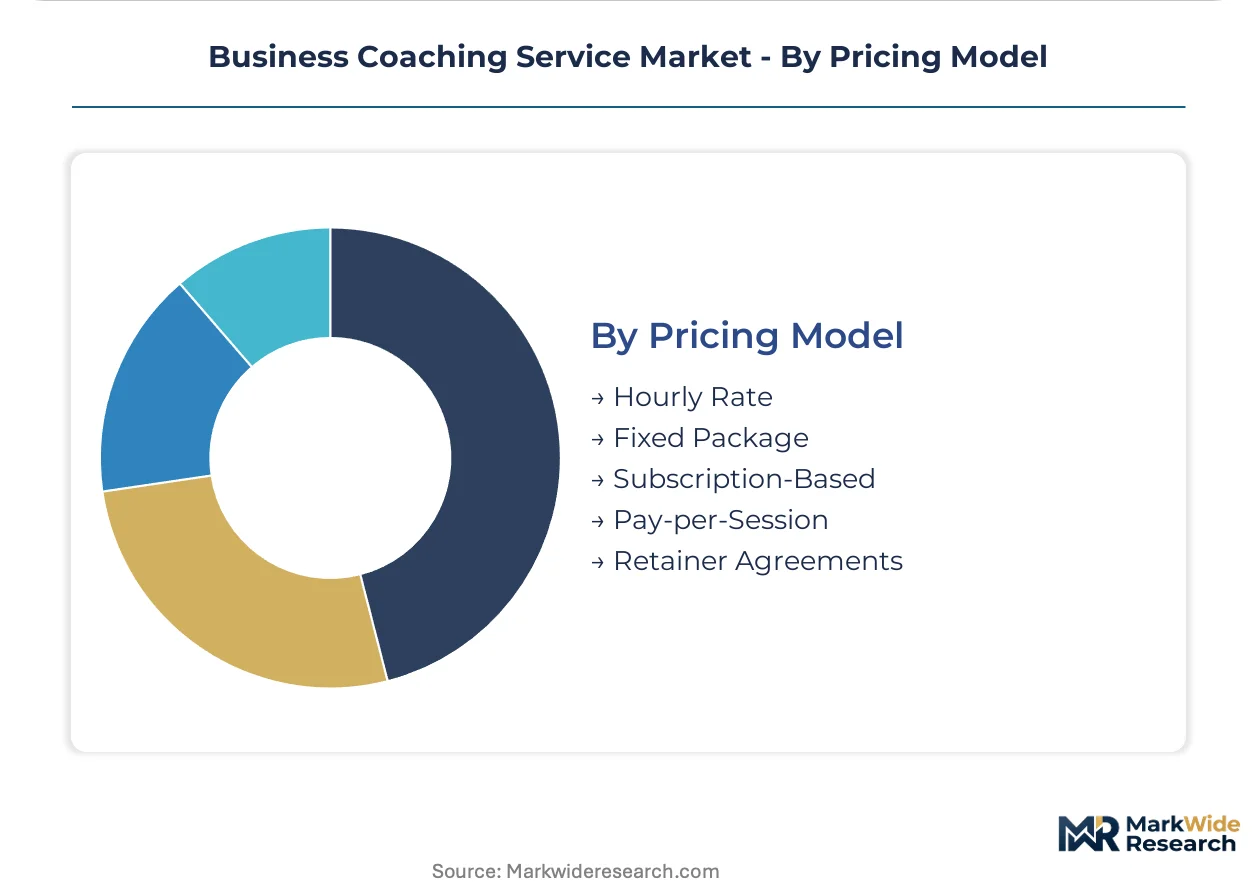
Pricing Model:
Revenue recognition patterns align with buyer procurement maturity and finance team contracting preferences.
- Subscription-Based:Recurring annual or quarterly arrangements with defined session allotments. United States technology and professional services sectors have standardized this template through SaaS-procurement habit transfer.
- Retainer Agreements:Ongoing practitioner access with flexible engagement timing, preferred by family-owned firms and entrepreneurs requiring episodic rather than scheduled support.
- Hourly Rate:Legacy time-based billing under pressure from digital marketplace commoditization at entry price points.
- Fixed Package:Defined-scope engagements with outcome milestones, common in career transition and performance improvement applications.
- Pay-per-Session:Transactional purchasing with minimal commitment, typical of small business and startup market entry.
Hourly Rate maintains legacy volume. Subscription-Based is ascending the share curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace mental health enforcement and state-level mandates in California and New York anchor the United States as the deepest coaching procurement market. The EU AI Act and CSRD disclosure timelines are converting European talent development spend into compliance-linked procurement. Demand clusters concentrate in metropolitan hubs with dense corporate headquarters and venture capital corridors.
United States
Corporate training expenditure norms and executive education infrastructure sustain the deepest coaching procurement globally. OSHA and state workplace mental health regulations in California and New York drive employer investment in resilience and stress-management modules. New York City and San Francisco Bay Area clusters concentrate senior practitioners with Fortune 500 placement track records.
Germany
Mid-sized enterprise succession pressures and family-owned firm governance formalization sustain robust coaching contract flow. EU AI Act algorithmic accountability requirements expand budgets for human-led leadership development alongside automation deployment. Munich and Frankfurt financial centers anchor practitioner supply for DAX-listed corporate accounts.
United Kingdom
Licensed facilitator networks and executive education traditions sustain premium coaching placement with multinational headquarters. CSRD implementation timelines mandate auditable human capital disclosures, converting coaching outcomes to ESG-relevant metrics. London's Square Mile and Canary Wharf concentrate demand from financial services and professional services sectors.
France
Board-level accountability mandates and C-suite succession protocols drive leadership development programming procurement. CNIL guidance on algorithmic management reinforces investment in credentialed human interventions over automated talent solutions. Paris-La Défense business district anchors enterprise coaching relationships with CAC 40 corporations.
Singapore
Multi-time-zone deployment capabilities and asynchronous platform expansion open enterprise accounts without proportional operational overhead. Regional headquarters concentration for Asia-Pacific multinationals generates demand for cross-cultural leadership development. Marina Bay financial district and One-North technology corridor concentrate technology and professional services sector procurement.
Business Coaching Service Market Competitive Landscape
AI-matching platforms and licensed facilitator networks split the market between technology-enabled placement and curriculum-controlled distribution. The vendor base concentrates around three strategic archetypes: digital marketplaces with behavioral health adjacencies, licensed facilitator networks controlling curriculum distribution, and AI-powered matching platforms sustaining premium enterprise placement. Competitive moves center on subscription pricing standardization and hybrid delivery model expansion to reduce per-session operational overhead.
Within the digital marketplace tier, CoachHub exemplifies behavioral health convergence while Ezra anchors AI-matching platform positioning. FranklinCovey occupies the licensed facilitator network archetype with curriculum distribution control across North American and Asian markets. These three entities represent the dominant strategic configurations competing for mid-sized enterprise subscription contracts and Fortune 500 HR department placement.
| Leading Market Players |
|---|
| Ezra |
| AceUp |
| BetterUp |
| Dale Carnegie Training |
| FranklinCovey |
| CoachHub |
| Bravely |
| Blanchard |
| GrowthSpace |
| Others |
Pricing and Supply Chain Analysis
New York City and San Francisco Bay Area practitioner clusters concentrate senior coaching capacity with Fortune 500 placement track records, creating geographic pricing power that diminishes in secondary markets where supply scarcity forces enterprise buyers toward digital marketplace alternatives.
Pricing Analysis
Metropolitan hub premiums of forty to sixty percent over secondary-market rates reflect practitioner credential concentration and relationship capital intensity. Three-tier pricing structure across premium, standard, and economy levels separates board-certified executive coaches from marketplace-vetted practitioners and self-service digital modules. Cost compression in entry-tier digital coaching is intensifying because AI-matching platforms commoditize discovery and reduce placement friction. Mid-sized enterprises exhibit highest price sensitivity, while Fortune 500 HR departments prioritize outcome verification over per-session cost.
Supply Chain Analysis
Extended payment terms from enterprise procurement departments strain boutique practitioner cash flows, accelerating consolidation toward platform-mediated coaching networks. Supply concentrates in the United States, United Kingdom, and Germany, with practitioner credentialing bodies in each jurisdiction maintaining non-interoperable certification standards. Raw material dependencies include psychometric assessment licenses, video conferencing infrastructure, and learning management system integrations. Single-source vulnerability runs through dominant AI-matching platforms that control practitioner-client discovery relationships. Distribution runs through direct enterprise contracts, licensed facilitator networks, and digital marketplace subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business coaching services represent a service-attach opportunity where subscription-based recurring revenue layers expand faster than traditional hourly project engagements, driven by finance team preference for predictable talent development budgets.
For Market Incumbents: Entrench platform control by deepening AI-matching algorithm training on Fortune 500 placement outcomes, and secure exclusive practitioner network contracts to defend against marketplace commoditization threatening premium positioning. ISO 30414 disclosure mandates in Europe create compliance-linked procurement that favors established vendors with audit-ready measurement protocols. For New Entrants and Emerging Players: Mid-sized enterprises in Australia, Singapore, and the United Arab Emirates represent the most penetrable entry point, where asynchronous platform capabilities open accounts without proportional operational overhead. Behavioral health convergence into resilience and stress-management modules addresses OSHA and state-level workplace mental health regulations in California and New York. Go-to-market through HR technology platform partnerships reduces direct sales cycle burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-matching platforms with behavioral health adjacencies over pure curriculum licensors, as human capital reporting standards convert coaching outcomes to auditable ESG metrics. Long-term viability hinges on outcome measurement standardization capabilities that satisfy enterprise procurement team ROI verification demands. Watch for EU AI Act enforcement intensity as inflection indicator for human-led leadership development budget expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Matching Platform Expansion | Virtualizes geographic barriers that historically concentrated premium coaching within Fortune 500 corridors. |
| Behavioral Health Module Integration | Addresses OSHA and California workplace mental health regulations driving employer investment. |
| Subscription Pricing Standardization | Aligns with SaaS-procurement templates that United States technology sector finance teams favor. |
| Hybrid Delivery Model Development | Reduces per-session operational overhead while maintaining premium positioning with HR departments. |
| ISO 30414 Measurement Protocol Investment | Converts coaching outcomes to audit-relevant metrics for European CSRD disclosure compliance. |
Research Methodology
Cross-validation between executive coaching practitioners and enterprise HR procurement leads anchors the qualitative findings, with secondary validation against credentialing body certification records and learning management system deployment data. Primary interviews with coaching platform product managers, licensed facilitator network directors, psychometric assessment providers, and Fortune 500 talent development executives informed demand-side dynamics. Bottom-up triangulation across practitioner supply estimates and top-down enterprise training budget allocations converged on market size figures.
Calibration against historical coaching contract values and disclosed platform user metrics refined growth trajectory assumptions across the analysis window. Segmentation modeling incorporated service type, delivery model, client scale, and pricing structure dimensions. CAGRs were derived from trend extrapolation of subscription pricing adoption curves and digital platform penetration rates, with sensitivity analysis for EU AI Act compliance timeline acceleration and OSHA enforcement intensity variation.
Stress conditions across enterprise budget contraction scenarios, practitioner classification regulatory changes, and platform market concentration thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about mid-sized enterprise retention urgency and ISO 30414 implementation pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Global Soft Skills Training Market
Professional Development and Training
Global Virtual Training and Simulation Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
RPA Platform Training Market
Professional Development and Training
Global Mechatronics and Robotics Courses Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
HSE Consulting Training Services Market
Professional Development and Training
Human Resource Professional Services Market
Professional Development and Training
Leadership Development Program Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
US Life Coaching Market
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
Personal Development Market
Professional Development and Training
GCC Soft Skills Training Market