
 EMV Smart Cards Market | 2026-2036
EMV Smart Cards Market Size, Share, and Industry Trends Forecast 2026-2036
EMV Smart Cards Market Foresight
Consolidation among tier-one financial institutions is repositioning procurement leverage toward fewer buyers with larger volume commitments. Thales leverages its semiconductor supply chain to sustain competitive positioning in dual-interface portfolios. IDEMIA anchors European banking relationships through specialized personalization services. Giesecke+Devrient competes on manufacturing scale across Asia-Pacific issuing programs.
EMV smart cards embed integrated circuit chips that store encrypted payment credentials and execute cryptographic authentication protocols during terminal transactions, primarily securing card-present payment environments against counterfeit fraud. The card type dimension shows contactless EMV cards capturing preference in transit and quick-service retail environments, while dual-interface EMV cards concentrate margin pools where banks seek single-inventory solutions for both chip-and-PIN and tap-to-pay channels. Tokenization within the technology dimension is accelerating as issuers replace static primary account numbers with dynamic credentials for mobile wallet integration.
PCI DSS standards govern data security requirements for card issuers and payment processors, while EMVCo specifications define interoperability protocols that determine product certification pathways. EBA guidelines in Europe and RBI directives in India mandate chip-based authentication for domestic transactions, directly shaping issuer procurement calendars and supplier qualification criteria. Stakeholders must monitor regulatory divergence between contactless transaction limits and authentication thresholds as central banks recalibrate fraud liability frameworks.
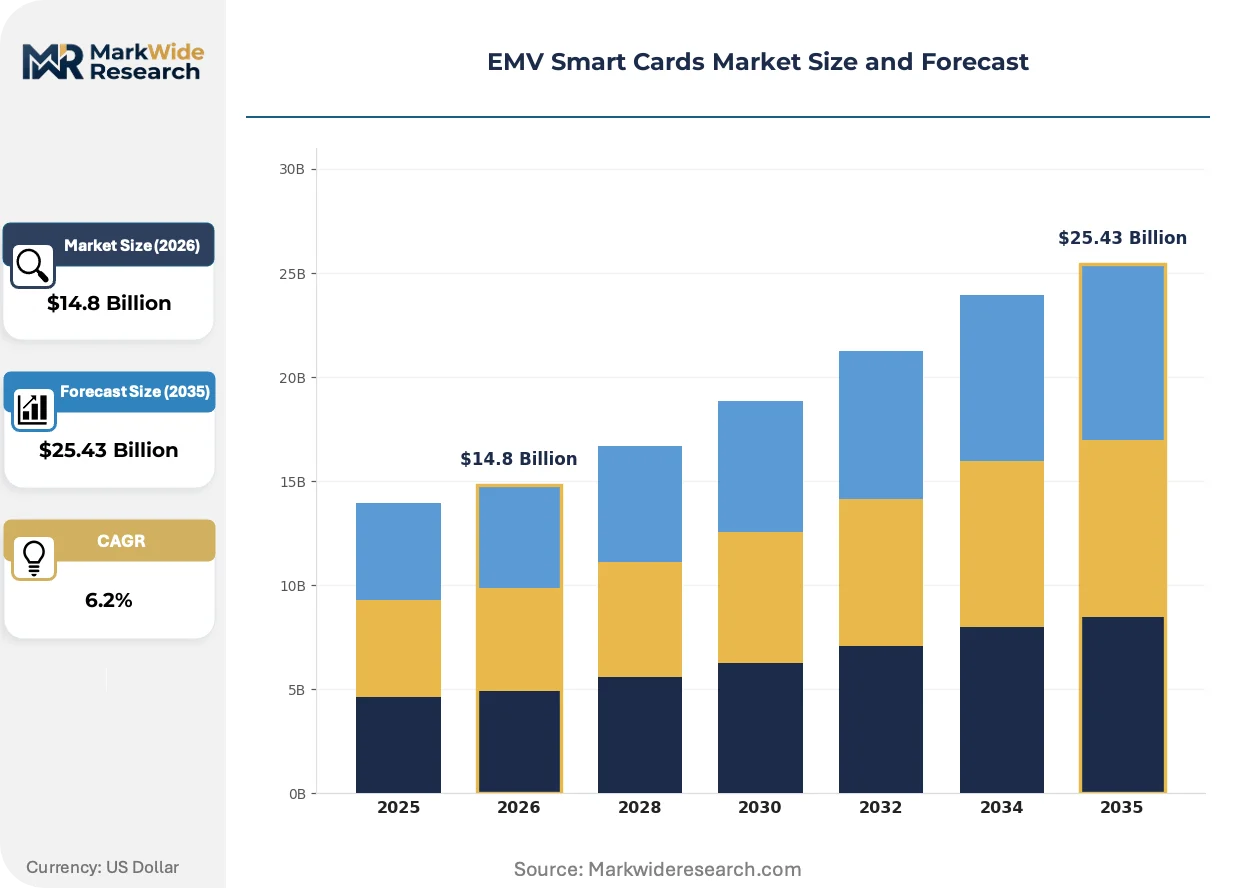
Market Dynamics
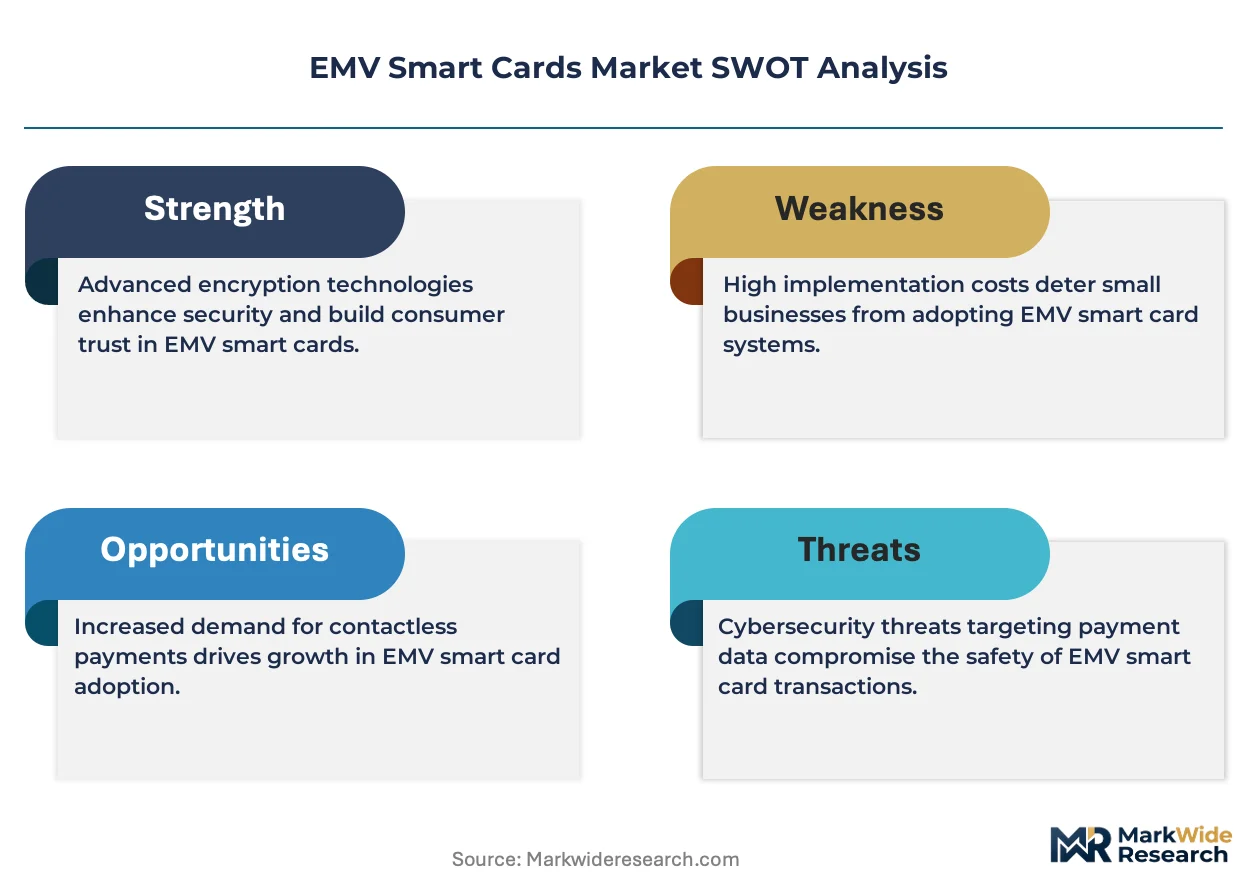
Contactless transaction volume is compressing card lifecycles and forcing issuers to consolidate personalization vendor relationships around dual-interface production capacity.
Growth Catalysts
- PCI DSS 4.0 compliance deadlines:US and European acquirers are accelerating chip card reissuance to meet authentication protocol upgrades, pulling forward replacement demand.
- India's domestic payment scheme expansion:RBI directives mandating chip-based RuPay authentication are driving dual-interface procurement across public sector banks.
- Transit open-loop payment adoption:Transport for London, Singapore's LTA, and New York MTA are deploying contactless EMV acceptance, expanding card utility beyond retail.
Market Restraints
- Semiconductor supply concentration:Wafer fabrication for secure microcontrollers concentrates among three foundry groups, creating allocation risk during demand spikes.
- PVC substrate cost volatility:Petrochemical input fluctuations compress personalization margins for standard card bodies.
- Mobile wallet substitution:Tokenized smartphone payments reduce physical card velocity in urban consumer segments.
Strategic Opportunities
- Biometric card pilot scaling:Fingerprint-on-card authentication is converging with dual-interface platforms, opening premium consumer segments.
- Indonesia's unbanked corridor:BI's National Payment Gateway roadmap creates whitespace for basic EMV debit issuance outside Java.
- Central bank digital currency bridging:Hardware wallet compatibility requirements are emerging as a design specification for next-generation card architectures.
Industry Challenges
- EMVCo certification queue congestion:New product approvals face extended testing timelines, delaying product launches.
- Legacy host system integration:Core banking modernization lags behind card technology refresh cycles, complicating dual-interface deployment.
- Secure element firmware talent scarcity:Cryptographic engineering capacity constraints limit vendor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMV Smart Cards Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Contact EMV Cards, Contactless EMV Cards, Dual-interface EMV Cards, Virtual EMV Cards End User: Retailers, Financial Institutions, Government Agencies, Telecommunication Companies Technology: Chip Technology, Magnetic Stripe, NFC, Tokenization Application: Payment Processing, Identification, Loyalty Programs, Access Control |
| Companies Covered | Thales, CPI Card Group, IDEMIA, Gemalto, HID Global, Giesecke+Devrient, Infineon Technologies, Linxens, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMV Smart Cards Market Shifts & Advancements
Payment credential architecture is fragmenting across physical, mobile, and emerging form factors, forcing card vendors to reposition around trust anchor services rather than plastic delivery alone.
Dynamic data authentication is modularizing card security architecture. EMV chips now host multiple payment applications alongside transit, access control, and identity credentials. Tier-one issuers in France and South Korea are deploying multi-application portfolios that compress unit economics through shared silicon. This convergence is modularizing vendor specialization boundaries, pushing personalization houses to integrate software layering capabilities.
EBA's Strong Customer Authentication enforcement is tightening transaction friction thresholds. European issuers must balance contactless convenience against step-up authentication triggers. Dutch and German banks are responding with risk-based biometric overlays that preserve tap-and-go speed while meeting PSD2 compliance. The regulatory calibration is compressing product development cycles for authentication firmware.
Consolidated procurement contracts are displacing fragmented issuing programs. Southeast Asian banking groups are centralizing card supply across subsidiary networks, reducing vendor counts from twelve to three. This buyer concentration is visible in Thailand and Vietnam, where state-owned banking conglomerates now negotiate enterprise-wide personalization agreements with volume-commitment clauses.
EMV Smart Cards Market Segmentation
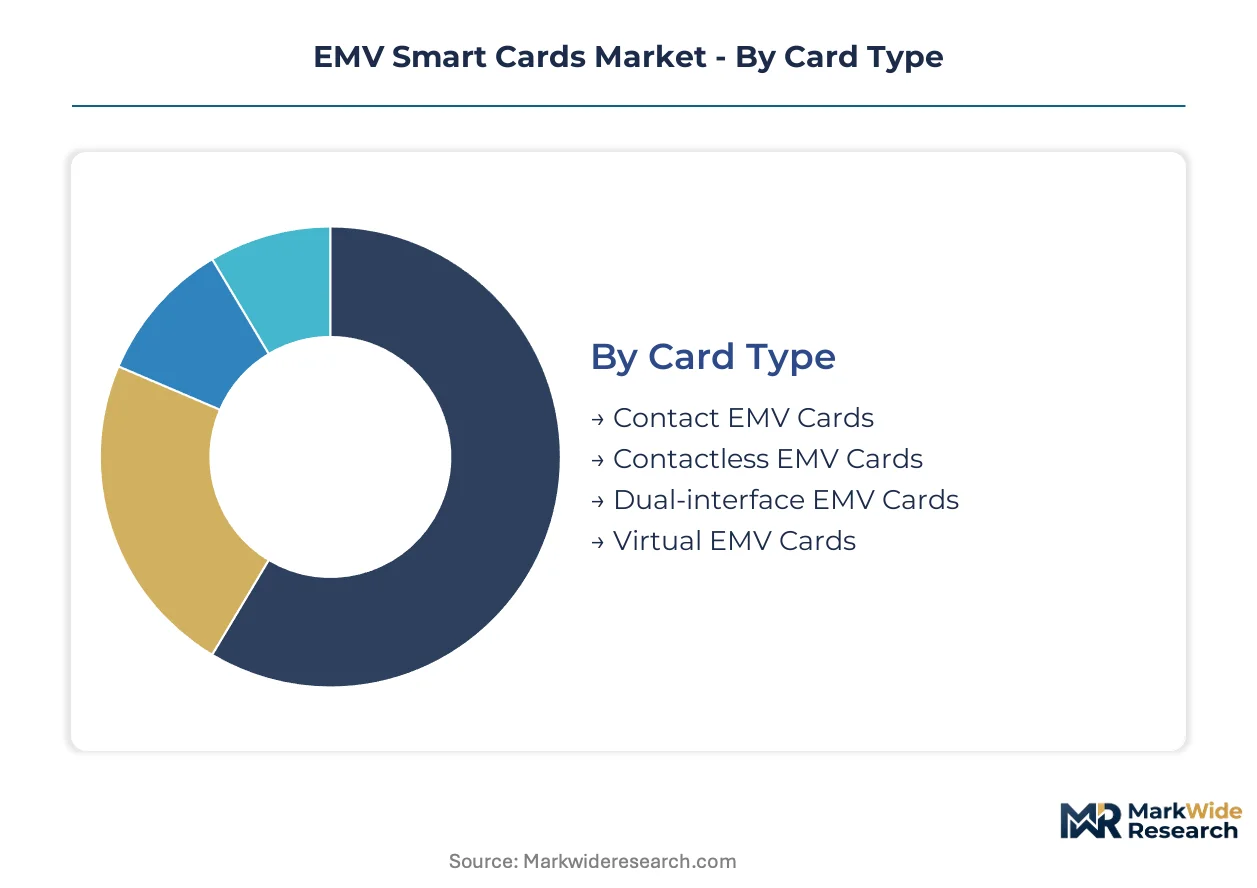
EMV smart card procurement patterns diverge sharply across interface architectures and credential delivery modes. Issuers optimize inventory strategies by matching card type to terminal infrastructure maturity and consumer behavior profiles in target markets.
Card Type:
Capital intensity concentrates in semiconductor fabrication and dual-interface antenna integration, where foundry allocation and lamination precision drive unit economics.
- Contact EMV Cards:These cards rely on physical chip-and-PIN insertion for transaction authentication, embedding secure microcontrollers in PVC or polycarbonate substrates. Demand persists in India's public sector banking network, where RBI mandates for domestic RuPay chip authentication are accelerating replacement cycles despite terminal infrastructure gaps.
- Dual-interface EMV Cards:Single-inventory solutions combine contact pads with embedded NFC antennas, enabling both dip-and-PIN and tap-to-pay functionality. European issuers under EBA Strong Customer Authentication requirements are consolidating procurement around this format to minimize SKU complexity across PSD2-compliant portfolios.
- Contactless EMV Cards:Pure tap-to-pay credentials without contact pads serve transit open-loop deployments and quick-service retail environments.
- Virtual EMV Cards:Software-based credentials provisioned to mobile wallets and wearables bypass physical manufacturing entirely.
Dual-interface cards absorb the bulk of installed capacity; virtual EMV credentials are expanding most quickly.
End User:
Procurement scale and personalization complexity separate enterprise buyers from fragmented retail deployments.
- Financial Institutions:Banks and credit unions drive volume concentration through centralized issuance programs, with tier-one groups negotiating enterprise-wide personalization agreements. PCI DSS 4.0 compliance deadlines are pulling forward replacement demand among US and European acquirers.
- Government Agencies:National ID and social benefit programs require specialized security certifications and domestic data residency compliance.
- Retailers:Closed-loop gift and loyalty card programs operate at smaller scale with faster design refresh cycles.
- Telecommunication Companies:SIM-secure element convergence for mobile payment enablement creates hybrid procurement specifications.
Financial institutions command the largest share of personalization capacity; government agencies are gaining share fastest on digital ID program expansion.
Technology:
Security architecture choices determine firmware development cycles and certification pathway complexity.
- Chip Technology:Secure microcontrollers with embedded cryptographic processors execute EMV authentication protocols, with wafer fabrication concentrating among specialty foundries. EMVCo certification queue congestion is extending testing timelines for new product launches.
- Tokenization:Dynamic credential substitution replaces static primary account numbers for mobile wallet integration, requiring vault infrastructure investment from issuers. This capability is becoming mandatory for premium consumer segment retention.
- NFC:Near-field communication antennas enable contactless transaction initiation at 13.56 MHz.
- Magnetic Stripe:Legacy fallback technology persists for backward compatibility in markets with terminal heterogeneity.
Chip technology anchors the installed base; tokenization infrastructure is climbing the fastest as mobile wallet penetration deepens.
Application:
Use case diversification is stretching personalization houses beyond payment credential delivery into multi-application software layering.
- Payment Processing:Core debit and credit authentication dominates volume, with transit open-loop adoption expanding card utility beyond retail in London, Singapore, and New York.
- Identification:National ID and corporate access programs require biometric template storage and specialized form factors.
- Access Control:Physical security integration converges with payment credentials on shared silicon platforms.
- Loyalty Programs:Closed-loop reward systems operate at lower security tiers with faster design refresh requirements.
Payment processing retains the steepest volume concentration; identification applications are gaining share fastest on digital government program rollout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement volume for dual-interface EMV cards as RBI mandates accelerate public sector bank replacement cycles. Financial institutions in France and Germany consolidate issuance programs under EBA Strong Customer Authentication requirements. Transit authorities in Singapore and the United Kingdom expand open-loop contactless acceptance beyond retail environments.
India
Public sector banks drive dual-interface procurement volume under RBI directives mandating chip-based RuPay authentication. The central bank's push for domestic payment schemes compresses procurement calendars across state-owned banking networks. Mumbai and Delhi host concentrated personalization capacity serving tier-one issuers with enterprise-wide volume commitments.
Germany
EBA guidelines enforce step-up authentication thresholds that reshape contactless transaction friction. Dutch and German banks deploy risk-based biometric overlays to preserve tap-and-go speed while meeting PSD2 compliance. Frankfurt anchors European personalization infrastructure for dual-interface portfolio consolidation.
United States
PCI DSS 4.0 compliance deadlines pull forward chip card reissuance demand among acquirers and issuers. The Federal Reserve's oversight of payment system risk shapes authentication protocol upgrade timelines. New York and Chicago concentrate transit open-loop deployment, expanding EMV utility beyond traditional retail acceptance.
Singapore
The Land Transport Authority's contactless fare collection system creates sustained demand for pure contactless EMV credentials. Monetary Authority of Singapore guidelines on e-payments interoperability determine terminal infrastructure refresh cycles. The city-state's banking hub hosts regional procurement centralization for Southeast Asian banking conglomerates.
France
CNIL oversight of biometric data processing constrains fingerprint-on-card pilot scaling among domestic issuers. EBA Strong Customer Authentication enforcement tightens transaction friction thresholds for contactless deployments. Paris hosts specialized personalization services anchoring European banking relationships through multi-application software layering capabilities.
EMV Smart Cards Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biometric authentication and digital identity convergence. The vendor base stratifies across semiconductor fabrication, antenna integration, and personalization services. Three archetypes dominate: secure microcontroller foundries, dual-interface lamination specialists, and end-to-end issuance integrators. Consolidation among tier-one financial institutions concentrates procurement leverage toward fewer buyers with larger volume commitments, while EMVCo certification queue congestion extends testing timelines for new product launches.
Within the European issuance integration tier, Thales and IDEMIA occupy positions anchoring banking relationships through specialized personalization services. Giesecke+Devrient sits within the manufacturing scale archetype, competing across Asia-Pacific issuing programs with dual-interface production capacity. These three entities exemplify how secure element supply chain control and personalization infrastructure determine competitive positioning as procurement centralizes among consolidated banking groups.
| Leading Market Players |
|---|
| Thales |
| CPI Card Group |
| IDEMIA |
| Gemalto |
| HID Global |
| Giesecke+Devrient |
| Infineon Technologies |
| Linxens |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Dual-interface card procurement consolidation among tier-one financial institutions is compressing vendor margins and forcing personalization houses to absorb antenna integration complexity without commensurate price recovery. This buyer concentration dynamic is reshaping supplier economics across EMV manufacturing tiers.
Pricing Analysis
Volume concentration among consolidated banking groups splits the market into enterprise contract tiers and spot procurement for smaller issuers. Pricing stratifies across EMVCo certification grade, volume commitment scale, and personalization service bundling. Cost compression in standard contactless cards is intensifying because PVC substrate volatility and foundry allocation premiums squeeze mid-tier suppliers. Regional banks and credit unions exhibit highest price sensitivity, while tier-one groups with multi-year enterprise agreements trade margin for capacity security.
Supply Chain Analysis
Freight cost volatility for secure microcontroller wafer shipments from Taiwan, South Korea, and Germany is amplifying landed cost uncertainty for personalization facilities. Semiconductor fabrication draws from specialty foundries in Taiwan and Germany, while PVC and polycarbonate substrates feed from petrochemical complexes in China and the United States. Single-source vulnerability concentrates in secure element firmware engineering capacity, which remains tethered to a narrow pool of cryptographic specialists. Distribution runs through centralized personalization houses with direct-to-issuer logistics rather than wholesale channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMV smart card market sits in a technology-transition phase as biometric authentication and tokenized mobile credentials displace legacy contact-only portfolios. Dual-interface platforms are absorbing development resources while virtual credentials bypass physical manufacturing entirely.
For Market Incumbents: Deploy backward integration into secure microcontroller supply to defend against foundry allocation risk during demand spikes. Consolidate personalization capacity around dual-interface antenna integration expertise to capture enterprise contract renewals. Counter mobile wallet substitution by anchoring banking relationships through multi-application software layering services that extend card utility beyond payment.
For New Entrants and Emerging Players: Fintech infrastructure providers represent the most accessible channel partner type for biometric card pilot programs targeting premium consumer segments. Indonesia's unbanked corridor outside Java offers whitespace for basic EMV debit issuance under BI's National Payment Gateway roadmap. Position around hardware wallet compatibility specifications emerging from central bank digital currency design requirements.
For Investors and Strategic Acquirers: The window for entry favors personalization houses with EMVCo certification infrastructure and established banking relationships. Long-term viability hinges on software-layering capabilities that transcend plastic delivery. Monitor transit authority open-loop procurement calendars as the inflection signal for contactless volume acceleration beyond retail environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Integration | Fingerprint-on-card deployment captures premium segments under EBA Strong Customer Authentication requirements. |
| Dual-Interface Capacity Expansion | Antenna integration investment secures enterprise contracts from consolidated Southeast Asian banking groups. |
| Tokenization Infrastructure Partnership | Dynamic credential vaulting preserves issuer relationships as mobile wallet penetration deepens. |
| Transit Open-Loop Certification | Transport for London and Singapore LTA specifications expand card utility beyond traditional retail acceptance. |
| Central Bank Digital Currency Bridging | Hardware wallet compatibility positions next-generation architectures for emerging CBDC program requirements. |
Research Methodology
Document review covered EMVCo certification databases, RBI and EBA regulatory filings, and payment processor annual disclosures, complemented by interviews with card personalization executives, secure element procurement leads at tier-one banks, transit authority payment integration officers, and semiconductor foundry account managers. Secondary sources included PCI SSC compliance timelines, central bank directive repositories, and customs records for secure microcontroller trade flows. Bottom-up unit economics modeling and top-down banking sector procurement estimates were cross-validated through triangulation.
Historical issuance volumes were cross-referenced against panel input from personalization house capacity planners to anchor growth trajectories across the projection horizon. Segmentation dimensions modeled include card interface architecture, end-user institution type, security technology tier, and application use case. CAGRs were derived from elasticity-adjusted replacement cycle analysis and regulatory mandate pull-forward effects. Industry-specific inputs encompassed EMVCo certification queue timelines and central bank directive implementation calendars.
Caveats apply where semiconductor foundry allocation disruptions, petrochemical input volatility, or mobile wallet substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance deadlines and transit infrastructure deployment schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Mission Critical Communication (MCX) Market
Information and Communication Technology
Australia Telecom Tower Market
Information and Communication Technology
Laboratory Robotics Market
Information and Communication Technology
North America Industrial IoT Market
Information and Communication Technology
Data Acquisition Market
Information and Communication Technology
US Customer Communication Management (CCM) Market
Information and Communication Technology
CRM Outsourcing Market
Information and Communication Technology
Global Application Release Automation Market
Information and Communication Technology
Dark Web Intelligence Market
Information and Communication Technology
Latin America IoT Security Market
Information and Communication Technology
Europe Human Resource (HR) Technology Market
Information and Communication Technology
Wigig Market
Information and Communication Technology
Wireless Connected Devices Market
Information and Communication Technology
IoT Smart Poles Market
Information and Communication Technology
South Africa Data Center Cooling Market
Information and Communication Technology
Cloud Machine Learning Market