
 Antivirus Software Market | 2026-2036
Antivirus Software Market Size, Share, and Industry Trends Forecast 2026-2036
Antivirus Software Market Intelligence
Multi-sourced vendor portfolios is broadening as enterprise buyers diversify beyond single-suite dependencies. Microsoft Corporation leverages its native OS integration to anchor cloud-based deployment pipelines. CrowdStrike Inc. specializes in behavioral analysis engines that differentiate its threat-hunting capabilities. Bitdefender S.R.L. operates a strong channel presence across European mid-market accounts.
Antivirus software comprises signature-matching engines, heuristic analyzers, and real-time behavioral monitors that detect, quarantine, and remediate malicious code across endpoints and networks. These systems serve the primary commercial purpose of preventing data exfiltration, ransomware encryption, and unauthorized system access before operational damage occurs. Cloud-based deployment now captures the fastest expansion as organizations abandon on-premise maintenance overhead, while endpoint protection solutions retain the deepest margin pools due to recurring subscription structures. Small businesses represent an underpenetrated end-user tier where managed service bundling is accelerating uptake.
The EU AI Act, NIS2 Directive, and GDPR jointly shape European product standards by mandating automated threat detection in critical infrastructure software and imposing severe penalties for data breach latency. The US FDA and FCC regulate antivirus deployment in healthcare devices and communications hardware respectively, creating segmented compliance obligations that vendors must architect around. Stakeholders should monitor how generative AI attack surfaces force recalibration of heuristic detection models before adversarial automation outpaces defensive tooling refresh cycles.
Market Dynamics
Cloud-native endpoint protection is compressing deployment cycles as enterprises abandon hardware-dependent security stacks. The shift forces vendors to rebuild architectures around API-first integration rather than agent-heavy installations.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators across Germany, France, and the United Kingdom must deploy automated threat detection by late 2024, mandating procurement of next-generation endpoint suites.
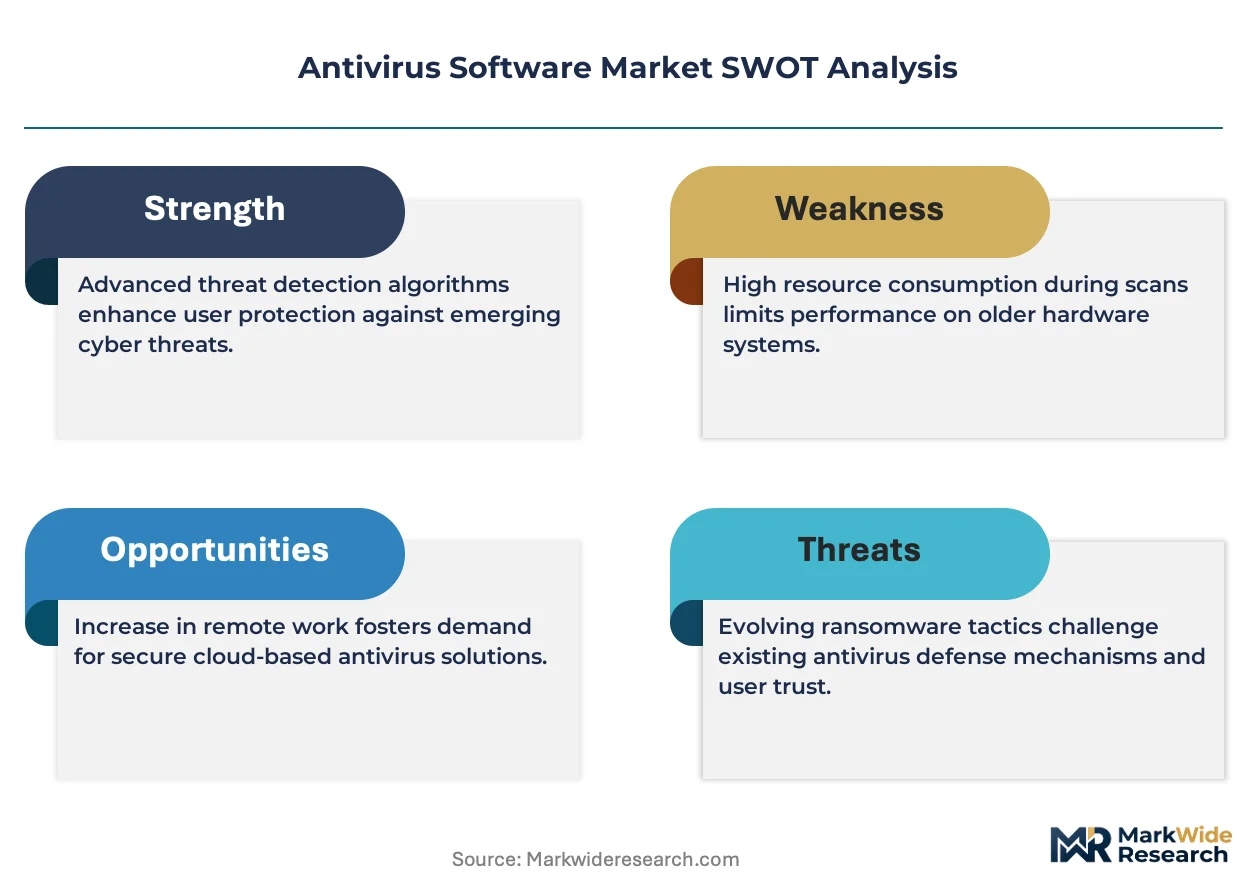
- Generative AI weaponization:Polymorphic malware engines now mutate signatures faster than traditional databases refresh, accelerating demand for behavioral heuristics that detect anomalous execution patterns without prior definition.
- Mid-market channel density:Managed service providers in European secondary cities bundle endpoint protection with remote monitoring, opening subscription revenue streams previously captured only by enterprise direct sales.
Market Restraints
- Input cost volatility:GPU compute for AI-powered threat modeling consumes 40-60% higher cloud infrastructure spend than signature-based systems, squeezing margins for pure-play vendors without hyperscaler partnerships.
- Technical limitation:Behavioral false-positive rates in legacy Windows environments remain 3-5x higher than in Linux or macOS deployments, constraining unified platform claims.
- Substitution threat:Operating system vendors embed baseline antivirus free of charge, commoditizing entry-tier protection and compressing pricing power below enterprise tiers.
Strategic Opportunities
- Small business underpenetration:German Mittelstand manufacturers with 50-250 employees maintain 60-day patching cycles and minimal endpoint coverage, presenting managed detection and response bundling potential.
- Technology convergence:Extended detection and response platforms merge identity threat detection with endpoint telemetry, enabling cross-domain correlation that siloed antivirus cannot replicate.
- Regulatory tailwind:The EU AI Act mandates conformity assessments for security software incorporating machine learning, creating certification barriers that favor established vendors with compliance infrastructure.
Industry Challenges
- Skill scarcity in threat hunting:European enterprises report 18-month average vacancies for security operations center analysts capable of interpreting behavioral alerts without vendor escalation.
- Integration complexity:Security information and event management migration projects stall when legacy antivirus agents conflict with modern extended detection and response collectors, requiring parallel deployment phases.
- Certification timeline compression:Common Criteria evaluations for government procurement now extend 14-18 months, delaying product releases in France and Germany's public sector channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antivirus Software Market |
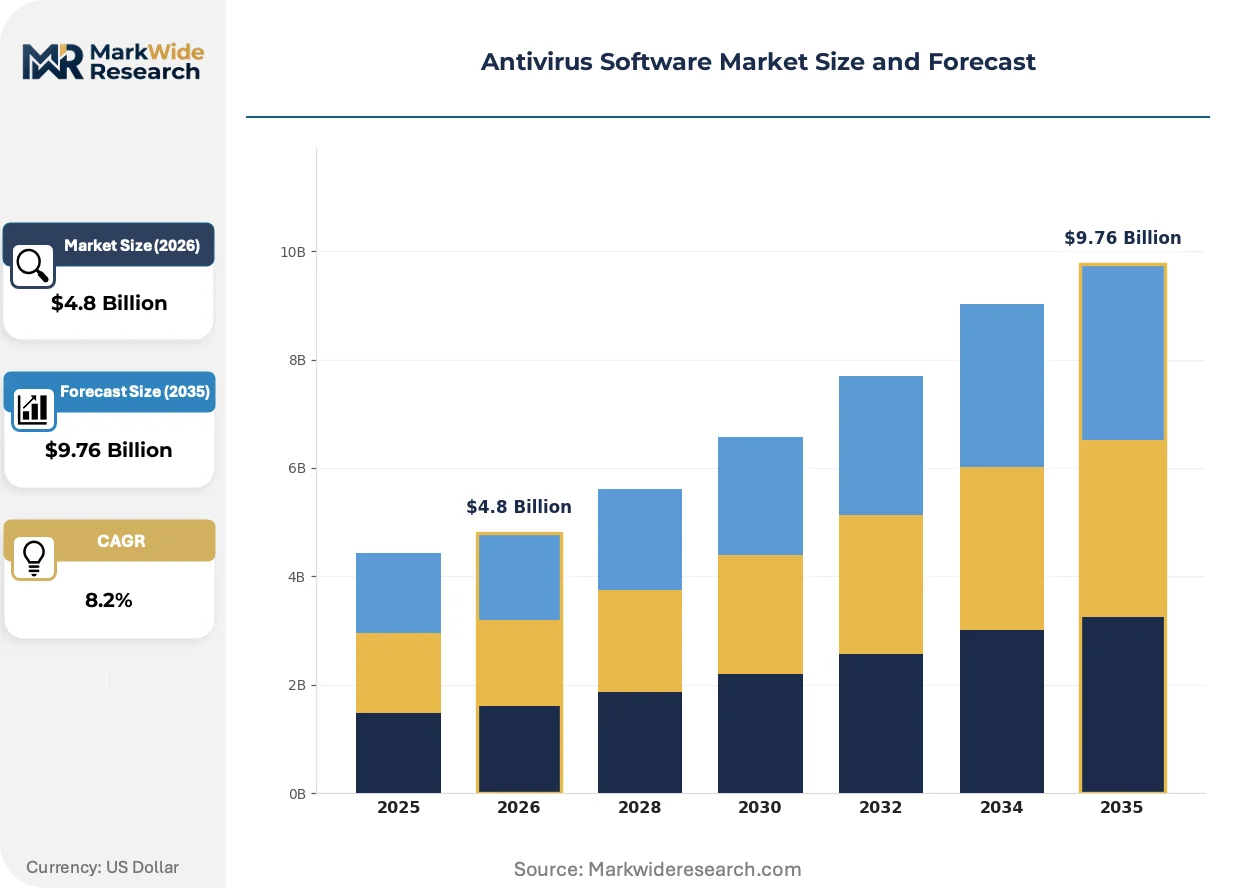
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed End User: Small Businesses, Enterprises, Educational Institutions, Government Agencies Solution: Endpoint Protection, Network Security, Malware Detection, Identity Protection Technology: Behavioral Analysis, Signature-Based, Heuristic Analysis, Cloud Detection |
| Companies Covered | Trend Micro Incorporated, Fortinet Inc., Microsoft Corporation, Kaspersky Lab AO, Avast Software s.r.o., McAfee LLC, Bitdefender S.R.L., CrowdStrike Inc., Symantec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antivirus Software Market Strategic Shifts & Innovations
Attack surface expansion through remote work infrastructure and software supply chain compromises is forcing architectural reinvention. Vendors now compete on telemetry breadth rather than detection speed alone.
Extended detection and response is modularizing security operations by decoupling data collection from analysis engines. Mid-market enterprises in the United Kingdom adopt lightweight collectors first, then activate threat-hunting modules as security maturity advances. This architecture compresses initial deployment from quarters to weeks while preserving upgrade pathways.
The EU AI Act imposes risk classification and documentation burdens on machine learning-enabled security tools. Vendors must maintain algorithmic transparency logs and human oversight protocols for high-risk system categories. French and German healthcare software suppliers face the steepest compliance ramps as medical device cybersecurity rules intersect with AI system regulations.
Security buying committees now demand consumption-based pricing tied to protected endpoint counts rather than perpetual licenses. Channel partners in France and the United Kingdom replace upfront resale with monthly recurring revenue shares. This shift concentrates vendor attention on retention metrics and expansion revenue within existing accounts rather than new logo acquisition.
Antivirus Software Market Segmentation
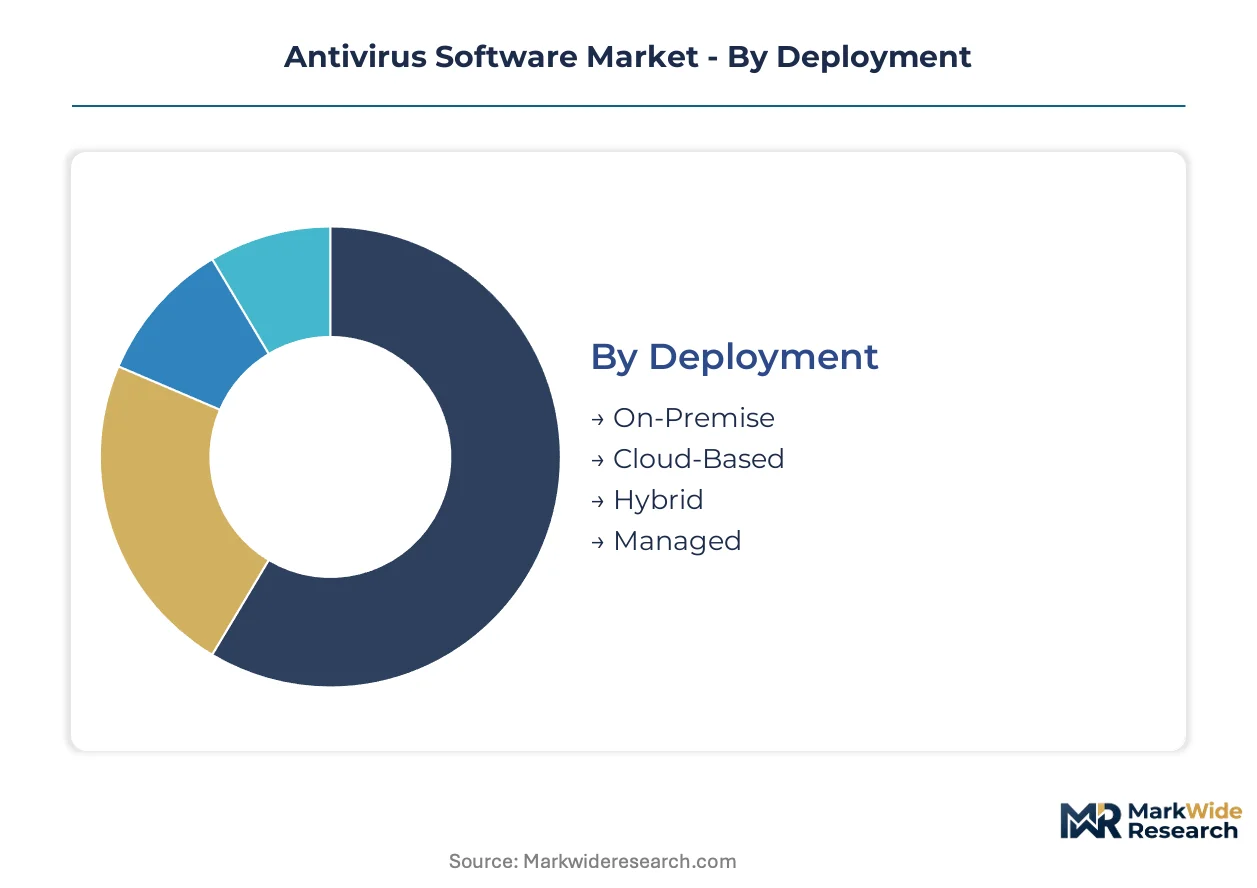
Antivirus software procurement patterns diverge sharply across deployment architectures and organizational scale. Vendors must architect pricing and channel strategies around these structural divisions rather than treating protection as a uniform commodity.
Deployment:
Cloud-native architectures demand substantially lower upfront capital than hardware-dependent installations, yet recurring subscription commitments alter lifetime value calculations.
- Cloud-Based:API-first architectures eliminate on-premise server maintenance while enabling real-time threat intelligence distribution. German and French mid-market enterprises prioritize this model to accelerate procurement cycles and reduce IT headcount.
- On-Premise:Air-gapped installations in defense and critical infrastructure sectors require dedicated appliance stacks with localized signature databases. United Kingdom government contractors maintain these configurations for compliance with classified network protocols.
- Hybrid:Split architectures route sensitive data through on-premise engines while pushing commodity traffic to cloud analytics.
- Managed:Outsourced security operations centers handle deployment, monitoring, and response through service-level agreements.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Managed services as European channel partners pivot from resale to recurring revenue.
End User:
Procurement sophistication and price elasticity separate organizational tiers, with compliance mandates driving purchasing authority to specialized committees.
- Enterprises:Centralized security operations centers demand extended detection and response integration with identity and access management platforms. Large German manufacturers bundle endpoint protection with operational technology security for factory floor convergence.
- Small Businesses:Limited IT staffing drives preference for managed service provider bundles combining antivirus with remote monitoring and patch management.
- Government Agencies:Common Criteria certification requirements extend sales cycles but lock in multi-year contracts.
- Educational Institutions:Volume licensing agreements and student device proliferation create complex deployment scenarios across dispersed campuses.
Enterprise accounts generate the deepest margin pools. Small Businesses represent the largest untapped addressable base.
Solution:
Functional specialization determines integration complexity and renewal rates, with converged platforms commanding premium positioning.
- Endpoint Protection:Agent-based collectors monitor file execution, registry modifications, and network connections across workstations and servers. United Kingdom financial services firms deploy these as baseline coverage for remote worker devices.
- Network Security:Gateway appliances inspect traffic flows for command-and-control communications and data exfiltration patterns.
- Malware Detection:Signature-matching engines and sandboxing tools isolate suspicious files before execution.
- Identity Protection:Credential monitoring and privileged access management prevent lateral movement post-compromise.
Endpoint Protection carries the highest installed base. Identity Protection is climbing the fastest as zero-trust architectures mature.
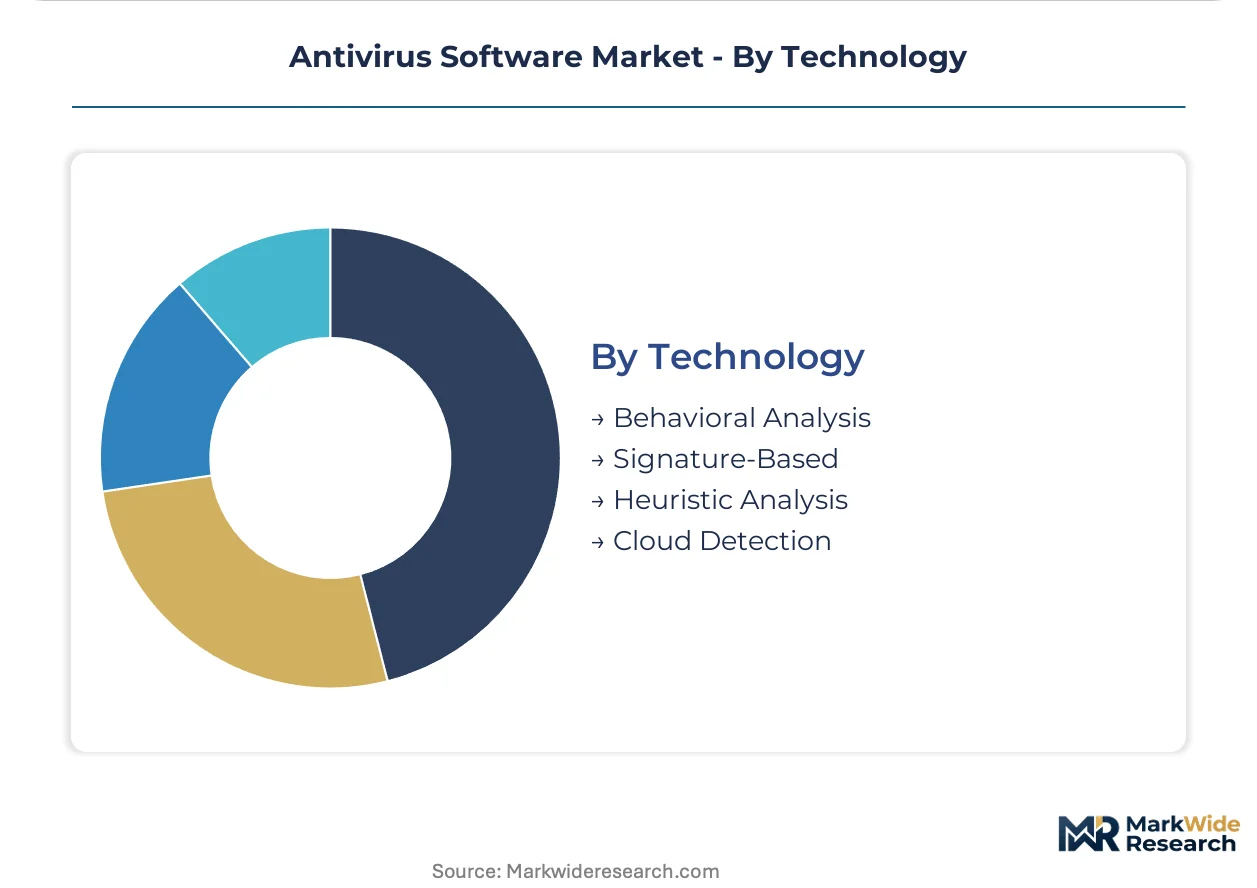
Technology:
Detection methodology directly shapes infrastructure costs and false-positive trade-offs, with machine learning models consuming disproportionate compute resources.
- Behavioral Analysis:Real-time execution monitoring identifies anomalous process trees and memory injection techniques without prior signature knowledge. French healthcare software vendors integrate these engines to satisfy EU AI Act documentation requirements for automated decision systems.
- Signature-Based:Hash and pattern matching against threat intelligence databases delivers deterministic detection with minimal processing overhead.
- Heuristic Analysis:Rule-based suspicion scoring flags potentially malicious code characteristics before full execution.
- Cloud Detection:Remote sandboxing and collective intelligence aggregation offload processing from endpoint hardware.
Signature-Based systems retain the broadest deployment footprint. Behavioral Analysis is gaining share fastest as polymorphic malware evades static detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Mittelstand manufacturers anchor European endpoint protection procurement as compliance mandates reshape procurement authority across national markets.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg drive demand for operational technology-integrated security suites. The EU NIS2 Directive mandates automated threat detection for critical infrastructure operators by late 2024. Frankfurt's financial services corridor accelerates cloud-native deployment to reduce on-premise maintenance overhead.
United Kingdom
London's fintech density generates concentrated procurement of behavioral analysis engines for remote worker protection. The National Cyber Security Centre publishes threat intelligence frameworks that shape vendor certification requirements. Manchester and Birmingham channel partners pivot from perpetual license resale to managed service recurring revenue models.
France
Paris-based healthcare software suppliers face intersecting compliance obligations under medical device cybersecurity rules and the EU AI Act. ANSM and CNIL jointly supervise algorithmic transparency documentation for machine learning-enabled tools. Lyon and Toulouse aerospace clusters maintain air-gapped installations for classified contract work.
United States
Silicon Valley technology firms and Washington DC federal contractors sustain dual demand vectors for cloud-native and certified on-premise stacks. The FDA and FCC regulate antivirus deployment in healthcare devices and communications hardware respectively. Boston's cybersecurity startup density feeds acquisition activity among established platform vendors.
Japan
Tokyo's financial institutions and Osaka manufacturing headquarters prioritize signature-based systems with minimal processing overhead for legacy infrastructure. METI guidelines encourage baseline security adoption among small enterprises with limited IT staffing. Fukuoka's emerging technology corridor experiments with managed detection and response bundling for regional banks.
Antivirus Software Market Key Industry Players
Global majors compete with regional champions across deployment architecture and compliance certification dimensions. The vendor base stratifies between hyperscaler-integrated platforms, behavioral analysis specialists, and channel-centric mid-market providers. Three archetypes dominate: native OS integrators leveraging distribution advantages, threat-hunting specialists differentiating on detection methodology, and managed service enablers capturing subscription revenue through partner networks. Consolidation pressure intensifies as extended detection and response convergence forces portfolio breadth, while certification timelines for government procurement extend competitive moats for incumbents.
Among the named players, Microsoft Corporation and CrowdStrike Inc. occupy positions at opposite ends of the integration-versus-specialization spectrum, while Bitdefender S.R.L. exemplifies the European channel-centric archetype. Microsoft leverages native operating system presence to anchor cloud deployment pipelines. CrowdStrike represents the behavioral analysis specialist model with differentiated threat-hunting positioning. Bitdefender maintains density across European mid-market accounts through managed service provider relationships.
| Leading Market Players |
|---|
| Trend Micro Incorporated |
| Fortinet Inc. |
| Microsoft Corporation |
| Kaspersky Lab AO |
| Avast Software s.r.o. |
| McAfee LLC |
| Bitdefender S.R.L. |
| CrowdStrike Inc. |
| Symantec Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up endpoint protection specialists anchor supply discipline through recurring revenue lock-in, compressing pricing flexibility for pure-play vendors lacking hyperscaler cloud credits. This ownership pattern tightens margin thresholds across European mid-market channels while forcing independent vendors toward managed service bundling to preserve yield.
Pricing Analysis
GPU compute pass-through for AI-powered threat modeling consumes 40-60% higher cloud infrastructure spend than signature-based systems, forcing vendors to absorb margin compression or push subscription tiers upward. Three-tier pricing structure across premium EDR-integrated suites, standard endpoint protection, and economy antivirus separates enterprise buyers with SOC integration needs from small businesses seeking MSP bundles. Pricing pressure stems from Microsoft Defender's native OS embedding, which commoditizes entry-tier protection. Small businesses exhibit highest price sensitivity, while financial services firms in London and Frankfurt accept premium positioning for behavioral analysis certification.
Supply Chain Analysis
Regional distribution centers in Ireland, Netherlands, and Germany aggregate threat intelligence feeds and cloud infrastructure for European deployment, with Frankfurt and Amsterdam serving as primary hubs for latency-sensitive behavioral analytics. Software supply chains draw from open-source detection libraries, proprietary ML training pipelines, and third-party telemetry partnerships concentrated in the United States and Israel. Single-source vulnerability in GPU cloud provisioning from AWS, Azure, and Google Cloud creates concentration risk for AI-powered vendors. Distribution runs through direct enterprise sales, MSP channel networks, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as compliance mandates under NIS2 and EU AI Act shift procurement authority toward certified vendors with documented algorithmic transparency, elevating premium specification demand.
For Market Incumbents: Cement defensive moats through Common Criteria certification investment for French and German government channels, extending competitive barriers against emerging cloud-native entrants. Deepen backward integration into threat intelligence sourcing through acquisition of specialized malware research boutiques, reducing dependency on third-party feed licensing. Prioritize API-first architecture standardization to preempt substitution by embedded OS security.
For New Entrants and Emerging Players: Begin with German Mittelstand manufacturers in 50-250 employee bands, where 60-day patching cycles and minimal endpoint coverage create managed detection and response bundling potential. Target United Kingdom channel partners pivoting from perpetual license resale to recurring revenue models, offering white-label SOC capabilities. Deploy consumption-based pricing tied to protected endpoint counts rather than upfront licensing.
For Investors and Strategic Acquirers: Valuations sit cheapest among behavioral analysis specialists with EU AI Act compliance infrastructure already deployed, as certification timelines extend to 14-18 months for government procurement. Long-term viability favors vendors with hybrid cloud-on-premise architectural flexibility across the 5-10 year compliance cycle. Watch for inflection when generative AI attack surfaces force heuristic model recalibration, separating adaptive vendors from legacy signature-dependent players.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | EDR convergence with identity threat detection enables cross-domain correlation beyond siloed antivirus capabilities. |
| Acquisition of Specialist Firm | Behavioral analysis boutiques add differentiated threat-hunting engines for EU AI Act documentation compliance. |
| Geographic Expansion | Channel density in French and United Kingdom secondary cities captures MSP recurring revenue migration. |
| Strategic Partnership | Hyperscaler cloud credits reduce GPU compute cost burden for AI-powered threat modeling infrastructure. |
| Product Launch | Lightweight cloud-native collectors compress deployment cycles from quarters to weeks for mid-market adoption. |
Research Approach
Coverage spans Germany, United Kingdom, France, United States, and Japan, with primary inputs from each market through structured interviews with CISOs, IT procurement officers, MSP channel partners, and security operations center directors. Secondary validation draws from SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and threat intelligence industry reports. Bottom-up endpoint deployment estimates triangulate against top-down software spending forecasts.
Rate-of-change decomposition separates volume effects from pricing migration across cloud-native, on-premise, hybrid, and managed deployment architectures over the projection horizon. Segmentation dimensions modeled include organization size, deployment model, detection technology, and regional compliance cluster. CAGRs derive from installation base expansion, subscription renewal rates, and attach ratios for advanced modules. Forecast inputs incorporate NIS2 implementation timelines and generative AI attack surface evolution.
Several conditions sit outside the modeled scope, including specific malware outbreak scenarios, hyperscaler pricing discontinuities, and geopolitical restrictions on threat intelligence sharing. Forecasts reflect documented assumptions around compliance enforcement intensity and cloud migration cadence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Encryption Software Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Single Sign-On Market
Security Software
Secure Email Gateway Market
Security Software
US Hardware Encryption Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Asia Pacific Video Management System Market
Security Software
Identity and Access Management (IAM) Market
Security Software
Global Network Encryption Market
Security Software
Devsecops Market
Security Software
Software Protection Dongle Market
Security Software
Banking Encryption Software Market
Security Software
Passport Reader Market
Security Software
User Provisioning Software Market
Security Software
US and Latin America Identity and Access Management (IAM) Market