
 Global Reputation Protection Software Market | 2026-2036
Global Reputation Protection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reputation Protection Software Market Outlook
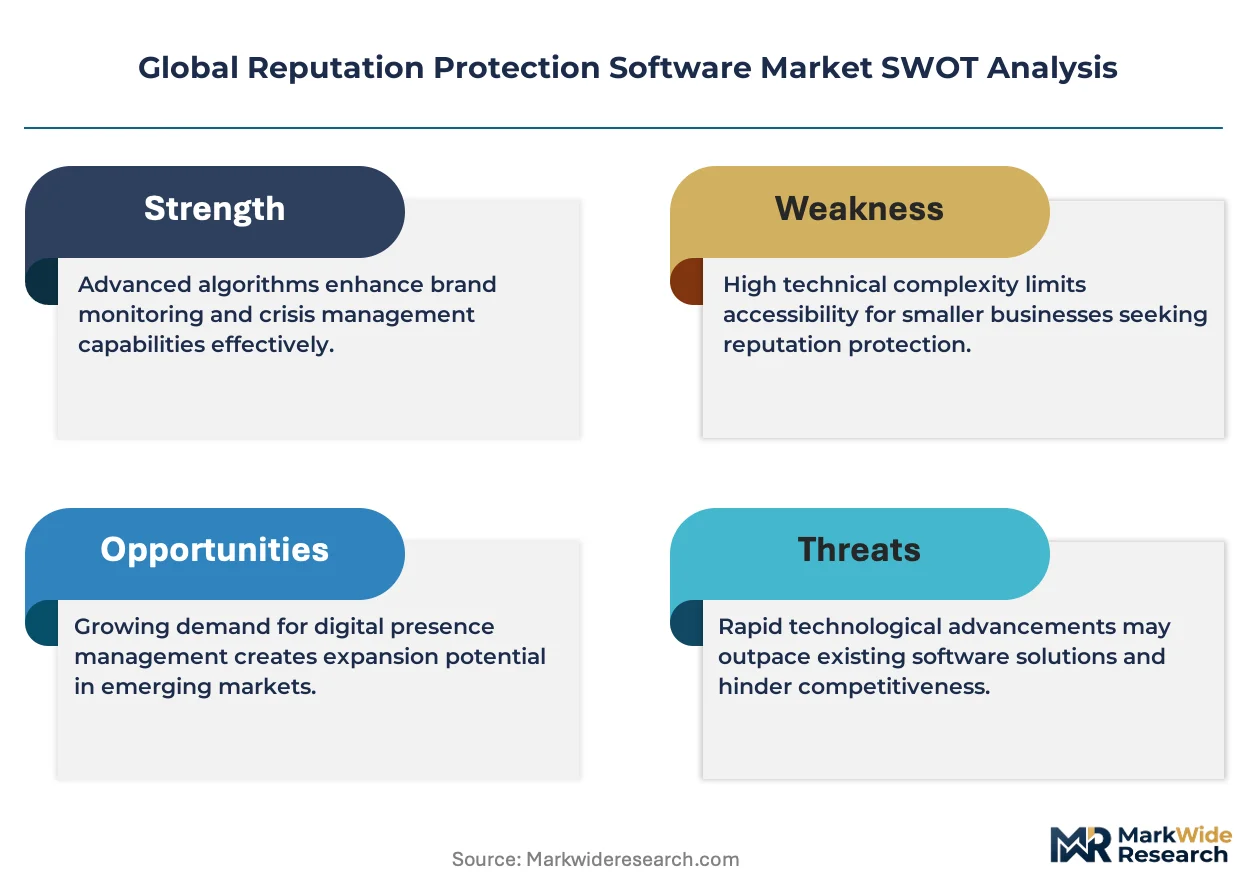
Healthcare provider networks is broadening as a buyer vertical for reputation protection software, driven by patient review platforms and HIPAA-related privacy incidents. ZeroFox leverages threat intelligence integration to anchor its position in digital risk monitoring for regulated industries. Meltwater competes through media monitoring scale and brand analytics depth across enterprise accounts. RepuGen specializes in healthcare-specific review aggregation and response automation, sustaining differentiation in a crowded field.
Reputation protection software encompasses platforms that monitor, analyze, and respond to brand-related signals across digital channels, using natural language processing, sentiment scoring, and real-time alert architectures to flag reputational threats before amplification. The primary commercial purpose centers on preserving stakeholder trust, reducing revenue at risk from negative information cascades, and enabling coordinated crisis response across marketing, legal, and communications functions. Cloud-based deployment leads in new customer acquisition due to lower implementation friction and faster time-to-value, while SaaS delivery models capture the strongest recurring revenue streams and margin expansion potential. Online monitoring represents the most mature product category with established pricing benchmarks, whereas crisis management modules command premium positioning due to high-stakes use cases and specialized workflow requirements.
The EU AI Act and GDPR shape European demand by mandating algorithmic transparency and data handling documentation, which reputation platforms must embed to serve regulated clients. In the United States, HIPAA and SEC disclosure rules create parallel compliance pressures that drive procurement in healthcare and publicly traded sectors. Stakeholders should monitor how generative AI content proliferation alters threat detection requirements and whether platform vendors can adapt scoring models faster than synthetic media techniques evolve.
Market Dynamics
Generative AI content proliferation is compressing detection windows for reputational threats, forcing platforms to accelerate NLP model refresh cycles and expand synthetic media identification capabilities across enterprise deployments.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must document algorithmic transparency and automated decision-making processes, creating procurement pull for platforms with embedded audit trails and explainable scoring architectures.
- Healthcare provider digitization:Patient review platforms and telehealth expansion multiply digital touchpoints where HIPAA-related privacy incidents can amplify rapidly, driving specialized monitoring demand.
- Real-time alert architectures:Sub-second sentiment spike detection enables crisis response before negative information cascades achieve viral velocity, anchoring value propositions for financial services and publicly traded firms.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominate hosting for reputation platforms, creating single-point vulnerability for service continuity and data sovereignty compliance.
- Training data access constraints:GDPR right-to-erasure provisions complicate historical sentiment dataset retention, degrading model accuracy for longitudinal threat pattern recognition.
- Open-source NLP substitution:Hugging Face transformers and similar libraries enable in-house sentiment analysis development, pressuring pricing for mid-market SaaS offerings.
Strategic Opportunities
- Saudi Arabia and UAE enterprise modernization:MOHAP and SFDA regulatory frameworks are maturing, creating first-mover advantage for platforms embedding Arabic-language NLP and regional social channel coverage.
- Voice and audio monitoring:Podcast and call center transcription integration converges with video deepfake detection, opening unified multimodal threat assessment product lines.
- SEC climate disclosure rules:Emerging requirements for ESG-related risk reporting extend reputation monitoring scope to sustainability controversies and greenwashing allegations.
Industry Challenges
- Multilingual NLP talent scarcity:Low-resource language model development and dialect-specific sentiment calibration require specialized computational linguists, constraining geographic expansion velocity.
- Legacy system API fragmentation:Enterprise CRM and ticketing platform heterogeneity forces costly custom integration work, extending implementation timelines and eroding SaaS margin profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reputation Protection Software Market |
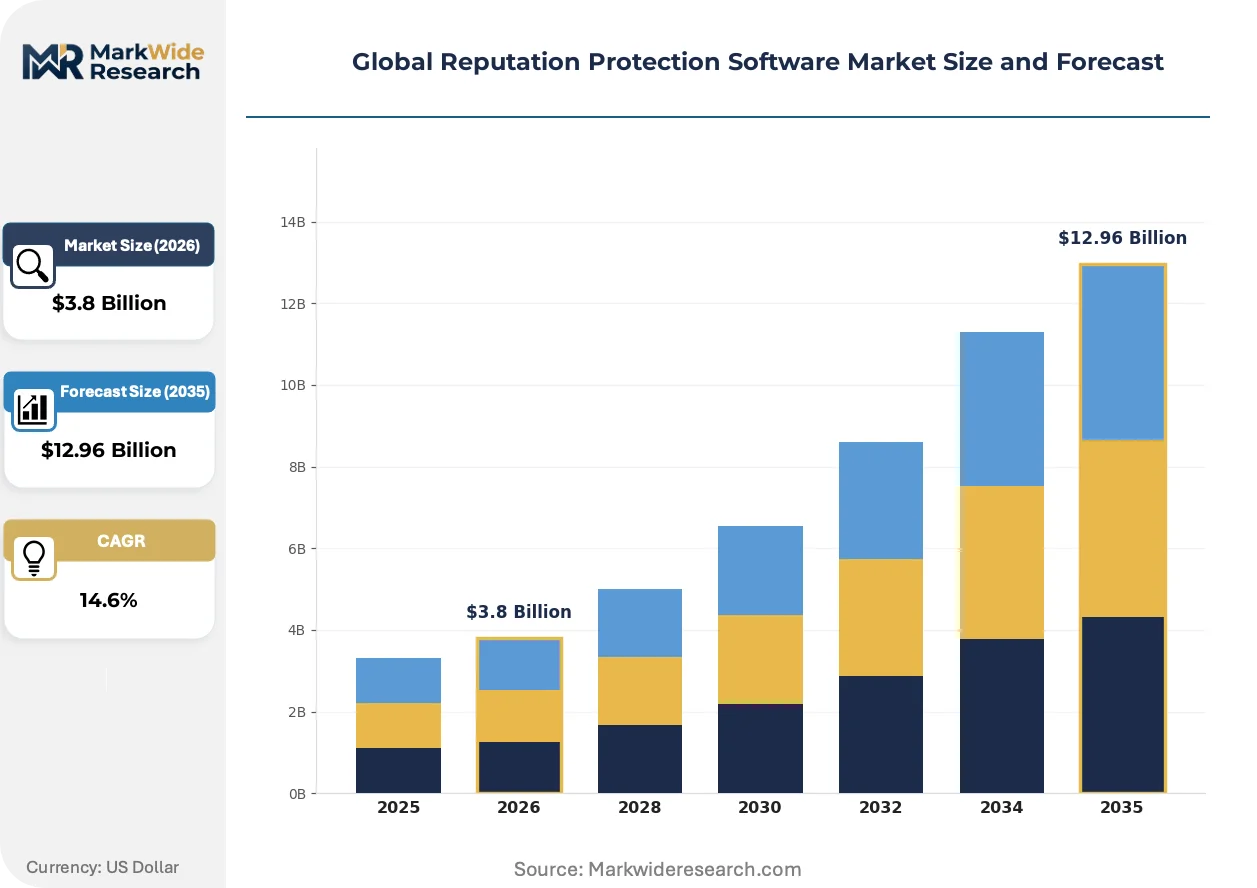
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online Monitoring, Brand Management, Social Listening, Crisis Management End User: SMEs, Corporate Companies, Government Agencies, Individuals Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | BrandYourself, ReputationDefender, ZeroFox, Terakeet, Meltwater, Netcraft, Red Points, RepuGen, Rankur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reputation Protection Software Market Strategic Shifts
Foundation model fine-tuning is compressing development cycles for threat detection capabilities, enabling smaller vendors to achieve parity with incumbents on synthetic media identification and cross-channel sentiment correlation.
Transformer-based architectures are overtaking recurrent neural networks for real-time sentiment classification tasks. Financial services compliance teams in the United States are deploying these models for SEC disclosure-related monitoring, replacing rules-based keyword systems that generated excessive false positives. The structural consequence is collapsing R&D barriers between tier-one platforms and specialized entrants, intensifying price competition in crisis management modules.
GDPR Article 22 enforcement is tightening documentation requirements for automated profiling decisions. European enterprises must now maintain human-in-the-loop override capabilities and algorithmic impact assessments, which reputation platforms are embedding as configurable workflow features. Healthcare networks in Germany and France represent the most affected segment, accelerating procurement of audit-ready systems ahead of CNIL and KBA supervisory examinations.
Subscription unbundling is fragmenting traditional all-inclusive SaaS contracts. Mid-market buyers in the United Kingdom and Australia are purchasing online monitoring à la carte while reserving crisis management modules for event-triggered activation, pressuring vendors to develop usage-based pricing without sacrificing recurring revenue predictability. This pattern is most visible among professional services firms with seasonal reputational risk exposure.
Global Reputation Protection Software Market Segmentation
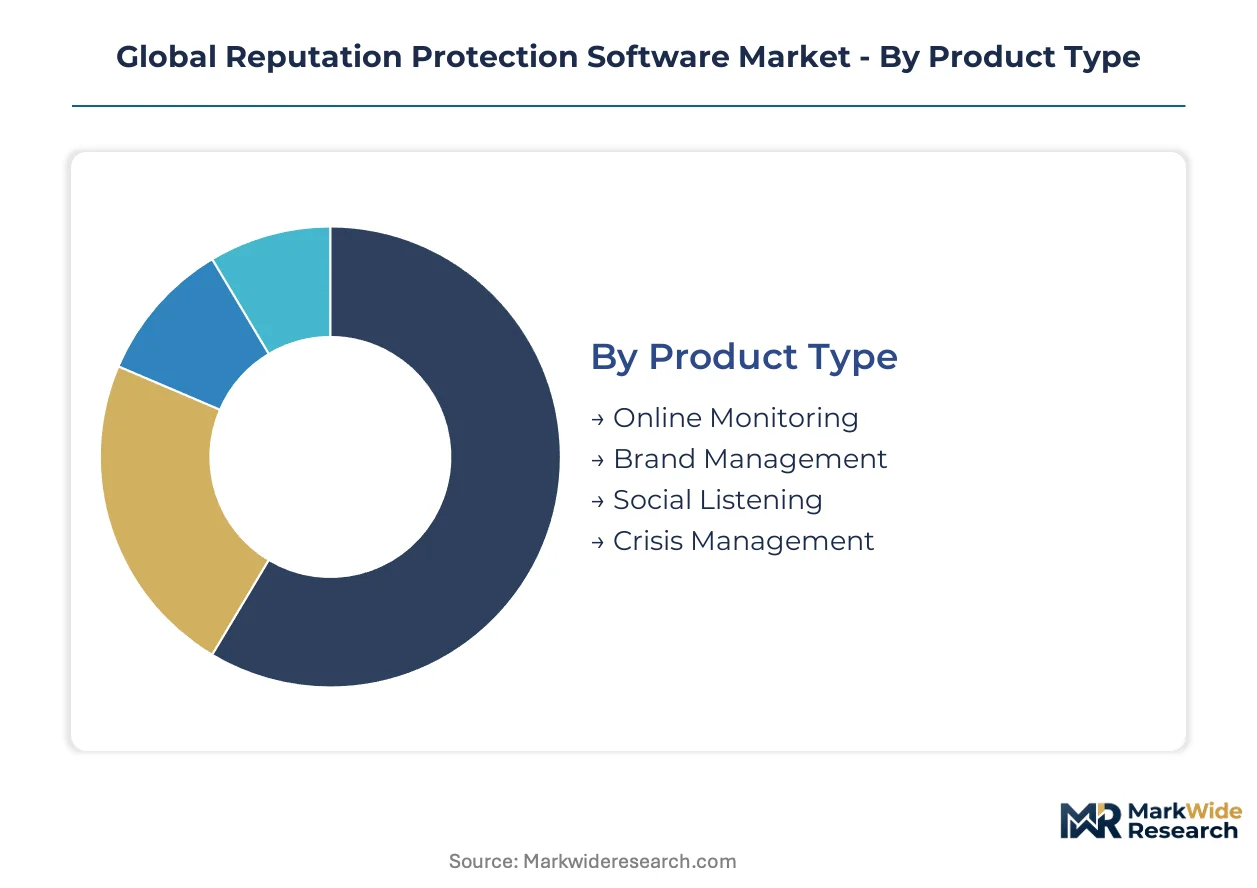
Reputation protection software vendors must architect compliance-ready platforms for divergent regulatory environments. Segmentation reveals where certification burdens concentrate and which deployment modes unlock geographic expansion.
Product Type:
EU AI Act algorithmic transparency requirements and GDPR automated decision-making documentation apply unevenly across functional modules, with crisis management facing the steepest audit obligations.
- Online Monitoring:Real-time sentiment scanning across digital channels using NLP pipelines and entity recognition. Demand concentrates in United States financial services, where SEC disclosure rules mandate rapid threat detection for publicly traded firms.
- Crisis Management:Workflow orchestration for coordinated response across legal, communications, and executive teams. German healthcare networks and French banking groups drive procurement under CNIL and KBA supervisory examination timelines.
- Brand Management:Unified dashboarding for brand health metrics and competitive positioning analysis.
- Social Listening:Platform-specific data ingestion for consumer sentiment tracking across regional social channels.
Online Monitoring sits at the top of the volume ranking, with Crisis Management climbing the fastest.
End User:
Procurement scale and compliance exposure diverge sharply across buyer types, with government agencies imposing sovereign data residency requirements that reshape vendor architecture decisions.
- Corporate Companies:Enterprise-grade deployments with multi-tenant architectures and API ecosystems for CRM integration. Saudi Aramco and UAE sovereign wealth funds anchor Middle Eastern demand as MOHAP and SFDA frameworks mature.
- Government Agencies:Classified-adjacent threat intelligence with air-gapped infrastructure options. Australian federal departments and Canadian provincial health authorities mandate TGA and Health Canada audit trail compatibility.
- SMEs:Self-service onboarding with pre-configured alert thresholds and limited customization scope.
- Individuals:Personal brand monitoring with automated takedown request generation for defamatory content.
Corporate Companies command the largest contract values, while Government Agencies show the steepest expansion trajectory.
Deployment:
Margin structures and implementation timelines separate delivery models, with hybrid architectures capturing buyers navigating incomplete cloud migration.
- Cloud-Based:AWS, Azure, or Google Cloud hosting with sub-24-hour provisioning. United Kingdom professional services firms favor this model for seasonal reputational risk exposure and rapid activation.
- SaaS:Recurring revenue optimization through usage-based tiering and modular feature access. Indian IT services exporters and Brazilian financial institutions drive volume under RBI and ANVISA data localization guidance.
- On-Premise:Dedicated infrastructure for air-gapped environments and legacy system tethering.
- Hybrid:Split architectures with sensitive processing on-premise and scale workloads in cloud.
SaaS dominates new customer acquisition velocity, with Hybrid deployments gaining share fastest among regulated European incumbents.
Service Type:
Professional services attach rates vary by buyer sophistication, with implementation complexity rising for enterprises replacing legacy rules-based keyword systems.
- Implementation:System integration with existing ticketing platforms and CRM environments. South Korean chaebols and Japanese keiretsu networks require METI-aligned project governance under MFDS pharmaceutical oversight timelines.
- Consulting:Risk assessment and response playbook development for industry-specific threat profiles. Swiss private banks and Luxembourg fund administrators purchase these services alongside Swissmedic and CSSF compliance reviews.
- Support:Tiered response SLAs with dedicated account management for enterprise accounts.
- Training:Certification programs for platform administration and crisis simulation exercises.
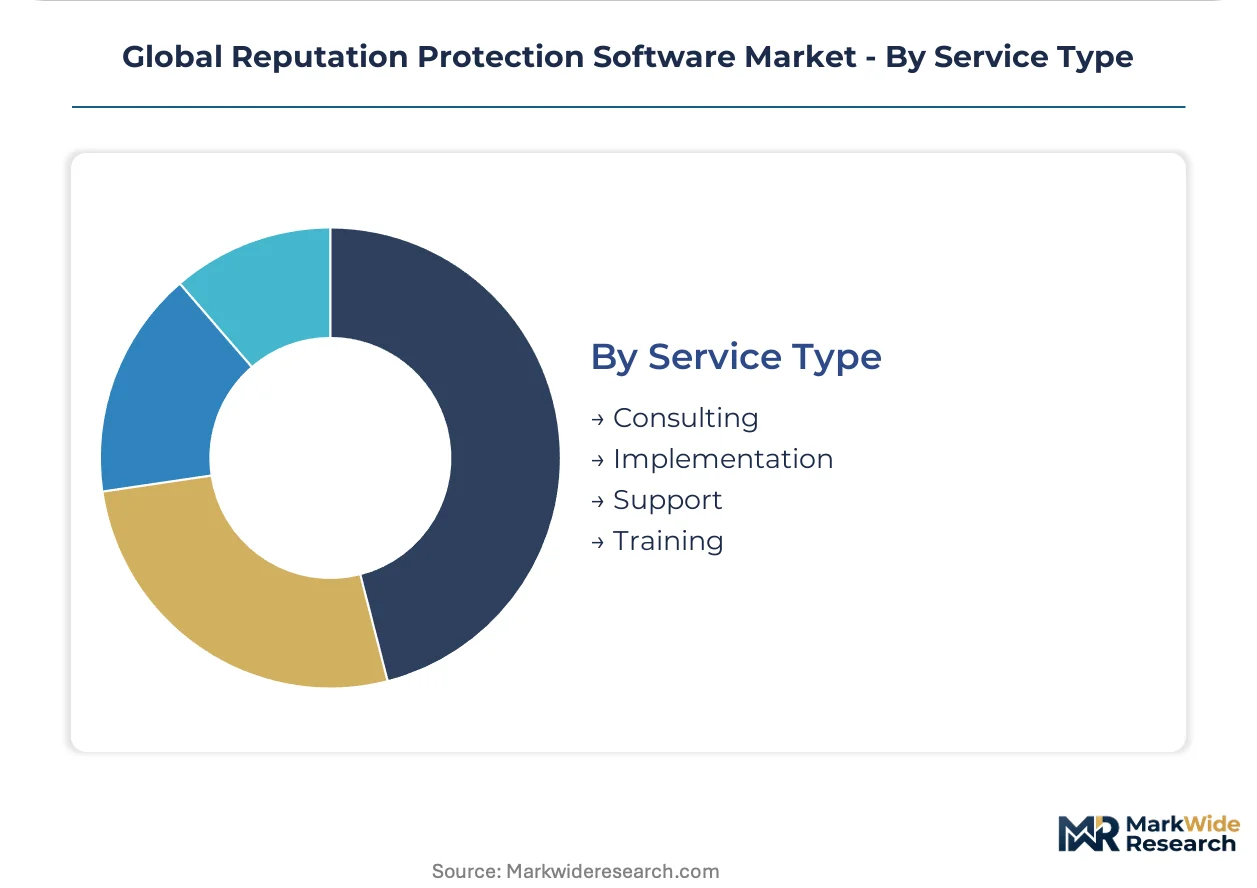
Implementation generates the highest services revenue per engagement, with Consulting expanding most quickly as ESG disclosure rules extend monitoring scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost arbitrage is redirecting procurement budgets toward jurisdictions with clearer regulatory roadmaps. Enterprises in high-enforcement zones accelerate platform adoption while others defer investment pending legislative clarity.
United States
SEC disclosure rules and HIPAA privacy mandates drive concentrated demand from publicly traded firms and healthcare networks. Financial services compliance teams in New York and Chicago deploy real-time sentiment monitoring for material event detection. Silicon Valley SaaS vendors anchor product development cycles around sub-second alert architectures.
Germany
CNIL-aligned enforcement of GDPR Article 22 and KBA supervisory examinations pressure banking and automotive sectors. Munich and Frankfurt-based enterprises mandate human-in-the-loop override capabilities for automated profiling decisions. Industrial Mittelstand firms in Baden-Württemberg purchase audit-ready crisis management modules ahead of regulatory deadlines.
United Kingdom
Professional services firms with seasonal reputational exposure favor cloud-based deployment for rapid activation. London's legal and consulting clusters unbundle subscription contracts, purchasing online monitoring à la carte. The Financial Conduct Authority's operational resilience requirements extend procurement to mid-market accountancies in Manchester and Edinburgh.
Saudi Arabia
MOHAP and SFDA regulatory maturation creates first-mover opportunity for Arabic-language NLP platforms. Riyadh-based sovereign wealth funds and enterprise modernization programs anchor regional demand. Jeddah healthcare networks deploy specialized monitoring as patient review platforms proliferate across the Kingdom.
Japan
METI-aligned project governance and MFDS pharmaceutical oversight shape procurement timelines for keiretsu networks. Tokyo and Osaka financial institutions replace rules-based keyword systems with transformer-based sentiment classification. Enterprise software vendors in the Kanto region embed crisis simulation training for cross-functional response coordination.
Global Reputation Protection Software Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents expand beyond core monitoring into adjacent threat detection capabilities. The vendor base organizes around three strategic archetypes: threat intelligence integrators, media monitoring scale players, and vertical-specialized boutiques. M&A activity concentrates on NLP talent acquisition and regional channel access. Technology licensing partnerships proliferate as foundation model providers seek enterprise distribution.
Within the threat intelligence tier, ZeroFox exemplifies integration-heavy positioning for regulated industries. Meltwater occupies a scale-driven position anchored in media monitoring breadth across enterprise accounts. RepuGen represents vertical specialization, embedding healthcare-specific workflows for patient review aggregation. These three anchors illustrate divergent paths to differentiation in a market where NLP capability parity is compressing.
| Leading Market Players |
|---|
| BrandYourself |
| ReputationDefender |
| ZeroFox |
| Terakeet |
| Meltwater |
| Netcraft |
| Red Points |
| RepuGen |
| Rankur |
| Others |
Value Chain & Pricing Dynamics
EU AI Act algorithmic transparency mandates gate both qualified supply and premium-tier pricing access for reputation protection platforms, forcing vendors to embed audit-ready architectures that separate certified providers from commodity sentiment tools. Cloud infrastructure concentration in AWS, Azure, and Google Cloud creates single-point dependencies that amplify pricing power for hyperscalers while compressing margins for downstream platform vendors.
Pricing Analysis
Direct-to-enterprise SaaS subscriptions dominate channel economics, with annual recurring revenue models capturing 70-85% of contract value upfront and minimizing distributor margin layers. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth—GDPR Article 22-ready crisis management modules command 40-60% premiums over basic online monitoring. Pricing pressure stems from open-source NLP substitution via Hugging Face transformers, which enables in-house development for mid-market buyers. Corporate enterprises in financial services show lowest price sensitivity due to SEC disclosure liability exposure, while UK professional services firms drive unbundling demand for à la carte activation.
Supply Chain Analysis
Returns and data deletion workflows shape reverse-logistics architecture as GDPR right-to-erasure provisions force historical dataset purging that degrades model retraining cycles. Core supply concentrates in the United States, Ireland, and Singapore—where AWS, Azure, and Google Cloud anchor hyperscale data center footprints for sub-second alert latency. Transformer model development draws from NVIDIA GPU clusters, specialized computational linguist talent pools, and foundation model licensing from OpenAI and Anthropic. Single-source vulnerability runs through cloud infrastructure concentration, with tariff exposure minimal but regulatory fragmentation across data residency regimes complicating multi-tenant deployments. Distribution runs through direct enterprise sales teams with professional services attach for implementation complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in reputation protection software rests on automated compliance documentation that reduces human-in-the-loop service costs while enabling premium pricing for audit-ready platforms. Foundation model fine-tuning is compressing R&D expenditure for specialized entrants, shifting value capture toward distribution scale and vertical workflow depth.
For Market Incumbents: Deploy threat intelligence integration as the primary defensive lever against specialized healthcare entrants like RepuGen. Consolidate position through acquisition of Arabic-language NLP capabilities for Saudi Arabia and UAE first-mover advantage, while embedding CNIL and KBA audit trail features ahead of European supervisory examination timelines. Counter open-source substitution pressure by anchoring enterprise stickiness through CRM and ticketing platform API ecosystems that extend switching costs. For New Entrants and Emerging Players: Mid-market healthcare networks in Germany and France represent the most penetrable buyer archetype, as GDPR Article 22 enforcement accelerates procurement of human-in-the-loop override systems ahead of regulatory deadlines. Voice and audio monitoring for podcast transcription and call center integration offers white-space product development with limited incumbent specialization. Pursue channel partnerships with ESG consulting firms to capture SEC climate disclosure rule-driven demand for sustainability controversy monitoring. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specialized boutiques because NLP capability parity is collapsing R&D differentiation and channel access determines customer acquisition efficiency. Target 5-10 year viability through platforms with embedded regulatory compliance architectures that sustain pricing power across enforcement cycles. Monitor generative AI content proliferation velocity as the critical inflection signal—detection window compression beyond current NLP refresh cycles would trigger platform obsolescence risk and M&A distress.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CRM and ticketing API ecosystems extend switching costs for financial services clients under SEC disclosure pressure. |
| Acquisition of Specialist Firm | Arabic-language NLP capabilities unlock MOHAP and SFDA-compliant deployments in Saudi Arabia and UAE modernization programs. |
| Product Launch | Voice and audio monitoring modules capture podcast and call center transcription demand converging with deepfake detection. |
| Strategic Partnership | Foundation model licensing agreements with OpenAI and Anthropic accelerate synthetic media identification parity. |
| Geographic Expansion | CNIL and KBA audit-ready positioning penetrates German healthcare networks ahead of supervisory examination timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs, compliance officers, marketing technology procurement leads, and NLP engineering directors with secondary validation against SEC filings, GDPR enforcement actions by CNIL and KBA, hyperscaler capex disclosures, and healthcare data breach notification databases. Bottom-up triangulation across deployment model, organization size, vertical specialization, and regional regulatory cluster dimensions converged with top-down macroeconomic sensitivity testing.
Segment-weighting approaches anchored the analytical framework, with product type, end user, deployment mode, and service type dimensions modeled across the projection horizon. CAGRs derived from historical adoption velocity in financial services and healthcare verticals, adjusted for generative AI content proliferation impact on detection window requirements and EU AI Act compliance timeline acceleration. Industry-specific inputs included transformer model refresh cycle compression rates and cloud infrastructure concentration risk coefficients.
Underlying measurement precision varies by segment; crisis management modules carry tighter precision than social listening due to established pricing benchmarks and high-stakes use case documentation. Forecasts reflect documented assumptions about regulatory enforcement intensity and synthetic media technique evolution velocity. Practitioners should monitor GDPR Article 22 examination outcomes and foundation model capability release cycles for early signals of platform obsolescence risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Video Intercom Devices and Equipment Market
Security Software
Banking Encryption Software Market
Security Software
Global Mobile Security Software Market
Security Software
Global Advanced Authentication Market
Security Software
Global SMS Firewall Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Employee Surveillance and Monitoring Software Market
Security Software
Endpoint Security Solutions Market
Security Software
Global Anti-Spam Software Market
Security Software
Consumer Endpoint Security Market
Security Software
Application Control Market
Security Software
Identity Governance and Administration Market
Security Software
Encryption As A Service Market
Security Software
Network Video Recorder (NVR) Market
Security Software
Security Software for Consumers Market
Security Software
Global Data Classification Market