
 Trade Surveillance Market | 2026-2036
Trade Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Trade Surveillance Market Intelligence
Cloud-native architecture is fragmenting the traditional on-premises trade surveillance stack. NICE Ltd leverages its voice analytics heritage to anchor compliance workflows across capital markets. Nasdaq, Inc. competes through real-time market data integration with surveillance engines. FIS sustains a broad installed base among tier-one banks with modular deployment options.
Trade surveillance encompasses the systematic monitoring, detection, and reporting of market abuse, insider trading, and order manipulation across financial instruments, typically processing millions of transactions daily through pattern-recognition algorithms and behavioral analytics. Cloud-based solutions lead adoption as banks shed fixed infrastructure costs, while machine learning represents the fastest-growing technology segment as firms replace brittle rule-based thresholds with adaptive anomaly detection. Hybrid deployments capture margin pools from institutions with data residency constraints. Compliance departments drive purchasing decisions, though asset managers represent an emerging buyer segment as regulatory scope widens.
SEC rules in the United States, MiFID II in Europe, and MAS guidelines in Singapore shape product standards by mandating trade reconstruction capabilities and cross-asset surveillance. The EU AI Act introduces additional algorithmic transparency requirements for automated surveillance systems. Banks and vendors must monitor how divergent supervisory expectations across jurisdictions affect deployment architecture and model documentation obligations.
Market Dynamics
Cloud-native architecture is fragmenting the traditional on-premises trade surveillance stack as investment banks shed fixed infrastructure costs. Machine learning adoption accelerates as compliance departments replace brittle rule-based thresholds with adaptive anomaly detection systems.
Growth Catalysts
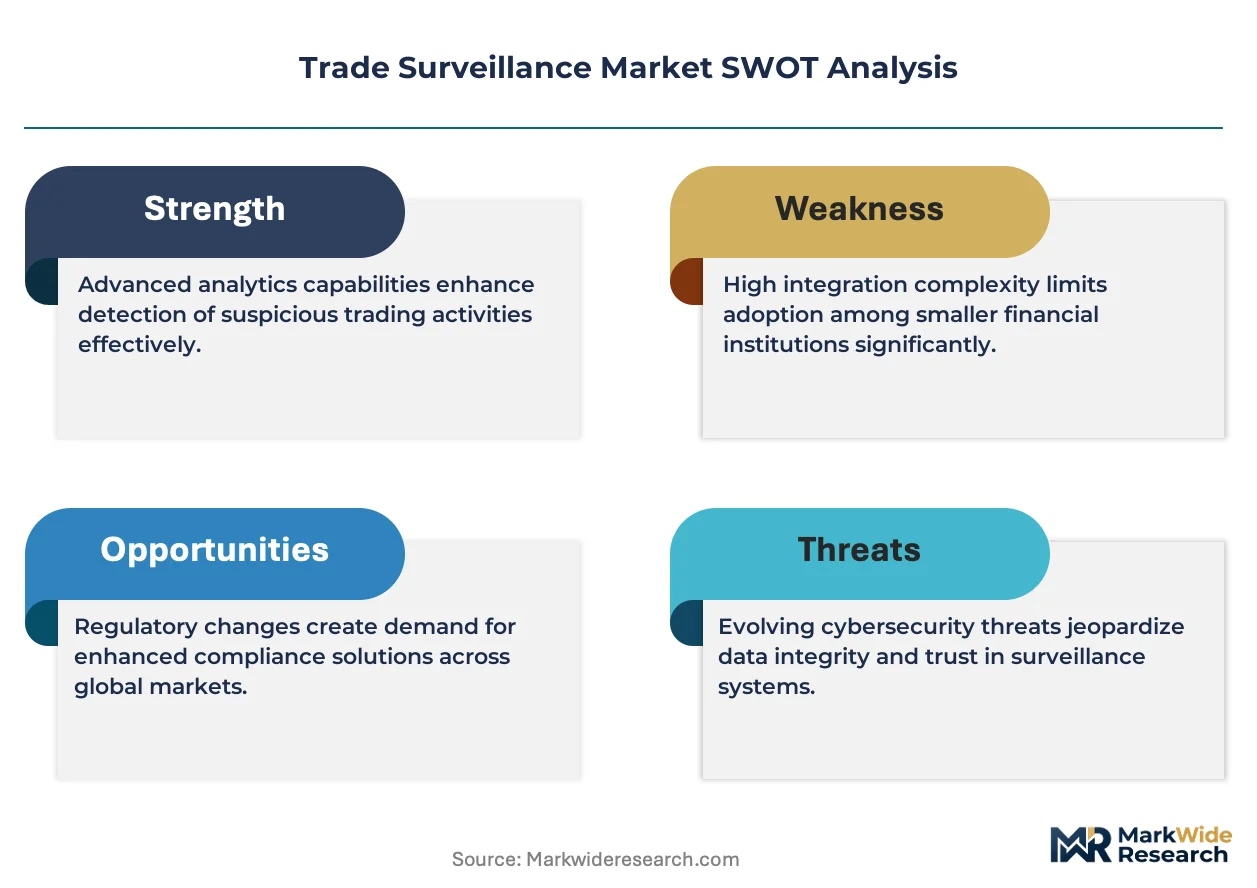
- MiFID II transaction reconstruction mandates:European investment firms must maintain complete audit trails across voice, electronic, and algorithmic order flows. Compliance departments allocate capital toward integrated surveillance platforms that unify these data streams.
- SEC cross-market surveillance program expansion:US broker-dealers face heightened scrutiny of wash trading and layering schemes across fragmented equity venues. Surveillance vendors capture upgrade cycles as firms consolidate point solutions.
- MAS guidelines on algorithmic trading:Singapore's financial regulator mandates pre-trade risk controls and post-trade surveillance for automated execution systems. Asset managers in the city-state accelerate procurement of real-time monitoring tools.
Market Restraints
- Data residency constraints:European and Asian banks with sovereign data requirements cannot deploy pure public-cloud surveillance architectures. Hybrid deployments impose higher total cost of ownership and extended implementation timelines.
- Specialized talent scarcity:Compliance technology teams require expertise spanning financial markets, machine learning operations, and regulatory frameworks. Compensation inflation for quantitative surveillance analysts constrains vendor delivery capacity.
- Legacy system entrenchment:Tier-one banks maintain decades-old transaction databases with incompatible data schemas. Migration costs for trade reconstruction capabilities often exceed seven-figure thresholds per implementation.
Strategic Opportunities
- Asset manager regulatory scope expansion:UCITS and AIFMD disclosure requirements now capture order routing transparency for fund complexes. Surveillance vendors can extend product suites from sell-side to buy-side workflows.
- EU AI Act algorithmic transparency mandates:Automated surveillance systems deployed in European jurisdictions must document model logic and training data provenance. Compliance documentation tools represent an adjacent revenue stream.
- Cryptocurrency surveillance standardization:Virtual asset service providers face emerging FATF travel rule obligations across Singapore, Switzerland, and the United States. Pattern-recognition engines trained on traditional instruments adapt to blockchain transaction monitoring.
Industry Challenges
- Model explainability requirements:Supervisory examinations now demand interpretable outputs from machine learning-based abuse detection. Engineering teams must balance predictive accuracy against regulatory auditability.
- Cross-jurisdictional alert reconciliation:Global banks operate under divergent definitions of market manipulation across SEC, FCA, and MAS regimes. Surveillance platforms require configurable rule engines that fragment product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trade Surveillance Market |
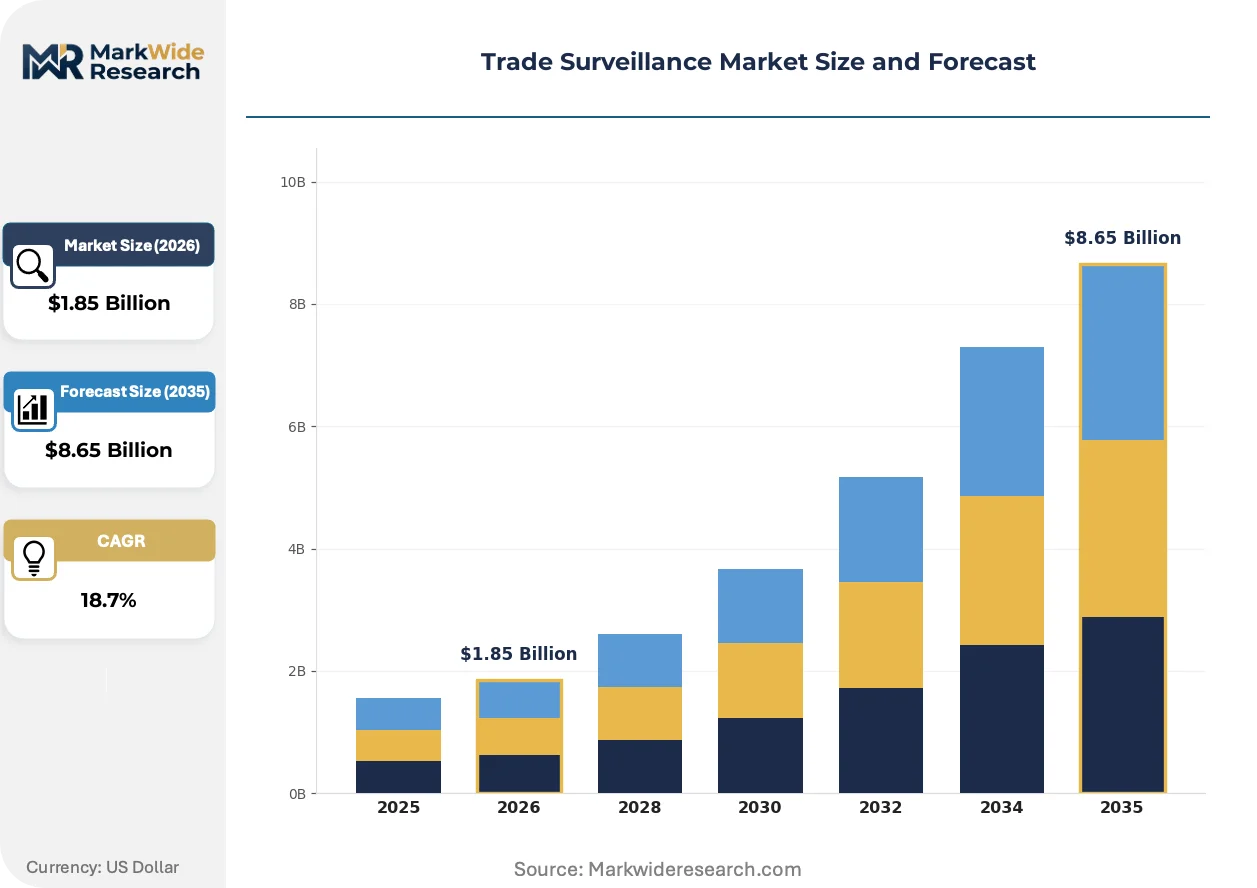
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: Machine Learning, Artificial Intelligence, Big Data Analytics, Rule-Based Systems End User: Investment Banks, Brokerage Firms, Asset Managers, Compliance Departments Deployment Model: Public Cloud, Private Cloud, Virtualization, Dedicated Hosting |
| Companies Covered | NICE Ltd, Nasdaq, Inc., FIS, ACA Group, OneMarketData, BAE Systems, Eventus Systems, Software AG, IPC Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trade Surveillance Market Strategic Shifts & Innovations
Artificial intelligence is compressing detection latency from T+1 batch processing to real-time streaming analytics. Surveillance vendors compete on model precision rather than data throughput alone.
Natural language processing engines are migrating from post-trade voice transcription to real-time trade reconstruction. Tier-one banks in London and New York deploy these tools to reconstruct trader intent across Bloomberg chat, Symphony messaging, and turret phone lines. Compliance officers gain contextual alerts that link spoken instructions to electronic order timestamps, collapsing investigation cycles from weeks to hours.
The EU AI Act introduces conformity assessment obligations for high-risk AI systems deployed in capital markets. Automated surveillance platforms must demonstrate human oversight mechanisms and bias mitigation protocols before deployment. European banks are restructuring vendor procurement processes to require algorithmic impact documentation, favoring established providers with dedicated model risk management functions.
Buy-side procurement patterns are fragmenting as asset managers build internal surveillance capabilities rather than relying on prime broker feeds. Large hedge funds in Connecticut and quantitative managers in Paris hire former sell-side compliance technologists to customize open-source surveillance frameworks. This talent rotation compresses vendor pricing power and accelerates feature commoditization across the mid-market segment.
Trade Surveillance Market Segmentation
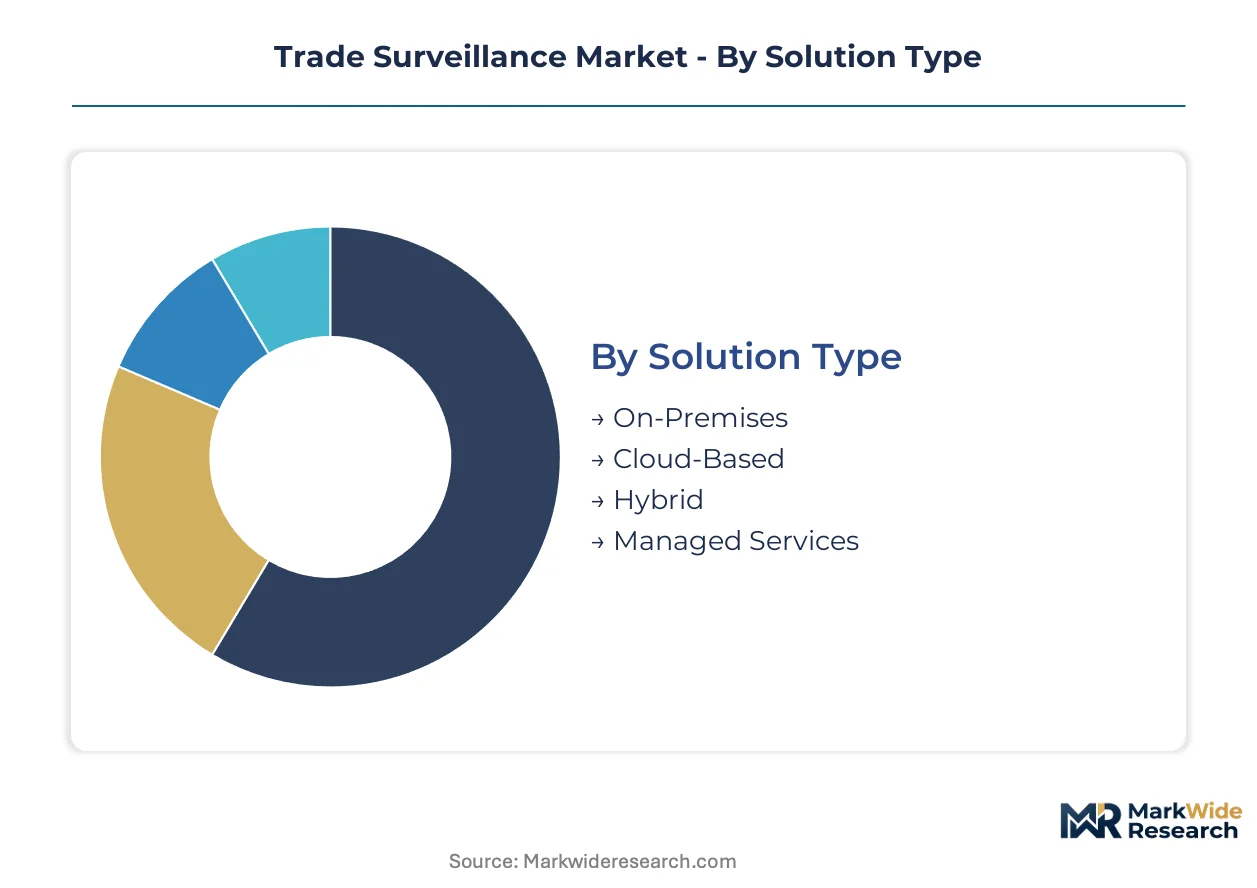
Trade surveillance procurement patterns diverge sharply across deployment architectures, analytical engines, institutional buyer types, and infrastructure models. Vendors must align product roadmaps with these four intersecting dimensions to capture upgrade cycles and compliance-driven replacement demand.
Solution Type:
Deployment architecture determines total cost of ownership and implementation timelines for financial institutions with varying data sovereignty requirements.
- Cloud-Based:Multi-tenant architectures eliminate fixed infrastructure overhead and enable elastic compute scaling during market volatility spikes. Investment banks in London and Singapore prioritize these solutions to accelerate MiFID II and MAS compliance timelines without capital expenditure commitments.
- On-Premises:Dedicated hardware installations within bank data centers satisfy strict data residency mandates from national regulators. European institutions with sovereign cloud restrictions maintain these deployments despite higher operational burdens and slower feature update cycles.
- Hybrid:Split architectures process sensitive transaction data locally while routing analytics workloads to private cloud instances. This configuration captures institutions transitioning from legacy stacks without full public cloud exposure.
- Managed Services:Outsourced surveillance operations transfer compliance accountability to vendor operations centers. Mid-tier brokerage firms lacking internal quantitative surveillance expertise adopt this model to access specialized talent pools.
The dominant share belongs to Cloud-Based solutions, while Hybrid deployments are closing the gap fastest among institutions with phased migration strategies.
Technology:
Analytical sophistication separates premium surveillance platforms from commodity compliance tools, with machine learning capabilities now table stakes for tier-one procurement.
- Machine Learning:Adaptive algorithms detect novel manipulation patterns without explicit rule programming, reducing false positive rates by orders of magnitude against static thresholds. Compliance departments at quantitative hedge funds and electronic market makers deploy these systems for real-time abuse detection across fragmented equity venues.
- Rule-Based Systems:Deterministic logic engines apply fixed thresholds to transaction attributes, delivering interpretable alerts favored by regulatory examiners. Legacy installations at established investment banks continue generating recurring maintenance revenue despite functional limitations.
- Artificial Intelligence:Natural language processing and computer vision extend surveillance to unstructured communications and alternative data sources. Voice analytics integration with electronic order timestamps enables complete trade reconstruction mandated by SEC and FCA examinations.
- Big Data Analytics:Distributed processing frameworks handle petabyte-scale transaction histories for longitudinal pattern analysis. These engines support cross-asset surveillance spanning equities, derivatives, and fixed income instruments within unified platforms.
Machine Learning commands the dominant technology investment, with Artificial Intelligence expanding most quickly as NLP capabilities mature for real-time deployment.
End User:
Buyer sophistication and procurement authority vary dramatically across sell-side and buy-side institutions, shaping vendor sales cycles and product configuration requirements.
- Investment Banks:Universal banks with global trading operations require comprehensive surveillance spanning cash equities, derivatives, and foreign exchange. These institutions drive platform consolidation as they retire fragmented point solutions accumulated through decades of technology investment.
- Compliance Departments:Centralized risk functions control capital allocation for surveillance technology, prioritizing audit trail completeness and regulatory defensibility. Procurement decisions emphasize vendor stability and documented model governance over feature velocity.
- Brokerage Firms:Agency execution businesses focus surveillance investment on order handling compliance and best execution documentation. Smaller firms favor managed service arrangements to access capabilities beyond internal technical capacity.
- Asset Managers:Buy-side institutions face expanding regulatory scope under UCITS and AIFMD disclosure requirements. Large hedge funds and quantitative managers increasingly build internal surveillance capabilities rather than relying on prime broker feeds.
Investment Banks retain the dominant procurement volume, though Asset Managers are gaining share fastest as regulatory perimeter expansion drives independent compliance investment.
Deployment Model:
Infrastructure abstraction level determines operational flexibility, security posture, and integration complexity with existing bank technology stacks.
- Private Cloud:Single-tenant virtualized environments deliver cloud economics without multi-tenant security exposure. Banks with classified data requirements deploy these models to satisfy internal risk committees while capturing automation benefits.
- Public Cloud:Shared infrastructure services from hyperscale providers enable rapid provisioning and global distribution of surveillance workloads. Adoption concentrates among digital-native financial institutions without legacy data center investments.
- Dedicated Hosting:Physically isolated server deployments within vendor or third-party facilities provide compliance documentation simplicity. Regional banks and specialized broker-dealers favor this model for predictable cost structures.
- Virtualization:Containerized application deployment abstracts surveillance software from underlying hardware, enabling portable configurations across on-premises and cloud substrates. Engineering teams leverage this flexibility for disaster recovery and capacity scaling.
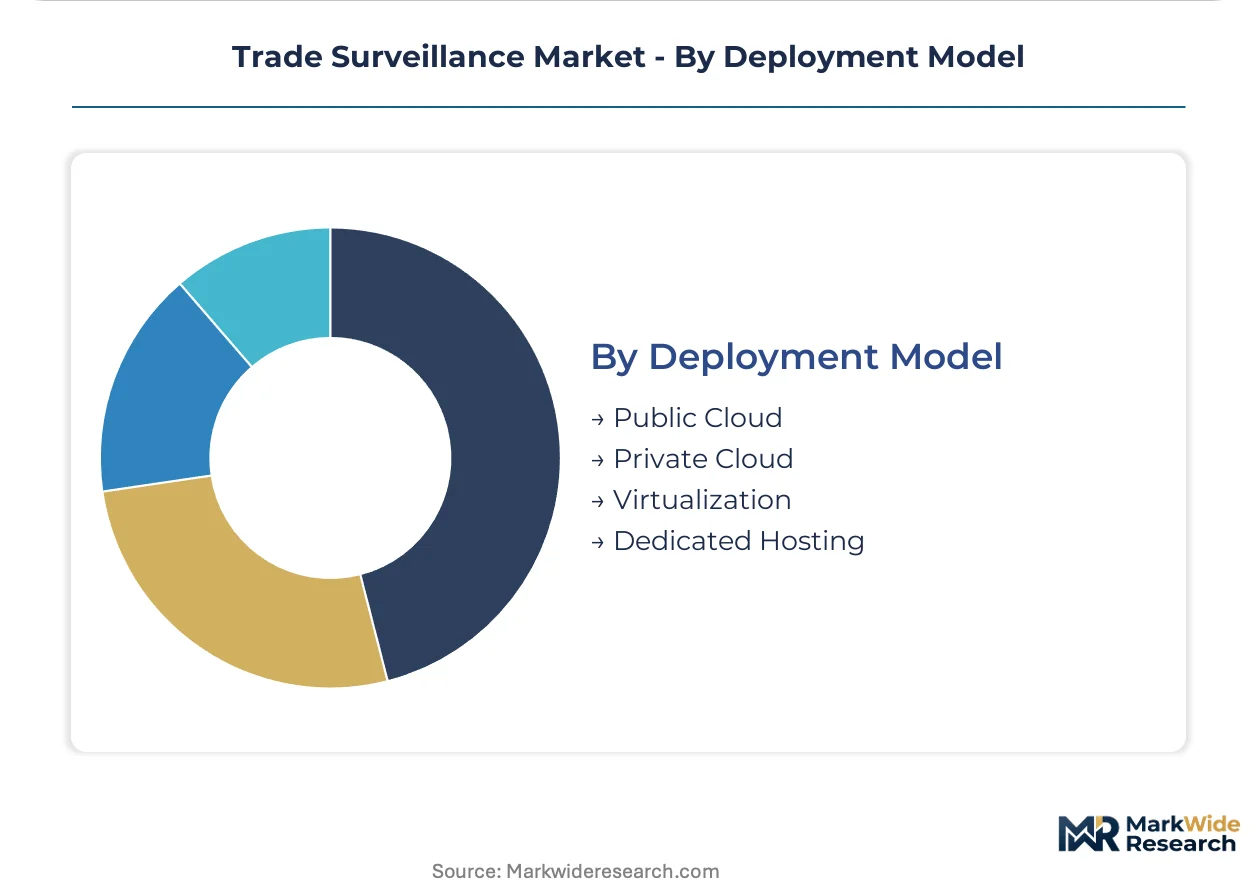
Private Cloud holds the dominant deployment preference among established institutions, while Public Cloud climbs fastest among fintech entrants and greenfield compliance builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Investment banks and asset managers concentrate procurement authority in financial centers with active capital markets and stringent regulatory oversight. Compliance technology spending clusters where transaction volumes and supervisory scrutiny intersect most intensely.
United States
Broker-dealers in New York and Chicago drive demand for cross-market surveillance covering fragmented equity venues. SEC examination priorities emphasize wash trading and layering detection across dark pools and lit exchanges. The Tri-State corridor anchors vendor delivery capacity, with compliance technology teams concentrated in Manhattan and Greenwich.
United Kingdom
Investment banking headquarters in the City of London and Canary Wharf mandate integrated voice and electronic surveillance for MiFID II transaction reconstruction. FCA supervisory expectations require complete audit trails linking trader communications to order timestamps. Compliance technology procurement exceeds continental European levels due to sell-side institution density.
Singapore
Asset managers and proprietary trading firms populate the Marina Bay financial district under MAS guidelines for algorithmic trading surveillance. Pre-trade risk controls and real-time monitoring obligations apply to automated execution systems. Regional banks use Singapore as a compliance technology hub for Southeast Asian operations.
Germany
Universal banks in Frankfurt maintain on-premises surveillance architectures to satisfy sovereign data requirements under national financial regulations. BaFin examinations scrutinize model governance for machine learning-based abuse detection. The Rhine-Main cluster hosts specialized compliance technology consulting practices serving DAX-listed institutions.
Switzerland
Private banks and wealth managers in Zurich and Geneva deploy surveillance platforms for cross-border transaction monitoring under FATF obligations. FINMA guidance shapes documentation standards for algorithmic transparency. The Swiss financial center attracts surveillance vendors seeking reference implementations for EU AI Act conformity assessment.
Trade Surveillance Market Key Industry Players
Channel-controlling players compete with product-specialist players across deployment architecture and analytical sophistication dimensions. The vendor base separates into three tiers: established financial technology conglomerates with broad installed bases, specialized surveillance pure-plays with machine learning differentiation, and managed service providers capturing mid-market outsourcing demand. Consolidation pressure intensifies as tier-one banks retire fragmented point solutions. Strategic moves center on cloud-native platform migration and compliance documentation tooling for EU AI Act readiness.
Within the established technology tier, NICE Ltd and Nasdaq, Inc. exemplify divergent heritage-based positioning. NICE leverages voice analytics capabilities developed in security applications to anchor trade reconstruction workflows. Nasdaq competes through exchange-operated market data integration with surveillance engines. FIS occupies a position among modular platform providers sustaining relationships with tier-one banks through flexible deployment options. These three entities represent distinct competitive vectors: communications-centric reconstruction, market data-anchored real-time detection, and infrastructure-modular enterprise delivery.
| Leading Market Players |
|---|
| NICE Ltd |
| Nasdaq, Inc. |
| FIS |
| ACA Group |
| OneMarketData |
| BAE Systems |
| Eventus Systems |
| Software AG |
| IPC Systems |
| Others |
Cost & Logistics Intelligence
Undercapacity in machine learning engineering talent across London and New York is compressing vendor delivery timelines and elevating implementation premiums. Tier-one banks absorb these costs through multi-year enterprise agreements, while mid-tier institutions face pricing exclusion from advanced surveillance capabilities.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate enterprise procurement for on-premises deployments, while SaaS-tiered subscriptions capture cloud-native adoptions. Pricing stratifies across premium, standard, and economy tiers based on data throughput volume and model customization depth. Pricing pressure stems from open-source surveillance frameworks commoditizing mid-market functionality. Asset managers exhibit highest price sensitivity due to discretionary compliance budgets, whereas investment banks prioritize audit defensibility over cost optimization.
Supply Chain Analysis
Contract manufacturing concentrates among hyperscale cloud providers AWS, Azure, and Google Cloud Platform for surveillance compute infrastructure, with specialized voice analytics hardware sourced from Israeli and Taiwanese component vendors. Software development draws from engineering talent pools in India, Poland, and Portugal. Supply chain risk centers on single-source vulnerability for GPU acceleration chips essential to real-time pattern recognition. Distribution runs through direct enterprise sales teams and systems integrators like Accenture and Deloitte for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of quantitative surveillance analysts capable of spanning financial markets, machine learning operations, and regulatory frameworks is constraining vendor scalability and inflating compensation costs across the ecosystem.
For Market Incumbents: Pre-empt talent poaching from buy-side internalization by building captive analytics academies in lower-cost jurisdictions. Acquire specialized NLP vendors to secure voice-to-electronic trade reconstruction capabilities before regulatory examinations intensify. Consolidate fragmented point solution portfolios to reduce customer switching incentives. For New Entrants and Emerging Players: Establish a beachhead in cryptocurrency surveillance for virtual asset service providers facing FATF travel rule obligations. Target mid-tier European asset managers with hybrid deployment options that satisfy BaFin data residency requirements without full on-premises burden. Lead with EU AI Act compliance documentation as a differentiated procurement wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native surveillance platforms as containerization reduces infrastructure overhead. Long-term viability favors vendors with recurring revenue concentration above sixty percent and demonstrated model governance frameworks. Acquisition target archetype: surveillance pure-plays with machine learning differentiation and established tier-two bank references. Monitor SEC examination priority shifts as inflection indicator for upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Elastic compute scaling during volatility spikes reduces fixed infrastructure commitments for tier-one banks. |
| EU AI Act Compliance Documentation | Algorithmic impact assessment tooling creates adjacent revenue streams beyond core surveillance licenses. |
| Voice Analytics Integration | Real-time trade reconstruction collapses investigation cycles from weeks to hours for FCA examinations. |
| Buy-Side Product Extension | UCITS and AIFMD scope expansion opens procurement relationships with hedge funds and quant managers. |
| Strategic Partnership with Hyperscalers | Co-selling arrangements with AWS and Azure accelerate enterprise procurement cycles for cloud deployments. |
Research Approach
A spread of perspectives from compliance technology officers, surveillance platform engineers, regulatory affairs directors, and quantitative risk analysts converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC examination letters, MiFID II technical standards, MAS circulars, and vendor RFP documentation. Bottom-up sizing of procurement volumes triangulated against top-down regulatory mandate scope across the analysis window.
Demand-supply balance modeling anchored forecast outputs, with segmentation across deployment architecture, analytical engine type, institutional buyer category, and infrastructure abstraction level. CAGRs derived from regression analysis of historical compliance technology spending against regulatory enforcement intensity. Forecast inputs incorporated algorithmic trading volume growth and cross-asset surveillance mandate expansion.
Sensitivities concentrate around divergent supervisory expectations across SEC, FCA, and MAS regimes that could fragment product roadmaps. Forecasts reflect assumptions regarding cloud adoption velocity and machine learning model explainability requirements. Quarterly review of regulatory examination priority shifts and vendor consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Asia-Pacific BFSI Biometrics Market
Risk Management and Compliance
Risk Management Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Financial Risk Management Software Market