
 AI in Fraud Management Market | 2026-2036
AI in Fraud Management Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Fraud Management Market Outlook
Buyer concentration across financial institutions is rebalancing as mid-tier banks and fintechs fragment the addressable base that legacy vendors once dominated. IBM Corporation leverages its Watson platform to anchor enterprise-scale fraud orchestration for tier-one banks. SAS Institute Inc. sustains deep analytical R&D intensity that differentiates its behavioral scoring engines. FICO competes through proprietary Falcon consortium data that controls risk-model performance benchmarks across North American card issuers.
AI in fraud management encompasses machine learning models, deep learning architectures, natural language processing engines, and neural network ensembles that analyze transactional velocity, device fingerprints, and behavioral biometrics to flag anomalous patterns in milliseconds. Its primary commercial purpose is to reduce false-positive rates while intercepting authorized push payment fraud before settlement finality. Machine learning and deep learning segments lead deployment volumes because supervised and unsupervised algorithms adapt fastest to evolving attack vectors. Cloud-based delivery is accelerating fastest among deployment modes as latency-sensitive inference migrates to edge-proximate infrastructure.
The Federal Reserve, SEC, and FFIEC in the United States enforce escalating expectations for model risk management and consumer protection in algorithmic fraud systems. The EU AI Act and GDPR impose parallel conformity requirements on automated decision-making for European financial institutions. Stakeholders must monitor divergence between U.S. sectoral guidance and EU horizontal AI regulation when architecting cross-border fraud platforms.
Market Dynamics
Real-time payment infrastructure deployment is compressing fraud detection windows from batch-based overnight scoring to sub-100-millisecond inference requirements. This velocity shift is forcing banks to rebuild decision architectures around streaming data pipelines and edge-compute inference clusters.
Growth Catalysts
- FedNow instant payment rail:The Federal Reserve's settlement system mandates real-time fraud screening, compelling financial institutions to upgrade from legacy batch systems to streaming analytics platforms.
- Behavioral biometrics:Keystroke dynamics, mouse-movement patterns, and touchscreen pressure analysis now authenticate users without friction, reducing abandonment rates at digital checkout.
- EU AI Act documentation mandates:Automated decision-making systems in European financial institutions must maintain algorithmic audit trails, creating procurement pull for explainable AI tooling.
Market Restraints
- GPU compute cost volatility:Training large transformer models for fraud detection requires sustained access to NVIDIA H100 clusters, with spot pricing fluctuations compressing vendor margins.
- Training data concentration:High-quality labeled fraud datasets remain concentrated among tier-one card networks, creating moats that disadvantage mid-tier bank technology procurement.
- Cross-border regulatory friction:Divergence between U.S. sectoral guidance and EU horizontal AI regulation forces dual compliance architectures, raising platform development costs.
Strategic Opportunities
- India's UPI expansion:The Unified Payments Interface processes billions of monthly transactions with minimal fraud infrastructure, creating whitespace for real-time scoring vendors.
- Embedded finance convergence:Non-bank platforms integrating lending and payments lack native risk capabilities, opening channel partnerships for fraud-as-a-service providers.
- GDPR Article 22 remediation:European institutions facing automated decision-making restrictions are procuring human-in-the-loop override systems as compliance-mandated add-ons.
Industry Challenges
- MLOps talent scarcity:Productionizing fraud models requires engineers fluent in both financial risk semantics and Kubernetes orchestration, a skill intersection with limited supply.
- Legacy core integration:Mainframe-based transaction processing systems at established banks resist API-native fraud orchestration, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Fraud Management Market |
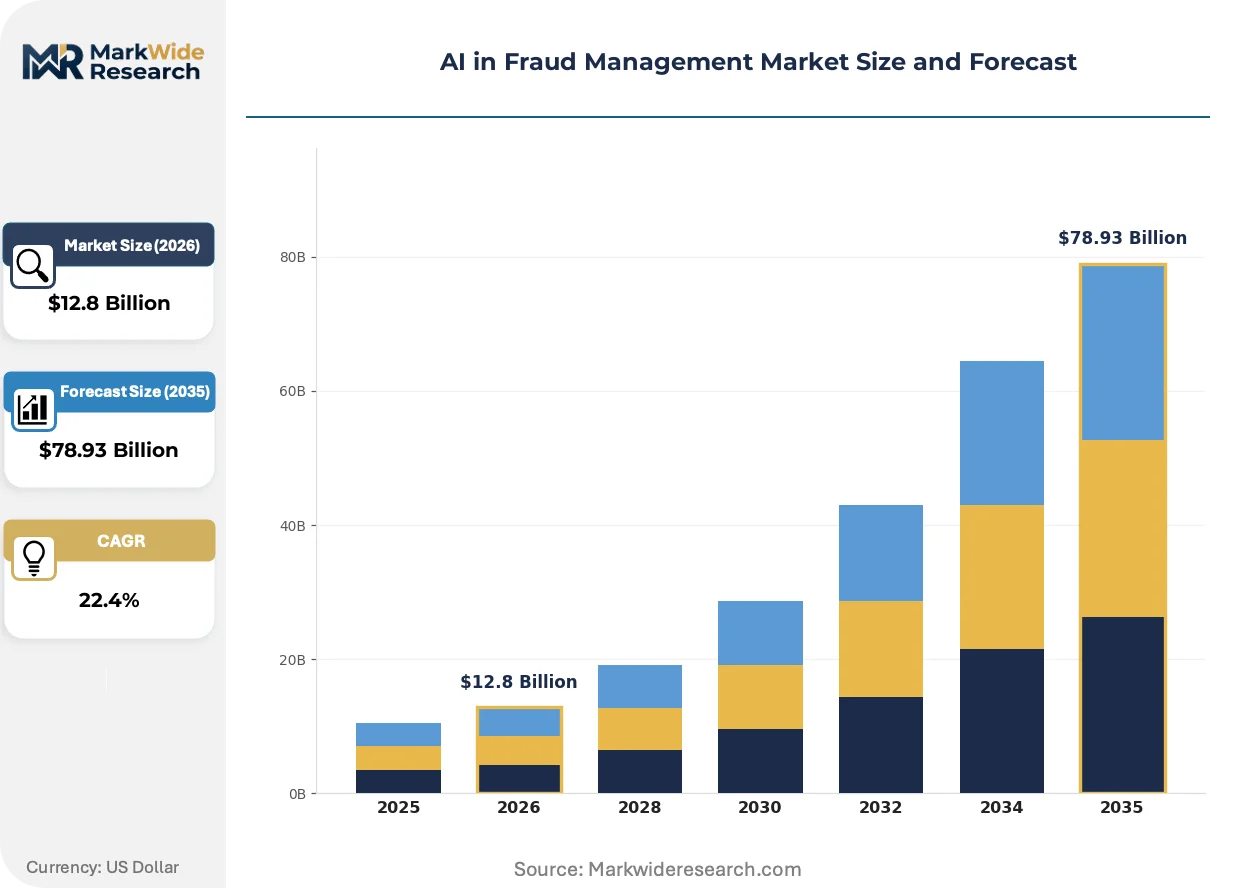
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $78.93 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Neural Networks Application: Payment Fraud Detection, Identity Theft Protection, Transaction Monitoring, Risk Assessment End User: BFSI, E-Commerce, Telecommunications, Insurance Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | IBM Corporation, SAS Institute Inc., Hewlett Packard Enterprise, BAE Systems plc, Capgemini SE, Cognizant Technology Solutions, Temenos AG, FICO, Splunk Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Fraud Management Market Strategic Shifts
Generative adversarial techniques are now weaponized by attackers to synthesize synthetic identities at scale, forcing defensive AI systems to evolve from pattern-matching to predictive behavioral simulation. This offensive-defensive arms race is compressing model retraining cycles and expanding the addressable market for autonomous security operations.
Graph neural networks are integrating device fingerprinting, transaction velocity, and social network topology into unified risk scores. Tier-one issuers in the United States are deploying these architectures for authorized push payment fraud prevention. The technology is integrating previously siloed data streams into single inference pipelines, collapsing the vendor stack for behavioral analytics.
The EU AI Act's risk-classification framework for biometric identification systems is forcing European banks to segregate high-risk algorithmic decisions from standard transaction scoring. Institutions must maintain human review protocols for flagged edge cases. French and German regulators are interpreting these provisions most strictly, creating compliance complexity for cross-border payment processors.
Merchant acquirers are unbundling fraud protection from core processing contracts, enabling competitive shopping for specialized scoring engines. Mid-market e-commerce platforms in the United Kingdom and Australia are driving this shift, procuring point solutions rather than bundled stacks. This purchasing pattern fragmentation is elevating vendors with narrow but deep model performance over generalist platforms.
AI in Fraud Management Market Segmentation
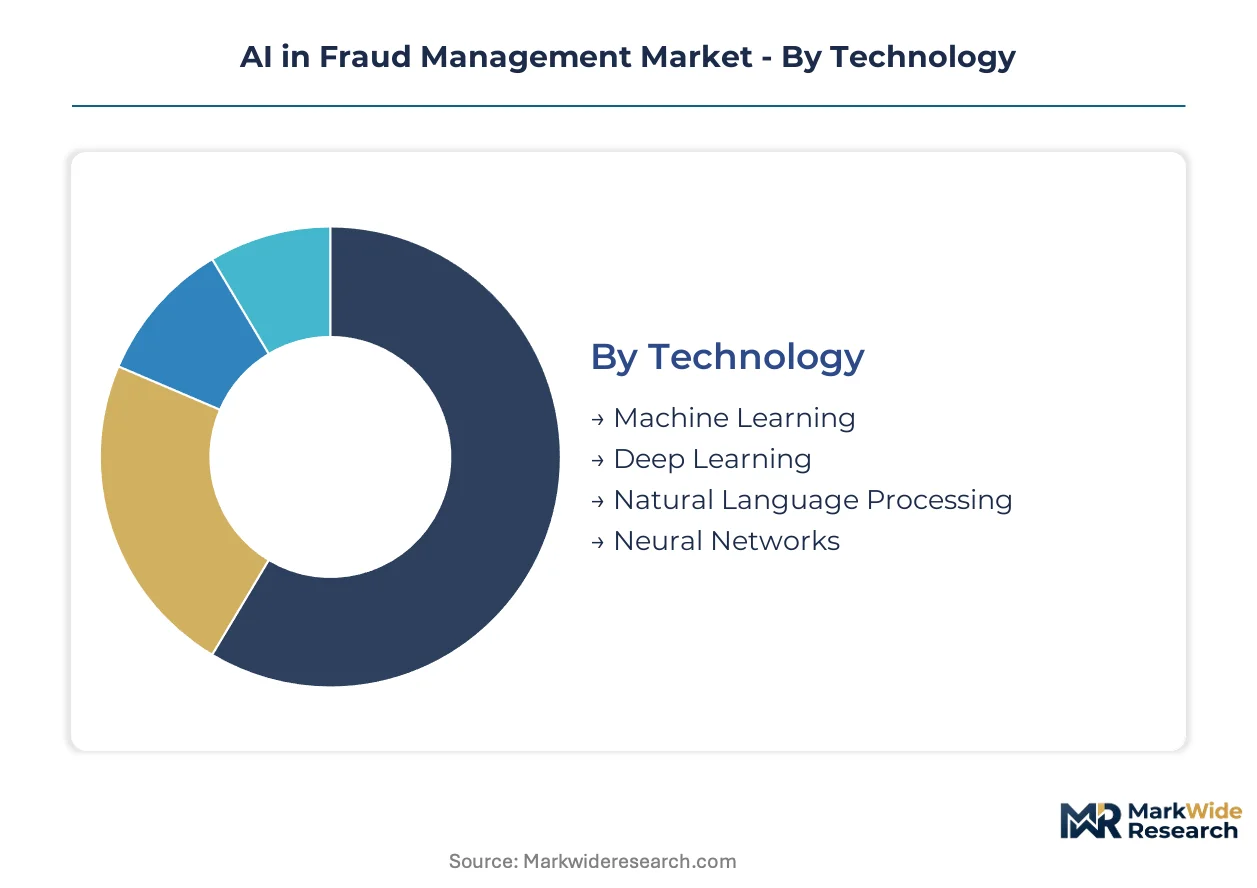
Technology selection in AI fraud management determines inference latency, model retraining frequency, and regulatory auditability. Deployment mode choices cascade into infrastructure cost structures and cross-border data residency compliance obligations.
Technology:
Architectural sophistication separates batch-trained classifiers from streaming adaptive systems that evolve with attack patterns.
- Machine Learning:Supervised and unsupervised algorithms process transactional velocity, device fingerprints, and historical chargeback patterns to flag anomalies. Demand concentrates among tier-one card issuers in the United States seeking to reduce false-positive rates below 2% while maintaining sub-100-millisecond decision windows.
- Deep Learning:Multi-layer neural architectures detect synthetic identity fraud through latent feature extraction across disparate data streams. European banks facing EU AI Act documentation mandates are procuring these systems for their inherent audit trail capabilities in automated decision-making.
- Natural Language Processing:Engines parse customer communication patterns, email headers, and chat transcripts to identify social engineering precursors.
- Neural Networks:Ensemble architectures combine recurrent and convolutional layers for behavioral biometric authentication.
Mature deployment sits with Machine Learning. Newer deployment is concentrated in Deep Learning.
Application:
Use-case specificity drives model architecture choices and integration complexity with legacy transaction processing systems.
- Payment Fraud Detection:Real-time scoring engines intercept authorized push payment fraud before settlement finality in instant payment rails. The Federal Reserve's FedNow infrastructure in the United States is accelerating procurement for sub-100-millisecond inference requirements.
- Identity Theft Protection:Synthetic identity detection combines document verification, biometric matching, and behavioral history analysis. Indian banks expanding digital onboarding face acute pressure from UPI transaction growth without proportional fraud infrastructure investment.
- Transaction Monitoring:Continuous surveillance of account activity generates suspicious activity reports for regulatory filing.
- Risk Assessment:Pre-transaction scoring evaluates merchant credibility and customer creditworthiness.
Established volume concentrates in Payment Fraud Detection. Steepest expansion trajectory is visible in Identity Theft Protection.
End User:
Industry verticals exhibit divergent fraud vector profiles and regulatory exposure levels.
- BFSI:Banks, payment processors, and insurers deploy enterprise-scale orchestration platforms integrating multiple detection modalities. Compliance obligations from the SEC, FFIEC, and EU AI Act force continuous model risk management investment.
- E-Commerce:Merchant platforms prioritize checkout friction reduction while maintaining chargeback rate ceilings. United Kingdom and Australian mid-market retailers are unbundling fraud protection from core processing contracts to shop for specialized scoring engines.
- Telecommunications:Mobile network operators detect SIM swap attacks and subscription fraud through device fingerprinting.
- Insurance:Carriers apply predictive models to claims verification and policy application screening.
Legacy investment depth sits with BFSI. Emerging procurement intensity clusters in E-Commerce.
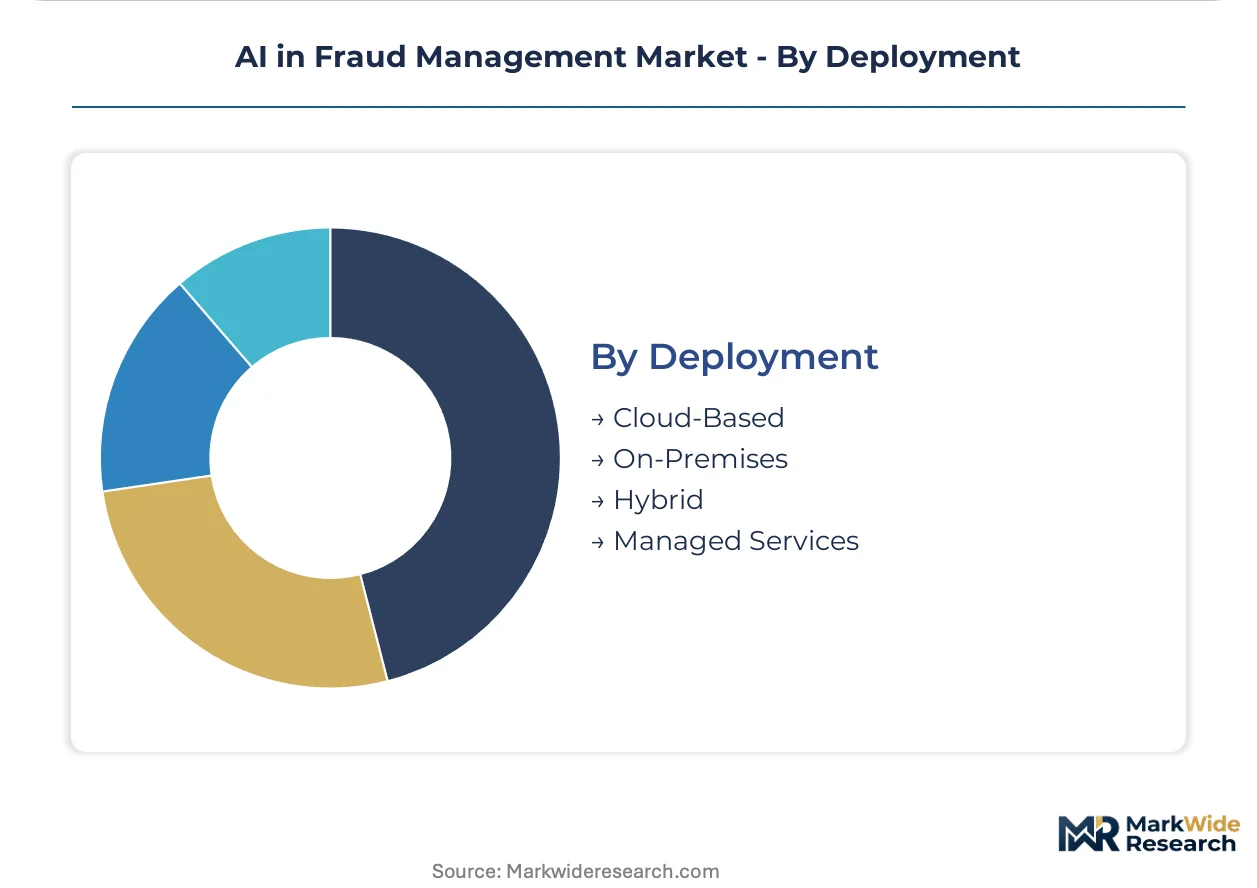
Deployment:
Infrastructure location choices reflect latency sensitivity, data sovereignty requirements, and operational control preferences.
- Cloud-Based:Elastic compute resources enable burst capacity for model training and edge-proximate inference deployment. Latency-sensitive scoring is migrating to distributed infrastructure as real-time payment windows compress.
- On-Premises:Captive data centers preserve operational control for institutions with stringent data residency mandates. French and German regulators interpret EU AI Act biometric provisions most strictly, reinforcing local infrastructure preferences.
- Hybrid:Split architectures route standard transactions to cloud inference while reserving sensitive decisions for on-premises processing.
- Managed Services:Third-party operation of fraud infrastructure reduces MLOps talent requirements for mid-tier institutions.
Installed base concentration remains in On-Premises. Cloud-Based deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in the United States currently concentrate procurement for real-time fraud prevention infrastructure, though regulatory divergence between Washington and Brussels is fragmenting platform architectures across jurisdictions.
United States
The Federal Reserve's FedNow instant payment rail mandates sub-100-millisecond fraud screening, compelling banks to migrate from batch overnight scoring to streaming analytics pipelines. SEC and FFIEC model risk management guidance enforces continuous documentation of algorithmic decision systems. New York and San Francisco anchor the vendor ecosystem, where tier-one issuers deploy graph neural networks for authorized push payment prevention.
Germany
BaFin and the KBA interpret EU AI Act biometric provisions with particular strictness, reinforcing on-premises infrastructure preferences among Frankfurt-based financial institutions. The country's national data protection regulator enforces GDPR Article 22 human-in-the-loop requirements for automated fraud decisions. Munich and Hamburg cluster specialist vendors serving cross-border payment processors navigating dual compliance architectures.
United Kingdom
Mid-market e-commerce platforms in London and Manchester are unbundling fraud protection from core processing contracts, creating procurement pull for specialized scoring engines. The Financial Conduct Authority's consumer duty rules elevate explainability requirements for algorithmic credit and fraud systems. The Southeast England corridor concentrates fintechs procuring behavioral biometric authentication without checkout friction.
India
The Unified Payments Interface processes billions of monthly transactions with minimal native fraud infrastructure, opening whitespace for real-time scoring vendors. The Reserve Bank of India's digital payment security guidelines mandate transaction monitoring upgrades for banks and non-bank payment companies. Mumbai and Bangalore anchor domestic technology procurement as financial institutions expand digital onboarding capabilities.
Australia
Mid-market retailers in Sydney and Melbourne are driving competitive shopping for point-solution fraud engines rather than bundled processor stacks. The country's prudential regulator enforces escalating expectations for operational resilience in payment systems. The southeastern corridor concentrates merchant acquirer unbundling activity, elevating vendors with narrow but deep model performance.
AI in Fraud Management Market Competitive Environment
United States producers anchor one tier of enterprise-scale orchestration platforms; European specialists hold differentiated positions in explainable AI tooling and regulatory compliance modules. The vendor base stratifies across three tiers: tier-one banks procuring integrated suites, mid-tier institutions selecting modular point solutions, and fintechs consuming fraud-as-a-service APIs. Dominant competitive moves include M&A activity consolidating behavioral analytics capabilities and strategic partnerships embedding scoring engines into cloud payment infrastructure.
Within the enterprise-scale tier, IBM Corporation and SAS Institute Inc. occupy positions representing integrated platform archetypes, while FICO anchors the proprietary data consortium model. Hewlett Packard Enterprise exemplifies infrastructure-forward positioning, and Capgemini SE sits within the systems integration and managed services vector. Splunk Inc. represents the security operations convergence archetype, with BAE Systems plc occupying defense-adjacent positioning for critical financial infrastructure protection.
| Leading Market Players |
|---|
| IBM Corporation |
| SAS Institute Inc. |
| Hewlett Packard Enterprise |
| BAE Systems plc |
| Capgemini SE |
| Cognizant Technology Solutions |
| Temenos AG |
| FICO |
| Splunk Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in behavioral analytics have consolidated scoring engine vendors across the United States and United Kingdom, concentrating supply-side pricing power while compressing procurement leverage for mid-tier banks seeking modular fraud detection components.
Pricing Analysis
Volume concentrates in cloud-based SaaS subscriptions with tiered seat-based pricing, while margin accretion sits with on-premises perpetual licensing bundled with managed MLOps services. Pricing stratifies across enterprise orchestration platforms, departmental point solutions, and API-native fraud-as-a-service tiers, with differentiation anchored in model explainability certification and sub-100-millisecond latency guarantees. Cost compression in mid-market cloud tiers is intensifying because hyperscaler infrastructure commoditizes inference workloads. Regional banks exhibit highest price sensitivity; tier-one card issuers prioritize performance benchmarks over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA for GPU clusters training transformer architectures, constraining vendor capacity expansion. Hardware supply concentrates in Taiwan, South Korea, and the United States; labeled training data feeds from tier-one card networks in North America and European banking consortia. Software supply draws from Israel, the United Kingdom, and India for specialist behavioral biometric engineering. Tariff exposure on semiconductor equipment imports threatens margin stability for on-premises infrastructure vendors. Distribution runs through direct enterprise sales teams, cloud marketplace listings, and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU cluster availability and MLOps engineering talent scarcity prop pricing power for vendors controlling training infrastructure, constraining buyer negotiation leverage across the forecast horizon.
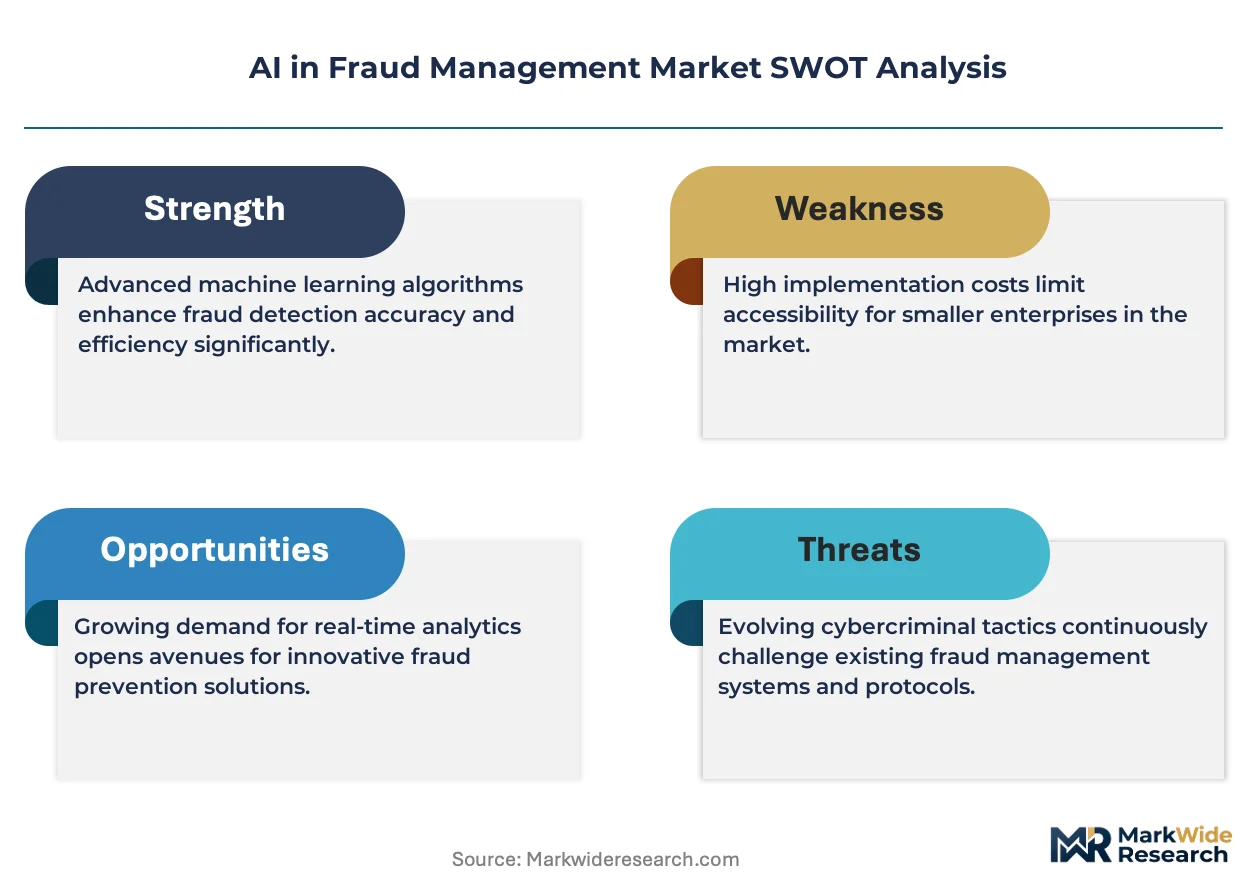
For Market Incumbents: Deepen vertical integration into edge-compute inference hardware to reduce hyperscaler dependency and defend margin position against cloud-native entrants. Consolidate behavioral biometric specialists before regulatory documentation mandates in Europe and the United States harden procurement requirements. Priority investment sits with explainable AI tooling satisfying EU AI Act audit trail obligations.
For New Entrants and Emerging Players: Mid-tier banks in India and Southeast Asia lacking native fraud infrastructure represent the most penetrable buyer archetype. White-space opportunity clusters in real-time scoring for UPI transaction volumes and embedded finance platforms integrating lending without risk capabilities. Go-to-market execution should anchor on API-first deployment with usage-based pricing eliminating upfront capital burden.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialist vendors with EU AI Act compliance modules in Germany and France facing valuation compression from dual-architecture cost burdens. Long-term viability favors behavioral analytics platforms with proprietary device fingerprinting datasets and recurring revenue concentration above seventy percent. Watch FedNow transaction velocity growth as inflection indicator for real-time scoring demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Behavioral Biometric Firms | Consolidates device fingerprinting capabilities required for FedNow compliance and EU AI Act documentation mandates. |
| Strategic Partnership with Hyperscaler Cloud Infrastructure | Secures burst GPU capacity for model training while distributing inference latency across edge-proximate zones. |
| Product Launch of Explainable AI Tooling Suite | Addresses BaFin and KBA strict interpretation of automated decision-making audit requirements in German markets. |
| Platform Integration with Core Banking Systems | Reduces deployment friction against mainframe-based transaction processing at established United States institutions. |
| Geographic Expansion into Indian UPI Ecosystem | Captures whitespace in real-time scoring for billions of monthly transactions lacking proportional fraud infrastructure. |
Study Parameters
Document review covered SEC 10-K filings from fraud detection vendors, FFIEC examination guidance, EU AI Act regulatory texts, and FedNow technical specifications, complemented by interviews with chief risk officers at tier-one United States banks, MLOps engineering leads at cloud-native fintechs, procurement directors at European payment processors, and regulatory compliance specialists at German BaFin-supervised institutions. Secondary validation drew from FFIEC call reports, ECB statistical data releases, and Reserve Bank of India payment system disclosures. Bottom-up transaction volume modeling and top-down market sizing triangulated segment-level estimates.
Segmentation outputs across technology type, deployment mode, application use case, and end-user vertical informed volume projections throughout the forecast period. CAGRs derived from regression analysis against real-time payment infrastructure deployment timelines and regulatory compliance spending patterns. Industry-specific inputs included FedNow transaction adoption curves, EU AI Act implementation phase deadlines, and UPI monthly volume growth trajectories.
Revisions become necessary when semiconductor export controls tighten, GPU spot pricing volatility exceeds historical bands, or major jurisdictions diverge further on algorithmic decision-making standards. Forecasts reflect documented assumptions about infrastructure deployment cadence and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Operations Advisory Service Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Loan Compliance Management Software Market
Risk Management and Compliance
Oil and Gas Risk Management Market
Risk Management and Compliance
NPL Management Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Financial Services Security Software Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Global Risk Management Software Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Crypto Compliance Software Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market