
 Loan Compliance Management Software Market | 2026-2036
Loan Compliance Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Loan Compliance Management Software Market Analysis
Enterprise-grade compliance automation is rotating toward real-time risk monitoring and API-first architectures. Temenos leverages its core banking integration depth to embed compliance workflows natively. Finastra anchors its position through open-platform connectivity across lending ecosystems. Sopra Banking Software specializes in modular compliance layers for tier-one and tier-two institutions.
Loan compliance management software orchestrates regulatory adherence across origination, servicing, and portfolio monitoring through automated policy engines, audit trails, and exception-based reporting. The system ingests multi-jurisdictional rule sets, applies dynamic scoring models, and generates regulator-ready documentation. Cloud-based deployment now leads technology adoption as banks pursue elastic infrastructure and faster patch cycles for evolving rules. Regulatory compliance commands the largest compliance-type share given mandatory reporting obligations to bodies such as the Federal Reserve and the European Banking Authority. Mortgage companies represent the fastest-growing end-user segment as non-bank lenders face intensified Consumer Financial Protection Bureau scrutiny.
The Federal Reserve, the Consumer Financial Protection Bureau, and the European Banking Authority collectively shape product roadmaps through stress-testing mandates, fair-lending examinations, and capital-adequacy frameworks. Software vendors must architect for concurrent multi-regulator reporting or face exclusion from institutional procurement shortlists. Stakeholders should monitor divergence between US prudential standards and EU sustainable-finance disclosure requirements as a source of product complexity and competitive differentiation.
Market Dynamics
Cloud-native architectures are displacing legacy on-premises compliance stacks as commercial banks pursue elastic infrastructure for real-time regulatory reporting. This migration compresses patch cycles from quarterly to continuous deployment models.
Growth Catalysts
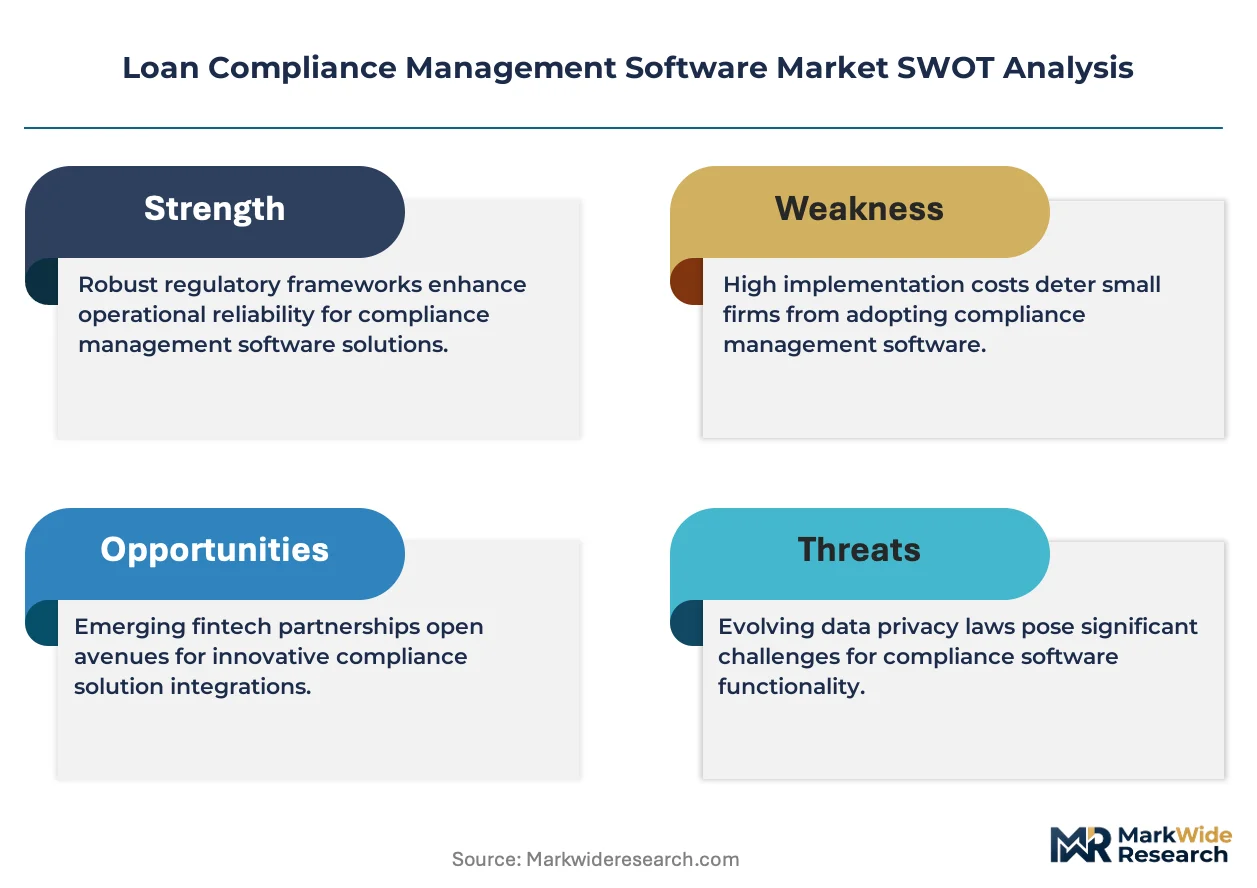
- Basel III capital requirements:Tightened prudential standards in North America force banks to automate risk-weighted asset calculations and stress-testing workflows.
- Non-bank mortgage lenders:Consumer Financial Protection Bureau scrutiny intensifies compliance automation demand among shadow banking entrants lacking legacy infrastructure.
- API-first integration:Open banking mandates enable real-time data exchange between compliance engines and core banking platforms.
Market Restraints
- Multi-jurisdictional rule fragmentation:Concurrent Federal Reserve, European Banking Authority, and national regulator reporting requirements inflate implementation complexity.
- Cloud concentration risk:Hyperscaler dependency creates single-point-of-failure exposure for critical compliance infrastructure.
- Legacy system entanglement:Decades-old COBOL-based loan servicing platforms resist API retrofitting without multimillion-dollar replacement.
Strategic Opportunities
- Sustainable-finance disclosure gaps:EU Green Deal taxonomy requirements create product differentiation potential for ESG-integrated compliance modules.
- Embedded compliance for fintechs:Banking-as-a-Service providers need lightweight, modular policy engines without enterprise overhead.
- Real-time exception monitoring:Machine learning anomaly detection converges with streaming data architectures to enable preemptive regulatory intervention.
Industry Challenges
- Regulatory technologist scarcity:Talent pools combining computer science expertise with Basel, Dodd-Frank, and GDPR fluency remain shallow across financial centers.
- Audit trail standardization delays:ISO certification timelines for immutable logging architectures stretch implementation roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loan Compliance Management Software Market |
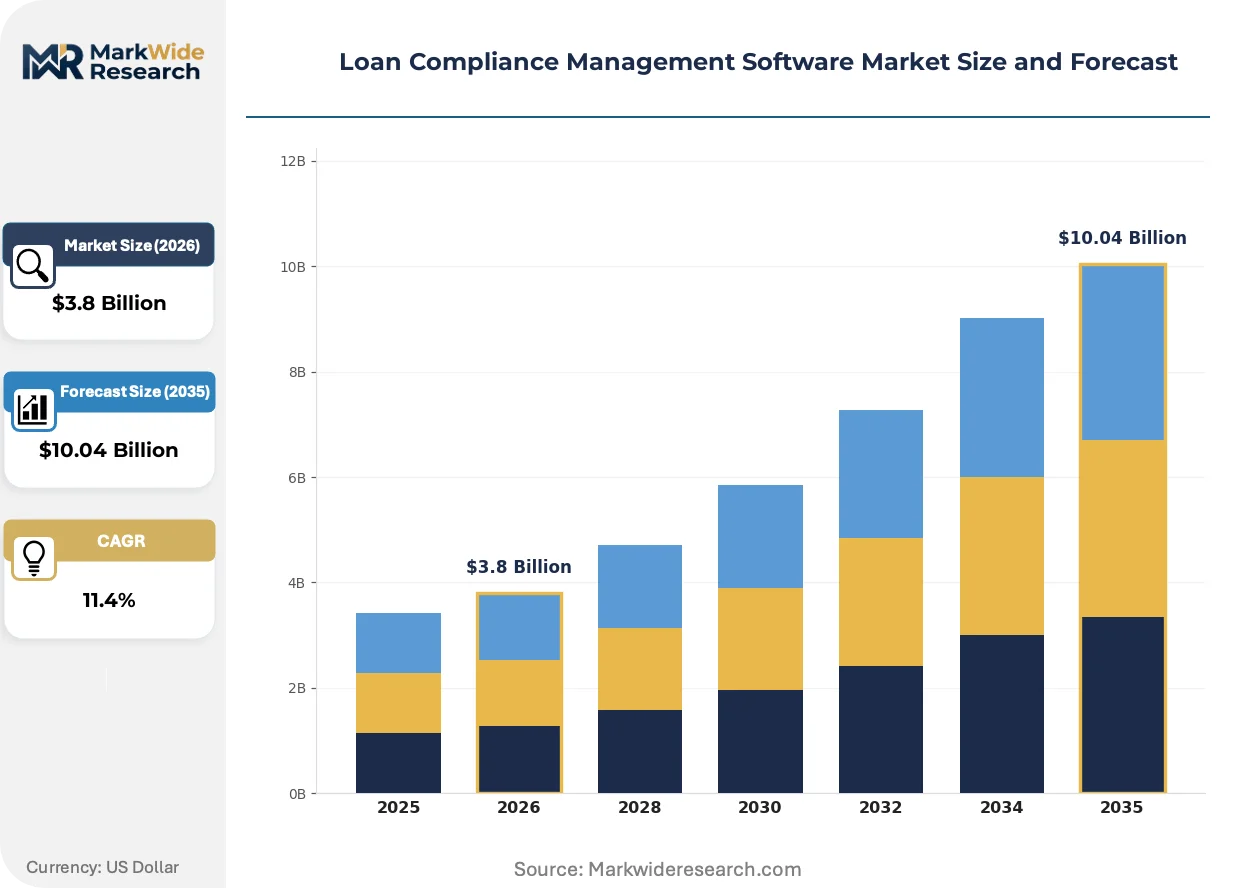
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, On-Premises, Hybrid, SaaS Deployment Model: Public Cloud, Private Cloud, Managed Services, Self-Hosted End User: Banks, Credit Unions, Mortgage Companies, Leasing Firms Compliance Type: Regulatory Compliance, Internal Compliance, Risk Compliance, Financial Compliance |
| Companies Covered | Temenos, TurnKey Lender, HES LoanBox, Sopra Banking Software, FICO, LoanPro, Finastra, Finlux, Mambu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loan Compliance Management Software Market Emerging Trajectories
Compliance technology is rotating from retrospective batch processing toward continuous monitoring architectures. This shift demands fundamental reengineering of data pipelines and policy engine design.
Real-time risk scoring is fragmenting the traditional compliance workflow into microservices-based components. Tier-one banks deploy containerized policy engines that ingest streaming loan data and trigger automated regulatory alerts. This architecture compresses exception detection from days to milliseconds while enabling horizontal scaling during peak reporting periods.
The European Banking Authority's digital operational resilience framework mandates granular incident reporting thresholds for critical loan servicing functions. Financial institutions must architect automated breach notification systems with sub-four-hour detection capabilities. German and French banks lead implementation, integrating these requirements into procurement specifications for new compliance platforms.
Mortgage servicers now unbundle compliance software from bundled core banking contracts, selecting best-of-breed modules through subscription pricing. This procurement pattern displaces decades-long single-vendor lock-in. United States non-bank lenders exhibit the most aggressive unbundling behavior, driving vendor specialization in fair-lending examination preparation tools.
Loan Compliance Management Software Market Segmentation
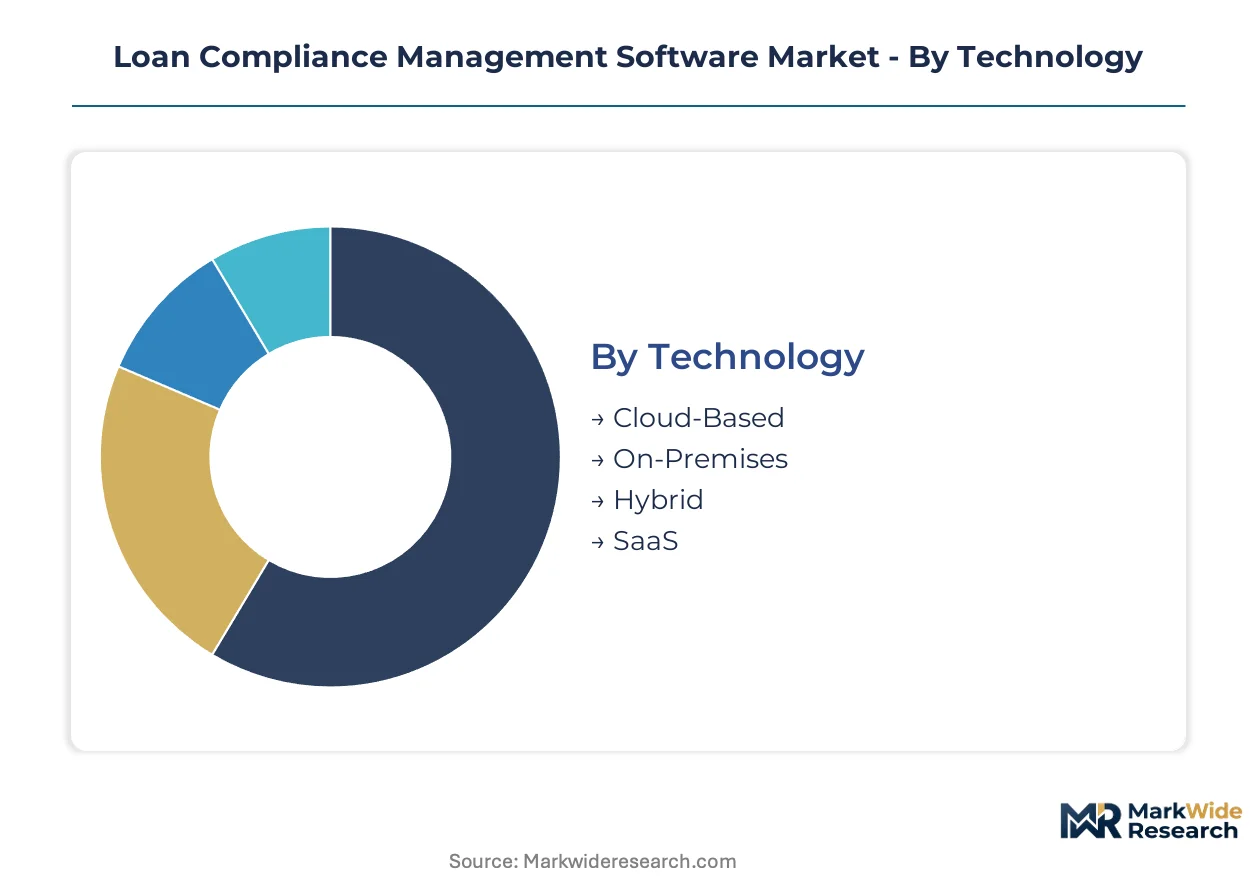
Loan compliance management software segments diverge sharply by infrastructure maturity and regulatory exposure. Technology choices determine patch velocity for evolving Basel III and Consumer Financial Protection Bureau mandates. End-user fragmentation between incumbent banks and non-bank mortgage lenders reshapes vendor pricing power.
Technology:
Cloud-native stacks face substitution pressure from hybrid architectures in institutions with sovereign data requirements. Banks weigh elastic scalability against residual latency sensitivity in core compliance calculations.
- Cloud-Based:Multi-tenant architectures enable continuous deployment of regulatory rule updates without on-site maintenance windows. United States commercial banks concentrate demand here as Federal Reserve stress-testing deadlines compress reporting cycles. The substitution threat from on-premises alternatives has collapsed outside defense and government lending entities.
- On-Premises:Air-gapped installations persist where national regulators mandate physical data residency for systemically important institutions. German Landesbanken and French mutual banks retain this stack for European Banking Authority capital-adequacy workflows. Maintenance burden and quarterly patch cycles expose users to compliance lag risk.
- Hybrid:Sensitive loan data remains on-site while analytics and reporting layers operate in cloud environments. Credit unions in the United Kingdom favor this model for Financial Conduct Authority audit trail requirements.
- SaaS:Subscription pricing with pre-configured regulatory templates lowers entry barriers for mid-tier mortgage originators. Non-bank lenders in the United States adopt this fastest to satisfy Consumer Financial Protection Bureau fair-lending examination protocols.
Cloud-Based retains volume leadership; SaaS holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates hyperscaler-dependent public deployments from captive infrastructure investments. Procurement patterns diverge by institution size and regulatory scrutiny intensity.
- Public Cloud:Shared infrastructure pools drive unit economics for regional banks with sub-$50 billion asset bases. United States institutions dominate adoption, leveraging Amazon Web Services and Microsoft Azure compliance-certified regions.
- Private Cloud:Single-tenant environments satisfy European Banking Authority digital operational resilience framework requirements for critical loan servicing functions. German and Dutch banks lead procurement.
- Managed Services:Vendor-operated infrastructure transfers operational risk while retaining regulatory accountability with the lending institution. United Kingdom building societies favor this model for limited internal IT capacity.
- Self-Hosted:Complete institutional control over hardware and software stacks persists in specialized leasing firms with bespoke collateral valuation workflows.
Public Cloud dominates transaction volume; Managed Services is climbing the fastest.
End User:
Customer type determines feature depth requirements and sales cycle duration. Mortgage companies exhibit the most acute compliance automation gap relative to legacy infrastructure investment.
- Banks:Tier-one institutions demand modular policy engines integrating with Temenos and Finastra core banking platforms. United States money center banks drive specification standards for real-time risk-weighted asset calculations.
- Credit Unions:Member-owned structures prioritize cost containment over feature breadth, favoring SaaS configurations with National Credit Union Administration pre-certification.
- Mortgage Companies:Non-bank originators lack legacy COBOL entanglements, enabling greenfield API-first compliance architectures. Consumer Financial Protection Bureau examination intensity accelerates procurement timelines here.
- Leasing Firms:Equipment and vehicle finance specialists require residual value risk modules alongside standard regulatory compliance layers.
Banks retain volume leadership; Mortgage Companies hold the steepest expansion curve.
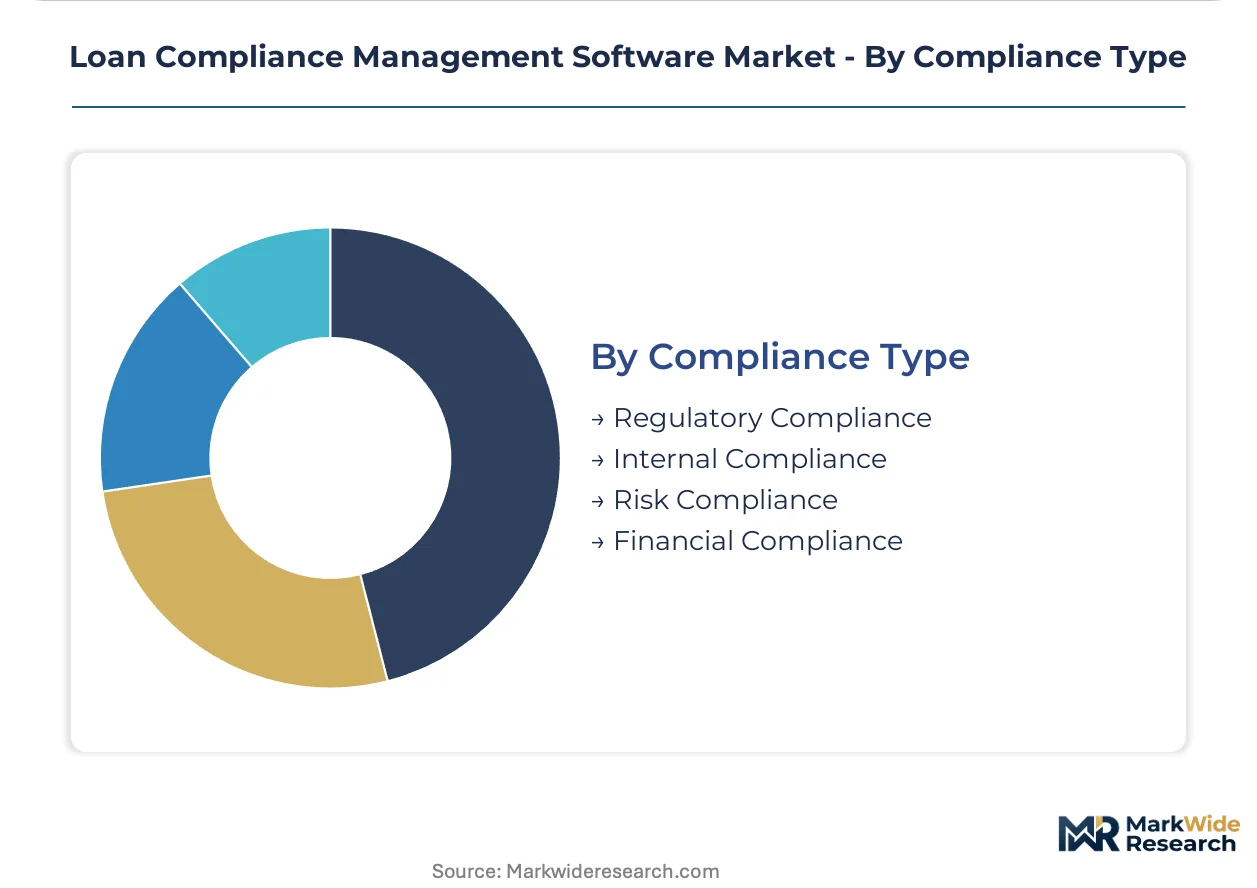
Compliance Type:
Maturity gradients separate mandatory external reporting from discretionary internal risk frameworks. Regulatory compliance commands non-negotiable budget allocation regardless of interest rate cycles.
- Regulatory Compliance:Automated generation of Federal Reserve, European Banking Authority, and national regulator documentation consumes the largest software module investment. Mandatory reporting obligations eliminate procurement discretion.
- Internal Compliance:Institution-specific policy enforcement beyond baseline regulatory requirements. Large United States banks deploy these layers for board-level risk appetite monitoring.
- Risk Compliance:Concentration limits, counterparty exposure tracking, and stress-testing scenario management. German banks integrate this tightly with Bundesbank reporting templates.
- Financial Compliance:Accounting standard alignment for loan loss provisioning and revenue recognition. United Kingdom institutions prioritize this for Financial Reporting Council coordination.
Regulatory Compliance retains volume leadership; Risk Compliance holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software export capacity from the United States and United Kingdom exceeds import dependency for compliance modules, while Germany maintains near-autonomous supply. Trade flows concentrate in transatlantic corridors serving Basel III and Consumer Financial Protection Bureau implementation demands.
United States
Commercial banks and non-bank mortgage lenders drive procurement velocity. Federal Reserve stress-testing mandates compress reporting cycles and elevate real-time automation requirements. New York and Chicago financial centers anchor deployment clusters for cloud-native compliance stacks.
Germany
Landesbanken and mutual banks sustain hybrid infrastructure investments amid European Banking Authority capital-adequacy pressures. Bundesbank reporting templates shape vendor product specifications. Frankfurt and Munich house the densest concentration of compliance technology procurement teams.
United Kingdom
Building societies and challenger banks favor managed services models with limited internal IT capacity. Financial Conduct Authority audit trail requirements sustain demand for hybrid deployment architectures. London dominates transaction volume while Edinburgh and Manchester emerge as secondary procurement hubs.
Japan
Mega-banks integrate compliance modules with core banking modernization programs. METI operational resilience guidelines influence system architecture decisions. Tokyo and Osaka financial districts concentrate vendor engagement activity for real-time risk monitoring solutions.
India
IT services exporters and domestic banks accelerate cloud migration for RBI regulatory reporting. Unified Payments Interface expansion creates compliance automation gaps for lending fintechs. Mumbai and Bangalore lead implementation scale among private sector banks.
Loan Compliance Management Software Market Vendor Landscape
Listed leaders compete with private specialists across platform integration depth. The vendor base stratifies into three tiers: core-anchored incumbents, modular specialists, and cloud-native challengers. Strategic archetypes include banking-platform extenders, compliance-point-solution vendors, and API-first infrastructure providers. Dominant competitive moves encompass M&A for regulatory technology talent and strategic partnerships for open-banking connectivity.
Within the core-anchored tier, Temenos and Finastra represent entrenched positions through native banking system integration. Sopra Banking Software exemplifies the modular specialist archetype with tier-one and tier-two institutional focus. Among cloud-native entrants, Mambu occupies a position serving Banking-as-a-Service providers with lightweight deployment models.
| Leading Market Players |
|---|
| Temenos |
| TurnKey Lender |
| HES LoanBox |
| Sopra Banking Software |
| FICO |
| LoanPro |
| Finastra |
| Finlux |
| Mambu |
| Others |
Supply Flow & Price Mechanics
Cloud-native infrastructure substitution for legacy on-premises stacks redraws supply geography toward hyperscaler regions while compressing pricing economics through continuous deployment models. This displacement simultaneously concentrates vendor development resources in United States and Western European cloud corridors and collapses maintenance-window premiums that once anchored on-premises pricing tiers.
Pricing Analysis
Tier-one commercial banks anchor subscription-based SaaS pricing stratified across enterprise, mid-market, and entry-level tiers. Price differentiation rests on API integration depth and real-time reporting certification level. Pricing pressure stems from non-bank mortgage lenders demanding lightweight modular configurations without enterprise overhead. Credit unions exhibit acute price sensitivity; money center banks prioritize compliance latency over cost.
Supply Chain Analysis
Container availability constraints on transatlantic trade lanes inflate implementation timelines for European Banking Authority-mandated infrastructure. Software development concentrates in the United States, the United Kingdom, and Germany. Cloud compute and regulatory content feeds from these jurisdictions. Single-source vulnerability attaches to hyperscaler concentration for critical compliance infrastructure. Distribution runs through direct enterprise sales with managed service overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loan compliance management software functions as a service-attach market where recurring regulatory content updates and managed compliance monitoring expand faster than base platform licensing. This recurring layer now commands disproportionate vendor investment and customer lifetime value.
For Market Incumbents: Consolidate through targeted acquisition of API-first regulatory technology specialists to neutralize cloud-native challengers. Deepen backward integration into real-time data streaming infrastructure to lock in latency advantages for Federal Reserve stress-testing workflows. Capacity expansion in Frankfurt and London cloud regions secures European Banking Authority digital operational resilience positioning. For New Entrants and Emerging Players: Anchor in the Banking-as-a-Service provider segment where embedded compliance modules lack incumbent saturation. The United States non-bank mortgage lender ecosystem offers the most penetrable white space given Consumer Financial Protection Bureau examination intensity and absence of legacy COBOL entanglement. A compliance-module-only go-to-market with pre-configured fair-lending templates accelerates procurement velocity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors modular specialists with tier-one referenceability and open-platform architecture. Long-term viability hinges on concurrent multi-regulator reporting capability spanning Federal Reserve, European Banking Authority, and national frameworks. The signal to watch is procurement specification divergence between US prudential standards and EU sustainable-finance disclosure requirements as competitive differentiation catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Regulatory Technology Specialist | Absorbs scarce Basel III and Dodd-Frank technical talent into platform engineering. |
| API-First Platform Integration | Embeds compliance engines directly into Temenos and Finastra core banking ecosystems. |
| Geographic Expansion in Cloud Regions | Positions real-time infrastructure adjacent to European Banking Authority jurisdictional requirements. |
| Strategic Partnership with Hyperscaler | Secures compliance-certified compute capacity for Federal Reserve stress-testing peak loads. |
| Product Launch in ESG-Integrated Module | Captures EU Green Deal taxonomy disclosure gaps ahead of regulatory mandate hardening. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, European Banking Authority regulatory guidance, and cloud infrastructure capex disclosures. Chief technology officers at commercial banks, compliance officers at non-bank mortgage lenders, and integration specialists at core banking platform vendors provided structured input. Bottom-up deployment model sizing triangulates against top-down regulatory mandate spend analysis.
Segmentation dimensions modeled span deployment architecture, institution size tier, compliance type, and geographic regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves calibrated to Basel III implementation deadlines and Consumer Financial Protection Bureau examination intensity. Forecast inputs incorporate cloud migration velocity at German Landesbanken and API unbundling patterns among United States mortgage servicers.
Material uncertainties — regulatory rule fragmentation, hyperscaler service continuity events, and legacy system replacement cycle delays — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Asset Liability Management (ALM) Solution Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Stress Testing Services Market