
 Europe Strategic Consulting Services Market | 2026-2036
Europe Strategic Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Strategic Consulting Services Market Foresight
The shift from single-source advisory relationships toward multi-source ecosystems is repositioning how European enterprises procure strategy expertise. Roland Berger leverages its deep industrial heritage to anchor complex manufacturing transformations across German and Austrian clients. McKinsey & Company sustains dominance in large-scale financial services restructuring through proprietary analytics platforms. Bain & Company differentiates via intensive private equity due diligence and portfolio value creation methodologies.
Strategic consulting services encompass structured advisory engagements that diagnose organizational performance, design competitive positioning frameworks, and implement operational improvement programs through data-driven analysis and change management protocols. These services deploy proprietary diagnostic tools, benchmark databases, and specialized expertise to resolve board-level decisions on market entry, M&A targeting, cost restructuring, and digital operating models. Management consulting and strategy consulting command the deepest margin pools due to recurring C-suite access and premium pricing for transformation mandates, while IT consulting segments expand fastest as cloud migration and cybersecurity imperatives reshape European enterprise architectures. The engagement model dimension reveals project-based structures still dominate revenue volume, though retainer arrangements gain traction among corporates seeking continuous geopolitical and regulatory scenario planning.
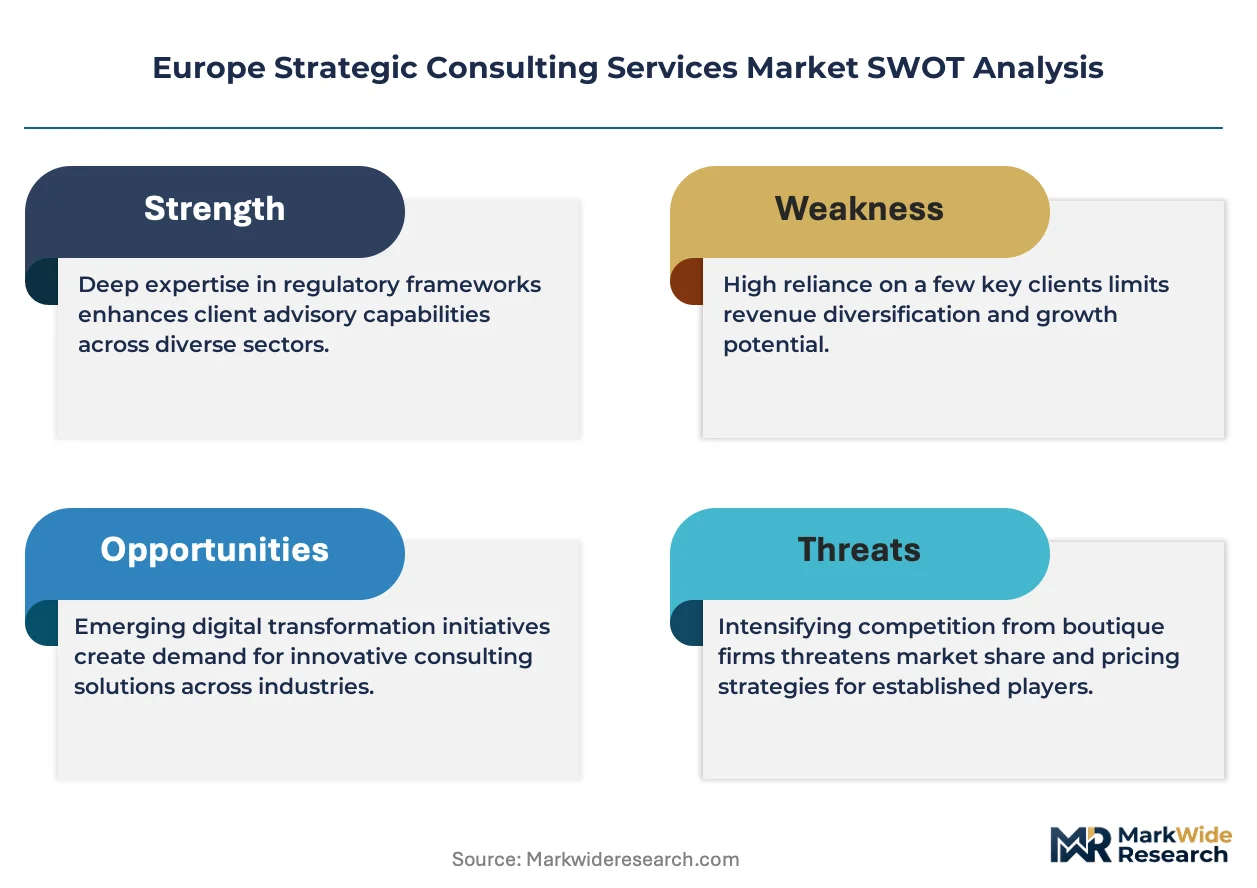
The EU AI Act and CSRD framework impose new governance and disclosure obligations that directly expand demand for compliance-oriented strategy advisory across European headquartered firms. EMA pharmaceutical regulations and ECB climate stress-testing protocols further segment consulting specialization, with firms building dedicated practices around regulatory interpretation and implementation. Stakeholders must monitor how the EU Green Deal's evolving taxonomy criteria and national transposition timelines reshape the competitive boundary between generalist strategy houses and vertically specialized regulatory advisory boutiques.
Market Dynamics
CSRD disclosure mandates and EU AI Act compliance deadlines are compressing procurement cycles for external strategy advisory, forcing European enterprises to embed continuous regulatory monitoring into retained consulting relationships rather than episodic project engagements.
Growth Catalysts
- EU Green Deal taxonomy alignment:Industrial conglomerates in Germany and France require specialist advisory to map operations against evolving sustainability criteria and secure transition financing eligibility.
- ECB climate stress-testing protocols:Financial services institutions across the Eurozone seek scenario modeling expertise to satisfy supervisory expectations and disclose portfolio climate risks.
- Cloud-native operating models:Mittelstand manufacturers are accelerating ERP modernization programs that demand concurrent business process redesign and change management support.
Market Restraints
- Talent scarcity in quantitative sustainability analytics:Specialized skillsets combining climate science, financial modeling, and regulatory interpretation command premium compensation that inflates engagement costs.
- Concentration of deep industrial expertise:Düsseldorf, Munich, and Vienna host disproportionate shares of senior partners capable of navigating complex manufacturing transformations, creating geographic supply bottlenecks.
- Substitution by captive strategy functions:Large European corporates including Siemens and Schneider Electric have built internal strategy units that absorb routine advisory work previously outsourced.
Strategic Opportunities
- Poland and Czechia manufacturing advisory:Automotive and electronics supply chain relocation from Asia is generating demand for greenfield operational design and workforce transition consulting.
- EU AI Act implementation services:High-risk AI system classification, conformity assessment, and governance framework design represent nascent advisory white space with limited incumbent specialization.
- Retainer-based regulatory intelligence:Continuous CSRD and taxonomy monitoring subscriptions offer recurring revenue models that reduce project-based revenue volatility.
Industry Challenges
- Partner-level capacity constraints:Senior practitioners capable of C-suite relationship management and complex diagnostic delivery are concentrated at top-tier firms, limiting scale-out of premium engagements.
- Client-side data readiness gaps:ESG reporting and AI governance advisory requires structured internal data that many European mid-caps lack, extending project timelines and compressing margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Strategic Consulting Services Market |
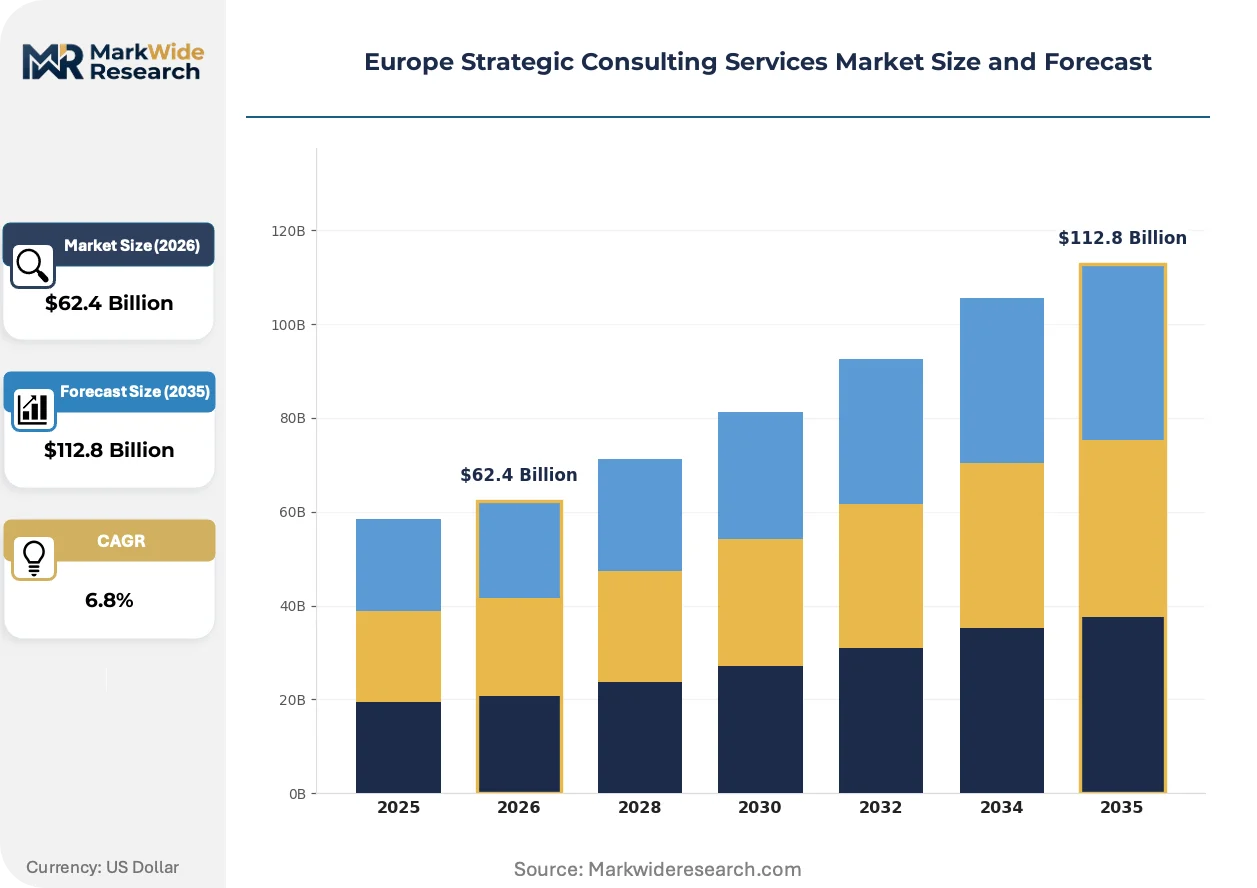
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Management Consulting, IT Consulting, Human Resources Consulting, Strategy Consulting Client Type: Corporates, Small and Medium Enterprises, Startups, Nonprofits Engagement Model: Project-Based, Retainer-Based, Time & Material, Consulting Agreements Industry Vertical: Financial Services, Healthcare, Manufacturing, Technology |
| Companies Covered | Roland Berger, Kearney, McKinsey & Company, Simon-Kucher & Partners, OC&C Strategy Consultants, Boston Consulting Group, Oliver Wyman, Strategy&, Bain & Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Strategic Consulting Services Market Shifts & Advancements
Advisory delivery models are fragmenting as generative tools and specialized boutiques compress the value capture of traditional generalist frameworks, while regulatory complexity deepens the premium for vertically integrated expertise.
Generative AI diagnostic engines are decentralizing the analytical layer of strategy engagements. Mid-tier consultancies in Amsterdam and Stockholm deploy large language models to automate market sizing and competitive benchmarking tasks previously requiring junior analyst teams. German automotive suppliers now expect real-time scenario modeling capabilities that compress traditional eight-week diagnostic phases into continuous data feeds.
CSRD phased implementation timelines are restructuring advisory demand curves. The European Commission's staggered disclosure deadlines for listed versus non-listed firms create predictable waves of compliance-driven procurement that specialist regulatory boutiques exploit through preemptive methodology development. French asset managers and Dutch pension funds face the earliest materiality assessment deadlines, driving concentrated advisory procurement in Paris and Rotterdam through 2025.
Multi-source procurement patterns are displacing sole-source advisory relationships among European corporates. Bayer and AstraZeneca-style vendor diversification strategies now extend to strategy advisory, with procurement teams segmenting engagements between tier-one firms for board-level credibility and specialized boutiques for technical depth. This fragmentation is most advanced in London and Frankfurt financial services, where chief strategy officers maintain active rosters of five to seven advisory relationships.
Europe Strategic Consulting Services Market Segmentation
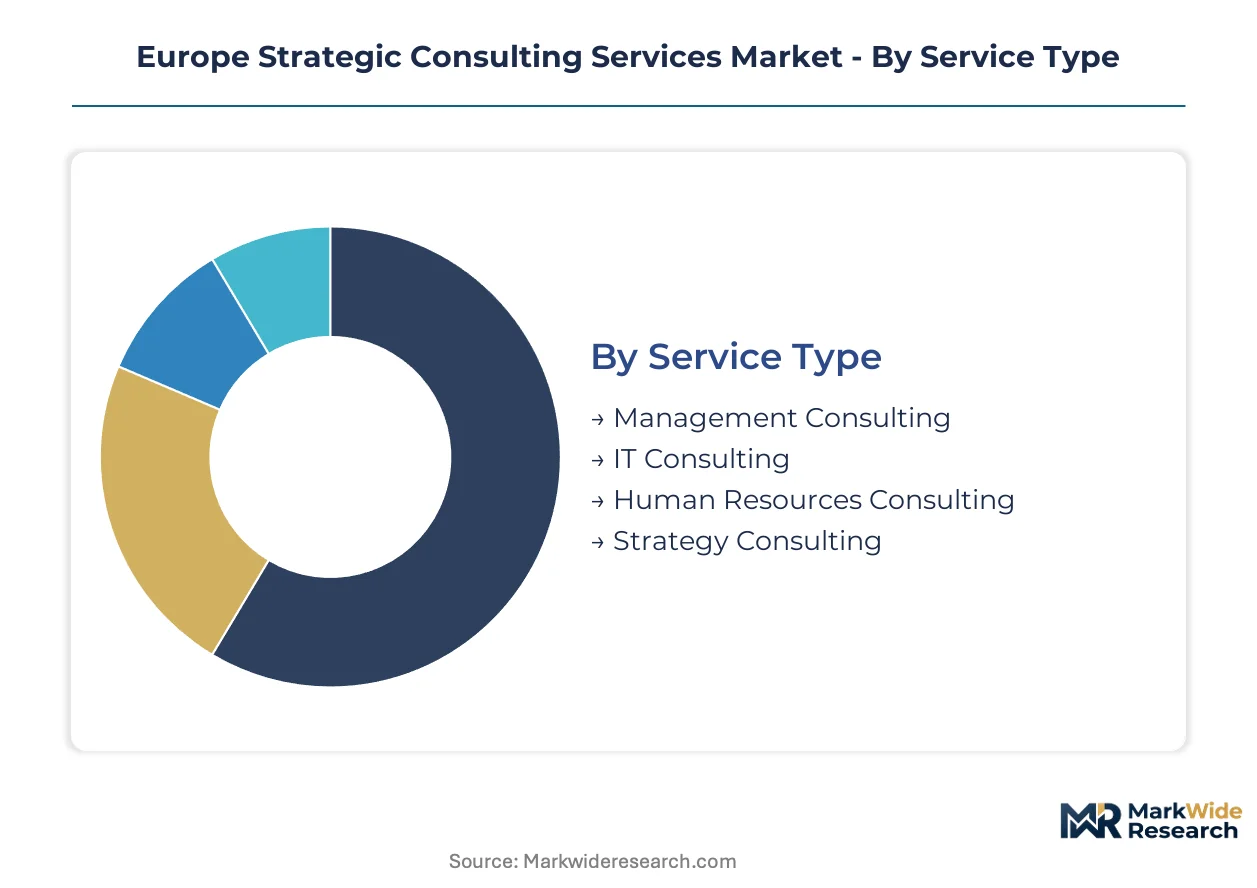
Strategic consulting services in Europe fragment across four distinct dimensions that shape how advisory firms structure their capabilities and pricing. Service type and client type classifications determine margin architecture, while engagement models and industry verticals dictate delivery protocols and partner staffing ratios.
Service Type:
Advisory buyers differentiate primarily by the depth of C-suite access required and the proprietary intellectual property embedded in deliverables.
- Management Consulting:Encompasses operational improvement, organizational design, and performance diagnostics delivered through structured change management protocols. German industrial conglomerates and French luxury houses sustain premium pricing for manufacturing footprint optimization and supply chain restructuring mandates.
- Strategy Consulting:Focuses on competitive positioning, market entry sequencing, and M&A target identification using proprietary benchmark databases and scenario modeling frameworks. Demand concentrates among private equity sponsors in London and Frankfurt seeking due diligence acceleration and portfolio value creation playbooks.
- IT Consulting:Addresses cloud migration architecture, ERP modernization, and cybersecurity governance for Mittelstand manufacturers accelerating digital operating model transitions. Project pipelines are expanding most quickly as CSRD data infrastructure requirements compound with legacy system replacement cycles.
- Human Resources Consulting:Covers workforce transition, executive compensation redesign, and talent analytics for organizations navigating EU AI Act compliance and green skill acquisition imperatives.
Volume sits with Management Consulting; growth tilts toward IT Consulting.
Client Type:
Procurement sophistication and budget scale separate advisory buyers more sharply than sector affiliation or ownership structure.
- Corporates:Multinational headquartered firms with dedicated procurement functions that negotiate multi-year framework agreements and demand real-time diagnostic dashboards. Bayer and AstraZeneca-style vendor diversification strategies now extend to strategy advisory, with active rosters of five to seven advisory relationships.
- Small and Medium Enterprises:Mittelstand manufacturers across Baden-Württemberg and Bavaria purchasing modular transformation packages through industry association referral networks. These buyers show the steepest expansion trajectory as EU Green Deal taxonomy alignment requirements penetrate mid-cap disclosure obligations.
- Startups:Venture-backed technology firms in Amsterdam and Stockholm procuring rapid market sizing and investor narrative development on compressed timelines.
- Nonprofits:European development banks and climate foundations seeking impact measurement frameworks and grant compliance advisory.
Revenue concentrates with Corporates; advisory firms are expanding most quickly into Small and Medium Enterprises.
Engagement Model:
Contract structure determines risk allocation between advisory firm and client, with implications for staffing continuity and knowledge retention.
- Project-Based:Fixed-scope engagements with defined deliverables, milestones, and acceptance criteria dominating revenue volume across German automotive and French pharmaceutical advisory procurement.
- Retainer-Based:Continuous access arrangements gaining traction among financial services institutions seeking regulatory scenario planning and CSRD monitoring subscriptions. Dutch pension funds and French asset managers facing earliest materiality assessment deadlines are driving concentrated adoption in Rotterdam and Paris.
- Time & Material:Hourly or daily rate structures for exploratory diagnostics and crisis-response mandates where scope uncertainty prevents fixed pricing.
- Consulting Agreements:Hybrid structures blending fixed fees for defined phases with success-based components tied to measurable outcome achievement.
Project-Based structures capture the largest share; Retainer-Based arrangements are climbing the fastest.
Industry Vertical:
Sector-specific regulatory complexity and capital intensity shape advisory specialization requirements and partner credentialing standards.
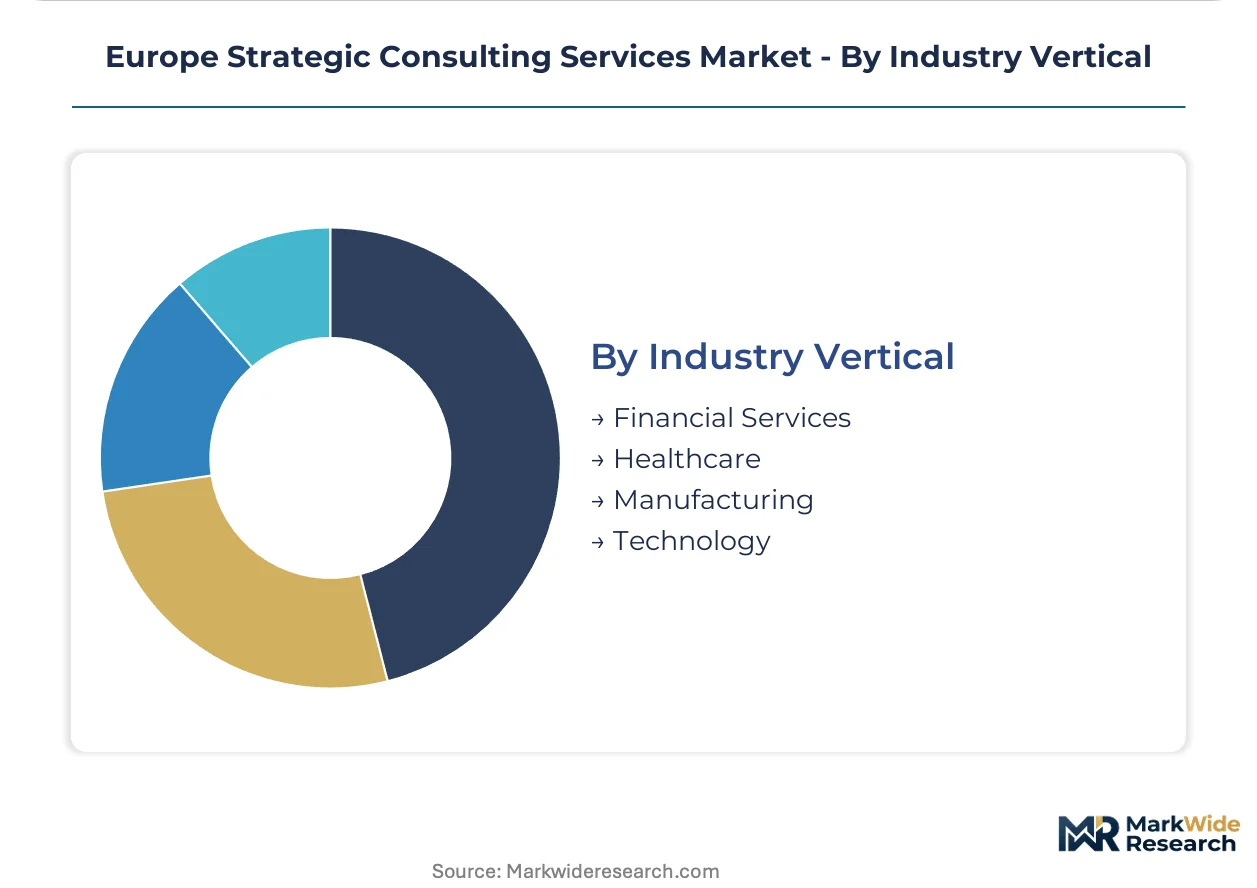
- Financial Services:ECB climate stress-testing protocols and CSRD disclosure mandates are compressing procurement cycles for scenario modeling and portfolio risk advisory. Eurozone banks and insurers represent the deepest margin pool due to recurring regulatory interpretation needs.
- Manufacturing:German industrial conglomerates and automotive suppliers drive premium engagements for greenfield operational design, workforce transition consulting, and EU Green Deal taxonomy alignment. Supply chain relocation from Asia into Poland and Czechia is generating fresh demand for manufacturing advisory.
- Healthcare:EMA pharmaceutical regulations and clinical trial digitalization requirements sustain specialized advisory practices around regulatory submission strategy and real-world evidence frameworks.
- Technology:EU AI Act implementation services including high-risk system classification, conformity assessment, and governance framework design represent nascent advisory white space with limited incumbent specialization.
Financial Services anchors revenue concentration; Technology verticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial expertise clusters in Germany's Rhine-Ruhr corridor supply the analytical talent that anchors European strategy advisory. This geographic concentration shapes how multinational firms procure transformation expertise across the continent.
Germany
ECB climate stress-testing protocols and CSRD disclosure mandates compress procurement cycles for financial services advisory in Frankfurt. The EU AI Act implementation deadlines accelerate demand for governance framework design among Düsseldorf-based industrial conglomerates. Bavarian Mittelstand manufacturers in Munich and Stuttgart drive premium engagements for ERP modernization and green taxonomy alignment.
United Kingdom
Private equity sponsors in London sustain deep demand for due diligence acceleration and portfolio value creation methodologies. The Financial Conduct Authority's evolving disclosure requirements prompt asset managers to seek continuous regulatory monitoring subscriptions. Canary Wharf and the City host concentrated advisory procurement for financial restructuring and scenario modeling mandates.
France
French asset managers face the earliest CSRD materiality assessment deadlines, driving concentrated advisory procurement in Paris through 2025. The Autorité des Marchés Financiers intensifies supervisory expectations for climate risk disclosure among institutional investors. Île-de-France luxury houses sustain premium pricing for supply chain restructuring and manufacturing footprint optimization.
Netherlands
Dutch pension funds in Rotterdam adopt retainer-based regulatory intelligence arrangements for continuous CSRD and taxonomy monitoring. The Dutch Authority for the Financial Markets implements ECB-aligned climate stress-testing protocols that expand scenario modeling advisory. Amsterdam's venture-backed technology firms procure rapid market sizing and investor narrative development on compressed timelines.
Poland
Automotive and electronics supply chain relocation from Asia generates demand for greenfield operational design in Warsaw and Kraków. EU Green Deal taxonomy alignment requirements penetrate mid-cap disclosure obligations among Polish manufacturers. Silesian industrial zones attract workforce transition consulting as production capacity expands.
Europe Strategic Consulting Services Market Competitive Landscape
Global majors compete with regional champions across advisory delivery models and regulatory specialization depth. The market structures around three tiers: full-service partnerships with board-level credibility, mid-tier firms deploying generative diagnostic tools, and regulatory boutiques exploiting preemptive methodology development. Strategic archetypes include heritage-rooted industrial specialists, analytics-driven financial services advisors, and AI governance pioneers. Competitive moves concentrate on retainer-based subscription expansion and multi-source procurement positioning.
Within the heritage industrial tier, Roland Berger anchors complex manufacturing transformations across German and Austrian client relationships. McKinsey & Company exemplifies the analytics-driven financial services archetype through proprietary platforms and large-scale restructuring mandates. Bain & Company occupies the private equity specialist position, intensive due diligence and portfolio value creation methodologies differentiating its advisory model.
| Leading Market Players |
|---|
| Roland Berger |
| Kearney |
| McKinsey & Company |
| Simon-Kucher & Partners |
| OC&C Strategy Consultants |
| Boston Consulting Group |
| Oliver Wyman |
| Strategy& |
| Bain & Company |
| Others |
Supply & Pricing Matrix
EU Green Deal taxonomy alignment gates both qualified advisory supply and premium-tier pricing access. Industrial conglomerates in Germany and France pay substantial premiums for partners credentialed in sustainability disclosure frameworks, while mid-tier consultancies without CSRD implementation track records face margin compression in commoditized diagnostic segments.
Pricing Analysis
Retainer-based service bundling separates premium advisory relationships from unbundled project engagements. Three-tier pricing structure across premium, standard, and economy levels stratifies by partner seniority, proprietary methodology access, and continuous regulatory monitoring inclusion. Cost compression in the standard tier is intensifying because generative diagnostic tools automate benchmark analyses previously requiring analyst teams. Mittelstand manufacturers in Bavaria and Baden-Württemberg demonstrate the highest price sensitivity, while Frankfurt financial institutions accept premium pricing for ECB climate stress-testing scenario modeling.
Supply Chain Analysis
Direct-to-client channels handle hyperscale corporate advisory demand in Frankfurt, London, and Paris. Senior partner talent concentrates in Düsseldorf, Munich, and Vienna, creating geographic supply bottlenecks for complex manufacturing transformation mandates. Raw material dependencies include proprietary benchmark databases, climate scenario modeling engines, and regulatory interpretation frameworks. Single-source vulnerability runs through concentrated partner expertise at heritage industrial firms. Distribution runs through multi-source procurement arrangements where chief strategy officers maintain active rosters of five to seven advisory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory specialization depth, with EU AI Act implementation deadlines forcing generalist boutiques toward acquisition or exit.
For Market Incumbents: Deploy retainer-based subscription models to capture recurring CSRD monitoring revenue and reduce project-based volatility. Incumbents should acquire regulatory interpretation boutiques in Paris and Rotterdam before CSRD materiality assessment deadlines concentrate talent premiums. Generative diagnostic tool proliferation from Amsterdam and Stockholm mid-tier firms threatens standard-tier margin pools. For New Entrants and Emerging Players: Boutique regulatory specialists in Warsaw and Prague offer partnership pathways into EU Green Deal taxonomy advisory for mid-cap manufacturers. The most penetrable segment sits with Polish and Czech automotive suppliers relocating Asian production capacity, where greenfield operational design demand outpaces established advisory presence. New entrants should position through industry association referral networks rather than direct corporate procurement channels. For Investors and Strategic Acquirers: Accelerated partner poaching from Roland Berger and Kearney by technology-focused boutiques is the leading indicator that heritage industrial advisory models face structural pressure. Long-term viability favors vertically integrated firms combining regulatory interpretation depth with proprietary analytics platforms. Acquisition targets should demonstrate preemptive EU AI Act methodology development and established ECB climate stress-testing client relationships. Periodic stress-testing of base assumptions is recommended.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Boutique Acquisition | Captures CSRD and EU AI Act implementation expertise before talent premiums spike in Paris and Rotterdam. |
| Retainer Subscription Launch | Converts project-based pharmaceutical and financial services clients to continuous monitoring revenue streams. |
| Generative Diagnostic Platform Deployment | Automates market sizing and competitive benchmarking for mid-tier competitiveness against Amsterdam and Stockholm rivals. |
| Poland-Czechia Geographic Expansion | Positions advisory teams for automotive and electronics supply chain relocation greenfield mandates. |
| EU AI Act Methodology Development | Establishes first-mover positioning in high-risk AI system classification and governance framework design. |
Research Methodology
Trade association filings, regulatory disclosure databases, and partner mobility tracking formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with managing partners at heritage industrial consultancies, chief strategy officers at German conglomerates, regulatory affairs leads at French asset managers, and procurement directors at Dutch pension funds supplied forward-looking demand intelligence. Bottom-up engagement volume estimates triangulated against top-down advisory revenue benchmarks across the analysis window.
Historical trendline analysis of advisory procurement cycles informed growth trajectory modeling across service type, client type, engagement model, and industry vertical dimensions. CAGRs derived from segmented demand curves incorporating CSRD phased implementation timelines, ECB climate stress-testing protocol adoption rates, and Mittelstand digital transformation budget expansion. Forecast inputs included partner-level capacity constraints, client-side data readiness gaps, and generative tool adoption velocity.
Several conditions sit outside the modeled scope, including geopolitical disruption to EU regulatory harmonization timelines and breakthrough generative capabilities that displace junior analyst functions entirely. Forecasts reflect assumptions about sustained CSRD enforcement intensity and continued ECB climate supervision expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Healthcare Safety and Risk Management Solutions Market
Risk Management and Compliance
Stress Testing Solutions Market
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Enterprise Governance, Risk, and Compliance (Egrc) Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Global Asset Integrity Management Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
Global Risk Management Software Market