
 Legal Advisory Service Market | 2026-2036
Legal Advisory Service Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Advisory Service Market Insights
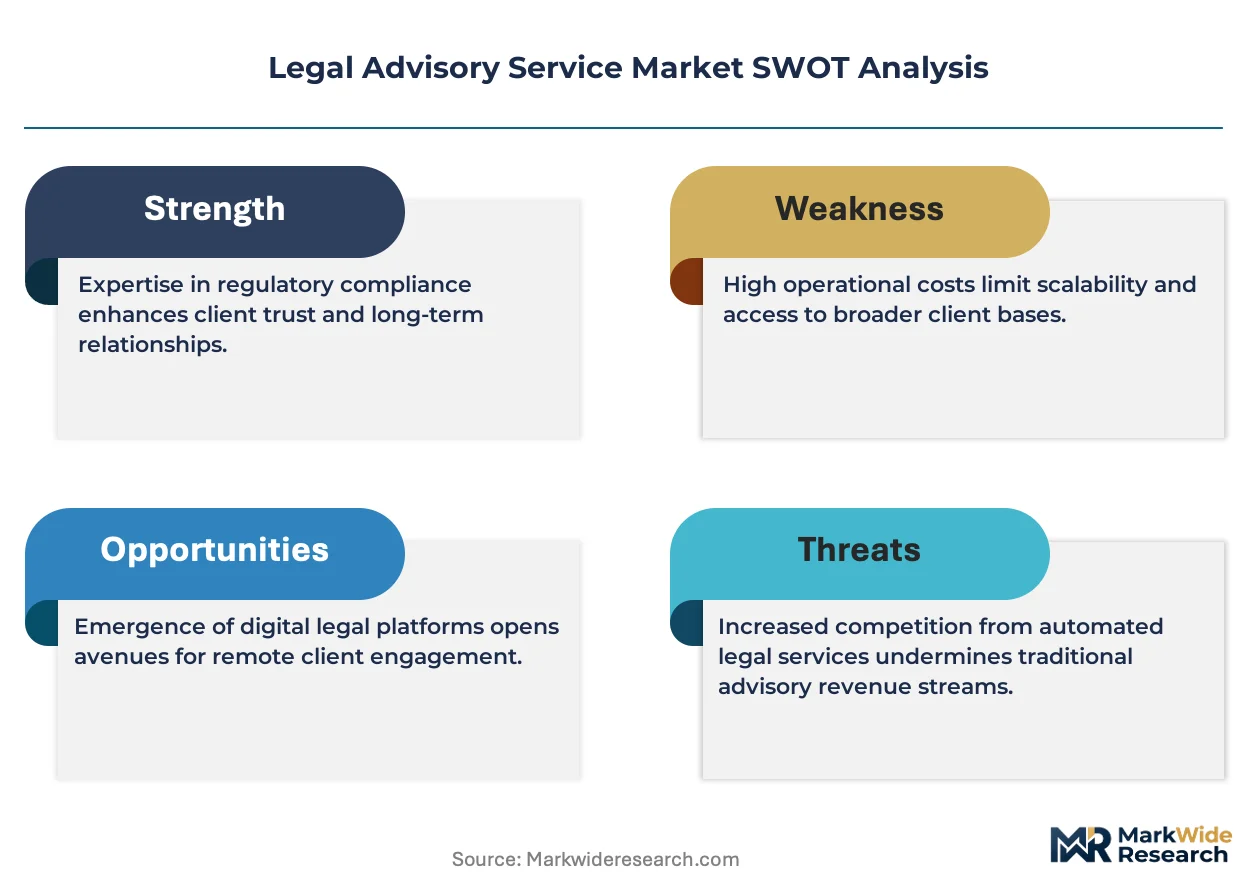
Alternative fee arrangements and managed legal services financing are reshaping competitive entry in legal advisory, allowing mid-tier firms to scale without traditional partner-capital burdens. Deloitte leverages its multidisciplinary consulting backbone to embed legal advice within broader enterprise transformation programs. Baker McKenzie LLP anchors its position through geographic dominance across emerging market jurisdictions. Kirkland & Ellis LLP specializes in high-stakes private equity and restructuring mandates that command premium pricing power.
Legal advisory services encompass strategic counsel on corporate governance, transactional structuring, dispute resolution, and regulatory compliance delivered through licensed practitioners operating under jurisdiction-specific professional standards. These services function as operational infrastructure for entities navigating enforceable obligations, mitigating liability exposure, and executing complex commercial arrangements. Corporate law and compliance consulting represent mature, high-margin service lines where established firms defend entrenched client relationships, while automated legal solutions within the delivery model segment attract capital as technology compresses document review costs and accelerates turnaround times. Subscription engagement models are gaining traction among small and medium enterprises seeking predictable legal spend without retainer minimums.
The US Securities and Exchange Commission intensifies disclosure requirements for public companies, expanding the scope of securities advisory work. The EU AI Act and GDPR impose parallel compliance obligations on multinational corporations operating across Atlantic markets, elevating demand for harmonized cross-border counsel. Stakeholders must monitor how generative AI tools redefine the boundary between automatable legal tasks and judgment-intensive advisory work that preserves practitioner margins.
Market Dynamics
Generative AI deployment across contract lifecycle management is compressing review timelines and forcing fee-structure recalibration across legal advisory delivery models.
Growth Catalysts
- EU AI Act compliance mandates:Multinational corporations operating across Atlantic markets require harmonized cross-border counsel to navigate parallel GDPR and AI governance obligations, expanding advisory scope.
- Securities enforcement intensity:The US Securities and Exchange Commission intensifies disclosure requirements for public companies, directly expanding securities advisory work volumes.
- Private equity transaction velocity:High-stakes restructuring and buyout mandates command premium pricing power and sustained practitioner utilization.
Market Restraints
- Partner-track talent scarcity:Elite practitioners with securities and antitrust specialization command compensation premiums that compress firm margins.
- Technology substitution pressure:Automated document review platforms reduce billable-hour opportunities in due diligence and contract abstraction workstreams.
- Client insourcing trends:Enterprise legal departments build captive capabilities for routine compliance monitoring, displacing external advisory retainers.
Strategic Opportunities
- Subscription engagement models:Small and medium enterprises seek predictable legal spend without retainer minimums, opening mid-market access.
- Climate disclosure advisory:CSRD implementation across European jurisdictions creates demand for sustainability-linked governance counsel.
- Managed legal services financing:Alternative capital structures allow mid-tier firms to scale without traditional partner-capital burdens.
Industry Challenges
- AI ethics and malpractice exposure:Practitioners face uncertain liability frameworks when delegating analytical tasks to generative tools without established professional standards.
- Cross-jurisdictional credentialing friction:Multinational mandates require rapid assembly of licensed practitioners across divergent admission regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Advisory Service Market |
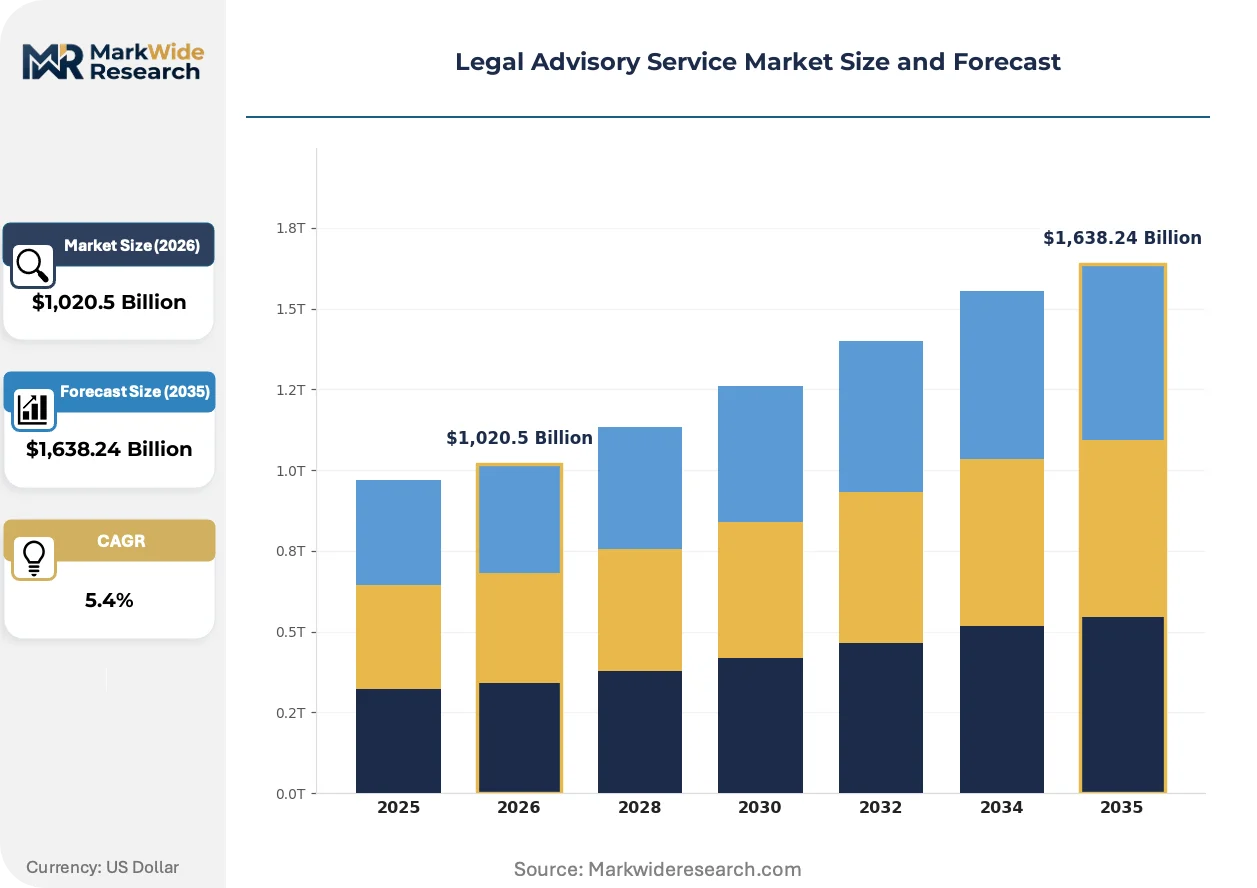
| Market Size in 2026 | $1,020.5 Billion |
| Market Size in 2035 | $1,638.24 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Law, Intellectual Property, Labor Law, Tax Advisory, Compliance Consulting, Contract Management Client Type: Startups, Small & Medium Enterprises, Multinational Corporations, Government Agencies, Non-Governmental Organizations, Educational Institutions Engagement Model: Retainer, Project-Based, Hourly Billing, Fixed Fee, Subscription, Value-Based Pricing Delivery Model: Onsite Consultation, Virtual Meetings, Legal Process Outsourcing, Hybrid Model, Document Review Platforms, Automated Legal Solutions |
| Companies Covered | Deloitte, PwC, EY, KPMG, McKinsey & Company, Baker McKenzie LLP, Clifford Chance, Kirkland & Ellis LLP, Latham & Watkins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Advisory Service Market Trends and Innovations
Technology convergence and regulatory fragmentation are simultaneously compressing delivery costs and expanding compliance complexity across legal advisory value chains.
Large language model integration into contract analytics platforms is virtualizing document review workflows previously requiring associate-level labor. Enterprise legal departments at Fortune 500 industrials deploy these tools for NDAs, vendor agreements, and procurement templates. The technology is virtualizing first-pass review functions and reallocating practitioner time toward negotiation strategy and risk interpretation.
The EU AI Act imposes algorithmic accountability obligations on legal tech vendors and advisory firms deploying automated decision-support tools. This creates parallel compliance architectures for firms operating across US and European jurisdictions. Multinational practices are responding by segregating AI-assisted work product by jurisdiction and building Brussels-based regulatory counsel capabilities.
General counsel procurement patterns favor embedded advisory relationships over episodic matter-based engagement. Industrial conglomerates and private equity sponsors consolidate outside counsel rosters to three-to-five preferred firms with sector-specific depth. This concentration is most pronounced in the United States, where antitrust and securities specialization drive vendor rationalization decisions.
Legal Advisory Service Market Segmentation
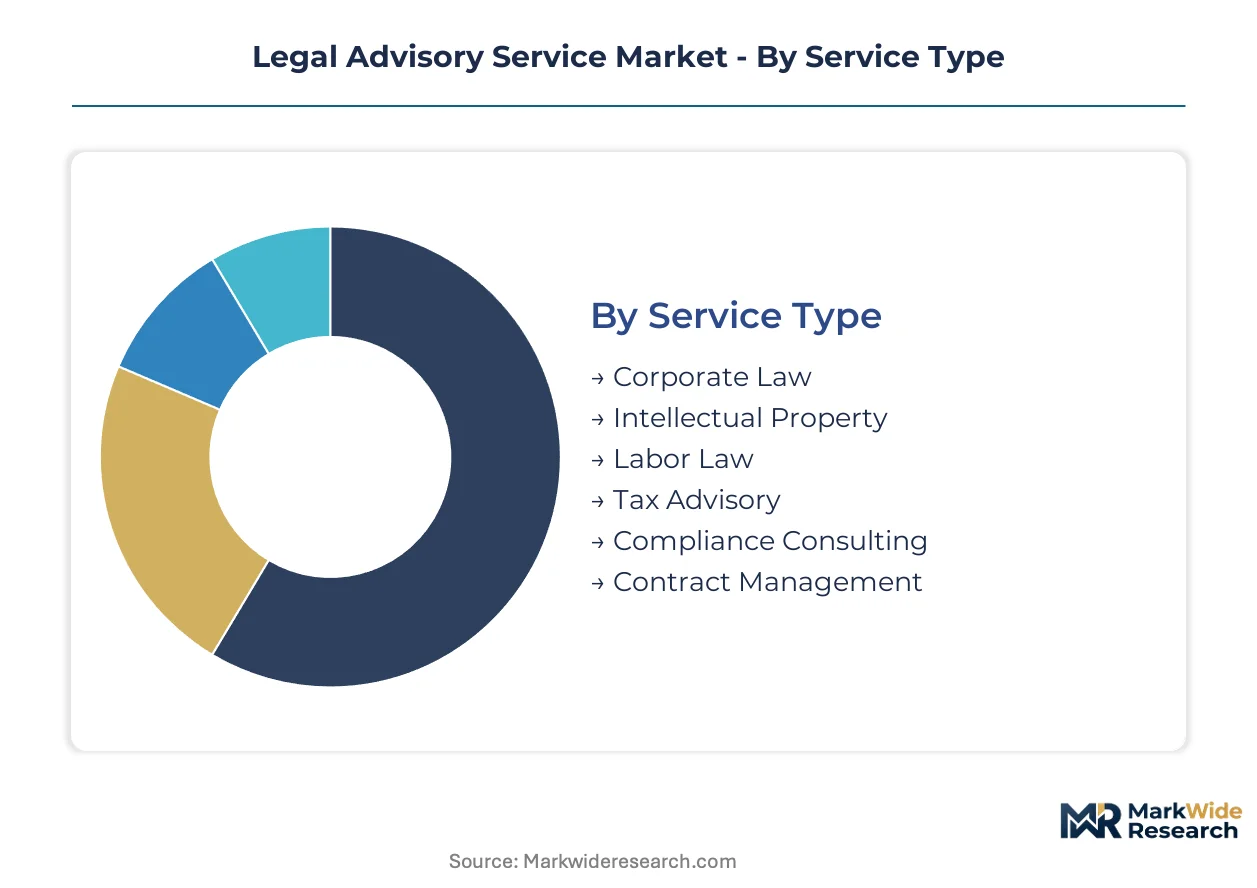
Legal advisory services fragment across service lines, client profiles, and delivery architectures that carry distinct margin profiles and capital intensity. Segmentation reveals where automation compresses pricing power versus where practitioner judgment sustains premium rates.
Service Type:
Corporate law mandates turn over fastest on transaction timelines, while compliance consulting runs on multi-year regulatory cycles with renewal stickiness.
- Corporate Law:Transactional structuring, M&A execution, and governance advisory constitute the highest-volume service line. Demand concentrates among private equity sponsors and Fortune 500 industrials in the United States where antitrust clearance complexity extends deal timelines and advisory scope.
- Compliance Consulting:Regulatory monitoring, policy implementation, and enforcement response functions operate on annual retainer structures. European-headquartered multinationals drive expansion here as CSRD and EU AI Act obligations layer atop existing GDPR programs.
- Intellectual Property:Patent prosecution, trademark enforcement, and licensing negotiation protect intangible asset value.
- Labor Law:Employment disputes, workforce restructuring, and collective bargaining advisory respond to sector-specific union density.
- Tax Advisory:Cross-border structuring, transfer pricing documentation, and controversy defense navigate OECD pillar implementation.
- Contract Management:Template standardization, clause negotiation, and obligation tracking increasingly shift to technology-augmented delivery.
Corporate law dominates installed base. Compliance consulting is where expansion concentrates.
Client Type:
Cost tier stratification separates episodic project buyers from embedded relationship clients with predictable annual spend.
- Multinational Corporations:Complex cross-border mandates require coordinated counsel across 10-plus jurisdictions. These clients concentrate demand in the United States and European Union where regulatory enforcement intensity justifies premium specialist rates.
- Small & Medium Enterprises:Subscription engagement models and fixed-fee structures address budget predictability needs. This segment is expanding most quickly as legal tech platforms democratize access to standardized document automation.
- Startups:Venture-backed formation, founder equity structuring, and fundraising documentation operate on compressed timelines.
- Government Agencies:Public procurement rules, administrative litigation, and regulatory drafting follow distinct fee constraints.
- Non-Governmental Organizations:Mission-aligned fee structures and pro bono commitments characterize this client class.
- Educational Institutions:Endowment management, research compliance, and employment matters generate steady institutional demand.
Multinational corporations anchor revenue concentration. Small and medium enterprises are gaining share fastest.
Engagement Model:
Volume distribution favors recurring revenue structures over episodic matter billing as general counsel procurement patterns shift.
- Retainer:Pre-committed advisory hours with monthly or annual minimums embed firms within client operations. Large-cap industrials in the United States favor this structure for securities and antitrust specialization.
- Subscription:Predictable monthly fees for defined service bundles attract mid-market buyers seeking cost certainty without partner-level minimums.
- Project-Based:Scoped mandates with defined deliverables and timelines suit discrete transactions.
- Hourly Billing:Time-recorded rates persist in bet-the-company litigation and novel regulatory matters.
- Fixed Fee:Agreed pricing for repeatable matter types like residential real estate closings or standard contract reviews.
- Value-Based Pricing:Outcome-contingent or success-fee structures align advisor compensation with client results.
Retainer structures dominate relationship economics. Subscription models are climbing the fastest.
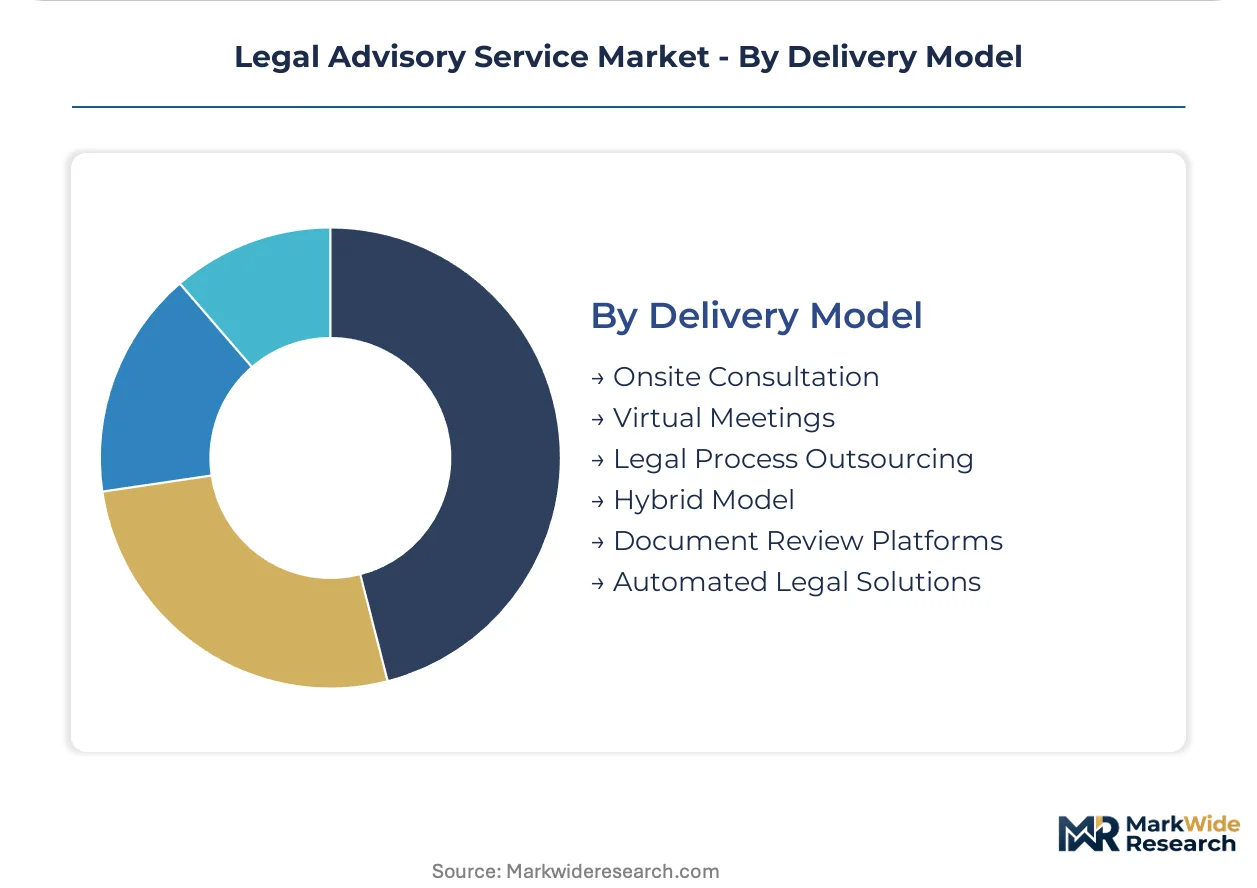
Delivery Model:
Technology substitution pressure varies sharply across delivery architectures, separating high-touch advisory from commoditized document processing.
- Automated Legal Solutions:Contract analytics, due diligence extraction, and template generation compress associate-level labor requirements. Enterprise legal departments at US-headquartered industrials deploy these tools for procurement and NDA workflows.
- Legal Process Outsourcing:Document review, regulatory filing preparation, and discovery management shift to lower-cost jurisdictions.
- Onsite Consultation:Embedded practitioners within client facilities support complex negotiations and crisis response.
- Virtual Meetings:Remote advisory delivery expanded permanently post-pandemic for routine counsel.
- Hybrid Model:Blended onsite and remote engagement optimizes cost and relationship depth.
- Document Review Platforms:Technology-assisted review for litigation discovery and transactional due diligence.
Onsite consultation retains premium positioning. Automated legal solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The legal advisory service trade flows through jurisdictional complexity rather than physical goods, creating export-import dynamics of expertise where US and UK firms generate surplus advisory capacity absorbed by regulatory-importing markets in Asia and the Middle East.
United States
Securities enforcement intensity and private equity transaction velocity concentrate demand for high-stakes advisory. The SEC intensifies disclosure requirements for public companies, expanding compliance scope. New York and Washington DC anchor the largest advisory clusters, with Delaware corporate law specialization creating jurisdictional export advantages.
United Kingdom
London's position as a financial center sustains demand for cross-border transactional and dispute resolution counsel. The Solicitors Regulation Authority and Financial Conduct Authority impose parallel compliance frameworks on advisory firms. The City of London and Canary Wharf concentrate Magic Circle and international firm headquarters serving European mandates.
Germany
Industrial conglomerate headquarters and Mittelstand export financing sustain corporate law demand. The Federal Financial Supervisory Authority (BaFin) and implementation of CSRD elevate compliance advisory scope. Frankfurt's financial district and Munich's technology corridor concentrate advisory capacity for DAX-listed enterprises.
Singapore
Wealth management and regional headquarters functions import UK and US advisory models into Southeast Asian markets. The Monetary Authority of Singapore and strict anti-money laundering enforcement create specialized compliance demand. The Marina Bay financial district concentrates international firm offices serving ASEAN cross-border mandates.
United Arab Emirates
Sovereign wealth fund activity and regional commercial arbitration sustain advisory import demand from UK and US firms. The Dubai International Financial Centre and Abu Dhabi Global Market operate under English common law frameworks. Dubai's financial free zones concentrate international advisory capacity serving Middle East and Africa outbound investment.
Legal Advisory Service Market Competitive Landscape
On the supply side, the industry is bifurcated between multidisciplinary professional services networks and specialized law partnerships. The top tier concentrates around ten global brands with cross-border credentialing capabilities. Two strategic archetypes dominate: consulting-anchored networks embedding legal advice within enterprise transformation, and elite partnerships commanding premium pricing on bet-the-company mandates. Competitive moves center on managed legal services financing structures and AI-enabled delivery platform investments.
Within the consulting-anchored tier, Deloitte, PwC, and EY exemplify the multidisciplinary model where legal advisory integrates with tax, risk, and technology consulting. These networks leverage existing enterprise relationships to embed compliance and transactional counsel within broader transformation programs. Their scale-driven delivery models compete with traditional law firm partnerships on cost-predictable mandates while maintaining regulatory admission across multiple jurisdictions.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| EY |
| KPMG |
| McKinsey & Company |
| Baker McKenzie LLP |
| Clifford Chance |
| Kirkland & Ellis LLP |
| Latham & Watkins |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in elite securities and antitrust specialization across the United States and United Kingdom drives partner-track talent premiums and reshapes both firm hiring posture and client fee structures. This utilization squeeze propagates through alternative fee arrangements and technology-augmented delivery models as firms seek margin defense.
Pricing Analysis
Industrial OEM buyers anchor retainer-based pricing structures for compliance consulting, while private equity sponsors command project-based premiums for transaction execution. Price differentiation rests on practitioner specialization depth and cross-jurisdictional credentialing density. Cost compression in document review tiers is intensifying because automated contract analytics platforms displace associate-level hours. Small and medium enterprises exhibit highest price sensitivity, seeking subscription models with predictable monthly floors, whereas multinational corporations accept premium hourly rates for bet-the-company litigation and regulatory defense.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for legal process outsourcing and document review platforms. Advisory capacity concentrates in the United States, United Kingdom, and Singapore, with emerging market mandates drawing from these export hubs. Raw material dependencies include licensed practitioner labor, regulatory intelligence databases, and AI-enabled contract analytics software. Single-source vulnerability sits with elite partner-level talent pools in securities and restructuring specializations. Distribution runs through embedded advisory relationships with general counsel procurement functions at Fortune 500 industrials and private equity sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The legal advisory service market is entering a cyclical recovery phase driven by private equity transaction velocity and cross-border regulatory complexity expansion. Firms that align capability investment with these demand pulses will capture disproportionate margin expansion.
For Market Incumbents: Insulate partner-track margins by building managed legal services financing structures that reduce fixed-cost intensity. Acquire AI-enabled contract analytics capabilities to defend document review revenue against technology substitution. Deepen vertical integration into regulatory intelligence platforms to capture recurring data revenue streams alongside advisory fees.
For New Entrants and Emerging Players: Pursue subscription engagement models targeting small and medium enterprises in underserved European jurisdictions facing CSRD implementation deadlines. Climate disclosure advisory represents the most penetrable white-space segment. Lead with fixed-fee compliance monitoring bundles rather than traditional retainer minimums to differentiate procurement conversations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated legal solutions delivery as cloud infrastructure and large language model APIs reduce platform build costs. Long-term viability favors asset-light, technology-augmented models over traditional partnership capital structures. Target mid-tier firms with established sector specialization and underinvested technology stacks. Monitor generative AI malpractice exposure litigation as the critical inflection signal for liability framework maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Delivery Platform Investment | Large language model integration compresses associate labor requirements in contract review workflows. |
| Managed Legal Services Financing Structure | Alternative capital arrangements allow mid-tier firms to scale without traditional partner-capital burdens. |
| Cross-Border Regulatory Intelligence Buildout | Brussels-based capabilities address EU AI Act and GDPR parallel compliance obligations for multinationals. |
| Climate Disclosure Advisory Practice Launch | CSRD implementation across European jurisdictions creates demand for sustainability-linked governance counsel. |
| Subscription Engagement Model Rollout | Predictable monthly fees attract mid-market buyers seeking cost certainty without partner-level minimums. |
Research Methodology
Cross-validation between general counsel interviews and regulatory filing analysis anchors the qualitative findings in this study. Primary fieldwork engaged managing partners at global law firms, chief legal officers at Fortune 500 industrials, legal operations directors at private equity sponsors, and procurement leads at multinational corporations. Secondary sources included SEC enforcement action databases, EU regulatory implementation notices, bar association admission records, and legal technology vendor disclosures. Bottom-up practitioner utilization estimates and top-down market size triangulation were reconciled through iterative calibration.
Calibration against historical matter volume trends and practitioner headcount expansion rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, client profile, engagement model, and delivery architecture alongside geographic regulatory intensity clustering. CAGRs were derived from regression analysis of advisory spend patterns against enforcement activity indices and transaction volume proxies. AI adoption curves and alternative fee arrangement penetration rates served as industry-specific forecast inputs.
Sensitivities concentrate around generative AI liability framework evolution and cross-jurisdictional credentialing liberalization. Forecasts embed assumptions regarding regulatory enforcement intensity continuity and private capital deployment velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Compliance As a Service Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Trade Surveillance Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
North America Strategic Consulting Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Financial Risk Management Software Market
Risk Management and Compliance
Third Party Risk Management Market