
 Anti-Money Laundering (AML) Market | 2026-2036
Anti-Money Laundering (AML) Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Money Laundering (AML) Market Analysis
Real-time behavioral analytics tier is bifurcating the competitive landscape between legacy rule-engine vendors and AI-native challengers. NICE Actimize leverages its established presence in tier-one banking to sustain dominant deployment across North American compliance departments. SAS Institute differentiates through deep statistical modeling heritage that anchors its risk-scoring credibility with regulators.
Anti-money laundering encompasses software systems, data architectures, and procedural frameworks designed to detect, prevent, and report illicit financial flows through transaction pattern analysis, identity verification protocols, and suspicious activity reporting mechanisms. Cloud-based deployment is accelerating as financial institutions abandon capital-intensive on-premises infrastructure for elastic compliance capacity. Machine learning solutions represent the fastest-expanding technology segment, though transaction monitoring retains the largest installed base and recurring revenue pool.
FinCEN, the EU's AMLA, and the Financial Conduct Authority shape procurement standards by mandating risk-based approaches and audit-ready documentation trails. The EU AI Act adds algorithmic transparency requirements that filter into vendor selection criteria for automated monitoring tools. Stakeholders must weigh model explainability against detection precision when evaluating next-generation platform investments.
Market Dynamics
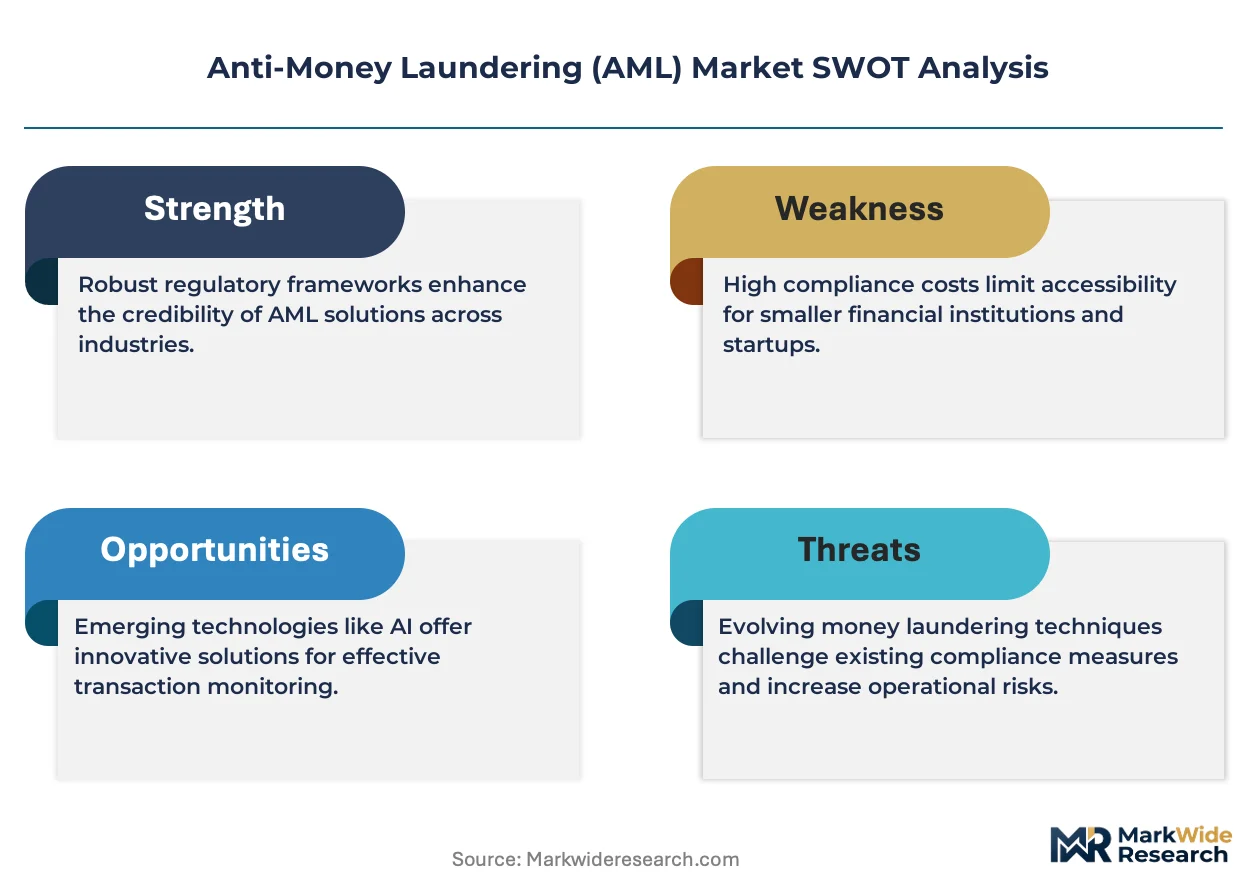
Real-time behavioral analytics is bifurcating the competitive landscape between legacy rule-engine vendors and AI-native challengers, forcing established players to retrofit explainability into black-box detection models.
Growth Catalysts
- EU AMLA Authority Mandates:The European Union's centralized anti-money laundering authority imposes uniform verification standards across member states, compelling cross-border banks to upgrade transaction monitoring infrastructure.
- Cloud Migration Acceleration:Financial institutions abandon capital-intensive on-premises systems for elastic compliance capacity, reducing deployment cycles from months to weeks.
- Beneficial Ownership Transparency:The US FinCEN final rule tightens corporate veil penetration requirements, expanding the addressable market for identity verification and entity resolution solutions.
Market Restraints
- Model Explainability Trade-offs:Machine learning detection precision conflicts with regulatory demands for audit-ready decision trails, forcing vendors to sacrifice accuracy for interpretability.
- Data Silo Fragmentation:Banking consortiums and correspondent networks maintain incompatible data architectures, limiting cross-institutional pattern recognition effectiveness.
- Specialized Talent Scarcity:The intersection of financial crime expertise and machine learning engineering concentrates in London, New York, and Singapore, inflating compensation costs.
Strategic Opportunities
- Real-Time Payment Rails:Instant settlement systems in Brazil, India, and the United Kingdom create demand for sub-second transaction screening that legacy batch architectures cannot satisfy.
- Embedded Finance Expansion:Non-bank fintechs integrating payment services face first-time BSA/AML obligations, opening greenfield deployment opportunities for compliance platforms.
- Regulatory Technology Convergence:The EU AI Act's algorithmic transparency requirements intersect with AML model governance, creating bundled procurement opportunities for explainable AI vendors.
Industry Challenges
- Legacy Core Integration:Mainframe transaction processing systems at tier-one banks resist API-based monitoring insertion, extending implementation timelines.
- False Positive Fatigue:Alert volumes overwhelm investigative units at major financial institutions, degrading the signal-to-noise ratio of detection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Money Laundering (AML) Market |
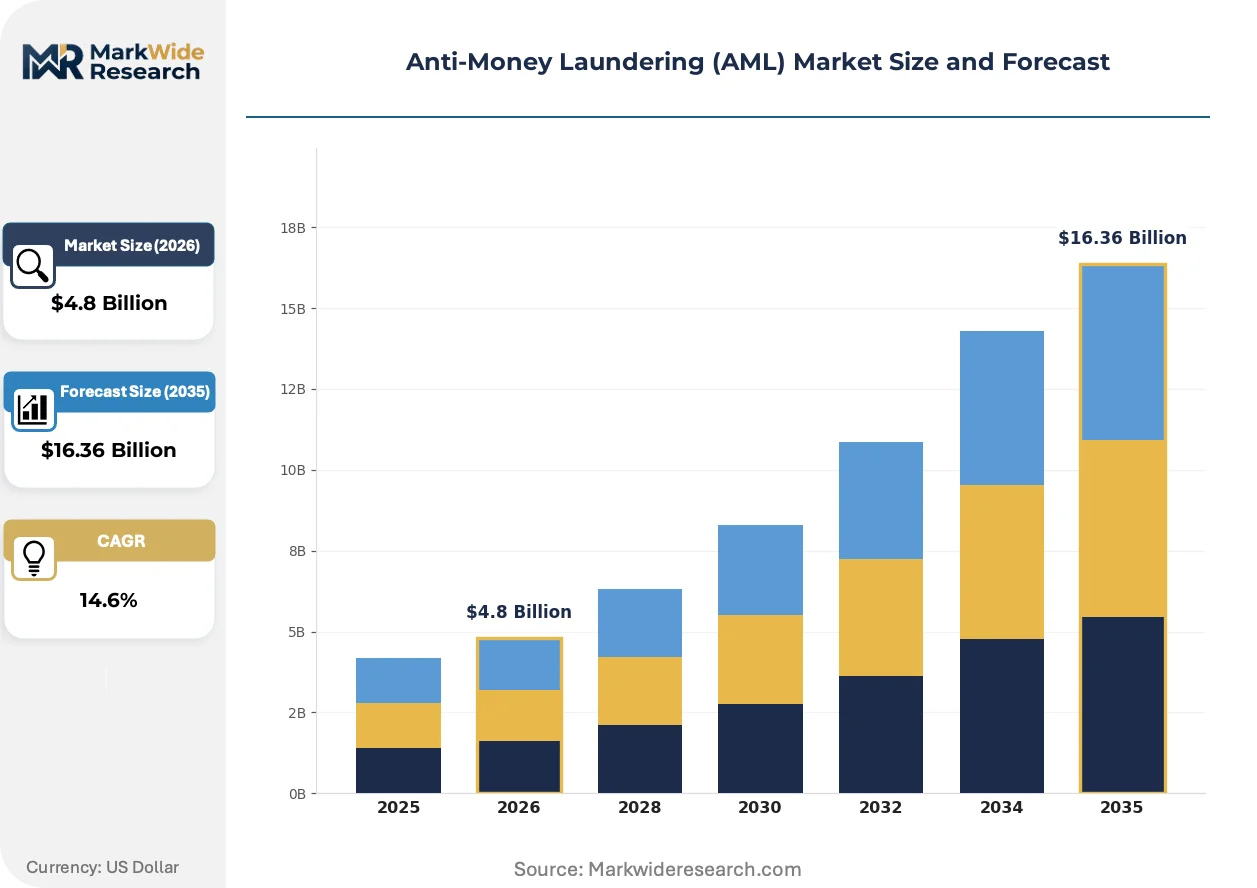
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Transaction Monitoring, Customer Due Diligence, Regulatory Reporting, Risk Assessment Deployment: On-Premises, Cloud-Based, Hybrid, Managed Service End User: Banks, Insurance Companies, Investment Firms, Government Agencies Technology: Machine Learning, Artificial Intelligence, Data Analytics, Blockchain |
| Companies Covered | NICE Actimize, FICO, SAS Institute, ACI Worldwide, LexisNexis Risk Solutions, Oracle Corporation, ComplyAdvantage, Experian, Trulioo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Money Laundering (AML) Market Emerging Trajectories
Behavioral biometrics and network graph analytics are reshaping how institutions distinguish legitimate customer anomalies from laundering typologies, compressing the window between detection and interdiction.
Machine learning is bifurcating the vendor landscape into two camps: established rule-engine providers retrofitting statistical models onto legacy architectures, and AI-native entrants building detection systems from probabilistic foundations. Tier-two and tier-three banks are adopting cloud-native challengers at twice the pace of money-center institutions, fragmenting procurement patterns that once concentrated in incumbent relationships. This technology shift is compressing the traditional seven-to-ten-year platform replacement cycles toward three-year refresh horizons.
The EU AI Act's risk classification framework for automated decision-making systems is mandating algorithmic impact assessments for high-risk AI deployments, including transaction monitoring tools. Financial institutions must now document training data provenance, model performance benchmarks, and human oversight protocols before regulatory approval. Vendors serving the European market are reengineering product roadmaps to embed technical documentation generators and audit trail exporters directly into platform workflows.
Buyers are unbundling detection software from implementation services, contracting specialized system integrators for deployment while negotiating direct SaaS relationships with technology vendors. This procurement fragmentation is displacing the traditional single-source model where vendors controlled both platform and integration revenue streams. The United Kingdom and United States exhibit the most pronounced unbundling, driven by procurement offices seeking to isolate software licensing costs from professional services markups.
Anti-Money Laundering (AML) Market Segmentation
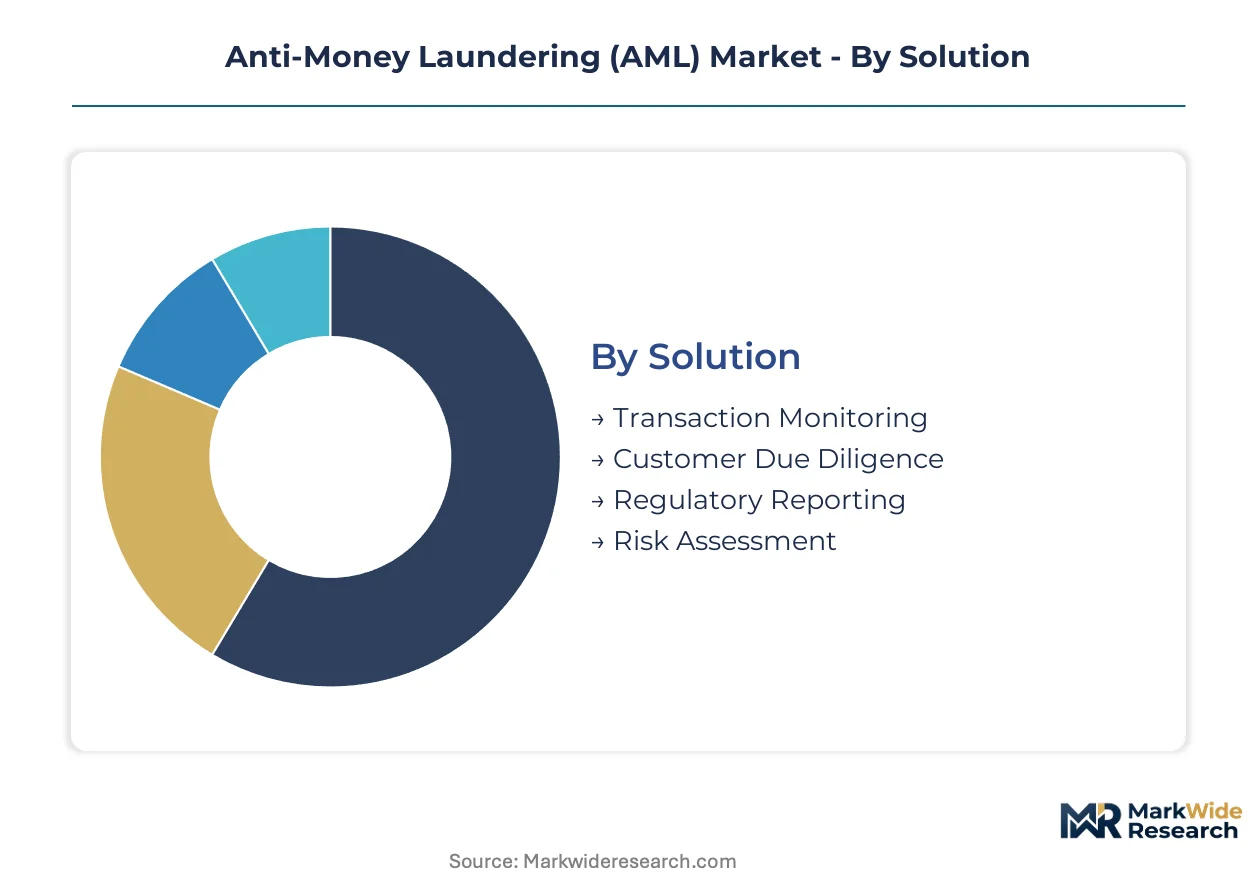
Regulatory mandates across the United States, United Kingdom, and European Union create divergent procurement requirements that reshape how AML solutions segment by compliance burden and audit complexity. Financial institutions map technology investments against specific jurisdictional enforcement intensity rather than pursuing uniform global deployments.
Solution:
FinCEN's final rule on beneficial ownership and the EU AMLA's cross-border verification standards impose distinct technical demands that differentiate solution procurement by regulatory geography.
- Transaction Monitoring:Real-time pattern recognition engines analyze payment flows against behavioral baselines to flag anomalies for investigator review. United States money-center banks concentrate demand here as FinCEN enforcement actions escalate penalties for missed suspicious activity reports.
- Customer Due Diligence:Identity verification and risk-rating workflows integrate biometric checks, document authentication, and adverse media screening. United Kingdom challenger banks and fintechs drive fastest adoption as the Financial Conduct Authority tightens onboarding standards for digital-first institutions.
- Regulatory Reporting:Automated suspicious activity report generation and filing systems streamline compliance documentation. European Union banks prioritize this segment to satisfy AMLA's standardized reporting formats across member states.
- Risk Assessment:Dynamic scoring models recalculate client risk profiles based on transaction behavior changes and external data feeds. Smaller regional banks in Singapore and Hong Kong deploy these tools to stretch limited compliance staffing.
Transaction Monitoring handles the majority of throughput; Customer Due Diligence is the fastest mover on share.
Deployment:
Capital intensity and data sovereignty requirements fragment deployment choices across institution size and regulatory jurisdiction.
- On-Premises:Dedicated hardware installations within bank data centers maintain physical control over sensitive transaction records. German and Swiss private banks persist here due to strict national data localization laws and historical risk aversion.
- Cloud-Based:Elastic SaaS platforms scale compute resources dynamically with transaction volume fluctuations. Tier-two banks in Brazil and India adopt this fastest as real-time payment systems strain legacy infrastructure.
- Hybrid:Split architectures keep core transaction data on-premises while pushing analytics workloads to cloud environments. Australian and Canadian institutions favor this model to balance regulator demands with cost optimization.
- Managed Service:Outsourced compliance operations where vendors assume alert investigation and regulatory filing responsibilities. Smaller credit unions in the United States contract these services to access expertise without building internal teams.
On-Premises retains the largest installed base; Cloud-Based deployment is climbing the fastest.
End User:
Supervisory intensity and penalty exposure concentrate vendor attention on institutions facing the most aggressive enforcement regimes.
- Banks:Universal banks, investment banks, and retail banking networks constitute the core revenue base for AML platform vendors. United States and United Kingdom institutions absorb the majority of industry compliance technology spending due to FinCEN and FCA enforcement visibility.
- Insurance Companies:Life insurers and property-casualty carriers apply AML protocols to premium payments and claims settlements. European Union insurers face expanding obligations under AMLA's sectoral coverage extensions.
- Investment Firms:Broker-dealers, asset managers, and private equity funds monitor investor capital flows and distribution payments. Singapore and Hong Kong wealth management hubs drive regional demand as Asian capital markets deepen.
- Government Agencies:Financial intelligence units and tax authorities deploy analytical tools to trace illicit flows across institutional boundaries. National regulators in India and Brazil build internal capabilities as emerging market enforcement matures.
Banks command the dominant procurement volume; Investment Firms are expanding most quickly as private markets attract regulatory scrutiny.
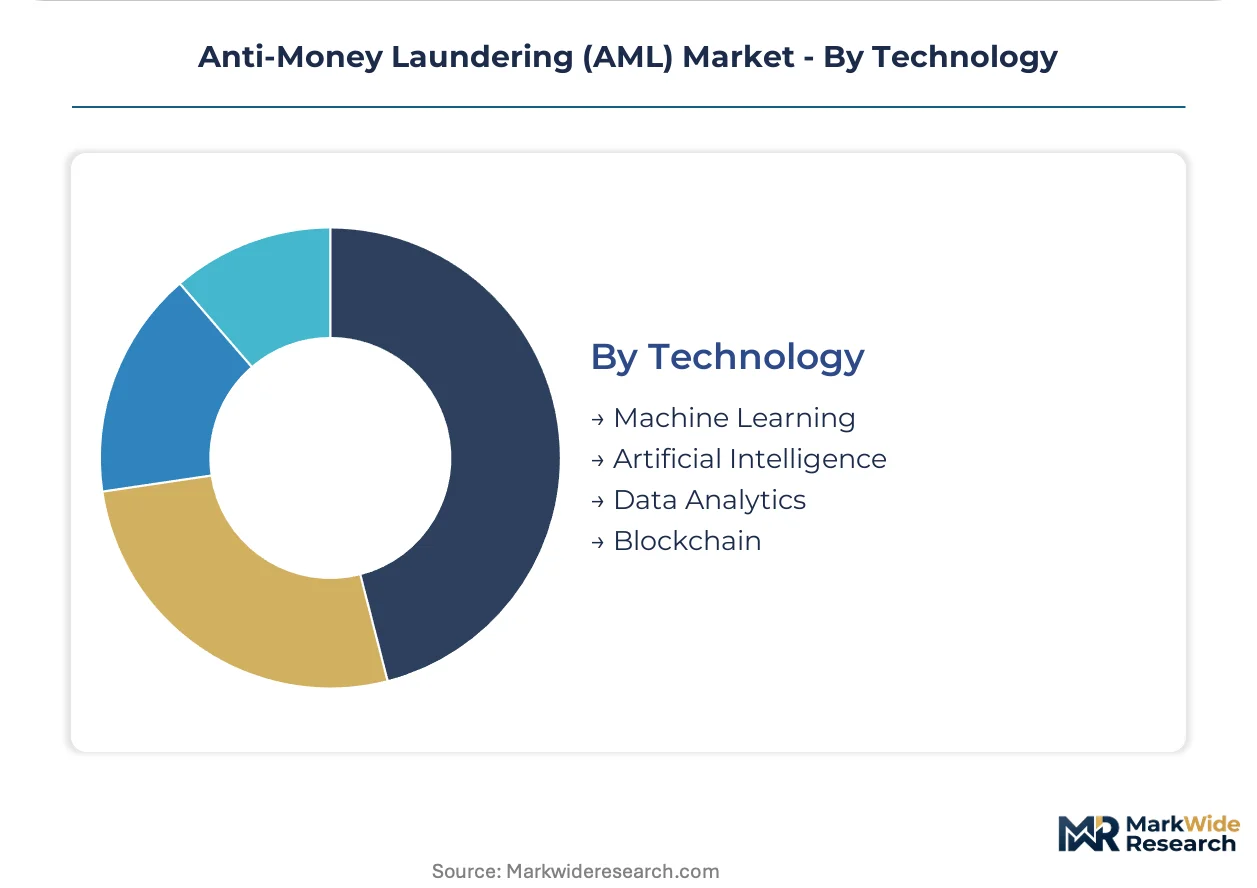
Technology:
Explainability requirements from the EU AI Act and model governance standards from US banking regulators create divergent technology adoption curves.
- Machine Learning:Supervised and unsupervised algorithms detect complex laundering typologies beyond rule-based pattern libraries. Vendors serving European markets reengineer architectures to satisfy algorithmic transparency mandates.
- Artificial Intelligence:Natural language processing and generative systems automate alert narrative generation and regulatory correspondence. Early deployment concentrates in London and New York where talent density supports advanced implementations.
- Data Analytics:Statistical visualization and network graph tools map entity relationships across fragmented data sources. Mid-tier banks in Australia and Canada leverage these capabilities without full machine learning investments.
- Blockchain:Distributed ledger analytics trace cryptocurrency transactions and stablecoin flows through decentralized networks. Specialized vendors in Singapore and Switzerland develop niche expertise as digital asset regulation crystallizes.
Data Analytics anchors the largest recurring revenue pool; Machine Learning shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across jurisdictions. United States banks absorb premium pricing for regulatory defensibility, while emerging market institutions prioritize cost-efficient cloud deployment over feature depth.
United States
FinCEN enforcement actions against money-center banks drive sustained investment in transaction monitoring infrastructure. The Corporate Transparency Act's beneficial ownership requirements expand entity resolution demand. New York's financial district concentrates vendor sales operations and compliance talent pools.
United Kingdom
Challenger banks and fintechs accelerate customer due diligence procurement as the Financial Conduct Authority tightens digital onboarding standards. Post-Brexit regulatory divergence creates parallel compliance obligations for cross-border institutions. London maintains its position as the primary European hub for AML technology development and professional services.
Germany
Private banking and wealth management segments sustain on-premises deployment preferences despite cloud migration trends elsewhere. BaFin's risk-based supervision mandates drive demand for audit-ready documentation systems. Frankfurt's concentration of universal banks anchors regional vendor relationships and implementation expertise.
Singapore
Wealth management hubs and private banking operations fuel investment firm-focused AML procurement. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria. The city-state's regulatory sandbox environment accelerates pilot deployments of behavioral analytics and network graph tools.
Brazil
Real-time payment system expansion strains legacy batch-processing infrastructure, opening cloud-native deployment opportunities. The central bank's Pix instant payment mandate creates sub-second screening requirements. São Paulo's fintech corridor concentrates demand from newly regulated non-bank payment institutions facing first-time BSA/AML obligations.
Anti-Money Laundering (AML) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Legacy rule-engine vendors leverage installed base relationships and regulatory credibility to sustain premium pricing in tier-one banking. AI-native challengers capture mid-market share through elastic SaaS delivery and compressed implementation timelines. Three archetypes dominate: established platform incumbents with deep statistical heritage, cloud-native specialists targeting real-time analytics, and managed service providers outsourcing investigative operations. Consolidation pressures intensify as incumbents acquire explainability capabilities and challengers seek scale through vertical partnerships.
Within the established platform tier, NICE Actimize and SAS Institute occupy positions anchored by decades of regulatory relationships and risk-scoring credibility. FICO exemplifies the statistical modeling heritage that underpins enforcement-defensible detection systems. Among cloud-native entrants, ComplyAdvantage represents the challenger archetype prioritizing elastic deployment and rapid configuration over legacy integration depth.
| Leading Market Players |
|---|
| NICE Actimize |
| FICO |
| SAS Institute |
| ACI Worldwide |
| LexisNexis Risk Solutions |
| Oracle Corporation |
| ComplyAdvantage |
| Experian |
| Trulioo |
| Others |
Supply Flow & Price Mechanics
FinCEN's beneficial ownership verification mandates and the EU AI Act's algorithmic transparency requirements simultaneously gate vendor qualification and stratify price tiers across deployment models. Institutions in the United States and United Kingdom absorb premium SaaS rates for audit-ready documentation trails, while emerging market banks prioritize cost-efficient cloud configurations with compressed feature sets.
Pricing Analysis
Implementation and managed services revenue streams now exceed initial license values across multi-year relationships. Three-tier pricing structure across premium, standard, and economy levels separates tier-one banking deployments with dedicated support teams from mid-market SaaS subscriptions and basic alert-generation tiers. Pricing pressure stems from procurement offices unbundling software from professional services to isolate licensing costs. Tier-two banks in Brazil and India exhibit highest price sensitivity; United States money-center institutions prioritize regulatory defensibility over unit economics.
Supply Chain Analysis
Extended configuration timelines for legacy core integration stretch vendor delivery schedules from weeks to quarters. Software development concentrates in the United States, United Kingdom, and Israel, with implementation expertise clustering in London, New York, and Singapore. Cloud infrastructure draws from hyperscaler networks anchored in Virginia, Frankfurt, and Dublin. Single-source vulnerability runs through specialized machine learning engineering talent pools. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for deployment execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of financial crime expertise and probabilistic modeling skills concentrates in three metropolitan corridors, constraining vendor scaling velocity and inflating compensation costs for qualified implementation teams.
For Market Incumbents: Consolidate alert investigation and regulatory filing operations through managed service offerings to capture recurring revenue streams and deepen client switching costs. Acquire explainable AI capabilities from specialized vendors to satisfy EU AI Act documentation requirements without sacrificing detection precision. Vertical integration into cloud infrastructure partnerships reduces hyperscaler dependency and protects margin compression from compute cost volatility. For New Entrants and Emerging Players: SOC 2 Type II and ISO 27001 fast-tracks accelerate procurement cycles with United Kingdom challenger banks and fintechs facing first-time BSA/AML obligations. Target Brazil's Pix-enabled payment institutions and India's real-time settlement corridors where legacy batch architectures fail sub-second screening requirements. Lead with API-first deployment models that compress implementation timelines from months to weeks against incumbent integration complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment tiers as elastic infrastructure replaces dedicated hardware installations. Evaluate targets with established regulatory relationships in United States or European Union jurisdictions and proven model explainability architectures. Watch for FinCEN enforcement action frequency as inflection indicator for compliance technology procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Architecture Investment | EU AI Act documentation mandates require technical transparency layers in detection models. |
| Real-Time Payment Rail Integration | Brazil's Pix and India's UPI instant settlement systems demand sub-second screening capabilities. |
| Managed Service Expansion | Smaller credit unions outsource investigative operations to access expertise without internal team buildout. |
| Cloud-Native Platform Development | Tier-two banks abandon capital-intensive on-premises systems for elastic compliance capacity. |
| Regulatory Technology Partnership | Systems integrators unbundle implementation from software licensing to capture procurement fragmentation. |
Methodological Framework
A standing panel of compliance technology officers, financial crime investigators, regulatory affairs directors, and procurement managers at tier-one and tier-two banks provided ongoing calibration across primary interview cycles. Secondary validation drew from FinCEN enforcement action databases, FCA consultation papers, EU AMLA regulatory drafts, and vendor SEC filings. Bottom-up deployment estimates triangulated against top-down compliance spending benchmarks from financial institution annual reports.
Consistency checks against external regulatory spend surveys and technology procurement databases validated volume and value outputs across the projection horizon. Segmentation modeling incorporated solution type, deployment architecture, end-user institution category, and underlying technology stack dimensions. CAGRs were derived from fitted growth curves anchored to documented procurement cycles and regulatory implementation timelines. Forecast inputs included real-time payment system expansion trajectories and algorithmic transparency mandate compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and cloud migration continuity; material deviation in FinCEN penalty escalation or data sovereignty restriction expansion would warrant model refresh. Forecasts reflect these base assumptions without claiming predictive certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Global Regulatory Reporting and Compliance Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
Sell-Side Due Diligence Services Market
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Third Party Risk Management Market
Risk Management and Compliance
Europe Risk Management Market
Risk Management and Compliance
Regtech Market
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Enterprise Risk Management Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Sustainable Finance Market
Risk Management and Compliance
Asia-Pacific Sustainable Finance Market
Risk Management and Compliance
Global Compliance Management Software Market