
 Healthcare Safety and Risk Management Solutions Market | 2026-2036
Healthcare Safety and Risk Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Safety and Risk Management Solutions Market Foresight
The gap between premium enterprise suites and commodity point solutions is repositioning competitive dynamics across the sector. RLDatix leverages its vertical integration into patient safety and workforce compliance modules to sustain pricing power in multi-hospital deployments. Riskonnect anchors its position through deep specialization in healthcare risk analytics, while symplr competes aggressively on channel control with group purchasing organization partnerships.
Healthcare safety and risk management solutions encompass software platforms and integrated services that capture, analyze, and act upon clinical incidents, operational hazards, and regulatory exposures across care delivery organizations. These systems typically employ real-time data ingestion, natural language processing of event narratives, and predictive algorithms scoring severity probability to prevent patient harm and organizational liability. Cloud-based delivery models are capturing the fastest expansion as hospitals prioritize interoperability and remote accessibility over capital-intensive on-premise infrastructure. Incident reporting systems remain the largest revenue pool given mandatory reporting requirements, though risk analytics applications are deepening margin profiles through subscription-based predictive insights.
FDA Sentinel surveillance requirements, OSHA workplace safety mandates, and the EU MDR adverse-event frameworks are elevating documentation standards and audit frequencies across jurisdictions. Compliance management solutions must now demonstrate algorithmic transparency and data lineage to satisfy these evolving oversight regimes. Stakeholders should evaluate vendor capabilities in cross-border regulatory mapping as enforcement divergence between FDA, EMA, and national health technology assessment bodies intensifies.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing vendor procurement cycles and demanding modular, interoperable safety platforms that span acute, ambulatory, and post-acute environments.
Growth Catalysts
- FDA Sentinel Initiative:Mandatory adverse-event surveillance requirements are forcing health systems to upgrade from passive reporting to active pharmacovigilance data infrastructure.
- Cloud-native architecture:IT departments are abandoning capital-intensive on-premise installations for SaaS delivery models that enable remote access and faster deployment cycles.
- Workforce safety mandates:OSHA workplace violence prevention rules are expanding incident reporting scope beyond patient harm to include staff injury tracking and predictive staffing analytics.
Market Restraints
- Implementation cost structure:Multi-year deployment timelines and change management expenses strain rural and critical access hospital budgets.
- Data interoperability gaps:Fragmented EHR ecosystems and proprietary data formats create integration friction with legacy clinical systems.
- Vendor concentration risk:Dominant platform providers control critical safety databases, creating switching costs and long-term contract lock-in.
Strategic Opportunities
- Home-based care expansion:Remote patient monitoring and hospital-at-home programs require distributed incident capture and risk scoring tools.
- EU MDR pharmacovigilance:European medical device regulations are mandating post-market surveillance systems that mirror FDA Sentinel capabilities.
- AI-augmented event detection:Natural language processing of unstructured clinical notes is enabling automated harm identification before manual reporting.
Industry Challenges
- Clinical informatics talent scarcity:Health systems struggle to hire analysts capable of configuring predictive algorithms and interpreting risk scores.
- Legacy system integration complexity:Decades-old mainframe-based incident databases resist API connectivity and real-time data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Safety and Risk Management Solutions Market |
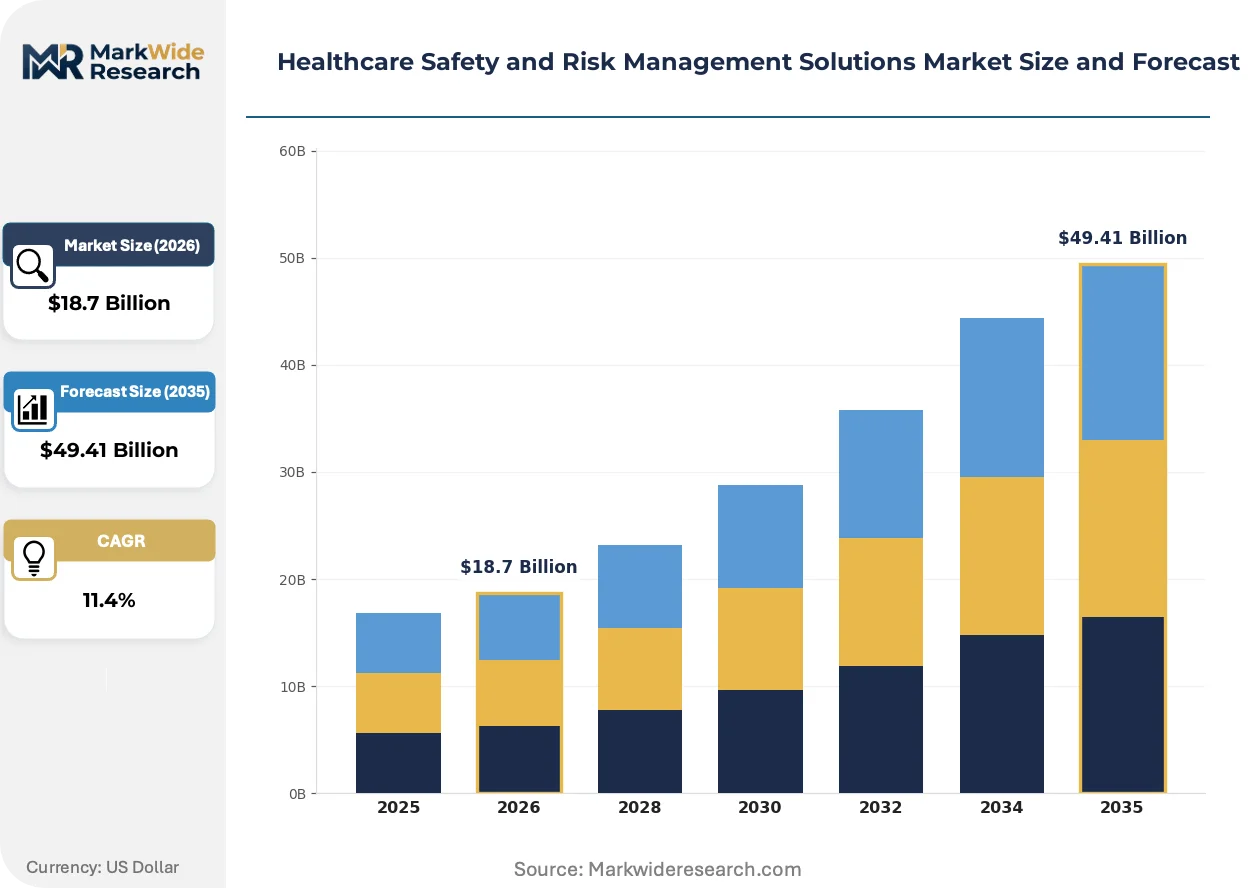
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incident Reporting Systems, Risk Assessment Tools, Compliance Management Solutions, Training Modules End User: Hospitals, Clinics, Long-term Care Facilities, Rehabilitation Centers Delivery Model: On-premise, Cloud-based, Hybrid, Mobile Applications Application: Patient Safety, Regulatory Compliance, Risk Analytics, Quality Improvement |
| Companies Covered | RLDatix, Riskonnect, Origami Risk, Quantros, symplr, Clarity Group, The Patient Safety Company, Performance Health Partners, Health Catalyst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Safety and Risk Management Solutions Market Shifts & Advancements
Real-time data architectures and predictive analytics are displacing retrospective reporting workflows across safety and risk management functions.
Natural language processing engines are integrating unstructured clinical documentation into structured risk databases. Large health systems in the United States and Germany are deploying these tools to auto-populate incident reports from nursing notes and physician handoffs. This compression of manual data entry is reallocating safety officer time toward root-cause analysis and prevention planning.
EU MDR post-market surveillance requirements are elevating documentation standards for medical device manufacturers and implanting hospitals. The regulation mandates systematic adverse-event tracking and periodic safety update reports that feed into EMA vigilance databases. Device-heavy surgical centers and implanting cardiologists face the steepest compliance burden and are prioritizing vendors with built-in MDR reporting modules.
Subscription-based risk intelligence services are unbundling from traditional software licenses. Group purchasing organizations and hospital alliances are pooling anonymized incident data to benchmark performance against peer institutions. This collective analytics model is most advanced in the United States, where consolidated delivery networks command sufficient scale to negotiate data-sharing agreements and demand predictive insights as a core contract deliverable.
Healthcare Safety and Risk Management Solutions Market Segmentation
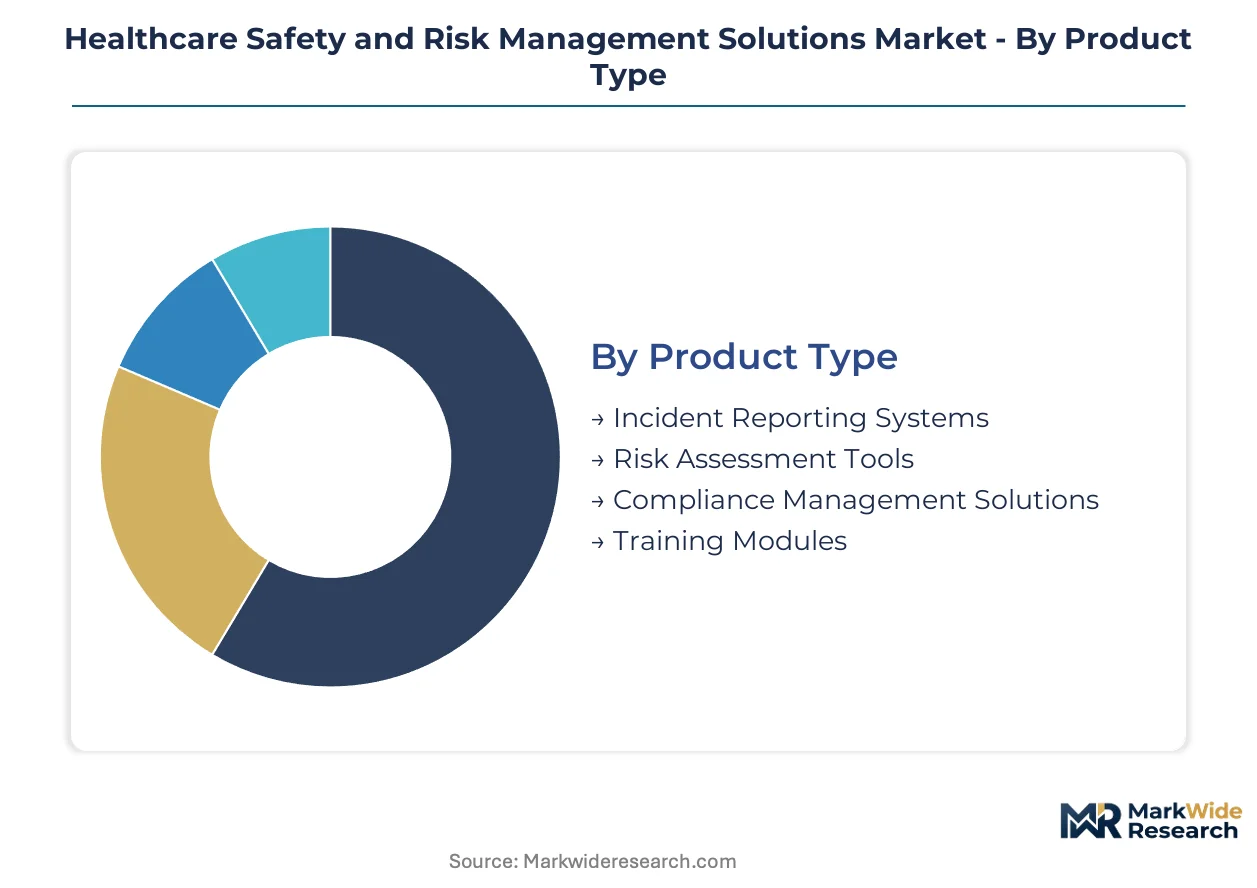
Segmentation in healthcare safety solutions reveals how regulatory pressure and infrastructure maturity shape procurement priorities. Hospital systems select platforms based on certification requirements, deployment complexity, and integration depth with existing clinical workflows.
Product Type:
FDA Sentinel pharmacovigilance mandates and EU MDR post-market surveillance rules create divergent certification burdens across product categories. Incident reporting systems face mandatory adverse-event documentation standards, while risk assessment tools must demonstrate algorithmic transparency for clinical decision support.
- Incident Reporting Systems:Core platforms capturing clinical events, near-misses, and operational hazards through structured forms and narrative fields. Demand concentrates in United States hospital systems upgrading from paper-based workflows to meet FDA Sentinel active surveillance requirements. OSHA workplace violence prevention rules are expanding scope to include staff injury tracking alongside patient harm.
- Risk Assessment Tools:Predictive algorithms scoring severity probability from structured and unstructured clinical data. German university hospitals and Japanese medical centers are deploying these for automated harm identification before manual reporting occurs. EMA transparency guidelines require explainable AI documentation for algorithmic risk scores used in patient care decisions.
- Compliance Management Solutions:Modular platforms mapping regulatory requirements to organizational policies and audit trails. HIPAA security rule compliance and state-level patient safety mandates drive procurement in US acute care networks.
- Training Modules:Digital curricula for workforce safety certification and incident response protocols. Critical access hospitals in rural United States leverage these for cost-effective staff education without dedicated safety officers.
Leading the category by volume: Incident Reporting Systems. Growing fastest: Risk Assessment Tools.
End User:
Scale of operations and regulatory exposure determine platform sophistication across customer types. Consolidated delivery networks demand enterprise-grade interoperability, while standalone facilities prioritize rapid deployment and minimal IT overhead.
- Hospitals:Multi-facility health systems with the highest regulatory exposure and incident volume. United States integrated delivery networks and German hospital federations drive demand for cloud-native platforms spanning acute, ambulatory, and post-acute environments. FDA Sentinel and EU MDR mandates force upgrades from passive to active surveillance infrastructure.
- Clinics:Outpatient and specialty practices with lighter incident volume but growing OSHA and state licensing requirements. Group purchasing organization contracts are compressing procurement cycles for mid-size ambulatory networks.
- Long-term Care Facilities:Nursing homes and assisted living operators facing CMS quality reporting mandates and state survey scrutiny. Workforce safety modules are expanding fastest here as OSHA workplace violence rules extend to residential care settings.
- Rehabilitation Centers:Post-acute facilities tracking patient falls, medication errors, and therapy-related adverse events. Medicare reimbursement penalties for preventable harm are elevating platform investment in US skilled nursing facilities.
Dominating procurement spend: Hospitals. Expanding most quickly: Long-term Care Facilities.
Delivery Model:
Capital availability and IT staffing levels create sharp segmentation between deployment approaches. Rural and critical access hospitals face implementation barriers that favor lighter delivery models.
- On-premise:Legacy installations in security-sensitive environments requiring air-gapped clinical data. Large United States health systems with existing data center infrastructure maintain these for EHR integration latency requirements.
- Cloud-based:SaaS platforms capturing fastest expansion as IT departments abandon capital-intensive installations. German and Japanese hospital alliances prioritize these for remote accessibility and faster deployment cycles.
- Hybrid:Configurations splitting sensitive data on-premise with analytics processing in cloud environments. HIPAA business associate agreement complexity drives this architecture in US multi-state health systems.
- Mobile Applications:Point-of-care incident capture and safety officer workflow tools. Home-based care expansion in United States and Japan is accelerating demand for distributed risk scoring on tablets and smartphones.
Highest revenue concentration: Cloud-based. Steepest expansion trajectory: Mobile Applications.
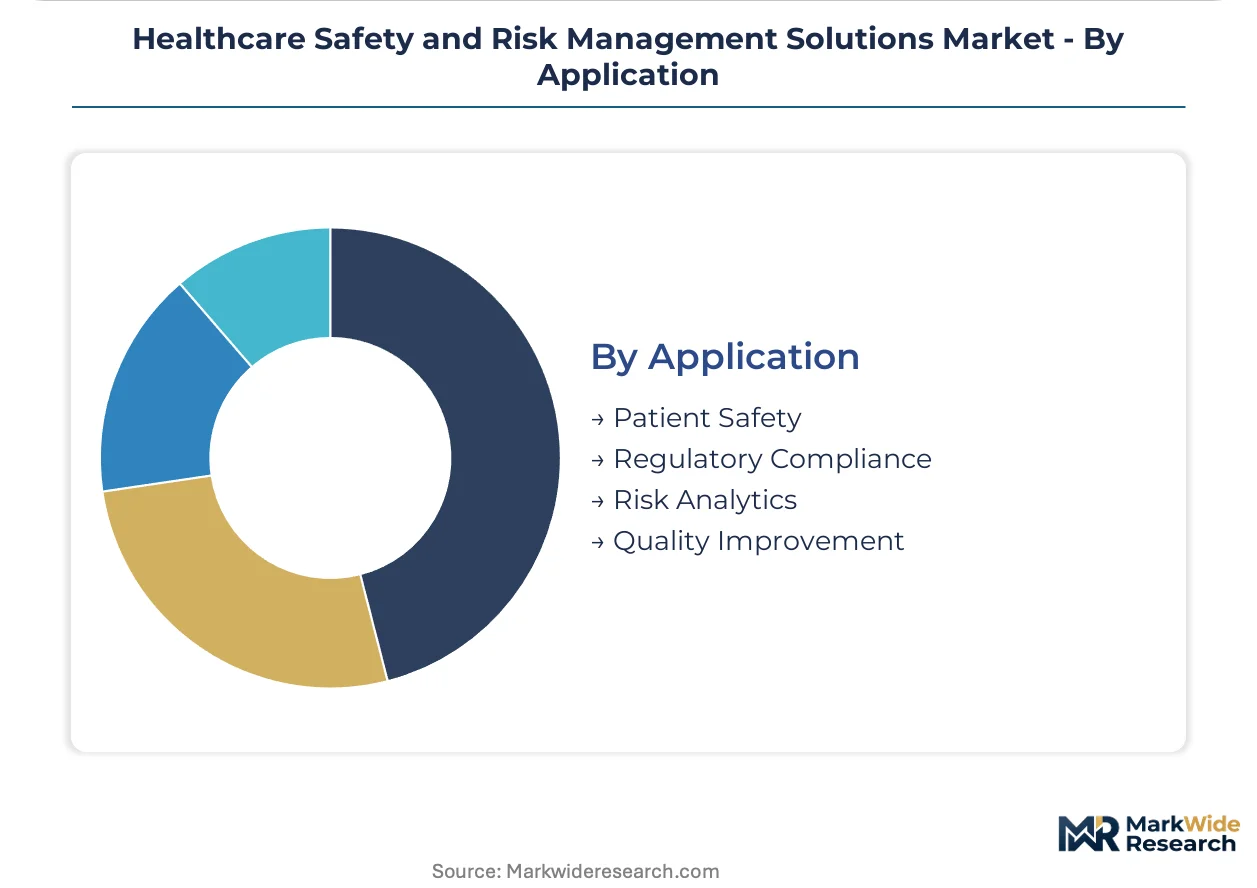
Application:
Functional priorities align with organizational risk profiles and payer contracting pressures. Medicare quality metrics and commercial insurance risk adjustment create divergent investment patterns.
- Patient Safety:Core applications preventing clinical harm through event detection, root-cause analysis, and prevention planning. Natural language processing of nursing notes and physician handoffs is auto-populating incident reports in leading United States health systems.
- Regulatory Compliance:Documentation and audit management for FDA, OSHA, EMA, and state survey requirements. EU MDR post-market surveillance mandates are elevating this priority for device-heavy surgical centers in Germany and implanting cardiologists in Japan.
- Risk Analytics:Predictive insights and peer benchmarking through pooled anonymized data. Group purchasing organizations in United States are unbundling these as subscription services from traditional software licenses.
- Quality Improvement:Continuous monitoring and intervention tracking tied to reimbursement metrics. CMS star ratings and value-based purchasing programs drive investment in US hospital systems.
Widest deployment base: Patient Safety. Gaining share fastest: Risk Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge corridor anchors North American demand for healthcare safety platforms, with Massachusetts General Brigham and Partners HealthCare driving enterprise-scale procurement of integrated incident reporting systems.
United States
Consolidated delivery networks in California and Texas are compressing vendor procurement cycles for cloud-native safety platforms. FDA Sentinel Initiative mandates force upgrades from passive reporting to active pharmacovigilance infrastructure. The Mayo Clinic in Rochester, Minnesota exemplifies multi-state deployment of predictive risk analytics across acute and ambulatory environments.
Germany
University hospital federations in Bavaria and North Rhine-Westphalia prioritize interoperability with legacy EHR systems. EU MDR post-market surveillance rules elevate documentation standards for device-heavy surgical centers. The Charité network in Berlin leads adoption of natural language processing for automated harm identification from clinical notes.
Japan
Metropolitan hospital alliances in Tokyo and Osaka demand remote accessibility for distributed risk scoring. PMDA pharmacovigilance guidelines align with FDA Sentinel capabilities for multinational device manufacturers. The University of Tokyo Hospital anchors enterprise deployments spanning implanting cardiology and orthopedic surgery units.
United Kingdom
NHS integrated care systems in London and Manchester consolidate safety platform procurement across former clinical commissioning groups. Care Quality Commission inspection frameworks intensify audit frequency for incident documentation. Guy's and St Thomas' NHS Foundation Trust exemplifies multi-site standardization of workforce safety modules.
Canada
Provincial health authorities in Ontario and British Columbia prioritize HIPAA-equivalent privacy architectures for cross-border data sharing. Health Canada post-market surveillance requirements mirror FDA active reporting standards. University Health Network in Toronto drives adoption of AI-augmented event detection for medication safety monitoring.
Healthcare Safety and Risk Management Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth and regulatory certification breadth. Enterprise-scale health systems demand modular platforms spanning acute, ambulatory, and post-acute environments, compressing procurement cycles toward consolidated vendor relationships. Two strategic archetypes dominate: vertically integrated suite providers controlling patient safety and workforce compliance modules, and specialized risk analytics firms deepening algorithmic transparency for EMA and FDA oversight regimes. Dominant competitive moves include strategic partnerships with group purchasing organizations and geographic expansion through cloud-native delivery models.
Within the integrated suite tier, RLDatix and symplr exemplify vendors anchoring multi-hospital deployments through backward integration into workforce compliance and patient safety modules. Riskonnect occupies a position among specialized risk analytics providers, representing the algorithmic transparency archetype required for European and North American pharmacovigilance frameworks.
| Leading Market Players |
|---|
| RLDatix |
| Riskonnect |
| Origami Risk |
| Quantros |
| symplr |
| Clarity Group |
| The Patient Safety Company |
| Performance Health Partners |
| Health Catalyst |
| Others |
Supply & Pricing Matrix
Clinical informatics specialists concentrated in Boston and the San Francisco Bay Area command salary premiums that widen pricing spreads between enterprise suites and commodity point solutions. Labor-cost differentials between these talent hubs and secondary markets feed directly into SaaS pricing tiers, with vendors embedding implementation service costs into subscription rates.
Pricing Analysis
Value-based pricing anchored to prevented patient harm incidents dominates enterprise contracting. Three-tier pricing structure across premium, standard, and economy levels separates FDA Sentinel-certified platforms from basic incident logging tools. Certification level and algorithmic transparency documentation drive the widest price spreads. Pricing pressure stems from group purchasing organization consolidation negotiating pooled analytics access. Critical access hospitals in rural United States exhibit highest price sensitivity; integrated delivery networks with risk-based contracts show lowest.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale data center operators in the United States, Germany, and Japan. Natural language processing engines and predictive algorithm libraries feed from specialized AI/ML development shops in Tel Aviv and Bangalore. Single-source vulnerability concentrates in API middleware connecting to legacy EHR systems. Distribution runs through direct enterprise sales teams and group purchasing organization channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
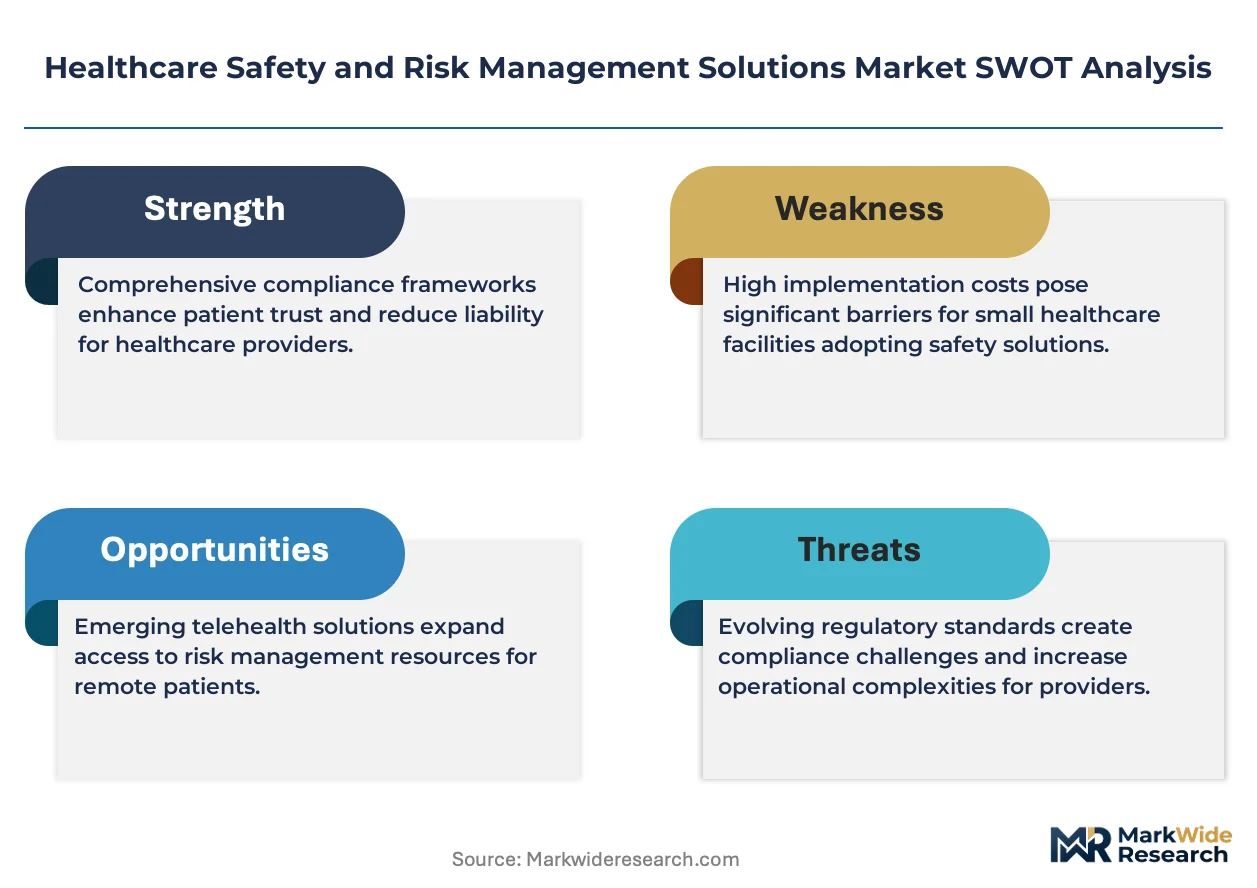
Hospital system consolidation into integrated delivery networks is compressing vendor counts, forcing point-solution providers toward acquisition or exit. FDA Sentinel and EU MDR compliance burdens favor scaled platforms with regulatory certification depth.
For Market Incumbents: Lock in multi-hospital deployments through backward integration into workforce safety modules that satisfy OSHA workplace violence mandates. Deepen algorithmic transparency documentation for EMA oversight regimes to defend margin position against specialized risk analytics entrants. Channel control through group purchasing organization partnerships remains the critical defensive lever.
For New Entrants and Emerging Players: Cloud-native distribution partnerships with hospital-at-home platform vendors open white-space access in remote patient monitoring risk scoring. Long-term care facilities face expanding OSHA compliance scope with underserved vendor options. Target these operators through mobile-first incident capture tools that bypass IT department procurement cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized risk analytics firms given EU MDR post-market surveillance mandate acceleration. Long-term viability over the next decade hinges on cross-border regulatory mapping capabilities. Watch FDA Sentinel initiative expansion into medical device surveillance as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Sentinel Integration | Active pharmacovigilance infrastructure meets FDA adverse-event surveillance mandates for multi-hospital systems. |
| CE Marking Pathway | EU MDR post-market surveillance modules unlock German and French surgical center procurement cycles. |
| Hospital System Partnership | Integrated delivery network contracts compress sales cycles and anchor recurring revenue streams. |
| Software Companion Development | NLP engines auto-populating incident reports from nursing notes reduce safety officer manual entry burden. |
| Reimbursement Strategy | CMS quality metrics alignment positions platforms for value-based purchasing program participation. |
Research Methodology
Independent corroboration across hospital chief medical officers, GPO contracts managers, biomedical informatics directors, and FDA regulatory consultants underwrites the qualitative findings. Primary interviews with safety officers and risk management executives combined with secondary validation from FDA Sentinel program documentation, CMS Medicare hospital compare data, and EU MDR implementation guidance. Bottom-up deployment sizing and top-down health system IT budget analysis triangulate market estimates.
Comparable-period anchoring to historical SaaS adoption curves and regulatory mandate implementation timelines shaped the projection horizon. The analytical framework models segmentation across product type, end user, delivery model, and application with geographic regulatory cluster overlays. CAGRs derive from vendor revenue trajectory analysis and health system procurement pipeline assessment. Forecast inputs incorporate FDA enforcement priority shifts and EU MDR audit frequency escalation patterns.
The model holds under stable regulatory enforcement intensity; deviation in FDA Sentinel mandate scope expansion or EU MDR penalty escalation would shift deployment timelines. Forecasts reflect these base-condition assumptions with acknowledged sensitivity to clinical informatics talent availability constraints. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
Surety Market
Risk Management and Compliance
Global Credit Risk Rating Software Market
Risk Management and Compliance
Travel Risk Management Services Market
Risk Management and Compliance
Stress Testing Services Market
Risk Management and Compliance
Digital Risk Management Market
Risk Management and Compliance
Global Backstop Netting Systems Market
Risk Management and Compliance
Global Patient Safety and Risk Management Softwares Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
China Enterprise Risk Management Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Medical Device Cyber Risk Quantification Market