
 Global Embedded Systems Market | 2026-2036
Global Embedded Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embedded Systems Market Analysis
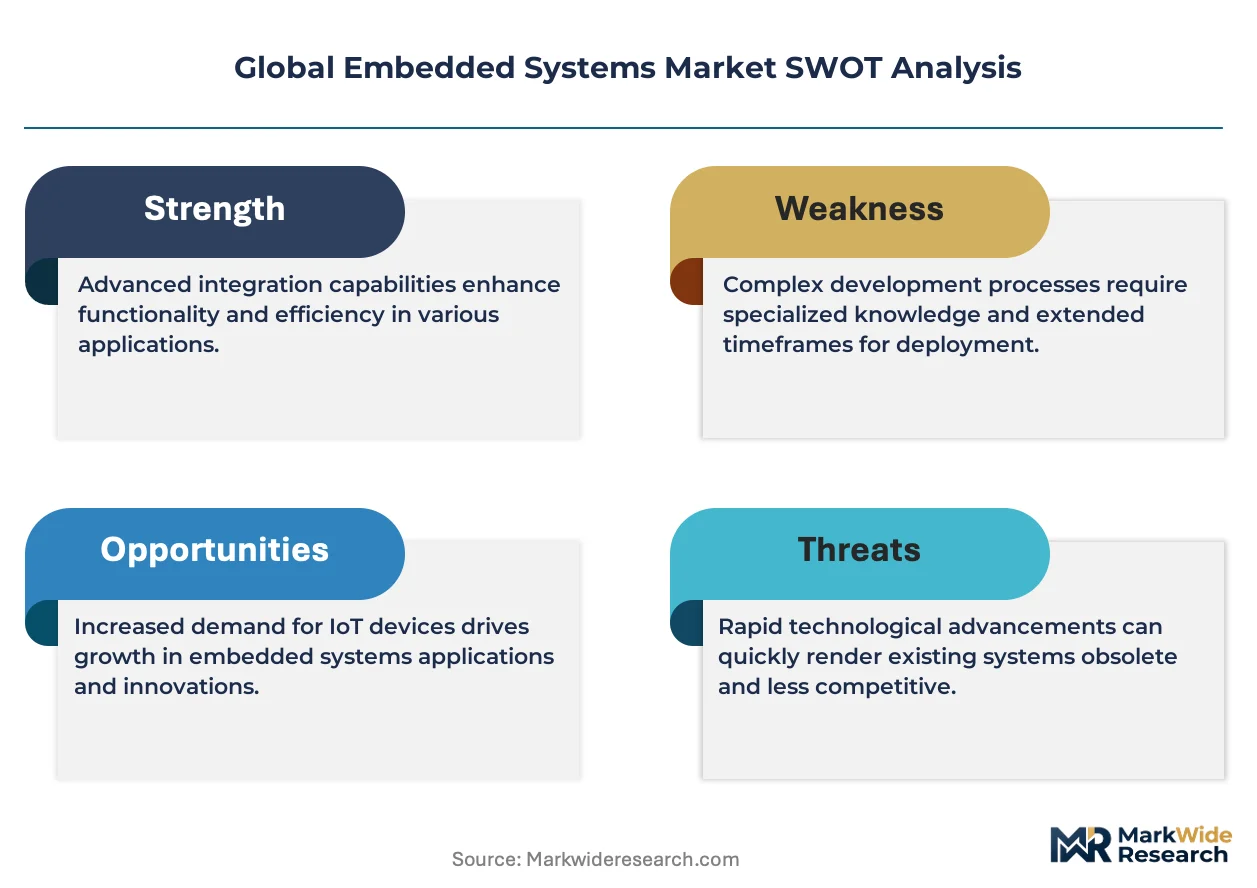
Automotive OEMs is collapsing the traditional consumer-electronics-first demand hierarchy that long dominated embedded semiconductor procurement. NXP Semiconductors anchors its position through captive automotive-grade microcontroller fabs across Europe and Asia. Texas Instruments differentiates by sustaining one of the broadest analog-integrated embedded portfolios in industrial automation. Intel Corporation competes aggressively in edge-AI system-on-chips, leveraging x86 architecture familiarity to penetrate medical imaging subsystems.
Embedded systems integrate dedicated computing hardware with tightly coupled software to perform predefined control, monitoring, or signal-processing functions within larger electromechanical assemblies, typically operating under strict real-time constraints with power budgets measured in milliwatts to watts. These systems serve as the invisible computational substrate powering everything from antilock braking modules to insulin pumps, where deterministic response latency matters more than raw throughput. Microcontrollers retain the largest revenue footprint across end-use verticals, though FPGAs capture disproportionate margin pools in aerospace and defense applications requiring field-reconfigurable logic. IoT-enabled embedded platforms represent the fastest-expanding technology segment, driven by sensor fusion demands in smart home and wearable device ecosystems where wireless connectivity stacks merge with local inference engines.
FDA software-as-medical-device guidelines, the EU AI Act risk-classification framework, and ISO 26262 automotive functional-safety standards collectively elevate validation costs and extend design-in cycles for new embedded platforms. REACH substance restrictions and RoHS compliance mandates further constrain component sourcing across European supply chains, favoring suppliers with pre-certified material traceability systems. Stakeholders must monitor how the EU Green Deal's embodied-carbon reporting requirements propagate downstream into embedded hardware procurement specifications, as this will reshape supplier qualification criteria faster than pure performance benchmarks.
Market Dynamics
Automotive OEM procurement of AI-enabled system-on-chips is collapsing the traditional consumer-electronics-first demand hierarchy that long dominated embedded semiconductor allocation.
Growth Catalysts
- EU AI Act Risk Classification:Mandatory conformity assessments for safety-critical firmware are accelerating design-in cycles for automotive-grade microcontrollers in Germany and France.
- Sensor Fusion Architectures:Smart home and wearable ecosystems demand wireless connectivity stacks merged with local inference engines, expanding addressable hardware content per device.
- Japan:METI subsidies for autonomous vehicle testing infrastructure are concentrating tier-one supplier R&D investment around Tokyo and Nagoya design centers.
Market Restraints
- Automotive-Grade Silicon Capacity:Foundry allocation for AEC-Q100 qualified processes concentrates in Taiwan and South Korea, creating single-source exposure for European module makers.
- REACH Substance Restrictions:ECHA compliance mandates constrain solder alloy and substrate material sourcing across European supply chains, elevating qualification costs.
- Functional Safety Validation:ISO 26262 ASIL-D certification timelines extend 18-24 months for new microcontroller platforms, compressing product refresh windows.
Strategic Opportunities
- Medical Imaging Subsystems:FDA software-as-medical-device pathways create first-mover advantage for edge-AI system-on-chips with deterministic latency profiles.
- India:PLI scheme incentives for electronics manufacturing are attracting embedded module assembly capacity away from traditional China-centric sourcing.
- FPGA-Reconfigurable Logic:Convergence of adaptive computing with AI inference engines opens aerospace and defense margin pools previously captured by fixed-function ASICs.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time operating system expertise and bare-metal programming skills concentrate among aging engineer cohorts in Germany and Japan.
- Legacy System Integration:Brownfield industrial automation deployments require protocol translation layers that inflate BOM cost and power consumption.
- CSRD Carbon Reporting:EU Green Deal embodied-carbon disclosure mandates force supplier qualification criteria reshaping faster than performance benchmarking cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embedded Systems Market |
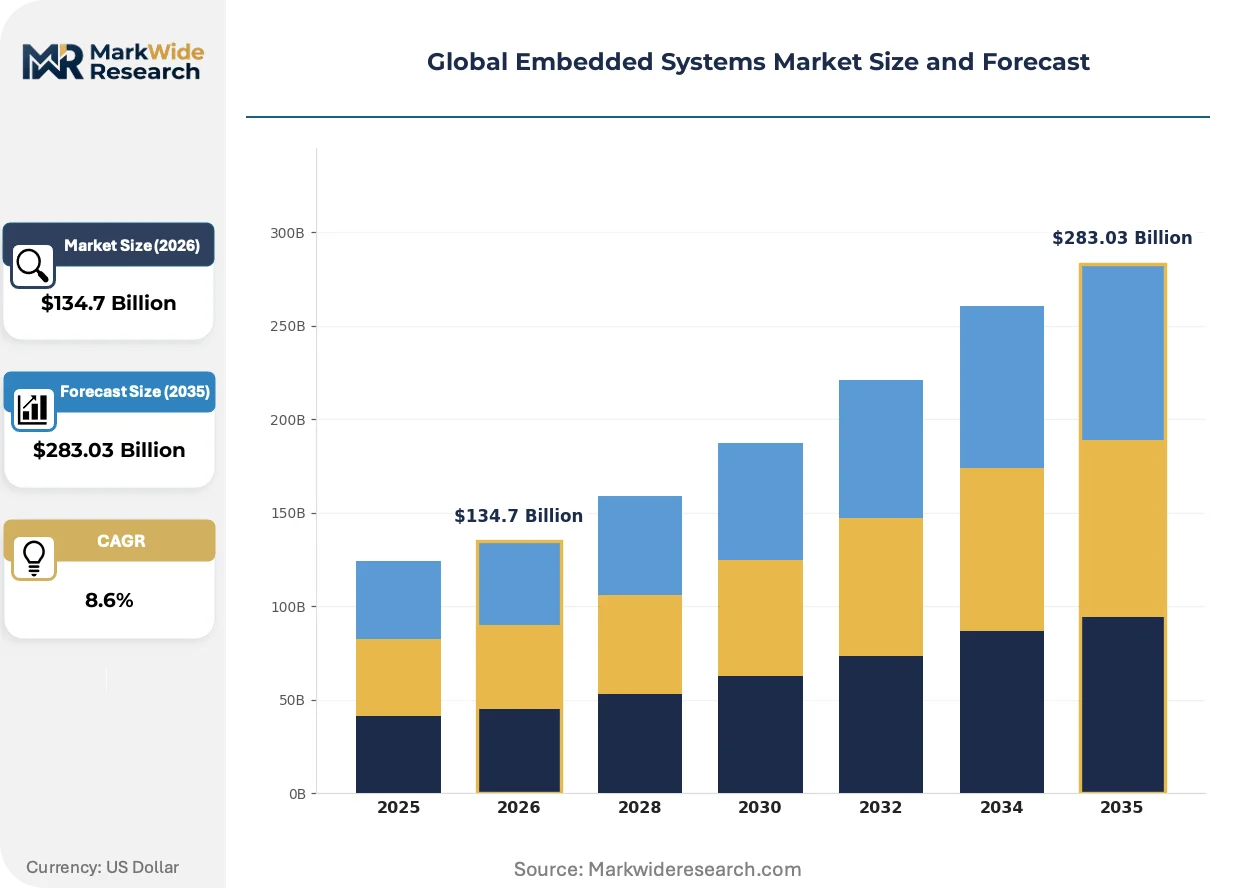
| Market Size in 2026 | $134.7 Billion |
| Market Size in 2035 | $283.03 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, DSPs, FPGAs, System-on-Chips Technology: IoT, AI, Machine Learning, Machine Vision End User: Consumer Electronics, Automotive, Healthcare, Industrial Automation Application: Smart Home, Wearable Devices, Medical Devices, Surveillance Systems |
| Companies Covered | NXP Semiconductors, Intel Corporation, Texas Instruments, Renesas Electronics Corporation, STMicroelectronics, Infineon Technologies AG, Microchip Technology, Qualcomm Incorporated, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embedded Systems Market Emerging Trajectories
RISC-V open instruction set architectures are eroding ARM's historical licensing dominance across cost-sensitive IoT endpoints and academic research pipelines.
Edge-native neural processing units with sub-watt thermal envelopes are supplanting cloud-tethered inference for predictive maintenance and acoustic anomaly detection. Automotive tier-one suppliers in Stuttgart and Detroit are qualifying these devices for 10-year lifecycle commitments. The shift is compressing data egress costs while elevating on-device memory requirements.
REACH substance restrictions and RoHS recast directives from ECHA are forcing solder alloy reformulations and substrate material substitutions across European automotive supply chains. Module makers in Bavaria and Baden-Württemberg are absorbing six-month requalification delays. Medical device OEMs face parallel FDA biocompatibility reviews that synchronize with EU MDR technical documentation.
Outcome-based hardware service contracts are displacing component spot purchasing in industrial automation accounts. German automotive OEMs now specify guaranteed uptime clauses for embedded controller fleets rather than per-unit procurement. Japanese machine tool builders in Aichi Prefecture have adopted similar total-cost-of-ownership frameworks that bundle predictive analytics with silicon supply.
Global Embedded Systems Market Segmentation
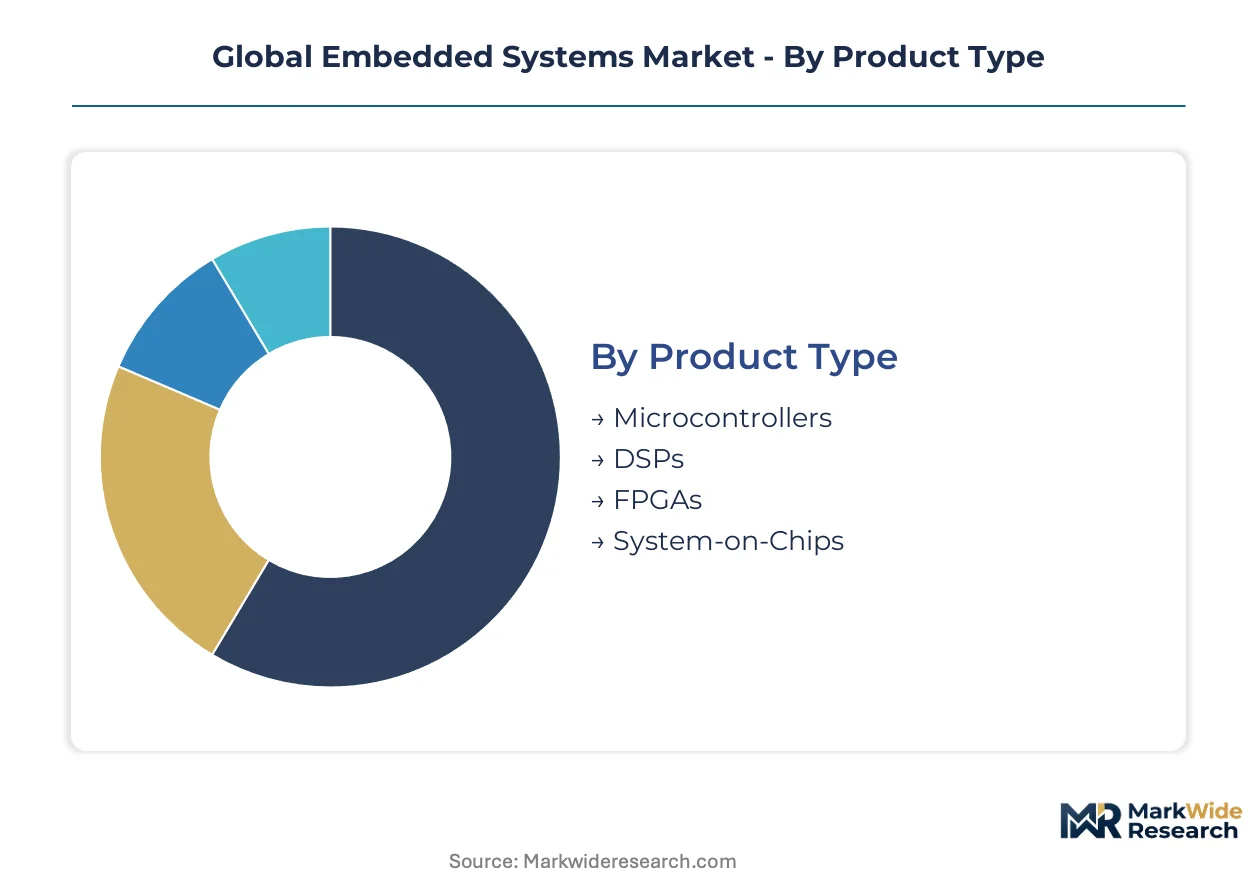
Embedded systems fragment across four intersecting dimensions where product architecture, intelligence layer, buyer industry, and deployment context each reshape supplier margin structures. Procurement patterns diverge sharply between deterministic control workloads and inference-heavy AI platforms.
Product Type:
FPGAs face the most acute substitution pressure as adaptive computing platforms encroach on their historical aerospace and defense strongholds.
- Microcontrollers:These integrated processors combine CPU core, memory, and peripherals on single die with power budgets under one watt. Automotive OEMs in Germany and Japan concentrate procurement for powertrain and chassis control modules where ISO 26262 ASIL-D certification gates supplier qualification.
- System-on-Chips:Heterogeneous integration of application processors, neural accelerators, and connectivity subsystems enables autonomous drive platforms and medical imaging subsystems. NXP Semiconductors and Qualcomm anchor supply through captive automotive-grade fabs.
- DSPs:Specialized arithmetic units optimized for real-time signal processing in audio codecs and radar front-ends.
- FPGAs:Field-reconfigurable logic arrays retain aerospace margin pools but face erosion from software-programmable AI accelerators.
Microcontrollers retain volume leadership; System-on-Chips holds the steepest expansion curve.
Technology:
Cost tier stratification separates legacy connectivity stacks from premium inference engines commanding 3-5x silicon area premiums.
- AI:Neural processing units with deterministic latency profiles penetrate FDA-regulated medical devices and NHTSA-monitored automotive platforms. Edge-native sub-watt thermal envelopes displace cloud-tethered inference in predictive maintenance applications.
- IoT:Wireless connectivity stacks merged with sensor fusion demand expand hardware content per smart home and wearable device. METI subsidies in Japan concentrate tier-one supplier R&D investment around Tokyo design centers.
- Machine Learning:TinyML frameworks compress trained models to kilobyte footprints for microcontroller-class endpoints.
- Machine Vision:Parallel processing architectures accelerate image recognition pipelines in surveillance and industrial inspection.
IoT retains volume leadership; AI holds the steepest expansion curve.
End User:
Application maturity diverges between saturated consumer electronics and regulated healthcare where validation timelines extend procurement cycles.
- Automotive:OEM procurement of AI-enabled platforms collapses traditional consumer-electronics-first demand hierarchies. EU AI Act risk classification and ISO 26262 functional-safety standards elevate firmware validation costs.
- Healthcare:FDA software-as-medical-device pathways and EU MDR technical documentation synchronize biocompatibility reviews with embedded hardware qualification. Insulin pumps and diagnostic imaging subsystems demand deterministic response latency.
- Industrial Automation:Brownfield deployments require protocol translation layers inflating BOM cost and power consumption.
- Consumer Electronics:Price-sensitive volumes concentrate in smartphone peripheral controllers and white-goods motor drives.
Automotive retains volume leadership; Healthcare holds the steepest expansion curve.
Application:
Supply concentration clusters around German automotive hubs and Japanese machine tool centers where outcome-based service contracts displace component spot purchasing.
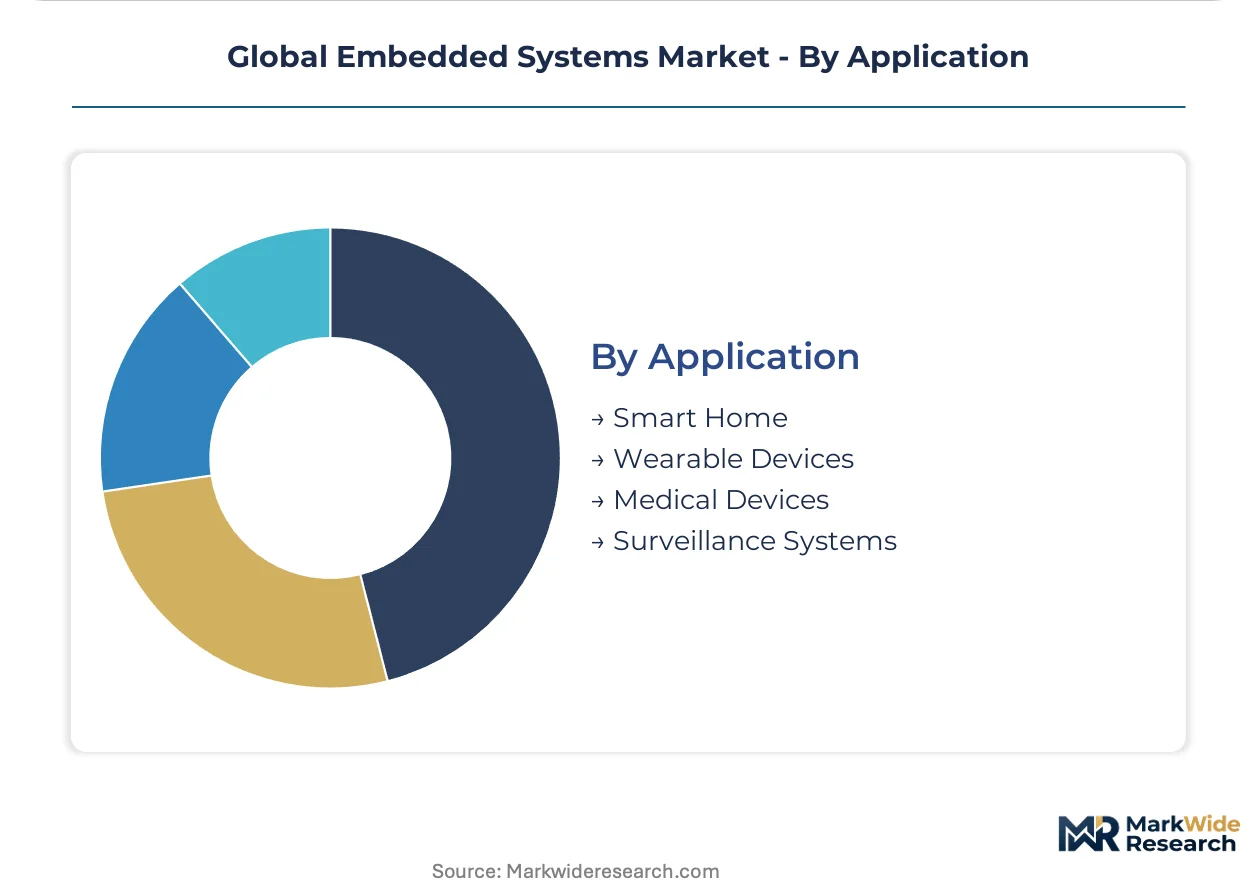
- Medical Devices:Software-as-medical-device regulatory pathways in the US and EU create first-mover advantage for edge-AI platforms with deterministic latency. ISO 14971 risk management and IEC 62304 software lifecycle standards gate market entry.
- Smart Home:Sensor fusion architectures merge wireless connectivity with local inference engines. REACH substance restrictions and RoHS recast directives from ECHA force solder alloy reformulations across European supply chains.
- Wearable Devices:Milliwatt power budgets constrain processor selection to ultra-low-voltage microcontroller variants.
- Surveillance Systems:Edge-based video analytics reduce data egress costs while elevating on-device memory requirements.
Smart Home retains volume leadership; Medical Devices holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Basel rail freight corridor underwrites Europe's embedded hardware distribution, while the Kaohsiung-Tokyo maritime lane secures Taiwan's foundry-to-OEM silicon pipeline for automotive module makers.
United States
Automotive OEMs in Detroit and Austin are accelerating procurement of AI-enabled system-on-chips for autonomous drive platforms. FDA software-as-medical-device pathways tighten validation timelines for safety-critical firmware in medical imaging subsystems. Boston and San Diego design centers concentrate edge-AI R&D investment for deterministic latency applications.
Germany
EU AI Act risk-classification mandates are accelerating conformity assessments for automotive-grade microcontrollers in Stuttgart and Munich. ISO 26262 ASIL-D certification gates supplier qualification for powertrain control modules. Bavaria and Baden-Württemberg host tier-one supplier clusters absorbing REACH substance restriction compliance costs.
Japan
METI subsidies for autonomous vehicle testing infrastructure are concentrating R&D investment around Tokyo and Nagoya design centers. JIS standards govern industrial automation embedded controller specifications for machine tool builders in Aichi Prefecture. Real-time operating system expertise concentrates among aging engineer cohorts in Osaka and Yokohama.
South Korea
Foundry allocation for AEC-Q100 qualified processes concentrates in Hsinchu-linked Korean fabrication partnerships, creating single-source exposure for European module makers. MFDS medical device regulations synchronize with FDA pathways for edge-AI diagnostic platforms. Seoul Capital Area design centers specialize in sub-watt neural processing units for wearable ecosystems.
India
PLI scheme incentives for electronics manufacturing are attracting embedded module assembly capacity away from traditional China-centric sourcing. BIS certification requirements govern industrial automation controller imports for Gujarat and Maharashtra manufacturing hubs. Bangalore and Hyderabad design centers concentrate IoT-enabled platform development for smart home applications.
Global Embedded Systems Market Vendor Landscape
Listed leaders compete with private specialists across semiconductor fabrication and intellectual property licensing dimensions. The vendor base stratifies into captive automotive-grade foundry operators, broad analog-integrated portfolio holders, and edge-AI system-on-chip architects. Three archetypes dominate: European automotive-grade microcontroller specialists, US industrial automation analog incumbents, and Asia-Pacific foundry-dependent fabless designers. Competitive moves concentrate on captive fab capacity expansion and strategic patent licensing for RISC-V architectures.
Within the automotive-grade tier, NXP Semiconductors and Infineon Technologies AG exemplify European captive-fab strategies, while Texas Instruments occupies a position anchoring US industrial automation analog integration. These three represent divergent approaches to regulatory-compliant design center concentration across Germany, Japan, and the United States.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Intel Corporation |
| Texas Instruments |
| Renesas Electronics Corporation |
| STMicroelectronics |
| Infineon Technologies AG |
| Microchip Technology |
| Qualcomm Incorporated |
| Analog Devices |
| Others |
Supply Flow & Price Mechanics
Eighteen-month microcontroller qualification timelines concentrate pricing power with AEC-Q100 certified foundry operators in Taiwan and South Korea, while European module makers absorb REACH compliance premiums that widen spreads between automotive-grade and industrial-tier silicon.
Pricing Analysis
Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-safety-rated microcontroller tiers separates automotive OEM procurement from industrial automation and consumer electronics buyers. Price differentiation hinges on ISO 26262 certification grade and volume scale, with 100,000-unit annual commitments unlocking 15-20 point discounts. Cost compression in the non-certified tier is intensifying because RISC-V IP licensing erodes ARM royalty structures. Consumer electronics buyers exhibit highest price sensitivity; medical device OEMs show lowest due to FDA validation switching costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive tier-one procurement, though METI-subsidized Japanese suppliers maintain strategic stockpiles of AEC-Q100 qualified wafers against foundry allocation volatility. Manufacturing concentrates in Taiwan, South Korea, and Germany. Silicon feedstock draws from polysilicon refineries in China and high-purity quartz mines in the United States. Single-source vulnerability permeates EU automotive supply chains dependent on Hsinchu-linked fabrication partnerships. Distribution runs through Rotterdam-Basel rail corridors for European module assembly and Kaohsiung-Tokyo maritime lanes for Asian foundry output.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory divergence between FDA software-as-medical-device pathways and EU AI Act risk classifications creates specialized design-in niches unreachable by standardized product portfolios.
For Market Incumbents: Shield automotive-grade margin pools by accelerating captive fab capacity expansion in Germany and Japan before RISC-V ecosystem maturity erodes ARM licensing leverage. Prioritize ISO 26262 ASIL-D certification investment to extend qualification-driven switching costs against adaptive computing substitutes. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized module assembly corridors, where BIS certification requirements lag EU and US regulatory complexity. Target medical imaging subsystems in South Korea and the United States where MFDS-FDA pathway synchronization creates first-mover windows for edge-AI deterministic latency platforms. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with embedded controller divisions orphaned by parent-level software pivot strategies. Five-to-ten year viability favors suppliers with pre-certified material traceability systems aligned to EU Green Deal embodied-carbon disclosure mandates. Watch CSRD reporting threshold propagation as the inflection signal reshaping supplier qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fab Capacity Expansion | Secures AEC-Q100 qualified process allocation for automotive OEMs in Stuttgart and Detroit. |
| RISC-V Architecture Licensing | Erodes ARM royalty structures across cost-sensitive IoT endpoint categories. |
| ISO 26262 ASIL-D Certification | Gates supplier qualification for powertrain control modules in Germany and Japan. |
| EU Green Deal Alignment | Pre-positions material traceability systems ahead of CSRD procurement specification changes. |
| Edge-AI Platform Development | Captures FDA software-as-medical-device pathway advantages in Boston and San Diego design centers. |
Methodological Framework
A standing panel of automotive platform engineers, industrial automation procurement leads, medical device regulatory affairs specialists, and semiconductor foundry planning officers provided ongoing calibration against primary fieldwork. Secondary validation drew from FDA 510(k) filings, ECHA REACH substance restriction updates, SEC 10-K semiconductor segment disclosures, and IHS Markit vehicle production databases. Bottom-up microcontroller unit shipment estimates triangulated against top-down OEM electronics content spending across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including foundry utilization reports, AEC-Q100 qualification databases, and EU MDR technical documentation filings. The analytical framework modeled product type, technology layer, end-use vertical, and application context across the projection horizon. CAGRs derived from regression analysis of historical procurement cycles, regulatory implementation timelines, and technology substitution elasticities. Industry-specific inputs included ISO 26262 certification pipeline data and METI subsidy allocation trajectories.
Material uncertainties — foundry allocation shocks, REACH substance list expansion, EU AI Act enforcement variance — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization stability and automotive platform electrification cadence. Revision becomes warranted when AEC-Q100 qualified process concentration crosses geopolitical risk thresholds or when CSRD carbon reporting mandates accelerate faster than supplier requalification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Systems and Devices
Electronic Tongue Market
Electronic Systems and Devices
Global Broadcast Switcher Market
Electronic Systems and Devices
SONAR System Market
Electronic Systems and Devices
Global Electronic Contract Assembly Market
Electronic Systems and Devices
Nanoelectromechanical Systems (NEMS) Market
Electronic Systems and Devices
Microelectromechanical System (MEMS) Market
Electronic Systems and Devices
Sound Reception System Market
Electronic Systems and Devices
Cold Start System Market
Electronic Systems and Devices
Electronic Prototyping Market
Electronic Systems and Devices
Global Automotive Electronic Brake System Market
Electronic Systems and Devices
Pre Terminated Systems Market
Electronic Systems and Devices
Embedded Computing Systems Market
Electronic Systems and Devices
Resist Strip System Market
Electronic Systems and Devices
Hi-Fi System Market
Electronic Systems and Devices
Saudi Arabia Wearable and Audio Devices Market
Electronic Systems and Devices
Embedded Controllers Market