
 Microhardness Testing System Market | 2026-2036
Microhardness Testing System Market Size, Share, and Industry Trends Forecast 2026-2036
Microhardness Testing System Market Foresight
Germany's precision instrumentation cluster is tilting toward higher-throughput microhardness platforms for automotive and aerospace supply chains. Mitutoyo Corporation leverages its metrology heritage to dominate optical measurement integration across Asian manufacturing hubs. ZwickRoell sustains competitive positioning through deep specialization in materials testing automation and German engineering standards. INNOVATEST anchors European demand with dedicated hardness testing portfolios that emphasize software-driven indentation analysis.
A microhardness testing system applies controlled force through a precision indenter to measure material resistance at microscopic scales, typically generating impressions between 1 and 1000 gf for subsequent diagonal or crack-length measurement under calibrated optical magnification. These systems serve primary industrial purposes in quality assurance, failure analysis, and process validation where bulk hardness testing destroys functional components or misses surface treatment effects. Vickers and Knoop product types command the largest installed base due to geometric self-similarity enabling consistent hardness numbers across force ranges, while automated technology segments attract replacement demand as laboratories seek operator-independent reproducibility. Optical technology persists in cost-sensitive education and small-lot manufacturing settings where capital constraints outweigh throughput requirements.
ASTM International governs indentation procedures through E384 and E92 standards that specify indenter geometry, force calibration, and verification intervals for laboratory accreditation. ISO 6507 and ISO 4545 provide parallel frameworks recognized under EU machinery directives and national metrology institute traceability requirements. FDA device manufacturing regulations and FAA material certification protocols in the United States further embed microhardness verification into supplier qualification workflows. Stakeholders must monitor evolving harmonization between regional standards bodies and automation protocol interoperability as laboratories consolidate multi-site data architectures.
Market Dynamics
ASTM E384 and ISO 6507 certification mandates are forcing metallurgy laboratories to retire manual indenters, compressing replacement cycles and tilting procurement toward automated Vickers platforms with integrated optical analysis.
Growth Catalysts
- Automotive OEM captive laboratories:Germany's precision engineering corridor drives demand for high-throughput microhardness verification of surface-treated powertrain components.
- FAA material certification protocols:Aerospace supplier qualification workflows in the United States mandate documented hardness traceability for flight-critical alloys.
- ISO 6507 harmonization:EU machinery directives embedding this standard accelerate laboratory accreditation investments across continental testing facilities.
Market Restraints
- Precision indenter supply concentration:Diamond pyramid indenter fabrication concentrates among specialized German and Japanese suppliers, creating single-source vulnerability.
- Optical calibration equipment costs:Certified reference blocks and interferometric verification systems require substantial capital outlay for laboratory accreditation.
- Manual system residual value:Secondary market liquidity for displaced optical microhardness units delays replacement decisions at budget-constrained institutions.
Strategic Opportunities
- India BIS laboratory certification expansion:Domestic manufacturing incentives under PLI schemes are driving captive metallurgy investments at automotive and defense suppliers.
- Additive manufacturing qualification:Powder-bed fusion and directed energy deposition processes require novel microhardness protocols for as-built lattice structures.
- Cloud-based indentation data architectures:Multi-site manufacturers seek centralized hardness databases linking production facilities to central quality systems.
Industry Challenges
- Metallographer skill scarcity:Automated platform operation still requires trained personnel for sample preparation and fracture interpretation, constraining throughput at smaller laboratories.
- Legacy LIMS integration complexity:Proprietary data formats from established hardness equipment vendors resist seamless connection to modern laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microhardness Testing System Market |
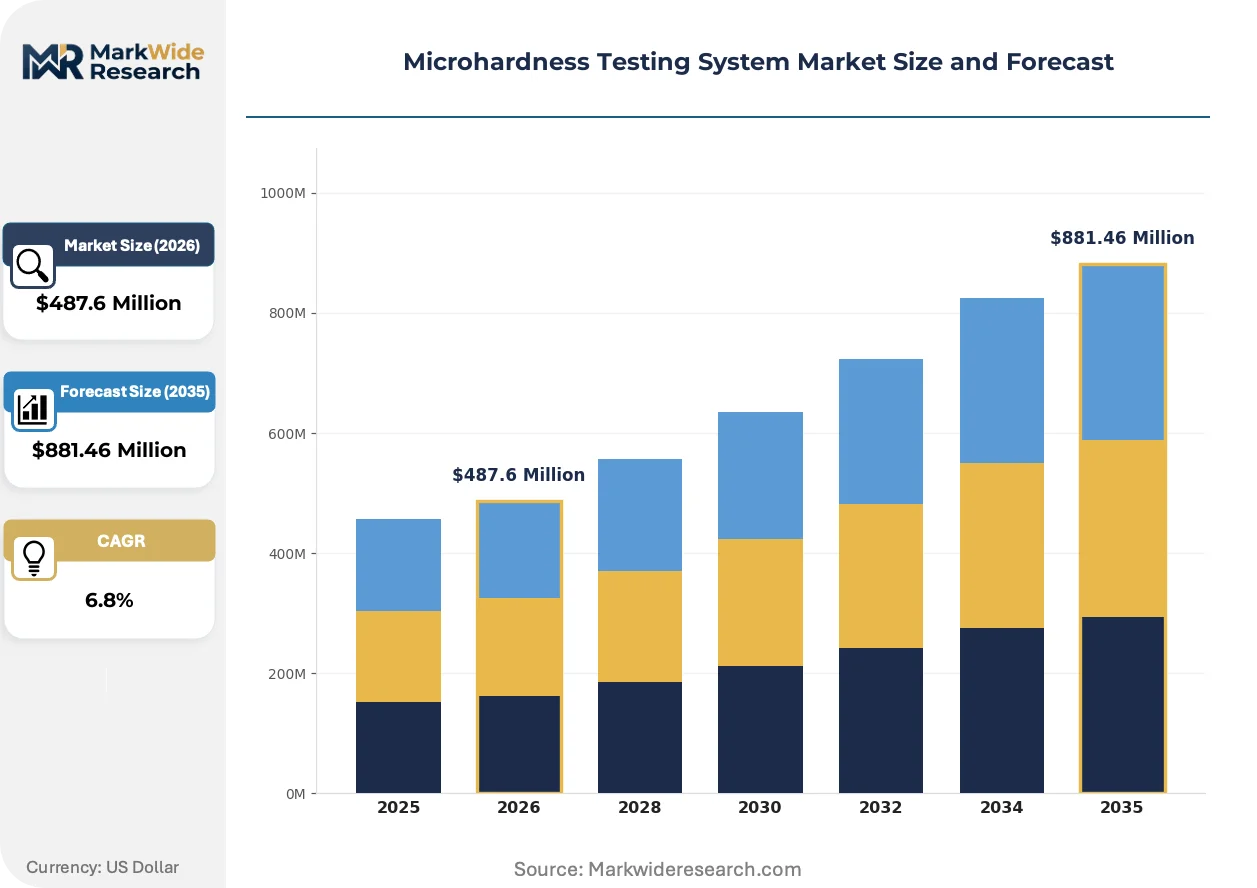
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knoop, Vickers, Mohs, Brinell Technology: Optical, Digital, Manual, Automated End User: Manufacturing, Research Labs, Quality Control, Education Application: Metallurgy, Ceramics, Polymer Testing, Coatings |
| Companies Covered | Mitutoyo Corporation, Buehler, ZwickRoell, Struers, LECO Corporation, Shimadzu Corporation, INNOVATEST, Future-Tech Corp., EMCO-TEST Prufmaschinen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microhardness Testing System Market Shifts & Advancements
Instrumentation convergence is compressing the boundary between indentation and surface characterization, with manufacturers embedding spectroscopic and topographic modules within single platforms.
Deep learning-enabled indentation imaging is collapsing operator-dependent measurement variance by automating diagonal detection and crack-length analysis in real-time. Automotive and aerospace first-tier suppliers in Germany and Japan are deploying these systems for 24-hour production-line verification. The technology is collapsing the traditional separation between quality control and materials research functions within single laboratory footprints.
REACH substance restrictions on certain polishing compound chemistries are forcing metallography laboratories to reformulate sample preparation workflows. ECHA's evolving candidate list now captures several traditional grinding suspension additives used in hardness specimen finishing. German automotive testing facilities are accelerating validation of alternative chemistries to maintain accreditation continuity.
Consolidated procurement through corporate metrology frameworks is displacing standalone laboratory purchasing authority. Multi-site manufacturers in the United States now mandate centralized vendor selection for hardness testing equipment across distributed quality networks. This pattern concentrates contract value with platform vendors capable of unified service coverage and spare part logistics.
Microhardness Testing System Market Segmentation
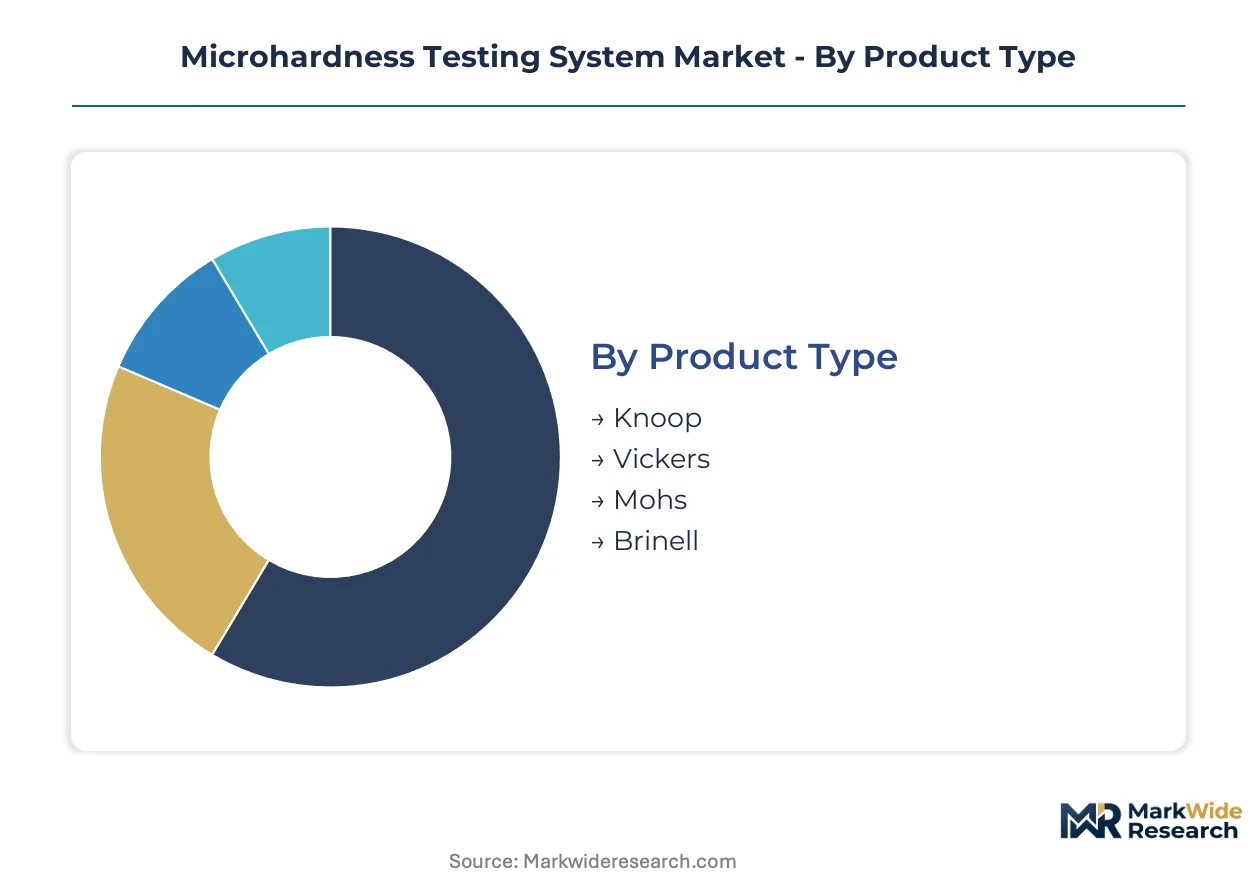
Microhardness testing systems serve divergent operational requirements across precision manufacturing and materials science. Segment boundaries reflect trade-offs between measurement accuracy, throughput demands, capital constraints, and regulatory compliance burdens.
Product Type:
Cost tier differentiation separates entry-level hardness verification from precision metrology platforms requiring diamond pyramid indenters and interferometric calibration.
- Vickers:The diamond pyramid indenter produces geometrically self-similar impressions enabling consistent hardness numbers across force ranges from 10 gf to 100 kgf. Automotive OEM captive laboratories in Germany's precision engineering corridor specify automated Vickers platforms for surface-treated powertrain component verification under ISO 6507 accreditation mandates.
- Knoop:The elongated diamond indenter geometry excels at measuring thin coatings and brittle materials where crack propagation risks distort Vickers readings. Aerospace supplier qualification workflows in the United States deploy Knoop testing for flight-critical alloy certification under FAA material protocols.
- Brinell:Large-diameter ball indenters serve castings and forgings where bulk hardness assessment outweighs microscopic resolution requirements.
- Mohs:Scratch-based comparative testing persists in mineralogy and geological specimen classification where absolute hardness values remain secondary to relative ranking.
Vickers commands the established base across industrial quality assurance. The steepest expansion runs through Knoop as thin-film deposition processes multiply in aerospace and electronics manufacturing.
Technology:
Application requirements determine whether laboratories prioritize operator independence, capital economy, or measurement traceability to national metrology institutes.
- Automated:Motorized turrets, automatic focusing, and software-driven diagonal measurement eliminate operator-dependent variance. First-tier automotive and aerospace suppliers in Germany and Japan deploy 24-hour production-line verification using deep learning-enabled indentation imaging.
- Digital:Electronic force application with digital readout bridges manual operation and full automation for mid-volume metallurgy laboratories.
- Optical:Traditional microscope-based measurement persists in education and small-lot manufacturing where capital constraints outweigh throughput requirements.
- Manual:Hand-cranked force application survives in budget-constrained institutions where secondary market liquidity delays replacement decisions.
Automated systems are gaining share fastest as ASTM E384 and ISO 6507 certification mandates compress replacement cycles. Optical technology retains residual demand in emerging economy education markets.
End User:
Customer type segmentation reveals divergent procurement authority and performance specifications between captive industrial laboratories and third-party testing facilities.
- Manufacturing:In-house metallurgy laboratories at automotive OEMs and aerospace tier suppliers require high-throughput platforms with LIMS integration for production-line verification.
- Quality Control:Third-party testing facilities serving multiple industrial clients prioritize accreditation compliance and multi-standard capability over single-application optimization.
- Research Labs:Materials science institutions demand modular platforms accommodating novel indentation protocols for additive manufacturing qualification.
- Education:Universities and technical colleges emphasize capital economy and durability over measurement throughput or automation.
Manufacturing commands the established base through captive laboratory expansion. The steepest expansion trajectory runs through Quality Control as consolidated corporate metrology frameworks displace standalone purchasing authority.
Application:
Volume concentration varies by material class according to surface treatment penetration and regulatory verification requirements.
- Metallurgy:Ferrous and non-ferrous alloy testing dominates installed base volume through automotive powertrain, aerospace structural component, and tool steel verification requirements.
- Coatings:PVD, CVD, and thermal spray surface treatments require microhardness protocols distinguishing substrate from deposited layer properties.
- Ceramics:Advanced structural ceramics and electronic substrates demand specialized low-load indentation to manage brittle fracture behavior.
- Polymer Testing:Shore and Rockwell alternatives limit microhardness penetration, though specialized nanoindentation applications are expanding in medical device materials.
Metallurgy commands the established base across industrial quality assurance. The steepest expansion runs through Coatings as surface engineering penetrates automotive, aerospace, and medical device supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diamond pyramid indenter fabrication concentrates among specialized German and Japanese suppliers, creating geographic chokepoints that shape procurement patterns. Laboratories in industrial clusters near these supply sources secure faster calibration turnaround and reduced spare part lead times.
United States
FAA material certification protocols mandate documented hardness traceability for flight-critical alloys at aerospace tier suppliers. NHTSA safety regulations and FDA device manufacturing standards embed microhardness verification into automotive and medical supplier qualification workflows. Greater Boston and Pacific Northwest defense contractors operate captive metallurgy laboratories with automated Vickers platforms.
Germany
Automotive OEM captive laboratories in the precision engineering corridor drive demand for high-throughput surface-treated powertrain component verification. REACH substance restrictions on polishing compound chemistries force metallography laboratories to reformulate sample preparation workflows. Bavaria and Baden-Württemberg host concentrated automotive testing facilities accelerating alternative chemistry validation.
Japan
METI industrial standards and JIS certification requirements sustain demand for precision metrology platforms across automotive and electronics supply chains. First-tier suppliers deploy 24-hour production-line verification using deep learning-enabled indentation imaging. Kanto and Kansai manufacturing belts concentrate automated system deployments for quality control integration.
China
GB standards harmonization with ISO 6507 accelerates laboratory accreditation investments at domestic automotive and defense suppliers. MIIT manufacturing incentives under industrial upgrading programs drive captive metallurgy investments. Yangtze River Delta and Pearl River Delta electronics manufacturers expand microhardness protocols for semiconductor packaging materials.
India
BIS laboratory certification expansion under PLI manufacturing incentives drives captive metallurgy investments at automotive and defense suppliers. CDSCO medical device regulations embed material verification into domestic production qualification. Maharashtra and Gujarat automotive clusters prioritize automated platforms for export-facing component testing.
Microhardness Testing System Market Competitive Landscape
Precision metrology heritage and materials testing automation split the market between optical measurement specialists and integrated platform engineers. The vendor base organizes around three strategic archetypes: diversified measurement conglomerates with hardness testing divisions, dedicated materials testing pure-plays, and regional fabrication specialists serving cost-sensitive education markets. Consolidated procurement through corporate metrology frameworks favors vendors with unified service coverage, while captive laboratory expansion at automotive OEMs rewards deep specialization in surface treatment verification.
Among diversified measurement conglomerates, Mitutoyo Corporation and Shimadzu Corporation occupy positions anchored by decades of optical metrology heritage across Asian manufacturing hubs. ZwickRoell and INNOVATEST exemplify the European pure-play archetype, with the former representing German engineering standards in materials testing automation and the latter anchoring software-driven indentation analysis portfolios. These four companies illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Buehler |
| ZwickRoell |
| Struers |
| LECO Corporation |
| Shimadzu Corporation |
| INNOVATEST |
| Future-Tech Corp. |
| EMCO-TEST Prufmaschinen GmbH |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight costs feed directly into diamond pyramid indenter landed pricing, amplifying procurement premiums for North American laboratories while compressing margins for optical platform vendors serving education markets. ISO 6507 certification mandates tilt buyer willingness-to-pay toward automated systems with integrated calibration, widening the gap between accredited and non-accredited equipment tiers.
Pricing Analysis
ASTM E384 and ISO 6507 dictate the pricing tier structure across the microhardness testing landscape. Three-tier pricing stratifies across fully automated platforms with deep learning imaging, digital systems with electronic force application, and residual optical units for budget-constrained institutions. Price differentiation centers on certification grade and after-sales service bundling, with accredited laboratories absorbing premium positioning for traceable measurement chains. Cost compression in manual and optical tiers intensifies because secondary market liquidity delays replacement decisions. Education and small-lot manufacturing segments exhibit highest price sensitivity, while automotive OEM captive laboratories prioritize throughput over capital economy.
Supply Chain Analysis
Extended payment terms from German and Japanese diamond indenter suppliers anchor working capital structures for platform manufacturers assembling automated systems. Precision indenter fabrication concentrates in Germany and Japan, with optical component sourcing drawing from China and South Korea. Synthetic diamond supply and interferometric calibration equipment constitute critical input dependencies. Single-source vulnerability in pyramid indenter supply creates structural risk for vendors lacking dual-qualified fabrication partners. Distribution runs through direct sales forces for automated platforms and regional distributors serving education markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable hardness testers and in-situ spectroscopic methods threaten to displace fixed laboratory microhardness systems in routine quality verification, forcing incumbents to defend their installed base through automation lock-in and data architecture integration.
For Market Incumbents: Pre-empt displacement by portable alternatives through embedding indentation modules within production-line robotics and hardening cloud-based data architectures against competitor platform integration. Deepen backward integration into diamond indenter supply through exclusive partnerships with German fabrication specialists. Certification investment in emerging BIS and GB standard harmonization creates switching costs for automotive and defense suppliers in India and China. For New Entrants and Emerging Players: Build out additive manufacturing qualification protocols as the most penetrable white-space target, where standardized microhardness methods remain underdeveloped for as-built lattice structures. India's PLI-driven captive laboratory expansion offers geographic entry with lower incumbent saturation than Germany or Japan. Channel partnership with metallography consumables distributors provides go-to-market leverage without direct sales force construction. For Investors and Strategic Acquirers: Software-driven indentation analysis specialists with established LIMS integration capabilities represent the priority acquisition archetype, as consolidated corporate metrology frameworks concentrate procurement authority. Long-term viability rests on automation protocol interoperability and multi-site service coverage scale. The signal to monitor is cloud-based indentation data architecture adoption rates among first-tier automotive suppliers, indicating platform stickiness and replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Protocol Interoperability | Seamless LIMS integration secures multi-site manufacturing contracts under consolidated procurement frameworks. |
| Deep Learning Imaging Deployment | Real-time diagonal detection collapses operator variance for 24-hour production-line verification at Japanese automotive suppliers. |
| Additive Manufacturing Qualification | Novel protocols for powder-bed fusion structures address unmet verification needs in aerospace lattice components. |
| Backward Integration into Indenter Supply | Captive diamond pyramid sourcing mitigates single-source vulnerability from German and Japanese fabricators. |
| Cloud-Based Data Architecture | Centralized hardness databases link distributed production facilities to central quality systems for multi-site manufacturers. |
Research Methodology
Operator-level perspectives from quality control managers at automotive OEMs, metallography laboratory directors, aerospace supplier certification leads, and hardness equipment service engineers anchored the qualitative base. Primary interview findings combined with secondary validation from ASTM International standards documentation, ISO technical committee publications, FAA material certification protocols, and BIS laboratory accreditation records. Customs data on precision instrument trade flows and SEC filings from diversified measurement conglomerates provided quantitative cross-checks. Bottom-up segment sizing and top-down market reconciliation ensured methodological triangulation.
Scenario-bracketing framed analytical projections across the analysis window, with sensitivity testing on additive manufacturing penetration rates and automated platform replacement cycle compression. Segmentation modeling captured product type, technology tier, end-user category, and application material class dimensions. CAGRs derived from installed base evolution, technology substitution curves, and regulatory mandate implementation timelines. Industry-specific inputs included REACH substance restriction compliance costs and PLI scheme investment trajectories.
Stress conditions across diamond indenter supply disruption, metallographer labor availability, and cloud data architecture adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on standard harmonization progress and automation technology maturation. Macroeconomic contraction, regulatory rollback, or breakthrough displacement by portable hardness methods would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Stress Test Chamber Market
Test and Measurement
Calorimeters Market
Test and Measurement
X-Ray Inspection System Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Precision Measuring Tools Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Global Video Extensometer Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market