
 Electrical and Electronic Test Equipment Market | 2026-2036
Electrical and Electronic Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical and Electronic Test Equipment Market Insights
The capability gap between bench-top instrument specialists and platform-scale automated test houses is unwinding as capital requirements for software-defined architectures climb. Keysight Technologies leverages its RF measurement heritage to dominate 5G and millimeter-wave validation workflows. Rohde & Schwarz sustains engineering-intensive development of spectrum analyzers with deep signal-analysis firmware. National Instruments Corporation anchors its position through modular PXI-based systems that integrate hardware-in-the-loop testing for automotive powertrain development.
Electrical and electronic test equipment comprises calibrated instruments that measure voltage, current, frequency, and signal integrity across operating ranges from microvolts to kilovolts, with precision thresholds often exceeding 0.001 percent accuracy for metrology-grade units. These instruments serve to verify design compliance, certify production quality, and diagnose field failures in electrified systems. Oscilloscopes and spectrum analyzers represent the largest revenue pools where margin accrues to vendors with proprietary ASIC-based acquisition front-ends. Automated test platforms are expanding fastest as contract manufacturers in consumer electronics and telecommunications adopt inline verification to reduce manual handling.
The US Federal Communications Commission shapes demand through emission compliance testing mandates for wireless devices, while the EU RoHS and REACH frameworks restrict hazardous substances in instrument assemblies and compel design-for-recycling protocols. China's Ministry of Industry and Information Technology enforces GB standards for grid-connected power electronics, creating localized certification barriers for imported analyzers. Stakeholders must monitor how IEC 61010 safety revisions and emerging AI-actuated self-calibration features redefine serviceable market boundaries.
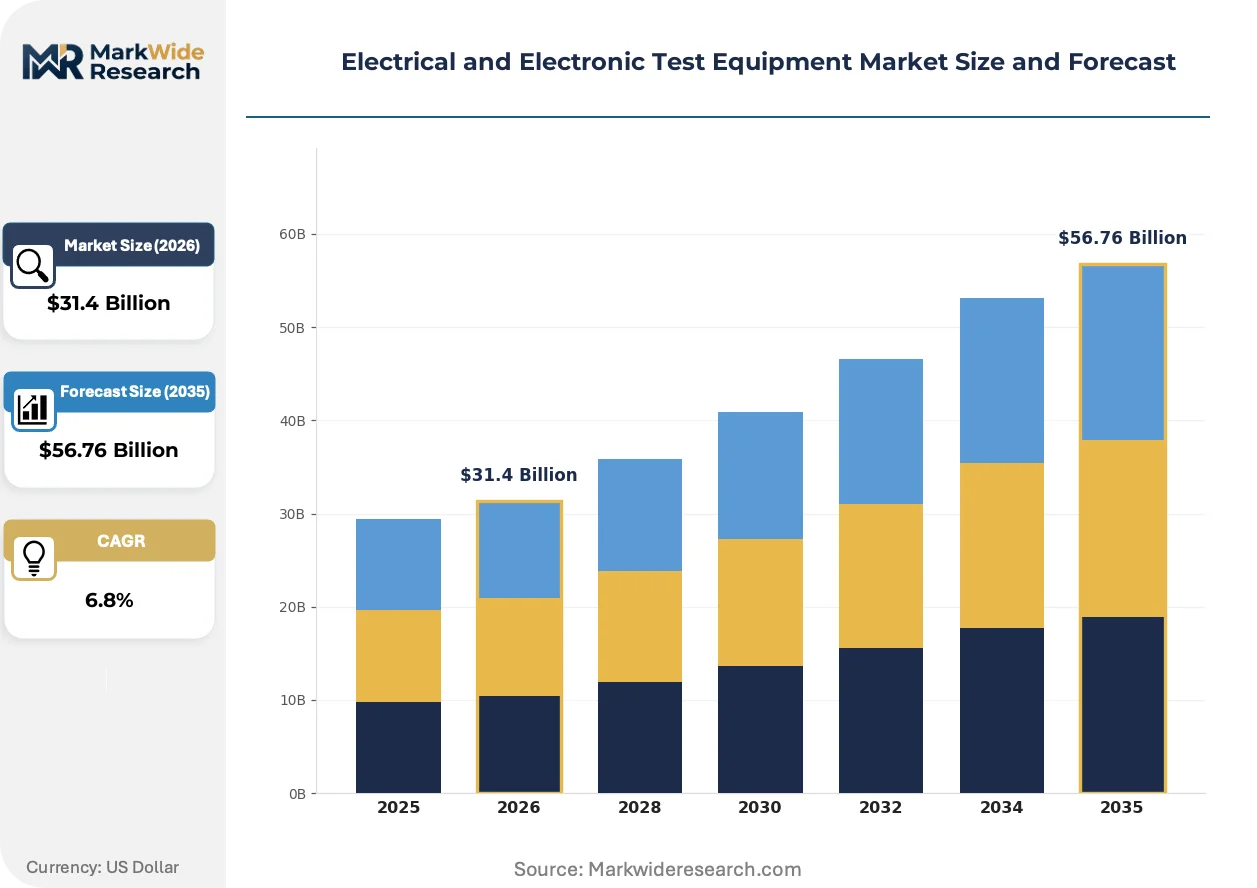
Market Dynamics
Software-defined instrumentation architectures are collapsing the historical separation between bench-top measurement tools and factory-floor automated test systems, forcing vendors to rebuild engineering teams around firmware competencies rather than hardware specialization alone.
Growth Catalysts
- Semiconductor self-sufficiency mandates:Taiwan and South Korea are expanding fab test capacity to meet chip sovereignty policies, driving demand for wafer-level parametric analyzers and probe stations.
- EU Green Deal ecodesign requirements:Energy-efficiency mandates for electrical devices are compelling manufacturers to adopt automated power-consumption validation platforms.
- 5G base station deployment:China's eastern manufacturing corridor requires precision RF validation for millimeter-wave antenna arrays and power amplifier modules.
Market Restraints
- ASIC front-end supply concentration:Proprietary acquisition chips for oscilloscopes and spectrum analyzers depend on a limited foundry base in Taiwan, creating single-source vulnerability.
- Specialized analog engineering scarcity:The talent pool for high-frequency circuit design has contracted as university programs pivot toward digital disciplines.
- Extended calibration certification timelines:Metrology-grade units require traceability to national standards bodies, creating 12-18 month approval cycles for new product introductions.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for telecom and automotive electronics are creating first-time demand for inline test equipment among contract manufacturers.
- Automotive powertrain electrification:Battery management system validation and inverter testing represent unmet need as EV platforms scale beyond prototype volumes.
- AI-actuated self-calibration:Machine learning algorithms that eliminate manual recalibration intervals could redefine service contract economics and customer switching costs.
Industry Challenges
- Legacy GPIB interface integration:Defense and aerospace installed bases depend on decades-old bus architectures, complicating migration to Ethernet-based instrument control.
- Cross-functional firmware talent competition:Vendors compete with automotive and consumer electronics sectors for embedded systems engineers capable of real-time signal processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical and Electronic Test Equipment Market |
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Power Analyzers, Spectrum Analyzers Technology: Analog, Digital, Hybrid, Automated End User: Automotive, Aerospace, Telecommunications, Consumer Electronics Application: Testing, Calibration, Verification, Maintenance |
| Companies Covered | Fortive Corporation, Anritsu Corporation, Keysight Technologies, Chroma ATE Inc., Yokogawa Electric Corporation, Rohde & Schwarz, Tektronix, Fluke Corporation, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical and Electronic Test Equipment Market Trends and Innovations
Open-source instrument control frameworks and cloud-native measurement data architectures are eroding the traditional moat of proprietary software ecosystems that once locked customers into single-vendor hardware portfolios.
Modular PXI-based measurement systems are decomposing the monolithic rack-and-stack configurations that dominated automated test through the 2010s. Automotive powertrain developers in Germany and Japan are adopting these reconfigurable platforms for hardware-in-the-loop validation of inverter controls. The shift is compressing capital deployment timelines from multi-year fixture commitments to quarterly reconfiguration cycles.
China's MIIT enforcement of GB standards for grid-connected power electronics is mandating localized certification testing that imported analyzers cannot satisfy without firmware modifications. Domestic vendors in Shenzhen and Suzhou are capturing this compliance-driven replacement cycle. European and North American instrument houses must establish joint ventures or regional engineering centers to retain access.
Subscription-based access to high-end measurement capabilities is displacing capital purchase models among mid-tier contract manufacturers. Taiwanese EMS providers now lease spectrum analyzer capacity by the hour through vendor-managed cloud platforms. The model is most visible in 5G device certification, where test volume spikes around product launches render ownership economics unfavorable.
Electrical and Electronic Test Equipment Market Segmentation
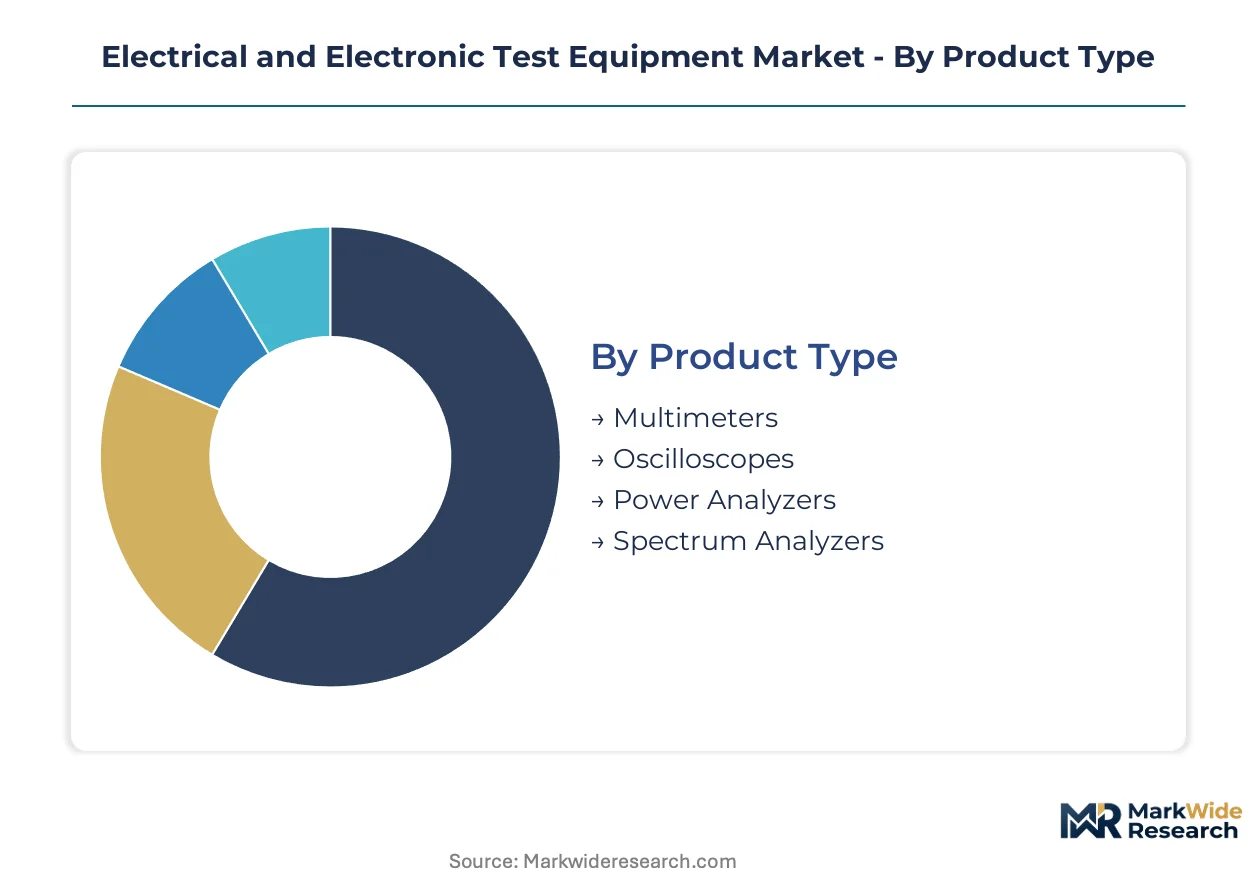
Test equipment segmentation reveals how margin migrates toward precision-intensive categories and software-defined architectures. Vendors calibrate R&D allocation across these dimensions to defend position against modular platform competitors.
Product Type:
Margin pools concentrate in instruments requiring proprietary ASIC front-ends and metrology-grade calibration chains.
- Oscilloscopes:These instruments capture transient signal phenomena with bandwidths extending into millimeter-wave ranges. Demand clusters in Taiwan's semiconductor probe stations and South Korea's memory fab expansion, driven by wafer-level parametric test requirements. Proprietary acquisition chips create vendor lock-in and sustain pricing power.
- Spectrum Analyzers:RF measurement engines with deep signal-analysis firmware dominate 5G base station validation workflows. China's eastern manufacturing corridor absorbs capacity for millimeter-wave antenna certification, compelled by MIIT emission compliance mandates. Engineering-intensive development cycles limit competitive entry.
- Multimeters:Handheld and bench-top units serve field maintenance and basic electrical verification across industrial facilities.
- Power Analyzers:Precision instruments measure harmonic distortion and efficiency in grid-connected inverters and EV powertrains.
The dominant share belongs to oscilloscopes, while spectrum analyzers are closing the gap fastest.
Technology:
Cost tier stratification separates legacy hardware from software-defined platforms requiring firmware competencies.
- Automated:Platform-scale systems integrate hardware-in-the-loop testing for automotive powertrain development. Germany's inverter manufacturers and Japan's EV suppliers deploy these for quarterly reconfiguration cycles rather than multi-year fixture commitments. Subscription-based access models are displacing capital purchases among Taiwanese EMS providers.
- Digital:Software-defined architectures collapse distinctions between bench-top and factory-floor systems, forcing vendor engineering team restructuring. Open-source control frameworks erode proprietary ecosystem moats.
- Analog:Legacy architectures persist in defense and aerospace installed bases dependent on GPIB bus interfaces.
- Hybrid:Mixed-signal approaches bridge transitional deployments in industrial settings with heterogeneous instrument fleets.
Automated platforms command premium positioning, with digital architectures expanding most quickly.
End User:
Application maturity determines whether procurement favors capital ownership or leased capacity models.
- Automotive:Battery management system validation and inverter testing represent unmet need as EV platforms scale beyond prototype volumes. Hardware-in-the-loop adoption concentrates in German and Japanese powertrain development centers.
- Telecommunications:5G device certification drives hourly leasing of spectrum analyzer capacity through vendor-managed cloud platforms. Test volume spikes around product launches render ownership economics unfavorable for mid-tier contract manufacturers.
- Aerospace:Decades-old GPIB dependencies complicate migration to Ethernet-based instrument control in defense installed bases.
- Consumer Electronics:Inline verification adoption reduces manual handling in high-volume production environments.
Automotive applications absorb the deepest investment, while telecommunications shows the steepest shift toward consumption-based procurement.
Application:
Customer type segmentation separates compliance-driven metrology from operational maintenance workflows.
- Testing:Design verification and production quality assurance dominate revenue contribution. EU Green Deal ecodesign requirements for energy-efficient devices compel automated power-consumption validation platform adoption.
- Calibration:Metrology-grade units require traceability to national standards bodies, creating extended approval cycles. This constraint protects incumbents with established certification infrastructure.
- Verification:Inline inspection workflows in consumer electronics and telecommunications manufacturing compress cycle times.
- Maintenance:Field diagnostic instruments prioritize portability and ruggedization over laboratory precision specifications.
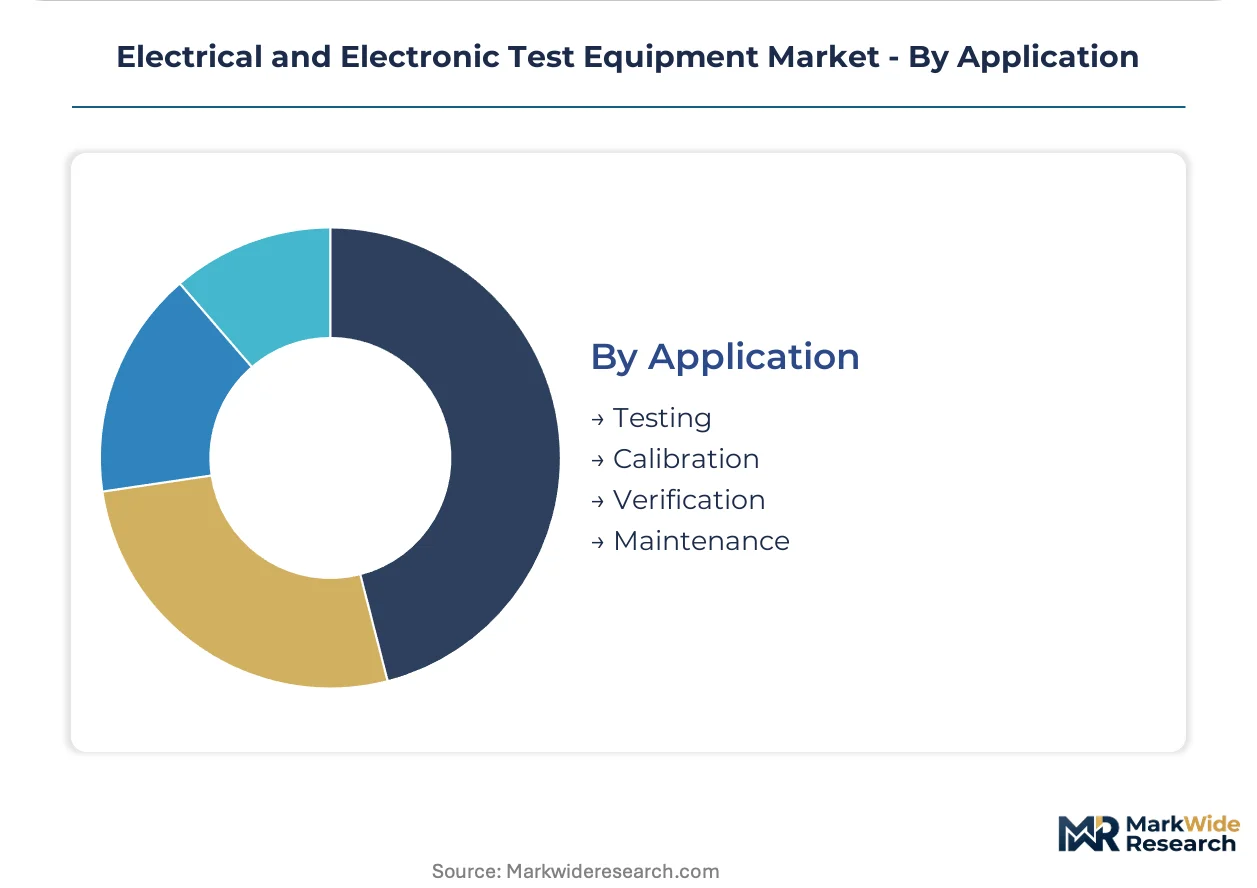
Testing applications retain the largest share, with calibration services demonstrating the most durable margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Taiwan and South Korea absorb premium pricing for wafer-level parametric analyzers with minimal elasticity, while Indian contract manufacturers negotiate aggressively on automated test platforms under PLI scheme procurement rules.
United States
Defense and aerospace installed bases sustain demand for legacy GPIB-compatible instruments, while 5G device certification labs in California and Texas expand millimeter-wave validation capacity. The FCC mandates emission compliance testing for all wireless devices entering commercial distribution. Boston-area research institutions and Silicon Valley semiconductor design houses anchor the highest-precision instrument procurement.
Germany
Automotive powertrain electrification drives hardware-in-the-loop testing adoption among inverter manufacturers and Tier-1 suppliers. The EU Green Deal ecodesign requirements compel automated power-consumption validation platform investments. Industrial clusters in Bavaria and Baden-Württemberg concentrate EV battery management system development and associated test equipment deployment.
China
MIIT enforcement of GB standards for grid-connected power electronics mandates localized certification testing that imported analyzers cannot satisfy without firmware modifications. The eastern manufacturing corridor spanning Suzhou, Shenzhen, and Shanghai absorbs precision RF validation equipment for 5G base station and EV production lines. Domestic vendors in Shenzhen capture compliance-driven replacement cycles previously served by foreign suppliers.
Japan
Automotive and consumer electronics manufacturers sustain demand for modular PXI-based systems with quarterly reconfiguration capabilities. METI industrial policy supports test equipment localization to reduce import dependency for critical measurement infrastructure. Nagoya-area automotive suppliers and Tokyo-Osaka electronics manufacturing corridors anchor platform-scale automated test adoption.
India
PLI scheme incentives for telecom and automotive electronics create first-time demand for inline test equipment among contract manufacturers previously dependent on manual verification. The CEA and BIS enforce certification requirements for grid-connected power electronics that favor domestically assembled instruments. Tamil Nadu and Karnataka electronics manufacturing clusters absorb initial automated platform deployments as EMS providers scale beyond prototype volumes.
Electrical and Electronic Test Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding proprietary ASIC front-end architectures and metrology-grade calibration chains that sustain pricing power. The middle tier fragments across modular PXI-based platform providers and legacy analog instrument houses serving defense installed bases. Two strategic archetypes predominate: vertically integrated measurement houses with captive semiconductor fabrication for acquisition chips, and software-defined platform vendors renting capacity through subscription models. Competitive moves concentrate on strategic partnerships with automotive powertrain developers and geographic expansion through regional engineering centers to satisfy localized certification requirements.
Among US-based measurement houses, Keysight Technologies and National Instruments Corporation exemplify contrasting platform strategies, with the former representing RF heritage dominance in 5G validation workflows and the latter anchoring modular hardware-in-the-loop adoption. Yokogawa Electric Corporation occupies a position within the precision power analyzer specialization tier. These three names illustrate how vendor origin and structural form—Inc. versus Corporation—signal distinct competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Fortive Corporation |
| Anritsu Corporation |
| Keysight Technologies |
| Chroma ATE Inc. |
| Yokogawa Electric Corporation |
| Rohde & Schwarz |
| Tektronix |
| Fluke Corporation |
| National Instruments Corporation |
| Others |
Pricing and Supply Chain Analysis
MIIT enforcement of GB standards for grid-connected power electronics gates both supply qualification and price differentiation simultaneously, forcing imported analyzers into costly firmware modifications while domestic Shenzhen vendors capture compliance-driven replacement cycles at lower price points. This regulatory barrier creates a dual-track market where certification capability separates premium positioning from economy-tier competition.
Pricing Analysis
Service contracts and extended calibration agreements drive lifetime value beyond the initial instrument sale, with metrology-grade units commanding recurring revenue streams that sustain vendor margins. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and proprietary ASIC front-end differentiation. Cost compression in the standard tier intensifies as modular PXI platforms displace monolithic rack-and-stack configurations. Taiwanese semiconductor fabs show minimal price elasticity for wafer-level parametric analyzers, while Indian PLI-scheme contract manufacturers negotiate aggressively on automated test platforms.
Supply Chain Analysis
Strategic stockpiling of proprietary acquisition chips dominates inventory strategy among oscilloscope and spectrum analyzer vendors confronting Taiwan foundry concentration. Taiwan, South Korea, and Japan anchor upstream supply for high-frequency ASIC front-ends and precision analog components. Single-source vulnerability in Taiwan-based foundry capacity for custom acquisition silicon creates structural risk for vendors dependent on proprietary chip architectures. Distribution runs through direct vendor relationships with automotive powertrain developers and tier-one EMS providers in Germany, Japan, and China's eastern manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward automotive OEMs and tier-one EMS providers consolidating procurement around platform-scale automated test systems, fragmenting demand across fewer volume purchasers with reconfiguration-cycle preferences.
For Market Incumbents: Secure proprietary ASIC front-end supply through captive foundry relationships or long-term capacity reservations at Taiwan semiconductor facilities. Deepen firmware talent pools through automotive sector recruitment to counter cross-functional engineering competition. The threat of open-source instrument control frameworks eroding software ecosystem moats demands accelerated investment in cloud-native measurement data architectures. For New Entrants and Emerging Players: Differentiate on AI-actuated self-calibration capabilities that eliminate manual recalibration intervals and redefine service contract economics. India's PLI-scheme electronics manufacturing clusters represent the most penetrable geography, with first-time automated test demand among contract manufacturers scaling beyond prototype volumes. A subscription-based capacity-leasing go-to-market angle bypasses capital purchase barriers among mid-tier Taiwanese EMS providers. For Investors and Strategic Acquirers: EU Green Deal ecodesign requirements reshaping the acquisition landscape toward automated power-consumption validation platforms with energy-efficiency certification capabilities. Long-term viability favors vertically integrated measurement houses with captive semiconductor fabrication for acquisition chips over software-defined platform vendors lacking hardware differentiation. Watch for MIIT firmware localization mandates crossing enforcement thresholds that trigger compliance-driven replacement cycles in China's grid-connected power electronics sector.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Engineering Center Establishment | Joint ventures in Shenzhen satisfy MIIT GB standard certification requirements for grid-connected analyzers. |
| ASIC Front-End Capacity Reservation | Long-term foundry agreements at Taiwan semiconductor facilities secure proprietary acquisition chip supply. |
| Subscription Platform Launch | Hourly spectrum analyzer leasing through vendor-managed cloud platforms captures Taiwanese EMS demand spikes. |
| Automotive HIL Partnership | Hardware-in-the-loop integration with German inverter manufacturers compresses capital deployment timelines. |
| AI Calibration Development | Machine learning self-calibration features redefine service economics and elevate customer switching costs. |
Research Methodology
Operator-level perspectives from test equipment procurement managers, automotive powertrain validation engineers, semiconductor fab metrology leads, and EMS provider operations directors anchored the qualitative base. Primary interviews combined with secondary validation drawing from FCC equipment authorization databases, MIIT GB standard filings, EU ecodesign regulatory texts, and SEC 10-K instrument vendor disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume assumptions.
Sensitivity analysis tested forecast robustness across semiconductor capital expenditure cycles, automotive EV platform ramp schedules, and regional certification timeline variations. Segmentation dimensions modeled include product type, technology architecture, end-use industry, and application workflow across the projection horizon. CAGRs derived from instrument replacement cycle analysis, fab capacity expansion announcements, and automated test adoption curves in consumer electronics manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor self-sufficiency policy execution or accelerated EU Green Deal enforcement would require recalibration. Forecasts reflect assumptions regarding Taiwan foundry capacity availability and analog engineering talent pipeline recovery. Revision becomes warranted when MIIT localization mandates or IEC 61010 safety revisions cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Surface Inspection Market
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Burn-In and System-Level Test (SLT) Platforms for AI Accelerators Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Europe Signal Generator Market
Test and Measurement
Active Dosimeter Market