
 Global IVR Software Market | 2026-2036
Global IVR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global IVR Software Market Foresight
Mid-market enterprises are reorganizing their contact center procurement priorities, shifting budget from legacy premises-based systems toward cloud-native IVR platforms that integrate with CRM stacks. Five9 leverages its cloud contact center heritage to anchor enterprise deals in North America. Genesys competes through AI-driven orchestration layers that span voice and digital channels. Twilio extends its programmable communications API dominance into IVR workflows for developers building custom self-service applications.
Interactive Voice Response software processes inbound and outbound telephone calls through automated menus using dual-tone multi-frequency signaling, speech recognition engines, and natural language processing to route callers or execute transactions without human agents. Its primary commercial purpose is deflecting routine inquiries from live agents while preserving service-level agreements at lower unit economics. Cloud-based deployments capture the fastest expansion as telecommunications and retail chains abandon capital-intensive hardware refresh cycles. Natural language processing segments command premium pricing due to longer implementation timelines and specialized conversational AI engineering talent. Hosted solutions retain residual share among BFSI institutions with strict data residency requirements.
The Federal Communications Commission governs telemarketing consent and call authentication standards that shape IVR outbound dialing architectures in the United States. The EU AI Act imposes risk-classification obligations on automated decision systems, compelling European deployments to embed human handoff protocols and transparency disclosures. India's Telecom Regulatory Authority mandates caller identification frameworks that influence how IVR systems authenticate inbound sessions. Stakeholders must weigh regulatory compliance roadmaps against the pace of conversational AI capability gains when selecting build-versus-buy strategies for voice automation infrastructure.
Market Dynamics
Cloud migration mandates under the EU AI Act and analogous data sovereignty frameworks are accelerating replacement cycles across enterprise contact center infrastructure, compressing hardware refresh timelines from seven-year cycles to three-year cloud-native transitions.
Growth Catalysts
- Healthcare automation:Providers in the United States are expanding IVR deployments for patient appointment management and prescription refill automation, reducing administrative burden on clinical staff.
- EU AI Act compliance:Risk-classification obligations on automated decision systems compel European enterprises to embed human handoff protocols, driving platform upgrades.
- Telecommunications modernization:India's TRAI caller identification frameworks are mandating authentication infrastructure that IVR systems must integrate, spurring replacement demand.
Market Restraints
- Specialized talent scarcity:Natural language processing implementations require conversational AI engineering expertise that concentrates in technology hubs, elongating deployment timelines.
- Data residency requirements:BFSI institutions in Germany and Switzerland maintain strict localization mandates that constrain cloud-native adoption and preserve hosted solution share.
- Speech recognition accuracy thresholds:Dialect variation and ambient noise sensitivity create persistent technical limitations for voice biometrics in emerging market deployments.
Strategic Opportunities
- Underpenetrated Indian mid-market:Domestic enterprises outside banking and telecommunications remain reliant on manual call routing, presenting greenfield SaaS conversion potential.
- API-first developer ecosystems:Programmable communications platforms are enabling custom self-service application construction that bypasses traditional vendor procurement cycles.
- Conversational AI convergence:Integration of large language models with legacy DTMF infrastructure is creating hybrid architectures that preserve existing investments while adding natural language capability.
Industry Challenges
- Legacy system integration complexity:Enterprises with premises-based PBX infrastructure face protracted migration timelines when connecting cloud IVR to existing CRM and workforce management stacks.
- Conversational design talent gap:Shortage of dialogue designers capable of architecting multi-turn voice interactions is delaying go-live dates for NLP-enabled deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IVR Software Market |
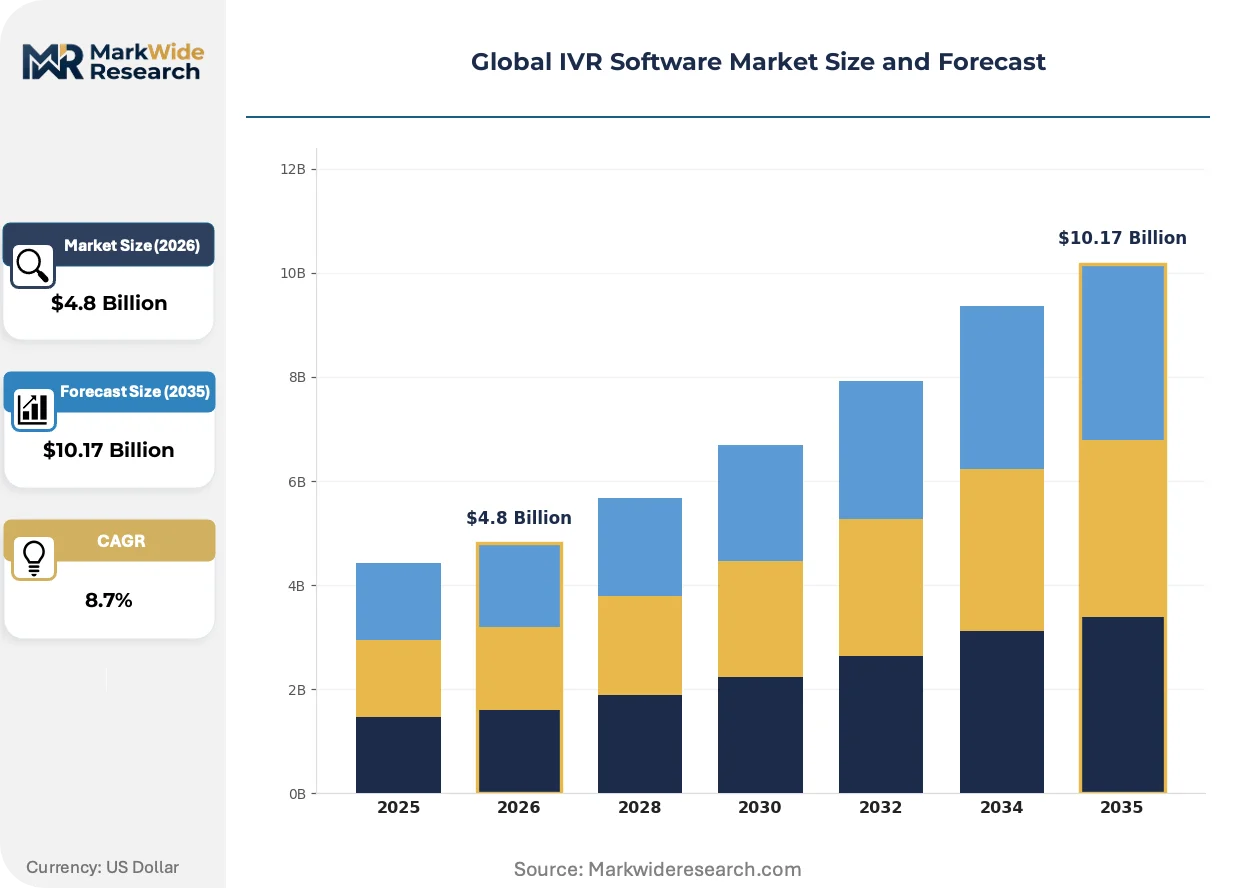
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hosted, Premises-Based, Cloud-Based, Hybrid Technology: Text-to-Speech, Speech Recognition, Natural Language Processing, DTMF Application: Customer Support, Telebanking, Surveys & Polls, Order Processing, Help Desk End User: Telecommunications, BFSI, Healthcare Providers, Retail Chains, Logistics Firms |
| Companies Covered | Talkdesk, RingCentral, Five9, Dialpad, CloudTalk, Genesys, NICE CXone, Zendesk, Twilio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IVR Software Market Shifts & Advancements
Voice automation architecture is undergoing fundamental restructuring as edge computing capabilities and generative AI compress the latency-performance tradeoff that historically constrained cloud IVR adoption.
Edge-deployed speech recognition is miniaturizing the hardware footprint required for real-time natural language processing. Retail chains with distributed store footprints are adopting lightweight edge nodes to process voice biometrics locally, eliminating round-trip latency to centralized data centers. This distributed architecture is compressing the total cost of ownership for multi-location deployments by reducing dedicated bandwidth requirements.
The EU AI Act's transparency disclosure mandates are reshaping conversational flow design across European deployments. Automated systems must now embed explicit handoff triggers and decision-logging capabilities that expose algorithmic reasoning to auditors. Healthcare and financial services verticals in Germany and France are responding by restructuring dialogue trees to incorporate mandatory human escalation points at defined risk thresholds.
Subscription consumption models are displacing perpetual license structures in mid-market procurement. Enterprise buyers in the United States are unbundling implementation services from platform fees, preferring month-to-month arrangements that transfer operational risk to vendors. This preference shift is most visible among technology and professional services firms with seasonal call volume volatility, who prioritize elasticity over capital efficiency.
Global IVR Software Market Segmentation
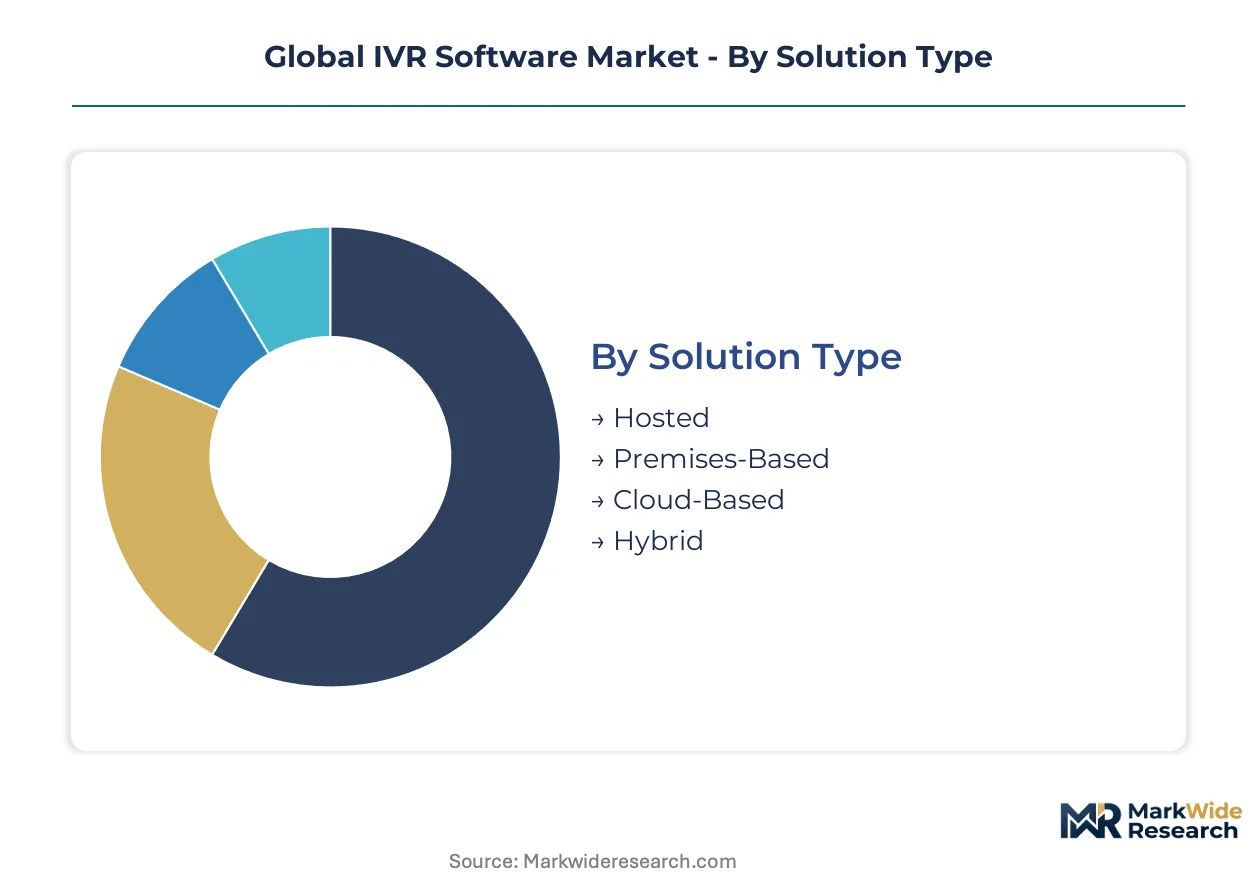
IVR software segmentation reveals how deployment models, interface technologies, and vertical applications create divergent margin profiles and implementation timelines across enterprise buyers. Understanding these splits enables vendors to align engineering roadmaps with procurement patterns that vary sharply by customer scale and regulatory exposure.
Solution Type:
Geographic spread distinguishes these segments sharply: cloud-based solutions serve export-oriented multinational programs, while premises-based deployments concentrate in domestic financial institutions with strict data localization mandates.
- Cloud-Based:Multi-tenant architectures with API-native integration layers enable rapid scaling across distributed contact center footprints. Demand concentrates in United States technology firms and German automotive suppliers modernizing customer service infrastructure under compressed timelines mandated by EU AI Act risk-classification obligations.
- Hosted:Single-tenant managed services delivered from vendor-operated data centers balance control with reduced capital burden. Swiss private banks and Indian public sector insurers favor this model to satisfy RBI and local regulator data residency requirements without owning hardware refresh cycles.
- Premises-Based:Legacy hardware stacks with perpetual licensing remain entrenched in Japanese manufacturing conglomerates with decade-old PBX investments and minimal cloud migration appetite.
- Hybrid:Split architectures routing sensitive transactions to on-premise nodes while pushing routine queries to cloud endpoints appeal to French healthcare networks navigating CNIL audit protocols.
Cloud-based holds the largest share; momentum sits with hybrid configurations bridging compliance and elasticity.
Technology:
Cost tier stratification separates these segments: natural language processing commands premium implementation fees, while DTMF infrastructure occupies the economy tier with minimal professional services attachment.
- Natural Language Processing:Transformer-based speech models with intent classification and entity extraction enable conversational self-service beyond menu navigation. United States healthcare providers deploy NLP for patient symptom triage, though specialized dialogue design talent scarcity in secondary metros elongates deployment timelines.
- Speech Recognition:Acoustic modeling with speaker adaptation supports voice biometrics and hands-free transaction execution. Indian telecommunications carriers integrate TRAI-mandated caller authentication frameworks using speech recognition layers that verify identity against national identity databases.
- Text-to-Speech:Neural voice synthesis with prosody control generates natural prompts for dynamic content delivery. German insurers leverage TTS for personalized policy notifications across regional dialect variations.
- DTMF:Touch-tone signaling with rigid menu hierarchies persists in cost-constrained logistics dispatch centers where call complexity remains low and agent deflection suffices.
DTMF retains volume leadership in transaction counts; NLP is gaining share fastest among new deployments.
Application:
Customer type differentiation shapes this split: business-to-consumer volumes dominate customer support and telebanking, while business-to-business procurement concentrates in order processing and help desk functions.
- Customer Support:Inbound call routing with CRM screen-pop integration deflects routine inquiries from live agents. United States retail chains deploy IVR for order status and return authorization, preserving service-level agreements during peak seasonal volumes without proportional staffing increases.
- Telebanking:Account balance inquiry, fund transfer, and card activation workflows with PCI-DSS compliant input masking. Brazilian banks facing ANVISA-aligned financial consumer protection rules embed explicit human handoff triggers for transaction disputes.
- Order Processing:Inventory availability checks and purchase confirmation workflows integrated with ERP systems. Logistics firms in the Netherlands automate freight booking through IVR linked to warehouse management platforms.
- Help Desk:IT incident logging and password reset automation with Active Directory integration. Technology vendors in Israel serve global enterprise clients through multilingual help desk IVR with automatic ticket escalation protocols.
- Surveys & Polls:Outbound dialing with interactive response capture for market research and post-interaction satisfaction scoring. Australian government agencies conduct census follow-up via IVR to reach demographics with limited internet access.
Customer support captures the greatest deployment count; telebanking shows the steepest expansion trajectory as developing market financial inclusion programs scale.
End User:
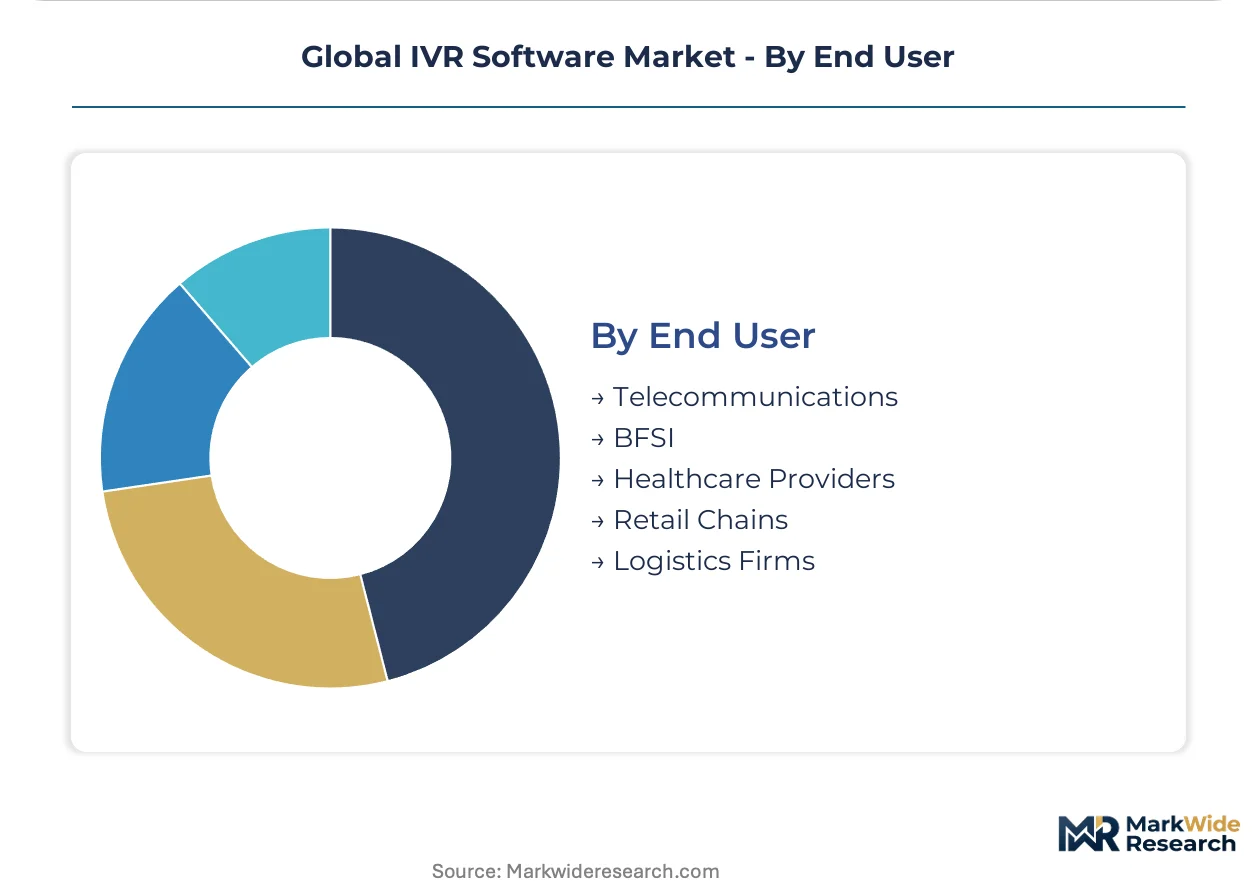
Supply concentration varies by vertical: telecommunications and BFSI consolidate procurement through carrier-grade vendors, while healthcare and retail fragment across specialized solution providers.
- Telecommunications:Carrier-scale deployments with millions of daily call sessions requiring five-nines reliability. Indian operators modernize prepaid recharge and plan migration IVR under TRAI quality-of-service mandates that penalize excessive call drop rates.
- BFSI:Fraud prevention integration with real-time transaction monitoring and regulatory reporting workflows. German cooperative banks maintain premises-based IVR for mortgage application pre-qualification to satisfy BaFin audit trail requirements.
- Healthcare Providers:Appointment scheduling, prescription refill, and lab result delivery with HIPAA-compliant logging. United States hospital systems expand IVR to reduce administrative burden on clinical staff facing persistent nursing shortages.
- Retail Chains:Distributed store footprints with edge-deployed speech recognition minimizing bandwidth costs. French grocery cooperatives process click-and-collect confirmations through store-level IVR nodes.
- Logistics Firms:Driver dispatch and delivery confirmation with GPS integration and proof-of-capture workflows. United Arab Emirates freight operators connect IVR to customs clearance status feeds for port coordination.
Telecommunications holds the largest share; momentum sits with healthcare providers as patient engagement automation budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based cloud contact center vendors export SaaS platforms to European healthcare networks and Indian telecommunications carriers, establishing a dominant trade corridor in voice automation infrastructure.
United States
Healthcare providers deploy IVR for patient appointment management and prescription refill automation, reducing administrative burden on clinical staff. FCC telemarketing consent rules and STIR/SHAKEN call authentication standards shape outbound dialing architectures. Hospital systems in Texas and California expand voice automation budgets fastest as nursing shortages persist.
Germany
Automotive suppliers and cooperative banks modernize customer service infrastructure under compressed timelines mandated by EU AI Act risk-classification obligations. BaFin audit trail requirements preserve premises-based deployments for mortgage pre-qualification workflows. Industrial clusters in Bavaria and Baden-Württemberg anchor cloud-native transitions for export-oriented manufacturers.
India
Telecommunications carriers modernize prepaid recharge and plan migration IVR under TRAI quality-of-service mandates that penalize excessive call drop rates. Domestic enterprises outside banking and telecommunications remain reliant on manual call routing, presenting greenfield SaaS conversion potential. Bangalore and Hyderabad technology corridors concentrate conversational AI engineering talent for NLP-enabled deployments.
United Kingdom
Financial services firms embed human handoff protocols to satisfy FCA consumer duty requirements for automated decision transparency. London-based fintechs prioritize API-first IVR integration with CRM stacks for rapid product iteration. Manchester and Birmingham contact center outsourcing hubs drive mid-market demand for subscription consumption models.
France
Healthcare networks navigate CNIL audit protocols by restructuring dialogue trees to incorporate mandatory human escalation points at defined risk thresholds. Retail cooperatives process click-and-collect confirmations through store-level IVR nodes with edge-deployed speech recognition. Paris and Lyon insurance carriers leverage neural text-to-speech for personalized policy notifications across regional dialect variations.
Global IVR Software Market Competitive Landscape
Player mix skews toward cloud-native platform specialists with API-centric architectures, creating a tiered structure where programmable communications vendors compete against integrated contact center suites. Strategic archetypes include developer-focused API platforms, full-stack cloud contact center providers, and conversational AI layer specialists. Competitive moves concentrate on M&A for NLP talent acquisition and strategic partnerships for CRM integration depth.
Among cloud contact center incumbents, Five9 and Genesys exemplify the integrated suite archetype, anchoring enterprise deals through pre-built orchestration layers that span voice and digital channels. Twilio occupies a distinct position within the API-first tier, extending programmable communications infrastructure into IVR workflows for developer-led custom self-service construction. These three names represent the dominant competitive vectors shaping procurement patterns across North American and European enterprise buyers.
| Leading Market Players |
|---|
| Talkdesk |
| RingCentral |
| Five9 |
| Dialpad |
| CloudTalk |
| Genesys |
| NICE CXone |
| Zendesk |
| Twilio |
| Others |
Supply & Pricing Matrix
EU AI Act risk-classification obligations gate both vendor qualification and price differentiation simultaneously, as compliance certification becomes a mandatory cost of market entry that stratifies procurement budgets across regulated and non-regulated buyer archetypes.
Pricing Analysis
Cloud-native IVR platforms command a substantial premium over premises-based legacy systems and hosted managed services, with natural language processing implementations carrying the steepest implementation fees due to scarce conversational AI engineering talent. Pricing stratifies across premium, standard, and economy tiers based on integration complexity and data residency certification levels. Cost compression in the mid-market SaaS tier is intensifying because subscription consumption models are displacing perpetual licenses, transferring operational risk to vendors. Healthcare providers in the United States exhibit the least price sensitivity due to nursing shortage-driven automation urgency, while Indian domestic enterprises outside banking remain most price-constrained.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for edge-computing hardware components destined for distributed retail deployments in the United States and Europe. Cloud infrastructure supply concentrates in the United States, Germany, and India, with conversational AI model training anchored in technology hubs like Bangalore and Hyderabad. The IVR software supply chain draws from specialized speech recognition engines, transformer-based NLP libraries, and telecommunications-grade server hardware. Single-source vulnerability in GPU availability for model training poses structural risk. Distribution runs through direct enterprise sales teams for large deployments and API platform marketplaces for developer-led procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IVR software represents a service-attach opportunity where implementation and conversational design services expand faster than core platform licensing, as enterprises unbundle professional services to accelerate deployment timelines.
For Market Incumbents: Shield installed-base revenue by embedding EU AI Act compliance modules as mandatory upgrades before competitive displacement can exploit regulatory deadlines. Prioritize backward integration into proprietary speech recognition models to reduce dependency on third-party NLP providers facing talent scarcity. Consolidate channel control through exclusive CRM integration partnerships that raise switching costs for enterprise buyers. For New Entrants and Emerging Players: Anchor in the underpenetrated Indian mid-market outside banking and telecommunications, where manual call routing persists and greenfield SaaS conversion offers low competitive friction. Target API-first developer ecosystems with programmable communications platforms that bypass traditional vendor procurement cycles. Pursue a vertical-specific go-to-market angle in French healthcare networks navigating CNIL audit protocols with hybrid compliance architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as multi-tenant architectures achieve scale efficiencies. The long-term viability window favors conversational AI layer specialists with proven dialogue design talent pipelines over hardware-dependent premises-based vendors. Monitor TRAI quality-of-service mandate enforcement in India as an inflection indicator for carrier-scale replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Talent Acquisition | Addresses specialized engineering scarcity elongating NLP deployment timelines for healthcare providers. |
| API-First Platform Expansion | Captures developer-led procurement bypassing traditional enterprise sales cycles in technology firms. |
| EU AI Act Compliance Certification | Gates market access for European deployments requiring embedded human handoff protocols. |
| Edge Computing Node Deployment | Reduces bandwidth costs for retail chains with distributed store footprints in France and Germany. |
| Hybrid Architecture Development | Preserves existing PBX investments while adding natural language capability for BFSI institutions. |
Research Methodology
Operator-level perspectives from contact center operations directors, CIOs at healthcare systems, telecommunications network engineers, and conversational AI product managers anchored the qualitative base. These primary insights combined with secondary validation from FCC rulemaking dockets, TRAI quality-of-service circulars, EU AI Act implementation guidance, SEC filings of cloud communications providers, and hyperscaler capex disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing derived from carrier infrastructure spend patterns.
Sensitivity analysis framed the quantitative modeling across deployment model, organization size, vertical application, integration complexity, and regional adoption pattern. CAGRs were derived from segment-level growth trajectory analysis incorporating healthcare automation budget expansion, EU regulatory compliance deadlines, and Indian telecommunications modernization mandates. Industry-specific forecast inputs included nursing shortage severity indices for United States hospital systems and TRAI penalty enforcement intensity for Indian carriers.
Decision-makers should treat outputs as directional under assumptions of sustained cloud migration appetite and stable regulatory enforcement timelines; material deviation in macroeconomic conditions or compliance interpretation would warrant model refresh. Forecasts reflect base-case assumptions regarding talent availability and carrier infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Clinical Communication and Collaboration Software Market
Software & Services
Software Consulting Market
Software & Services
Global PEO Software Market
Software & Services
Online Lottery Software Market
Software & Services
Interview Scheduling Software Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Calorie Metering Software Market
Software & Services
Attendance Tracking Software Market
Software & Services
Document Capture Software Market
Software & Services
Enterprise Performance Management (EPM) Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Outsourced Software Testing Services Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
Asia Pacific Content Services Platform Market