
 Electric Vehicle Flat Wire Motor Market | 2026-2036
Electric Vehicle Flat Wire Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Flat Wire Motor Market Insights
Modular platform bundling of flat wire motors with integrated inverters and thermal management systems is hardening as the dominant procurement configuration. BorgWarner leverages its powertrain integration expertise to anchor multi-component contracts with premium OEMs. Denso sustains manufacturing scale across Japan and Southeast Asia, competing on winding automation and quality consistency.
An electric vehicle flat wire motor employs rectangular copper conductors wound with higher slot fill ratios than round wire equivalents, typically achieving 60-70% copper density to improve thermal performance and power density in confined axle spaces. Permanent magnet configurations currently lead volume shipments due to their torque density advantage in passenger vehicles, while induction motor variants gain traction in commercial trucks where rare-earth cost volatility drives alternative magnet strategies. Winding technique differentiation separates premium suppliers from standard-tier competitors, as hairpin and continuous wave winding methods demand specialized capital equipment and process control.
EPA tailpipe regulations, EU Green Deal vehicle CO2 mandates, and China's MIIT new energy vehicle credit system collectively tighten efficiency requirements that flat wire architectures satisfy. NHTSA safety standards and ECE R10 electromagnetic compatibility rules add compliance layers that favor established suppliers with certification depth. Stakeholders must monitor how battery-electric platform standardization across OEMs affects motor specification consolidation versus customization demands.
Market Dynamics
Platform standardization across battery-electric architectures is compressing motor specification diversity while amplifying volume concentration among suppliers capable of integrated powertrain bundling.
Growth Catalysts
- EPA Tailpipe Standards:Tighter efficiency mandates in the United States force powertrain redesigns toward flat wire architectures that reduce copper losses and extend electric range.
- China's MIIT Credit System:Domestic new energy vehicle quotas accelerate procurement from the Yangtze River Delta manufacturing cluster where motor suppliers co-locate with battery producers.
- Hairpin Winding Automation:Advanced winding techniques achieve 60-70% slot fill ratios, enabling torque density gains that permanent magnet configurations exploit in passenger vehicle platforms.
Market Restraints
- Rare-Earth Cost Volatility:Permanent magnet dependency exposes motor producers to neodymium and dysprosium price swings that compress margin predictability.
- Capital Equipment Intensity:Continuous wave winding lines require specialized automation that limits supplier entry and concentrates production among scaled incumbents.
- ECE R10 Compliance Burden:Electromagnetic certification timelines extend product qualification cycles, favoring established vendors with regulatory depth over emerging competitors.
Strategic Opportunities
- Commercial Truck Induction Motors:Rare-earth alternative strategies open volume potential in heavy-duty segments where magnet cost exposure drives specification shifts.
- EU Green Deal CO2 Mandates:European vehicle efficiency requirements create procurement pull for thermal-integrated motor-inverter bundles that optimize axle packaging.
- Integrated Thermal Management Convergence:Combining flat wire motors with liquid cooling circuits and inverter housings enables platform-level value capture beyond component supply.
Industry Challenges
- Winding Technician Scarcity:Hairpin and wave winding process control demands specialized skill sets that outpace vocational training pipeline output.
- Platform Integration Complexity:Axle-space constraints and NVH requirements force simultaneous optimization across electromagnetic, thermal, and mechanical domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Flat Wire Motor Market |
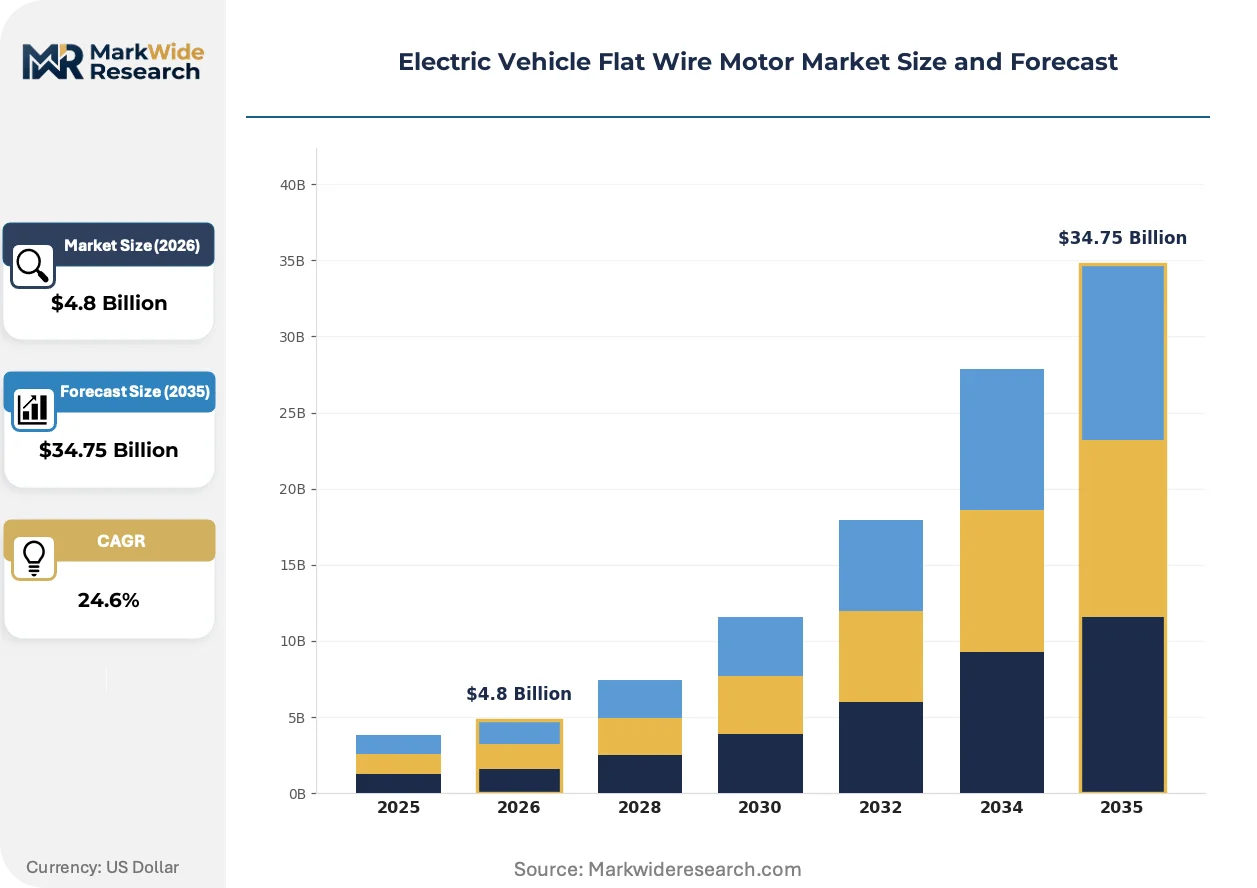
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $34.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet, Induction Motor, Synchronous Motor, Stepper Motor Technology: Winding Technique, Cooling System, Power Electronics, Control System End User: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Buses Drive Type: Front-Wheel Drive, Rear-Wheel Drive, All-Wheel Drive, Hybrid Drive |
| Companies Covered | BorgWarner, Denso, Hitachi, Hasco, LG, Santroll, Huayu Automotive Systems, HYCET Technology, Tianjin Santroll Electric Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Flat Wire Motor Market Trends and Innovations
Powertrain integration architectures are hardening around bundled motor-inverter-thermal systems that compress supplier interfaces and shift value toward subsystem specialists.
Continuous wave winding technology is modularizing motor manufacturing by enabling automated conductor placement that reduces labor content while improving slot fill consistency. Tier-one suppliers in Germany and Japan are adopting these lines for premium electric platform contracts. The technology is modularizing competitive positioning around capital scale rather than manual winding craft.
The EU Green Deal vehicle CO2 mandate tightens fleet-average requirements through 2035, forcing OEM powertrain roadmaps toward efficiency-maximizing architectures. Flat wire motors satisfy these thresholds while enabling downsized thermal systems. European premium passenger vehicle programs are responding with integrated e-axle specifications that embed motor and inverter in single housings.
Fleet procurement departments are consolidating motor specifications across multiple vehicle programs to extract volume pricing and reduce qualification overhead. This specification compression displaces custom motor designs in favor of platform-shared variants. The pattern is most visible in China's domestic OEM consolidation, where group-level purchasing centralizes around Yangtze River Delta supply bases.
Electric Vehicle Flat Wire Motor Market Segmentation
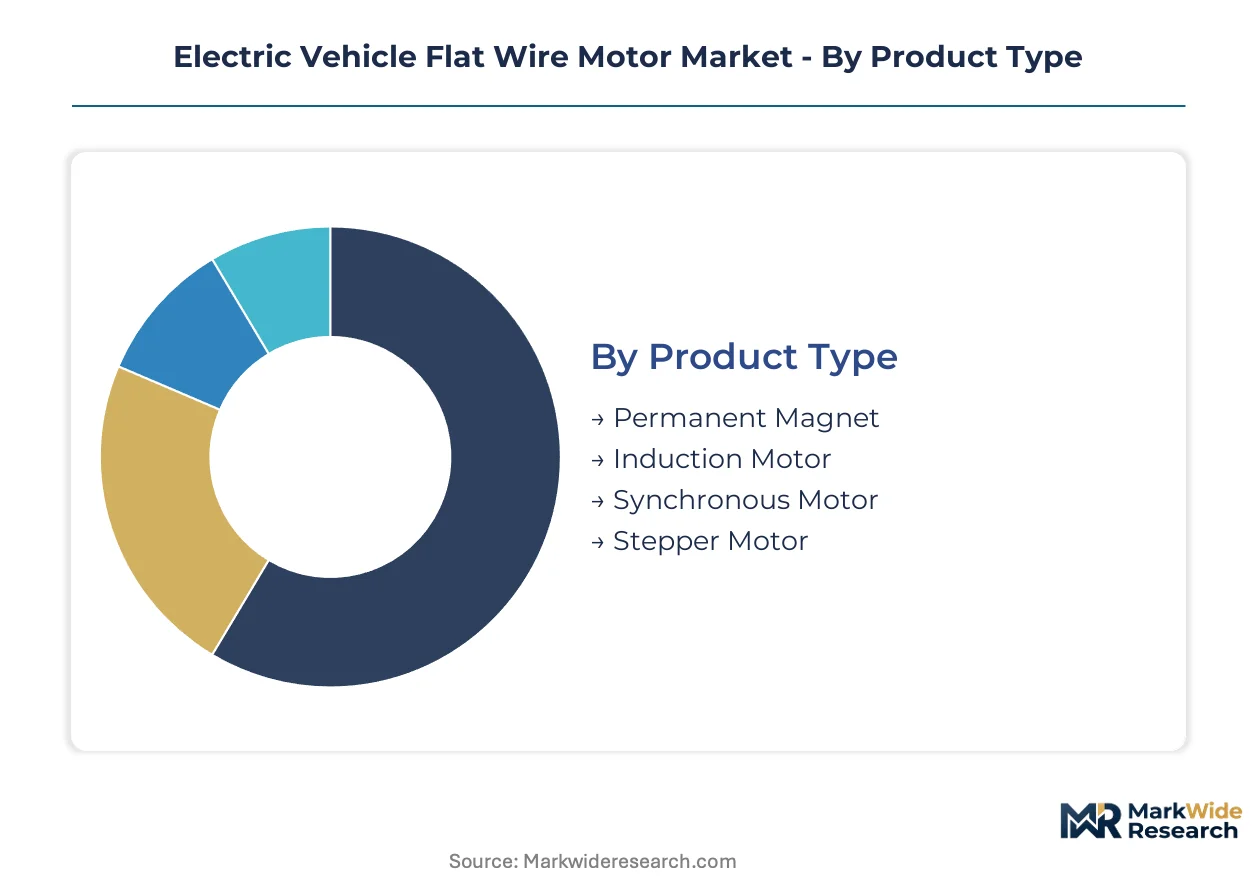
Flat wire motor procurement patterns diverge sharply across application contexts, with winding automation requirements and thermal integration complexity creating distinct investment thresholds for suppliers. Segment boundaries harden around power density specifications and platform bundling configurations that OEMs demand for axle packaging efficiency.
Product Type:
Permanent magnet configurations demand the steepest capital outlays due to rare-earth magnet supply security investments and precision rotor assembly lines.
- Permanent Magnet:Neodymium-iron-boron rotor assemblies achieve torque densities exceeding 4 kW/kg in passenger vehicle axle spaces. China's Yangtze River Delta manufacturing cluster concentrates procurement for domestic OEM electric platforms, though dysprosium price volatility forces hedge strategies.
- Induction Motor:Copper rotor cage designs eliminate rare-earth dependencies through aluminum or copper conductor bars. Commercial truck specifications in North America and Europe are shifting toward these architectures as fleet operators reject magnet cost exposure in heavy-duty duty cycles.
- Synchronous Motor:Wound-field rotor topologies enable field weakening for extended speed ranges without permanent magnet mass.
- Stepper Motor:Limited to auxiliary positioning applications within thermal management valves and active grille shutters.
Permanent magnet architectures absorb the bulk of installed capacity; induction motor specifications are expanding most quickly in commercial vehicle programs.
Technology:
Process control intensity separates competitive tiers, with hairpin winding automation requiring specialized capital equipment that limits supplier entry.
- Winding Technique:Hairpin forming and laser welding stations achieve 60-70% slot fill ratios that round wire cannot match. German and Japanese equipment suppliers dominate continuous wave winding line production, constraining motor manufacturer sourcing flexibility.
- Cooling System:Direct oil jet impingement and hollow-shaft liquid circuits manage copper loss heat flux in confined axle packages. Integrated thermal management convergence with inverter housings is compressing supplier interfaces toward subsystem specialists.
- Power Electronics:Silicon carbide inverter pairing reduces switching losses and enables higher motor operating frequencies.
- Control System:Field-oriented control algorithms with resolver or encoder position feedback optimize torque ripple and NVH performance.
Winding technique specialization commands premium positioning; cooling system integration is climbing the fastest as axle packaging density tightens.
End User:
Volume concentration and specification diversity create divergent margin structures across mobility segments.
- Passenger Vehicles:Platform-shared e-axle specifications dominate procurement, with China's domestic OEM consolidation centralizing purchasing around Yangtze River Delta supply bases. MIIT new energy vehicle credit quotas accelerate flat wire motor adoption in volume electric architectures.
- Commercial Trucks:Rare-earth alternative strategies and induction motor topologies gain specification share as fleet procurement departments reject magnet cost volatility. EPA greenhouse gas standards for heavy-duty vehicles force powertrain efficiency redesigns toward flat wire copper density advantages.
- Two-Wheelers:Cost-optimized hub motor configurations prioritize winding automation over thermal sophistication.
- Buses:Transit authority procurement cycles favor established suppliers with ECE R10 electromagnetic certification depth.
Passenger vehicles anchor production volume; commercial truck specifications are gaining share fastest as electrification penetrates heavy-duty segments.
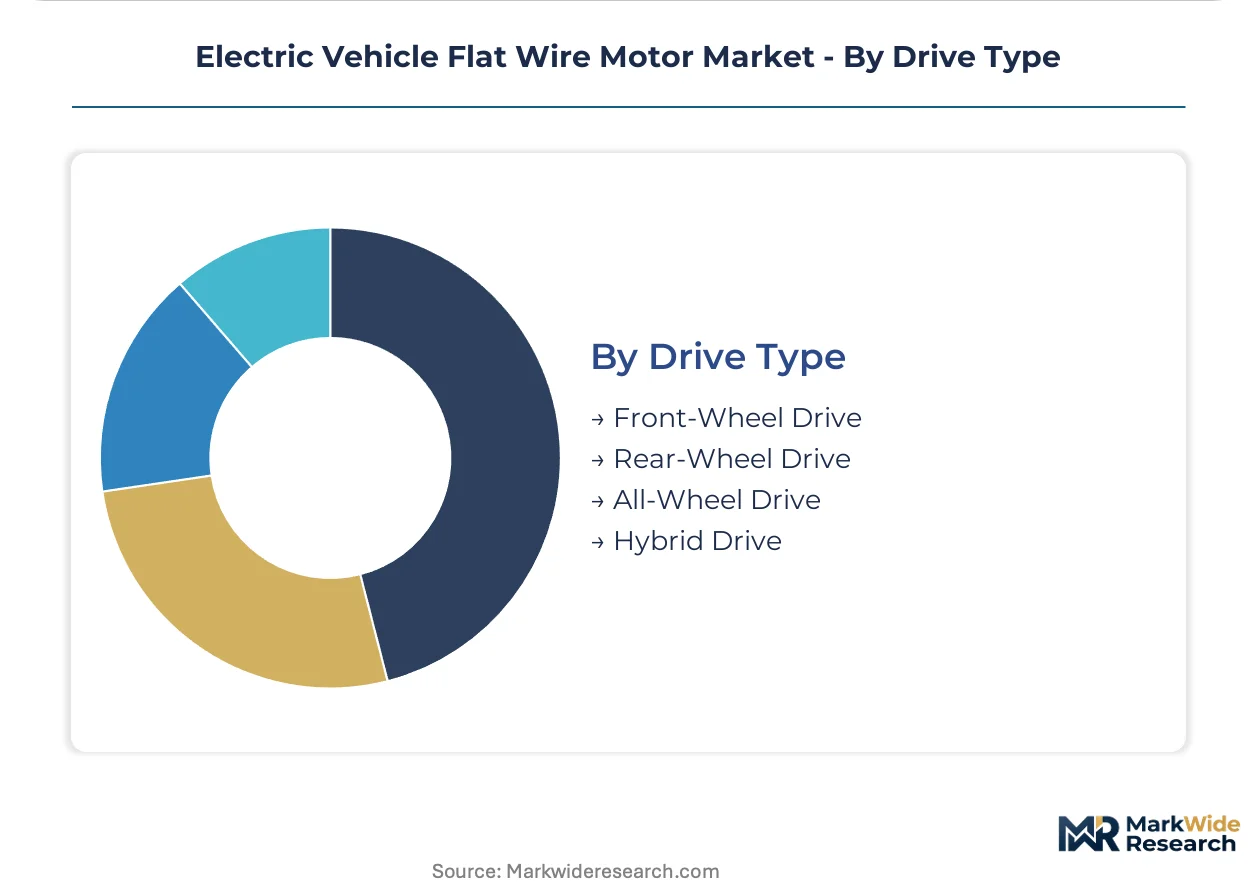
Drive Type:
Axle integration complexity scales with wheel torque distribution requirements, amplifying motor-inverter bundling value capture.
- Front-Wheel Drive:Transverse motor packaging constraints favor compact flat wire designs with integrated reduction gears. European A-segment and B-segment electric platforms specify these configurations for urban range optimization.
- All-Wheel Drive:Dual-motor architectures with torque vectoring demand synchronized control systems and matched thermal management circuits. Premium passenger vehicle programs in Germany and Japan specify these for performance differentiation.
- Rear-Wheel Drive:Longitudinal motor mounting enables larger diameter stators and improved power density.
- Hybrid Drive:Transmission-integrated motor generators require compact axial flux or concentric winding topologies.
Front-wheel drive configurations dominate unit economics; all-wheel drive specifications are expanding most quickly in premium platform lineups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of flat wire motor output while Europe and North America absorb premium integrated systems. Domestic OEM procurement concentrates in eastern manufacturing clusters. Regulatory pressure across three continents accelerates platform electrification timelines.
China
MIIT new energy vehicle credit quotas force domestic automakers toward high-efficiency motor architectures. The dual carbon goals framework tightens industrial emissions standards for motor production facilities. Yangtze River Delta suppliers co-locate with CATL and BYD battery plants to compress logistics costs.
Germany
Premium passenger OEMs specify integrated e-axle bundles that embed motor and inverter in single housings. The KBA enforces ECE R10 electromagnetic certification that extends qualification cycles for new entrants. Bavarian equipment suppliers dominate continuous wave winding line production for European motor manufacturers.
United States
EPA tailpipe standards compel powertrain redesigns toward copper-dense flat wire geometries that extend electric range. NHTSA safety standards add compliance layers favoring established suppliers with certification depth. Michigan and Ohio manufacturing corridors anchor motor assembly for Detroit Three electric platforms.
Japan
METI carbon neutrality roadmaps accelerate electrification investment across keiretsu supply networks. JIS standards govern precision winding tolerances that separate premium from standard-tier suppliers. Kansai and Chubu industrial belts concentrate hairpin winding automation expertise among tier-one component houses.
South Korea
Domestic battery majors backward-integrate into motor production to capture e-axle value chains. MFDS automotive component standards align with EU regulatory frameworks for export market access. Seoul Capital Area suppliers leverage proximity to Hyundai-Kia design centers for platform co-development.
Electric Vehicle Flat Wire Motor Market Competitive Landscape
The competitive structure tilts toward integrated powertrain specialists with winding automation depth. Tier-one automotive suppliers anchor premium contracts through multi-component bundling. Three archetypes dominate: capital-intensive winding equipment owners, rare-earth supply security players, and thermal integration specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification timelines favor incumbents.
Within the integrated powertrain tier, BorgWarner and Denso exemplify archetypes of bundling expertise and manufacturing scale respectively. Hitachi occupies a position among Japanese industrial conglomerates with electromagnetic design heritage. These three represent distinct geographic and capability anchors rather than interchangeable competitors.
| Leading Market Players |
|---|
| BorgWarner |
| Denso |
| Hitachi |
| Hasco |
| LG |
| Santroll |
| Huayu Automotive Systems |
| HYCET Technology |
| Tianjin Santroll Electric Technology |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ECE R10-qualified suppliers and uncertified competitors creates divergent pricing power and sourcing configurations across the electric vehicle flat wire motor landscape. MIIT credit system compliance in China and EPA efficiency mandates in the United States force OEMs toward validated suppliers, compressing procurement options while amplifying premium capture for qualified incumbents.
Pricing Analysis
Price erosion across standard-tier hairpin winding motors traces to automation scale advantages concentrated among Yangtze River Delta equipment owners. Contract-based long-term offtake agreements dominate procurement, with pricing stratifying across premium ECE R10-certified, standard MIIT-compliant, and economy non-certified tiers. Volume scale and thermal integration bundling drive differentiation, with fleet procurement departments in commercial trucks exhibiting highest price sensitivity while premium passenger OEMs absorb certification premiums.
Supply Chain Analysis
Domestic-content mandates in China's new energy vehicle credit system reshape sourcing toward Yangtze River Delta co-location with CATL and BYD battery plants. Manufacturing concentrates in China, Germany, and Japan, with copper conductor supply drawing from Chilean mining operations and rare-earth magnet feedstock resting on Chinese processing dominance. Single-source vulnerability in continuous wave winding equipment from German and Japanese suppliers poses structural risk. Distribution runs through Tier 1 powertrain integrators bundling motor-inverter-thermal systems for OEM platform delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
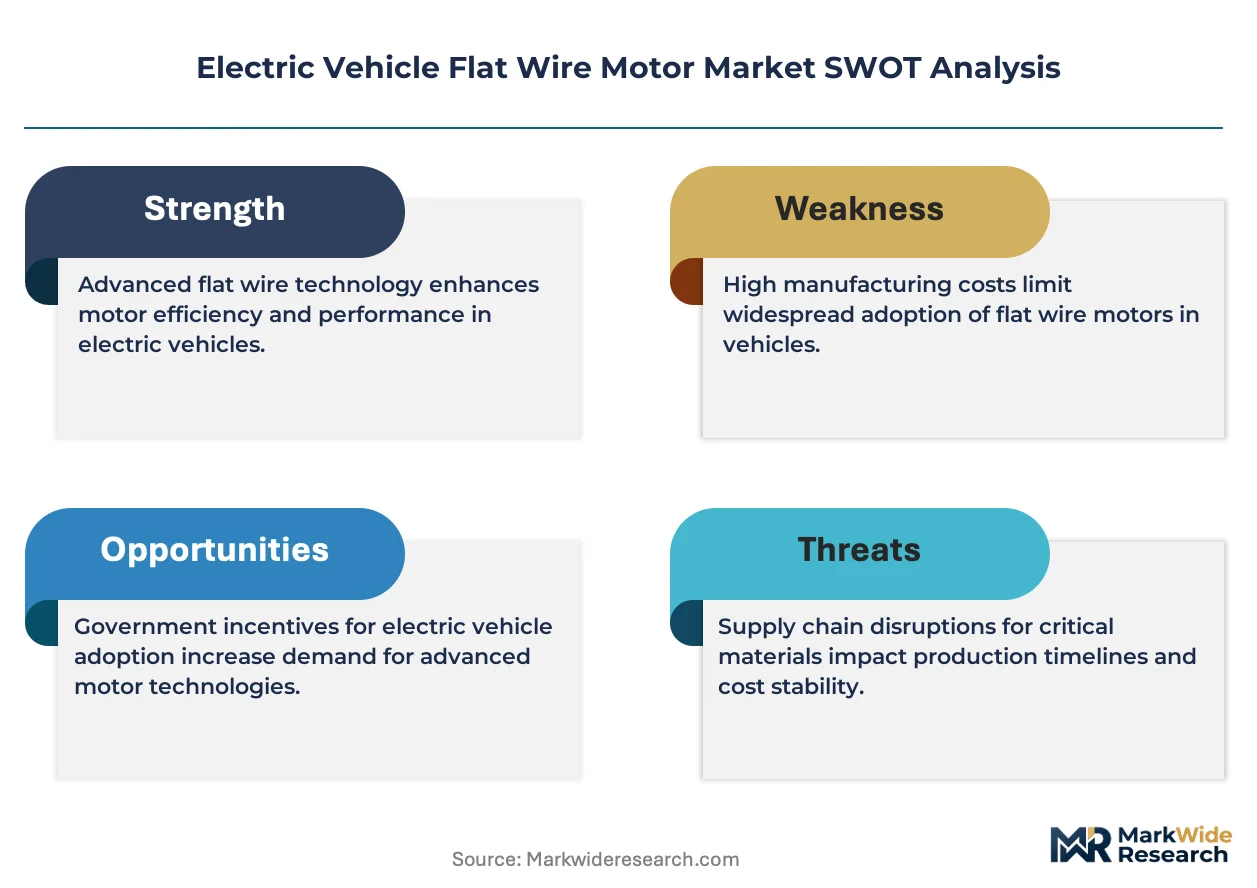
Hairpin winding automation capacity scarcity props pricing power for qualified suppliers, creating supply-constrained conditions that favor incumbents with capital equipment depth over emerging competitors lacking certification timelines.
For Market Incumbents: Cement multi-component bundling contracts with premium OEMs before platform standardization consolidates procurement around integrated e-axle specifications. Expand winding automation capacity in Yangtze River Delta manufacturing corridors to capture China's MIIT credit-driven volume concentration. Rare-earth cost volatility and induction motor substitution threats in commercial trucks demand hedge strategies through copper rotor cage technology licensing. For New Entrants and Emerging Players: Tier 2 commercial truck fleet operators represent the most penetrable channel partner type for induction motor architectures rejecting magnet cost exposure. Target North American heavy-duty electrification programs where EPA greenhouse gas standards force powertrain redesigns without established supplier lock-in. White-space exists in thermal-integrated subsystem co-development with emerging battery-electric truck platforms seeking axle packaging optimization. For Investors and Strategic Acquirers: Re-rating potential sits with winding automation specialists possessing ECE R10 certification depth given EU Green Deal CO2 mandate acceleration through 2035. Long-term viability favors acquisition targets with hairpin forming and laser welding equipment ownership anchored in qualified supplier relationships. Monitor induction motor specification share in commercial truck RFPs as inflection indicator for rare-earth substitution trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around shared e-axle specifications compresses motor diversity toward volume-efficient architectures. |
| Battery Supply Agreement | Co-location with CATL and BYD in Yangtze River Delta clusters reduces logistics friction for integrated powertrain delivery. |
| Software-Defined Vehicle Investment | Field-oriented control algorithm development enables torque ripple optimization for NVH-sensitive premium platforms. |
| Geographic Manufacturing Footprint | Michigan and Ohio corridors anchor Detroit Three electrification programs under tightening EPA tailpipe standards. |
| Charging Infrastructure Partnership | Commercial truck fleet electrification demands coordinated motor-inverter-thermal bundling with depot charging hardware. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 powertrain procurement leads, and hairpin winding equipment manufacturers underwrites the qualitative findings in this study. Primary interviews with thermal management specialists and e-axle integration engineers combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of automotive suppliers, and MIIT new energy vehicle credit disclosures. Bottom-up motor shipment estimates triangulate against top-down electric vehicle production forecasts across the analysis window.
Comparable-period anchoring to historical flat wire motor adoption curves in China's Yangtze River Delta cluster informed the projection horizon. The analytical framework models segmentation across vehicle class, propulsion architecture, winding technique specialization, and regional production cluster. CAGRs derive from volume trajectory synthesis against efficiency mandate tightening schedules. Copper density improvement curves and rare-earth price volatility scenarios constitute key forecast inputs.
Caveats apply where rare-earth supply disruptions or induction motor technology breakthroughs could materially shift the outlook toward magnet-free architectures. Forecasts reflect assumptions around MIIT credit system continuity, EPA tailpipe standard enforcement timelines, and ECE R10 certification backlog resolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Motor Soft Starter Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Electric AC Motors Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
North America Electric Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Europe Electric Commercial Vehicle Battery Pack Market
Electric Motor
Starter Motor Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Global Automotive Onboard Charger Market