
 Europe Electric Commercial Vehicle Battery Pack Market | 2026-2036
Europe Electric Commercial Vehicle Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Commercial Vehicle Battery Pack Market Insights
Poland and Hungary are reconfiguring Central European battery supply chains through new cell-to-pack assembly investments. Northvolt AB anchors Nordic production with in-house cathode active material processing and renewable energy integration. CATL leverages its Erfurt gigafactory footprint to sustain cost-competitive LFP supply for regional van and truck builders. Samsung SDI differentiates through high-nickel NMC chemistry leadership in premium long-haul applications.
Europe electric commercial vehicle battery pack denotes an integrated energy storage system comprising cells, modules, thermal management, and battery management electronics housed in a structural enclosure rated for commercial duty cycles, typically operating at 400-800V with energy densities between 160-300 Wh/kg depending on chemistry. The assembly converts stored electrochemical energy into traction power for buses, trucks, and delivery vehicles while managing degradation across thousands of deep-discharge cycles. LFP chemistry dominates urban logistics and food delivery fleets where cost-per-cycle and thermal stability outweigh gravimetric density requirements. NMC variants capture premium positioning in long-distance freight and public transport buses demanding maximum range per installed kilowatt-hour. Solid-state technology attracts early development funding for next-generation platforms, though lithium-ion architectures retain near-term manufacturing scale advantages across all capacity tiers from 100 kWh last-mile vans through 400 kWh regional haulers.
The EU Green Deal, F-Gas Regulation, and CE marking directives collectively mandate carbon-intensity thresholds and safety certification pathways that determine product eligibility for public procurement tenders. ECHA substance restrictions under REACH and RoHS constrain cobalt sourcing and recyclability design, pushing manufacturers toward chemistry diversification and closed-loop material recovery. Battery pack stakeholders must monitor how the EU AI Act and impending battery passport requirements reshape traceability obligations and aftermarket value capture across European commercial vehicle operating leases.
Market Dynamics
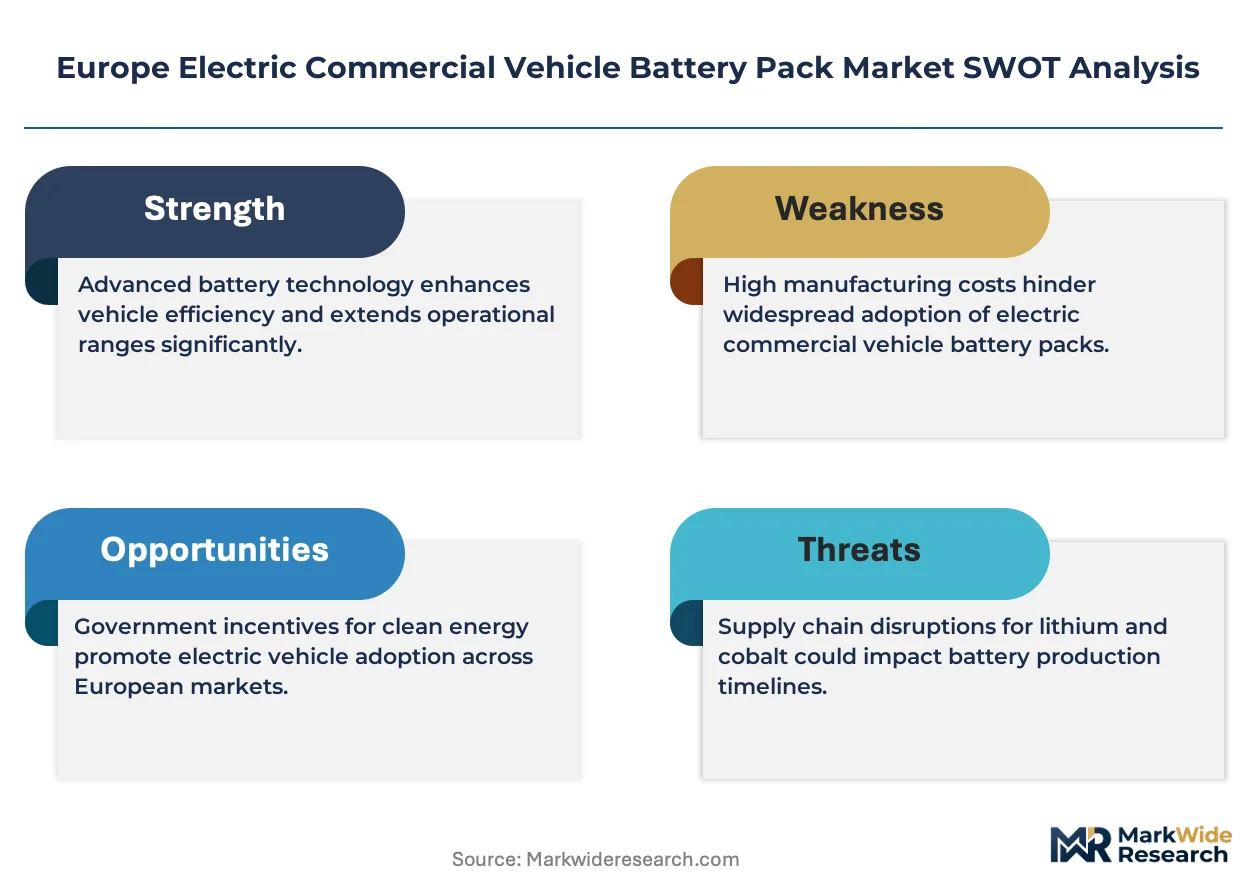
The EU Green Deal's tightening CO2 standards for heavy-duty vehicles are compressing fleet electrification timelines, forcing logistics operators to accelerate battery procurement before 2025 compliance windows close. This regulatory pressure is reshaping supplier relationships and capacity allocation across European cell-to-pack assembly networks.
Growth Catalysts
- EU Green Deal mandates:Binding carbon-intensity thresholds for commercial fleets trigger accelerated procurement cycles for high-capacity battery systems in regional haulage corridors.
- Urban freight electrification:Last-mile delivery operators in Germany, France, and the Netherlands deploy LFP chemistry packs to exploit superior cycle life and thermal stability in stop-start duty profiles.
- Battery passport traceability:Upcoming EU regulations mandate full lifecycle documentation, creating captive demand for integrated pack-as-a-service business models.
Market Restraints
- Cobalt supply concentration:ECHA REACH substance restrictions constrain DRC-sourced material availability, forcing chemistry reformulation toward nickel-heavy or iron-phosphate alternatives.
- Cell production bottlenecks:European cathode active material capacity lags behind pack assembly investments, creating upstream shortages for regional truck builders.
- Grid infrastructure lag:Distribution network upgrades along the TEN-T core network corridors proceed slower than fleet electrification schedules, limiting high-power charging deployment.
Strategic Opportunities
- Polish battery corridor:New cell-to-pack assembly investments in Lower Silesia offer proximity to German automotive demand while accessing lower-cost engineering talent pools.
- Second-life stationary storage:Retired commercial vehicle packs with 70-80% residual capacity unlock grid-balancing revenue streams for fleet operators.
- Solid-state pre-development:Early funding for sulfide-electrolyte architectures targets premium long-haul segments where energy density premiums justify manufacturing scale-up risks.
Industry Challenges
- Thermal engineering talent scarcity:Pack-level thermal management design expertise concentrates among automotive incumbents, constraining startup scaling.
- CE marking timeline compression:Safety certification pathways for 800V architectures face testing backlogs at notified bodies, delaying product launches.
- Legacy fleet integration:Retrofit compatibility with existing truck chassis requires bespoke mechanical and electrical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Commercial Vehicle Battery Pack Market |
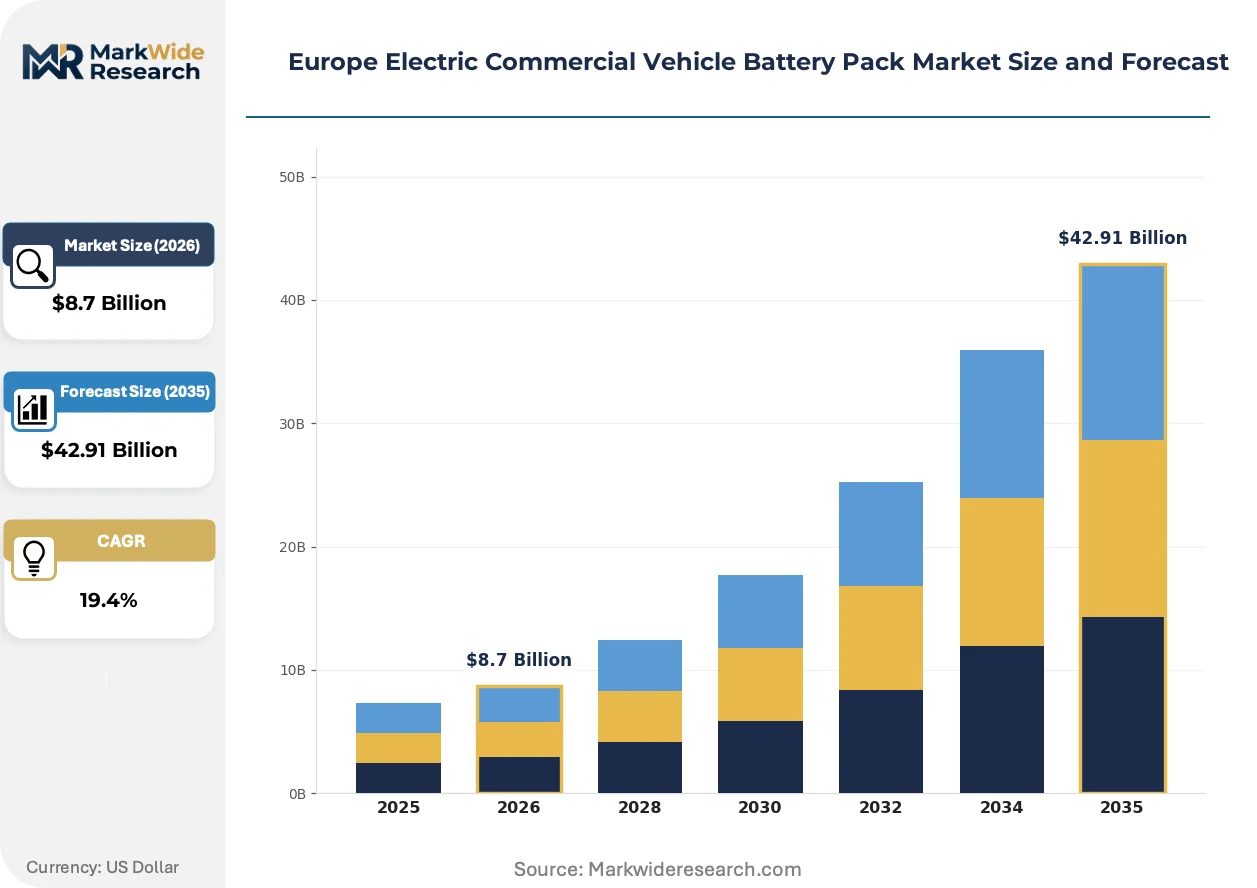
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, LTO, NCA Capacity: 100 kWh, 200 kWh, 300 kWh, 400 kWh Technology: Lithium-ion, Solid State, NiMH, Flow Battery End User: Logistics, Public Transport, Freight, Food Delivery |
| Companies Covered | Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution Ltd., Samsung SDI Co. Ltd., BYD Company Ltd., Panasonic Holdings Corporation, Northvolt AB, Toshiba Corporation, BMZ Holding GmbH, Akasol AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Commercial Vehicle Battery Pack Market Trends and Innovations
Digital twin architectures are penetrating battery pack engineering workflows, compressing validation cycles and enabling predictive degradation modeling across heterogeneous fleet deployments.
Cell-to-pack structural designs are eliminating module housings to improve volumetric energy density. European van manufacturers adopt these architectures for 100-150 kWh configurations where packaging efficiency determines payload retention. This consolidation is virtualizing traditional tier-2 module supplier roles into direct cell-pack integration contracts.
The EU AI Act's risk classification framework is reshaping battery management system software development. Predictive algorithms for state-of-charge estimation now face conformity assessment requirements that extend certification timelines. Long-haul freight operators in Germany and France experience the steepest compliance cost increases as they deploy cloud-connected telematics.
Leasing structures are displacing outright purchase for battery assets in commercial vehicle fleets. Logistics operators in the Netherlands and Belgium prefer power-by-the-mile contracts that transfer degradation risk to pack suppliers. This shift concentrates financial underwriting capability among balance-sheet-strong manufacturers and specialized battery financiers.
Europe Electric Commercial Vehicle Battery Pack Market Segmentation
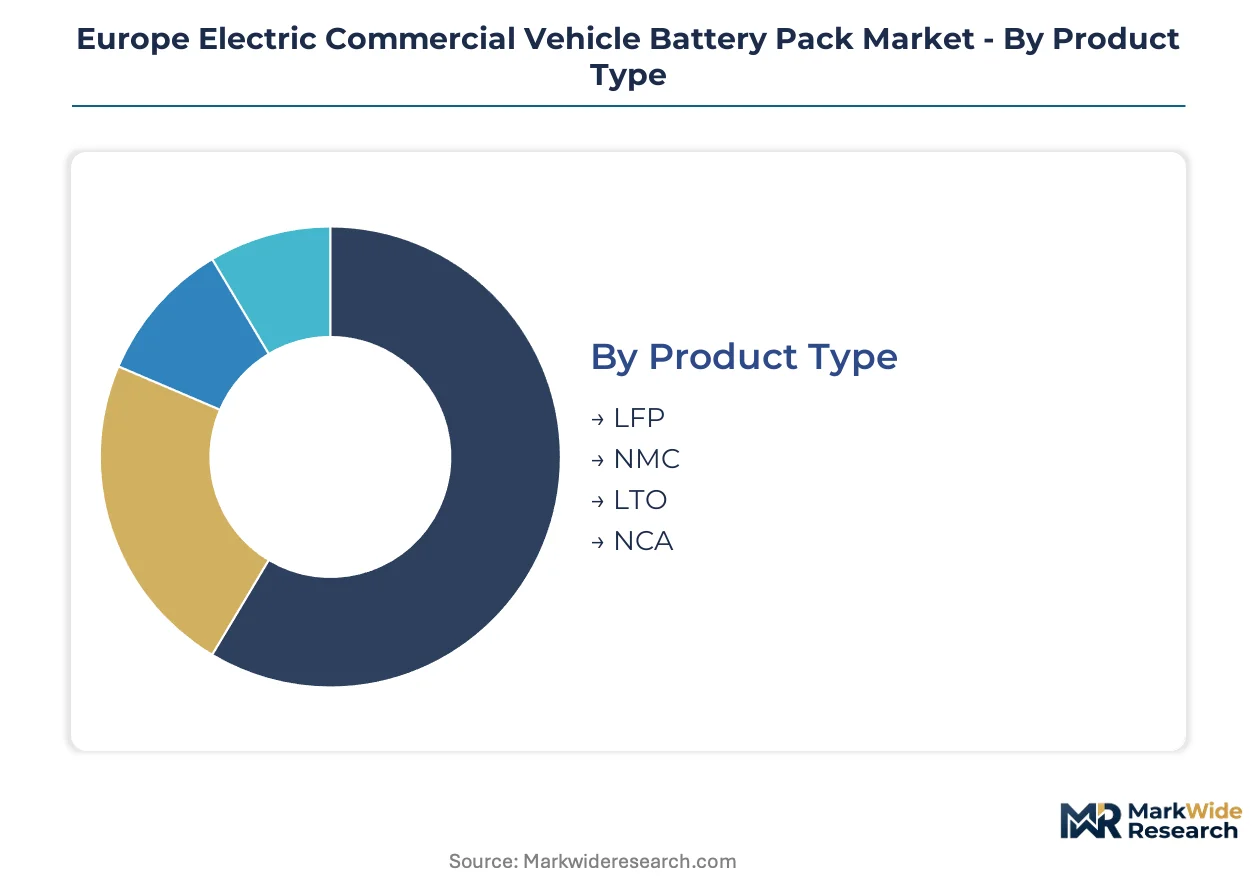
Fleet electrification timelines vary sharply across chemistry types and duty cycles. Understanding segment turnover rates enables suppliers to align capacity investments with procurement windows that range from 18-month van replacement cycles to 8-year heavy-duty truck depreciation schedules.
Product Type:
LFP chemistry turns over fastest in urban delivery fleets where thermal stability drives replacement decisions, while NMC packs cycle slower in long-haul applications where energy density premiums justify extended service life.
- LFP:Iron-phosphate cathodes deliver 4,000+ deep-discharge cycles with minimal thermal runaway risk. German food delivery operators in Berlin and Munich prioritize this chemistry for refrigerated van fleets where safety certification accelerates municipal permit approvals.
- NMC:Nickel-manganese-cobalt layered oxides achieve 250-300 Wh/kg gravimetric density. Regional haulage corridors between Rotterdam and the Ruhr Valley concentrate demand for 300-400 kWh NMC configurations where payload-range tradeoffs determine fleet economics.
- LTO:Lithium-titanate anodes enable 10,000+ cycle lifespans at the cost of 70-80 Wh/kg density. Polish mining vehicle retrofitters specify LTO for underground operations where charging infrastructure constraints favor extreme longevity over energy density.
- NCA:Nickel-cobalt-aluminum formulations occupy niche positioning in premium coach bus segments. French intercity operators on Paris-Lyon routes deploy NCA packs where 350+ km single-charge capability supports competitive scheduling against diesel alternatives.
LFP dominates installed base. NMC is where expansion concentrates.
Capacity:
Cost tiers stratify sharply around charging infrastructure availability, with 100 kWh packs accessible to small fleet operators and 400 kWh systems requiring balance-sheet strength for depot charging investments.
- 100 kWh:Compact configurations serve last-mile parcel delivery in Dutch and Belgian urban centers. Stop-start duty profiles in Amsterdam and Antwerp exploit regenerative braking efficiency where daily distances rarely exceed 150 km.
- 200 kWh:Mid-range systems capture regional distribution routes between 200-400 km daily. Hungarian automotive parts suppliers operating Budapest-Vienna corridors specify this capacity tier where overnight depot charging eliminates en-route infrastructure dependency.
- 300 kWh:Heavy-duty regional haulage applications in the German Mittelstand logistics sector require this scale. Family-owned freight operators in Lower Saxony deploy 300 kWh NMC packs for overnight trunk routes between Bremen and Hamburg port facilities.
- 400 kWh:Maximum configurations target long-haul corridors with mandatory driver rest periods enabling high-power charging windows. Spanish-Portuguese cross-border freight on the Lisbon-Madrid axis represents emerging demand where EU TEN-T corridor electrification proceeds.
200 kWh systems anchor current procurement volumes. 400 kWh configurations are climbing the fastest as charging infrastructure matures.
Technology:
Manufacturing maturity determines supplier margins, with lithium-ion architectures generating positive unit economics while solid-state platforms consume development funding without near-term revenue contribution.
- Lithium-ion:Established cell-to-pack assembly networks across Poland, Hungary, and Germany sustain cost-competitive supply. CATL's Erfurt facility and Northvolt's Skellefteå complex anchor European production capacity for liquid-electrolyte architectures.
- Solid State:Sulfide and oxide electrolyte research programs target 400+ Wh/kg density thresholds. BMW and Volkswagen Group pre-development contracts with European solid-state specialists concentrate technical talent in Munich and Stuttgart engineering centers.
- NiMH:Mature nickel-metal hydride technology persists in hybrid bus retrofits where full electrification capital requirements exceed municipal budget cycles. Italian and Greek island municipalities specify NiMH for coastal tourist shuttle applications.
- Flow Battery:Vanadium redox systems occupy experimental positioning in grid-connected depot storage configurations. Dutch port authorities in Rotterdam pilot flow battery integration with shore power systems for berthed electric truck charging.
Lithium-ion retains manufacturing scale advantages. Solid-state is gaining share fastest in premium long-haul pre-development programs.
End User:
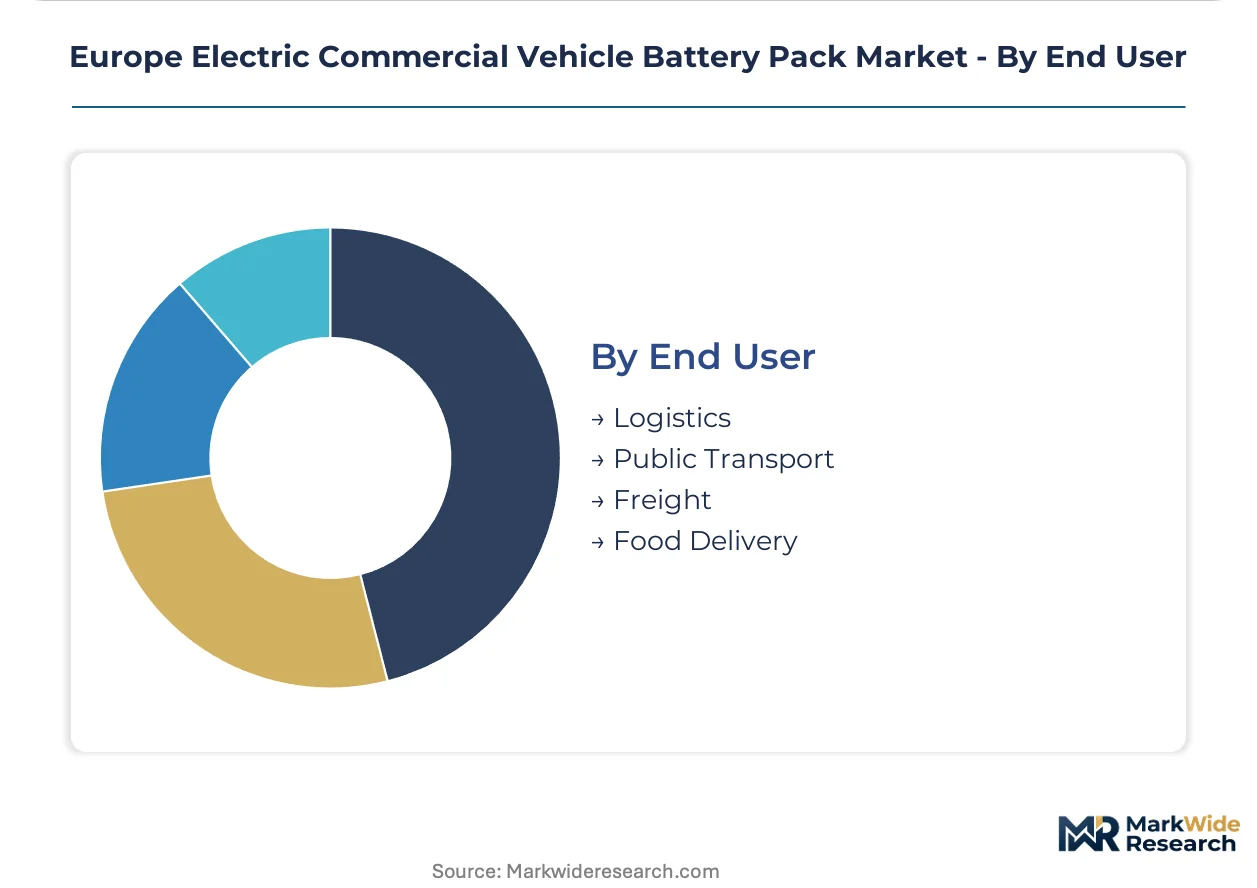
Customer concentration patterns diverge between fragmented last-mile operators and consolidated freight carriers, with procurement scale determining supplier negotiation leverage and pack-as-a-service contract structures.
- Logistics:Parcel and express delivery operators including DHL, DPD, and GLS deploy mixed chemistry fleets scaled to route density. German hub-and-spoke networks around Leipzig and Cologne prioritize LFP for urban distribution and NMC for intercity trunking.
- Public Transport:Municipal bus operators across France, the Netherlands, and Scandinavia specify high-capacity NMC configurations. Stockholm's SL and Amsterdam's GVB enforce 350+ km daily range requirements that eliminate opportunity charging infrastructure dependency.
- Freight:Heavy-duty trucking fleets in the Rhine-Alpine corridor face the steepest EU CO2 compliance pressure. Swiss and Austrian alpine freight operators specify 400 kWh systems where gradient climbing demands exceed flatland route energy consumption by 40-60%.
- Food Delivery:Temperature-controlled last-mile operators in Paris, London, and Madrid require thermal management integration with refrigeration systems. Cold chain logistics specialists prioritize LFP chemistry where simultaneous traction and cooling loads stress cell thermal stability.
Logistics commands the largest procurement volumes. Public transport is where expansion concentrates as municipal electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys NMC chemistry for long-haul freight corridors, while the Netherlands and France prioritize LFP systems for urban logistics where thermal stability outweighs energy density premiums in municipal procurement decisions.
Germany
Rhine-Alpine freight corridors drive demand for 300-400 kWh NMC configurations where payload-range tradeoffs determine fleet economics. The EU Green Deal's CO2 standards for heavy-duty vehicles compress compliance timelines through 2025. Northvolt's planned cathode active material processing in Heide anchors domestic supply chain expansion for premium long-haul applications.
Netherlands
Last-mile delivery operators in Amsterdam and Rotterdam exploit LFP chemistry's 4,000+ cycle lifespan for stop-start urban duty profiles. Battery passport traceability requirements under upcoming EU regulations accelerate pack-as-a-service contract adoption. The Randstad logistics cluster concentrates procurement volume for 100-150 kWh compact configurations serving parcel distribution networks.
France
Intercity coach operators on Paris-Lyon routes deploy high-nickel NMC packs where 350+ km single-charge capability supports competitive scheduling. CE marking directives and ECHA REACH substance restrictions constrain cobalt sourcing, pushing manufacturers toward chemistry diversification. The Auvergne-Rhône-Alpes region hosts engineering centers developing solid-state pre-development programs for next-generation platforms.
Poland
Lower Silesia's emerging cell-to-pack assembly investments target proximity to German automotive demand while accessing lower-cost engineering talent pools. F-Gas Regulation compliance pressures reshape thermal management system specifications for regional truck builders. Mining vehicle retrofitters in Silesian industrial zones specify LTO chemistry for underground operations where charging infrastructure constraints favor extreme longevity.
Sweden
Stockholm's SL municipal bus operator enforces 350+ km daily range requirements that eliminate opportunity charging infrastructure dependency. The EU AI Act's risk classification framework extends battery management system certification timelines for cloud-connected telematics deployments. Northvolt's Skellefteå gigafactory integrates renewable energy processing for in-house cathode material production serving Nordic commercial vehicle markets.
Europe Electric Commercial Vehicle Battery Pack Market Competitive Landscape
Capability concentration sits with integrated cell manufacturers possessing cathode material processing expertise; scale advantage sits with established Asian producers with European manufacturing footprints. The market structure tiers between chemistry specialists, system integrators, and captive automotive suppliers. Strategic archetypes include renewable-energy-integrated Nordic producers, cost-competitive LFP specialists, and high-nickel NMC leaders. Dominant competitive moves encompass cell-to-pack architecture investments and power-by-the-mile financing structures that transfer degradation risk to suppliers.
Among Asian-origin producers with European manufacturing presence, Contemporary Amperex Technology Co. Limited exemplifies scale-driven LFP supply positioning, while Samsung SDI Co. Ltd. occupies the high-nickel chemistry tier. Northvolt AB represents the renewable-energy-integrated archetype with in-house material processing capabilities. These three anchors demonstrate how geographic production placement and chemistry specialization stratify competitive positioning across the European commercial vehicle battery pack market.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution Ltd. |
| Samsung SDI Co. Ltd. |
| BYD Company Ltd. |
| Panasonic Holdings Corporation |
| Northvolt AB |
| Toshiba Corporation |
| BMZ Holding GmbH |
| Akasol AG |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Polish cell-to-pack assembly facilities is compressing supplier margins and accelerating contract renegotiations for German logistics operators seeking fixed-price offtake security. This utilization dynamic concentrates pricing power with cathode material processors while forcing pack integrators toward longer-term service bundling.
Pricing Analysis
Long-term offtake contracts dominate procurement between fleet operators and integrated cell manufacturers, with spot purchasing limited to emergency capacity fills. Price differentiation rests on chemistry tier and volume scale, with NMC packs commanding premiums over LFP equivalents for high-nickel formulations. Cost compression in LFP configurations is intensifying as CATL's Erfurt facility expands output for regional van builders. Small fleet operators in Belgian urban logistics exhibit the highest price sensitivity, while Rhine-Alpine freight carriers prioritize energy density over per-kWh cost.
Supply Chain Analysis
Extended payment terms from German OEMs are reshaping working capital requirements for Polish and Hungarian pack assemblers, with supply-chain finance facilities increasingly intermediating component procurement. European production draws from Chinese cathode precursor supply, South Korean separator technology, and domestic German electrolyte formulation. Single-source vulnerability concentrates in cobalt hydroxide shipments from DRC via Antwerp processing hubs. Distribution runs through Tier 1 system integrators holding direct OEM relationships, with module suppliers virtualized by cell-to-pack consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around EU battery passport requirements and CE marking pathways creates durable incumbent advantages. Switching costs for fleet operators escalate as integrated telematics and degradation-risk transfer contracts deepen supplier relationships.
For Market Incumbents: Build certification moats by accelerating CE marking investments for 800V architectures before notified body backlogs extend further. Secure cathode active material supply through backward integration into precursor processing, countering the cell production bottlenecks threatening regional truck builders. DPD and GLS procurement consolidation represents the primary margin pressure point requiring volume commitment defense. For New Entrants and Emerging Players: Pursue white-space positioning in Polish mining vehicle retrofit applications where LTO chemistry demand outpaces established supplier attention. Target second-life stationary storage services for Dutch grid operators seeking retired commercial pack capacity. A pack-as-a-service financing angle bypasses capital constraints blocking smaller fleet electrification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state pre-development programs as BMW and Volkswagen Group concentrate technical talent in Munich and Stuttgart engineering centers. Acquisition targets should concentrate on thermal engineering specialists possessing pack-level management expertise, where automotive incumbent concentration constrains startup scaling. Watch for EU AI Act conformity assessment timeline extensions as the signal indicating cloud-connected BMS deployment cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Investment | Eliminates module supplier tier, improving volumetric density for 100-150 kWh van configurations. |
| Cathode Active Material Backward Integration | Northvolt's Heide facility reduces DRC cobalt dependency under tightening ECHA REACH restrictions. |
| Power-by-the-Mile Financing Structure | Transfers degradation risk to suppliers, concentrating financial underwriting among balance-sheet-strong manufacturers. |
| Battery Passport Traceability System | Creates captive demand for integrated pack-as-a-service business models under upcoming EU regulations. |
| Solid-State Sulfide-Electrolyte Pre-Development | BMW and Volkswagen Group contracts target 400+ Wh/kg density for premium long-haul segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, automotive production databases, and customs trade records. Battery pack engineering directors, fleet procurement managers at DHL and DPD, and cathode material supply specialists provided operational perspective. ECHA substance restriction updates, CE marking directive amendments, and TEN-T corridor electrification schedules furnished external validation. Bottom-up capacity assessments triangulate against top-down fleet electrification mandate compliance modeling.
Forecast inputs incorporate chemistry-specific adoption curves, charging infrastructure deployment rates along core logistics corridors, and OEM platform electrification timelines. Segmentation dimensions span chemistry type, capacity tier, vehicle duty cycle, and regional regulatory cluster. CAGRs derive from installed base turnover analysis and replacement cycle compression under EU CO2 standards. Cell production capacity utilization rates and cathode material supply lag indicators inform trajectory sensitivity.
Sensitivities concentrate around ECHA REACH amendment timing, notified body certification backlog resolution, and TEN-T high-power charging deployment pace. Forecasts reflect assumptions regarding fleet operator procurement acceleration and supplier capacity alignment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Propulsion Systems Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Electric AC Motors Market
Electric Motor
High Speed Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
United States AC Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Global Hub Motors Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market