
 North America Electric Motor Market | 2026-2036
North America Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Motor Market Intelligence
The capability gap between integrated motor-drive suppliers and component assemblers is collapsing as electrification standards tighten across North America. ABB Ltd leverages its vertical integration in power electronics to sustain margin advantages in medium-voltage industrial applications. Siemens AG anchors its position through dense service networks across the US Midwest manufacturing belt.
An electric motor converts electrical energy into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, typically operating at efficiencies exceeding IE3 premium levels under NEMA MG-1 or IEC 60034 frameworks. AC Motors dominate installed base volumes across HVAC and industrial pump applications where induction technology offers proven durability. Servo Motors command premium positioning in precision robotics and aerospace actuation systems where closed-loop control and rapid torque response justify higher unit economics.
The US Department of Energy enforces minimum efficiency standards under NEMA MG-1 and EPAct regulations, while Canada's Natural Resources Canada administers comparable MEPS requirements that effectively bar sub-IE3 equipment from cross-border commerce. Mexico's CONUEE alignment with North American harmonization protocols creates a unified compliance perimeter for manufacturers serving integrated supply chains. Stakeholders must monitor how impending revisions to IEEE 841 and CSA C390 efficiency test methods reshape product development priorities and factory certification investments.
Market Dynamics
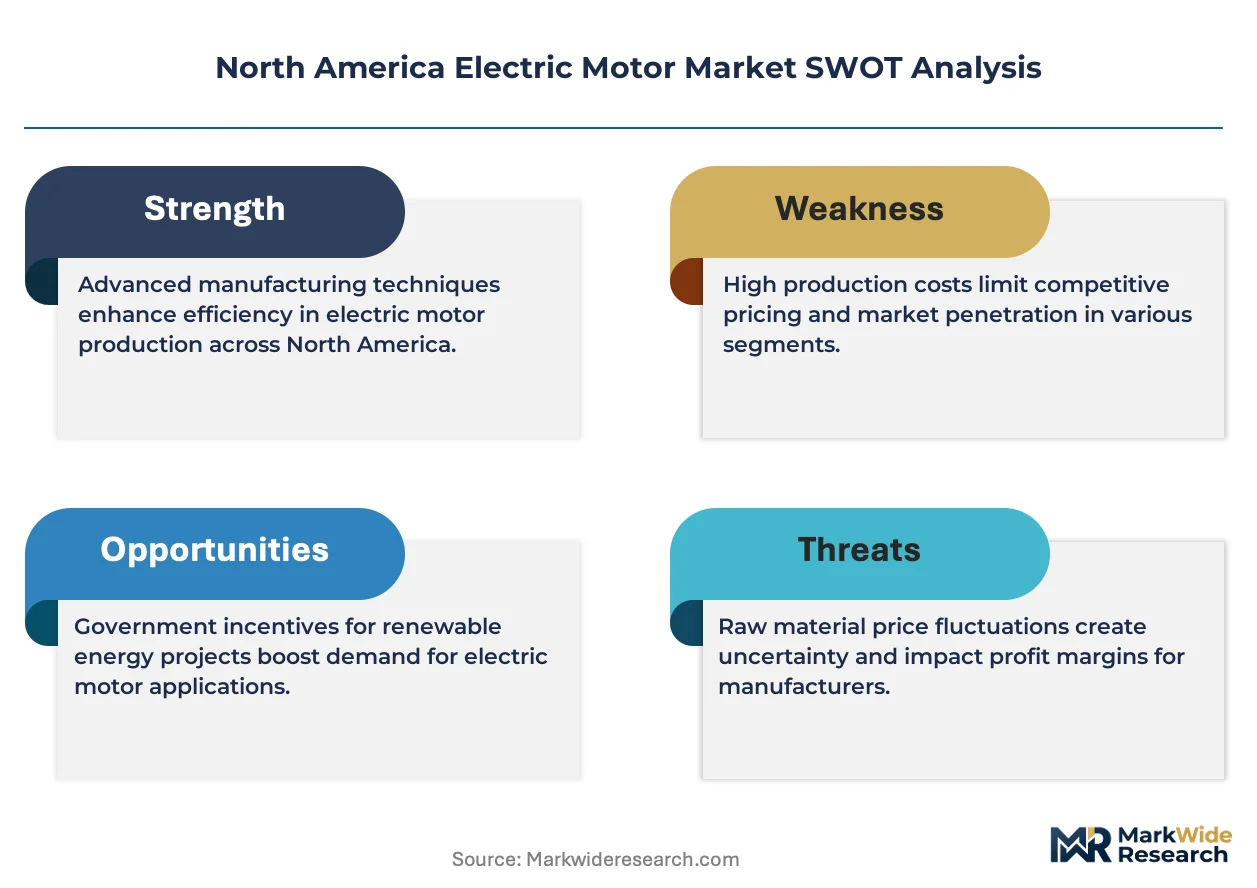
IE4 and IE5 ultra-premium efficiency mandates are compressing the supplier base across North America as smaller assemblers lack capital to redesign stator laminations and rotor die-castings for the next NEMA MG-1 revision cycle.
Growth Catalysts
- US Department of Energy EPAct efficiency tiers:Minimum performance floors now exclude IE2 equipment from federal procurement contracts, forcing industrial buyers toward premium induction and permanent magnet motor platforms.
- Electric vehicle powertrain integration:Traction motor demand from Detroit Three and Tesla Gigafactory supply chains is pulling high-speed permanent magnet and switched reluctance designs into volume production.
- Ontario automotive supplier belt concentration:Tier-1 motor suppliers cluster around St. Catharines and Windsor to serve just-in-time delivery requirements for Canadian EV assembly plants.
Market Restraints
- Neodymium-dysprosium price volatility:Rare earth magnet cost swings from Chinese export quotas destabilize permanent magnet motor bill-of-materials forecasting for US manufacturers.
- Stator core lamination supply concentration:Grain-oriented electrical steel production concentrates in Indiana and Ohio mills, creating single-source vulnerability for medium-voltage motor builders.
- IEC 60034-2-1 test method harmonization delays:Divergent IEEE 841 and CSA C390 efficiency measurement protocols force redundant certification spending for cross-border product lines.
Strategic Opportunities
- US Inflation Reduction Act clean manufacturing tax credits:Section 45X advanced manufacturing credits offset capital costs for domestic motor core stamping and winding automation investments.
- Predictive maintenance sensor integration:Vibration and thermal monitoring embedded at the motor-drive interface opens recurring revenue streams for industrial service providers.
- Mexico CONUEE alignment with NEMA standards:Harmonized efficiency labeling creates unified product platforms for maquiladora supply chains serving integrated North American automotive production.
Industry Challenges
- High-voltage insulation expertise scarcity:Medium-voltage motor winding design requires specialized VPI resin and mica tape application skills that aging US manufacturing workforces no longer cultivate.
- Legacy DC motor retrofit complexity:Industrial facilities running Ward Leonard drive systems face control architecture incompatibility when upgrading to AC variable frequency platforms.
- CSA C390 third-party certification backlog:Testing laboratory capacity constraints extend product launch timelines for Canadian market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Motor Market |
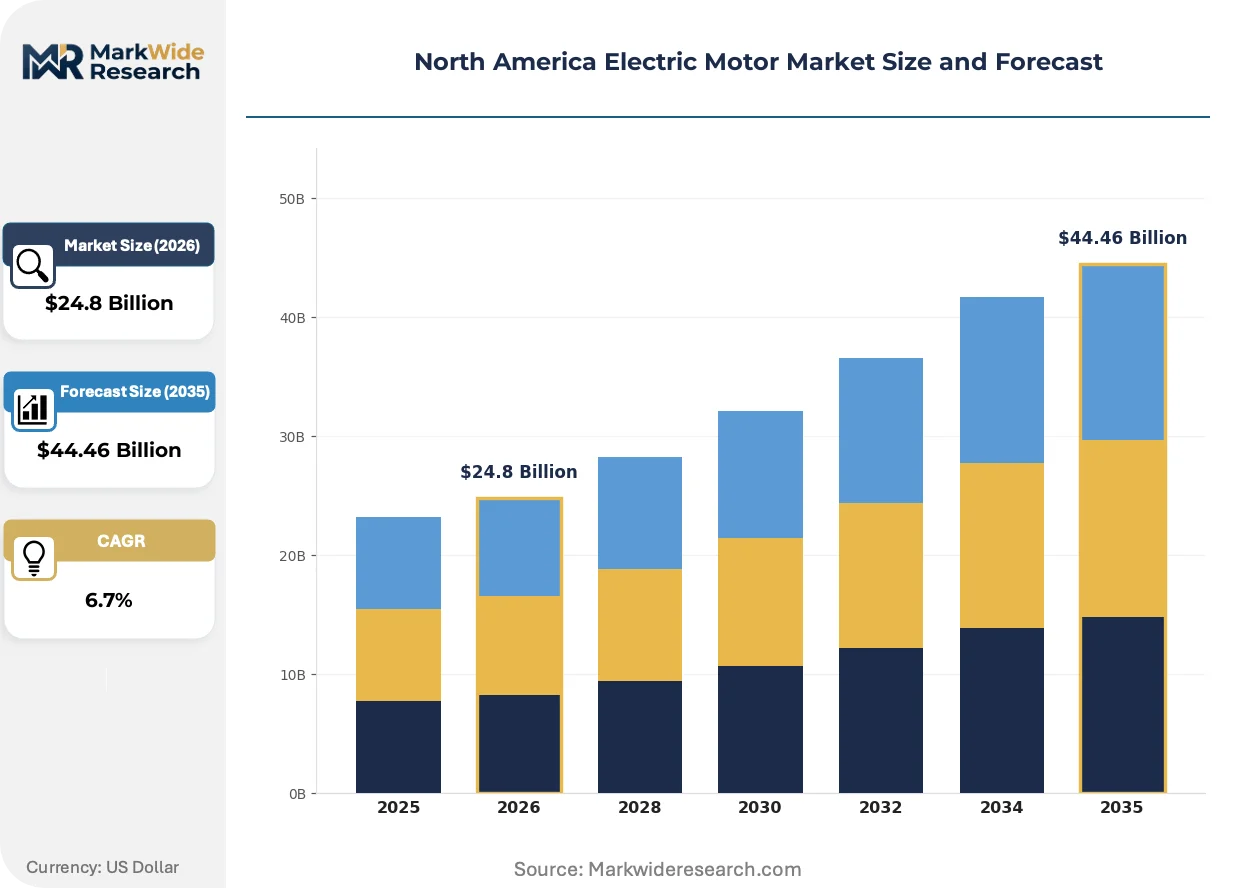
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors End User: Automotive, Aerospace, Industrial Machinery, HVAC Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Technology: Brushless, Brushed, Induction, Synchronous |
| Companies Covered | ABB Ltd, Siemens AG, General Electric Company, Rockwell Automation, AMETEK, Inc., Johnson Electric Holdings Limited, Nidec Motor Corporation, Regal Rexnord Corporation, Mitsubishi Heavy Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Motor Market Strategic Shifts & Innovations
Silicon carbide power electronics and advanced magnetic materials are rewriting motor-drive system architectures. Permanent magnet synchronous designs now penetrate applications once dominated by induction technology.
Axial-flux motor topologies are displacing radial-flux configurations in commercial vehicle traction applications where packaging constraints dominate. Daimler and Volvo Group procurement teams specify pancake-form-factor motors for battery-electric medium-duty trucks. The technology is displacing conventional frame-size induction motors in weight-sensitive mobile equipment segments.
Canada's Natural Resources Canada MEPS revision cycle tightens minimum efficiency thresholds for 1-200 horsepower general-purpose motors. The regulation compresses margins for component assemblers lacking in-house lamination stamping capabilities. Ontario-based HVAC OEMs accelerate IE4 platform transitions to maintain federal and provincial procurement eligibility.
Integrated motor-drive systems with embedded condition monitoring reshape aftermarket service economics. Food and beverage processors in the US Great Lakes corridor now specify vibration-sensor-equipped washdown motors to eliminate unplanned downtime. The shift compresses traditional spare parts distribution channels as predictive analytics replace scheduled maintenance contracts.
North America Electric Motor Market Segmentation
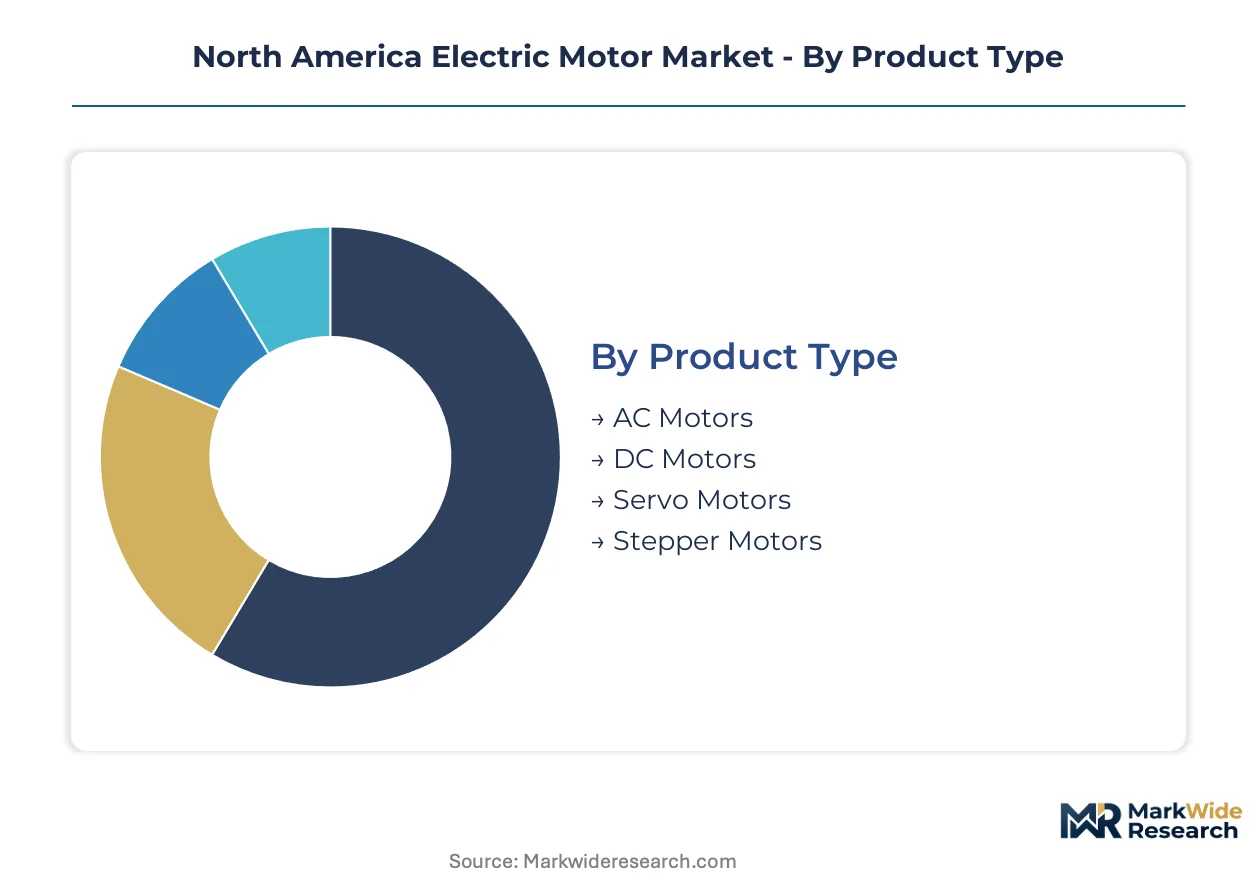
Segmentation reveals how efficiency mandates and electrification trends concentrate demand across distinct technical specifications. Procurement patterns diverge sharply between industrial buyers seeking NEMA MG-1 compliance and automotive OEMs integrating power-dense traction systems.
Product Type:
AC Motors anchor domestic manufacturing demand across the US Great Lakes corridor, while DC and servo platforms skew toward export-oriented precision applications.
- AC Motors:Induction and synchronous designs dominate HVAC and pump installations where NEMA MG-1 efficiency tiers mandate IE3 minimums. Procurement concentrates in Ohio and Indiana steel-belt manufacturing clusters serving federal infrastructure contracts.
- DC Motors:Brushed and brushless configurations persist in legacy industrial drives and battery-electric material handling equipment. Ward Leonard retrofit demand from aging US paper mills constrains upgrade cycles despite efficiency penalties.
- Servo Motors:Closed-loop precision systems command premium positioning in Michigan automotive robotics and Canadian aerospace actuation.
- Stepper Motors:Open-loop positioning drives populate 3D printing and medical device manufacturing across Ontario and Illinois.
AC Motors holds the largest share; momentum sits with Servo Motors as EV powertrain integration accelerates.
End User:
Cost tier stratification separates commodity motor procurement from engineered system integration, with automotive and aerospace commanding 3-5x unit economics over HVAC.
- Automotive:Traction motor demand from Tesla Gigafactory and Detroit Three supply chains pulls high-speed permanent magnet designs into volume production. Ontario's Windsor-St. Catharines corridor anchors just-in-time delivery for Canadian EV assembly.
- Aerospace:Actuation systems require fault-tolerant brushless designs with MIL-STD-810 environmental qualification. Boeing and Bombardier procurement specifications drive electromagnetic compatibility testing investments.
- Industrial Machinery:General-purpose induction motors serve pump and compressor OEMs across Pennsylvania and Wisconsin.
- HVAC:Fan and blower applications in commercial buildings face DOE furnace fan efficiency standards tightening minimum performance.
Industrial Machinery holds the largest share; momentum sits with Automotive as powertrain electrification climbs the fastest.
Power Rating:
Volume concentration sits in low-voltage fractional horsepower, while margin capture concentrates in medium-voltage industrial drives where insulation expertise scarcity protects pricing.
- Low Voltage:Fractional and integral horsepower units populate residential appliances and commercial HVAC across the US Southeast manufacturing belt. DOE appliance standards compress margins for import-dependent assemblers.
- Medium Voltage:2.3-13.8kV systems serve oil and gas extraction in Alberta and Texas Permian Basin operations. VPI resin and mica tape winding skills concentrate in aging US workforces.
- High Voltage:Mining and metals processing in Minnesota Iron Range and Quebec demand ruggedized frame designs.
- Ultra High Voltage:Specialized traction and grid applications remain captive to ABB and Siemens integrated offerings.
Low Voltage holds the largest share; momentum sits with Medium Voltage as industrial electrification expands most quickly.
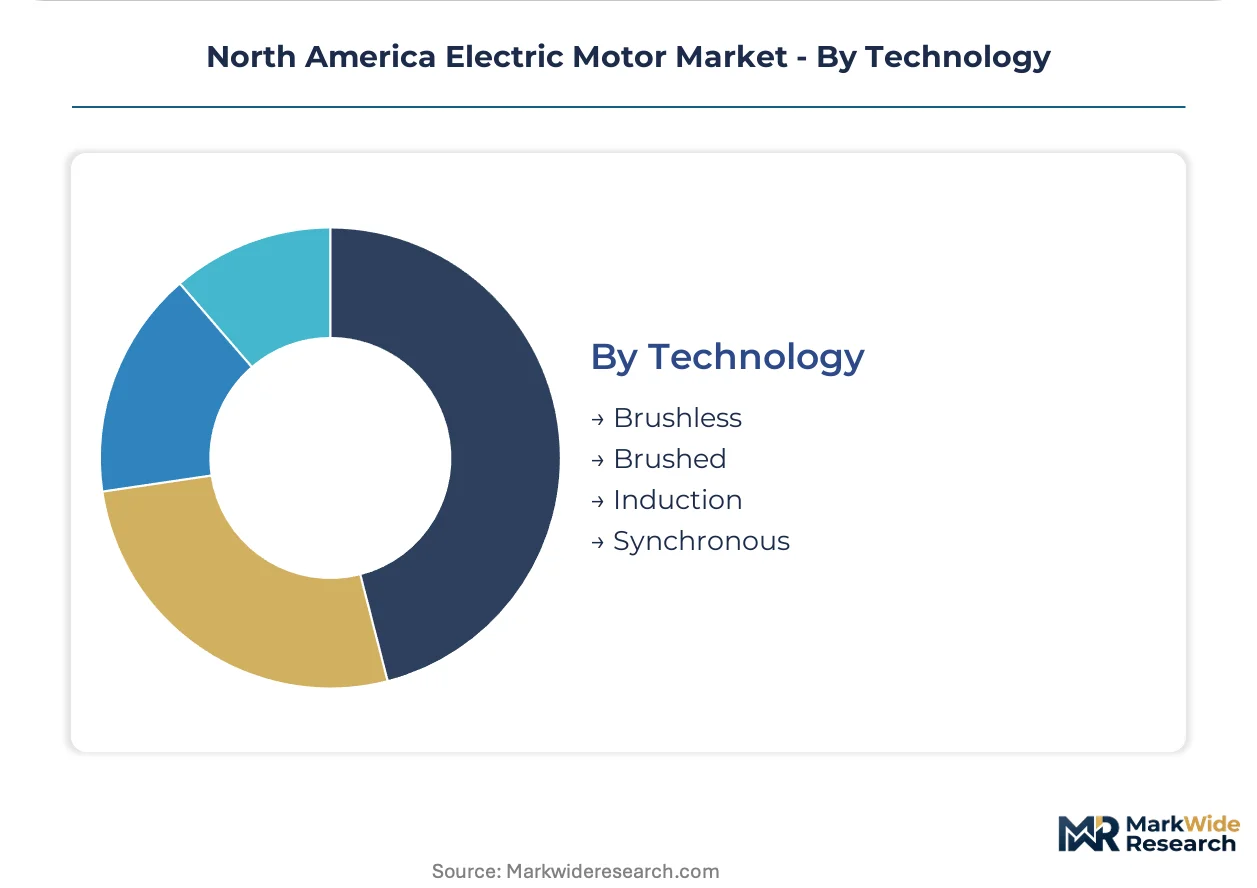
Technology:
Maturity curves separate established induction platforms from emerging permanent magnet synchronous designs displacing conventional architectures in weight-sensitive applications.
- Brushless:Permanent magnet synchronous and switched reluctance designs penetrate EV traction and aerospace actuation where power density outweighs magnet cost volatility. Daimler specifies axial-flux topologies for medium-duty electric trucks.
- Induction:Squirrel-cage designs retain cost advantages in constant-speed pump and fan applications. NEMA MG-1 test method harmonization with CSA C390 streamlines cross-border certification.
- Brushed:Commutator motors persist in cost-sensitive automotive auxiliary systems and consumer power tools.
- Synchronous:Reluctance and PM-assisted designs bridge efficiency gaps between induction and full permanent magnet systems.
Induction holds the largest share; momentum sits with Brushless as silicon carbide inverters enable higher switching frequencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes electric motors predominantly for industrial automation and HVAC infrastructure, while Canada concentrates demand in automotive powertrains and oil-field equipment, and Mexico absorbs volumes for maquiladora assembly operations serving cross-border supply chains.
United States
The US Department of Energy's EPAct efficiency tiers now exclude IE2 equipment from federal procurement contracts, forcing industrial buyers toward premium induction and permanent magnet platforms. DOE furnace fan efficiency standards tighten minimum performance for residential and commercial HVAC applications. Ohio and Indiana steel-belt manufacturing clusters anchor NEMA MG-1 compliant motor production serving federal infrastructure contracts.
Canada
Natural Resources Canada administers MEPS requirements that effectively bar sub-IE3 equipment from cross-border commerce with the United States. Canada's evolving clean energy standards tighten minimum performance requirements for general-purpose motors in federal and provincial procurement. Ontario's Windsor-St. Catharines corridor concentrates tier-1 motor suppliers serving just-in-time delivery requirements for Canadian EV assembly plants.
Mexico
CONUEE alignment with North American harmonization protocols creates a unified compliance perimeter for manufacturers serving integrated automotive supply chains. The country's national energy regulator coordinates efficiency labeling standards with NEMA frameworks to streamline cross-border certification. Maquiladora operations in Nuevo León and the Bajío Region absorb motor volumes for appliance and automotive component assembly serving US markets.
North America Electric Motor Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the North America electric motor market. The upper tier commands medium-voltage industrial applications and integrated motor-drive systems through captive power electronics capabilities. Mid-tier specialists concentrate on fractional horsepower HVAC motors and automotive auxiliary systems. Dominant competitive moves include backward integration into stator lamination stamping and strategic partnerships with silicon carbide inverter suppliers.
Among Switzerland-based industrial conglomerates, ABB Ltd occupies a position exemplifying vertical integration in power electronics. Siemens AG anchors the German-engineered systems archetype through dense service networks. General Electric Company represents the diversified industrial portfolio model with historical concentration in US utility-scale applications. These three entities collectively illustrate how scale and integration separate market tiers.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| General Electric Company |
| Rockwell Automation |
| AMETEK, Inc. |
| Johnson Electric Holdings Limited |
| Nidec Motor Corporation |
| Regal Rexnord Corporation |
| Mitsubishi Heavy Industries, Ltd. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for grain-oriented electrical steel lock in both lamination supply access and price visibility for US motor manufacturers facing volatile raw material markets. These arrangements shield medium-voltage builders from spot market swings while committing buyers to minimum volume thresholds that strain working capital.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value capture for integrated motor-drive suppliers. Three-tier pricing structure across premium IE5 platforms, standard IE3 induction systems, and economy IE2 legacy equipment reflects certification grade and efficiency tier differentiation. Cost compression in fractional horsepower residential motors is intensifying because DOE appliance standards force redesign cycles without commensurate price recovery. HVAC OEMs exhibit highest price sensitivity due to thin margins and import competition, while oil and gas operators show lowest sensitivity given total cost of ownership focus.
Supply Chain Analysis
Inventory buffers for VPI resin and mica tape windings have stretched lead times for medium-voltage motor deliveries beyond historical norms. Stator core lamination supply concentrates in the United States, China, and Japan, with grain-oriented electrical steel production anchored in Indiana and Ohio mills. Rare earth magnet procurement draws from Chinese and Australian sources, exposing permanent magnet motor builders to export quota volatility. Distribution runs through authorized industrial distributors serving the US Great Lakes corridor and direct OEM supply agreements for automotive powertrain integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players who control scarce high-voltage insulation expertise and captive lamination stamping capacity, as aging US workforces no longer replenish specialized winding skills. The capability gap between integrated suppliers and component assemblers is widening under tightening efficiency mandates.
For Market Incumbents: Compound service network density across the US Midwest manufacturing belt to capture predictive maintenance revenue streams as integrated motor-drive systems displace standalone equipment. Backward integration into silicon carbide inverter partnerships protects margin capture in premium traction applications threatened by rare earth magnet cost volatility. Prioritize CSA C390 certification investments to clear Canadian market entry backlogs before regulatory harmonization completes. For New Entrants and Emerging Players: Anchor in axial-flux motor topologies for commercial vehicle traction applications where packaging constraints and weight sensitivity favor pancake-form-factor designs over radial-flux alternatives. Target the Ontario automotive supplier belt for just-in-time delivery partnerships with Canadian EV assembly plants underserved by incumbent lead times. Pursue maquiladora supply chain integration through CONUEE-aligned efficiency platforms serving cross-border automotive production. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with in-house lamination stamping and VPI winding capabilities that larger conglomerates lack. Long-term viability hinges on exposure to industrial electrification and EV powertrain demand rather than commodity HVAC replacement cycles. Watch for IEEE 841 and CSA C390 test method harmonization completion as the signal indicating unified product platform economics and cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lamination Stamping | Captive stator core production insulates margins from grain-oriented electrical steel price volatility. |
| Silicon Carbide Inverter Partnership | High-frequency switching capability enables permanent magnet synchronous motor penetration in weight-sensitive applications. |
| Predictive Maintenance Platform Launch | Embedded vibration and thermal monitoring transforms aftermarket economics for food and beverage processors. |
| CSA C390 Certification Investment | Third-party testing clearance accelerates Canadian market entry before harmonization with NEMA MG-1 completes. |
| Maquiladora Supply Chain Integration | CONUEE-aligned efficiency labeling streamlines cross-border certification for automotive component assembly serving US markets. |
Research Approach
Desk research of trade association filings, customs records, and DOE regulatory dockets preceded structured interviews with motor OEM procurement directors, plant engineers at industrial end-users, aftermarket service managers, and tier-1 automotive supplier quality leads. Primary fieldwork across the US Great Lakes corridor, Ontario manufacturing belt, and northern Mexico maquiladora zones validated secondary data on production capacity and lead time dynamics. Bottom-up shipment data triangulated against top-down efficiency mandate compliance forecasts to anchor volume estimates.
Variance decomposition across product type, power rating, technology architecture, and end-use industry segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling against regulatory compliance deadlines and electrification adoption curves. Motor-drive integration intensity, rare earth magnet price trajectories, and industrial automation capital expenditure patterns served as key forecast inputs.
Material uncertainties — rare earth export quota shifts, IEEE 841 revision timing, and medium-voltage insulation workforce attrition — sit outside the modeled envelope and could alter trajectory assumptions. Forecasts reflect documented assumptions about regulatory harmonization progress and automotive powertrain electrification penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Traction Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Implant Motors Market
Electric Motor
Positive Displacement Motor Market