
 North America Alternating Current (AC) Motor Market | 2026-2036
North America Alternating Current (AC) Motor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alternating Current (AC) Motor Market Analytics
Equipment leasing and power-by-the-hour contracts is rewriting competitive access across the North America AC motor landscape. Siemens AG leverages its captive financing arm to place premium three-phase units directly into automotive OEM lines. ABB Ltd anchors its position through backward integration into variable frequency drive production. Rockwell Automation differentiates via embedded sensor architectures that feed plant-level control systems.
An alternating current (AC) motor converts electrical energy into mechanical rotation through electromagnetic induction, typically operating at frequencies of 50 or 60 hertz with squirrel-cage or wound-rotor constructions designed for continuous-duty industrial cycles. Three-phase induction units dominate heavy manufacturing applications due to their rugged construction and minimal maintenance requirements, while servo motor architectures command premium positioning in precision robotics where closed-loop control is mandatory. HVAC systems represent a mature, high-volume application segment where brushless technology is displacing conventional induction designs in premium chiller installations.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431, while NEMA MG 1 defines performance and dimensional benchmarks that govern product interoperability across Canadian and US supply chains. Mexico's energy regulator complements this framework through CONUEE efficiency labeling requirements that filter substandard imports from Asian suppliers. Stakeholders must monitor how impending DOE rulemakings on small motor categories will reshape sourcing economics for residential and light commercial segments.
Market Dynamics
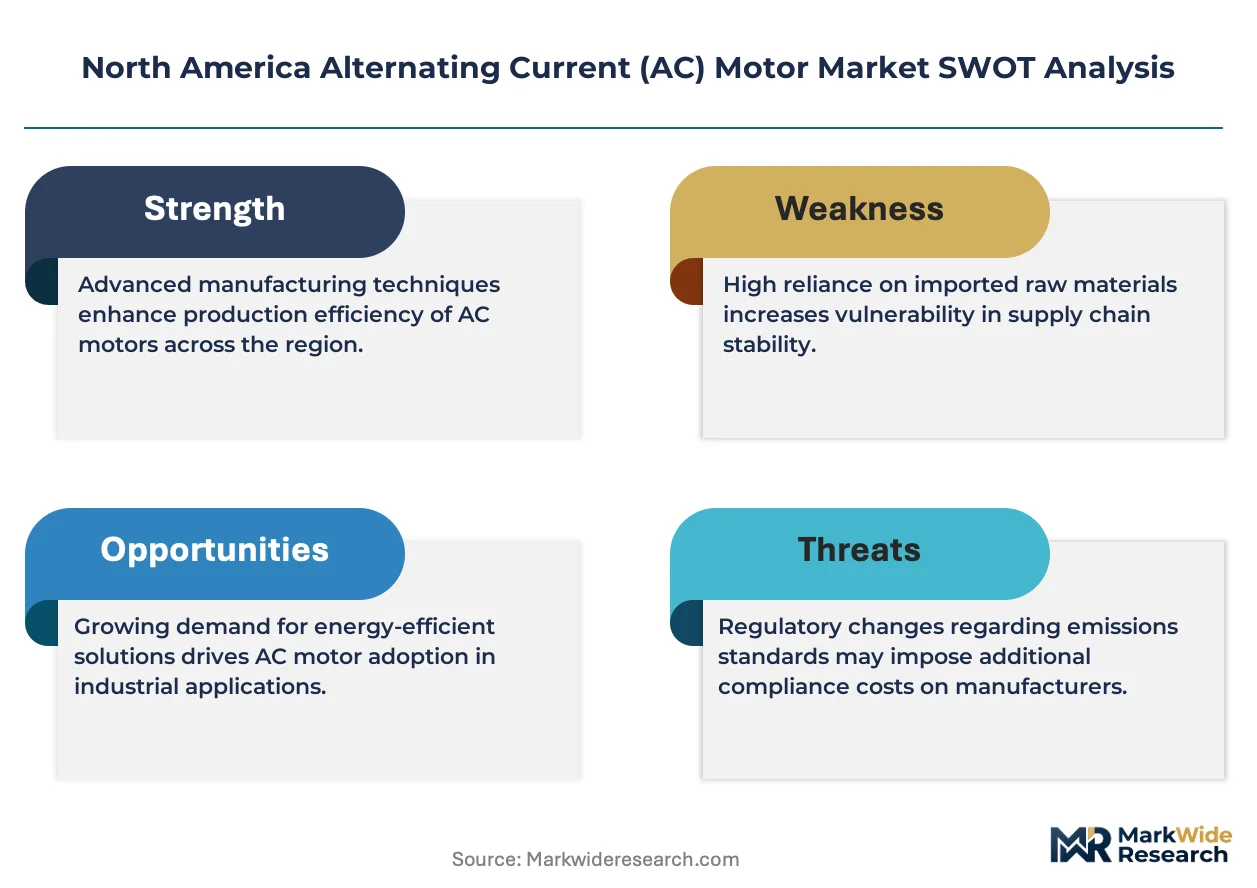
The US Department of Energy's pending small motor efficiency rulemaking is compressing sourcing economics for fractional horsepower suppliers while Mexican automotive clusters accelerate three-phase procurement for EV component lines.
Growth Catalysts
- NEMA MG 1 Revisions:Updated performance benchmarks are forcing cross-border interoperability upgrades across Canadian and US supply chains, expanding replacement demand for premium efficiency units.
- Petrochemical Corridor Expansion:Gulf Coast ethylene crackers and LNG export terminals are commissioning continuous-duty squirrel-cage motors for process-critical compressor trains.
- Brushless DC Convergence:Permanent magnet architectures are penetrating HVAC chiller retrofits, creating hybrid specification demand that lifts AC motor attach rates for integrated drive packages.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export quotas are compressing margins for high-efficiency permanent magnet motor variants.
- Copper Concentration Risk:Winding material dependence on Chilean and Peruvian concentrate supplies exposes producers to smelter bottlenecks and LME price spikes.
- 10 CFR 431 Compliance Friction:DOE certification timelines and third-party testing backlogs are extending product launch cycles for residential fractional horsepower categories.
Strategic Opportunities
- Canadian Mining Electrification:Ontario and Quebec hard-rock operations are replacing diesel haulage with trolley-assist and battery-electric fleets requiring ruggedized traction motors.
- Power-by-the-Hour Contracts:Automotive OEMs in Mexican Bajío clusters are adopting uptime-guaranteed leasing models that bypass traditional CapEx approval cycles.
- Industrial IoT Convergence:Embedded vibration and thermal sensor integration with edge analytics platforms is creating premium pricing tiers for predictive maintenance-ready units.
Industry Challenges
- NEMA Premium Certification Bottlenecks:Third-party laboratory capacity constraints are stretching compliance documentation timelines for mid-tier manufacturers.
- Legacy Control System Integration:Brownfield manufacturing facilities face protocol translation complexity when retrofitting smart motors into existing DeviceNet and Modbus architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alternating Current (AC) Motor Market |
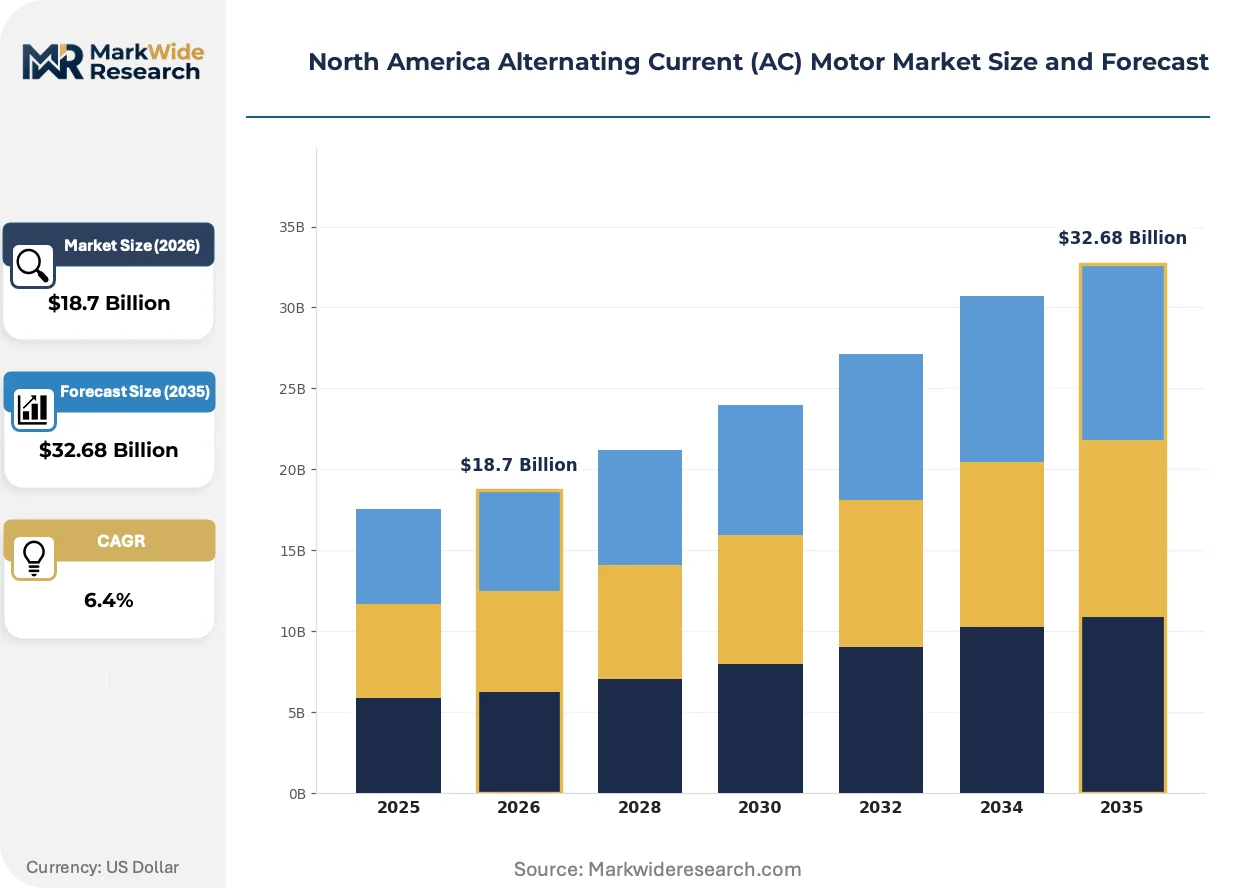
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-phase, Three-phase, Multi-phase, Servo Application: Industrial Automation, HVAC Systems, Consumer Appliances, Pumps End User: Manufacturing, Residential, Commercial, Agriculture Technology: Induction, Synchronous, Brushless, Others |
| Companies Covered | Siemens AG, ABB Ltd, Rockwell Automation, Johnson Electric, Toshiba International Corporation, Nidec Motor Corporation, WEG Electric Corporation, Yaskawa Electric Corporation, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alternating Current (AC) Motor Market Evolving Landscape
Digital twin architectures and edge-native sensor packages are compressing the traditional divide between motor hardware and plant-level control systems across North American industrial facilities.
Integrated motor-drive systems with embedded condition monitoring are digitizing maintenance workflows by streaming vibration spectra and thermal profiles directly to cloud-based reliability platforms. Food and beverage processors in the US Midwest are deploying these units at pilot scale. The technology is digitizing aftermarket service revenue models toward subscription-based uptime guarantees.
The US Department of Energy's 10 CFR 431 rulemaking on small electric motors is mandating minimum full-load efficiency thresholds that disqualify standard induction designs from residential and commercial HVAC applications. Manufacturers are responding with copper rotor and advanced lamination steel formulations. Fractional horsepower suppliers serving the US Southeast cooling market face the steepest compliance ramps.
Automotive OEM procurement teams are consolidating supplier relationships around vertically integrated motor-drive-sensor bundles. Tier-1 component buyers in Mexican manufacturing clusters are rejecting discrete motor quotes in favor of powertrain-integrated packages. The shift is most pronounced in Guanajuato and Querétaro assembly operations where line-side inventory reduction targets dominate sourcing criteria.
North America Alternating Current (AC) Motor Market Segmentation
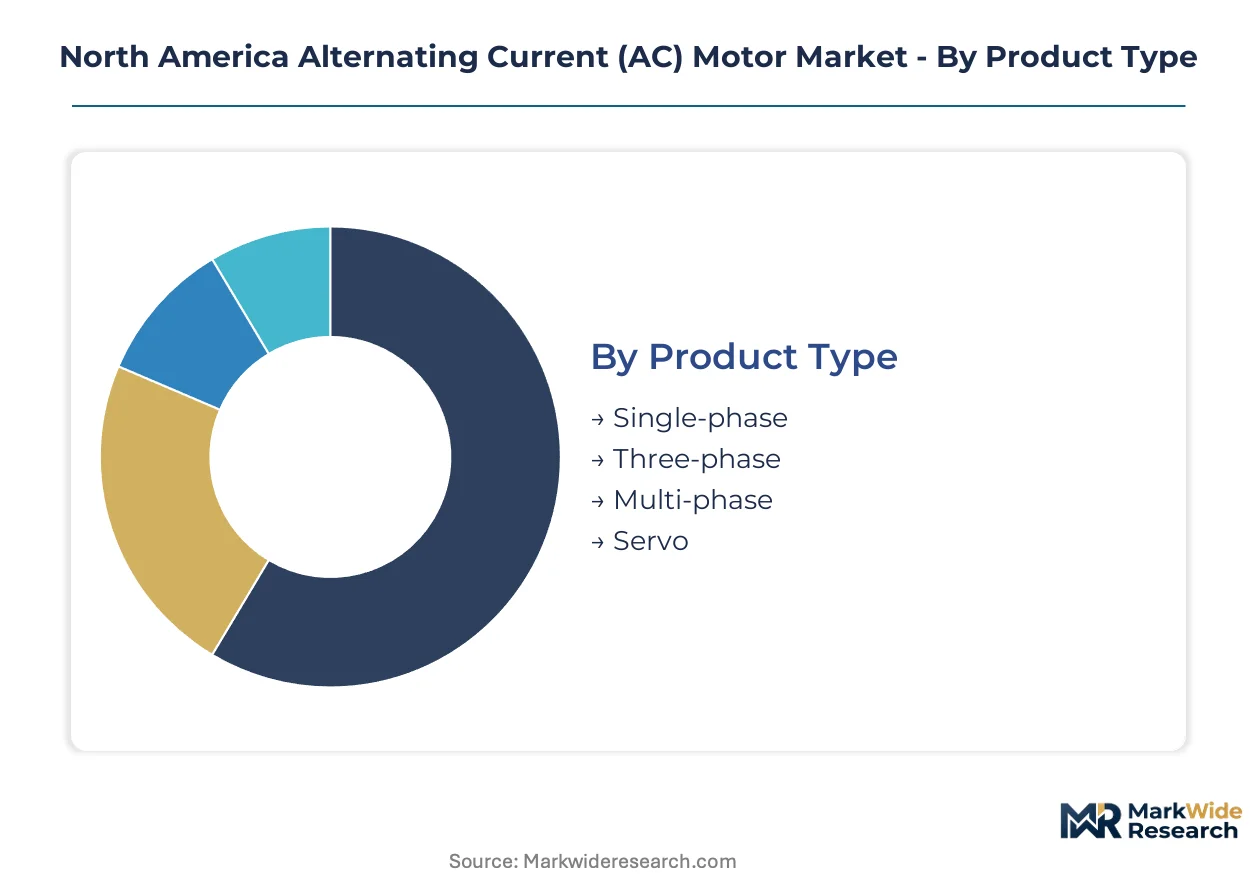
AC motor procurement patterns diverge sharply across voltage classes, duty cycles, and control architectures. Buyers in North American industrial corridors specify equipment through fundamentally different technical lenses than residential HVAC contractors or agricultural pump distributors.
Product Type:
Maturity spans from century-old induction designs to digitally integrated servo architectures that embed position feedback loops.
- Single-phase:Capacitor-start and split-phase constructions dominate fractional horsepower residential applications. Fractional horsepower suppliers serving the US Southeast cooling market face steep DOE compliance ramps under pending 10 CFR 431 rulemakings.
- Three-phase:Squirrel-cage induction units with NEMA Premium efficiency ratings anchor heavy manufacturing procurement. Gulf Coast petrochemical corridors and Mexican automotive manufacturing clusters concentrate demand for continuous-duty compressor train applications.
- Multi-phase:Specialized polyphase configurations serve high-torque traction and mining electrification requirements in Ontario and Quebec hard-rock operations.
- Servo:Closed-loop permanent magnet motors with encoder feedback command premium positioning in precision robotics and CNC machining centers.
Three-phase units handle the majority of throughput; servo architectures are gaining share fastest in automotive EV component lines.
Application:
Volume concentration tilts toward process industries with 24/7 duty cycles, while retrofit markets reward integrated drive packages.
- Industrial Automation:Conveyor systems, robotic workcells, and material handling equipment specify NEMA MG 1-compliant motors with embedded vibration sensors. Smart manufacturing lines in the US Midwest food and beverage sector are deploying pilot-scale integrated motor-drive systems.
- HVAC Systems:Chillers, air handlers, and cooling towers represent mature high-volume demand. Brushless permanent magnet architectures are penetrating premium chiller retrofits, creating hybrid specification demand.
- Consumer Appliances:Washing machines, refrigerators, and power tools require compact fractional horsepower units with copper rotor formulations to meet efficiency thresholds.
- Pumps:Municipal water infrastructure and agricultural irrigation specify TEFC and ODP enclosures for wet-environment durability.
Industrial automation commands the steepest pricing tiers; HVAC systems deliver the highest unit volumes.
End User:
Customer sophistication ranges from specification-engineered manufacturing procurement to price-sensitive residential replacement markets.
- Manufacturing:Automotive OEMs in Guanajuato and Querétaro assembly operations are consolidating supplier relationships around vertically integrated motor-drive-sensor bundles. Line-side inventory reduction targets dominate sourcing criteria.
- Residential:HVAC replacement cycles and appliance OEM contracts drive seasonal demand patterns. Third-party testing backlogs are extending product launch cycles for fractional horsepower categories.
- Commercial:Building automation systems specify premium efficiency units with BACnet and Modbus connectivity for centralized energy management.
- Agriculture:Irrigation pump motors in California Central Valley and Texas High Plains operations prioritize ruggedized enclosures and minimal maintenance requirements.
Manufacturing absorbs the most advanced integrated packages; residential channels show the strongest price elasticity.
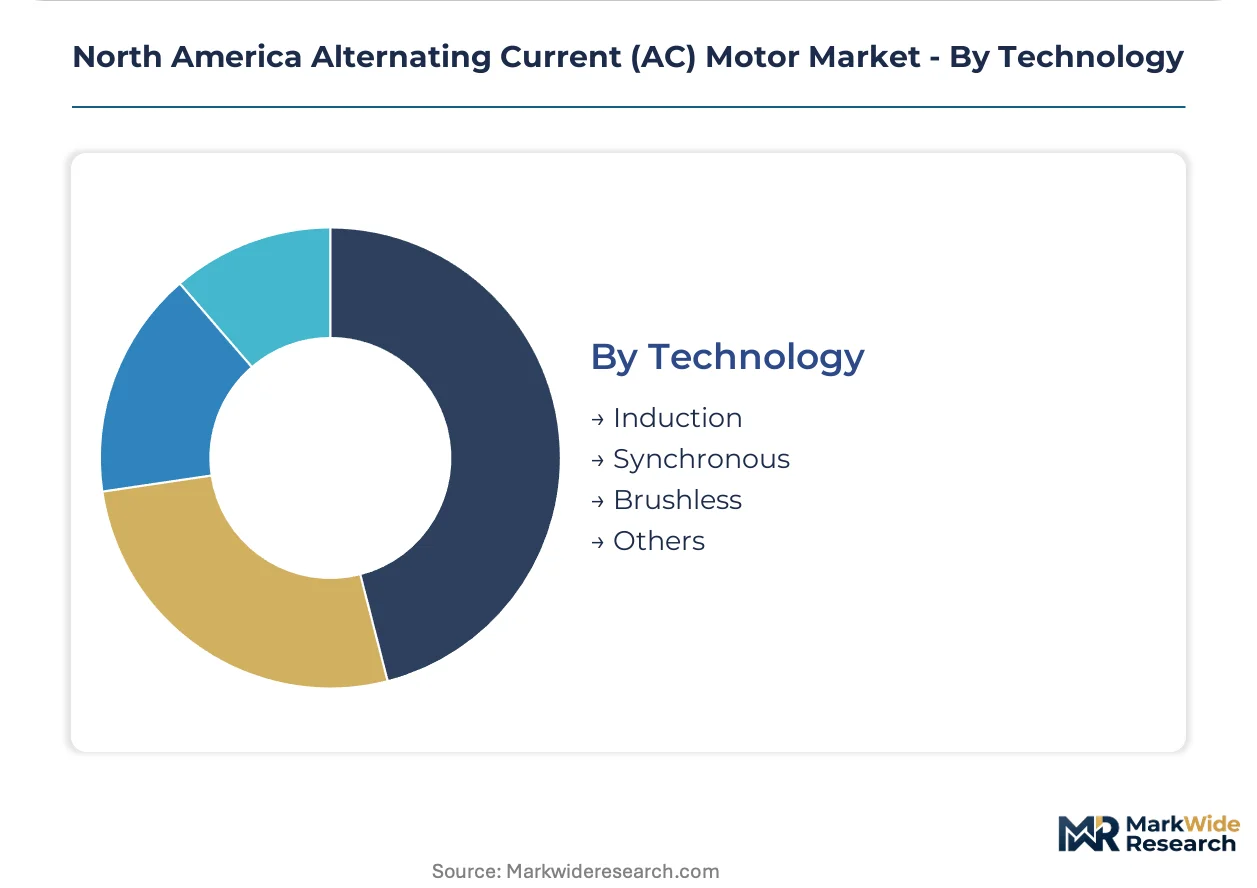
Technology:
Electromagnetic architectures split between rugged induction dominance and synchronous precision for variable-speed applications.
- Induction:Squirrel-cage and wound-rotor designs with cast aluminum or copper bars constitute the workhorse technology. Continuous-duty ratings and minimal maintenance requirements sustain penetration in brownfield manufacturing facilities.
- Synchronous:Reluctance and permanent magnet synchronous motors deliver precise speed control for variable frequency drive pairing. Rare earth magnet volatility from Chinese export quotas compresses margins for high-efficiency variants.
- Brushless:Electronically commutated permanent magnet motors eliminate slip rings and brushes for HVAC chiller and premium appliance applications.
- Others:Switched reluctance and axial flux architectures serve niche high-torque density requirements in specialized traction and aerospace ground support equipment.
Induction technology retains the installed base; synchronous designs are expanding most quickly in precision motion control segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Asian motor manufacturers into North America face mounting regulatory friction, while intra-regional trade between the United States, Canada, and Mexico strengthens under USMCA provisions. Duty-free component sourcing across the three markets accelerates integrated motor-drive assembly.
United States
Gulf Coast petrochemical corridors drive continuous-duty three-phase procurement for ethylene crackers and LNG export terminals. The Department of Energy enforces 10 CFR 431 efficiency standards that disqualify standard induction designs from residential HVAC applications. Houston and Corpus Christi anchor compressor train motor demand for process-critical infrastructure.
Canada
Ontario and Quebec hard-rock mining operations replace diesel haulage with trolley-assist and battery-electric fleets requiring ruggedized traction motors. Natural Resources Canada administers efficiency labeling through the EnerGuide program that filters substandard imports. Sudbury and Val-d'Or concentrate demand for multi-phase high-torque configurations in underground extraction.
Mexico
Automotive OEMs in Guanajuato and Querétaro consolidate supplier relationships around vertically integrated motor-drive-sensor bundles. The National Commission for the Efficient Use of Energy operates CONUEE efficiency labeling requirements governing product entry. Bajío region assembly operations reject discrete motor quotes in favor of powertrain-integrated packages.
North America Alternating Current (AC) Motor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base organizes around three structural tiers: diversified industrial conglomerates with captive financing arms, automation specialists with embedded sensor architectures, and regional manufacturers with cost-optimized fractional horsepower lines. Consolidation pressure intensifies as automotive OEMs demand vertically integrated bundles. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Among diversified industrial conglomerates, Siemens AG and ABB Ltd occupy positions exemplifying the system-integration archetype through financing-enabled placement and drive production integration. Rockwell Automation sits within the automation specialist tier. These three anchors illustrate how competitive positioning diverges between hardware-centric and control-system-centric approaches.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Rockwell Automation |
| Johnson Electric |
| Toshiba International Corporation |
| Nidec Motor Corporation |
| WEG Electric Corporation |
| Yaskawa Electric Corporation |
| General Electric |
| Others |
Value Network & Pricing Analysis
Port of Long Beach container freight corridors transmit cost volatility from Asian component sourcing directly into landed motor costs, compressing margins for fractional horsepower suppliers while amplifying price premiums for NEMA Premium-certified three-phase units serving Gulf Coast petrochemical buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates NEMA Premium-certified continuous-duty units from standard efficiency induction motors and imported fractional horsepower alternatives. Cost compression in the residential HVAC segment is intensifying because DOE 10 CFR 431 compliance investments are eroding margins for Southeast cooling market suppliers. Automotive OEM procurement teams show the least price sensitivity, prioritizing uptime-guaranteed power-by-the-hour contracts over unit economics.
Supply Chain Analysis
Chinese rare earth export quota restrictions limit neodymium and dysprosium flows into North American permanent magnet motor production. Manufacturing concentration centers on China for lamination steel and wound copper, Mexico for final assembly integration, and the United States for NEMA-certified finished goods. Raw material sourcing rests on Chilean copper concentrate, Chinese silicon steel, and processed rare earth oxides. Single-source vulnerability in magnet supply chains exposes producers to smelter bottlenecks. Distribution runs through authorized distributor networks serving industrial MRO channels and direct OEM line-side contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DOE efficiency rulemakings on small motor categories are accelerating technological disruption across residential and light commercial segments, compressing product lifecycles and rewiring competitive economics.
For Market Incumbents: Insulate core three-phase margins through backward integration into variable frequency drive production and captive copper rotor casting capacity. Secure NEMA MG 1 certification pipelines ahead of pending revisions to lock out mid-tier competitors facing laboratory capacity constraints. Defensive consolidation around sensor-embedded motor-drive bundles neutralizes emerging IoT-native challengers. For New Entrants and Emerging Players: Canadian hard-rock mining electrification in Ontario and Quebec offers underpenetrated traction motor demand with specification flexibility and limited incumbent presence. Target trolley-assist and battery-electric fleet retrofits with ruggedized multi-phase configurations. Pursue power-by-the-hour contract structures that bypass traditional CapEx approval cycles and align revenue with operational uptime. For Investors and Strategic Acquirers: Sensor-embedded motor specialists with edge analytics integration capabilities represent the priority acquisition archetype for platform consolidation plays. Long-term viability hinges on software-defined service revenue streams displacing transactional hardware sales. Watch for CONUEE efficiency label expansion in Mexico as the signal indicating accelerated regional procurement standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Drive Electronics | Captive VFD production secures margin capture from integrated motor-drive bundles demanded by automotive OEMs. |
| NEMA Premium Certification Pre-Positioning | Early laboratory capacity allocation avoids compliance bottlenecks threatening mid-tier manufacturer launch timelines. |
| Power-by-the-Hour Contract Expansion | Uptime-guaranteed leasing models align revenue with Mexican automotive cluster operational continuity requirements. |
| Embedded Sensor Architecture Development | Vibration and thermal monitoring integration enables predictive maintenance subscriptions digitizing aftermarket revenue. |
| Copper Rotor Formulation Investment | Advanced winding materials satisfy DOE 10 CFR 431 thresholds disqualifying standard induction designs from HVAC applications. |
Research Methodology
A spread of perspectives from plant engineers, OEM procurement directors, aftermarket service heads, and distributor technical sales teams converged on the working assumptions shaping motor specification trends. Primary fieldwork combined structured interviews with maintenance directors at Gulf Coast petrochemical facilities and sourcing leads at Mexican automotive assembly operations. Secondary validation drew from DOE 10 CFR 431 rulemaking dockets, NEMA MG 1 revision documentation, CONUEE efficiency labeling databases, and USMCA trade flow records. Bottom-up unit demand estimates triangulated against top-down industrial capital expenditure patterns.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions included voltage class, duty cycle rating, control architecture, and end-use industry vertical. CAGRs were derived from trend extrapolation of replacement cycle compression and efficiency upgrade mandates. Industry-specific inputs incorporated petrochemical capacity expansion timelines, EV component line commissioning schedules, and HVAC seasonal demand coefficients.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending, copper LME pricing, and cross-border freight rates would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timing and technology substitution elasticities. Material shifts in rare earth export quota enforcement or NEMA laboratory accreditation backlogs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
E-Bike Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Traction Motor Core Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Electric Vehicle Motor Micro Controller Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Electric Motors for IC Engine Vehicle Market
Electric Motor
Automotive Induction Motors Market