
 Automotive Wiper Motor Market | 2026-2036
Automotive Wiper Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wiper Motor Market Outlook
The shift from brushed to brushless DC motor architectures is reshaping how wiper systems integrate with vehicle electrical networks and energy-management controllers. Robert Bosch GmbH leverages its powertrain electronics heritage to embed smart-control logic directly into motor housings. Mitsuba Corporation anchors Asian supply chains through captive magnet production and just-in-time delivery to Japanese OEMs. Denso Corporation competes on thermal efficiency, optimizing copper winding density to reduce current draw during high-speed operation.
An automotive wiper motor is an electromechanical actuator that converts electrical energy into oscillating mechanical motion through a worm-gear reduction system, typically delivering 30–60 rpm output shaft speed with 10–20 Nm torque to sweep windscreen blades across prescribed arcs. Its primary purpose is to maintain driver visibility under precipitation, debris, and contamination conditions across all vehicle classes. Flat wiper motors now lead in passenger-vehicle fitments because their compact axial profile frees cowl-space for sensor arrays and HVAC ducting. Brushless technology represents the fastest-expanding segment as PWM control enables variable-speed algorithms that reduce noise and extend service intervals. Heavy-duty wiper motors retain stable margin pools in commercial-fleet applications where replacement cycles are shorter and torque requirements exceed standard passenger-vehicle specifications.
NHTSA Federal Motor Vehicle Safety Standard 104 governs windshield wiping and washing systems in the United States, mandating minimum swept-area coverage and response times that directly influence motor torque specifications. The EU's CE marking and REACH chemical-compliance frameworks restrict hazardous substances in motor insulation and gear lubricants, pushing suppliers toward reformulated materials. China's GB standards, administered by MIIT, set electromagnetic-compatibility thresholds that brushless designs satisfy more readily than legacy brushed architectures. Stakeholders must monitor how software-defined vehicle architectures will redistribute wiper-motor control intelligence between dedicated motor controllers and centralized domain computers.
Market Dynamics
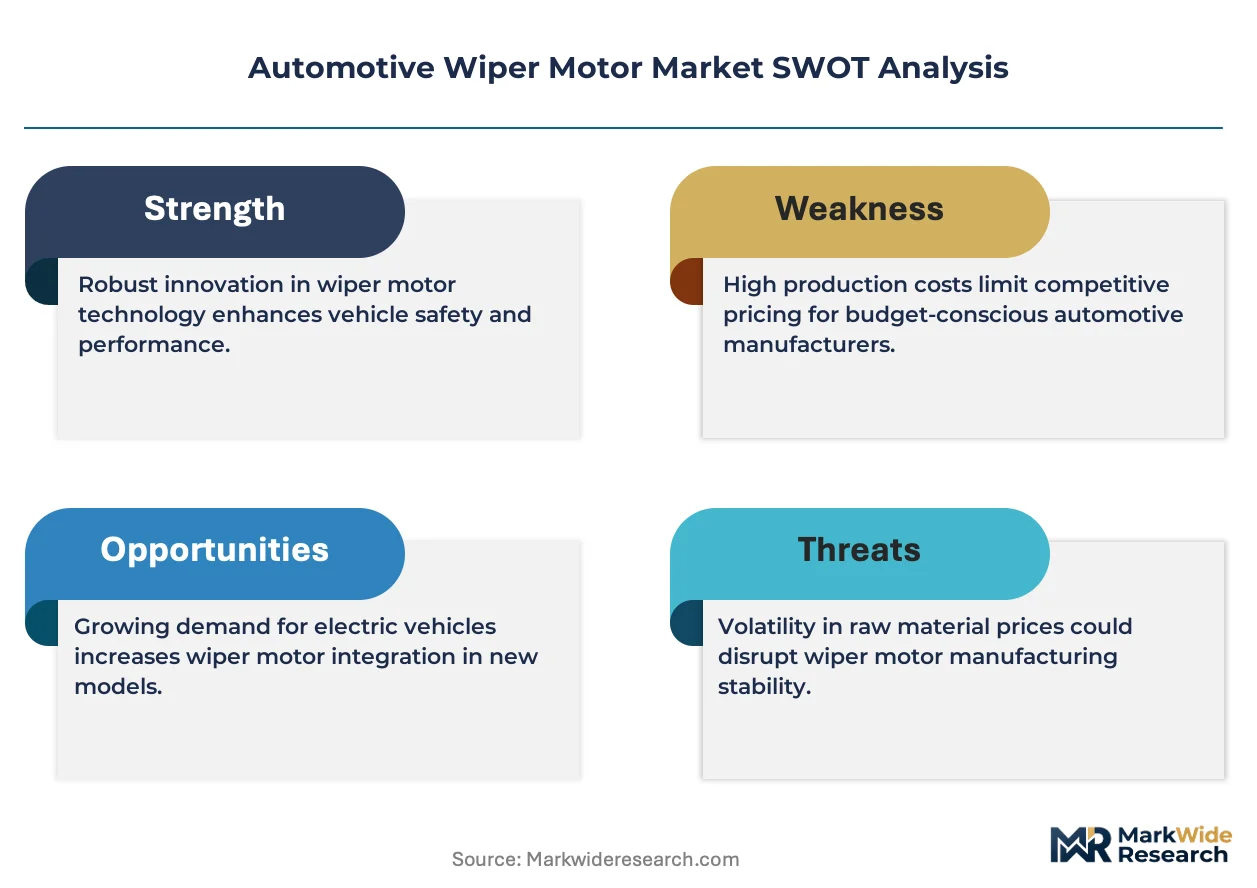
Brushless DC motor architectures are collapsing the traditional boundary between wiper systems and vehicle energy-management networks, forcing suppliers to embed control intelligence directly into motor housings rather than relying on discrete controllers.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 104:Mandated swept-area coverage and response-time thresholds compel OEMs to upgrade motor torque specifications, expanding replacement demand for compliant systems.
- Flat wiper motor adoption:Compact axial profiles free cowl-space for ADAS sensor arrays and HVAC ducting, accelerating fitment rates in electric-vehicle platforms.
- China GB electromagnetic-compatibility standards:Brushless designs satisfy MIIT thresholds more readily than legacy brushed architectures, channeling procurement toward compliant suppliers.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium sourcing concentrates in limited geographic corridors, exposing brushless motor producers to input volatility and trade-policy friction.
- EU REACH chemical-compliance frameworks:Restrictions on hazardous substances in motor insulation and gear lubricants force costly material reformulation and requalification cycles.
- Heavy-duty torque limitations:Commercial-fleet applications requiring sustained high-load operation exceed standard brushless thermal envelopes, preserving niche demand for brushed alternatives.
Strategic Opportunities
- Software-defined vehicle architectures:Redistribution of wiper-motor control intelligence from dedicated controllers to centralized domain computers creates openings for motor suppliers with embedded firmware capabilities.
- India automotive assembly expansion:Underpenetrated domestic wiper-motor manufacturing capacity positions early entrants to serve Maruti Suzuki, Tata Motors, and Mahindra procurement programs.
- ISO 26262 functional-safety certification:ASIL-rated motor systems command premium positioning as OEMs integrate wipers into automated driving visibility stacks.
Industry Challenges
- Embedded software talent scarcity:Motor suppliers lack sufficient firmware engineers to develop PWM control algorithms and diagnostic protocols required by domain-computer integration.
- Worm-gear precision manufacturing capex:Tolerance requirements for quiet brushless operation demand grinding equipment investments that strain mid-tier supplier balance sheets.
- Dual-certificate timelines:Simultaneous NHTSA and EU type-approval processes extend time-to-revenue for new motor variants by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wiper Motor Market |
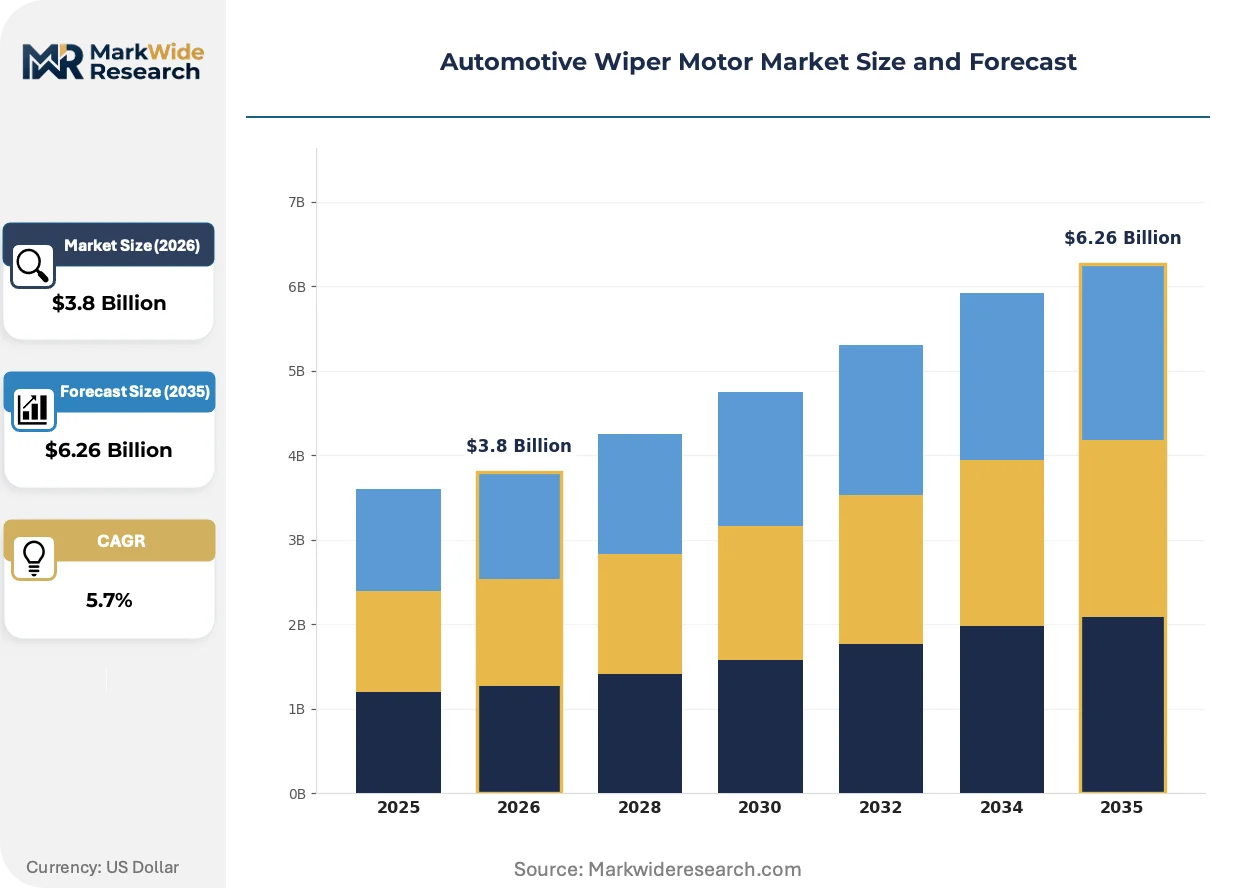
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Wiper Motors, Flat Wiper Motors, Intermittent Wiper Motors, Heavy-Duty Wiper Motors Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Manufacturers Technology: Brushless Technology, DC Motors, PWM Control, Smart Wiper Systems |
| Companies Covered | ZF Friedrichshafen AG, Mitsuba Corporation, Robert Bosch GmbH, Marelli Holdings Co., Ltd., Nidec Corporation, Denso Corporation, Continental AG, Trico Products Corporation, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wiper Motor Market Strategic Shifts
Electrification of vehicle platforms is collapsing legacy subsystem boundaries, forcing wiper-motor suppliers to compete on software integration and thermal efficiency rather than mechanical durability alone.
Integrated motor-controller units are collapsing the traditional separation between electromechanical actuators and power electronics. Tier-1 suppliers now embed MOSFET arrays and PWM drivers within motor housings, eliminating external control modules. Electric-vehicle manufacturers in Germany and China are specifying these consolidated units for new platforms. This integration is collapsing supplier tiers, as motor producers must now source semiconductor fabrication capacity directly.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are accelerating reformulation of gear lubricants toward synthetic hydrocarbon and polyether alternatives. Motor manufacturers face requalification costs for new lubricant chemistries that maintain worm-gear efficiency across temperature extremes. Commercial-vehicle segments in Scandinavia and Alpine corridors are most affected, as cold-start torque requirements stress boundary-lubrication performance.
Fleet operators are compressing wiper-motor replacement cycles through predictive maintenance algorithms rather than fixed-interval service schedules. Telematics platforms aggregate motor current-draw signatures to detect gear-wear progression, triggering just-in-time component replacement. This behavioral shift is most visible in North American long-haul trucking and European bus fleets, where uptime guarantees dominate total-cost-of-ownership calculations.
Automotive Wiper Motor Market Segmentation
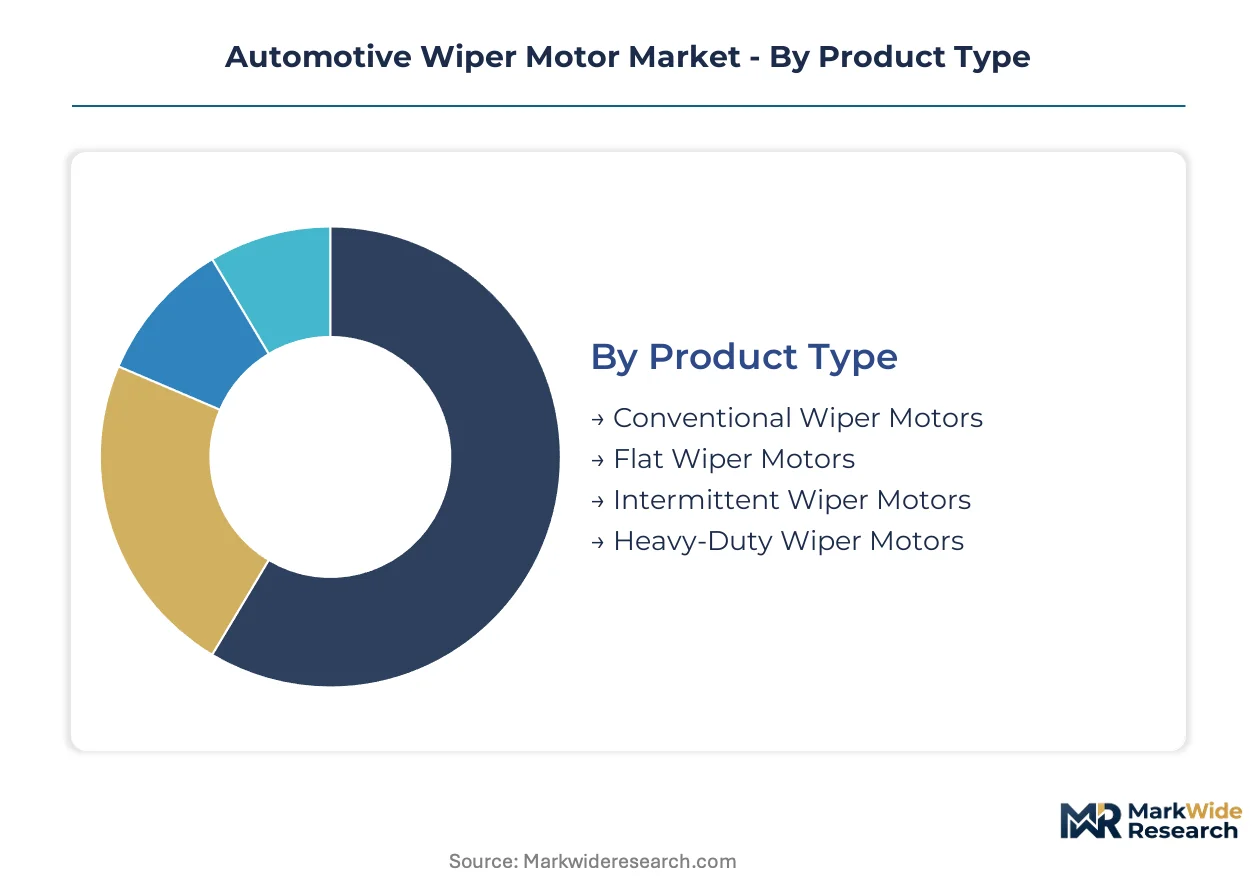
Wiper motor segmentation reveals how supplier capabilities align with diverging customer requirements across vehicle electrification, automation, and fleet digitization. Technical specifications, procurement channels, and control architectures fragment the addressable market into distinct competitive arenas.
Product Type:
Cost tier differentiation separates commodity replacement units from precision-engineered platforms serving electric-vehicle and ADAS-dense architectures.
- Flat Wiper Motors:Compact axial designs reduce cowl-space intrusion to accommodate sensor arrays and HVAC routing. Passenger-vehicle OEMs in Germany and China specify these units for new electric platforms where packaging efficiency determines platform feasibility.
- Heavy-Duty Wiper Motors:High-torque worm-gear systems deliver sustained load capacity for commercial-fleet applications with shorter replacement cycles. North American long-haul trucking and European bus operators maintain stable procurement volumes despite brushless displacement in lighter segments.
- Conventional Wiper Motors:Brushed DC architectures persist in emerging-market vehicle production and aftermarket replacement channels.
- Intermittent Wiper Motors:Time-delay control modules enable variable sweep intervals for light precipitation conditions.
Flat wiper motors hold installed capacity. Heavy-duty wiper motors are rotating up the share rankings in commercial-fleet renewal programs.
Application:
Vehicle class determines torque specifications, duty-cycle requirements, and integration complexity with domain-computer architectures.
- Electric Vehicles:Brushless platforms with embedded PWM controllers reduce current draw to preserve range targets. Manufacturers specify these units for integration with centralized energy-management networks in battery-electric platforms.
- Passenger Vehicles:Noise-optimized flat-motor fitments dominate premium and mass-market segments where cabin quietness influences consumer preference. ADAS sensor packaging constraints accelerate adoption of reduced-profile designs.
- Commercial Vehicles:Fleet operators prioritize field-serviceability and parts-commonality across tractor-trailer configurations.
- Off-Road Vehicles:Sealed housings and enhanced corrosion resistance address agricultural and construction equipment operating environments.
Passenger vehicles hold installed capacity. Electric vehicles are climbing the fastest as OEMs consolidate electrical architectures.
End User:
Procurement channel structure separates captive supply relationships from open-market distribution and influences technical specification authority.
- OEMs:Direct platform-integration contracts specify motor-controller firmware compatibility with domain-computer architectures. Vehicle manufacturers in Japan and South Korea maintain long-term supply agreements with dedicated motor producers.
- Tier-1 Suppliers:System-integration responsibility positions these intermediaries to consolidate motor, linkage, and control-module procurement for final assembly delivery.
- Aftermarket Providers:Independent distributors serve replacement demand through catalog-matching against legacy vehicle populations.
- Vehicle Manufacturers:Captive component divisions in vertically integrated OEMs source internally for specific model lines.
OEMs hold installed capacity. Tier-1 suppliers are gaining share fastest through system-integration consolidation.
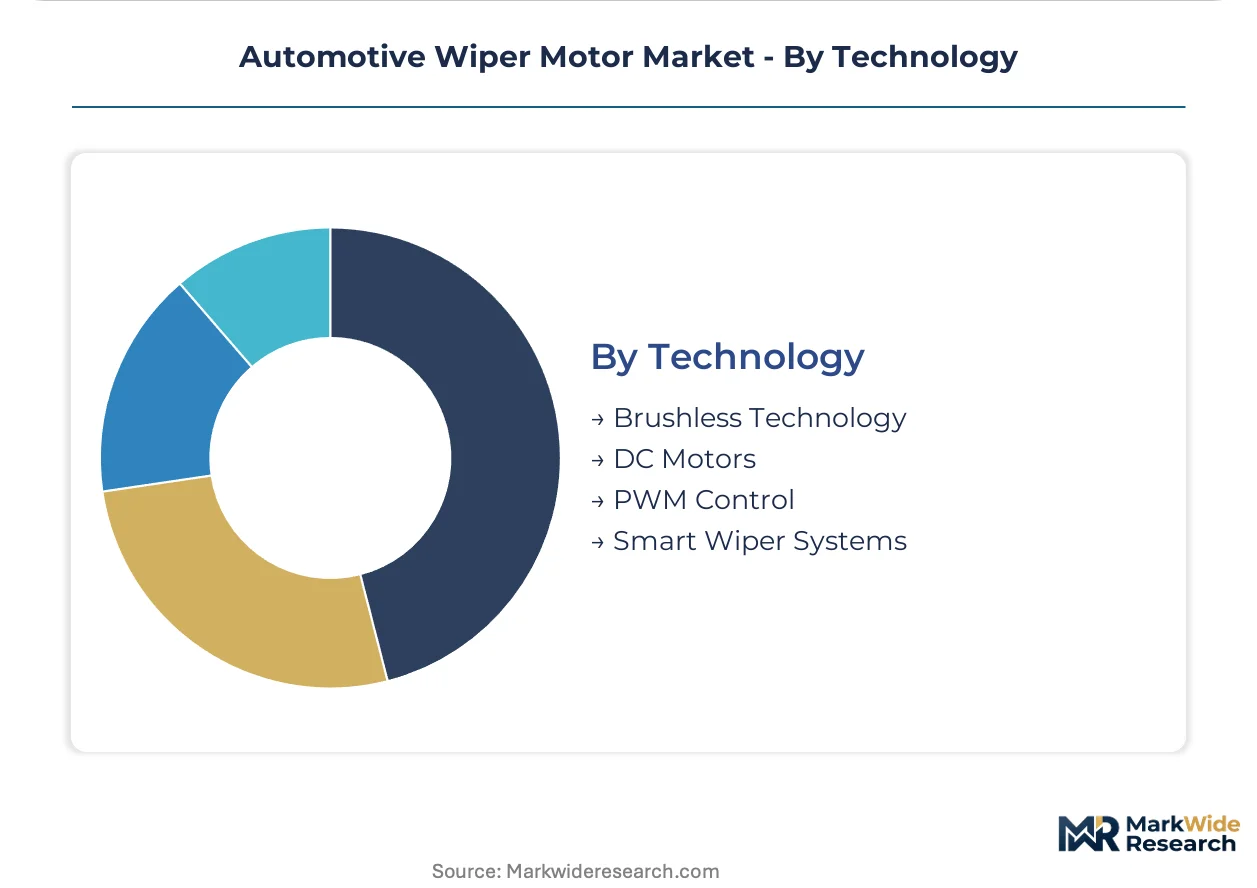
Technology:
Control architecture maturity separates legacy electromechanical systems from software-defined motor platforms with embedded diagnostic capabilities.
- Brushless Technology:Permanent-magnet synchronous designs with Hall-effect position sensing eliminate commutator wear and enable precise speed modulation. NHTSA visibility-response thresholds and China GB electromagnetic-compatibility standards favor these architectures for new platform certification.
- Smart Wiper Systems:Rain-sensor integration and predictive-maintenance algorithms embed wiper control within automated driving visibility stacks. German luxury OEMs specify these units for Level 2+ automation platforms.
- DC Motors:Brushed commutator designs persist in cost-sensitive vehicle segments and aftermarket replacement.
- PWM Control:Pulse-width modulation enables variable-speed operation and reduced acoustic signature in brushless implementations.
DC motors hold installed capacity. Brushless technology is rotating up the share rankings as electrification platforms reach production scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive wiper motor procurement concentrates around final-assembly clusters in China, Germany, Japan, and the United States, with tier-1 system integrators and OEM captive divisions dominating channel control in each corridor.
China
MIIT GB electromagnetic-compatibility standards channel procurement toward brushless architectures as domestic EV manufacturers consolidate electrical platforms. Shanghai and Guangzhou host the densest concentrations of wiper motor final assembly, supplying BYD, NIO, and XPeng production lines with integrated motor-controller units.
Germany
Luxury OEM specifications for ADAS-compatible flat wiper motors drive precision-engineering requirements across Bavarian and Baden-Württemberg supplier parks. EU F-Gas Regulation restrictions on fluorinated lubricants force reformulation of gear systems, with Stuttgart-area motor producers leading qualification cycles for synthetic hydrocarbon alternatives.
United States
NHTSA Federal Motor Vehicle Safety Standard 104 mandates swept-area coverage thresholds that expand replacement demand for compliant torque-specified systems. Detroit-area tier-1 integrators and Mexican maquiladora operations serve North American light-truck and commercial-fleet renewal programs with heavy-duty motor configurations.
Japan
Long-term supply agreements between domestic OEMs and dedicated motor producers lock in procurement channels for hybrid and battery-electric platforms. Kanto and Chubu regional clusters concentrate brushless motor manufacturing, with Aichi Prefecture suppliers embedding Hall-effect position sensing for PWM control integration.
South Korea
Hyundai Motor Group and Kia Corporation platform consolidation drives specification authority toward Seoul-area tier-1 system integrators. Gyeonggi-do supplier parks specialize in compact axial-profile motors for electric SUV and crossover architectures where cowl-space packaging constraints determine platform feasibility.
Automotive Wiper Motor Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidated tier-1 system integrators dominate OEM direct contracts through firmware integration capabilities and long-term supply agreements. Mid-tier motor specialists compete on thermal efficiency and precision manufacturing for premium passenger-vehicle fitments. Fragmented regional fabricators serve aftermarket replacement channels and emerging-market vehicle production. Dominant competitive moves include backward integration into magnet supply chains and strategic partnerships with semiconductor foundries for embedded controller sourcing.
Within the diversified industrial conglomerate tier, Robert Bosch GmbH and Denso Corporation exemplify channel-controlling archetypes through captive electronics heritage and direct OEM platform integration. Mitsuba Corporation occupies a specialist position, anchoring Asian supply relationships through dedicated Japanese OEM procurement programs. ZF Friedrichshafen AG represents the tier-1 system integrator model, leveraging chassis-electronics consolidation to bundle wiper motor supply with broader visibility-system contracts.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Mitsuba Corporation |
| Robert Bosch GmbH |
| Marelli Holdings Co., Ltd. |
| Nidec Corporation |
| Denso Corporation |
| Continental AG |
| Trico Products Corporation |
| Valeo SA |
| Others |
Value Chain & Pricing Dynamics
Rare-earth magnet supply concentration in Chinese processing corridors determines both the cost-plus contract indexation patterns for brushless motor tiers and the geographic shape of upstream procurement networks. NHTSA and EU REACH compliance costs feed directly into pricing spreads between premium embedded-controller units and commodity replacement motors.
Pricing Analysis
Cost-plus contracts with neodymium and dysprosium price indexation dominate OEM direct procurement, spreading price volatility across quarterly adjustment clauses. Price differentiation separates ASIL-certified motor systems with embedded firmware from standard brushed units serving aftermarket channels. Cost compression in the conventional brushed segment is intensifying because of Chinese domestic oversupply and Indian import substitution. Fleet operators show lowest price sensitivity, prioritizing uptime guarantees over per-unit motor costs.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare-earth separation facilities, with secondary magnet alloy production concentrating in Japan and Germany. Copper winding, Hall-effect sensors, and MOSFET arrays constitute critical component inputs. Single-source vulnerability in Chinese rare-earth processing exposes brushless motor producers to export quota disruptions. Distribution runs through tier-1 system integrators in Stuttgart, Detroit, and Shanghai for OEM fitment, with aftermarket channels fragmenting across regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wiper motor procurement is converging toward software-defined vehicle platform economics, where motor-controller firmware interoperability with centralized domain architectures determines supplier viability.
For Market Incumbents: Insulate margin pools by securing captive magnet supply through backward integration into rare-earth alloy production or long-term offtake with Chinese separation facilities. Accelerate ISO 26262 ASIL certification timelines to defend against semiconductor-capable entrants targeting embedded-controller consolidation. For New Entrants and Emerging Players: Indian domestic vehicle assembly expansion represents the most penetrable entry point, with Maruti Suzuki and Tata Motors procurement programs seeking localized motor-controller supply. Target tier-2 system integration partnerships as the go-to-market angle, bypassing entrenched direct-OEM relationships in Germany and Japan. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors embedded-software-capable motor specialists over pure-play mechanical fabricators. Long-term viability rests on firmware differentiation and domain-computer integration capabilities. Monitor NHTSA rulemaking on automated driving visibility systems as the signal to watch for demand inflection toward ASIL-rated motor platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Controller Firmware Development | Enables direct integration with vehicle domain computers, collapsing traditional tier separation. |
| Rare-Earth Magnet Supply Security | Reduces exposure to Chinese export policy volatility through captive alloy production. |
| ISO 26262 ASIL Certification Investment | Positions motor systems for automated driving visibility stack procurement by German luxury OEMs. |
| Indian Manufacturing Footprint Expansion | Captures localization requirements from Maruti Suzuki and Tata Motors platform consolidation. |
| Predictive Maintenance Algorithm Partnership | Aligns with North American fleet operator telematics platforms for just-in-time replacement scheduling. |
Study Parameters
The analysis maps brushless DC motor architectures, heavy-duty commercial configurations, and embedded controller integration tiers, each validated through OEM platform engineers, tier-1 supplier procurement leads, aftermarket distribution managers, and rare-earth magnet trading specialists. Primary interview findings triangulate against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 104 compliance filings, and EU REACH substance restriction updates. Bottom-up segment sizing and top-down market reconciliation anchor value estimates.
Forecast assumptions hold fixed NHTSA visibility standard enforcement timelines, EU F-Gas lubricant restriction phase-in schedules, and Chinese MIIT electromagnetic-compatibility certification thresholds, while varying EV platform penetration rates and brushless motor displacement speed across the projection horizon. Segmentation dimensions include vehicle propulsion architecture, motor control technology, and regional production cluster. CAGRs derive from fitted adoption curves applied to OEM platform launch schedules and fleet replacement cycle compression trends.
Macroeconomic conditions sit as an overlay; deviation in rare-earth oxide pricing, automotive semiconductor availability, or Chinese export licensing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology substitution elasticities. Cross-checking against IHS Markit powertrain forecast benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Motor Sales Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Fluid Conveyance Products Motors Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Frameless Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Global Motor Soft Starter Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Global Hub Motors Market