
 Europe Household Refrigerator Market | 2026-2036
Europe Household Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Household Refrigerator Market Foresight
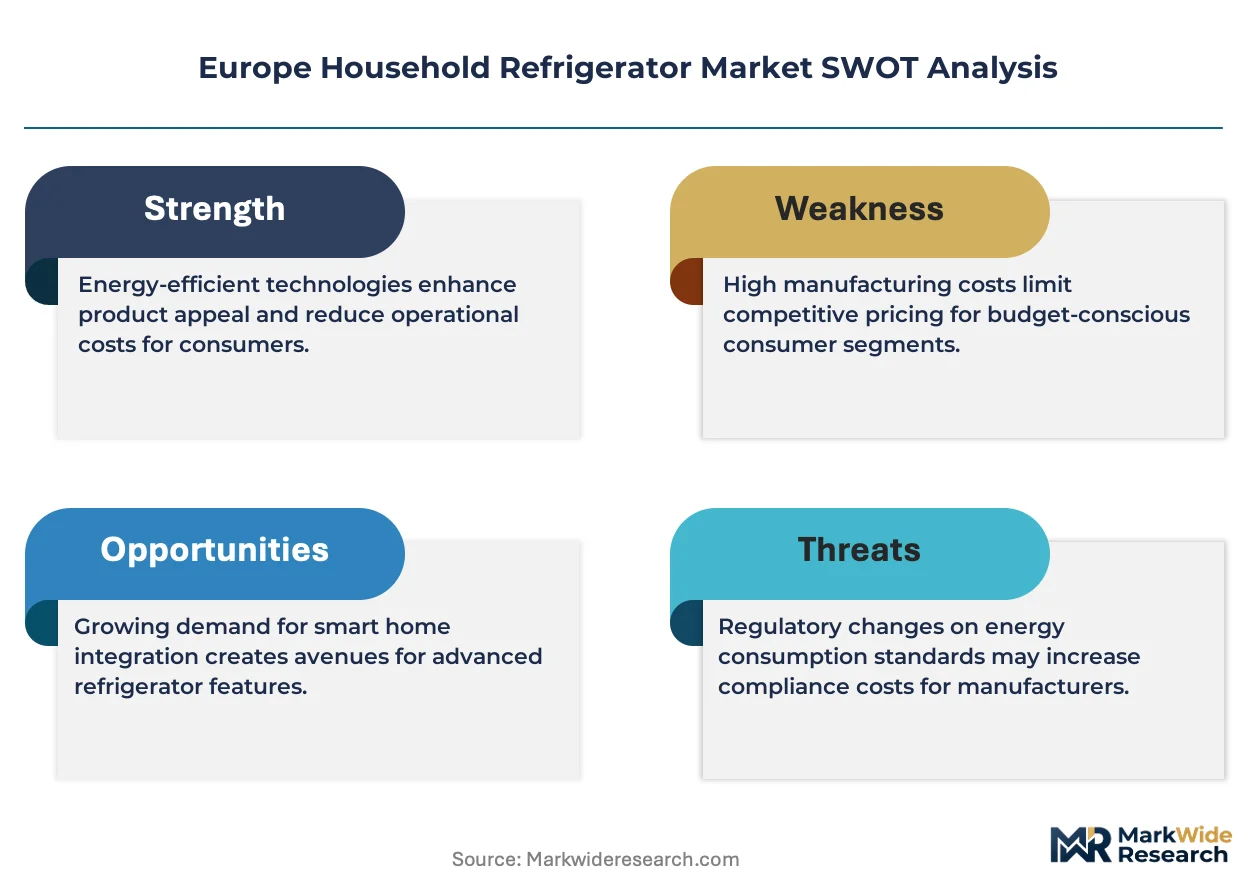
Premium energy-efficiency certification tiers is unwinding across European retail channels as consumers trade up from basic models. BSH Hausgeräte GmbH leverages its German manufacturing base to dominate high-end segmentation. Electrolux AB sustains Nordic market share through specialized cold-climate engineering. Liebherr anchors Alpine premium positioning with commercial-grade reliability.
Europe household refrigerator denotes an electrically powered insulated cabinet maintaining temperatures between 0°C and 5°C for fresh food preservation, typically employing vapor-compression refrigeration with isobutane or R600a refrigerant. French Door configurations command margin pools in family households, while Smart Refrigerators represent the fastest-growing technology segment as IoT integration spreads. Energy Efficient models lead volume across Germany and France where electricity tariffs pressure operating costs.
EU Ecodesign requirements and the F-Gas Regulation shape product roadmaps by mandating lower-GWP refrigerants and minimum efficiency thresholds. ECHA chemical restrictions further constrain insulation foam formulations. Stakeholders must monitor upcoming CE marking revisions and national appliance rebate programs as regulatory alignment between Brussels and member states tightens.
Market Dynamics
EU Ecodesign requirements and the F-Gas Regulation are compressing product development cycles while forcing manufacturers to abandon high-GWP refrigerants and retool insulation foam chemistries across European production lines.
Growth Catalysts
- EU Green Deal appliance efficiency mandates:Tighter energy-performance thresholds accelerate replacement demand in Germany and France as households trade up from aging units.
- Urban apartment densification:Compact French Door configurations gain traction in metropolitan Paris and Berlin where kitchen footprints shrink.
- Isobutane (R600a) refrigerant adoption:Lower-GWP chemistry aligns with ECHA chemical restrictions and opens rebate eligibility in national efficiency programs.
Market Restraints
- Polyurethane foam input cost volatility:Blowing agent transitions under F-Gas Regulation create formulation instability and margin pressure.
- Compressor supply concentration:Sourcing dependency on specialized German and Italian component houses limits production flexibility.
- Heat pump refrigeration technical limitation:Ambient temperature performance gaps constrain Nordic market penetration without auxiliary heating.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show lagging smart refrigerator adoption, creating first-mover whitespace for IoT-integrated models.
- CE marking revision preparation:Early compliance with anticipated cybersecurity and energy-labeling updates secures shelf positioning.
- Direct-to-builder channel innovation:New construction appliance bundling bypasses retail markups in high-rise developments across Madrid and Milan.
Industry Challenges
- Refrigeration engineer skill scarcity:Specialized training for hydrocarbon handling and electronic control integration outpaces vocational pipeline output.
- Multi-certification timeline compression:Parallel CE marking, national energy-label, and ECHA chemical compliance reviews extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Household Refrigerator Market |
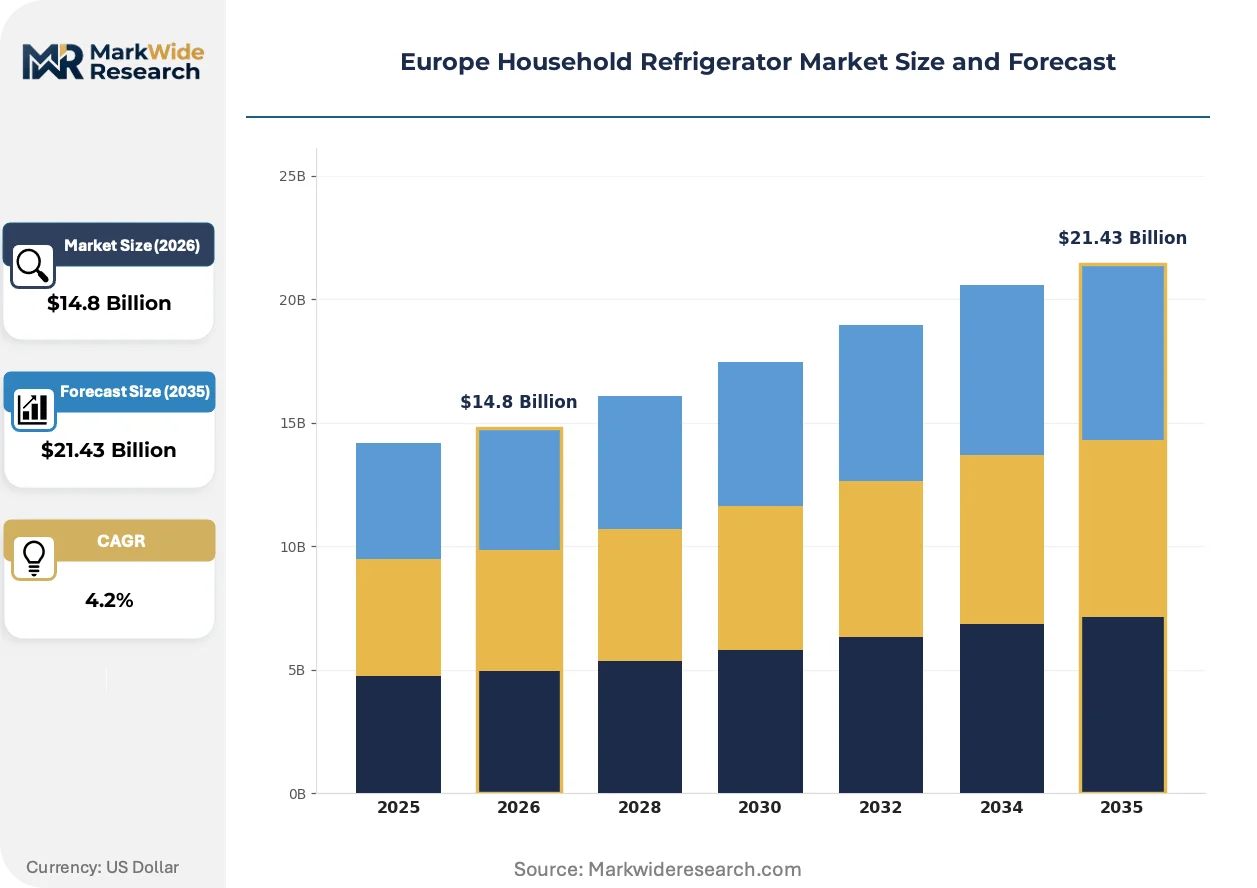
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Freezer, Bottom Freezer, Side-by-Side, French Door Technology: Smart Refrigerators, Energy Efficient, Standard Refrigerators, Mini Refrigerators End User: Residential, Apartments, Single-Family Homes, Multi-Family Units Size: Compact, Standard, Large Capacity, Commercial Use |
| Companies Covered | BSH Hausgeräte GmbH, Whirlpool Corporation, Electrolux AB, Samsung Electronics, LG Electronics, Haier Smart Home, Arçelik A.Ş., Miele & Cie. KG, Liebherr, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Household Refrigerator Market Shifts & Advancements
Connected appliance ecosystems and refrigerant chemistry transitions are redrawing competitive boundaries, while procurement patterns favor energy-certificate transparency over brand heritage in household decision-making.
Variable-speed inverter compressors are displacing fixed-speed reciprocating units in mid-tier European SKUs. German and French retailers now stock inverter models as default configurations. This displacement compresses margin pools for legacy compressor suppliers while rewarding electronics-integrated system houses.
REACH chemical restrictions and F-Gas Regulation amendments are forcing foam-blowing agent substitutions across insulation manufacturing. Reformulated polyurethane cores now dominate new product introductions. Alpine and Nordic markets show fastest compliance adoption due to stricter national implementation timelines.
Certificate-driven purchasing now governs replacement cycles in electricity-tariff-stressed markets. German households prioritize A+++ and A++++ energy labels over capacity specifications. Retail channels respond with label-transparent merchandising that accelerates premium-tier turnover in Berlin and Munich showrooms.
Europe Household Refrigerator Market Segmentation
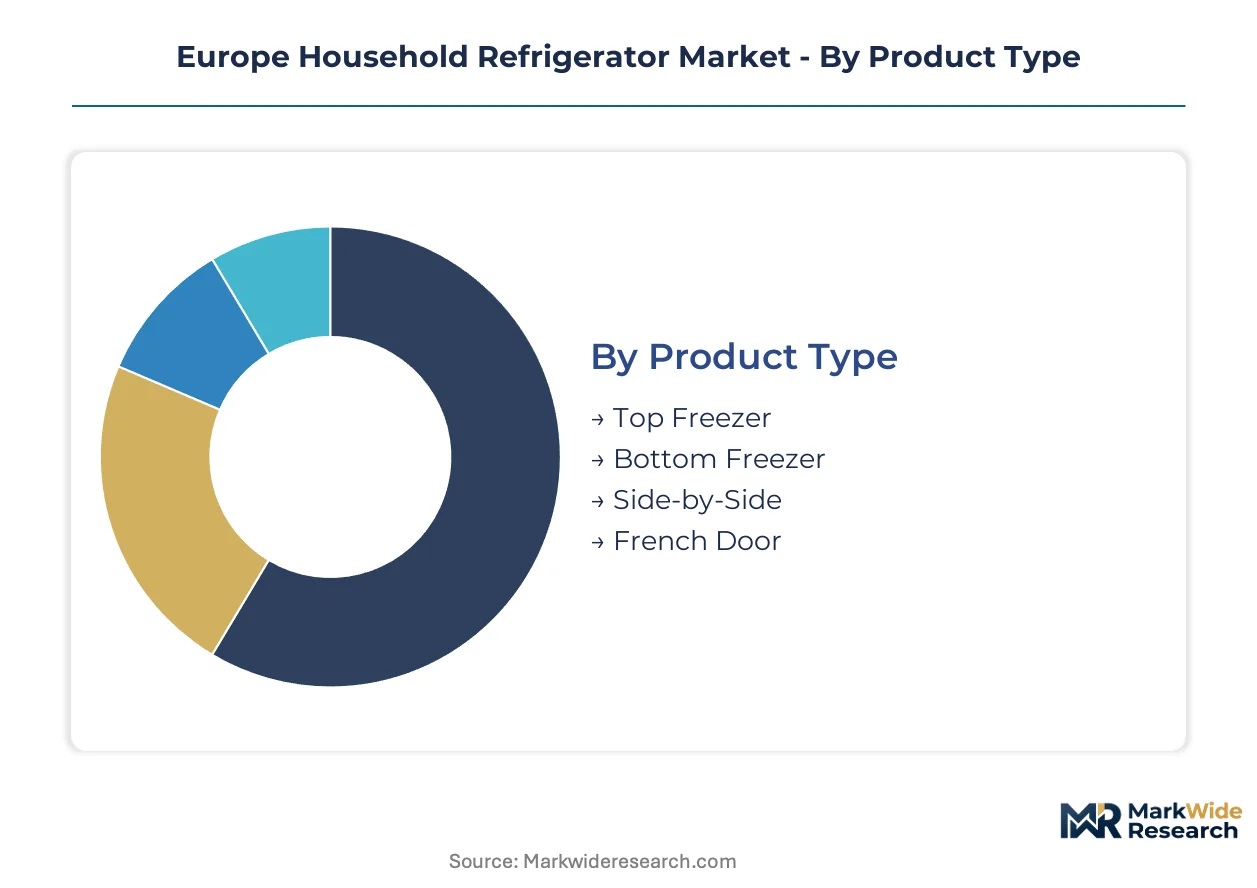
Refrigerator segmentation in Europe reflects divergent kitchen footprints, energy-cost pressures, and housing stock across metropolitan and rural zones. Manufacturers align portfolio depth to national rebate eligibility and apartment density patterns rather than treating the region as a uniform demand pool.
Product Type:
French Door and Side-by-Side models concentrate in export-oriented German and Italian manufacturing, while Top Freezer variants serve price-sensitive domestic markets in Poland and Romania.
- Top Freezer:Vertical evaporator placement above the refrigeration compartment suits narrow kitchen layouts common in post-war apartment blocks across Berlin and Warsaw. Demand concentrates in Eastern European markets where replacement cycles lag Western efficiency upgrades and purchase decisions prioritize unit cost over annual operating expenditure.
- Bottom Freezer:Drawer-based frozen food access aligns with ergonomic preferences in aging Western European populations. French and Belgian households favor this configuration for reduced bending frequency, though the compressor placement raises repair complexity that challenges service networks in rural Alpine zones.
- Side-by-Side:Split-column design with through-door ice dispensing dominates Nordic large-family installations.
- French Door:Triple-compartment layout with convertible middle drawers commands premium positioning in London and Paris new-build kitchens.
Top Freezer commands the established base. The steepest expansion runs through French Door.
Technology:
Cost-tier stratification separates rebate-eligible premium efficiency tiers from entry-level standard units, with smart connectivity emerging as a margin layer above hardware specifications.
- Smart Refrigerators:IoT-enabled inventory tracking and energy optimization algorithms integrate with utility demand-response programs in Denmark and the Netherlands. German retailers bundle these models with home energy management systems, though cybersecurity certification delays under pending CE marking revisions constrain rollout velocity in privacy-sensitive markets.
- Energy Efficient:A+++ and A++++ labeled units dominate replacement demand in electricity-tariff-stressed Germany and France. The EU Ecodesign directive mandates minimum efficiency thresholds that render sub-A++ models non-compliant, compressing volume for standard-tier manufacturers and accelerating portfolio consolidation toward inverter-compressor architectures.
- Standard Refrigerators:Fixed-speed compressor units persist in rental-property installations across Southern Europe.
- Mini Refrigerators:Sub-100 liter units serve hotel room and home office applications in dense urban cores.
Energy Efficient variants anchor volume shipments. Smart Refrigerators are climbing the fastest.
End User:
Customer-type segmentation tracks housing tenure patterns, with owner-occupied single-family installations driving premium specification while rental markets prioritize durability and repair simplicity.
- Residential:Aggregate category spanning all dwelling types, with purchasing authority concentrated in household rather than institutional procurement. This segment absorbs the majority of French Door and smart-technology adoption as discretionary upgrade cycles accelerate in high-income metropolitan zones.
- Apartments:Space-constrained installations under 70 square meters dominate Paris, Madrid, and Milan demand. Compact and bottom-freezer configurations predominate, with noise-level specifications (below 40 dB) often superseding capacity in purchase criteria due to open-plan kitchen-living layouts.
- Single-Family Homes:Detached and semi-detached dwellings in suburban Germany and the Netherlands favor large-capacity Side-by-Side and French Door models with dedicated wine preservation zones.
- Multi-Family Units:Purpose-built rental developments across Nordic capitals specify standardized mid-tier units for landlord-furnished installations.
Single-Family Homes anchor premium revenue. Apartments are gaining share fastest.
Size:
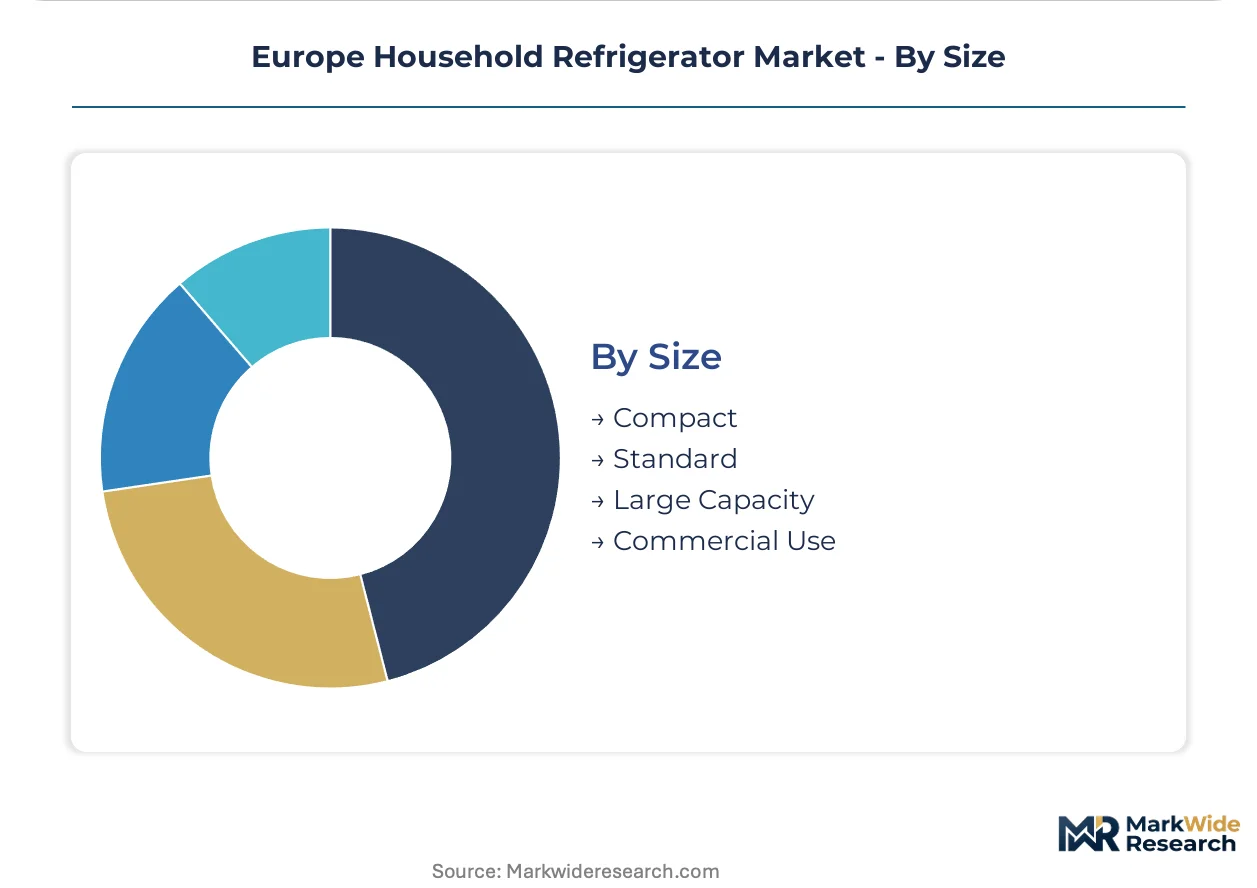
Volume-tier distribution correlates with kitchen square footage and household composition, with commercial-scale units penetrating prosumer segments rather than true food-service applications.
- Compact:Under-150 liter capacity serves secondary refrigeration needs in home offices, guest accommodations, and elderly single-person households across Southern France and Northern Italy. Energy labeling compliance challenges persist for this tier due to disproportionate standby consumption relative to usable volume.
- Standard:250-350 liter range matches average European household size and dominates replacement cycles in Germany and France. This tier faces the most intense price competition as inverter-compressor technology diffuses from premium positioning into mid-market SKUs.
- Large Capacity:Exceeding 400 liters, these units target multi-generational households and culinary enthusiasts in affluent suburban zones.
- Commercial Use:Prosumer-grade preservation equipment with precise humidity control serves wine collectors and charcuterie enthusiasts in Belgium and Switzerland.
Standard size commands the established base. Compact units are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component sourcing and final assembly concentrate in Germany, Italy, and Poland, creating a manufacturing corridor that supplies Western European retail channels. French and Benelux markets absorb premium-tier output, while Eastern European facilities serve cost-sensitive demand tiers. National rebate programs and electricity tariff structures fragment go-to-market strategies across the region.
Germany
Replacement demand from aging housing stock and the EU Green Deal efficiency mandates accelerate upgrade cycles in Berlin and Munich metropolitan zones. BAFA federal rebates for A+++ appliances compress payback periods for inverter-compressor models. BSH Hausgeräte anchors manufacturing in Giengen an der Brenz, supplying German retail chains with domestically produced French Door configurations.
France
Paris apartment densification drives compact bottom-freezer adoption where kitchen footprints average under eight square meters. The Coup de pouce Chauffage program extends appliance efficiency incentives beyond heating systems, capturing refrigerator replacements. Lyon and Grenoble clusters host specialized cold-chain engineering firms serving Alpine premium positioning.
Italy
Milan and Turin manufacturing bases export Side-by-Side models to Nordic markets while domestic demand favors standard-capacity units in aging rural housing. The Conto Termico 2.0 incentive scheme excludes standalone refrigerators, pushing manufacturers toward bundled kitchen appliance offerings. Emilia-Romagna component suppliers specialize in variable-speed inverter modules.
Poland
Warsaw and Kraków retail channels lag Western European smart refrigerator penetration, creating whitespace for IoT-integrated entry-tier models. National energy labeling enforcement remains less stringent than EU Ecodesign minima, allowing fixed-speed compressor inventory clearance. Poznań assembly plants serve re-export demand to Baltic states and Ukraine.
Netherlands
Amsterdam and Rotterdam households integrate refrigerators with home energy management systems under net-metering tariff structures. The ISDE sustainable energy investment deduction accelerates premium-tier turnover in Randstad urban cores. Philips legacy electronics expertise diffuses into connected appliance control module development in Eindhoven.
Europe Household Refrigerator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Premium-tier positioning concentrates among German and Nordic engineering specialists, while scale-driven manufacturers anchor mid-market volume through Eastern European production. Three archetypes dominate: vertically integrated appliance conglomerates, component-specialist system integrators, and premium-brand engineering houses. Competitive moves center on refrigerant chemistry transitions and inverter-compressor technology licensing.
Among Germany-based manufacturers, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify the premium-engineering archetype, while Electrolux AB represents Nordic cold-climate specialization. These three occupy positions defined by manufacturing geography and certification-tier focus rather than scale-driven cost structures.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Whirlpool Corporation |
| Electrolux AB |
| Samsung Electronics |
| LG Electronics |
| Haier Smart Home |
| Arçelik A.Ş. |
| Miele & Cie. KG |
| Liebherr |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with German and Italian compressor houses lock in component access while freezing input cost visibility for refrigerator manufacturers navigating EU Ecodesign compliance timelines. These contractual structures insulate BSH Hausgeräte and Electrolux AB from spot market volatility in copper winding and rare-earth magnet pricing, though they constrain flexibility when F-Gas Regulation amendments force rapid refrigerant chemistry pivots.
Pricing Analysis
EU Ecodesign requirements dictate the pricing tier structure by rendering sub-A++ models non-compliant and compressing volume toward premium efficiency certifications. Three-tier pricing structure across premium, standard, and economy levels separates A++++ inverter-compressor units from fixed-speed legacy models and rental-property basic configurations. Cost compression in mid-tier SKUs intensifies because inverter technology diffuses downward from premium positioning. Eastern European markets show highest price sensitivity, while German owner-occupiers prioritize energy-label transparency over unit cost.
Supply Chain Analysis
Germany, Italy, and Poland anchor refrigerator component manufacturing and final assembly across the European corridor. Production draws from specialized polyurethane foam formulation houses in Alpine zones, variable-speed inverter module suppliers in Emilia-Romagna, and hydrocarbon-compatible compressor specialists in Bavaria and Lombardy. Single-source vulnerability concentrates in German reciprocating compressor engineering, where vocational pipeline gaps constrain capacity expansion. Distribution runs through retail chains in metropolitan France and Germany, direct-to-builder channels in Madrid and Milan high-rises, and re-export networks from Poznań to Baltic states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerator purchasing is shifting from discrete appliance replacement toward connected home energy management platform participation, as IoT integration and utility demand-response interoperability reshape household decision criteria across Denmark and the Netherlands.
For Market Incumbents: Fortify inverter-compressor technology licensing positions against emerging Korean electronics integrators by deepening captive supply of variable-speed control modules. Secure early CE marking revision compliance for cybersecurity certification to defend shelf positioning against privacy-sensitive market fragmentation. Channel control through direct-to-builder partnerships in Milan and Madrid high-rise developments limits retail markup exposure. For New Entrants and Emerging Players: Lead with IoT-integrated entry-tier models in Polish and Romanian markets where smart refrigerator penetration lags Western European adoption curves. Target Warsaw and Kraków retail whitespace before incumbent rebate bundling tightens. Go-to-market angle should emphasize utility demand-response program eligibility under national efficiency schemes. For Investors and Strategic Acquirers: Capital is best deployed toward component-specialist system integrators with hydrocarbon handling expertise and electronic control integration capabilities, as refrigeration engineer skill scarcity constrains vocational pipeline output. Long-term viability favors manufacturers with backward integration into inverter module production and foam-blowing agent formulation. Watch CE marking revision implementation velocity as inflection indicator for compliance cost differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter-Compressor Technology Licensing | Secures margin pools as variable-speed architectures displace fixed-speed units in German retail channels. |
| CE Marking Revision Preparation | Early cybersecurity and energy-labeling compliance secures shelf positioning in privacy-sensitive Benelux markets. |
| Direct-to-Builder Channel Development | Bypasses retail markups in Madrid and Milan high-rise developments where appliance bundling concentrates. |
| Hydrocarbon Refrigerant Transition | Aligns with F-Gas Regulation mandates and unlocks BAFA federal rebate eligibility in German metropolitan zones. |
| IoT Platform Integration | Captures utility demand-response program participation in Dutch net-metering tariff structures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Ecodesign directive filings, F-Gas Regulation amendment drafts, national energy-label databases, and refrigerator manufacturer SEC disclosures. Primary interviews engaged product development directors at German and Italian appliance conglomerates, procurement leads at polyurethane foam suppliers, retail category managers in Paris and Berlin, and refrigeration engineer training program administrators. Bottom-up unit shipment triangulation against top-down value aggregation validates volume and value estimates across the analysis window.
Segmentation dimensions modeled include product type configuration, technology tier, end-user housing tenure pattern, and capacity sizing, cross-referenced with national rebate eligibility and electricity tariff structures. CAGRs were derived from replacement cycle compression analysis and efficiency upgrade elasticity in tariff-stressed markets. Forecast inputs incorporated EU Green Deal mandate implementation timelines and REACH chemical restriction phase-in schedules.
Forecasts assume regulatory continuity in EU Ecodesign requirements, F-Gas Regulation enforcement, and national appliance rebate programs; material policy shifts would require re-modeling. Specific risks include ECHA chemical restriction acceleration, compressor supply concentration disruption, and CE marking revision scope expansion. Recalibration cycles align with material shifts in refrigerant chemistry adoption and inverter-compressor technology diffusion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Smart Kettle Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Russia Kitchen Appliances Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Electric Grill Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market