
 North America Facilities Management Market | 2026-2036
North America Facilities Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Facilities Management Market Outlook
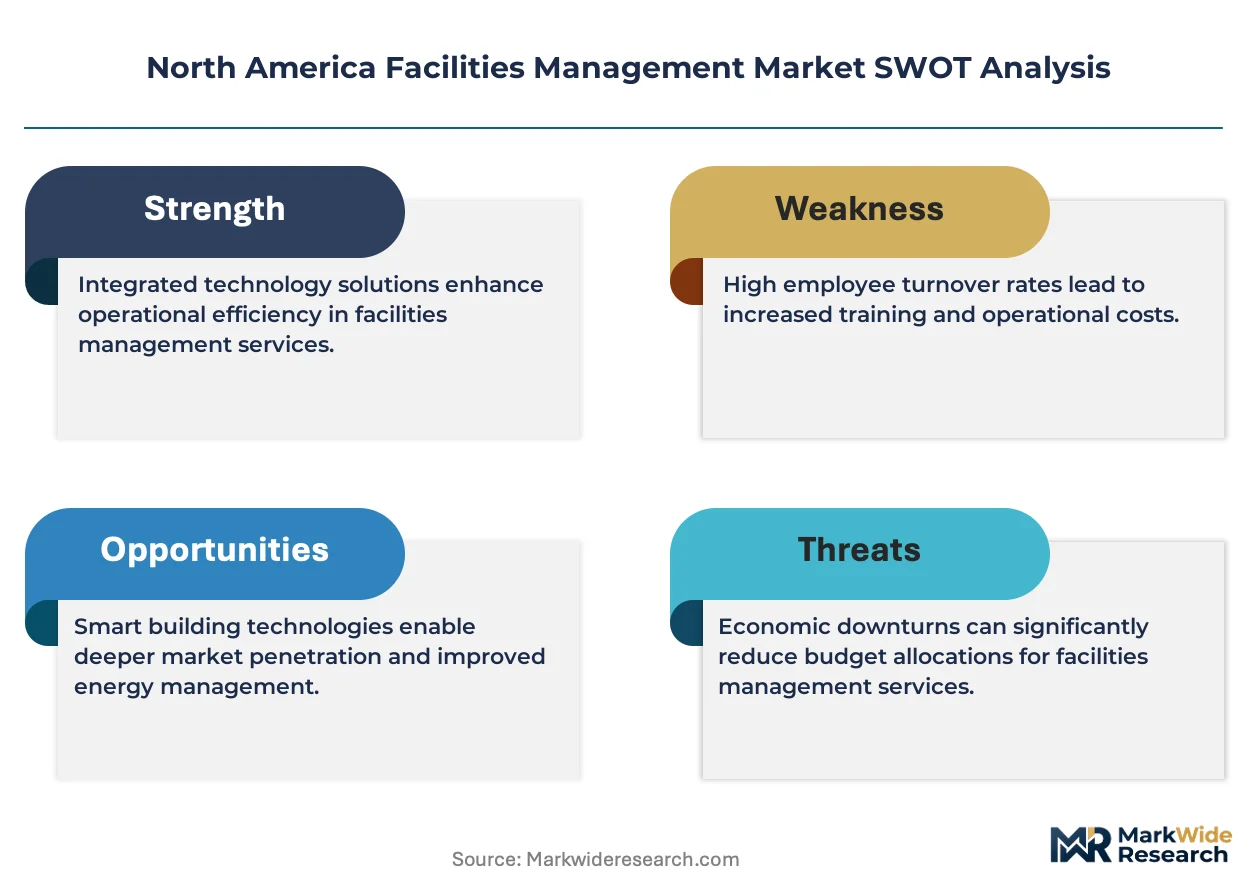
Smart building technology is fragmenting traditional facilities management into sensor-driven, predictive service layers that reshape how mechanical, electrical, and plumbing systems are maintained. CBRE Group leverages its proprietary technology platform to integrate IoT-enabled asset monitoring across client portfolios. JLL anchors its competitive stance through deep vertical expertise in life sciences and data center facilities. EMCOR Group sustains market position through in-house mechanical contracting capabilities that reduce subcontractor dependency.
Facilities management encompasses the coordinated delivery of hard services (mechanical, electrical, HVAC, and structural maintenance) and soft services (cleaning, security, catering, and groundskeeping) to ensure operational continuity, occupant safety, and asset lifecycle optimization across commercial and institutional properties. Hard maintenance services dominate current revenue pools due to capital-intensive equipment replacement cycles and regulatory compliance burdens, while AI-powered predictive maintenance within the technology segment captures the fastest expansion as building operators shift from scheduled to condition-based interventions. Cloud-based CMMS deployments are displacing on-premise legacy systems, concentrating margin pools in subscription-based platform providers.
OSHA workplace safety standards, EPA energy efficiency mandates, and the US Inflation Reduction Act retrofit incentives collectively elevate compliance costs and create procurement preference for full-service providers with certified environmental management systems. Canada’s National Energy Code for Buildings and provincial carbon reduction targets in Ontario and British Columbia further tighten operational performance requirements. Stakeholders must evaluate whether technology investments or outsourcing partnerships offer superior paths to meeting tightening energy and safety benchmarks.
Market Dynamics
Energy retrofit mandates under the US Inflation Reduction Act are compressing payback periods for smart building investments, forcing facility operators to choose between capital-intensive technology stacks and outsourced integrated service contracts. This regulatory pressure is restructuring procurement patterns across commercial real estate portfolios.
Growth Catalysts
- OSHA workplace safety standards:Compliance burdens are expanding scope requirements for full-service facilities management contracts as building operators seek bundled certification support.
- Healthcare facilities:Hospital networks are consolidating vendor relationships into integrated hard and soft service agreements covering predictive maintenance and specialized cleaning protocols.
- IoT-enabled asset monitoring:Sensor networks are enabling condition-based interventions that reduce emergency repair costs and extend equipment lifecycles across multi-site portfolios.
Market Restraints
- Skilled technician shortage:Licensed HVAC and electrical trades face aging workforce demographics that constrain service capacity expansion in Texas and California.
- Subcontractor dependency:Specialized mechanical contracting capabilities concentrate among regional players, creating supply concentration risk for national facilities management providers.
- Legacy CMMS integration costs:Cloud platform migrations require substantial data migration expenditure that delays technology adoption among mid-market property owners.
Strategic Opportunities
- Data center vertical:Hyperscale computing expansion in Northern Virginia and Phoenix is creating demand for mission-critical facilities management with 24/7 uptime guarantees.
- Canada carbon reduction targets:Ontario and British Columbia provincial mandates are accelerating building performance contracting opportunities for energy service companies.
- AI-powered predictive maintenance:Machine learning convergence with building automation systems is opening subscription revenue streams for performance-guaranteed service models.
Industry Challenges
- Certified energy auditor scarcity:EPA and utility program requirements for retrofit incentive eligibility face qualified assessor bottlenecks that delay project initiation.
- Multi-vendor platform integration:Disparate IoT protocols and proprietary data formats create interoperability friction when consolidating sensor networks across acquired properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Facilities Management Market |
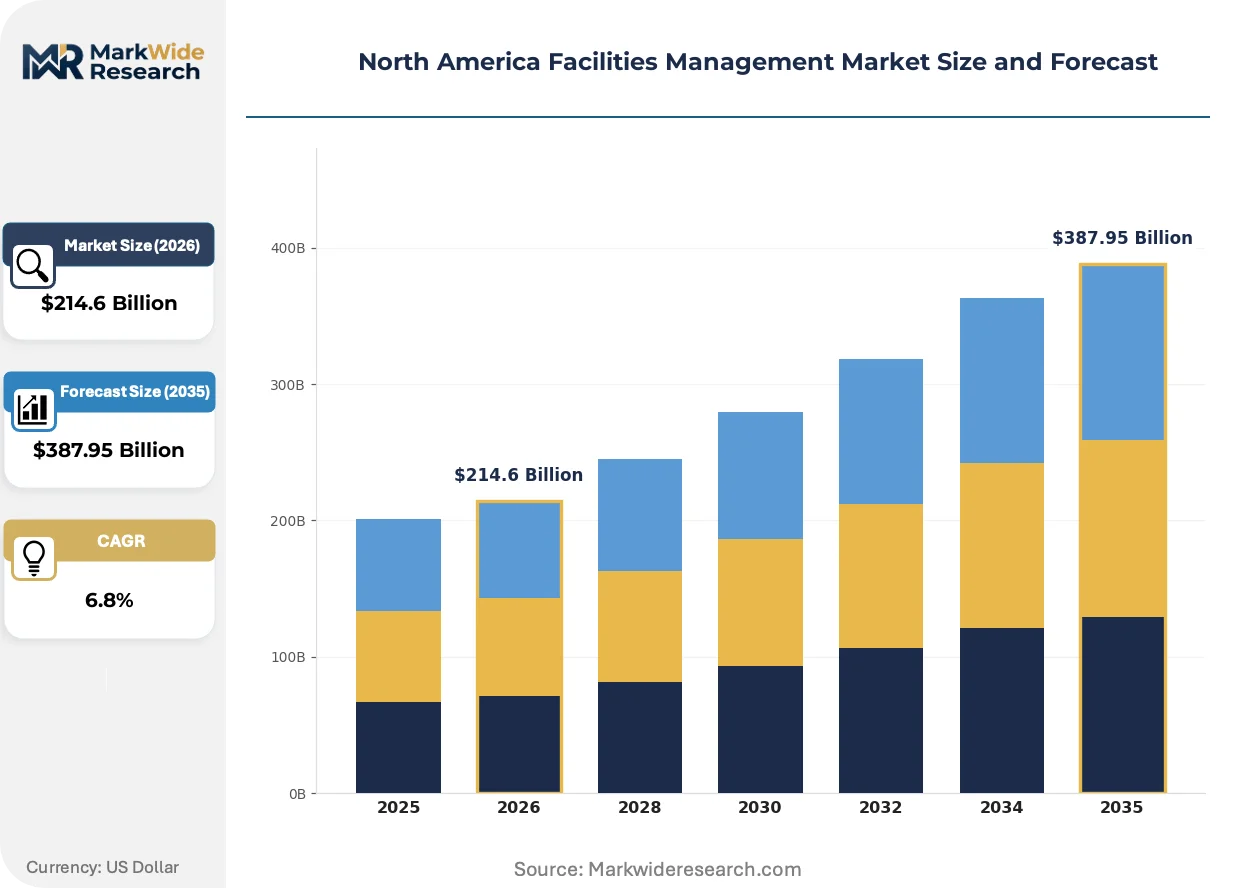
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Utilities End User: Commercial, Industrial, Educational, Healthcare Technology: IoT, AI, Cloud Computing, CMMS Pricing Model: Perpetual License, Subscription, Pay-Per-Use, Fixed Rate |
| Companies Covered | CBRE Group, Inc., JLL, EMCOR Group, Inc., ABM Industries Inc., Aramark, Cushman and Wakefield PLC, Sodexo Inc., SMI Facility Services, GDI Integrated Facility Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Facilities Management Market Strategic Shifts
Digital twin technology is compressing commissioning timelines and enabling remote facility optimization, while regulatory pressure on embodied carbon is reshaping material selection and equipment replacement cycles across North American commercial portfolios.
Digital twin platforms are creating virtual replicas of building systems that simulate HVAC performance under varying occupancy loads. Large office landlords in Manhattan and Chicago are deploying these tools during capital planning cycles. The technology is rendering obsolete traditional energy modeling that relied on static assumptions rather than real-time operational data.
The US Inflation Reduction Act's Section 179D deduction expansion is tightening energy efficiency thresholds for commercial building retrofits. Property owners must now document 25% energy cost reductions to capture full incentives. Data center operators in Texas and Arizona are most affected, accelerating procurement of integrated design-build-maintain contracts that guarantee performance outcomes.
Corporate real estate teams are consolidating vendor relationships from fragmented specialty contractors to single-source integrated facilities management providers. Healthcare systems and financial services firms are leading this consolidation, replacing transactional maintenance with outcome-based agreements. This pattern is most visible in Ontario's Greater Toronto Area where hospital network expansion is driving demand for certified environmental management systems.
North America Facilities Management Market Segmentation
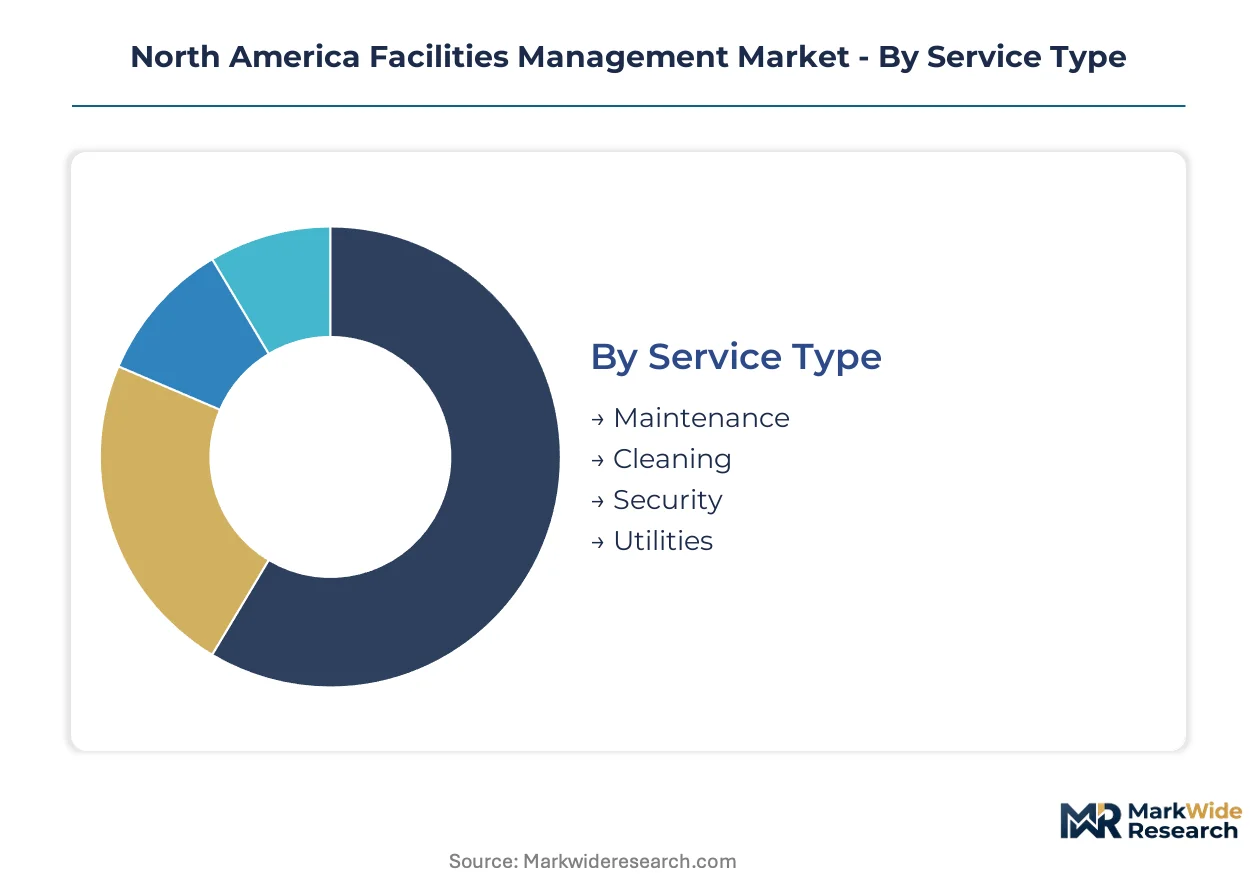
Facilities management procurement varies sharply by operational complexity and capital intensity. Service bundling decisions hinge on whether clients prioritize cost predictability, specialized compliance, or technology integration.
Service Type:
Hard services dominate capital planning cycles while soft services offer margin expansion through recurring contracts.
- Maintenance:Mechanical, electrical, and HVAC upkeep commands premium pricing due to licensed technician requirements and regulatory inspection schedules. Hospital networks in Ontario and Texas are consolidating predictive maintenance contracts to reduce emergency repair frequency and satisfy Joint Commission accreditation standards.
- Cleaning:Specialized protocols for healthcare and food service environments carry certification requirements that fragment the vendor base. Demand concentrates in California's life sciences corridor where cleanroom standards exceed standard commercial specifications.
- Security:Integrated access control and manned guarding services scale with facility risk profiles.
- Utilities:Energy procurement and water management services expand under carbon reduction mandates.
The dominant share belongs to Maintenance, while Cleaning is closing the gap fastest.
End User:
Customer archetypes range from price-sensitive multi-tenant offices to mission-critical infrastructure operators.
- Commercial:Office landlords and retail property managers prioritize service cost predictability over technical sophistication. Manhattan and Chicago Class A towers are driving integrated contract adoption as vacancy pressures squeeze operating budgets.
- Healthcare:Hospital systems require Joint Commission-compliant environmental services and 24/7 equipment uptime guarantees. Texas Medical Center expansion and Ontario hospital network consolidation are accelerating vendor consolidation into single-source agreements.
- Industrial:Manufacturing and warehouse facilities demand heavy equipment maintenance and safety compliance.
- Educational:University campuses balance deferred maintenance backlogs against tight state funding cycles.
Commercial captures the largest contract volume, though Healthcare is expanding most quickly.
Technology:
Adoption maturity splits between established building automation and emerging AI applications.
- IoT:Sensor networks for occupancy, air quality, and equipment vibration monitoring enable condition-based interventions. Northern Virginia data center operators are deploying edge-connected devices to meet 99.999% uptime requirements.
- AI:Machine learning platforms analyze equipment degradation patterns to forecast failures before critical thresholds. Phoenix hyperscale facilities are piloting neural network models that reduce cooling energy consumption.
- Cloud Computing:Distributed processing supports real-time analytics across geographically dispersed portfolios.
- CMMS:Computerized maintenance management systems transition from on-premise legacy installations to SaaS platforms.
IoT holds established deployment share, while AI is gaining share fastest.
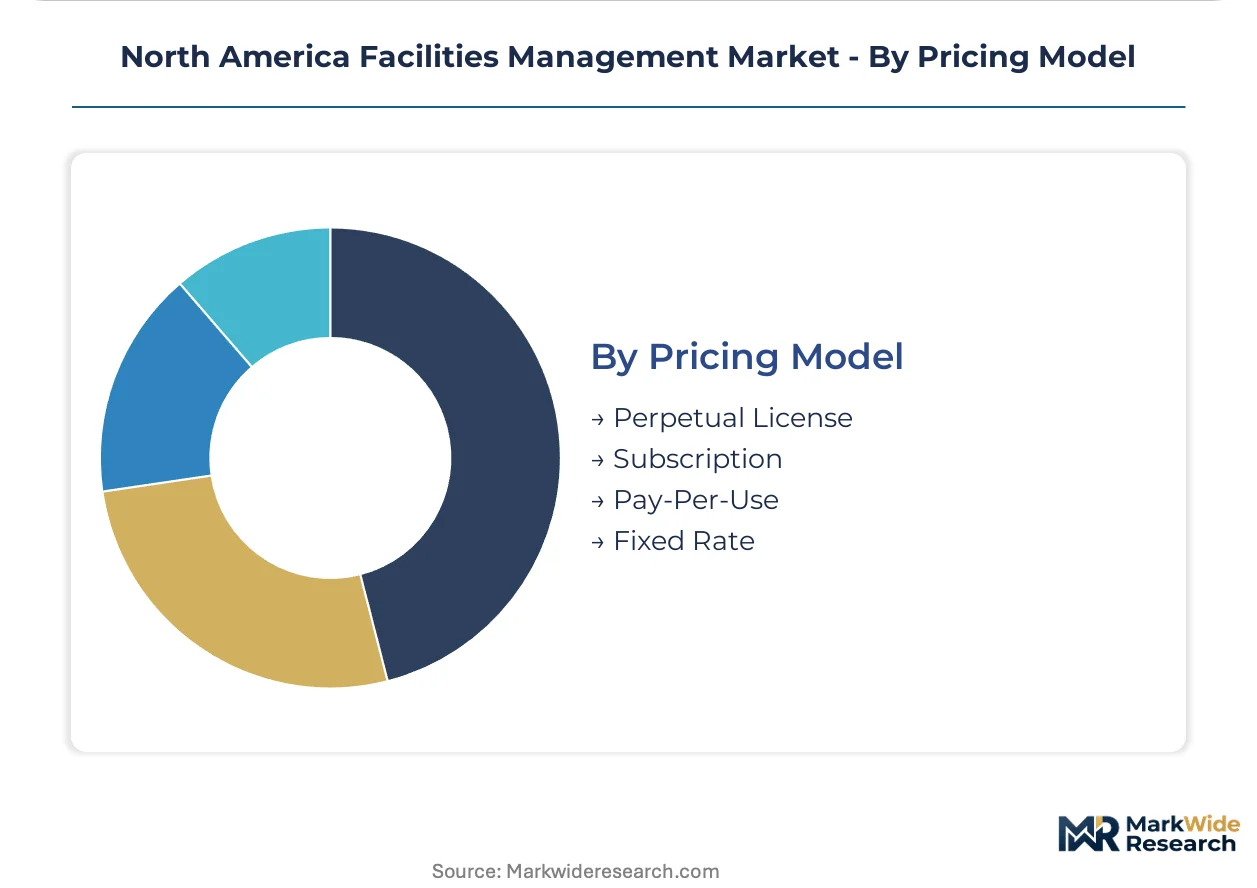
Pricing Model:
Contract structures reflect risk allocation preferences between clients and service providers.
- Subscription:Recurring SaaS fees for CMMS and IoT platforms align vendor incentives with system uptime outcomes. Mid-market property owners in California favor this model to avoid capital expenditure approval cycles.
- Fixed Rate:Comprehensive facilities management contracts transfer operational risk to service providers for predictable annual fees. Ontario healthcare systems are mandating fixed-rate structures to align vendor payments with patient satisfaction scores.
- Perpetual License:One-time software purchases with maintenance fees appeal to capital-rich institutional owners.
- Pay-Per-Use:Consumption-based pricing for specialized equipment or emergency services matches cost to actual utilization.
Subscription claims the dominant share, while Fixed Rate is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems and data center operators concentrate procurement power in Texas, California, and Ontario, where commercial real estate development and regulatory retrofit mandates drive integrated service contract adoption.
United States
Texas Medical Center expansion and Northern Virginia hyperscale data center construction dominate demand. OSHA workplace safety standards and the US Inflation Reduction Act retrofit incentives compress technology payback periods. Phoenix operators pilot AI-powered cooling optimization while Austin hospital networks consolidate vendor relationships.
Canada
Ontario hospital network consolidation and British Columbia carbon reduction targets accelerate building performance contracting. Canada's National Energy Code for Buildings tightens operational requirements. Greater Toronto Area healthcare systems mandate fixed-rate structures aligned with patient satisfaction metrics.
California
Life sciences corridor cleanroom specifications and Class A office vacancy pressures reshape procurement. EPA energy efficiency mandates elevate compliance costs. San Francisco and Los Angeles landlords drive integrated contract adoption to squeeze operating budgets.
Illinois
Chicago Class A tower operators prioritize cost predictability amid vacancy pressures. State funding cycles constrain university campus maintenance budgets. Downtown commercial landlords deploy digital twin platforms during capital planning cycles.
New York
Manhattan office landlords consolidate vendor relationships under outcome-based agreements. Deferred maintenance backlogs compete with tight operating budgets. Large commercial portfolios drive adoption of subscription-based CMMS platforms to avoid capital expenditure approval cycles.
North America Facilities Management Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates margin pools in subscription-based platform providers and integrated service bundlers. The vendor base organizes into three strategic archetypes: technology-anchored integrators leveraging proprietary IoT platforms, vertically capable mechanical contractors reducing subcontractor dependency, and vertical specialists commanding premium positioning in mission-critical segments. Dominant competitive moves include M&A to capture in-house mechanical capabilities and strategic partnerships to consolidate sensor network interoperability.
Within the technology-anchored integrator tier, CBRE Group and JLL occupy positions exemplifying platform-driven portfolio management. Among vertically integrated mechanical contractors, EMCOR Group represents the archetype of in-house capability capture. These three entities anchor the competitive structure through differentiated control points: proprietary technology deployment, vertical mechanical expertise, and deep sector specialization.
| Leading Market Players |
|---|
| CBRE Group, Inc. |
| JLL |
| EMCOR Group, Inc. |
| ABM Industries Inc. |
| Aramark |
| Cushman and Wakefield PLC |
| Sodexo Inc. |
| SMI Facility Services |
| GDI Integrated Facility Services |
| Others |
Value Chain & Pricing Dynamics
Northern Virginia data center clusters anchor capacity expansion for mission-critical facilities management, concentrating pricing power among providers with certified 99.999% uptime guarantees and in-house mechanical contracting capabilities that bypass subcontractor bottlenecks.
Pricing Analysis
Cost-plus contracts indexed to licensed technician wage benchmarks dominate integrated facilities management agreements, particularly in Texas and California where HVAC and electrical trades face acute labor shortages. Price differentiation rests on certification tiers—Joint Commission accreditation for healthcare and ISO 14001 environmental management systems command 15-25% premiums over standard commercial service tiers. Pricing pressure stems from cloud-based CMMS subscription models displacing perpetual licenses, compressing margins for legacy platform providers. Mid-market property owners in California exhibit highest price sensitivity due to capital expenditure approval constraints, while Ontario hospital networks prioritize outcome-based fixed-rate structures over cost minimization.
Supply Chain Analysis
Export controls on advanced IoT sensors and edge computing hardware limit technology flows to North American facilities management providers, constraining smart building deployment timelines. Component sourcing draws from Mexico for mechanical assemblies, Taiwan for semiconductor-dependent sensors, and domestic US fabrication for building automation controllers. Supply chain risk centers on single-source vulnerability for predictive maintenance software platforms, where proprietary data formats create vendor lock-in. Distribution runs through national account structures anchored by CBRE Group and JLL, with regional mechanical contractors serving as secondary channels for specialized hard services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed HVAC technician deficits and certified energy auditor scarcity constrain service capacity expansion across Texas, California, and Ontario, elevating strategic value for providers with captive training pipelines and in-house mechanical expertise.
For Market Incumbents: Entrench market position through backward integration into mechanical contracting capabilities that reduce subcontractor dependency, particularly in Texas where hospital network expansion accelerates. Acquire regional HVAC specialists to secure licensed technician pipelines against aging workforce demographics. Prioritize IoT platform certification investments to meet EPA energy efficiency mandates and capture Inflation Reduction Act retrofit incentives before qualified assessor bottlenecks ease. For New Entrants and Emerging Players: Pursue white-space opportunities in British Columbia building performance contracting, where provincial carbon reduction targets outpace established provider capacity. Target mid-market data center operators in Phoenix seeking alternatives to incumbent pricing for AI-powered cooling optimization services. Deploy subscription-based CMMS platforms with guaranteed uptime SLAs as the primary go-to-market wedge against capital-constrained California property owners. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement pattern shifts toward single-source integrated contracts favor scaled providers with technology platforms and vertical mechanical capabilities. Acquisition targets should profile as regional mechanical contractors with EPA-certified environmental management systems and established relationships with Ontario healthcare networks. Watch certified energy auditor pipeline expansion as the signal indicating when retrofit incentive capture becomes commoditized and technology differentiation erodes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Contracting | Reduces subcontractor dependency in Texas and California where licensed technician scarcity constrains capacity expansion. |
| IoT Platform Certification Investment | Captures EPA energy efficiency mandate compliance and Inflation Reduction Act retrofit incentive eligibility. |
| Predictive Maintenance SaaS Launch | Transitions revenue from transactional repairs to subscription-based condition-based intervention models. |
| Healthcare Vertical Specialization | Secures Joint Commission-compliant environmental services contracts amid Ontario hospital network consolidation. |
| Data Center Mission-Critical Certification | Commands premium pricing for 99.999% uptime guarantees in Northern Virginia and Phoenix hyperscale markets. |
Study Parameters
Operator-level perspectives from facilities directors at Texas Medical Center hospitals, Northern Virginia data center operations managers, Ontario healthcare procurement leads, and California Class A office property managers anchored the qualitative base. Secondary validation drew from OSHA workplace safety filings, EPA energy efficiency compliance databases, SEC 10-K disclosures from publicly traded service providers, and provincial building code updates from Ontario and British Columbia. Bottom-up service contract value aggregation triangulated against top-down market sizing from commercial real estate development pipelines.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, upside, and downside cases reflecting regulatory enforcement intensity and technology adoption velocity. Segmentation dimensions modeled encompassed service type, end-user vertical, technology deployment maturity, and pricing model structure. CAGRs derived from historical contract value trajectories adjusted for Inflation Reduction Act incentive phase-in schedules and IoT sensor cost decline curves. Forecast inputs incorporated skilled technician workforce projections from Bureau of Labor Statistics and hospital capital expenditure plans from Ontario Ministry of Health disclosures.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate vacancy rates, construction lending availability, or utility energy price trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory incentive continuity and technology interoperability standardization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Asia Pacific Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
France Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
GCC Facility Management Market