
 Australia Mobile Payment Market | 2026-2036
Australia Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Mobile Payment Market Analysis
Market Context
Small business merchant adoption is hardening as cafes, restaurants, and independent retailers replace traditional terminals with smartphone-based checkout systems. Commonwealth Bank of Australia leverages its extensive merchant network to sustain dominance in integrated point-of-sale solutions. Afterpay Limited differentiates through its buy-now-pay-later embedded checkout experience, while Zip Co Limited competes aggressively for retailer partnerships in the mid-market segment.
Technical Definition and Structural Segments
Australia mobile payment denotes electronic fund transfers executed through portable computing devices, utilizing tokenized credentials, near-field communication protocols, and real-time banking rails to settle transactions without physical card presentation. The technology encompasses NFC-enabled tap-to-pay, QR code scanning, and host card emulation systems that route payments through domestic schemes including the New Payments Platform. Digital wallets lead transaction volume growth as consumers consolidate credentials, while peer-to-peer service models capture expanding share through social payment use cases; QR code technology remains fastest-growing among merchant categories seeking low-friction onboarding without dedicated terminal hardware.
Regulatory Frame and Outlook
The Australian Competition and Consumer Commission enforces payment system access rules, while the Reserve Bank of Australia governs interchange fee regulation and real-time settlement infrastructure standards; the Australian Prudential Regulation Authority shapes operational risk requirements for licensed deposit-taking institutions offering mobile wallets. The Consumer Data Right, administered by the Office of the Australian Information Commissioner, mandates data portability that intensifies competition among wallet providers. Stakeholders must monitor open banking API maturity and forthcoming digital identity frameworks that will determine authentication standards and market access conditions.
Market Dynamics
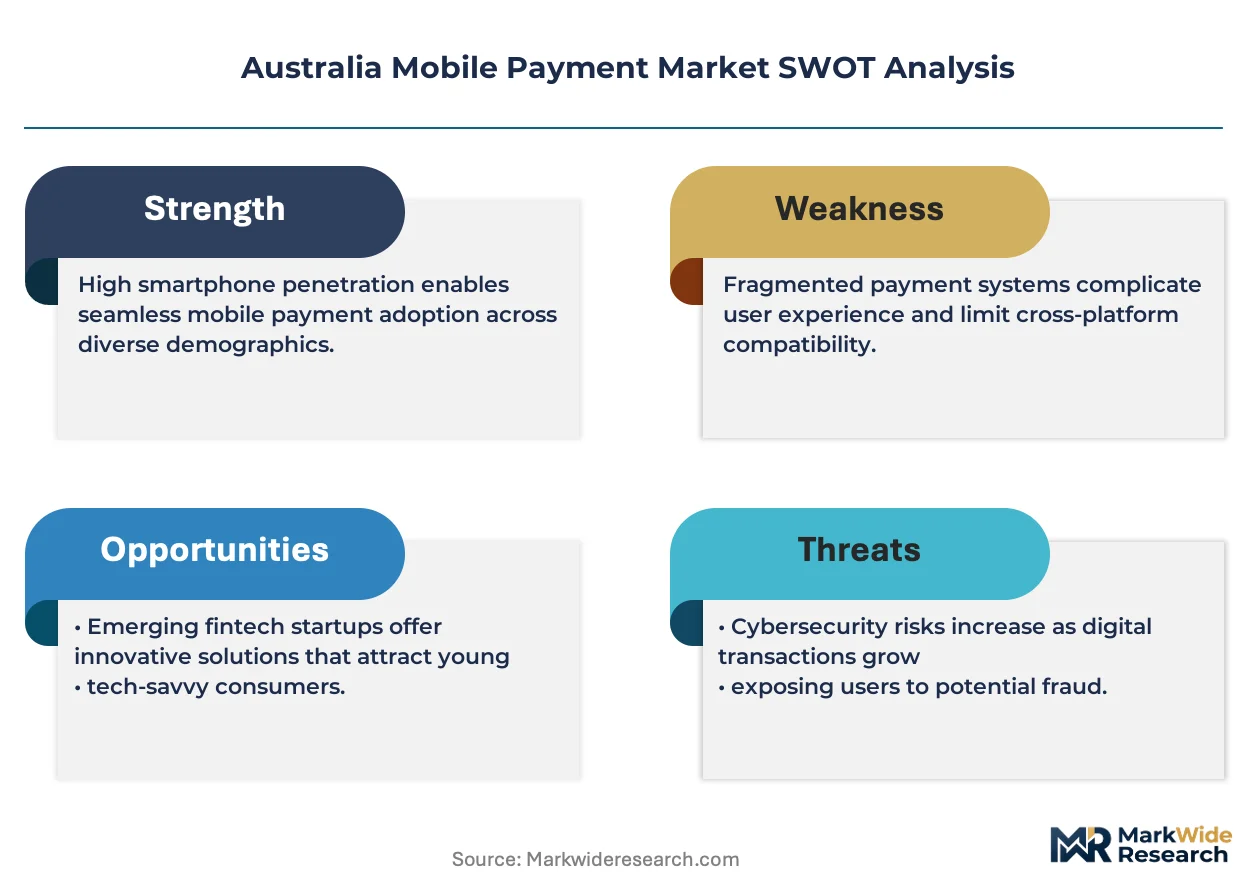
The Consumer Data Right regime is forcing open banking interoperability across Australia's financial sector, dismantling proprietary data silos that previously locked consumers into single-institution wallet ecosystems.
Growth Catalysts
- New Payments Platform:Real-time settlement infrastructure eliminates transaction delays, enabling instant peer-to-peer transfers and merchant settlements that accelerate cashless adoption.
- Hospitality sector digitization:Cafes and restaurants are replacing legacy terminals with smartphone-based checkout systems to reduce hardware costs and queue times.
- Tokenization standards:Host card emulation protocols secure credential storage, reducing fraud liability and consumer hesitation at point-of-sale.
Market Restraints
- Interchange fee compression:Reserve Bank of Australia regulations cap merchant service fees, squeezing revenue margins for payment processors and wallet providers.
- Regional connectivity gaps:Rural Queensland and Northern Territory areas lack reliable 4G/5G coverage, limiting NFC transaction reliability outside metropolitan zones.
- Biometric authentication costs:Facial recognition and fingerprint hardware requirements raise device replacement expenses for small merchants.
Strategic Opportunities
- Tasmanian SME penetration:Hobart and Launceston merchant categories show sub-40 percent digital wallet acceptance, presenting first-mover expansion potential.
- Superannuation fund integration:Retirement savings platforms are exploring embedded payment credentials for bill-pay and recurring contributions.
- QR-to-NFC convergence:Hybrid checkout systems combining quick-response codes with near-field communication reduce hardware barriers for pop-up retail and event commerce.
Industry Challenges
- API standardization delays:Inconsistent open banking endpoint implementations across major banks force wallet developers to maintain multiple integration codebases.
- Legacy terminal replacement cycles:Independent retailers operate 5-7 year depreciation schedules, slowing smartphone-based point-of-sale migration despite total-cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Mobile Payment Market |
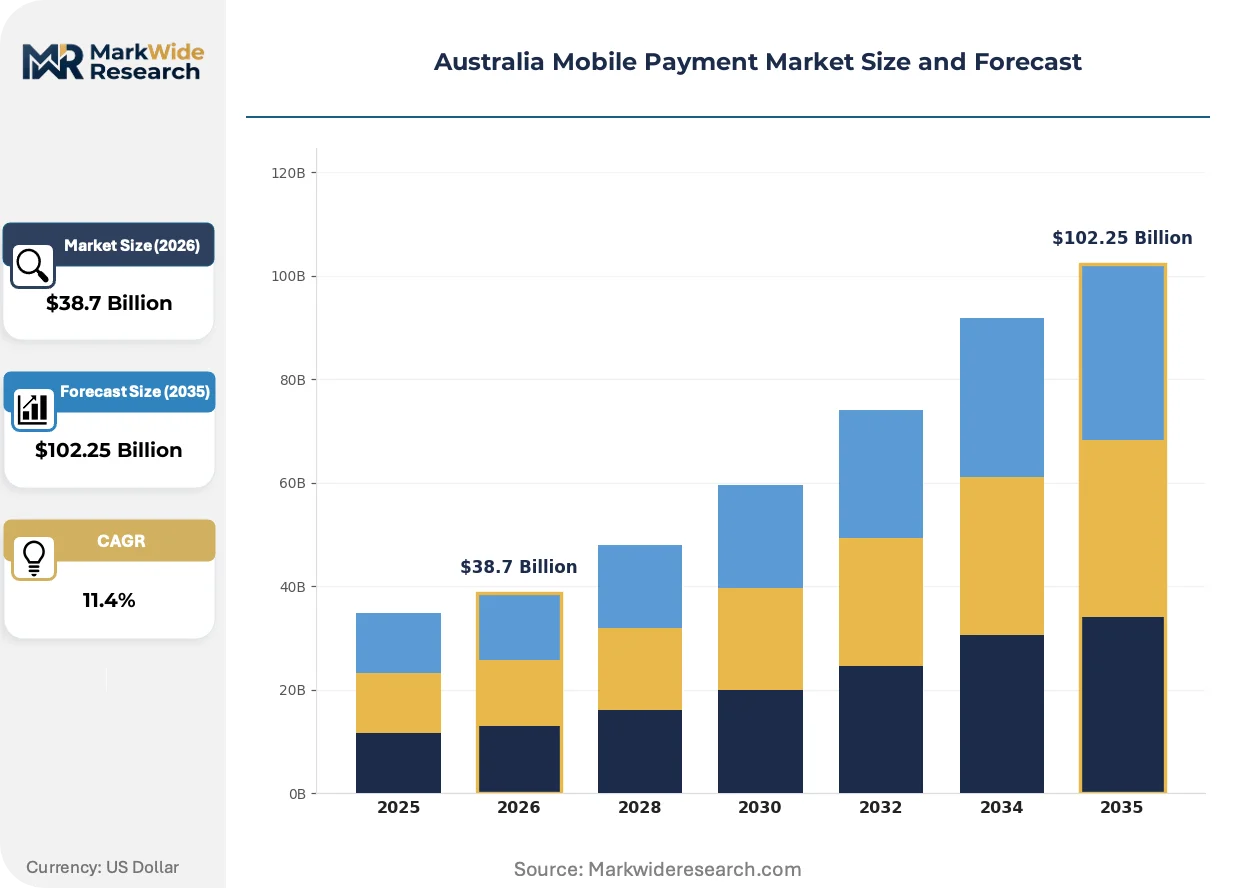
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallets, Bank Transfers End User Type: Consumers, Retailers, Merchants, Financial Institutions Technology: NFC, QR Code, SMS, Contactless Service Model: Peer-to-Peer, Point-of-Sale, E-commerce, Subscription |
| Companies Covered | Apple Inc., Google LLC, PayPal Holdings, Inc., Commonwealth Bank of Australia, Afterpay Limited, Zip Co Limited, Australia and New Zealand Banking Group Limited, National Australia Bank Limited, Samsung Electronics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Mobile Payment Market Emerging Trajectories
Real-time payment rails and credential consolidation are compressing transaction friction to near-zero thresholds, while regulatory mandates dismantle data monopolies that previously protected incumbent positions.
Host card emulation technology is unifying physical and digital credential storage into single-device architectures. Major banks are deploying software-based token vaults that eliminate dedicated secure-element chips, reducing per-device manufacturing costs by removing hardware dependencies. This convergence is compressing the premium-tier smartphone feature set into mid-market price bands, expanding addressable consumer base for tap-to-pay functionality.
The Consumer Data Right administered by the Office of the Australian Information Commissioner mandates transactional data portability between authorized deposit-taking institutions. Financial services providers must now engineer consent-management frameworks that expose historical payment patterns to competing wallet applications. Retail banking divisions are responding by accelerating loyalty-program integration to retain customer engagement despite data mobility.
Social payment use cases are displacing traditional bill-splitting applications among younger demographic cohorts. Messaging platforms and social networks are embedding peer-to-peer transfer functionality directly into conversation threads, bypassing standalone banking applications for casual fund exchanges. New South Wales and Victoria urban centers exhibit the highest concentration of this behavior, with weekend hospitality spending driving volume spikes.
Australia Mobile Payment Market Segmentation
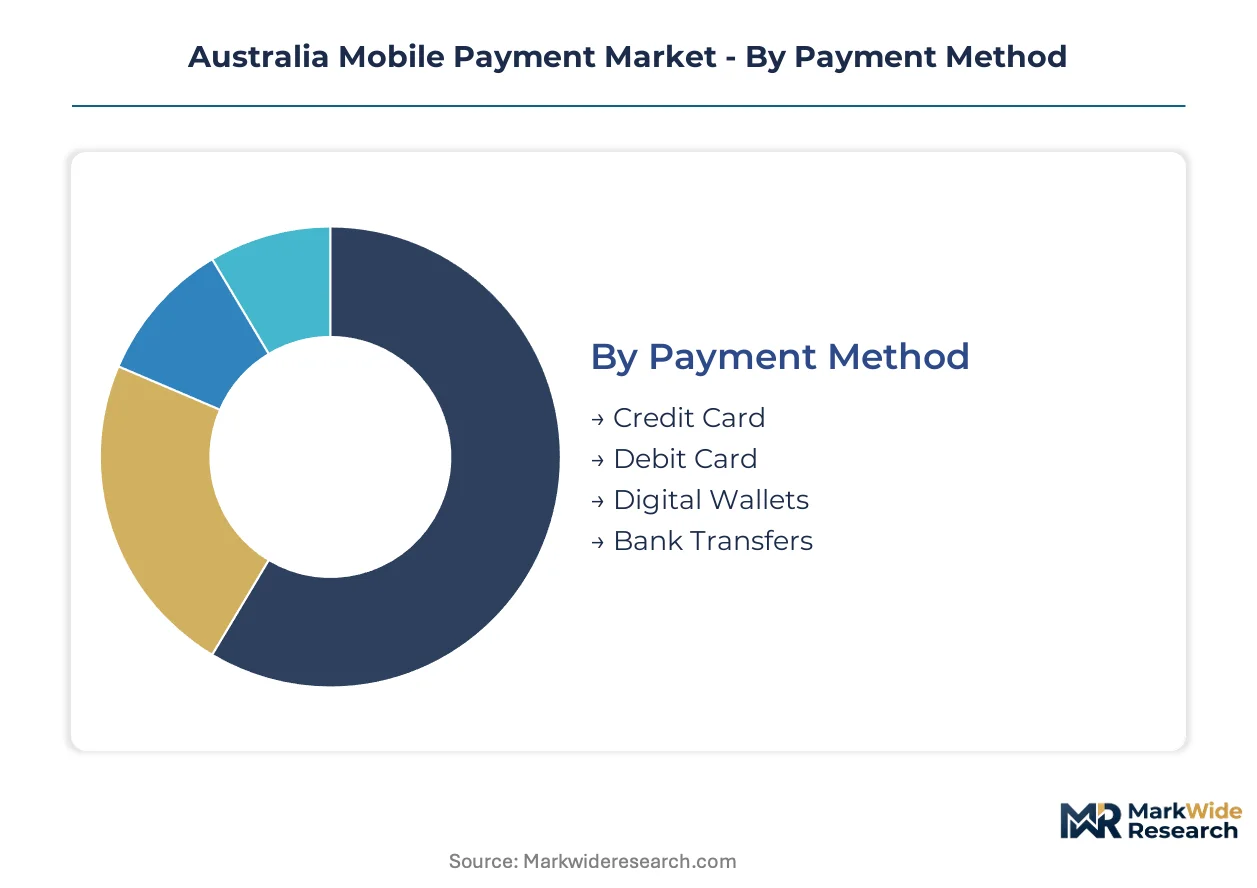
Payment infrastructure replacement cycles in Australia are fragmenting along technology, user, and service dimensions. Understanding these fault lines reveals where merchant upgrade budgets and consumer credential consolidation are concentrating.
Payment Method:
Merchant terminal replacement schedules are accelerating as legacy hardware reaches end-of-life and software-based alternatives reduce capital requirements.
- Credit Card:Tokenized credential storage enables tap-to-pay without physical card presentation. Demand concentrates in hospitality venues across New South Wales and Victoria, where higher average transaction values justify interchange fee absorption.
- Debit Card:Direct linkage to deposit accounts eliminates credit risk for merchants. Small retailers in metropolitan Sydney and Melbourne favor this method for lower processing costs, though per-transaction limits constrain high-value purchases.
- Digital Wallets:Credential consolidation into smartphone architectures reduces checkout friction. The Consumer Data Right regime is forcing interoperability between competing wallet ecosystems.
- Bank Transfers:Real-time settlement via the New Payments Platform eliminates card network fees. B2B merchants and subscription services leverage this for recurring payment optimization.
Digital wallets sit at the top of the volume ranking, with bank transfers climbing the fastest as merchants seek interchange avoidance.
End User Type:
Cost tier differentiation separates enterprise-grade solutions from smartphone-based entry points serving micro-merchants.
- Consumers:Urban demographics in Sydney and Melbourne drive credential consolidation into single-device architectures. The Reserve Bank of Australia's interchange regulations indirectly shape consumer choice through merchant acceptance patterns.
- Retailers:Mid-market chains require integrated inventory-payment systems. Queensland and Western Australia expansion depends on 4G/5G coverage reliability for terminal connectivity.
- Merchants:Cafes and restaurants replace dedicated terminals with smartphone-based checkout to reduce queue times. Hardware depreciation cycles of 5-7 years slow migration despite total-cost advantages.
- Financial Institutions:Deposit-taking institutions engineer consent-management frameworks for data portability compliance. Loyalty program integration retains engagement despite Consumer Data Right mandates.
Consumers dominate transaction volume, with merchants expanding most quickly as terminal replacement accelerates.
Technology:
Application-specific deployment separates high-frequency retail environments from low-infrastructure event commerce.
- NFC:Near-field communication protocols enable sub-second transaction completion. Supermarket chains and transit operators in capital cities mandate this for throughput optimization.
- QR Code:Optical scanning eliminates dedicated terminal hardware requirements. Pop-up retail and event commerce in Hobart and Launceston adopt this for low-friction onboarding.
- SMS:Text-based authorization extends payment access to feature phone users. Regional Queensland connectivity gaps limit reliability outside metropolitan zones.
- Contactless:Host card emulation unifies physical and digital credential storage. Software-based token vaults reduce per-device manufacturing costs for mid-market smartphone tiers.
NFC sits at the top of the volume ranking, with QR code adoption gaining share fastest among merchant categories seeking hardware minimization.
Service Model:
Customer type stratification separates social payment use cases from commercial settlement workflows.
- Peer-to-Peer:Messaging platform integration displaces standalone banking applications. Younger demographics in New South Wales and Victoria urban centers drive weekend hospitality spending spikes.
- Point-of-Sale:Integrated checkout systems link payment acceptance to inventory management. Commonwealth Bank of Australia's merchant network sustains dominance in this segment.
- E-commerce:Embedded checkout experiences reduce cart abandonment. Afterpay Limited differentiates through buy-now-pay-later integration.
- Subscription:Recurring authorization frameworks optimize for retention. Superannuation fund platforms explore embedded credentials for contribution automation.
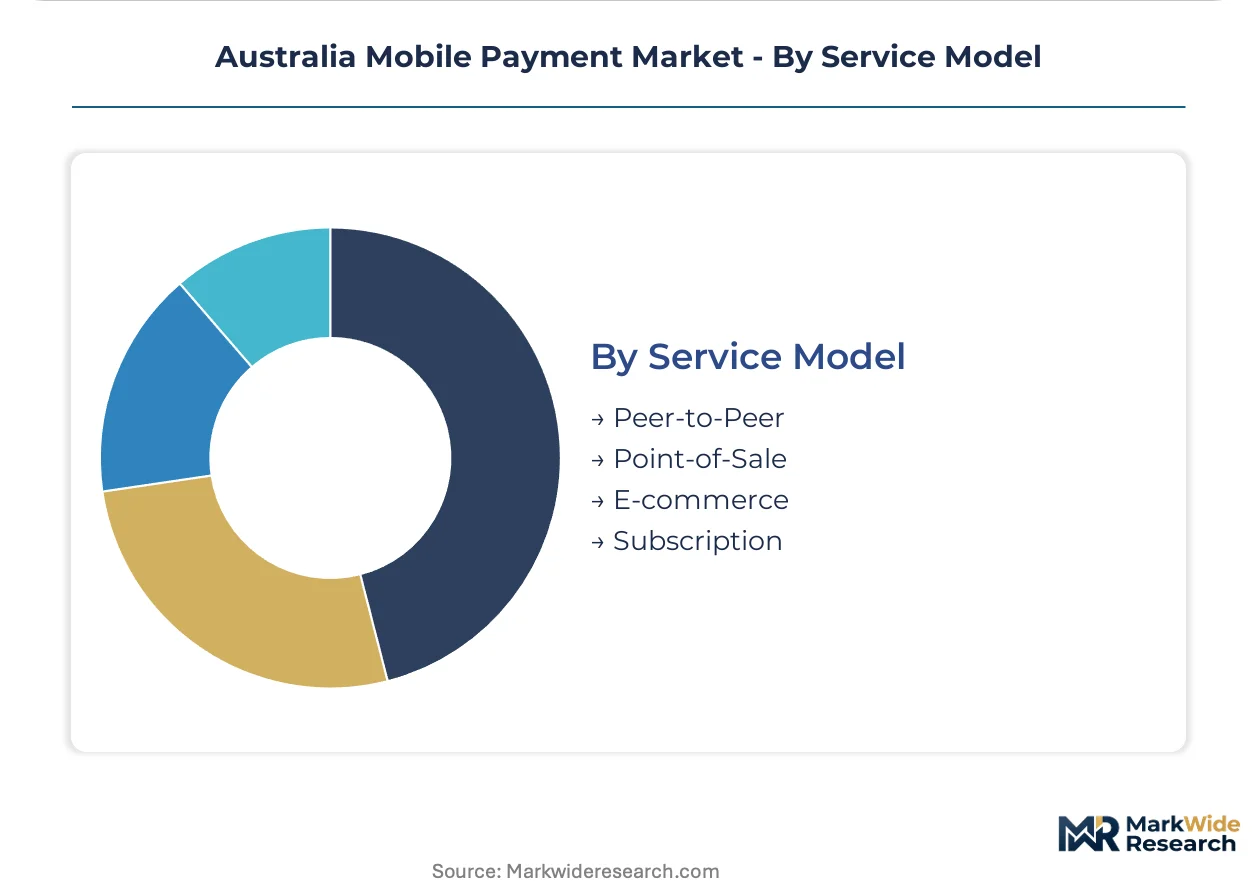
Point-of-Sale commands the volume ranking, with peer-to-peer services climbing fastest as social payment behavior displaces traditional bill-splitting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fintech investment flows as the Reserve Bank of Australia's interchange fee compression pushes payment processors toward higher-margin adjacent services. The Consumer Data Right regime creates compliance cost differentials between incumbent banks and neobank entrants, accelerating geographic specialization within the national market.
New South Wales
Sydney's dense hospitality cluster drives smartphone-based checkout adoption among cafes and restaurants. The Australian Prudential Regulation Authority's operational risk requirements shape deposit-taking institution behavior across the state. Fintech development concentrates in the Sydney CBD and Parramatta corridor, where merchant density supports real-time payment rail utilization.
Victoria
Melbourne's retail ecosystem generates elevated digital wallet transaction volumes relative to national averages. The Office of the Australian Information Commissioner enforces Consumer Data Right consent frameworks that intensify competition among financial services providers. Inner-urban merchant categories in Fitzroy and Richmond lead terminal replacement cycles, displacing legacy hardware with software-based point-of-sale systems.
Queensland
Regional connectivity gaps constrain NFC reliability outside Brisbane and Gold Coast metropolitan zones. The Australian Competition and Consumer Commission monitors payment system access rules affecting non-bank wallet providers. Tourism-dependent merchants in Cairns and the Sunshine Coast adopt QR-code checkout to minimize hardware investment for seasonal demand fluctuations.
Western Australia
Perth's mining sector payroll patterns create concentrated demand for peer-to-peer transfer functionality. The Reserve Bank of Australia's real-time settlement infrastructure standards govern transaction finality across the state's dispersed population centers. Merchant digitization lags national benchmarks in Kalgoorlie and regional mining towns, presenting infrastructure investment requirements.
South Australia
Adelaide's small-business density supports smartphone-based point-of-sale migration among independent retailers. The Australian Prudential Regulation Authority shapes licensed institution requirements for mobile wallet offerings. Sub-40 percent digital wallet acceptance in suburban merchant categories indicates first-mover expansion potential for low-friction onboarding solutions.
Australia Mobile Payment Market Vendor Landscape
Strategic partnerships dominate the current landscape as technology platforms and deposit-taking institutions negotiate data-sharing arrangements under Consumer Data Right mandates. The market exhibits tiered concentration with global technology conglomerates controlling consumer-facing wallet interfaces, domestic banks retaining merchant relationship dominance, and specialized buy-now-pay-later providers occupying embedded checkout niches. Three archetypes define competitive positioning: integrated banking-technology hybrids, standalone fintech specialists, and hardware-software convergence plays. M&A activity and API standardization efforts constitute the primary competitive vectors as firms seek to reduce integration maintenance burdens.
Among global technology platforms, Apple Inc. and Google LLC exemplify the consumer-interface archetype through device-embedded wallet architectures. Commonwealth Bank of Australia anchors the integrated banking-technology tier, leveraging extensive merchant networks for point-of-sale solution distribution. Afterpay Limited occupies the embedded finance specialist position, representing buy-now-pay-later integration models that reduce cart abandonment through deferred payment structures.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| PayPal Holdings, Inc. |
| Commonwealth Bank of Australia |
| Afterpay Limited |
| Zip Co Limited |
| Australia and New Zealand Banking Group Limited |
| National Australia Bank Limited |
| Samsung Electronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Australian Prudential Regulation Authority's operational risk requirements for licensed deposit-taking institutions gate both qualified supply and premium-tier pricing access, as compliance investments filter hardware procurement decisions and service-tier qualification across the mobile payment ecosystem.
Pricing Analysis
Merchant service fee compression at the channel-margin layer squeezes processor revenue pools, with the Reserve Bank of Australia's interchange caps forcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on settlement speed tier and API integration depth, with real-time New Payments Platform settlement commanding premium positioning. Cost compression in the mid-market tier is intensifying because neobank entrants undercut legacy processor rates. Small hospitality merchants in Hobart and Launceston exhibit highest price sensitivity, while enterprise retail chains prioritize throughput reliability over per-transaction economics.
Supply Chain Analysis
Domestic-content mandates under the Consumer Data Right regime are reshaping sourcing, requiring local data residency and consent-management infrastructure deployment. Hardware supply concentrates in China, Taiwan, and South Korea for NFC chipsets and secure-element components. Raw material dependencies span semiconductor wafers, lithium-ion battery cells for portable terminals, and optical-grade polymers for QR scanning modules. Single-source vulnerability in Taiwan semiconductor fabrication creates chokepoint exposure for tokenization hardware. Distribution runs through Commonwealth Bank of Australia's merchant network and independent payment service provider channels to terminal endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia mobile payment market functions as a geographic-arbitrage play, with Tasmania's sub-40 percent digital wallet penetration offering expansion runway absent the saturation pressures compressing margins in Sydney and Melbourne.
For Market Incumbents: Lock in merchant relationship durability through embedded inventory-payment integration and accelerate loyalty-program engineering to offset Consumer Data Right data portability threats. Commonwealth Bank of Australia's network density provides defensive moat material if leveraged for smartphone-based point-of-sale solution preloading. Vertical integration into token vault software reduces per-device manufacturing cost exposure.
For New Entrants and Emerging Players: Capture QR-code onboarding demand among pop-up retail and event commerce operators in Hobart, Launceston, and Adelaide suburban corridors where terminal hardware depreciation cycles stall incumbent migration. Tasmania and South Australia merchant categories represent the most penetrable geography. Go-to-market positioning should emphasize zero-hardware deployment with New Payments Platform real-time settlement as the anchor capability.
For Investors and Strategic Acquirers: Roll-up economics work for API standardization specialists because inconsistent open banking endpoint implementations across major banks force wallet developers to maintain multiple integration codebases, creating consolidation value in unified middleware platforms. Long-term viability favors firms with consent-management framework deployment and superannuation fund integration pipelines. Watch open banking API maturity as the inflection signal determining authentication standard winners.
| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Platform | Unifies integration codebases across ANZ, NAB, and CBA endpoint variations. |
| QR-to-NFC Hybrid Deployment | Reduces hardware barriers for Queensland tourism merchants in Cairns. |
| Superannuation Fund Integration | Opens embedded credential channels for retirement platform bill-pay automation. |
| Tasmanian Merchant Acquisition | Captures first-mover expansion in sub-40 percent penetration corridors. |
| Consent-Management Framework | Retains customer engagement despite Consumer Data Right portability mandates. |
Methodological Framework
Multiple input streams — primary interviews with payment platform engineers, merchant operations directors, and regulatory compliance officers at licensed deposit-taking institutions, alongside secondary validation through Reserve Bank of Australia interchange filings, ACCC payment system access determinations, and Office of the Australian Information Commissioner Consumer Data Right guidance documents — were reconciled through bottom-up transaction volume modeling and top-down market sizing triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning payment method, end user type, technology protocol, and service model. CAGRs were derived from fitted growth curves against historical adoption patterns and infrastructure deployment timelines. Forecast inputs incorporated New Payments Platform transaction volume trajectories and open banking API endpoint proliferation rates.
Regulatory enforcement variance, infrastructure deployment delays, and merchant terminal replacement cycle extension are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding Consumer Data Right compliance timelines and 4G/5G coverage expansion in regional Queensland and Northern Territory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Latin America Retail Cash Management Market
Payments
United States Electronic Toll Collection Market
Payments
Gift Card and Incentive Card Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
South Africa Real Time Payments Market
Payments
Payment Instruments Market
Payments
Global Gift Card Market
Payments
Instant Payments Market
Payments
Egypt Mobile Payments Market
Payments
Cloud Billing Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
Middle East and Africa Payments Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Digital Money Transfer Market
Payments
Electronic Payment Processing Software Market
Payments
Saudi Arabia Cash Management Services Market