
 United Arab Emirates Payment Market | 2026-2036
United Arab Emirates Payment Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Payment Market Analytics
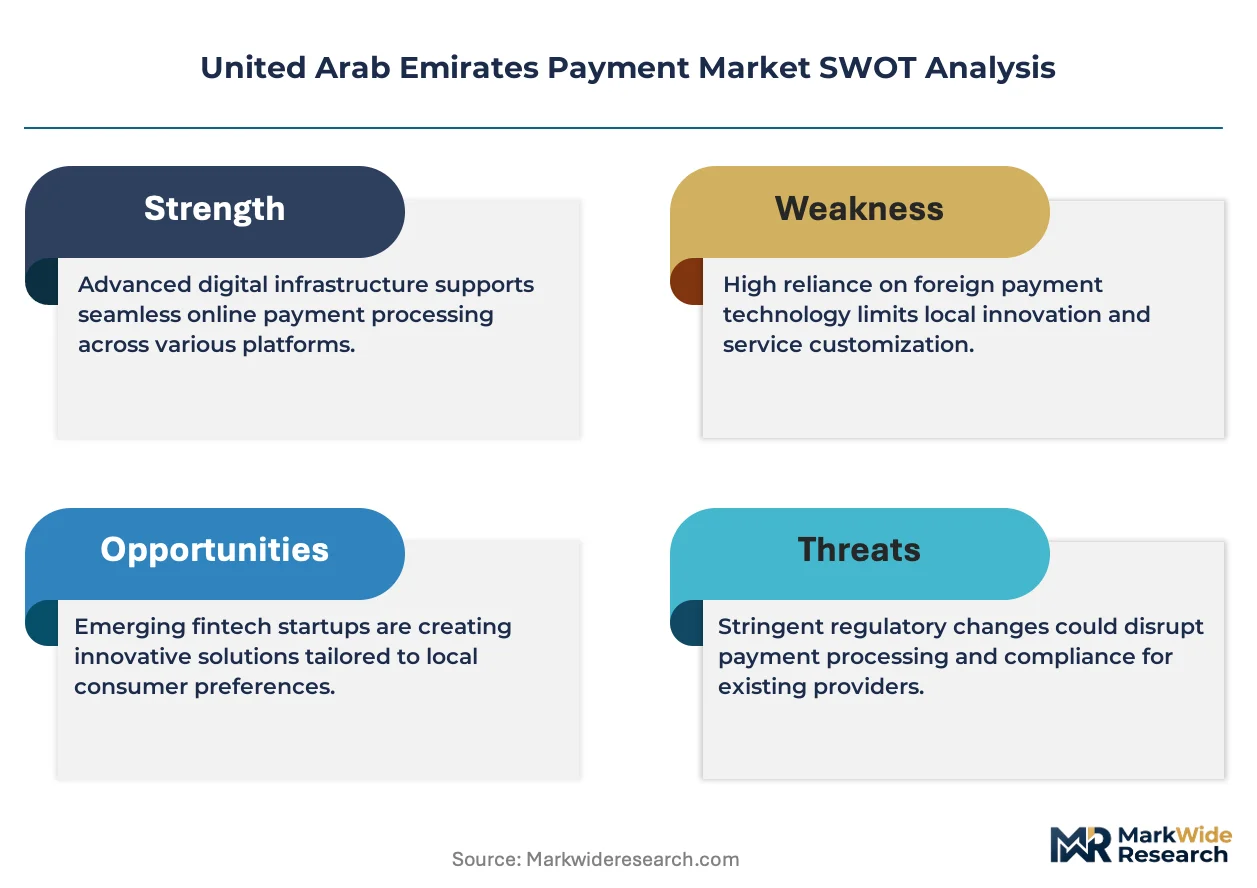
Asset-light platform licensing is reconfiguring competitive entry in the UAE payment ecosystem. Checkout.com leverages its regional licensing to anchor cross-border merchant processing across Gulf markets. Telr sustains its SME-focused gateway specialization with localized Arabic-language checkout tools. Network International dominates merchant acquiring through its banking partnerships with Emirates NBD Bank and First Abu Dhabi Bank.
Payment systems in the United Arab Emirates encompass digital fund transfer infrastructures, card networks, and mobile wallet platforms that authenticate, clear, and settle transactions in dirham and multicurrency formats. These systems rely on ISO 20022 messaging standards, tokenization protocols, and real-time gross settlement links to the UAE Central Bank to enable retail, corporate, and government disbursements. E-wallet and contactless transaction types are capturing the fastest growth as NFC penetration at UAE point-of-sale terminals exceeds legacy mag-stripe reliance. Credit card payment methods retain the largest value pool among consumer segments, though Gen Z and millennial users are shifting volume toward peer-to-peer and subscription service types.
The UAE Central Bank governs payment service provider licensing and capital adequacy, while SAMA-aligned open banking standards and the country's anti-money laundering framework shape product architecture and customer onboarding rigor. Compliance with these requirements determines market access for domestic fintechs and foreign platform operators. Stakeholders must monitor regulatory sandbox expansions and real-time payment scheme participation rules as competitive differentiation shifts toward settlement speed and interoperability.
Market Dynamics
The UAE Central Bank's real-time gross settlement infrastructure and open banking mandates are compressing settlement windows and forcing legacy payment processors to re-architect their core systems around ISO 20022 messaging standards.
Growth Catalysts
- Real-time payment rails:The UAE Central Bank's Instant Payment Platform mandates same-dirham settlement for retail transactions, eliminating float-based revenue models and forcing infrastructure upgrades across merchant acquirers.
- E-commerce merchant onboarding:Dubai's fintech corridor attracts cross-border sellers seeking multicurrency checkout capabilities, concentrating gateway demand in the emirate's free zones.
- NFC terminal penetration:Contactless point-of-sale hardware deployment exceeds mag-stripe reliance, enabling tap-to-pay adoption across retail and hospitality verticals.
Market Restraints
- Capital adequacy requirements:The UAE Central Bank mandates minimum paid-up capital thresholds for payment service providers, creating barriers for fintech entrants without banking consortium backing.
- Concentrated banking partnerships:Merchant acquiring relationships cluster with Emirates NBD Bank and First Abu Dhabi Bank, limiting price competition and alternative routing options.
- Legacy core banking integration:ISO 20022 migration timelines vary across tier-one banks, fragmenting interoperability and delaying real-time settlement ubiquity.
Strategic Opportunities
- Abu Dhabi Global Market licensing:The financial free zone's regulatory sandbox permits controlled testing of blockchain-based settlement and tokenized deposits outside federal banking law constraints.
- Subscription economy tooling:Recurring billing infrastructure for SaaS and streaming platforms remains underdeveloped relative to one-time checkout solutions, creating white space for specialized providers.
- Cross-border remittance corridors:Real-time dirham settlement links to SAMA's Saudi payment infrastructure enable corridor-specific products for South Asian worker remittances.
Industry Challenges
- ISO 20022 talent scarcity:Message mapping and API development expertise concentrates with incumbent technology vendors, inflating implementation costs for domestic fintechs.
- Legacy gateway migration:Merchants operating on decade-old hosted payment pages face technical debt and downtime risk during infrastructure transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Payment Market |
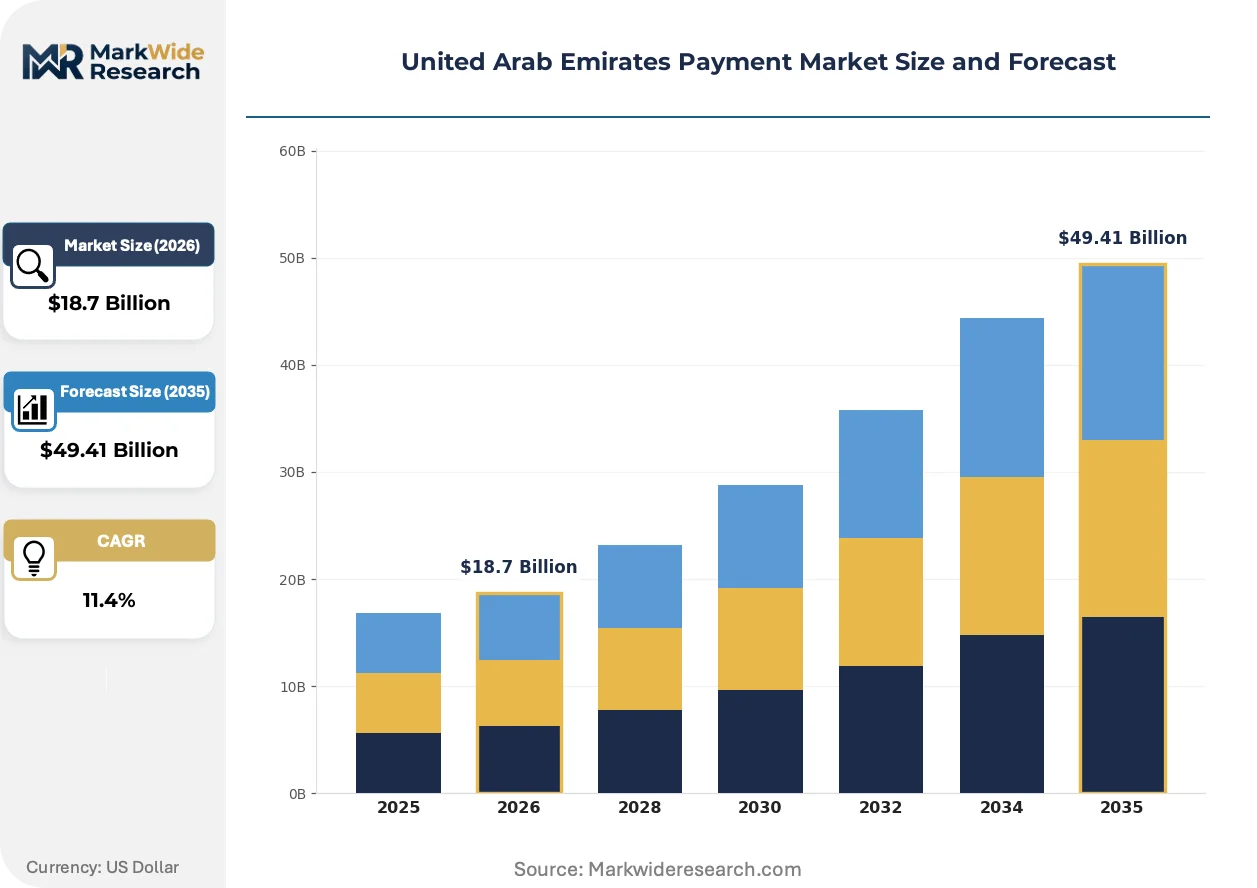
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, E-Wallet, Cash Transaction Type: Online, In-Store, Mobile, Contactless Consumer Segment: Millennials, Gen Z, Small Businesses, Corporates Service Type: Remittance, Bill Payment, Peer-to-Peer, Subscription |
| Companies Covered | Stripe, Checkout.com, PayTabs, Emirates NBD Bank, First Abu Dhabi Bank, Amazon Payment Services, Telr, Tabby, Network International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Payment Market Evolving Landscape
Tokenization protocols and embedded finance architectures are dismantling traditional merchant-processor relationships across the Emirates, compressing the value chain and redistributing margin pools toward software platforms.
Host card emulation technology is rendering obsolete dedicated point-of-sale terminals for micro-merchants. Food delivery aggregators and ride-hailing platforms in Dubai are adopting smartphone-based acceptance, eliminating hardware procurement cycles. This shift compresses merchant onboarding from weeks to hours and collapses the addressable market for traditional terminal manufacturers.
The UAE Central Bank's open banking framework mandates standardized API access to customer transaction data, compelling banks to expose core systems to licensed third parties. Retail payment apps are integrating account aggregation and personal finance management tools. Fintechs in Abu Dhabi's financial free zone are leveraging this data portability to pre-qualify credit products at checkout.
Buy-now-pay-later options are displacing traditional credit card installments at UAE e-commerce checkouts. Younger consumers in Dubai's retail corridors prefer split-payment interfaces over revolving credit lines. Merchants in fashion and electronics verticals report higher conversion rates when embedding these alternatives directly into native checkout flows rather than redirecting to external lenders.
United Arab Emirates Payment Market Segmentation
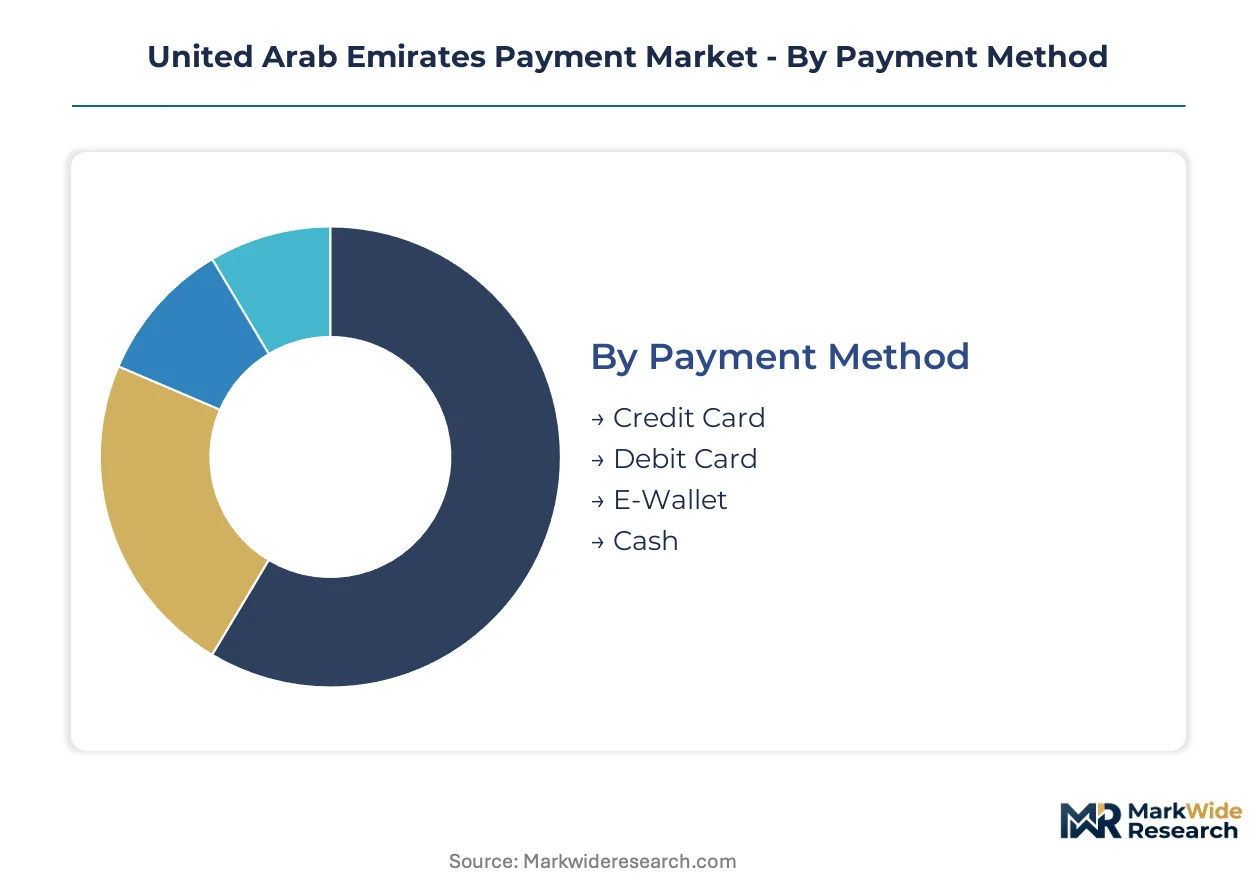
Payment method fragmentation across the Emirates demands granular segmentation to capture divergent infrastructure requirements. Transaction type and consumer demographics determine settlement speed mandates and compliance architecture for providers operating under UAE Central Bank supervision.
Payment Method:
Cost tier differentiation separates high-interchange card products from low-friction digital alternatives in merchant pricing strategies.
- Credit Card:Revolving credit instruments carrying interchange fees of 1.5-2.5% on dirham-denominated transactions. Corporate travel and luxury retail in Dubai Mall corridors sustain premium authorization volumes despite merchant cost burden.
- E-Wallet:Tokenized stored-value accounts enabling QR-code and NFC-triggered debits without physical card presence. Dubai's food delivery aggregators and ride-hailing platforms are migrating settlement preference toward Apple Pay and Samsung Pay to compress checkout abandonment.
- Debit Card:Direct-linked checking instruments with lower interchange structures. Salary disbursement corridors through Emirates NBD and First Abu Dhabi Bank anchor retail penetration.
- Cash:Physical dirham notes and coins requiring armored logistics and vault infrastructure. Remittance-heavy corridors in Deira and Al Aweer retain residual dependence despite Central Bank digitization mandates.
Credit Card commands the established base. The steepest expansion runs through E-Wallet.
Transaction Type:
Application context determines authentication rigor and settlement window requirements across merchant verticals.
- Contactless:NFC-enabled tap-to-pay protocols completing authentication in under 500 milliseconds. UAE point-of-sale terminal penetration now exceeds legacy mag-stripe deployment in Dubai's hospitality sector.
- Mobile:Smartphone-native transactions leveraging host card emulation and biometric verification. Abu Dhabi's retail free zones are mandating soft-POS acceptance for micro-merchants to eliminate hardware procurement barriers.
- Online:Card-not-present flows requiring 3D Secure authentication and tokenization protocols. Cross-border e-commerce merchants in Dubai Internet City concentrate gateway demand for multicurrency checkout.
- In-Store:Physical terminal-present transactions with chip-and-PIN fallback. Malls and hypermarkets across Sharjah and Ajman maintain hybrid acceptance infrastructure.
Contactless captures volume leadership in retail corridors. Mobile climbs the fastest as smartphone penetration saturates merchant acceptance tiers.
Consumer Segment:
Customer type dictates product packaging, credit underwriting, and channel preference across the Emirates.
- Corporates:Treasury-managed payment instruments with centralized reconciliation and spend-control features. Abu Dhabi sovereign wealth-adjacent entities drive demand for virtual card programs and API-embedded accounting integration.
- Gen Z:Digital-native cohorts aged 18-26 prioritizing split-payment interfaces and social commerce checkout. Dubai's fashion verticals report conversion lift from buy-now-pay-later embedding.
- Millennials:Salaried professionals aged 27-42 with established credit histories and subscription service density. Fitness and streaming platforms target this segment for recurring billing optimization.
- Small Businesses:Owner-operated merchants requiring working capital-linked acceptance tools. Telr and Network International compete on same-day settlement guarantees for this tier.
Corporates anchor transaction value. Gen Z gains share fastest through native-app commerce adoption.
Service Type:
Maturity stage separates legacy remittance infrastructure from emerging subscription billing platforms.
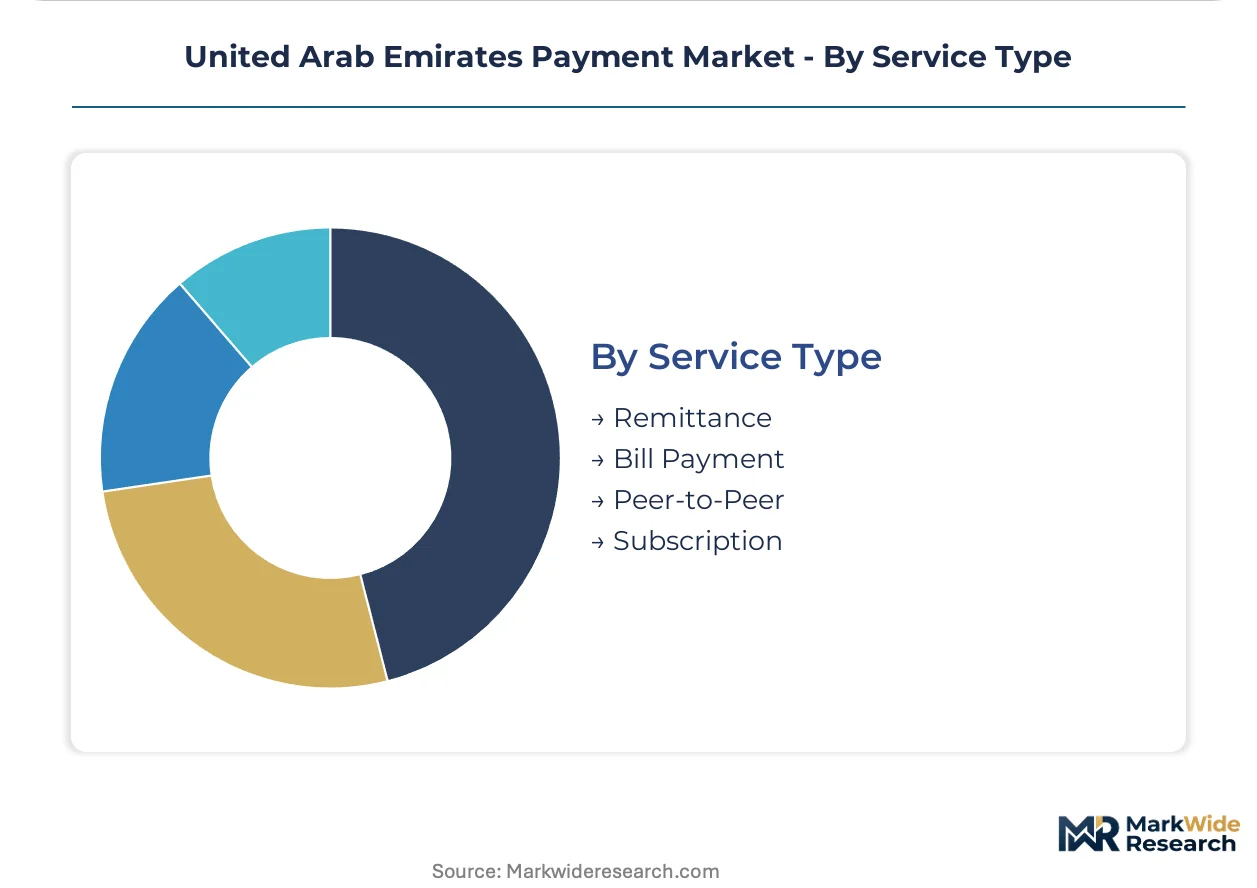
- Remittance:Cross-border worker payment corridors linking UAE dirham to South Asian currencies. Exchange houses in Deira and Bur Dubai process volume through SAMA-interoperable rails.
- Subscription:Recurring authorization frameworks for SaaS and streaming platforms. UAE billing infrastructure remains underdeveloped versus one-time checkout solutions, creating white space for specialized providers.
- Peer-to-Peer:Individual-to-individual transfer protocols via mobile number or QR code. Emirates NBD's Liv. and FAB's Payit dominate retail person-to-person flows.
- Bill Payment:Utility and government disbursement aggregation through centralized portals. DEWA and Etisalat integrations anchor merchant biller networks.
Remittance retains the deepest infrastructure. Subscription exhibits the steepest trajectory as SaaS penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border merchants and sovereign wealth-adjacent corporates anchor payment demand across the Emirates. Dubai's fintech corridor concentrates gateway providers serving Gulf-wide e-commerce. Abu Dhabi's financial free zones host licensed payment institutions targeting institutional treasury flows.
Dubai
E-commerce aggregators and food delivery platforms drive merchant acquiring demand. The Dubai International Financial Centre's regulatory sandbox permits payment innovation testing outside federal banking constraints. Dubai Internet City clusters cross-border sellers seeking multicurrency checkout capabilities.
Abu Dhabi
Sovereign wealth funds and government entities anchor corporate payment volumes. The Abu Dhabi Global Market licensing framework enables blockchain-based settlement pilots. Al Maryah Island concentrates fintechs building API-embedded treasury tools for institutional clients.
Sharjah
Traditional retail and hospitality sectors sustain in-store terminal deployment. The emirate's economic development department mandates contactless acceptance infrastructure upgrades. Sharjah's industrial zones anchor manufacturing-linked supplier payment corridors.
Northern Emirates
Worker remittance corridors through Ras Al Khaimah and Fujairah retain cash-to-digital transition potential. The UAE Central Bank's financial inclusion initiatives target underbanked populations in these emirates. Border-adjacent exchange houses process South Asian labor payment flows.
United Arab Emirates Payment Market Competitive Landscape
Channel-controlling players compete with product-specialist players for merchant relationships across the Emirates. Banking consortium-backed acquirers dominate transaction volume through established correspondent networks. Three archetypes define competitive positioning: global platform operators with regional licensing, domestic gateway specialists with localized tooling, and bank-owned processors with captive deposit bases. Strategic moves center on sandbox licensing in financial free zones and API-based embedded finance partnerships.
Within the global platform tier, Stripe and Checkout.com anchor cross-border merchant processing with multicurrency capabilities. Among domestic specialists, Telr exemplifies SME-focused gateway provision with Arabic-language checkout optimization. Network International occupies a position bridging bank-owned scale with independent processor flexibility.
| Leading Market Players |
|---|
| Stripe |
| Checkout.com |
| PayTabs |
| Emirates NBD Bank |
| First Abu Dhabi Bank |
| Amazon Payment Services |
| Telr |
| Tabby |
| Network International |
| Others |
Value Network & Pricing Analysis
Jebel Ali Port's container throughput cost dynamics compress margins for payment hardware importers while amplifying price differentiation between bank-owned processors and independent gateway providers across the Emirates.
Pricing Analysis
Cost-plus contracts with UAE Central Bank indexation anchor merchant acquiring fee schedules. Three-tier pricing structure across premium, standard, and economy levels separates enterprise treasury clients from SME gateway users and micro-merchant soft-POS tiers. Price differentiation rests on settlement speed guarantees and ISO 20022 certification status. Cost compression in the independent processor tier is intensifying because Emirates NBD and First Abu Dhabi Bank leverage captive deposit bases to subsidize acquiring margins. Small businesses exhibit highest price sensitivity; sovereign wealth-adjacent corporates show least.
Supply Chain Analysis
US Commerce Department export controls on advanced chipsets constrain NFC terminal component flows into UAE assembly facilities. Hardware supply concentrates in China, Taiwan, and South Korea for secure element manufacturing. Raw material dependencies span semiconductor wafers, biometric sensors, and tamper-resistant enclosures. Single-source vulnerability runs through TSMC-fabricated payment processors. Distribution runs through Dubai's Jebel Ali free zone logistics clusters for Gulf-wide fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE payment market sits in early-cycle expansion as real-time dirham settlement infrastructure penetrates merchant tiers previously dependent on legacy float-based models.
For Market Incumbents: Entrench merchant relationships through API-embedded treasury tools and same-day settlement guarantees. Deepen vertical integration into tokenization protocol development to offset margin pressure from open banking disintermediation. Lock in exclusive ISO 20022 implementation partnerships with tier-one banks before sandbox entrants capture mid-market share.
For New Entrants and Emerging Players: Establish a beachhead in Sharjah's industrial supplier payment corridors where contactless infrastructure remains underdeployed. Target Northern Emirates exchange houses for remittance corridor digitization. Pursue Abu Dhabi Global Market licensing to test blockchain settlement outside federal banking constraints.
For Investors and Strategic Acquirers: Payment infrastructure specialists with SAMA-interoperable remittance rails represent the priority acquisition archetype. Long-term viability hinges on regulatory sandbox participation rights and real-time payment scheme access. Watch for UAE Central Bank sandbox expansion announcements as inflection indicators for platform valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Payment Platform Integration | Same-dirham settlement mandates eliminate float revenue and force core system upgrades. |
| Abu Dhabi Global Market Licensing | Blockchain settlement pilots outside federal constraints attract institutional treasury flows. |
| ISO 20022 Migration Partnerships | Message standardization with Emirates NBD and FAB secures interoperability advantages. |
| Cross-Border Remittance Corridor Development | SAMA-interoperable rails capture South Asian worker payment volumes through Deira exchange houses. |
| Embedded Finance API Expansion | Pre-qualified credit products at checkout leverage open banking data portability mandates. |
Research Methodology
The analysis maps payment method infrastructure, transaction type protocols, consumer segment tooling, and service type platforms, each validated through payment operations executives, regulatory compliance officers, merchant acquiring leads, and fintech product managers. Primary fieldwork combined structured interviews with secondary validation against UAE Central Bank circulars, SAMA interoperability frameworks, DIFC regulatory filings, and customs data on payment hardware imports. Bottom-up merchant tier sizing triangulated with top-down dirham transaction flow estimates.
Assumptions held fixed include UAE Central Bank open banking mandate timelines and SAMA real-time payment interoperability schedules; variables tested across the projection horizon encompass merchant onboarding velocity and NFC terminal replacement cycles. Segmentation dimensions modeled cover payment method, transaction type, consumer segment, and service type. CAGRs derived from installed base growth rates and average revenue per merchant trajectories. Forecast inputs incorporated e-commerce merchant density in Dubai Internet City and sovereign wealth fund payment automation mandates.
Macroeconomic conditions sit as an overlay; deviation in oil revenue flows, expatriate population shifts, or dirham-dollar peg stability would shift the trajectory. Forecasts reflect assumptions around regulatory sandbox participation thresholds and real-time payment scheme fee structures. Material shifts in UAE Central Bank capital adequacy requirements or SAMA corridor interoperability terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Africa Real Time Payments Market
Payments
Spain Payments Market
Payments
Norway POS Terminals Market
Payments
UK Prepaid Cards Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Electronic Payment System for Transportation Market
Payments
Global Real-Time Payments Market
Payments
Global Mobile Payment Technology Market
Payments
Greece POS Terminals Market
Payments
Australia Payments Market
Payments
Finland POS Terminals Market
Payments
US Buy Now Pay Later Services Market
Payments
Mobile Payment Security Market
Payments
Argentina Payments Market
Payments
LAMEA Payment Gateway Market
Payments
India Buy Now Pay Later Services Market