
 Asia-Pacific Cloud DLP Market | 2026-2036
Asia-Pacific Cloud DLP Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cloud DLP Market Analytics
Cybersecurity talent scarcity is bifurcating the Asia-Pacific Cloud DLP landscape into enterprise self-managed deployments and vendor-delivered managed services. Microsoft Corporation leverages its native cloud ecosystem to anchor DLP functionality within broader security suites across Azure deployments. Trend Micro, Inc. competes through specialized endpoint-to-cloud data protection architectures optimized for hybrid Japanese and Australian enterprise environments.
Asia-Pacific Cloud DLP encompasses policy-driven technologies that inspect, classify, and block unauthorized exfiltration of structured and unstructured data across SaaS, IaaS, and PaaS environments, utilizing machine learning classification engines and encryption gateways to enforce data residency and confidentiality obligations. Public Cloud deployments dominate current revenue as organizations prioritize scalable API-native inspection for Office 365 and Salesforce workloads, while Hybrid Cloud configurations represent the fastest-growing structural segment as regulated industries seek unified policy enforcement across on-premises and cloud repositories. Managed Services capture expanding margin pools as skills gaps push mid-market buyers toward fully operated DLP programs.
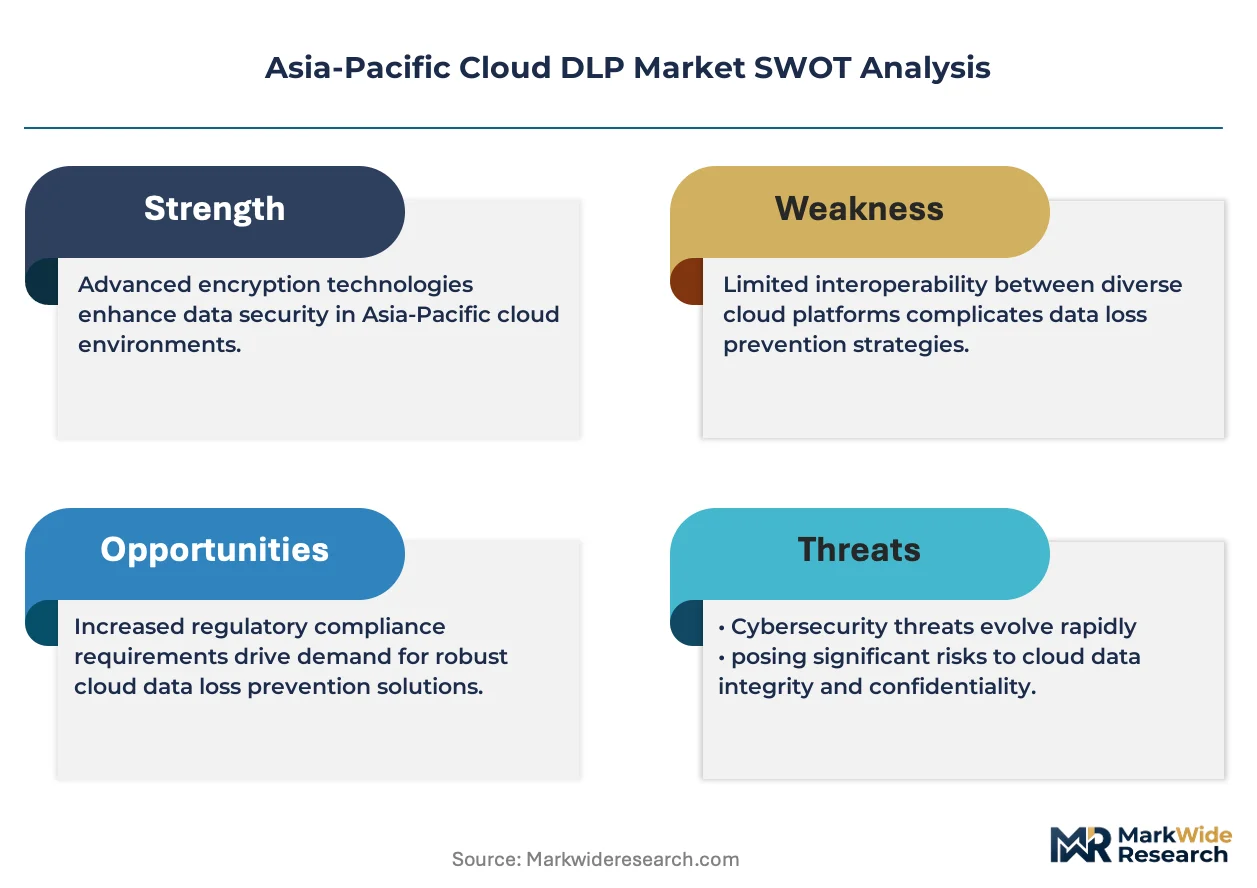
India's Digital Personal Data Protection Act and Australia's Privacy Act, enforced by the Office of the Australian Information Commissioner, mandate demonstrable data handling controls that directly expand procurement budgets for automated discovery and incident response modules. Japan's Act on the Protection of Personal Information, administered by the Personal Information Protection Commission, similarly drives demand for cross-border data transfer monitoring capabilities. Stakeholders must evaluate vendor architectures for seamless integration with emerging sovereign cloud requirements before committing to long-term platform contracts.
Market Dynamics
Machine learning classification engines are compressing detection latency for unstructured data inspection, forcing incumbent vendors to rearchitect API-native inspection pipelines or cede mid-market accounts to specialized entrants.
Growth Catalysts
- India's Digital Personal Data Protection Act:The law mandates automated data handling controls that expand procurement budgets for discovery and incident response modules across banking and insurance verticals.
- Financial services cloud migration:Southeast Asian banks moving core systems to public cloud environments generate concentrated demand for API-native DLP inspection of Office 365 and Salesforce workloads.
- Hybrid cloud architectures:Regulated enterprises in Australia and Japan seek unified policy enforcement across on-premises and cloud repositories, accelerating procurement of cross-environment DLP platforms.
Market Restraints
- Certified security architect scarcity:Skills gaps in cloud-native DLP deployment and tuning inflate implementation timelines and force reliance on vendor professional services.
- Sovereign cloud fragmentation:Divergent data residency requirements across Australia, India, Japan, and Singapore complicate single-platform standardization for multinational enterprises.
- Encryption gateway interoperability:Legacy on-premises encryption hardware lacks native API integration with SaaS inspection engines, requiring costly middleware development.
Strategic Opportunities
- Indonesia's underpenetrated mid-market:Local banks and telcos with nascent cloud adoption represent greenfield accounts for managed DLP services delivered through regional system integrators.
- Cross-border data transfer monitoring:Japan's Act on the Protection of Personal Information creates specialized demand for tools tracking data flows to non-adequacy jurisdictions.
- Convergence of DLP with zero-trust architectures:Integration of data classification with identity-aware proxies enables unified policy enforcement across IaaS and PaaS environments.
Industry Challenges
- Cloud security engineer shortage:The gap between trained practitioners and deployment demand stretches vendor implementation teams and delays customer go-live dates.
- Multi-cloud policy synchronization:Enterprises operating across Azure, AWS, and Alibaba Cloud struggle to maintain consistent DLP rules without vendor-agnostic orchestration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cloud DLP Market |
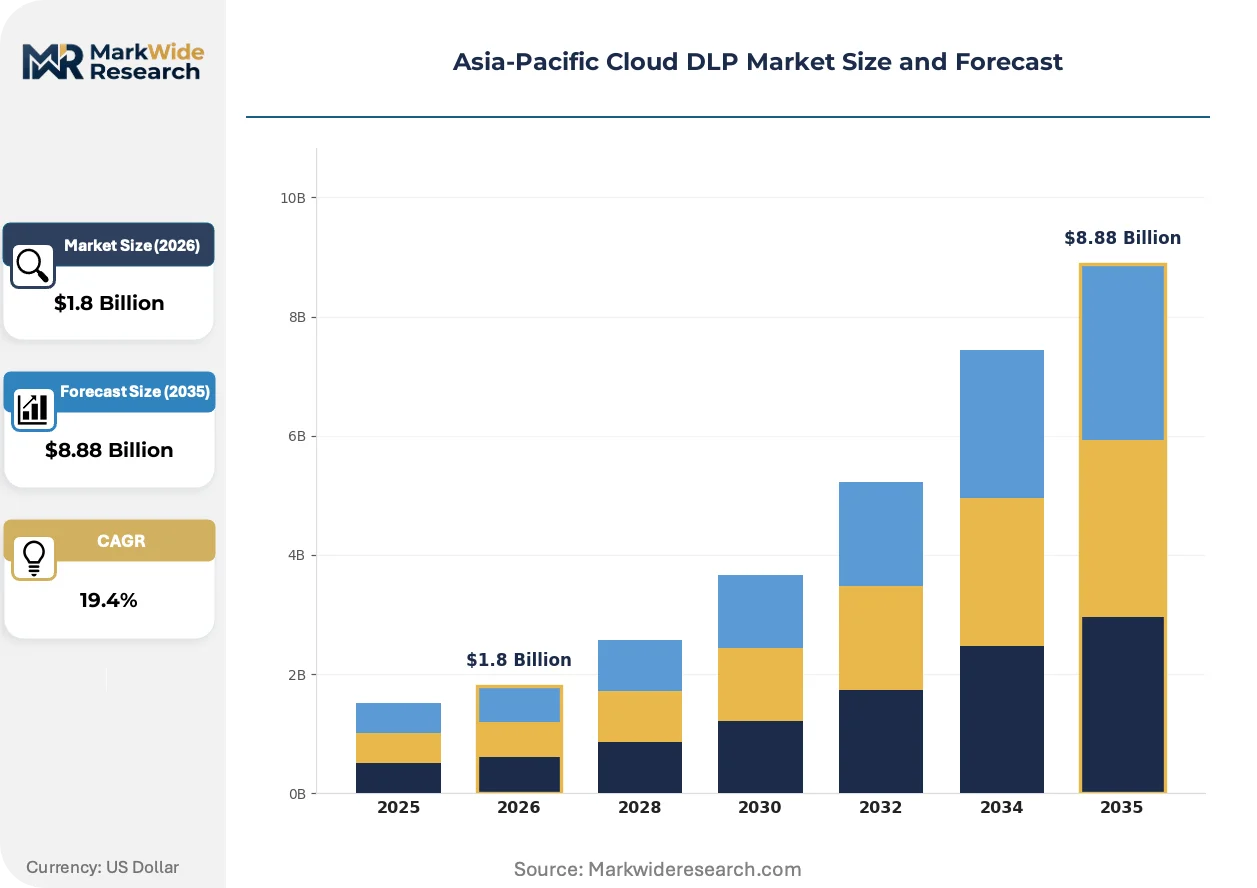
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Managed Services, Professional Services, Consulting, Support Services End User: Healthcare, Education, BFSI, Government Solution: Data Discovery, Data Monitoring, Incident Response, Compliance Management |
| Companies Covered | Broadcom, Inc., IBM Corporation, Microsoft Corporation, Trend Micro, Inc., McAfee Corp, Palo Alto Networks, Inc., GTB Technologies, Inc., Infowatch, Cisco Systems, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cloud DLP Market Evolving Landscape
Behavioral analytics engines are displacing static regex-based classification, enabling real-time risk scoring that adapts to user context and data sensitivity without predefined rule maintenance.
Natural language processing for data classification is bifurcating the vendor landscape into generalist platforms and specialized engines trained on regional language corpora. Japanese and Korean financial institutions prioritize vendors with native support for CJK character sets and local idiom recognition. This capability gap is compressing margins for Western entrants unable to demonstrate equivalent precision in Asia-Pacific linguistic contexts.
Australia's Privacy Act amendments, enforced by the Office of the Australian Information Commissioner, mandate breach notification timelines that compress incident response windows to 72 hours. Healthcare and government contractors are retrofitting automated discovery modules to meet these obligations. The regulatory pressure is accelerating replacement cycles for legacy DLP tools lacking real-time alerting pipelines.
Mid-market buyers in Singapore and Hong Kong are consolidating security procurement under managed detection and response providers that bundle DLP with broader cloud security posture management. This channel shift displaces direct enterprise sales motions and forces pure-play DLP vendors to develop MSSP-compatible pricing and API architectures. The trend concentrates margin capture with regional system integrators possessing established customer relationships.
Asia-Pacific Cloud DLP Market Segmentation
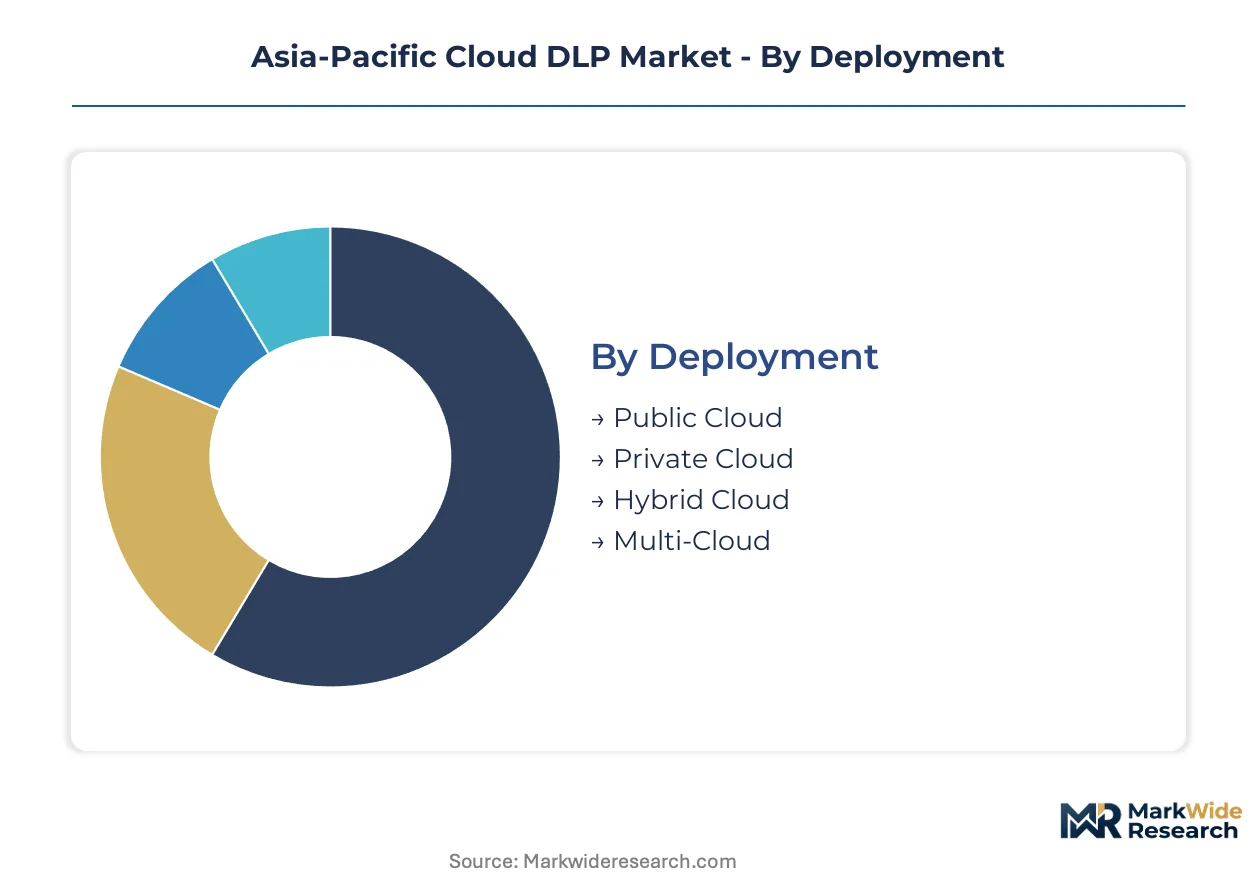
Cloud DLP procurement patterns across Asia-Pacific diverge sharply by deployment architecture and regulatory exposure. Buyers select segment configurations based on data residency mandates, cloud maturity, and internal security engineering capacity.
Deployment:
Public Cloud dominates Australian and Japanese enterprise procurement, while Hybrid Cloud configurations concentrate in India and Southeast Asian banking sectors navigating sovereign data requirements.
- Public Cloud:API-native inspection engines scan SaaS workloads including Office 365 and Salesforce at scale. Australian financial institutions and Japanese manufacturers drive concentrated demand for turnkey deployments requiring minimal on-premises infrastructure.
- Hybrid Cloud:Unified policy enforcement bridges on-premises repositories with cloud-native applications. Indian banks under the Digital Personal Data Protection Act and Singaporean government contractors prioritize this architecture for cross-environment data lineage tracking.
- Private Cloud:Isolated infrastructure serves defense contractors and critical infrastructure operators in South Korea and Australia with air-gapped security requirements.
- Multi-Cloud:Orchestration layers synchronize DLP rules across Azure, AWS, and Alibaba Cloud deployments. Regional conglomerates with heterogeneous cloud estates adopt this segment despite higher integration complexity.
Public Cloud holds the largest share; momentum sits with Hybrid Cloud as regulated industries pursue unified governance frameworks.
Service Type:
Skills scarcity across Asia-Pacific elevates managed service models above self-managed alternatives, particularly in mid-market accounts lacking certified cloud security architects.
- Managed Services:Fully operated DLP programs include policy tuning, incident response, and compliance reporting delivered by regional system integrators. Indonesian banks and Vietnamese manufacturers lacking internal security operations centers drive fastest expansion in this segment.
- Professional Services:Implementation and architecture design engagements support complex hybrid and multi-cloud deployments. Australian enterprises with mature cloud footprints utilize these services for customization and legacy migration.
- Consulting:Advisory engagements map data flows and classify sensitive information repositories ahead of technical deployment. Japanese corporations preparing for APPI compliance audits represent concentrated demand.
- Support Services:Tiered technical assistance and maintenance contracts sustain operational continuity. Standard offering across all deployment scales with limited differentiation.
Managed Services capture the steepest expansion trajectory as skills gaps push buyers toward operated programs.
End User:
BFSI verticals generate disproportionate revenue concentration due to regulatory pressure and cloud migration timelines, while Healthcare lags in adoption despite stringent privacy mandates.
- BFSI:Banks and insurers migrating core systems to public cloud environments require real-time transaction monitoring and cross-border transfer controls. Southeast Asian institutions in Thailand, Malaysia, and the Philippines represent greenfield expansion opportunities.
- Government:National and state-level agencies deploy sovereign cloud configurations with encrypted gateways. Australian federal contractors and Indian public sector banks prioritize this segment under procurement frameworks mandating domestic data residency.
- Healthcare:Hospitals and pharmaceutical researchers implement discovery modules for patient records and clinical trial data. Adoption accelerates in Australia following Privacy Act amendments compressing breach notification windows.
- Education:Universities and research institutions protect intellectual property and student records. Smaller addressable market with price-sensitive procurement patterns.
BFSI holds the largest share; momentum sits with Government as sovereign cloud requirements harden across the region.
Solution:
Automation depth separates premium offerings from baseline capabilities, with machine learning classification engines commanding pricing premiums over static rule-based alternatives.
- Data Discovery:Automated scanning identifies structured and unstructured sensitive data across cloud repositories and on-premises archives. Australian healthcare providers retrofit these modules to meet 72-hour breach notification obligations under Privacy Act amendments.
- Incident Response:Automated quarantine, alerting, and forensic logging compress mean-time-to-containment. Japanese financial institutions prioritize this capability for APPI compliance and cross-border transfer documentation.
- Data Monitoring:Continuous inspection of data-in-motion across email, web, and API channels. Standard component integrated within broader platform offerings.
- Compliance Management:Pre-configured policy templates and audit reporting for regional regulations. Bundled feature rather than standalone purchase driver.
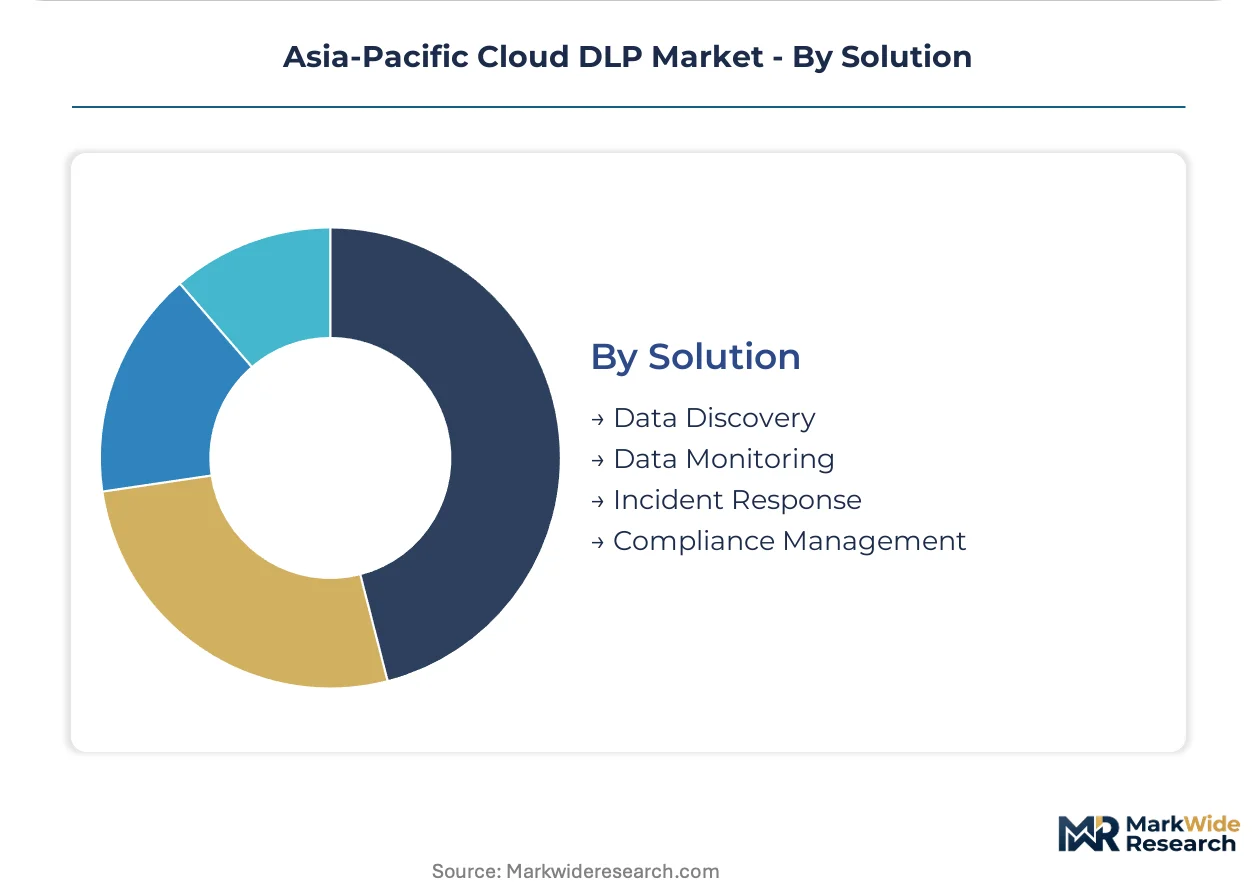
Data Discovery holds the largest share; momentum sits with Incident Response as regulatory enforcement tightens breach notification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Office of the Australian Information Commissioner enforces breach notification timelines that compress incident response windows across the region's most mature cloud security market. India's Digital Personal Data Protection Act and Japan's Act on the Protection of Personal Information create parallel compliance pressures that shape procurement patterns. Southeast Asian financial hubs add cloud migration momentum as banks modernize core systems.
Australia
Financial institutions and government contractors drive concentrated demand for API-native inspection engines. The Privacy Act amendments mandate 72-hour breach notification, forcing healthcare providers to retrofit automated discovery modules. Sydney and Melbourne host the region's densest clusters of managed security service providers delivering fully operated DLP programs.
India
Banks and insurers under the Digital Personal Data Protection Act expand procurement budgets for discovery and incident response capabilities. The Reserve Bank of India's cloud guidelines push regulated entities toward automated data handling controls. Mumbai and Bengaluru emerge as centers for hybrid cloud deployments bridging on-premises core banking systems with public cloud workloads.
Japan
The Personal Information Protection Commission administers strict cross-border data transfer rules that elevate demand for flow monitoring tools. Manufacturers and financial institutions prioritize vendors with native CJK character set recognition. Tokyo and Osaka anchor enterprise procurement for endpoint-to-cloud data protection architectures.
Singapore
Government contractors and regional headquarters of multinational banks seek unified policy enforcement across multi-cloud estates. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria. The city-state's system integrators capture expanding margin pools by bundling DLP with broader cloud security posture management offerings.
Indonesia
Local banks and telecommunications operators with nascent cloud adoption represent greenfield accounts for managed DLP services. The national data protection law, administered by the Ministry of Communication and Informatics, creates compliance obligations that outpace internal security engineering capacity. Jakarta's emerging fintech cluster drives initial procurement of SaaS inspection for Office 365 environments.
Asia-Pacific Cloud DLP Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Cloud DLP landscape. Native cloud platform vendors anchor integrated security suites, while specialized data protection vendors compete through endpoint-to-cloud architectures. The market structure fragments across three strategic archetypes: hyperscale platform providers, regional cybersecurity specialists, and managed security service orchestrators. Competitive moves concentrate on API-native inspection pipeline development and regional system integrator partnership expansion.
Among hyperscale platform providers, Microsoft Corporation exemplifies the integrated-suite archetype by embedding DLP functionality within broader cloud security offerings. Trend Micro, Inc. occupies a specialist position optimized for hybrid enterprise environments across Japanese and Australian markets. IBM Corporation represents the services-heavy approach that leverages consulting and managed delivery capabilities to address skills gaps in mid-market accounts.
| Leading Market Players |
|---|
| Broadcom, Inc. |
| IBM Corporation |
| Microsoft Corporation |
| Trend Micro, Inc. |
| McAfee Corp |
| Palo Alto Networks, Inc. |
| GTB Technologies, Inc. |
| Infowatch |
| Cisco Systems, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation timelines for hybrid cloud DLP deployments compress vendor pricing power while inflating professional services premiums across Australia and Japan. Supply concentration among hyperscale platform providers in the United States and regional system integrators in Singapore creates asymmetric margin capture, with managed service orchestrators extracting value from skills gaps that elongate customer procurement cycles.
Pricing Analysis
Australian enterprises pay 25-40% premiums over Indonesian mid-market buyers for equivalent API-native inspection capabilities, reflecting maturity-driven feature depth and compliance automation requirements. SaaS-tiered subscription models dominate, with pricing stratifying across premium, standard, and economy tiers based on machine learning classification engine sophistication and cross-border transfer monitoring scope. Cost compression in the standard tier intensifies as Microsoft and regional specialists compete for Southeast Asian banking accounts with bundled security suite positioning. Mid-market buyers in Indonesia and Vietnam exhibit highest price sensitivity, while Australian government contractors demonstrate lowest elasticity due to sovereign cloud mandates.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore trade lane elevates inbound logistics costs for encryption hardware destined to Australian and South Korean defense contractors with air-gapped requirements. Software supply chains draw from the United States, Israel, and India for machine learning classification engines, while professional services capacity concentrates in Singapore, Australia, and Japan. Single-source vulnerability persists for CJK-optimized natural language processing modules trained on regional language corpora. Distribution runs through regional system integrators possessing established relationships with financial institutions and government procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Cloud DLP market functions as a certified security architect scarcity story, where deployment velocity depends on vendor professional services capacity rather than product availability alone. Skills gaps inflate implementation timelines and concentrate margin capture with managed service providers.
For Market Incumbents: Fortify API-native inspection pipeline architectures against behavioral analytics entrants displacing static regex-based classification. Invest in CJK character set recognition capabilities to defend Japanese and Korean financial institution accounts. Prioritize regional system integrator certification programs in Indonesia and Vietnam to preempt mid-market channel displacement by managed detection and response providers. For New Entrants and Emerging Players: Australia's 72-hour breach notification compliance fast-track offers immediate white-space access for automated discovery modules retrofitting legacy DLP tools. Indonesia's underpenetrated mid-market banking sector presents greenfield expansion opportunity through managed service partnerships with Jakarta-based system integrators. Lead with sovereign cloud integration capabilities to differentiate against hyperscale platform bundling. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-velocity play because compliance timeline compression across India, Australia, and Japan sustains replacement cycle demand regardless of macroeconomic conditions. Target acquisition profiles center on specialized vendors with CJK-optimized NLP engines and established Personal Information Protection Commission audit relationships. Monitor Japan's cross-border data transfer adequacy negotiations as signal for APPI enforcement intensity and associated tooling demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Inspection Pipeline Development | Machine learning classification engines reduce detection latency for unstructured data across Office 365 and Salesforce workloads. |
| Regional System Integrator Partnership Expansion | Singapore and Australian MSSPs capture margin pools from mid-market buyers consolidating security procurement. |
| CJK Language Corpus Training Investment | Japanese financial institutions prioritize vendors with native character set recognition for APPI compliance documentation. |
| Sovereign Cloud Architecture Certification | Indian banks under RBI cloud guidelines require automated data handling controls with domestic residency verification. |
| Behavioral Analytics Engine Integration | Real-time risk scoring displaces static rule maintenance for unstructured data inspection in hybrid environments. |
Research Methodology
Initial hypotheses were tested against primary input from CISOs at Australian financial institutions, cloud security architects at Indian banks, procurement officers at Japanese manufacturers, and regional system integrator delivery leads, then refined through secondary validation. Sources included SEC filings from hyperscale platform providers, Reserve Bank of India technology risk circulars, Personal Information Protection Commission enforcement notices, and Office of the Australian Information Commissioner breach notification statistics. Bottom-up deployment sizing and top-down regulatory mandate analysis were triangulated to constrain variance.
Variance decomposition across deployment architecture, service type, and end-user vertical shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass public, hybrid, private, and multi-cloud configurations alongside managed services penetration and BFSI versus government vertical intensity. CAGRs were derived from regulatory enforcement velocity and cloud migration timeline assumptions, with machine learning adoption curves and sovereign cloud procurement frameworks serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and skills gap persistence; material deviation in either would warrant model refresh. Forecasts reflect base-case assumptions without contingency for abrupt trade restriction imposition or hyperscale platform bundling acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Europe Digital Forensics Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
United States Virtualization Security Market
Cybersecurity
Cyber Security Consulting Market
Cybersecurity
Enterprise Mobility Security Market
Cybersecurity
Global Online Fraud Detection and Prevention Market
Cybersecurity
United Arab Emirates Cybersecurity Market
Cybersecurity
Network Security Market
Cybersecurity
Europe IoT Security Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market
Cybersecurity
South Korea Cybersecurity Market
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
Global Sandboxing Market
Cybersecurity
Global Digital Forensic Laboratory As a Service Market
Cybersecurity
Europe Data Protection-As-A-Service Market
Cybersecurity
Indonesia Cybersecurity Market