
 Dysprosium Market | 2026-2036
Dysprosium Market Size, Share, and Industry Trends Forecast 2026-2036
Dysprosium Market Analysis
Australia is reshaping upstream supply security through rare earth concentrate expansion at Mount Weld and Nolans. Lynas Rare Earths leverages integrated cracking and leaching capacity to sustain non-Chinese oxide output. Arafura Resources Limited anchors its offtake strategy around the Nolans project north of Alice Springs. MP Materials competes via Mountain Pass ore extraction and progressive downstream commissioning in the United States.
Dysprosium is a heavy rare earth element with atomic number 66, typically occurring in xenotime and monazite ores, and its oxide commands high thermal neutron absorption cross-sections critical for magnetic coercivity at elevated temperatures. Permanent magnets consume the dominant share of refined dysprosium, with each neodymium-iron-boron magnet requiring 2-12% dysprosium substitution to maintain performance above 150°C in traction motors. The metal form commands premium pricing against oxide and alloy intermediates due to additional electro-reduction and refining steps. Aerospace end users represent a concentrated margin pool despite smaller volumes, as flight-certified magnet specifications tolerate minimal substitution.
The EU Critical Raw Materials Act mandates that 25% of strategic raw material processing occur within member states, directly incentivizing European magnet recycling and separation investments. China's Ministry of Industry and Information Technology governs production quotas and environmental compliance for ionic clay mining in southern provinces. The United States Department of Defense offtake agreements under Defense Production Act authorities are redirecting concentrate flows toward domestic oxide and metal capacity. Stakeholders must monitor quota announcements from Beijing and subsidy disbursement timelines in Washington to calibrate inventory and contracting strategies.
Market Dynamics
China's export quota system and the EU Critical Raw Materials Act are creating a bifurcated supply architecture where magnet fabricators must secure dual-qualified oxide streams to maintain production continuity. This regulatory compression is forcing inventory strategies and contracting patterns to restructure around jurisdictional provenance rather than pure cost optimization.
Growth Catalysts
- EU Critical Raw Materials Act:The 25% domestic processing mandate is channeling capital into European magnet recycling and separation infrastructure, creating captive demand for non-Chinese oxide.
- Electric vehicle traction motors:Neodymium-iron-boron magnets require 2-12% dysprosium substitution to sustain coercivity above 150°C, locking in volume pull from automotive OEMs.
- Ionic clay mining in southern China:Heavy rare earth enrichment in Jiangxi and Guangdong provinces concentrates ion-adsorption ore access, sustaining primary supply despite environmental compliance tightening.
Market Restraints
- Input cost volatility:Ammonium sulfate and sulfuric acid prices fluctuate with energy markets, directly impacting ionic clay leaching economics in southern Chinese operations.
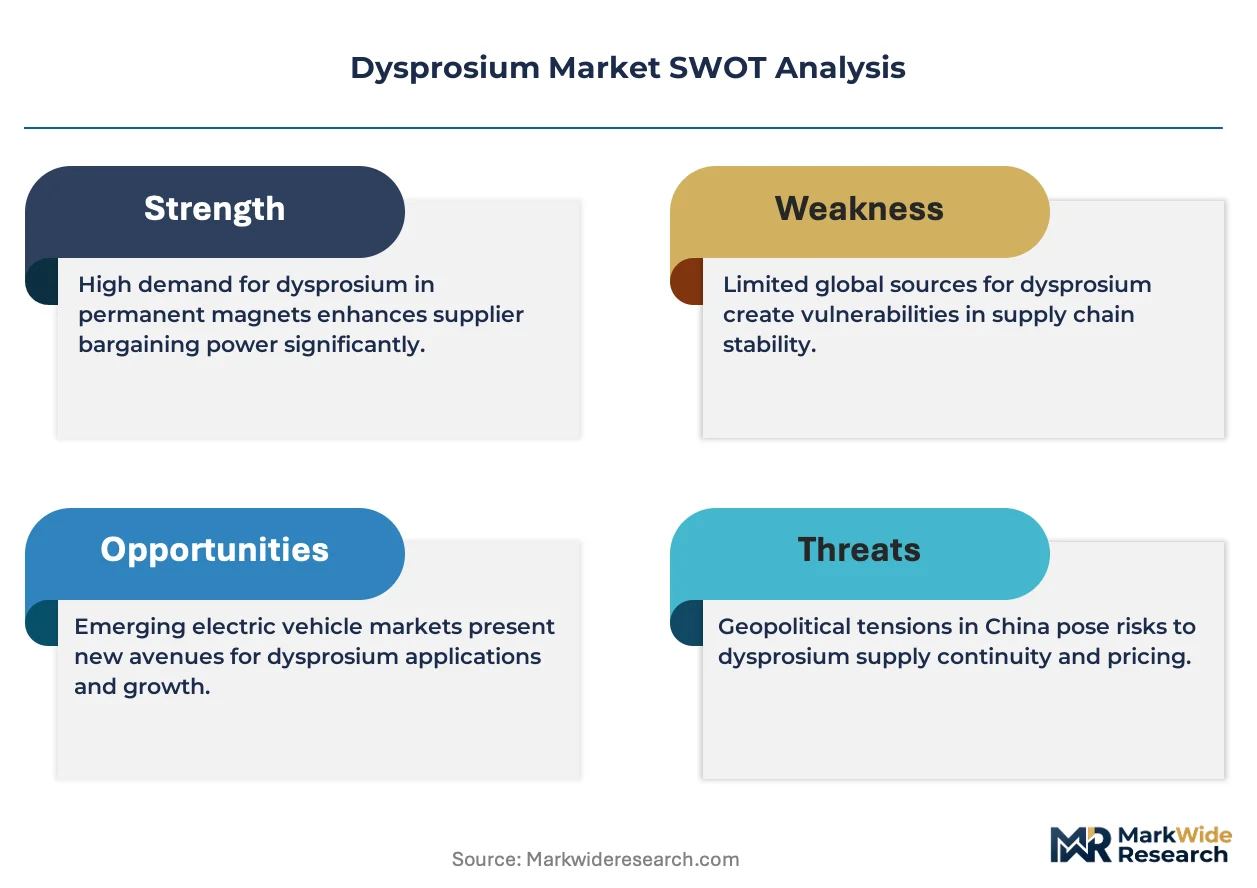
- Supply concentration risk:China's Ministry of Industry and Information Technology controls production quotas and environmental licensing, creating single-point governance exposure for global oxide availability.
- Substitution threat:Cerium-cobalt magnet formulations and grain-boundary diffusion techniques are reducing per-unit dysprosium intensity in lower-temperature motor applications.
Strategic Opportunities
- United States defense offtake:Defense Production Act authorities are redirecting concentrate flows toward domestic oxide and metal capacity, creating a parallel procurement channel outside commercial pricing.
- Magnet recycling technology:Hydrometallurgical separation and direct reuse processes are converging with automated sorting systems to unlock urban mine feedstocks.
- Japan's magnet fabrication sector:TDK and Hitachi Metals are qualifying Australian and US concentrate sources to reduce quota exposure, creating premium offtake terms for non-Chinese supply.
Industry Challenges
- Skill scarcity in solvent extraction:Qualified operators for rare earth separation circuits are concentrated in Chinese state-owned enterprises, complicating Western capacity commissioning.
- Flight certification timelines:Aerospace magnet specifications require multi-year qualification cycles with FAA and EASA, compressing supplier switching flexibility despite price premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysprosium Market |
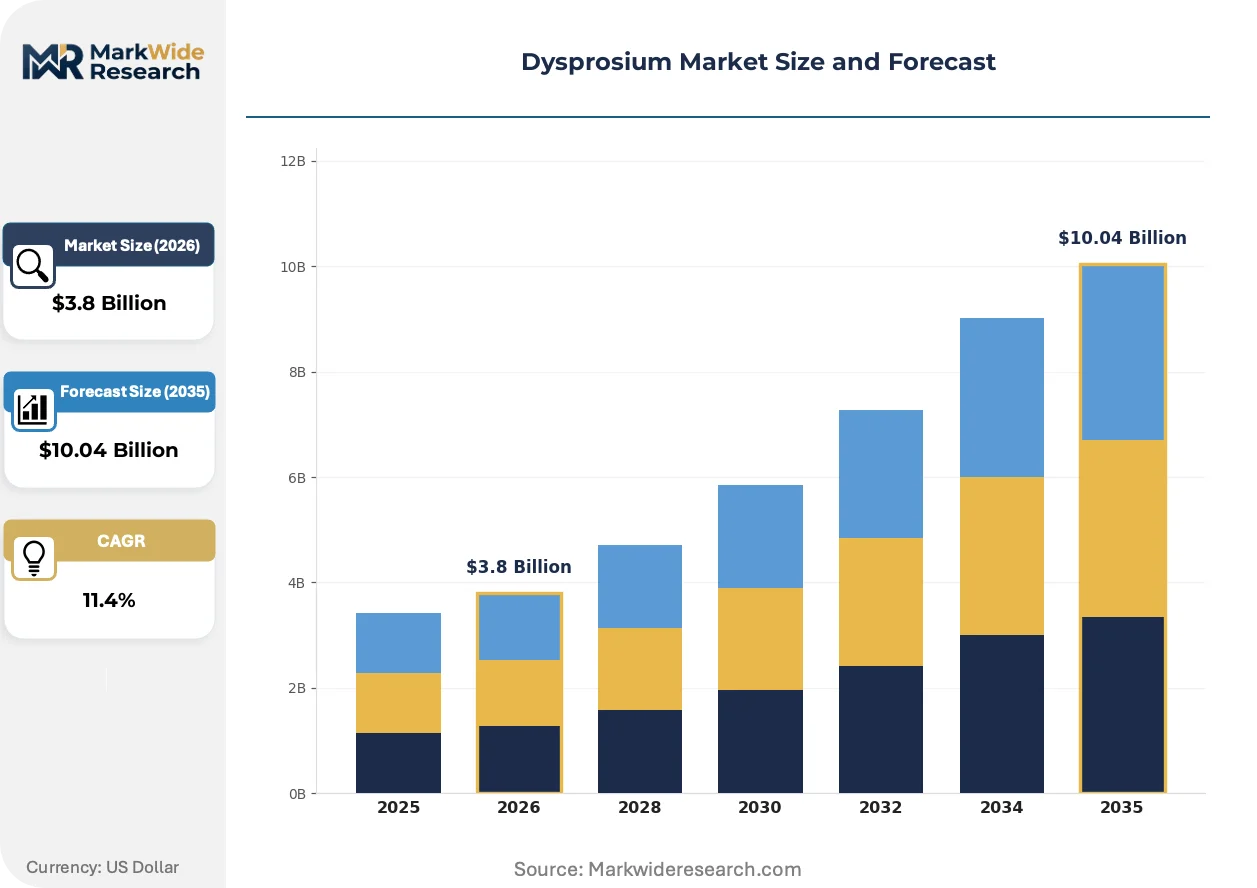
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Permanent Magnets, Nuclear Reactors, Phosphors, Laser Materials End User: Electronics, Automotive, Renewable Energy, Aerospace Form: Metal, Oxide, Alloy, Compounds Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | MP Materials, Arafura Resources Limited, China Northern Rare Earth Group, Energy Fuels, Inner Mongolia Baotou Steel, Shenghe Resources Holding Co. Ltd., Iluka Resources, Aclara Resources, Lynas Rare Earths, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysprosium Market Emerging Trajectories
Digital process control and automated separation systems are compressing yield variability in rare earth refining. These technologies are enabling real-time assay feedback and reducing batch rejection rates in oxide production.
Machine vision and sensor fusion systems are digitizing quality assurance in magnet manufacturing lines. Automotive OEMs in Germany and Japan are mandating digital traceability certificates for rare earth provenance. This digitizing of supply chain documentation is enabling automated compliance verification against EU Critical Raw Materials Act thresholds and reducing manual audit overhead.
China's MIIT is tightening wastewater discharge standards for ionic clay operations in Jiangxi province. The regulation is forcing facility retrofits and capacity consolidation among smaller leaching operators. Heavy rare earth processors are responding by relocating cracking capacity to northern rare earth corridors with integrated environmental infrastructure.
Long-term offtake contracting is displacing spot market purchasing among magnet fabricators. Japanese and Korean buyers are locking in five-year supply agreements with Australian concentrate producers to secure non-quota volumes. This preference shift is most visible in Tokyo and Osaka trading desks, where procurement teams are accepting price premiums for supply jurisdiction certainty.
Dysprosium Market Segmentation
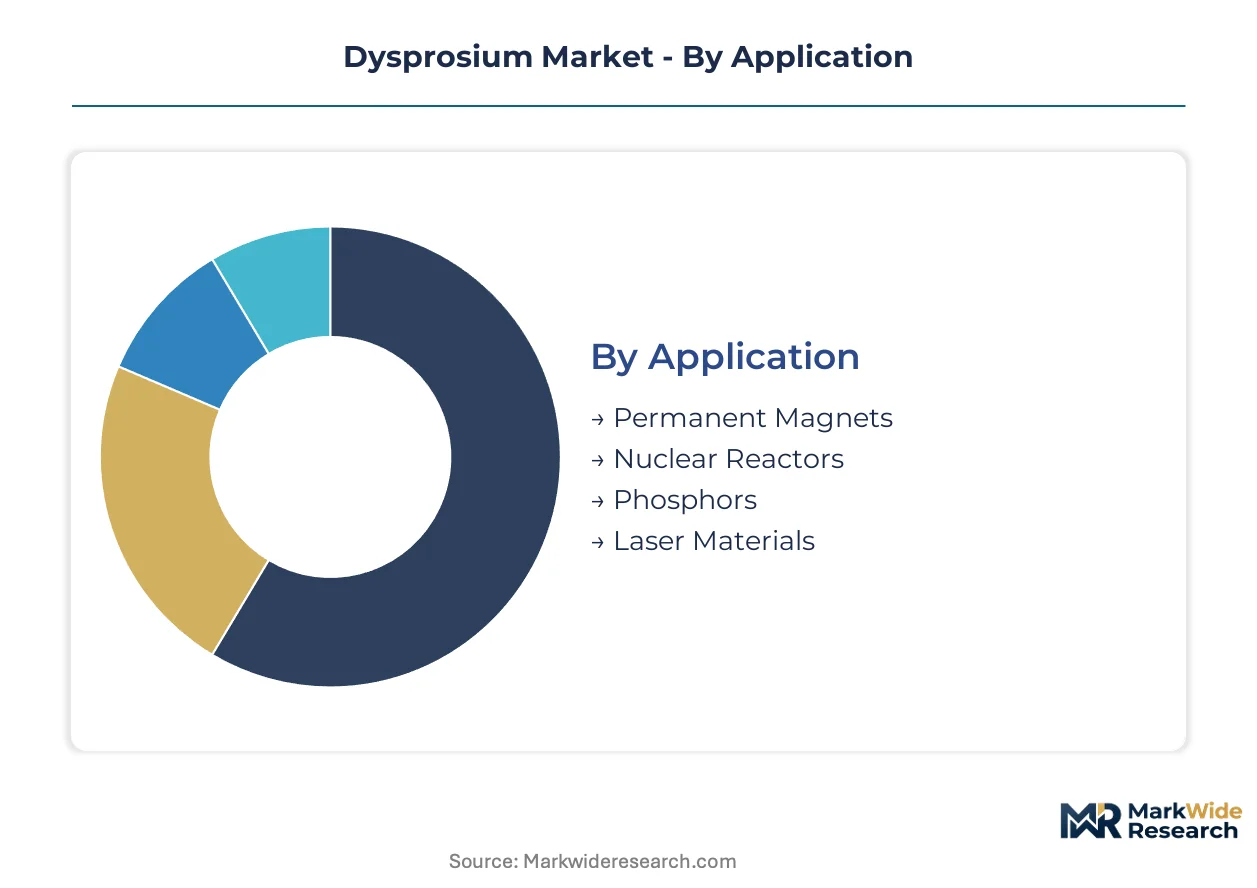
Dysprosium's value chain fragments sharply across functional forms and end-use specifications. Each segment carries distinct purity requirements, thermal stability thresholds, and qualification timelines that reshape procurement economics.
Application:
Mature magnet applications dominate volume throughput while emerging nuclear and laser segments command premium pricing tiers.
- Permanent Magnets:Neodymium-iron-boron formulations incorporate 2-12% dysprosium substitution to sustain magnetic coercivity above 150°C. Traction motor manufacturers in Japan and Germany are locking in five-year offtake agreements to secure non-Chinese oxide streams under EU Critical Raw Materials Act compliance timelines.
- Nuclear Reactors:Dysprosium oxide's thermal neutron absorption cross-section enables control rod fabrication for pressurized water reactors. French and South Korean reactor operators specify high-purity metal forms with minimal europium and gadolinium contamination, creating dedicated supply contracts outside commercial magnet channels.
- Phosphors:Halophosphate and triphosphor lamp coatings utilize dysprosium-activated compounds for narrow emission bandwidths.
- Laser Materials:Doped garnet crystals for medical and industrial solid-state lasers require exacting stoichiometry.
Permanent magnets handle the majority of throughput; laser materials are gaining share fastest on medical device qualification cycles.
End User:
Automotive electrification and renewable energy deployment are restructuring demand concentration across customer categories.
- Automotive:Electric vehicle traction motors consume heavy rare earth oxides through neodymium-iron-boron magnet supply chains. OEMs in Germany and Japan mandate digital traceability certificates verifying non-Chinese provenance to satisfy EU Critical Raw Materials Act thresholds.
- Electronics:Hard disk drive spindle motors and acoustic transducers utilize grain-boundary diffusion techniques to reduce per-unit dysprosium intensity. Japanese fabricators TDK and Hitachi Metals are qualifying Australian concentrate sources to reduce quota exposure.
- Renewable Energy:Direct-drive wind turbine generators require high-temperature stability specifications.
- Aerospace:Flight-certified magnet specifications tolerate minimal substitution, compressing supplier switching flexibility.
Automotive handles the majority of throughput; renewable energy is expanding most quickly on offshore wind capacity additions.
Form:
Processing depth determines pricing stratification and end-use accessibility across material states.
- Oxide:Refined Dy₂O₃ serves as the principal feedstock for magnet alloy production and ceramic applications. Chinese ionic clay operations in Jiangxi province concentrate heavy rare earth enrichment, though MIIT wastewater discharge standards are forcing facility consolidation.
- Metal:Electro-reduced dysprosium metal commands premium pricing against oxide intermediates due to additional refining steps. US Department of Defense offtake agreements under Defense Production Act authorities are redirecting concentrate flows toward domestic metal capacity.
- Alloy:Neodymium-dysprosium-iron master alloys enable direct magnet fabrication.
- Compounds:Halides and nitrates serve specialized phosphor and catalyst applications.
Oxide handles the majority of throughput; metal is climbing the fastest on defense procurement premiums.
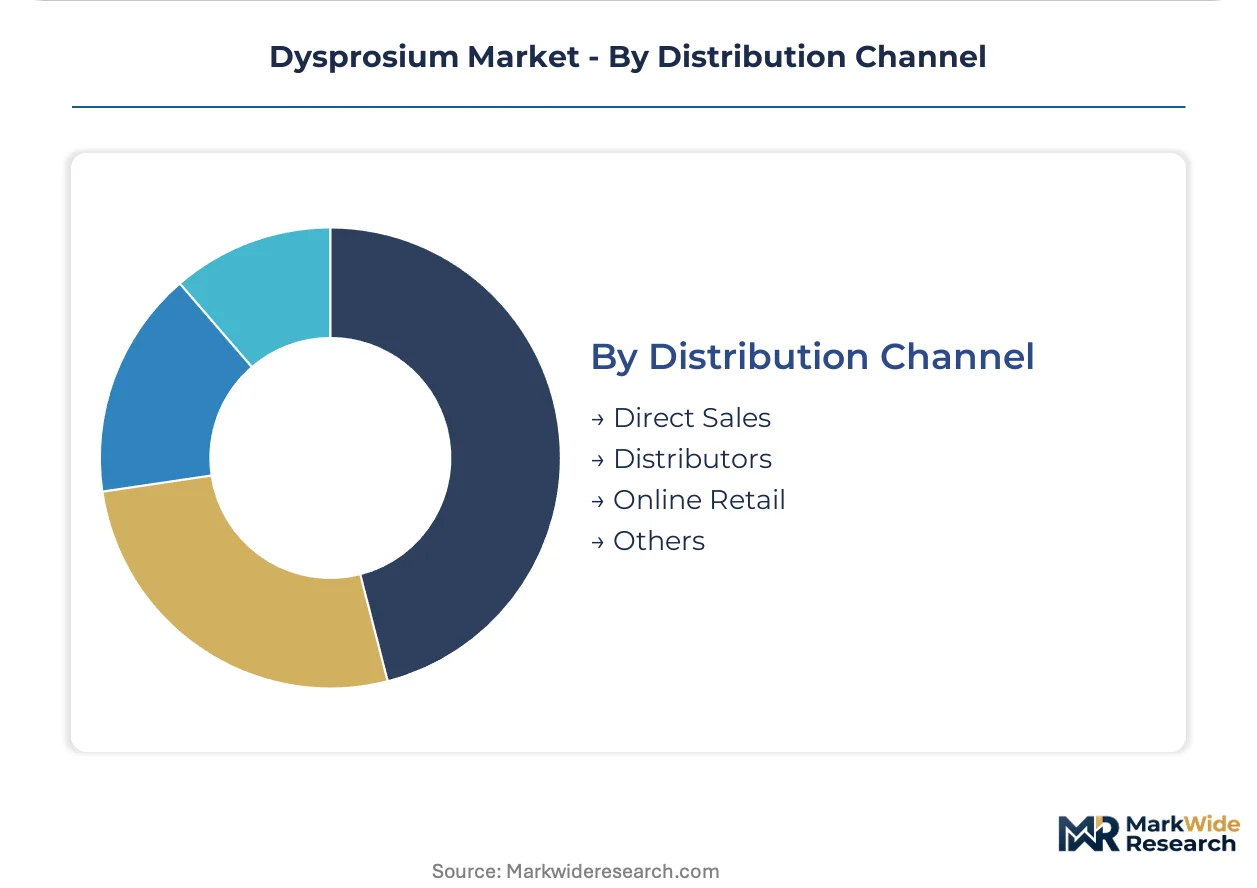
Distribution Channel:
Contracting patterns are displacing spot purchasing as fabricators seek supply jurisdiction certainty.
- Direct Sales:Long-term offtake agreements between concentrate producers and magnet fabricators lock in volume and pricing. Lynas Rare Earths and Arafura Resources Limited anchor procurement strategies around Australian concentrate expansion to service Japanese trading desks in Tokyo and Osaka.
- Distributors:Regional stockists manage inventory for smaller magnet manufacturers without qualified supplier relationships.
- Online Retail:Specialty chemical platforms serve research and prototype quantities.
- Others:Consignment arrangements and toll processing agreements.
Direct sales handles the majority of throughput; distributors are expanding most quickly on mid-tier fabricator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ionic clay mining corridors in southern China concentrate upstream heavy rare earth supply, yet environmental licensing and quota governance are dispersing processing investments toward Australian concentrate expansion and US defense-backed metal capacity. This geographic reconfiguration is restructuring procurement patterns for magnet fabricators in Japan and Germany.
China
Jiangxi and Guangdong provinces host ion-adsorption clay deposits with heavy rare earth enrichment ratios unmatched elsewhere. MIIT production quotas and wastewater discharge standards are forcing facility consolidation among smaller leaching operators. Processing gravity is shifting northward to Inner Mongolia's integrated rare earth corridors where environmental infrastructure accommodates stricter compliance.
United States
Defense Production Act authorities are redirecting Mountain Pass concentrate toward domestic oxide and metal commissioning. The Department of Defense offtake agreements create a parallel procurement channel outside commercial pricing structures. Texas and California clusters are emerging as downstream separation and magnet alloy fabrication zones.
Australia
Mount Weld and Nolans projects anchor non-Chinese concentrate expansion for Japanese trading desk procurement. Lynas Rare Earths leverages integrated cracking and leaching capacity to sustain oxide output outside Beijing's quota system. Western Australian mining jurisdictions offer environmental permitting timelines that accelerate project commissioning relative to Chinese regulatory cycles.
Japan
TDK and Hitachi Metals magnet fabricators are qualifying Australian and US concentrate sources to reduce quota exposure. Tokyo and Osaka trading desks are accepting price premiums for supply jurisdiction certainty under EU Critical Raw Materials Act compliance timelines. Kansai industrial corridors concentrate qualification laboratories and magnet alloy production.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate digital traceability certificates verifying non-Chinese provenance. The EU Critical Raw Materials Act 25% domestic processing mandate is channeling capital into magnet recycling infrastructure. Rhine-Ruhr industrial zones are emerging as separation technology development clusters.
Dysprosium Market Vendor Landscape
Integrated miners and downstream processors split the market between upstream concentrate control and midstream separation capability. Chinese state-owned enterprises concentrate ionic clay access and cracking capacity. Australian and US developers compete via hard-rock rare earth expansion. Western fabricators are consolidating offtake relationships outside quota-dependent supply. Competitive moves center on long-term contracting and jurisdictional diversification rather than price-based rivalry.
Among Australian concentrate developers, Lynas Rare Earths and Arafura Resources Limited exemplify the integrated-miner archetype with cracking and leaching infrastructure. MP Materials occupies a position representing US-based upstream expansion backed by defense procurement channels. These three entities anchor non-Chinese supply development as magnet fabricators in Japan and Germany restructure procurement strategies.
| Leading Market Players |
|---|
| MP Materials |
| Arafura Resources Limited |
| China Northern Rare Earth Group |
| Energy Fuels |
| Inner Mongolia Baotou Steel |
| Shenghe Resources Holding Co. Ltd. |
| Iluka Resources |
| Aclara Resources |
| Lynas Rare Earths |
| Others |
Supply Flow & Price Mechanics
Chinese ionic clay mining corridors in Jiangxi and Guangdong provinces concentrate upstream heavy rare earth supply, anchoring pricing power with state-controlled quota releases and directing margin pools toward Japanese magnet fabricators and German automotive OEMs seeking non-quota qualification.
Pricing Analysis
China's MIIT production quota system dictates the pricing tier structure across oxide, metal, and alloy forms. Three-tier pricing structure across premium flight-certified metal, standard magnet-grade oxide, and economy phosphor-grade compounds separates aerospace specifications from automotive traction motor feedstock. Price differentiation centers on thermal neutron absorption purity and jurisdictional provenance certification. Cost compression in standard-grade oxide intensifies because ammonium sulfate leaching economics fluctuate with energy markets. Automotive OEMs demonstrate highest price sensitivity, while aerospace end users tolerate premiums for minimal substitution tolerance.
Supply Chain Analysis
Extended payment terms from Japanese trading desks in Tokyo and Osaka are financing concentrate offtake from Australian developers, compressing working capital cycles for upstream miners. Supply draws from Chinese ionic clay corridors, Australian hard-rock concentrate at Mount Weld and Nolans, and US Mountain Pass ore extraction. Raw material dependencies rest on ammonium sulfate for southern Chinese leaching, sulfuric acid for cracking circuits, and organic solvents for solvent extraction separation. Single-source vulnerability concentrates in Chinese state-owned enterprise control of ion-adsorption ore access. Distribution runs through long-term offtake agreements displacing spot market purchasing among magnet fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle traction motor electrification and EU Critical Raw Materials Act compliance timelines are accelerating demand inflection for non-Chinese dysprosium supply, creating structural disruption across concentrate procurement and magnet fabrication.
For Market Incumbents: Pre-empt substitution threats from cerium-cobalt magnet formulations and grain-boundary diffusion techniques by deepening captive oxide capacity in Australia and the United States. Lock in five-year offtake agreements with Japanese and Korean fabricators before secondary developers commission competing separation circuits. Prioritize flight certification maintenance with FAA and EASA to defend aerospace margin pools against emerging metal producers. For New Entrants and Emerging Players: Mid-tier magnet fabricators in South Korea and Taiwan without qualified supplier relationships represent the most penetrable entry point for non-Chinese concentrate qualification. Toll processing agreements with existing cracking capacity in Texas or Western Australia enable market entry without full vertical separation infrastructure. Target consignment arrangements with distributors serving prototype and research quantities to establish assay credibility before scaling to automotive volumes. For Investors and Strategic Acquirers: Capital is best deployed toward integrated miners with cracking and leaching infrastructure rather than pure exploration plays. Long-term viability across the analysis window hinges on jurisdictional diversification away from single-country quota exposure. Monitor Beijing's MIIT quota announcement timing as the critical inflection signal for oxide availability and pricing volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Concentrate Supply | Lynas Rare Earths and Arafura Resources secure captive ore access outside Chinese quota governance. |
| Long-term Offtake Agreement | Japanese trading desks in Tokyo lock in five-year volume commitments with Australian developers. |
| Defense Production Act Channel Development | US Department of Defense procurement creates parallel pricing structures outside commercial magnet markets. |
| Magnet Recycling Infrastructure Investment | Hydrometallurgical separation in Germany's Rhine-Ruhr corridor unlocks urban mine feedstocks under EU mandates. |
| Flight Certification Maintenance | Aerospace suppliers preserve multi-year qualification cycles with FAA and EASA against switching pressure. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with rare earth separation plant managers, magnet procurement leads at Japanese trading desks, automotive OEM platform engineers, and defense acquisition officers; and secondary validation against customs trade records, MIIT quota announcements, SEC filings from listed concentrate developers, and EU Critical Raw Materials Act implementation timelines. Bottom-up modeling of oxide, metal, and alloy throughput triangulated against top-down demand estimates from traction motor and wind turbine deployment forecasts.
Forecast inputs considered electric vehicle production trajectories, offshore wind capacity additions, and defense procurement authorization levels across the projection horizon. Segmentation dimensions modeled include functional form purity tiers, end-use thermal stability specifications, and regional regulatory compliance clusters. CAGRs were derived from elasticity-adjusted demand curves and supply constraint scenarios. Industry-specific inputs incorporated ionic clay leaching yield variability and solvent extraction operator skill scarcity.
Macroeconomic conditions sit as an overlay; deviation in energy market volatility affecting ammonium sulfate pricing or Chinese environmental enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions around quota release timing and defense procurement disbursement schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Precision Stainless Steel Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
Global Special Steel Market
Specialty Metals
Metal Halide Market