
 Algeria Fruits and Vegetables Market | 2026-2036
Algeria Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Algeria Fruits and Vegetables Market Outlook
Traditional souk networks are reshaping how fresh produce reaches Algerian consumers, with modern retail formats eroding their historical dominance. Groupe Amor Benamor leverages its integrated farm-to-shelf infrastructure to control quality across the value chain. SPA Fruital anchors the citrus export segment through specialized cold-chain logistics. CEVITAL competes aggressively on processed vegetable derivatives, extending its industrial footprint beyond raw commodity trading.
Algeria fruits and vegetables encompass fresh and minimally processed edible plant products cultivated across Mediterranean coastal zones and Saharan oases, requiring controlled atmosphere storage to preserve organoleptic properties and nutritional value for domestic consumption and cross-border shipment. The product type dimension shows citrus dominating volume flows due to established grove infrastructure in Blida and Skikda provinces, while berries represent the fastest-expanding margin pool as protected greenhouse cultivation spreads. Distribution channel dynamics reveal wholesale still commanding upstream aggregation, though online platforms are capturing urban household demand through same-day delivery promises in dense municipal zones.
Algeria's national food safety regulator enforces pesticide maximum residue limits aligned with evolving Codex Alimentarius frameworks, while the Ministry of Agriculture monitors irrigation water quality standards under drought adaptation protocols. Compliance costs are rising for smallholder cooperatives unable to finance laboratory certification requirements. Stakeholders must track how export destination rules in adjacent Mediterranean markets evolve, as sanitary conformity determines access to premium pricing tiers beyond domestic absorption capacity.
Market Dynamics
Supermarket chains in Algiers and Oran are consolidating procurement power, squeezing traditional souk intermediaries while demanding traceable cold-chain documentation that smallholders struggle to furnish.
Growth Catalysts
- Sanitary Standard Modernization:Algeria's national food safety authority enforces updated pesticide residue limits aligned with Codex Alimentarius frameworks, compelling supply chain upgrades that unlock export eligibility to adjacent Mediterranean markets.
- Urban Income Concentration:Households in the northern coastal zone command purchasing power sufficient to absorb premium-grade fresh produce, rewarding quality-differentiated sourcing from integrated farm-to-shelf operators.
- Greenhouse Infrastructure:Protected cultivation technology spreads across Blida province, extending berry production seasons and insulating growers from rainfall volatility that damages open-field harvests.
Market Restraints
- Water Access Constraints:Irrigation quotas under drought adaptation protocols limit expansion of grove acreage in Skikda province, capping citrus volume growth regardless of export demand signals.
- Labor Cost Escalation:Harvest mechanization remains underdeveloped for delicate fruits, binding producers to seasonal wage pressures that compress margins during peak collection windows.
- Import Substitution Policy:Restrictive trade measures shield domestic processors from foreign competition but deprive them of cost-competitive input alternatives when local harvests underperform.
Strategic Opportunities
- Oran Metropolitan Expansion:Second-tier urban clusters outside Algiers exhibit underpenetrated modern retail presence, offering first-mover positioning for cold-chain-equipped distributors establishing controlled-atmosphere storage nodes.
- Processed Derivative Diversification:Industrial capacity for minimally processed vegetable products lags domestic demand, creating white space for operators with pasteurization and aseptic packaging capabilities.
- Digital Platform Integration:Same-day delivery aggregators capture urban household demand through mobile ordering interfaces, compressing traditional wholesale layers and capturing margin previously absorbed by souk intermediaries.
Industry Challenges
- Certification Bottlenecks:Laboratory testing capacity for pesticide residue verification concentrates in Algiers, imposing logistical delays and spoilage risk for cooperatives in remote growing regions seeking export documentation.
- Cold-Chain Fragmentation:Refrigerated transport coverage gaps between harvest zones and coastal export terminals force reliance on ambient trucking, degrading organoleptic quality and disqualifying shipments from premium pricing tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algeria Fruits and Vegetables Market |
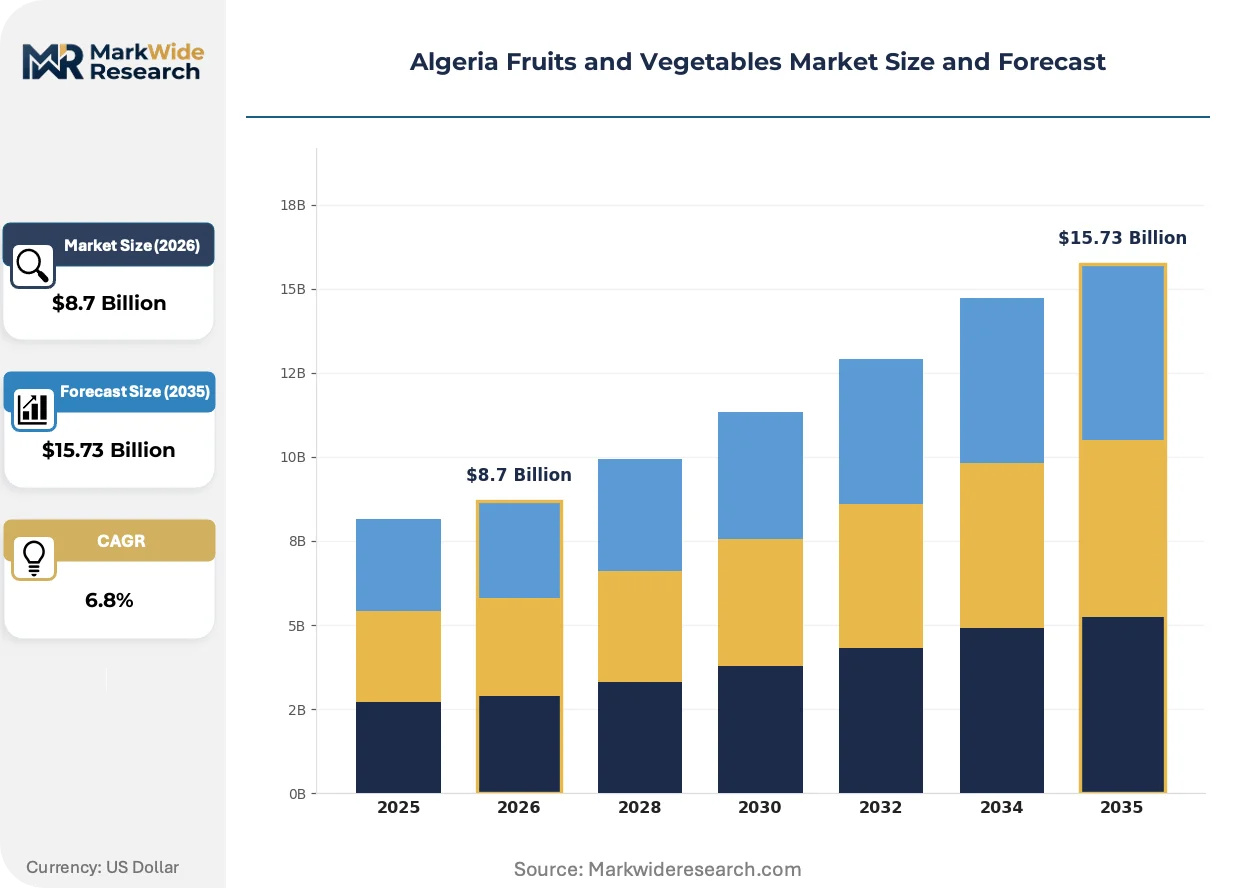
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Wholesale, Retail, Direct Sales, Online Platforms End User: Restaurants, Grocery Stores, Exporters, Households Packaging Type: Cartons, Plastic Bags, Bulk, Vacuum Packs |
| Companies Covered | Groupe Amor Benamor, SPA Fruital, Société Industrielle de Conserves Alimentaires de Medjez El Bab, Ziban Agro Fruits, Izdihar SpA, Numidis SpA, CEVITAL, Tolga Palms, Arcofina Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algeria Fruits and Vegetables Market Strategic Shifts
Technological adoption across Algerian agriculture concentrates on preserving perishable value through storage and logistics innovation rather than genetic or chemical input modification.
Controlled-atmosphere storage technology is hybridizing conventional warehouse infrastructure with nitrogen-flush and ethylene-scrubbing capabilities. Large-scale distributors serving supermarket chains deploy these systems to extend citrus marketing windows by several weeks. The technology compresses seasonal price volatility and enables scheduled release aligned with import-competitor supply gaps.
Algeria's Ministry of Agriculture monitors irrigation water quality standards under drought adaptation protocols, tightening permissible salinity thresholds for grove operations. Blida province growers face capital calls for reverse-osmosis treatment installations or well-deepening projects. Citrus exporters to European markets must document compliance through third-party audit trails that smallholders cannot self-certify.
Urban households are consolidating weekly produce purchases through mobile-enabled delivery platforms that bypass traditional souk visits. Dense municipal zones in Algiers exhibit the fastest platform adoption, with same-day fulfillment promises capturing time-constrained professional segments. This channel disintermediation threatens wholesale aggregation margins and forces traditional traders toward specialty or bulk commodity positioning.
Algeria Fruits and Vegetables Market Segmentation
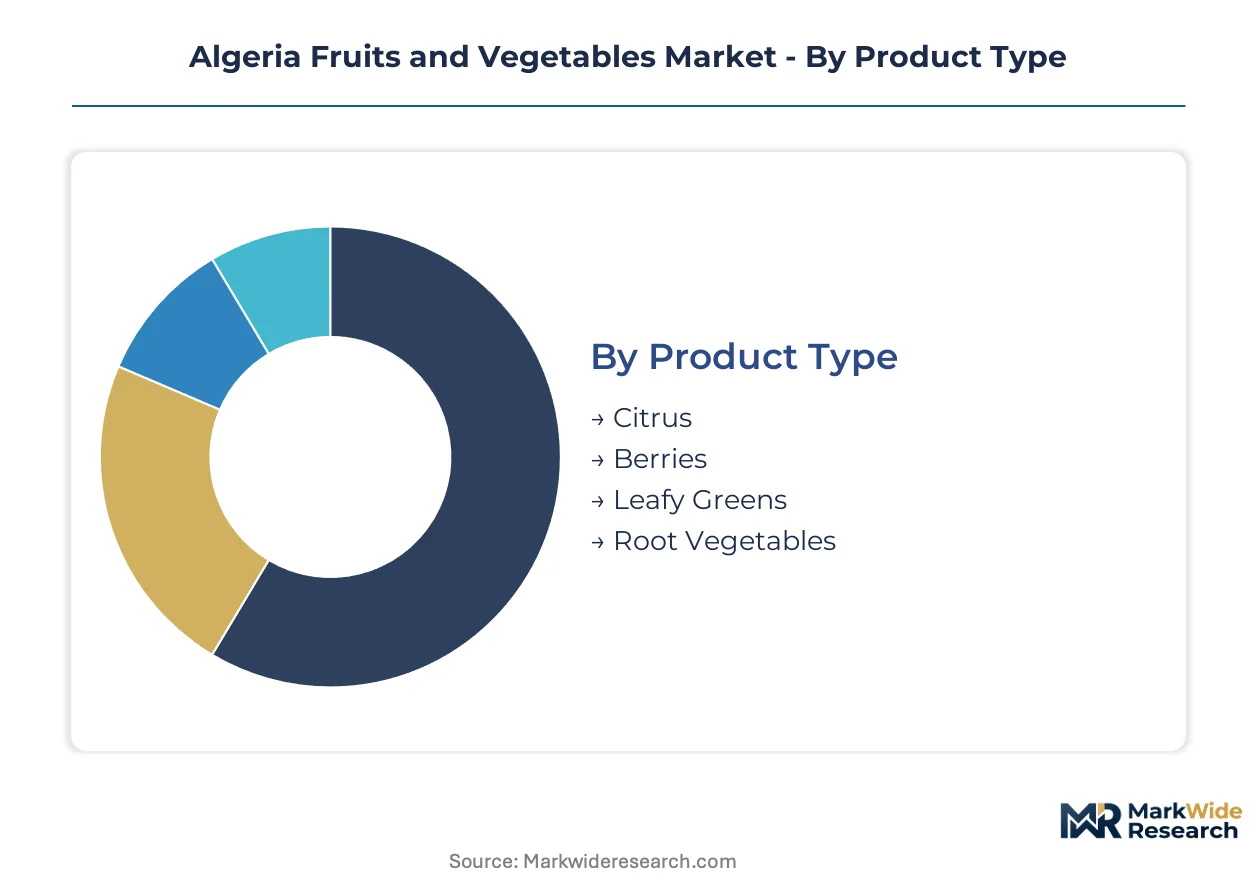
Segmentation in Algeria's fruits and vegetables market reveals how product perishability, channel infrastructure, and end-user specifications create distinct competitive arenas. Each dimension carries unique margin profiles and capital requirements that shape operator positioning across the value chain.
Product Type:
Volume concentration across crop categories reflects decades of grove infrastructure investment and emerging protected-cultivation adoption.
- Citrus:Oranges and mandarins dominate harvested tonnage, with established orchards in Blida and Skikda provinces supplying domestic processors and Mediterranean exporters. Coastal humidity patterns and deep-rooted irrigation networks sustain year-round availability that anchors procurement contracts with supermarket chains.
- Berries:Strawberry and raspberry cultivation is expanding fastest under greenhouse canopies that moderate temperature extremes and extend marketing windows. Protected infrastructure in Blida province captures premium pricing from urban households seeking out-of-season fresh produce.
- Leafy Greens:Lettuce and spinach require rapid cold-chain transit to preserve shelf life, limiting viable production radius to peri-urban zones serving Algiers and Oran metropolitan areas.
- Root Vegetables:Carrots and potatoes tolerate ambient storage longer, enabling smallholder cooperatives in interior provinces to aggregate shipments without immediate refrigeration.
Citrus holds installed capacity. Berries is rotating up the share rankings.
Distribution Channel:
Channel selection determines traceability obligations, payment terms, and exposure to quality degradation during handling.
- Wholesale:Central souk aggregators in Algiers and Oran consolidate fragmented smallholder output, offering volume access to institutional buyers but limited lot documentation for export certification.
- Retail:Supermarket chains demand palletized deliveries with barcode traceability and residue testing certificates that filter out uncertified suppliers.
- Direct Sales:Farm-gate transactions bypass intermediary margins for bulk purchasers with self-arranged transport, common among restaurant groups and processing plants.
- Online Platforms:Mobile-ordering aggregators promise same-day fulfillment to dense municipal zones, compressing delivery windows and capturing household demand previously served by neighborhood grocers.
Wholesale channels hold throughput volume. Online platforms are climbing the fastest.
End User:
Customer type dictates specification stringency, from aesthetic grading for retail display to biochemical tolerances for industrial processing.
- Restaurants:Foodservice operators prioritize consistent sizing and reliable delivery cadence over organic certification, sourcing through specialized distributors with early-morning drop schedules.
- Grocery Stores:Independent retailers and chain outlets demand visual uniformity and residue documentation that satisfies Algeria's national food safety authority protocols.
- Exporters:European-bound shipments face EFSA-aligned pesticide maximum residue limits requiring third-party laboratory verification that concentrates testing demand in Algiers facilities.
- Households:Individual consumers show rising preference for pre-packed convenience formats and mobile-ordering platforms that eliminate souk negotiation time.
Grocery stores command the largest procurement volume. Exporters are gaining priority for quality-tier supply allocation.
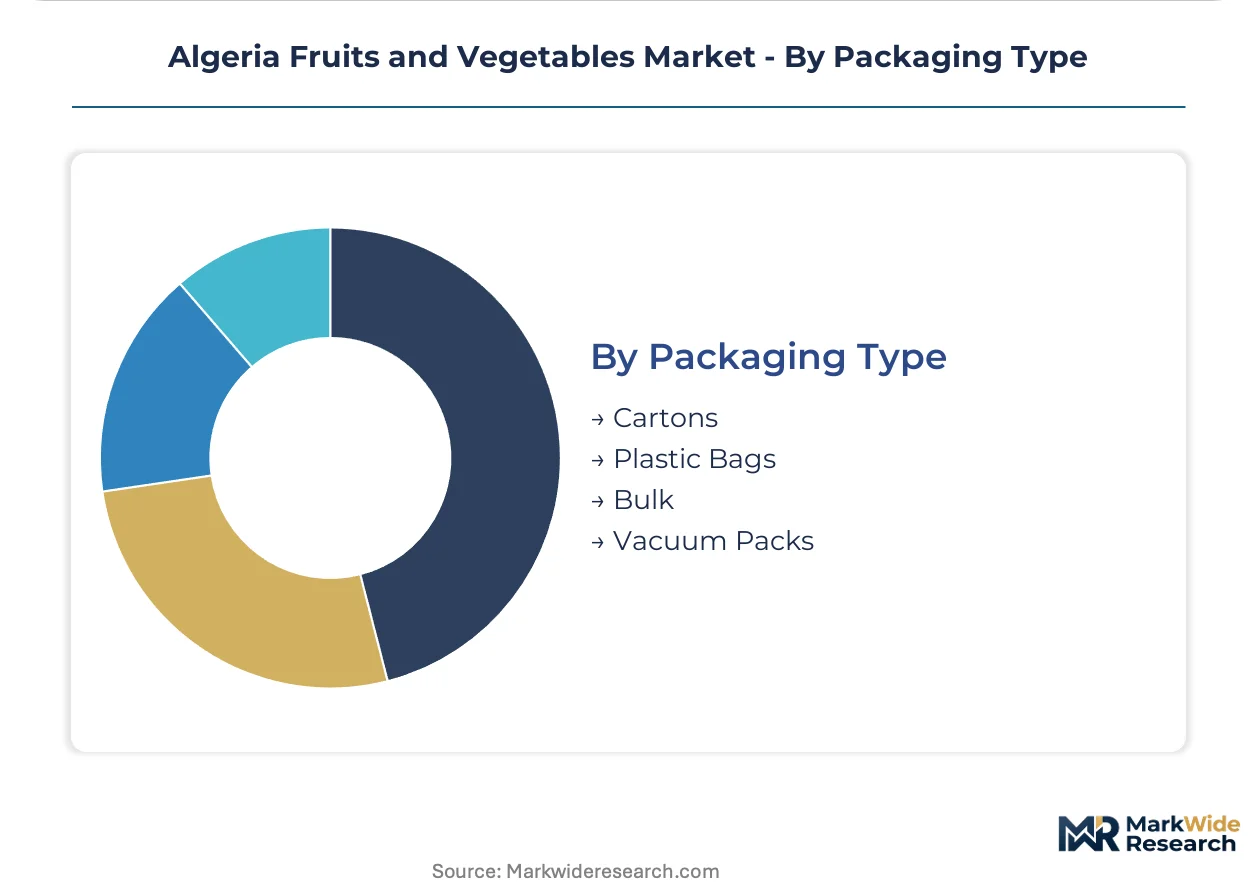
Packaging Type:
Packaging selection balances protection against mechanical damage, shelf-life extension, and cost per unit moved.
- Cartons:Corrugated fiberboard dominates citrus export shipments, with ventilation perforations and stacking strength engineered for palletized container loading at Oran and Algiers ports.
- Plastic Bags:Polyethylene sacks serve bulk root vegetable distribution through wholesale channels where moisture retention matters less than transport economy.
- Bulk:Unpacked loose produce persists in traditional souk transactions, minimizing material cost but exposing contents to contamination and compression damage.
- Vacuum Packs:Modified-atmosphere sealing for pre-cut leafy greens extends retail shelf life, requiring capital investment that limits adoption to integrated packers serving supermarket chains.
Cartons hold export-destined capacity. Vacuum packs are expanding most quickly for premium retail positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Algiers anchors national produce distribution, handling citrus and vegetable shipments bound for European markets while receiving controlled-atmosphere equipment imports for cold-chain expansion.
Algiers Metropolitan Area
Urban household purchasing power concentrates demand for premium fresh produce and same-day delivery platforms. The national food safety authority enforces pesticide residue documentation requirements that filter supplier eligibility. Supermarket chains in Bab Ezzouar and Hydra districts deploy controlled-atmosphere storage nodes to extend citrus marketing windows.
Oran Coastal Zone
Second-tier urban clusters exhibit underpenetrated modern retail presence with rising professional-class consumption. Port infrastructure at Mers El Kébir enables Mediterranean export shipments requiring cold-chain integrity. Distributors establishing regional aggregation hubs capture procurement contracts from expanding supermarket footprints.
Blida Province
Greenhouse infrastructure investment accelerates berry production season extension for urban premium markets. The Ministry of Agriculture monitors irrigation water quality standards under drought adaptation protocols requiring reverse-osmosis treatment installations. Protected cultivation clusters around El Affroun supply out-of-season strawberries to Algiers retail channels.
Skikda Province
Established citrus grove infrastructure faces irrigation quota constraints that cap volume expansion regardless of export demand signals. Deep-rooted irrigation networks sustain year-round orange and mandarin availability. Port proximity at Skikda terminal supports containerized shipments to France and Spain contingent on residue certification compliance.
Saharan Oases
Date palm cultivation dominates arid-zone output with tolerance for ambient storage and extended shelf life. Oasis cooperatives supply domestic processors and bulk export channels with minimal cold-chain requirements. Tolga Palms anchors regional aggregation from Tébessa and Biskra growing zones.
Algeria Fruits and Vegetables Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The Algeria fruits and vegetables market structures around vertically integrated farm-to-shelf operators, export-focused citrus aggregators, and industrial processors of vegetable derivatives. Three archetypes dominate: integrated producers controlling cultivation through retail placement, specialized exporters managing cold-chain logistics for Mediterranean shipment, and diversified conglomerates extending industrial processing capacity. Competitive moves concentrate on backward integration into captive grove ownership and geographic expansion of controlled-atmosphere storage networks.
Among integrated Algerian operators, Groupe Amor Benamor exemplifies the farm-to-shelf archetype with quality control across cultivation and retail placement. SPA Fruital occupies the export-specialist position, anchoring citrus shipment logistics through cold-chain infrastructure. CEVITAL represents the diversified industrial processor archetype, extending capacity beyond raw commodity handling into pasteurized and aseptically packaged vegetable derivatives.
| Leading Market Players |
|---|
| Groupe Amor Benamor |
| SPA Fruital |
| Société Industrielle de Conserves Alimentaires de Medjez El Bab |
| Ziban Agro Fruits |
| Izdihar SpA |
| Numidis SpA |
| CEVITAL |
| Tolga Palms |
| Arcofina Holding |
| Others |
Value Chain & Pricing Dynamics
Blida province's greenhouse clusters concentrate premium berry capacity, translating controlled-atmosphere storage access into pricing power over urban retail channels in Algiers and Oran. Coastal supermarket chains leverage procurement scale to compress margins on standard-grade citrus, while smallholders without cold-chain documentation face price discounts of twenty to thirty percent below certified tiers.
Pricing Analysis
Volume-discount tiering structures dominate citrus transactions, with supermarket chains extracting favorable terms on palletized shipments exceeding ten metric tons. Three-tier pricing separates export-certified produce from domestic retail grade and uncertified bulk, with differentiation anchored in residue documentation and cold-chain integrity. Pricing pressure stems from Moroccan and Spanish import competition during Algeria's off-peak harvest windows. Price-sensitive household segments through traditional souks resist premium positioning, while export-oriented aggregators absorb certification costs to access European pricing tiers.
Supply Chain Analysis
Contract-manufacturing concentration for processed derivatives rests with CEVITAL's industrial facilities and specialized canneries in Medjez El Bab. Geographic supply concentration centers on Blida province for protected cultivation, Skikda province for citrus groves, and Saharan oases for date palm aggregation. Raw material dependencies include phosphate fertilizers, polyethylene greenhouse films, and refrigerated container equipment. Single-source vulnerability concentrates in Algiers-based laboratory certification capacity for export documentation. Distribution runs through port terminals at Algiers and Oran for Mediterranean shipment, with ambient trucking dominating interior aggregation routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from Moroccan citrus and Spanish greenhouse vegetables penetrating Algeria's premium retail channels through relaxed trade enforcement periods. Defense requires preemptive quality-tier positioning and geographic expansion before foreign competitors establish cold-chain beachheads.
For Market Incumbents: Pre-empt Moroccan import encroachment by securing backward integration into Blida greenhouse acreage and Skikda grove rehabilitation. Anchor procurement contracts with supermarket chains through dedicated controlled-atmosphere storage nodes in Oran. Certification investment in third-party audit trails unlocks European export eligibility that import competitors cannot match under Algeria's sanitary protocols.
For New Entrants and Emerging Players: Saharan oases exhibit underpenetrated date processing capacity, with Tolga Palms anchoring regional aggregation that newcomers can complement through aseptic packaging investments. Digital platform infrastructure for same-day delivery remains fragmented outside Algiers dense zones, offering white-space capture through mobile-ordering interfaces targeting Oran professional households. Go-to-market positioning should emphasize convenience-tier pricing below supermarket premiums.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated farm-to-shelf operators with captive cultivation and cold-chain assets over commodity traders exposed to margin compression. Long-term viability across the analysis window rests on drought adaptation infrastructure and export certification capacity as climate stress intensifies. Acquisition targets should demonstrate proven compliance with Algeria's national food safety authority protocols. The signal to watch is Ministry of Agriculture irrigation quota tightening, which would accelerate consolidation toward capitalized operators with reverse-osmosis installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Expansion | Extends citrus marketing windows at Oran and Algiers nodes, compressing seasonal price volatility. |
| Greenhouse Infrastructure Investment | Blida province protected cultivation insulates berry harvests from rainfall volatility damaging open-field output. |
| Export Certification Compliance | Third-party residue documentation unlocks European market access under EFSA-aligned standards enforced by Algeria's regulator. |
| Digital Platform Integration | Same-day delivery aggregators capture urban household demand previously served by traditional souk intermediaries. |
| Backward Integration into Grove Ownership | Captive citrus and berry cultivation secures supply quality for supermarket chain procurement contracts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with supermarket chain procurement managers, greenhouse operators in Blida province, citrus export aggregators at Skikda port, and officials from Algeria's national food safety authority. Secondary validation drew from customs records at Algiers and Oran ports, Ministry of Agriculture irrigation allocation disclosures, Codex Alimentarius framework updates, and cold-chain equipment import manifests. Bottom-up cultivation area estimates and top-down consumption surveys were triangulated to anchor volume projections.
Calibration approaches cross-referenced historical price series across wholesale souks, retail supermarket scanner data, and export FOB quotations at Mediterranean terminals. Segmentation dimensions modeled include product perishability tier, distribution channel infrastructure requirements, end-user specification stringency, and regional climatic adaptation. CAGRs were derived from trend extrapolation of planted acreage, yield improvement trajectories, and urban household income elasticity estimates. Industry-specific forecast inputs incorporated drought adaptation protocol stringency and European import demand fluctuation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Moroccan state-backed citrus exporters or Spanish greenhouse consortiums would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding continued enforcement of Algeria's sanitary standards and stable irrigation quota allocation. Quarterly review of port shipment volumes, greenhouse construction permits, and residue testing backlog duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
North America Christmas Tree Market
Vegetables
Ghana Fruit and Vegetable Market
Vegetables
Europe Pea Market
Vegetables
UAE Tomato Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Tomato Market
Vegetables
IQF Vegetables Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Air Dried Vegetables Market
Vegetables
United States Microgreens Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Asia-Pacific Peas Market
Vegetables
Vegetable Chutney Market