
 Olive Market | 2026-2036
Olive Market Size, Share, and Industry Trends Forecast 2026-2036
Olive Market Outlook
Capital-intensity divergence between integrated millers and commodity packagers is collapsing as climate-driven harvest volatility forces smaller operators to outsource crushing and storage. Deoleo leverages its Spanish and Italian milling infrastructure to secure year-round supply continuity. California Olive Ranch anchors North American production through super-high-density orchard models that reduce per-acre labor inputs. Borges International Group competes across private-label and branded tiers with vertically controlled sourcing from Mediterranean cooperatives.
Olive fruit and its derivatives comprise the drupe of Olea europaea, typically containing 15-30% oil by fresh weight depending on cultivar and ripeness, with cold-press extraction preserving polyphenol concentrations above 150 mg/kg for extra virgin grades. The primary commercial purpose spans edible oil, table fruit, and oleochemical feedstock for cosmetics and nutraceuticals. Extra Virgin Olive Oil commands the dominant value share within product type segments due to certified origin premiums and health-positioned branding, while Olive Extract is gaining fastest traction in personal care and supplement applications as formulators seek plant-derived active ingredients. Glass Bottles remain the standard for premium retail positioning, though Tetra Packs are capturing volume in food-service and emerging-market channels where cost and logistics efficiency outweigh shelf aesthetics.
EU regulators including EFSA and EMA govern health claims and novel food approvals for olive-derived ingredients, while REACH compliance shapes chemical handling standards for industrial oleochemical processing. The USDA and FDA in the United States enforce grade standards and adulteration testing that determine import access and domestic labeling legitimacy. Stakeholders must monitor evolving polyphenol quantification methodologies and origin-verification technologies as authentication becomes central to margin defense across all price tiers.
Market Dynamics
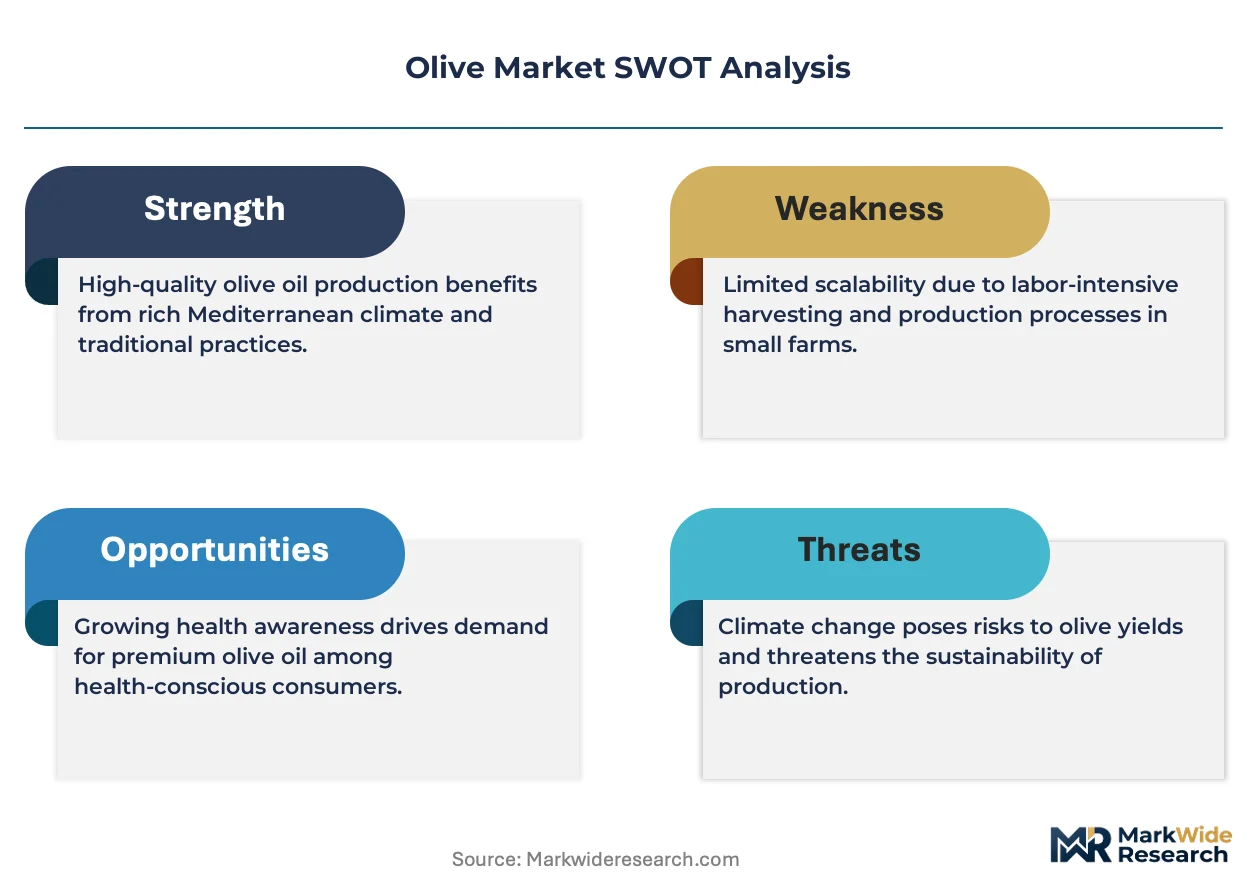
EU Green Deal sustainability mandates and the F-Gas Regulation are forcing cold-chain and processing infrastructure upgrades across Mediterranean extraction facilities, compressing margins for operators lacking capital reserves.
Growth Catalysts
- Mediterranean Diet Expansion:Specialty food retailers in North America and Northern Europe are broadening olive-based product assortments as consumer preference shifts toward polyphenol-rich ingredients with certified origin status.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating adoption of ammonia-based and transcritical CO2 cold-chain systems in Andalusian processing clusters.
- Super-High-Density Orchards:Mechanized harvesting systems in California and Australia are reducing per-acre labor inputs by over 60 percent compared to traditional grove architectures.
Market Restraints
- Harvest Volatility:Climate-driven alternate bearing cycles in Spain and Italy create 30-40 percent year-on-year volume swings that destabilize bulk pricing benchmarks and forward-contract reliability.
- Input Concentration:Phosphate fertilizer and agricultural diesel supply chains remain concentrated among a limited set of Mediterranean and North African suppliers, exposing growers to energy-cost pass-through.
- Adulteration Detection Gaps:Current isotope-ratio mass spectrometry protocols cannot reliably distinguish blended oils from discrete origin claims, undermining premium-tier authentication.
Strategic Opportunities
- Indian Market Entry:FSSAI novel food approvals for hydroxytyrosol and olive leaf extract remain underutilized, creating first-mover positioning for functional ingredient suppliers targeting Ayurveda-adjacent wellness positioning.
- Nutraceutical Formulation:EFSA health claim approvals for olive polyphenol cardiovascular benefits are driving supplement manufacturer demand for standardized oleuropein concentrates above 20 percent purity.
- Tetra Pack Channel Expansion:Food-service operators in Southeast Asian and Middle Eastern markets are adopting aseptic carton formats to reduce glass breakage losses and extend ambient distribution reach.
Industry Challenges
- Polyphenol Quantification Talent:Laboratory capacity for HPLC-DAD and LC-MS/MS analysis of complex phenolic profiles remains concentrated in Spanish and Italian research institutes, creating bottlenecks for new market entrants seeking grade certification.
- Legacy System Integration:Cooperative mills with decades-old continuous extraction lines face retrofit complexity when incorporating real-time acidity and peroxide monitoring sensors required for EU export compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olive Market |
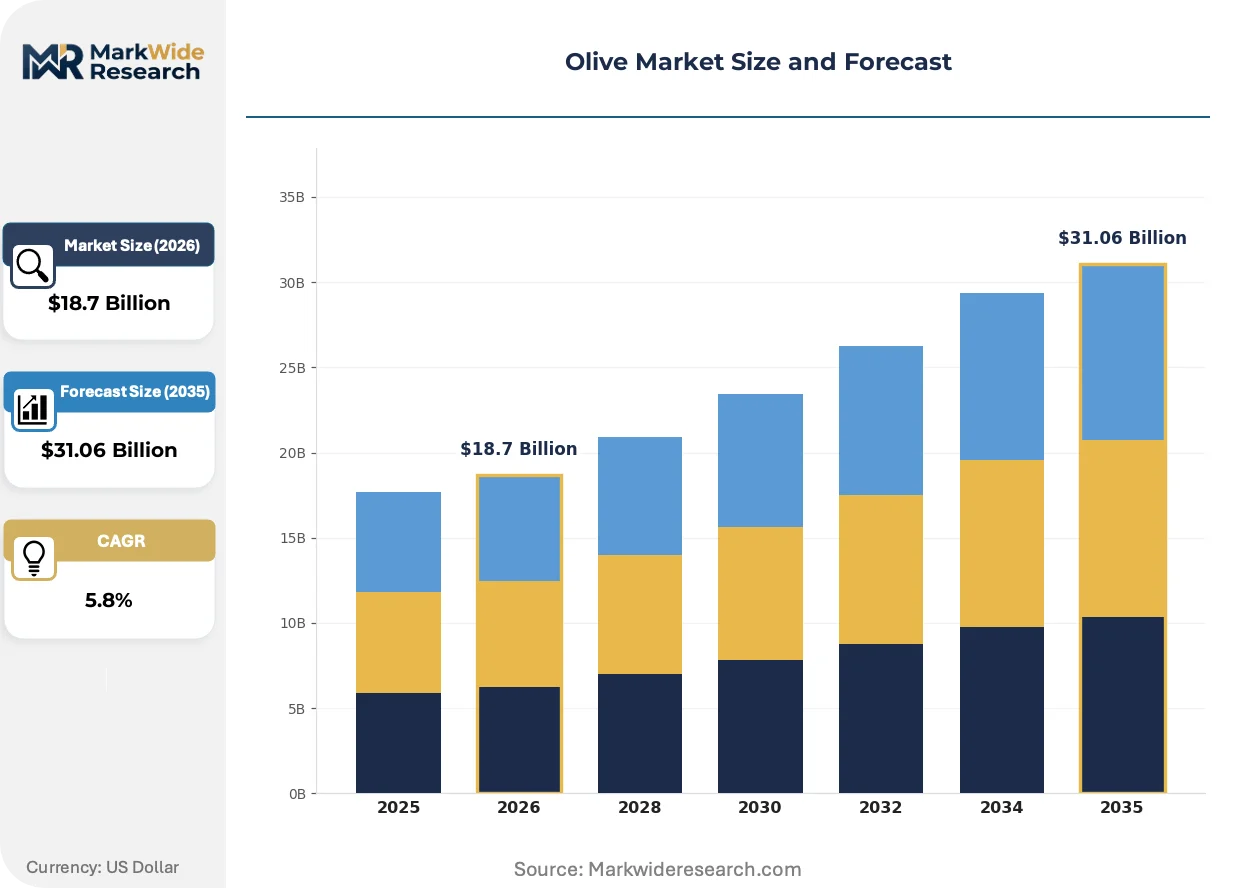
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extra Virgin Olive Oil, Olive Paste, Olive Snacks, Olive Extract Application: Culinary Use, Personal Care, Dietary Supplements, Industrial Packaging Type: Glass Bottles, Tetra Packs, Jerry Cans, Plastic Bottles Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | California Olive Ranch, Musco Family Olive Co., Conagra Brands, Monini, Bell-Carter Foods, Deoleo, Borges International Group, Grupo SOS, Sovena Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olive Market Strategic Shifts
Processing technology convergence and regulatory disclosure requirements are compressing traditional quality-assurance timelines while opening new value-capture mechanisms for traceability-enabled operators.
Near-infrared spectroscopy coupled with blockchain-based provenance logging is decomposing the traditional laboratory testing bottleneck for extra virgin grade verification. Spanish and Portuguese millers with integrated crushing-to-bottling operations are deploying these systems at receiving stations to release payment to cooperative suppliers within 48 hours rather than the historical two-week cycle. This compression is decomposing working-capital advantages previously held by large commodity traders with captive laboratory infrastructure.
REACH compliance for oleochemical derivatives used in cosmetics and personal care is tightening documentation requirements for substance volume tracking and downstream user communication. ECHA registration dossiers for olive-derived squalene and fatty acid esters now require updated exposure scenarios reflecting cosmetic formulation concentration limits. German and French formulators are responding by qualifying alternative Mediterranean suppliers with pre-submitted full registrations rather than relying on traditional Italian sources with ongoing evaluation status.
Direct-to-restaurant procurement platforms are displacing traditional wholesale distributor relationships for premium extra virgin grades in urban North American markets. These platforms connect certified-origin producers with executive chefs seeking specific cultivar profiles and harvest-date specificity. The shift is most visible in California and New York metropolitan areas where menu transparency requirements and local sourcing narratives drive purchasing decisions independent of conventional food-service pricing structures.
Olive Market Segmentation
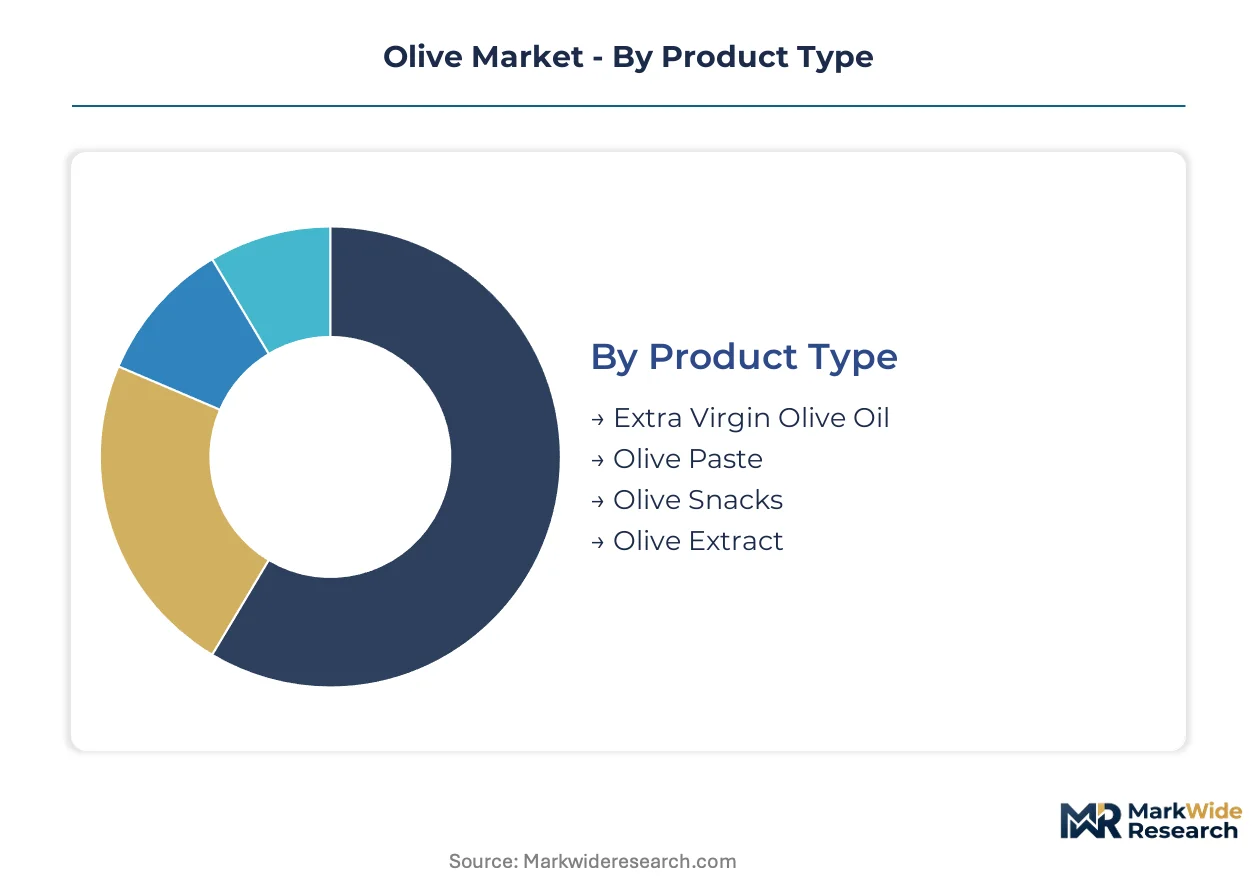
Segmentation in the olive market reflects divergent regulatory pathways and margin architectures. EFSA health claim approvals, USDA grade standards, and EU Green Deal sustainability mandates each favor distinct product formats and channel strategies. Understanding these fault lines determines where capital deployment captures pricing power versus commodity exposure.
Product Type:
Regulatory differentiation separates polyphenol-certified grades from commodity classifications, with EFSA cardiovascular health claims and USDA extra virgin standards creating enforceable tier boundaries that command origin premiums.
- Extra Virgin Olive Oil:Cold-press extraction preserves polyphenol concentrations above 150 mg/kg, meeting IOC chemical standards for free acidity below 0.8%. Spanish Andalusian cooperatives and Italian Puglian millers dominate bulk supply, with certified origin premiums defending margin against commodity blending. Climate-driven harvest volatility in Spain creates 30-40% year-on-year volume swings that destabilize forward-contract reliability.
- Olive Extract:Standardized oleuropein concentrates above 20% purity target nutraceutical formulation, with EFSA health claim approvals driving supplement manufacturer demand. REACH compliance for oleochemical derivatives tightens documentation requirements, favoring suppliers with pre-submitted ECHA registration dossiers over sources with ongoing evaluation status.
- Olive Paste:Industrial food-service formulations concentrate in Mediterranean processing clusters with integrated pitting and milling infrastructure.
- Olive Snacks:Table fruit applications follow distinct USDA and FDA grade standards for size, color, and defect tolerances.
Established volume favors Extra Virgin Olive Oil; emerging adoption favors Olive Extract.
Application:
Application segmentation tracks customer procurement sophistication, with food-service operators prioritizing harvest-date specificity while industrial buyers emphasize REACH-compliant documentation chains.
- Culinary Use:Direct-to-restaurant procurement platforms displace traditional wholesale distributors in California and New York metropolitan areas, with executive chefs seeking specific cultivar profiles independent of conventional food-service pricing. Menu transparency requirements and local sourcing narratives drive purchasing decisions that bypass commodity packagers.
- Dietary Supplements:EFSA health claim approvals for olive polyphenol cardiovascular benefits create formulation demand for hydroxytyrosol and oleuropein concentrates. FSSAI novel food approvals in India remain underutilized, creating first-mover positioning for functional ingredient suppliers targeting Ayurveda-adjacent wellness positioning.
- Personal Care:German and French formulators qualify alternative Mediterranean suppliers with pre-submitted REACH registrations rather than relying on Italian sources with ongoing evaluation status.
- Industrial:Oleochemical feedstock for cosmetics requires updated ECHA exposure scenarios reflecting cosmetic formulation concentration limits.
Culinary Use captures dominant revenue share; Dietary Supplements is climbing the fastest on polyphenol standardization.
Packaging Type:
Packaging economics reflect channel cost structures and breakage risk tolerance, with ambient distribution reach and logistics efficiency determining format selection.
- Glass Bottles:Premium retail positioning standard for certified-origin extra virgin grades, with transparency and shelf aesthetics supporting origin-premium pricing. Urban North American direct-to-restaurant platforms favor glass for menu transparency narratives despite higher logistics cost.
- Tetra Packs:Aseptic carton formats reduce glass breakage losses and extend ambient distribution reach in Southeast Asian and Middle Eastern food-service channels where cost and logistics efficiency outweigh shelf aesthetics.
- Jerry Cans:Bulk food-service and industrial procurement in price-sensitive emerging markets.
- Plastic Bottles:Mass-market retail tiers with lower origin-certification requirements.
Glass Bottles defend premium positioning; Tetra Packs gain share fastest in food-service expansion.
Distribution Channel:
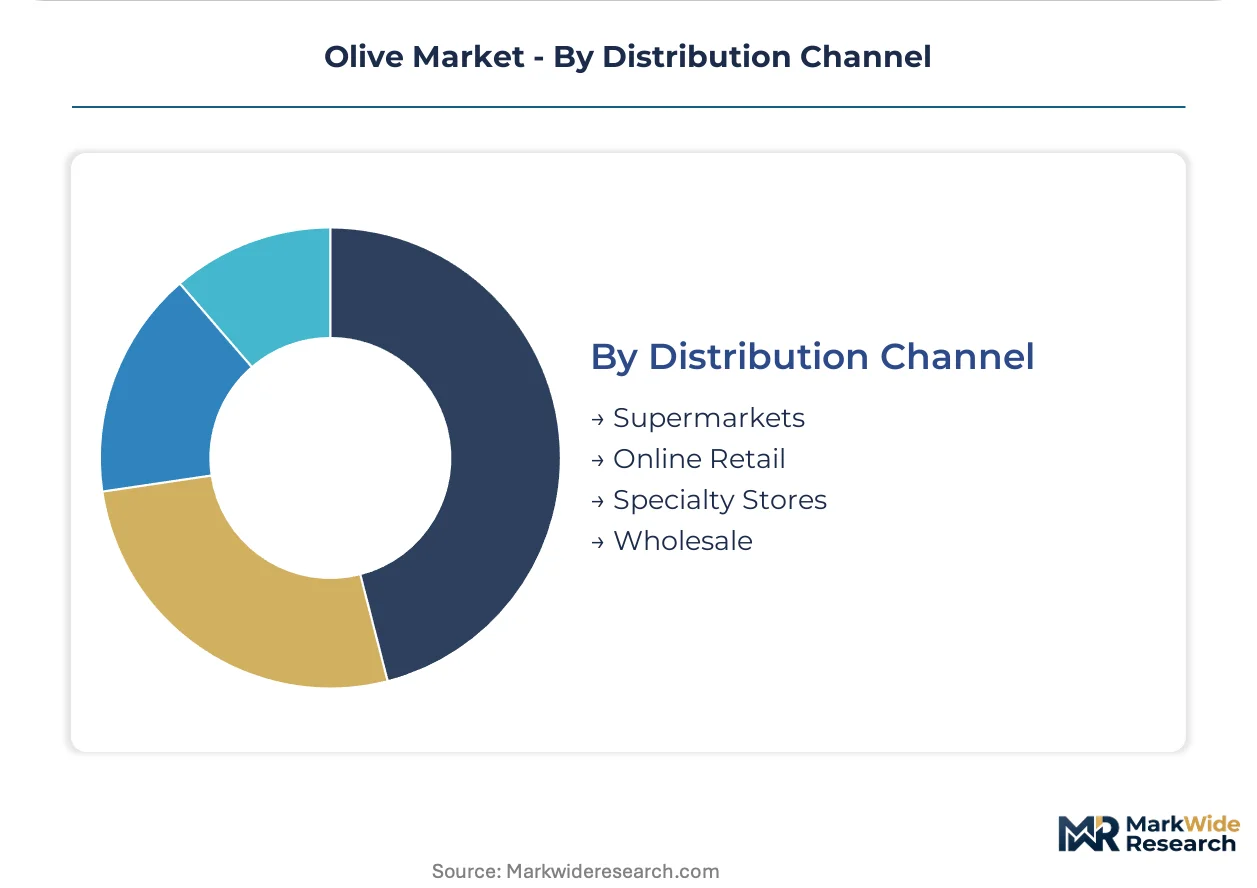
Channel segmentation reveals disintermediation pressure, with digital platforms and direct procurement compressing traditional wholesale margin capture.
- Specialty Stores:Mediterranean diet ingredient positioning drives North American and Northern European assortment expansion, with polyphenol-rich certified origin products commanding shelf space independent of mass-market price tiers. Staff training on harvest date and cultivar differentiation supports premium conversion.
- Online Retail:Direct-to-consumer platforms enable harvest-date specificity and cultivar traceability that bypass conventional distributor markups, with blockchain-based provenance logging supporting authentication claims that laboratory testing alone cannot defend.
- Supermarkets:Volume concentration for standard and economy tiers with private-label penetration.
- Wholesale:Traditional food-service distributor relationships facing displacement in premium urban markets.
Supermarkets retain volume concentration; Online Retail is expanding most quickly on traceability-enabled disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish buyers exhibit the lowest price elasticity for certified-origin extra virgin grades, while Indian and Southeast Asian food-service operators prioritize logistics efficiency over origin premiums. Mediterranean diet expansion in Northern Europe and North America sustains premium-tier demand despite harvest volatility. Climate-driven alternate bearing cycles in Andalusia create pricing asymmetries that arbitrageurs exploit across Atlantic and Pacific trade lanes.
Spain
Andalusian processing clusters in Jaén and Córdoba dominate bulk extra virgin supply and set global pricing benchmarks through cooperative aggregation. The EU F-Gas Regulation mandates ammonia-based cold-chain retrofits for extraction facilities, compressing margins for operators lacking capital reserves. Seville-based logistics hubs coordinate year-round export scheduling that buffers 30-40 percent harvest volume swings.
Italy
Puglian millers and Tuscan bottlers command origin premiums through DOP-certified cultivar specificity and polyphenol-standardized grades. EFSA health claim enforcement for olive polyphenol cardiovascular benefits drives supplement manufacturer demand for oleuropein concentrates. Bologna-Modena corridor laboratories concentrate HPLC-DAD analytical capacity, creating certification bottlenecks for new market entrants.
United States
California super-high-density orchards reduce per-acre labor inputs through mechanized harvesting systems, anchoring North American production autonomy. FDA and USDA grade standards enforce adulteration testing protocols that determine import access and domestic labeling legitimacy. Sacramento Valley processing infrastructure integrates real-time acidity monitoring to meet EU export compliance requirements.
India
Ayurveda-adjacent wellness positioning creates first-mover opportunities for hydroxytyrosol and olive leaf extract suppliers pending FSSAI novel food approvals. Mumbai and Bangalore specialty retailers expand Mediterranean diet ingredient assortments as urban consumer preference shifts toward polyphenol-rich functional foods. Domestic formulators remain dependent on Spanish and Italian bulk supply for extra virgin feedstock.
Germany
REACH compliance documentation requirements for olive-derived squalene and fatty acid esters drive formulator qualification of alternative Mediterranean suppliers. Hamburg and Bremen ports concentrate oleochemical import handling for cosmetics and personal care manufacturing. Berlin-based distributors face displacement from direct-to-restaurant procurement platforms connecting certified-origin producers with executive chefs.
Olive Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated millers compete against commodity packagers and specialty extract suppliers. The market fragments across origin-certified premium positions, private-label volume plays, and nutraceutical ingredient standardization. Three archetypes dominate: vertically controlled Mediterranean cooperatives, super-high-density orchard operators with mechanized harvesting, and REACH-registered oleochemical specialists. Competitive moves concentrate on cold-chain infrastructure upgrades for EU Green Deal compliance and blockchain-based provenance systems that compress quality-assurance timelines.
Among Spanish and Italian integrated millers, Deoleo and Borges International Group occupy positions that exemplify vertically controlled sourcing from Mediterranean cooperative networks. California Olive Ranch anchors the mechanized-production archetype through North American super-high-density orchard models. These three companies represent distinct strategic responses to climate-driven harvest volatility: cooperative aggregation for supply continuity, geographic diversification across Mediterranean crushing infrastructure, and domestic production autonomy through labor-saving orchard architecture.
| Leading Market Players |
|---|
| California Olive Ranch |
| Musco Family Olive Co. |
| Conagra Brands |
| Monini |
| Bell-Carter Foods |
| Deoleo |
| Borges International Group |
| Grupo SOS |
| Sovena Group |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Andalusian cooperatives and bulk traders lock in supply access while anchoring price visibility against climate-driven harvest volatility. These arrangements compress working-capital cycles for integrated millers and expose commodity packagers to spot-market swings when Spanish volumes contract.
Pricing Analysis
After-sales service contracts for polyphenol-certified grades drive lifetime value through recurring laboratory verification and origin-authentication renewals. Pricing stratifies across premium extra virgin, standard virgin, and economy refined tiers, with EFSA health claim certification and IOC chemical standards as primary differentiation drivers. Cost compression in standard tiers is intensifying as private-label penetration rises in North American supermarkets. Food-service operators exhibit highest price sensitivity, while specialty retailers and direct-to-restaurant platforms show lowest elasticity for certified-origin products.
Supply Chain Analysis
Inventory cycles extending twelve to eighteen months from harvest through bottling create working-capital intensity that favors well-capitalized operators. Supply concentrates in Spain, Italy, and Greece for bulk extra virgin feedstock, with California and Australia anchoring mechanized alternatives. Phosphate fertilizer, agricultural diesel, and glass packaging feed from concentrated Mediterranean and North African suppliers. Single-source vulnerability runs through Andalusian cooperative aggregation for global pricing benchmarks. Distribution runs through Seville and Bologna logistics hubs for European export, with direct-to-restaurant platforms disintermediating traditional wholesale channels in North American urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyphenol quantification services and blockchain-based provenance logging represent service-attach layers expanding faster than commodity oil sales, creating recurring revenue streams for technology-enabled operators.
For Market Incumbents: Shield margin position by deepening backward integration into crushing infrastructure across Mediterranean cooperative networks, and accelerate cold-chain retrofit completion ahead of EU F-Gas Regulation enforcement windows. Climate-driven harvest volatility from emerging super-high-density orchard operators in California and Australia threatens traditional supply continuity advantages. For New Entrants and Emerging Players: FSSAI novel food fast-tracks for hydroxytyrosol and olive leaf extract offer regulatory arbitrage into India's underpenetrated functional ingredient market. Target dietary supplement manufacturers seeking EFSA-compliant oleuropein concentrates above twenty percent purity, and pursue white-label supply partnerships with German and French cosmetics formulators facing REACH documentation gaps from incumbent Italian sources. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated millers with captive laboratory infrastructure and blockchain-enabled traceability systems. Long-term viability centers on operators capable of compressing quality-assurance timelines from two-week laboratory cycles to forty-eight-hour payment releases. Watch for inflection signals in polyphenol quantification talent scarcity creating acquisition premiums for Spanish and Portuguese analytical service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Retrofit | Ammonia-based and transcritical CO2 systems satisfy EU F-Gas Regulation mandates for Andalusian extraction facilities. |
| Blockchain Provenance Integration | Near-infrared spectroscopy coupled with distributed ledger logging compresses payment cycles to cooperative suppliers. |
| Super-High-Density Orchard Expansion | Mechanized harvesting systems in California reduce per-acre labor inputs and anchor North American production autonomy. |
| REACH Registration Dossier Completion | Pre-submitted ECHA registrations for olive-derived squalene qualify alternative Mediterranean suppliers for German and French formulators. |
| Direct-to-Restaurant Platform Launch | Digital procurement channels connect certified-origin producers with executive chefs in California and New York metropolitan areas. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, IOC trade statistics, and EFSA health claim registers. Interviews with cooperative mill managers, olive oil procurement leads at specialty retailers, cold-chain equipment suppliers, and nutraceutical formulation scientists inform supply-side and demand-side validation. Customs data from Spanish and Italian export authorities, USDA grade standard documentation, and REACH registration dossiers at ECHA provide secondary triangulation. Bottom-up volume modeling across cultivar-specific production clusters cross-checks against top-down value estimates from trade association aggregates.
Segmentation dimensions modeled include product grade tier, application end-use, packaging format, and distribution channel across the analysis window. CAGRs derive from trend extrapolation of harvest volume data, price elasticity coefficients by buyer archetype, and regulatory compliance cost trajectories. Forecast inputs incorporate climate-driven alternate bearing cycle patterns and mechanized harvesting adoption curves in non-Mediterranean production regions.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and stable FSSAI approval timelines for novel food ingredients; material deviation in regulatory stringency or harvest volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Dried Jujubes Market