
 North America Organic Fruits Market | 2026-2036
North America Organic Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
North America Organic Fruits Market Analytics
Direct-to-restaurant distribution is rewriting procurement patterns across the North America organic fruits landscape. Dole Food Company Inc leverages its integrated farm-to-port logistics to sustain volume contracts with major food service operators. SunOpta anchors its position through specialized organic berry processing and aseptic packaging capabilities. Driscoll's Inc differentiates via proprietary berry genetics and stringent field-level quality protocols that command premium placement.
Organic fruits comprise produce cultivated without synthetic pesticides, genetically modified organisms, or petroleum-based fertilizers, relying instead on composting, biological pest management, and crop rotation systems that maintain soil microbiome health. Their primary commercial purpose centers on supplying retail and food service channels with certified produce meeting USDA National Organic Program standards for residue thresholds and traceability. Berries command the strongest margin pools due to perishability-driven supply constraints and year-round greenhouse demand, while citrus benefits from extended shelf stability that reduces cold-chain cost exposure. Supermarkets dominate volume throughput, though online retail channels are capturing faster growth as subscription produce boxes normalize recurring organic purchases.
The USDA National Organic Program, EPA pesticide tolerance regulations, and Mexico's organic certification equivalency agreement with the United States collectively shape cross-border trade flows and label integrity requirements. California's state-level organic enforcement protocols exceed federal minimums, creating a dual-compliance burden that filters smaller growers from premium distribution channels. Stakeholders must monitor evolving equivalency negotiations between Mexican certifiers and the USDA, as any friction in mutual recognition would immediately disrupt the integrated North American supply base that currently underpins year-round organic fruit availability.
Market Dynamics
Cross-border supply integration between California's Central Valley and Mexico's Baja California growing belt is compressing seasonal price volatility while concentrating procurement leverage among vertically integrated distributors serving year-round food service contracts.
Growth Catalysts
- USDA National Organic Program certification expansion:Tightening residue thresholds are filtering conventional growers from premium channels, creating dedicated shelf space for certified organic produce in mainstream retail.
- Food service menu reformulation:Restaurant chains and institutional cafeterias are embedding organic fruit requirements into procurement specifications, locking in multi-year volume commitments.
- Greenhouse berry production:Controlled-environment agriculture in Mexico's Baja California belt is eliminating seasonal supply gaps, enabling consistent year-round availability for North American buyers.
Market Restraints
- Input cost volatility:Organic compost and biological pest management inputs carry price premiums 40-60% above synthetic alternatives, compressing grower margins during weather-stressed seasons.
- Geographic supply concentration:Over 70% of North American organic fruit volume originates from California and Baja California, exposing buyers to single-region climate and labor disruption risks.
- Regulatory friction:California's state-level organic enforcement protocols exceed federal USDA minimums, creating dual-compliance burdens that exclude smaller growers from premium distribution channels.
Strategic Opportunities
- Pacific Northwest expansion:Washington State's apple and cherry growing regions remain underpenetrated for organic conversion, offering land-bank opportunities for growers seeking climate diversification.
- Direct-to-institutional channels:K-12 school districts and university food service systems are mandating organic produce quotas, creating dedicated procurement pipelines outside conventional retail.
- Subscription produce box normalization:Recurring delivery models are capturing household buyers seeking traceability, bypassing supermarket margin extraction while building brand loyalty.
Industry Challenges
- Certification timeline compression:USDA organic transition periods require three years of documented synthetic-free cultivation, locking land out of premium pricing during conversion.
- Cold-chain capex intensity:Perishable organic berries require continuous temperature monitoring and rapid throughput infrastructure, demanding capital deployment that smaller distributors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Organic Fruits Market |
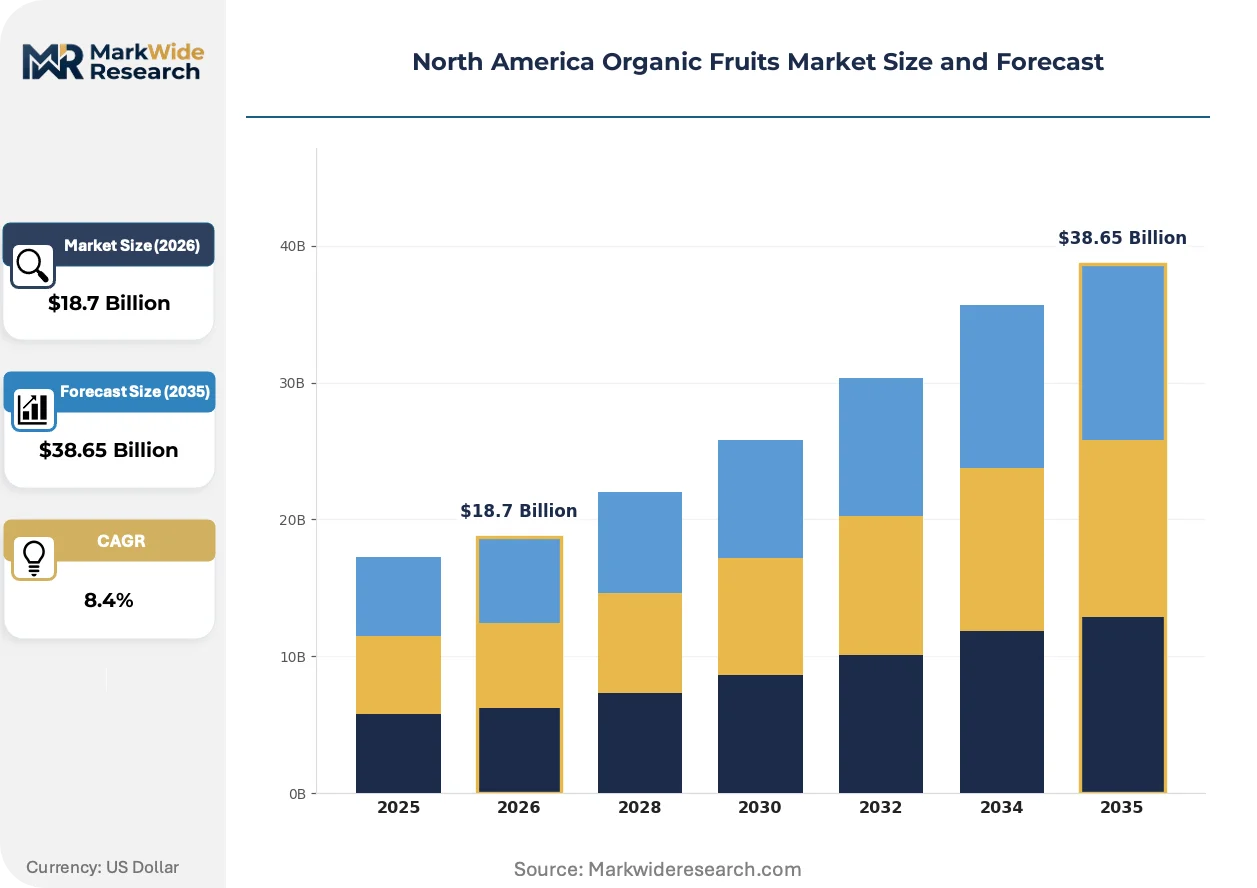
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apples, Bananas, Berries, Citrus Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Grocery Stores End User: Households, Restaurants, Cafes, Food Service Pricing Tier: Premium, Mid-range, Discount, Bulk |
| Companies Covered | Dole Food Company Inc, General Mills Inc., SunOpta, Driscoll's Inc., The Hain Celestial Group, Organics Unlimited, Taylor Farms, Calavo Growers Inc., Robinson Fresh Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Organic Fruits Market Evolving Landscape
Biological soil amendments and precision irrigation systems are displacing conventional cultivation practices across North American organic fruit operations. Field-level quality protocols and blockchain traceability are compressing information asymmetries between growers and buyers.
Biostimulant-based soil microbiome management is rendering obsolete traditional compost-heavy fertility programs in organic strawberry and raspberry operations. Large-scale greenhouse operators in Baja California are adopting these microbial inoculant systems to accelerate fruit set cycles. The technology is rendering obsolete the three-month lag between soil preparation and first harvest that constrained conventional organic production economics.
California's state-level organic enforcement protocols now exceed federal USDA National Organic Program minimums, creating a dual-compliance burden for growers seeking premium distribution access. The state's Department of Food and Agriculture mandates additional field inspection frequency and residue testing thresholds. Berry growers in the Central Valley are responding by segregating California-bound inventory from federal-compliant shipments to other states.
Subscription produce box services are capturing recurring household purchases that previously flowed through supermarket produce departments. These direct-to-consumer channels bypass traditional wholesale margin extraction while building traceability relationships between named growers and end buyers. The shift is most visible in urban coastal markets where consumers prioritize origin transparency over immediate availability.
North America Organic Fruits Market Segmentation
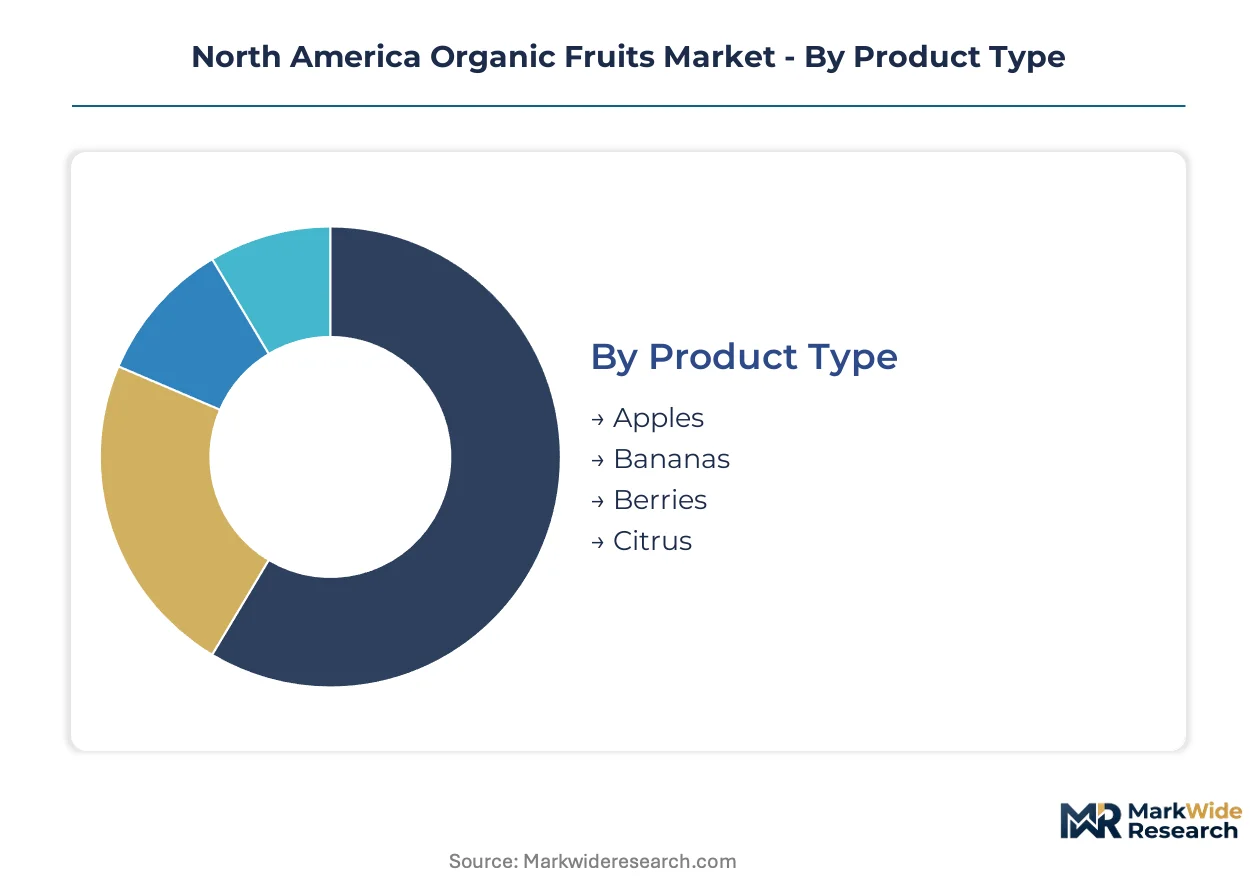
Segmentation in the North America organic fruits market reveals how certification tiers, channel structures, and end-use specifications create distinct competitive arenas. Procurement requirements diverge sharply between institutional food service buyers and household consumers, forcing suppliers to configure separate inventory and logistics systems.
Product Type:
Mature categories anchor volume throughput while emerging segments reshape margin structures across North American organic fruit supply chains.
- Apples:Long-established organic orchards in Washington State and Michigan's Lake Michigan shoreline supply varieties meeting dual USDA and state-level residue protocols. Demand concentrates in K-12 school district procurement programs and autumn seasonal retail promotions where shelf stability reduces cold-chain cost exposure.
- Bananas:Central American import corridors feed year-round North American consumption through ripening facilities in Gulf Coast and Southern California distribution hubs. Mexican organic certification equivalency agreements with the USDA enable seamless cross-border throughput into Texas and Arizona retail networks.
- Berries:Controlled-environment greenhouse operations in Baja California and California's Central Valley supply strawberries, raspberries, and blueberries with compressed harvest cycles. Perishability constraints command premium placement in direct-to-restaurant channels and subscription produce boxes.
- Citrus:Extended post-harvest durability supports ocean freight economics from Mexican and Texan growing regions into Midwest and Northeast population centers. California's state-level organic enforcement protocols exceed federal minimums, creating dual-compliant inventory segregation for in-state versus interstate shipments.
Apples retain volume leadership; berries hold the steepest expansion curve.
Distribution Channel:
Channel cost structures stratify sharply between capital-intensive cold-chain infrastructure and minimal-asset direct sales models.
- Supermarkets:Dominant throughput channel requiring certified organic produce departments with segregated receiving, storage, and display infrastructure. Chains operating across California face dual state-federal compliance verification at distribution center level.
- Online Retail:Subscription produce box models capture recurring household purchases with named-grower traceability bypassing wholesale margin extraction. Urban coastal markets in California, Washington, and British Columbia normalize recurring organic fruit delivery.
- Farmers' Markets:Direct producer-to-consumer sales with simplified certification documentation requirements under USDA farmer exemption thresholds. Seasonal concentration in Pacific Northwest and Northeast metropolitan areas.
- Grocery Stores:Independent and regional chains with flexible procurement specifications accommodating smaller organic fruit lot sizes excluded from national supermarket contracts. Mexican Baja California supply integration supports year-round inventory for Southwestern independents.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
End User:
End-use specifications diverge between traceability-demanding institutional buyers and price-sensitive household purchasers.
- Households:Individual and family consumption driving recurring purchase patterns through subscription services and conventional retail. California and Pacific Northwest urban markets show strongest origin transparency preferences.
- Restaurants:Fine-dining and fast-casual chains embedding organic fruit requirements into procurement specifications with multi-year volume commitments. Direct-to-restaurant distribution bypasses traditional wholesale layers.
- Cafes:Coffeehouse and juice bar segments with specialized organic berry and citrus demand for beverage and fresh preparation applications. Baja California greenhouse supply eliminates seasonal menu gaps.
- Food Service:Institutional cafeterias, hospital systems, and corporate dining operations mandating organic produce quotas under wellness and sustainability procurement policies. USDA National Organic Program certification filters conventional suppliers from contract eligibility.
Households retain volume leadership; food service holds the steepest expansion curve.
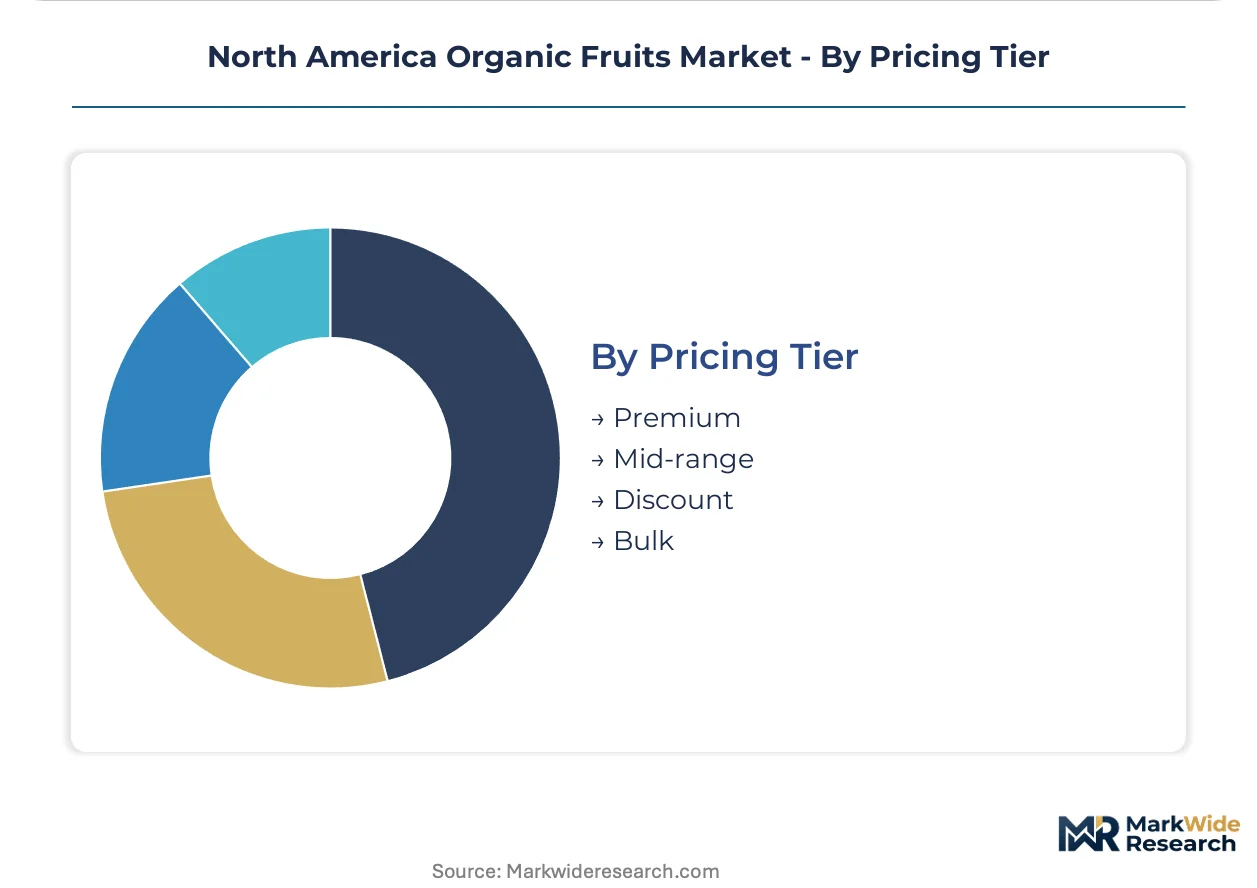
Pricing Tier:
Pricing stratification reflects certification grade, volume scale, and supply chain length from grower to final buyer.
- Premium:Proprietary genetics, field-level quality protocols, and named-origin traceability commanding placement in fine-dining and direct-to-consumer channels. Driscoll's and similar branded berry programs occupy this tier.
- Mid-range:USDA-certified organic produce meeting standard residue thresholds without proprietary variety or extended traceability documentation. Mainstream supermarket organic departments concentrate here.
- Discount:Organic certification compliance with minimal packaging, branding, or cold-chain investment. Farmers' markets and independent grocery stores in price-sensitive geographies.
- Bulk:Institutional volume contracts with simplified handling specifications and extended payment terms. K-12 districts and university food service systems negotiate multi-year commitments at this tier.
Mid-range retains volume leadership; premium holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and the Laredo-Colombia Solidarity International Bridge anchor North American organic fruit logistics, channeling Mexican greenhouse supply into US distribution networks while California's Central Valley rail spurs feed Midwest cold-chain corridors.
United States
California's Central Valley and Washington's Yakima Valley drive domestic organic fruit volume through K-12 procurement mandates and restaurant chain specifications. The USDA National Organic Program sets baseline certification standards, though California's Department of Food and Agriculture imposes stricter residue testing and inspection frequencies. Berry growers in Monterey County now segregate inventory streams to satisfy dual state-federal compliance requirements.
Mexico
Baja California's greenhouse belt eliminates seasonal supply gaps through controlled-environment strawberry and raspberry production serving year-round US contracts. Mexico's organic certification equivalency agreement with the USDA enables seamless cross-border label recognition, administered by SADER and certifiers accredited under the US-Mexico organic trade arrangement. Maneadero and San Quintín anchor the highest-density organic berry cluster in North America.
Canada
British Columbia's Fraser Valley and Ontario's Niagara Peninsula supply organic apples and tender fruit to domestic retailers and US border markets. Health Canada and the Canadian Food Inspection Agency enforce organic standards aligned with USDA equivalency, with the Safe Food for Canadians Regulations governing import verification. Vancouver's container terminal infrastructure supports re-export of Mexican organic produce to Asian markets.
North America Organic Fruits Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. Vertically integrated distributors with captive farm networks and cold-chain assets dominate volume contracts, while specialized organic processors and branded genetics holders capture premium placement. Three archetypes define competitive positioning: integrated farm-to-port operators, proprietary variety developers, and aseptic processing specialists. Consolidation pressure favors scale players with multi-year food service commitments, while smaller growers retreat into direct-to-consumer channels.
Within the integrated distribution tier, Dole Food Company Inc and Robinson Fresh Inc exemplify platform scale through cross-border logistics control. Driscoll's Inc occupies the proprietary genetics position, anchoring premium-tier berry placement through field-level quality protocols. SunOpta represents the processing specialization archetype, converting organic fruit inputs into shelf-stable ingredients for branded food manufacturers.
| Leading Market Players |
|---|
| Dole Food Company Inc |
| General Mills Inc. |
| SunOpta |
| Driscoll's Inc. |
| The Hain Celestial Group |
| Organics Unlimited |
| Taylor Farms |
| Calavo Growers Inc. |
| Robinson Fresh Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Baja California's controlled-environment greenhouse belt is compressing per-unit economics for organic berry producers while simultaneously strengthening procurement leverage among vertically integrated distributors serving multi-year food service contracts. This utilization dynamic forces smaller growers toward direct-to-consumer channels or volume discount acceptance, reshaping margin distribution across the North American organic fruit value chain.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with K-12 districts and university food service systems negotiating multi-year commitments at bulk rates while premium placement in fine-dining channels commands proprietary-genetics surcharges. Price differentiation rests on certification grade and named-origin traceability, with California's dual state-federal compliance burden adding a compliance-premium layer absent from federal-only shipments. Pricing pressure stems from input cost volatility in organic compost and biological pest management, which carry premiums above synthetic alternatives. Household subscribers through produce box services show least price sensitivity, while independent grocery stores in price-sensitive geographies exhibit highest elasticity.
Supply Chain Analysis
Single-region climate exposure dominates supply chain risk, with over seventy percent of North American organic fruit volume originating from California and Baja California, exposing buyers to synchronized weather and labor disruption. Geographic supply concentration centers on the United States and Mexico, with Canadian re-export hubs adding tertiary nodes. Raw material dependencies include organic compost, biological pest control inputs, and precision irrigation infrastructure. Distribution runs through vertically integrated farm-to-port operators controlling cross-border cold-chain corridors from the Port of Long Beach and Laredo-Colombia Solidarity International Bridge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where subscription produce box normalization and direct-to-restaurant traceability services expand faster than commodity fruit throughput, rewarding players who capture recurring revenue layers beyond one-time sales.
For Market Incumbents: Pre-empt margin compression in bulk-tier institutional contracts by deepening backward integration into Baja California greenhouse capacity and accelerating proprietary genetics pipelines that command premium placement. Defend against emerging controlled-environment agriculture entrants by locking multi-year food service volume commitments before seasonal supply gaps close entirely. Certification investment in California's dual-compliance protocols filters smaller competitors from premium distribution access.
For New Entrants and Emerging Players: Pursue underpenetrated organic conversion in Washington State's Yakima Valley apple and cherry regions, where land-bank opportunities offer climate diversification outside California-Baja concentration. Target direct-to-institutional channels in K-12 districts mandating organic produce quotas, bypassing supermarket margin extraction entirely. A named-grower traceability go-to-market angle captures urban coastal household buyers prioritizing origin transparency over immediate availability.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap distributors with captive farm networks and cold-chain assets, as consolidation pressure favors scale players with multi-year food service commitments. Long-term viability over a five-to-ten year window hinges on cross-border logistics control and greenhouse production capacity. Watch for friction in USDA-Mexico organic certification equivalency negotiations as the critical inflection signal that would immediately disrupt integrated North American supply bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Greenhouse Capacity Expansion | Baja California controlled-environment operations eliminate seasonal supply gaps for year-round berry contracts. |
| Backward Integration into Farm Networks | Captive organic acreage secures volume commitments from restaurant chains and institutional cafeterias. |
| Dual-Compliance Certification Investment | California state-level protocols exceeding USDA minimums filter competitors from premium distribution channels. |
| Direct-to-Restaurant Channel Development | Bypassing wholesale layers captures margin pools in fast-casual and fine-dining procurement specifications. |
| Subscription Produce Box Launch | Recurring delivery models build traceability relationships between named growers and urban coastal households. |
Research Methodology
A standing panel of organic fruit procurement directors at restaurant chains, food service operators, and supermarket category buyers provided ongoing calibration against operating reality throughout the study. Primary interviews with greenhouse operators in Baja California, Central Valley berry growers, and cold-chain logistics specialists were triangulated against secondary validation from USDA National Organic Program certification databases, California Department of Food and Agriculture inspection records, and Mexican SADER equivalency agreement documentation. Bottom-up volume modeling across product type, distribution channel, and end-use segments was cross-checked against top-down market sizing derived from customs trade flows and retail audit data.
Scenario-bracketing framed the analytical approach, with sensitivity testing across regulatory friction, input cost volatility, and climate disruption assumptions over the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user, and pricing tier, with additional granularity on certification grade and geographic supply origin. CAGRs were derived from trend extrapolation adjusted for structural shifts in procurement patterns and supply chain integration, incorporating greenhouse production cycle compression and subscription service penetration as industry-specific forecast inputs.
Sensitivities concentrate around equivalency negotiations between Mexican certifiers and the USDA, input cost spikes in biological pest management, and synchronized climate events in California-Baja production zones. Forecasts reflect documented assumptions on certification timeline compression and cold-chain infrastructure deployment that could accelerate or delay market development. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
GCC Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Global Hass Avocado Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Global Fresh Berries Market