
 Global Pet Companion Robots Market | 2026-2036
Global Pet Companion Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Companion Robots Market Outlook
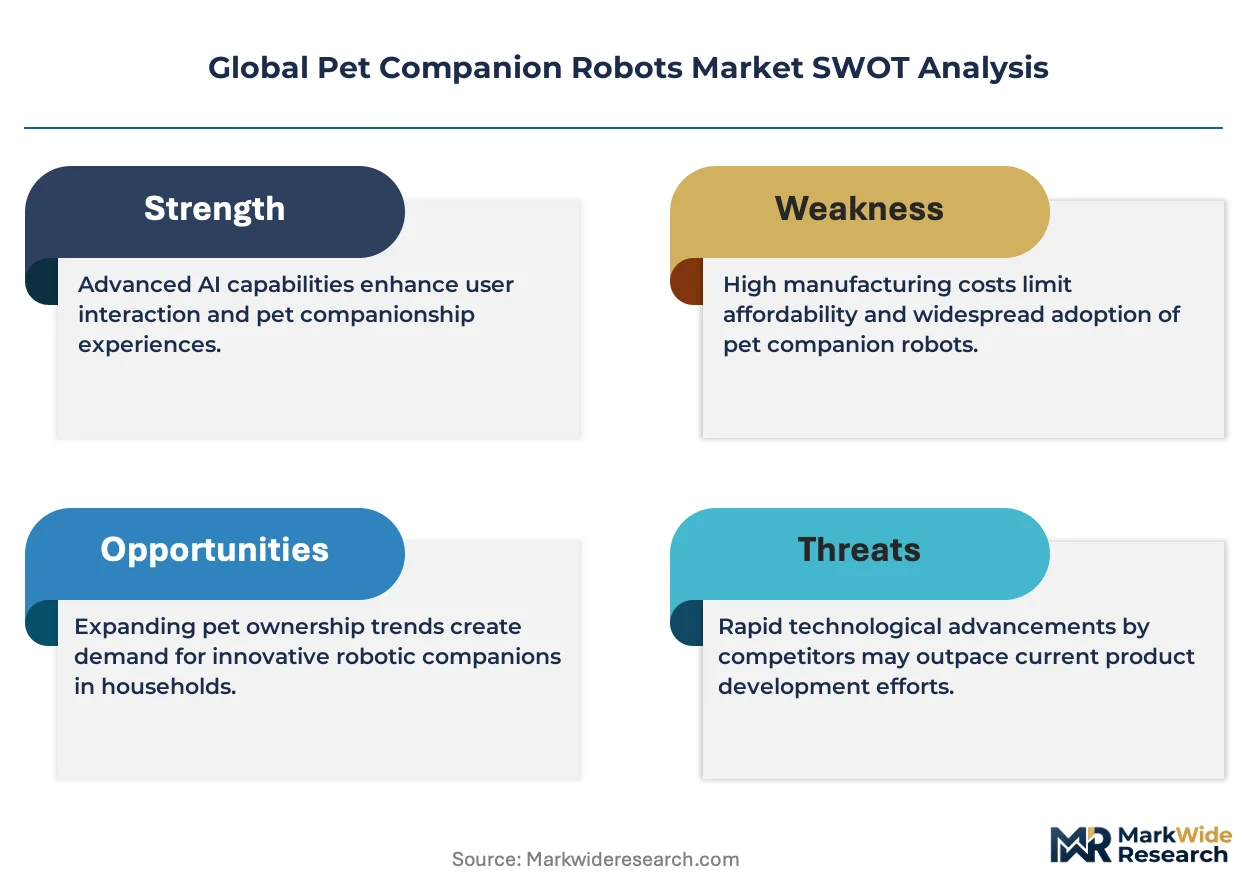
A shortage of embedded systems engineers with mechatronics training is reorganizing production timelines across the industry. Sony Group Corporation leverages its legacy in sensor miniaturization to sustain premium positioning in interactive robots. Elephant Robotics anchors its competitive stance through open-source hardware architectures that lower barriers for developers. Beijing Keyi Technology dominates domestic manufacturing scale while navigating export certification complexity.
Pet companion robots are electromechanical systems integrating servo motors, lithium-polymer power cells, and edge-computing processors to simulate responsive animal behaviors for household or clinical environments. Units typically operate on 12-24V DC with Wi-Fi or Bluetooth Low Energy connectivity for remote command relay. Interactive Robots capture the dominant margin pool due to emotional attachment mechanics and repeat firmware engagement, while Monitoring Devices represent the fastest-expanding category as veterinary clinics adopt remote diagnostic workflows. Voice Interaction features concentrate R&D spending among premium-tier developers, whereas Feeding Automation segments compete primarily on unit cost and platform interoperability.
The EU AI Act and CE marking framework impose algorithmic transparency requirements on autonomous pet devices sold across Europe, while the FCC in the United States governs radio-frequency emissions for wireless-enabled units. Japan's METI sets voluntary safety guidelines that frequently prefigure mandatory standards elsewhere. Stakeholders must track whether emerging product liability doctrines assign fault to manufacturers for animal stress responses triggered by robotic interaction patterns.
Market Dynamics
Algorithmic transparency mandates under the EU AI Act are forcing hardware developers to redesign sensor fusion architectures and document decision pathways for autonomous pet interaction systems.
Growth Catalysts
- EU AI Act compliance frameworks:Mandatory algorithmic documentation for autonomous devices sold across Europe is creating certification-driven demand for transparent robotic architectures.
- Veterinary remote diagnostics:Clinics in Germany and Japan are deploying robotic monitoring systems to extend post-operative observation beyond physical facility hours.
- Edge-computing processor miniaturization:Advances in low-power neural inference chips enable real-time behavioral simulation without cloud dependency.
Market Restraints
- Lithium-polymer cell supply concentration:Battery pack sourcing clusters in East Asian manufacturing hubs expose producers to logistics volatility and input cost swings.
- CE marking timeline friction:Extended conformity assessment periods for autonomous pet devices delay European market entry by six to twelve months against comparable consumer electronics.
- Human-animal bond substitutes:Traditional pet ownership retains cultural primacy in markets with accessible veterinary infrastructure and flexible housing policies.
Strategic Opportunities
- Japan's aging household penetration:Demographic compression and high companion animal density create addressable demand for social robotics in metropolitan prefectures.
- Telehealth-veterinary convergence:Integration of robotic monitoring data with remote consultation platforms opens recurring-revenue service models.
- India's BIS standards evolution:Emerging national safety protocols for electronic pet devices offer first-mover positioning as formal certification pathways crystallize.
Industry Challenges
- Embedded mechatronics talent scarcity:Shortages of engineers trained in servo motor control, sensor fusion, and real-time operating systems compress product development schedules.
- Multi-jurisdictional certification stacking:Simultaneous navigation of FCC emissions rules, CE marking requirements, and METI voluntary guidelines fragments regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Companion Robots Market |
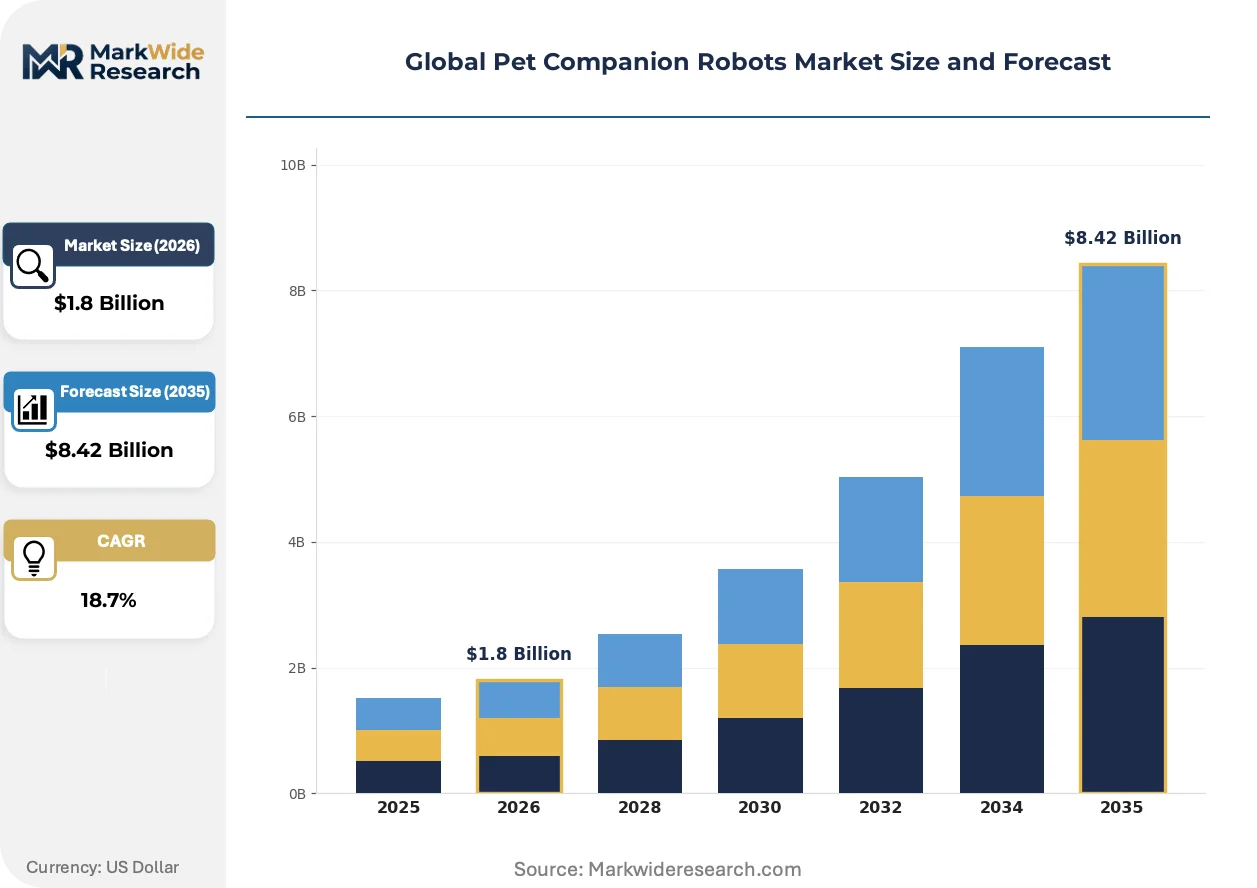
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Robots, Automated Feeders, Monitoring Devices, Cleaning Robots End User: Pet Owners, Veterinary Clinics, Pet Sitters, Research Institutions Features: Voice Interaction, Remote Surveillance, Activity Tracking, Feeding Automation Distribution Channel: Online Retailers, Specialty Pet Stores, Supermarkets, Direct Sales |
| Companies Covered | Yukai Engineering, Elephant Robotics, Sony Group Corporation, Petoi Corporation, Beijing Keyi Technology, Ageless Innovation, Casio, WowWee Group Limited, Tombot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Companion Robots Market Strategic Shifts
Hardware architectures are diverging between premium interactive systems and cost-optimized monitoring devices, while regulatory documentation requirements reshape firmware development workflows.
Edge-based behavioral inference is bifurcating the processor market. High-end companion robots deploy dedicated neural accelerators for real-time emotional response generation. Veterinary monitoring devices prioritize power efficiency over computational depth. This technological split is compressing mid-tier positioning and forcing vendors to commit to either premium interaction fidelity or clinical utility specialization.
The EU AI Act's algorithmic transparency provisions are restructuring firmware development practices. Developers must now maintain auditable decision logs for autonomous movement and vocalization triggers. Premium interactive robot segments face the heaviest documentation burden, with some manufacturers pre-emptively withdrawing complex behavioral models from European distribution.
Subscription-based firmware engagement is displacing one-time hardware transactions among premium-tier buyers. Clinics and multi-pet households in Japan and Germany now prioritize vendors offering continuous behavioral library updates. This consumption-pattern shift rewards developers with captive cloud infrastructure and compresses margins for hardware-only competitors lacking service attach rates.
Global Pet Companion Robots Market Segmentation
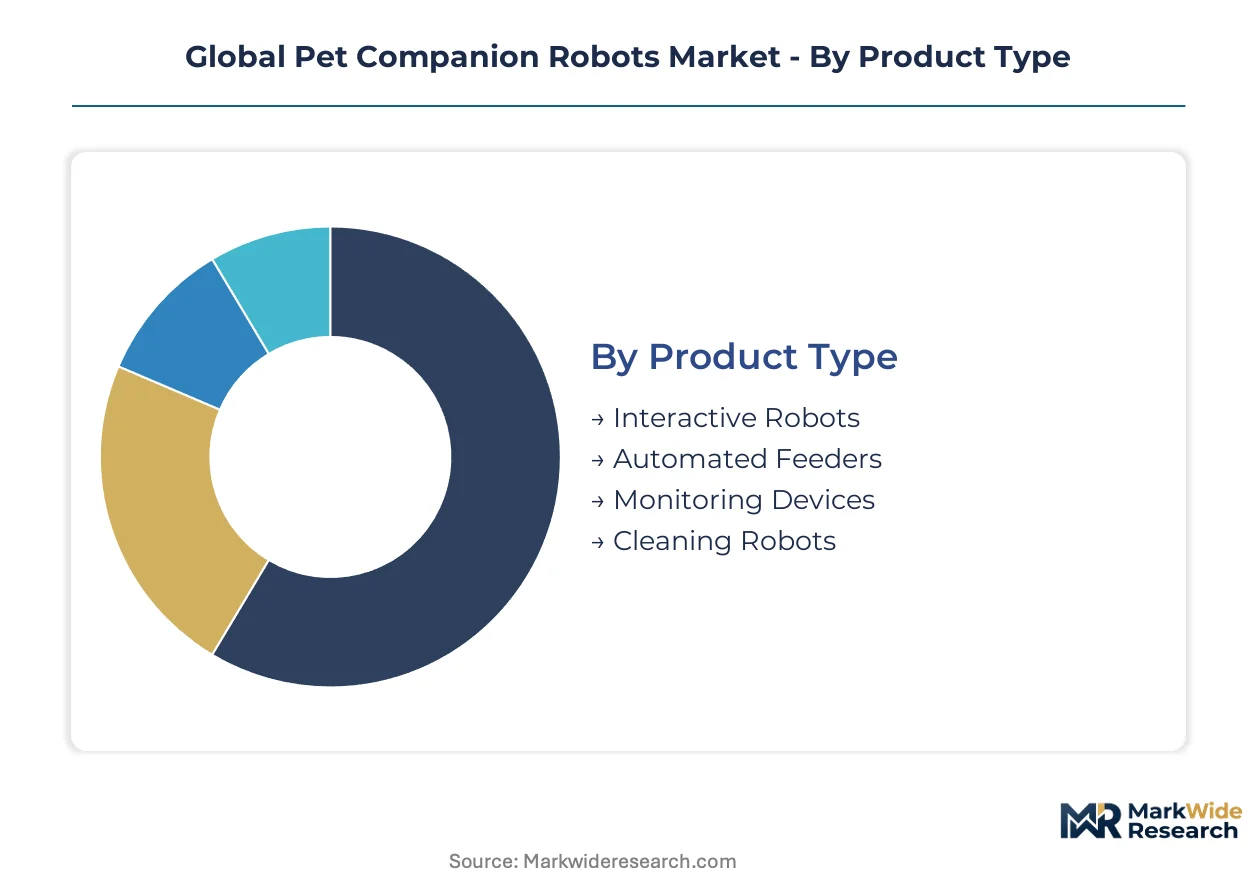
Pet companion robots fragment across four distinct category axes. Product architecture determines margin structure and regulatory burden. End-user concentration shapes distribution economics and service attach rates.
Product Type:
Traditional pet care substitutes exert uneven pressure across product categories, with passive monitoring devices facing the weakest displacement threat from conventional ownership models.
- Interactive Robots:Electromechanical systems integrate servo motors, edge-computing processors, and sensor arrays to simulate responsive animal behaviors. Demand concentrates in Japanese metropolitan prefectures where aging demographics and high companion animal density create addressable need for social robotics. Firmware subscription models now displace one-time hardware transactions among premium-tier buyers.
- Monitoring Devices:Units prioritize power efficiency and clinical data relay over computational depth, typically operating on 12-24V DC with Wi-Fi or Bluetooth Low Energy connectivity. Veterinary clinics in Germany deploy these systems to extend post-operative observation beyond physical facility hours, driving the steepest category expansion curve.
- Automated Feeders:Cost-optimized dispensing mechanisms compete primarily on unit price and platform interoperability rather than behavioral simulation depth.
- Cleaning Robots:Specialized units address pet hair accumulation and dander management in household environments with limited clinical crossover.
Interactive Robots retain volume leadership; Monitoring Devices hold the steepest expansion curve.
End User:
Procurement sophistication varies sharply across customer types, with institutional buyers demanding certification documentation that consumer channels ignore.
- Pet Owners:Individual purchasers in Japan and Germany now prioritize vendors offering continuous behavioral library updates, rewarding developers with captive cloud infrastructure.
- Veterinary Clinics:Clinical facilities require CE-marked autonomous devices with algorithmic transparency documentation under EU AI Act mandates. Remote diagnostic workflow integration drives hardware selection criteria.
- Pet Sitters:Intermittent-use operators favor lower capital outlay and simplified onboarding over advanced feature depth.
- Research Institutions:Academic and commercial R&D facilities source units for behavioral studies and sensor validation protocols.
Veterinary Clinics command the highest per-unit spend; Pet Owners deliver the broadest addressable base.
Features:
Development resource allocation concentrates where emotional attachment mechanics enable recurring revenue conversion.
- Voice Interaction:Natural language processing subsystems require dedicated neural accelerators for real-time emotional response generation. Premium-tier developers concentrate R&D spending here despite the heaviest EU AI Act documentation burden.
- Remote Surveillance:Camera and microphone arrays with cloud relay functionality serve clinical monitoring use cases and absent-owner reassurance.
- Activity Tracking:Accelerometer and gyroscope fusion enables behavioral pattern logging for health anomaly detection.
- Feeding Automation:Scheduling and portion control mechanisms compete on platform interoperability with existing smart home ecosystems.
Voice Interaction captures premium pricing; Remote Surveillance expands most quickly into veterinary workflows.
Distribution Channel:
Channel selection determines regulatory exposure and customer education burden for complex autonomous systems.
- Online Retailers:E-commerce platforms aggregate demand across geographies but complicate CE marking compliance verification for EU-bound shipments.
- Specialty Pet Stores:Staff-assisted consultation environments suit high-consideration interactive robot purchases requiring feature explanation.
- Supermarkets:Mass retail channels move cost-optimized feeding automation and cleaning units with limited service attach potential.
- Direct Sales:Manufacturer-controlled channels enable veterinary clinic relationship management and subscription service bundling.
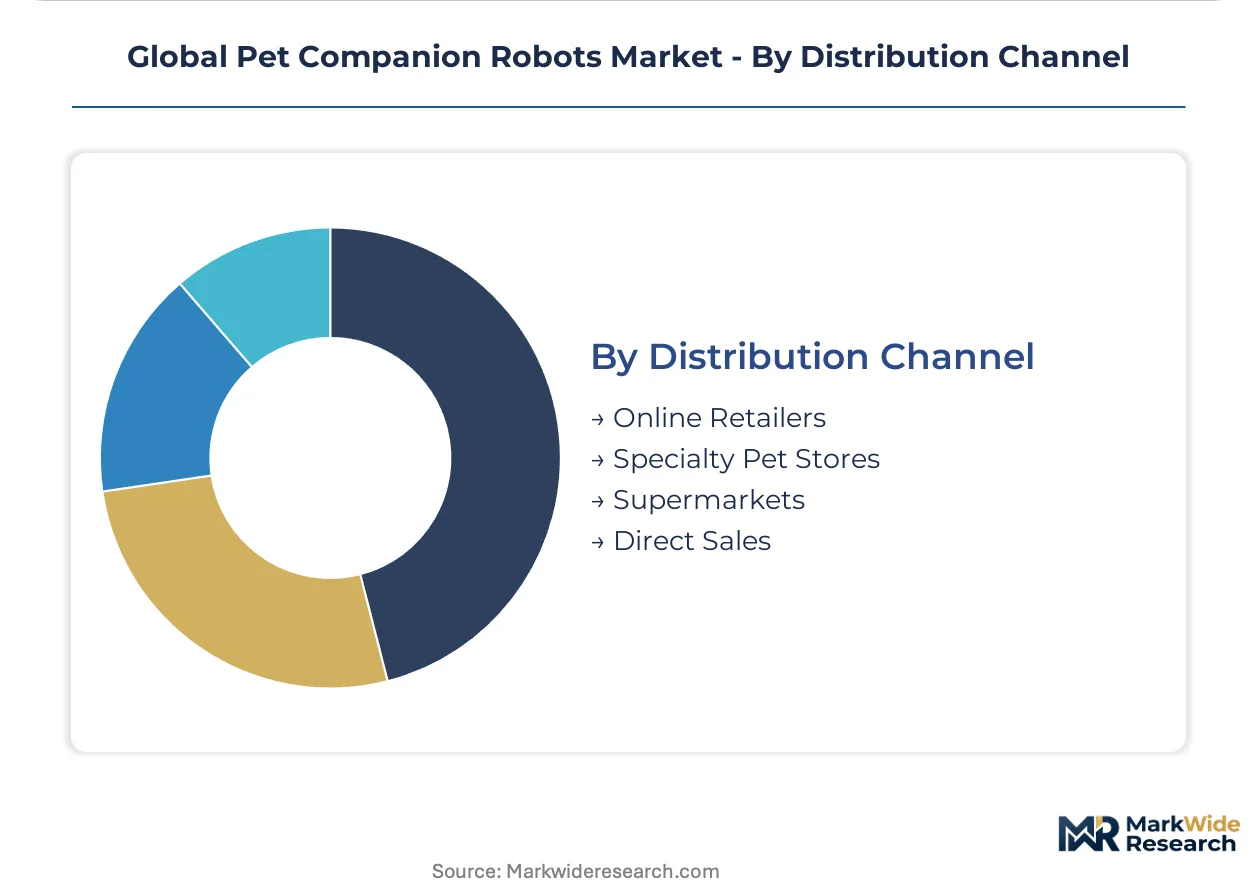
Online Retailers aggregate the widest selection; Direct Sales secure the highest service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI voluntary safety guidelines in Japan frequently prefigure mandatory standards adopted by regulators elsewhere, positioning Japanese technical protocols as the de facto global benchmark for autonomous pet device certification.
Japan
Aging demographics and high companion animal density in metropolitan prefectures create concentrated demand for social robotics. METI guidelines on autonomous device safety shape firmware development practices across the industry. Tokyo and Osaka anchor domestic manufacturing clusters where sensor miniaturization expertise feeds into premium interactive robot production.
Germany
Veterinary clinics deploy robotic monitoring systems to extend post-operative observation beyond facility hours. CE marking requirements under the EU AI Act impose algorithmic transparency mandates on autonomous pet devices sold across Europe. Munich and Stuttgart host engineering centers where embedded mechatronics talent concentrates for servo motor control development.
United States
FCC radio-frequency emissions rules govern wireless-enabled units for remote command relay functionality. Research institutions source units for behavioral studies and sensor validation protocols. Boston and San Francisco Bay Area clusters concentrate venture funding for edge-computing processor startups serving companion robot applications.
China
Domestic manufacturing scale advantages support cost-optimized automated feeder and cleaning robot production. Export certification complexity for CE marking and FCC compliance fragments regulatory affairs bandwidth for producers. Shenzhen and Dongguan electronics manufacturing hubs concentrate lithium-polymer cell integration and Wi-Fi module sourcing.
India
Emerging BIS standards evolution for electronic pet devices offers first-mover positioning as formal certification pathways crystallize. Pet owner demand concentrates in metropolitan areas with flexible housing policies limiting traditional companion animal ownership. Bangalore and Hyderabad technology corridors attract firmware developers for platform interoperability solutions.
Global Pet Companion Robots Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with premium interactive robot developers commanding pricing power through captive cloud infrastructure while cost-optimized monitoring device manufacturers compete on unit economics and platform interoperability. The vendor base separates into three archetypes: sensor-integrated systems houses, open-source hardware platforms, and contract manufacturing scale operators. Competitive moves concentrate on strategic partnerships for firmware subscription bundling and geographic expansion into certification-emerging markets.
Within the integrated systems tier, Sony Group Corporation and Casio represent legacy electronics conglomerates leveraging sensor miniaturization heritage. Elephant Robotics exemplifies the open-source hardware archetype that lowers developer barriers. Beijing Keyi Technology anchors the manufacturing-scale tier navigating multi-jurisdictional certification complexity.
| Leading Market Players |
|---|
| Yukai Engineering |
| Elephant Robotics |
| Sony Group Corporation |
| Petoi Corporation |
| Beijing Keyi Technology |
| Ageless Innovation |
| Casio |
| WowWee Group Limited |
| Tombot |
| Others |
Value Chain & Pricing Dynamics
Edge-computing processor substitution for cloud-dependent inference engines simultaneously shifts procurement geography toward Taiwan and South Korea semiconductor foundries and compresses premium-tier pricing power by reducing recurring cloud subscription attach rates.
Pricing Analysis
Price spreads between Japanese premium interactive robots and Chinese cost-optimized monitoring devices exceed threefold at retail. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by neural accelerator inclusion and CE marking documentation depth. Pricing pressure stems from lithium-polymer cell cost volatility and extended EU AI Act compliance timelines. Veterinary clinics demonstrate lowest price sensitivity due to reimbursement-adjacent procurement budgets, while individual pet owners in India and Southeast Asia concentrate demand in economy tiers.
Supply Chain Analysis
Inventory strategy bifurcates between just-in-time component flows for consumer-facing interactive robots and strategic stockpiling of lithium-polymer cells by veterinary monitoring device manufacturers. Supply concentrates in China for battery pack integration and mechanical assembly, Japan for sensor miniaturization, and Taiwan for neural inference chip fabrication. Raw material dependencies span lithium carbonate from Chile and Australia, rare earth magnets from China, and precision servo motors from Japanese suppliers. Single-source vulnerability in edge-computing processor supply creates concentration risk. Distribution runs through direct manufacturer channels for clinical accounts and online retailers for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as firmware subscription models splinter demand between cloud-native developers and hardware-centric manufacturers, creating niche positioning for specialized veterinary workflow integrators.
For Market Incumbents: Consolidate captive cloud infrastructure advantages by acquiring edge-computing optimization specialists before neural accelerator commoditization erodes premium positioning. Deepen backward integration into lithium-polymer cell supply through long-term offtake agreements with South Korean producers. Prioritize CE marking documentation investment as EU AI Act enforcement tightens algorithmic transparency requirements.
For New Entrants and Emerging Players: Lead with India's emerging BIS certification pathway to establish first-mover positioning before formal standards crystallize and incumbent documentation advantages solidify. Target veterinary clinic monitoring device segments where procurement sophistication favors specialized workflow integration over brand heritage. Deploy direct sales channels with bundled telehealth platform partnerships to circumvent retail margin compression.
For Investors and Strategic Acquirers: EU AI Act full enforcement reshapes the acquisition landscape by devaluing complex behavioral models lacking auditable decision logs and elevating transparent architecture developers. Long-term viability centers on recurring-revenue service attach rates rather than hardware transaction volumes. Target acquisition archetypes include firmware subscription platforms with captive cloud infrastructure and veterinary workflow integration specialists. Watch for lithium-polymer supply contract renegotiation announcements as inflection indicators for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU AI Act compliance documentation accelerates European market entry for transparent robotic architectures. |
| Veterinary Workflow Integration | Telehealth platform partnerships with German and Japanese clinics create recurring-revenue service models. |
| Edge-Computing Processor Sourcing | Taiwan and South Korea foundry relationships reduce cloud dependency and subscription attach vulnerability. |
| Firmware Subscription Platform | Continuous behavioral library updates displace one-time hardware transactions among premium-tier Japanese buyers. |
| India BIS Standards Engagement | First-mover positioning in emerging certification pathways captures metropolitan pet owner demand before incumbent entry. |
Study Parameters
A standing panel of robotics firmware developers, veterinary clinic procurement managers, embedded systems engineers, and CE marking consultants provided ongoing calibration against primary interview findings with secondary validation from METI technical guideline documents, EU AI Act regulatory filings, FCC equipment authorization databases, and BIS standards development committee records. Bottom-up unit shipment estimates triangulated against top-down addressable household projections across Japanese metropolitan prefectures and German veterinary clinic counts.
Consistency checks validated volume and value outputs against neural accelerator chip foundry capacity disclosures, lithium-polymer cell production forecasts, and telehealth platform partnership announcements. Segmentation modeling spanned product architecture, end-user procurement sophistication, feature complexity tiers, and regional regulatory cluster alignment. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable social robotics categories. Forecast inputs incorporated veterinary remote diagnostic workflow penetration rates and firmware subscription attach rate assumptions.
Forecasts assume regulatory continuity in EU AI Act implementation timelines and METI voluntary guideline stability; material policy shifts would require re-modeling. Revision becomes warranted when lithium-polymer supply contract renegotiation frequency or BIS standards enforcement intensity crosses thresholds indicating structural cost or market access disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Car Seat Market
Pet Care Products
Japan Dog Food Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Aquarium Market
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Cat Bed Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Europe Pet Food Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Dog Clippers Market