
 Poland Pet Food Market | 2026-2036
Poland Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Pet Food Market Insights
Aftermarket nutritional consulting and subscription-based diet planning is reshaping how Polish pet owners allocate spending across the care continuum. Mars Incorporated leverages its veterinary health network to sustain direct-to-consumer engagement. Nestlé Purina anchors premium positioning through specialized therapeutic formulations. VAFO Group dominates private-label manufacturing for Polish and Central European retailers.
Poland pet food comprises formulated nutritional products manufactured through extrusion, canning, or cold-pressing processes, with macronutrient profiles calibrated to species-specific metabolic requirements and life-stage needs. Dry food remains the volume backbone due to shelf stability and cost efficiency in mass retail. Wet food commands margin premiums through palatability and hydration benefits that resonate with aging pet demographics. Functional ingredient formulations represent the fastest-expanding margin pool as owners seek digestive, joint, and coat-health benefits.
Poland's Chief Veterinary Officer enforces EU Regulation 183/2005 on feed hygiene, while Białystok and Poznań veterinary inspectorates conduct regional compliance audits that shape market access for imported products. The EU F-Gas Regulation indirectly affects cold-chain logistics for wet food distribution. Stakeholders must monitor evolving EU packaging sustainability mandates and veterinary channel consolidation to anticipate where formulation investment and route-to-market control will confer durable advantage.
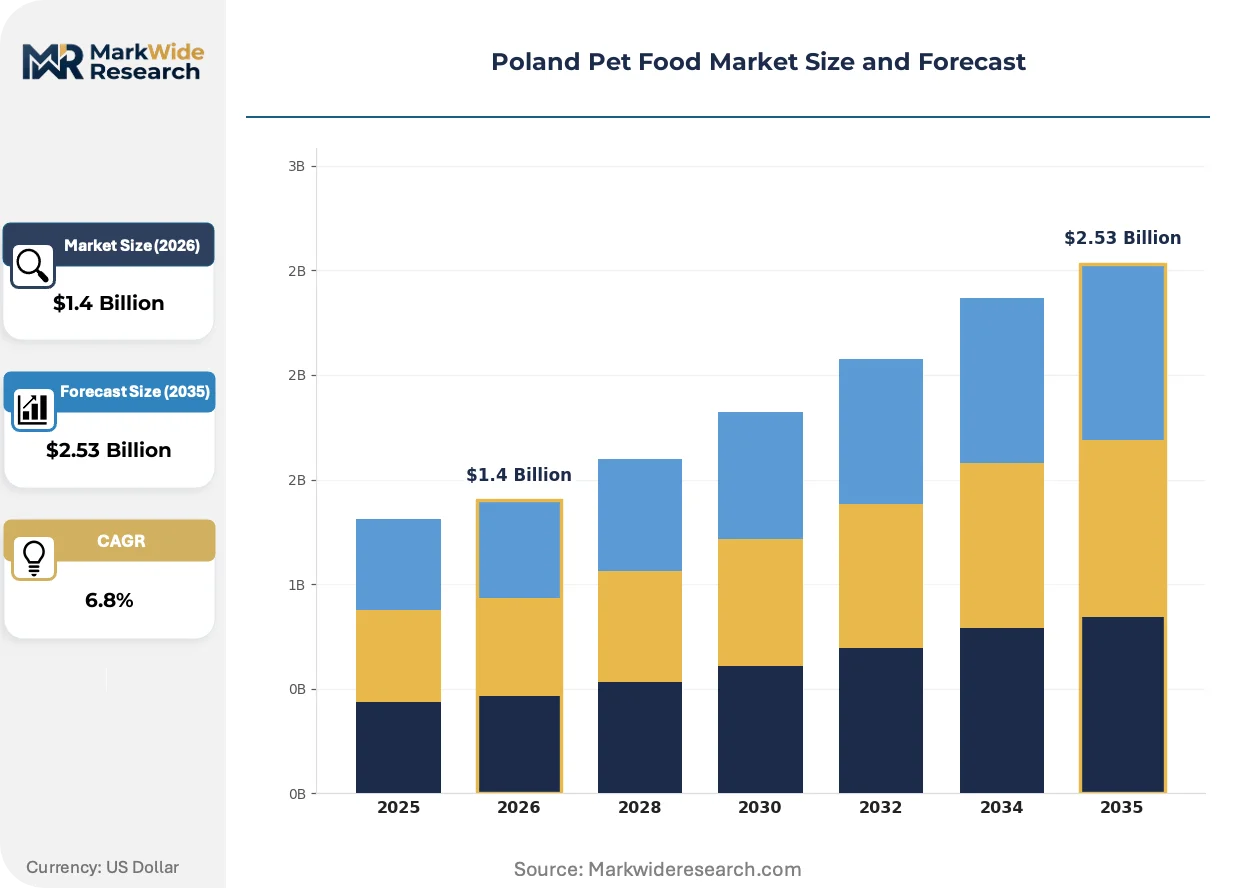
Market Dynamics
Veterinary channel consolidation under Poland's Chief Veterinary Officer is compressing route-to-market autonomy and forcing manufacturers to rebuild distribution relationships around inspection-compliant logistics networks.
Growth Catalysts
- EU Regulation 183/2005 feed hygiene mandates:Mandatory HACCP protocols for all Polish pet food facilities are accelerating capital investment in automated extrusion and canning lines that reduce microbial risk.
- Masovian Voivodeship urban density:Warsaw's concentrated pet-owning households generate sufficient volume to justify dedicated cold-chain infrastructure for premium wet food distribution.
- Cold-pressing technology adoption:Lower-temperature processing preserves thermolabile vitamins and enzymes, attracting owners of senior pets with compromised digestive function.
Market Restraints
- Protein input cost volatility:Polish pet food manufacturers depend on imported poultry meal and fish hydrolysates, exposing margin structures to Black Sea grain corridor disruptions and Baltic freight rate swings.
- Veterinary inspectorate concentration:Białystok and Poznań regional offices handle the majority of import compliance audits, creating inspection bottlenecks that delay new product market entry.
- Wet food cold-chain dependency:EU F-Gas Regulation phase-down of hydrofluorocarbon refrigerants forces fleet retrofitting costs onto distributors serving premium segments.
Strategic Opportunities
- Subcarpathian and Podlaskie Voivodeships:These eastern regions show rising pet ownership rates with limited specialty retail penetration, offering first-mover advantage for direct-to-veterinary distribution models.
- Subscription-based diet planning:Digital platforms that integrate veterinary diagnostic data with automated reordering are capturing recurring revenue streams currently untapped by mass retail.
- EU packaging sustainability mandates:Pending recycled content requirements for flexible packaging create incentive for early investment in mono-material structures that simplify end-of-life sorting.
Industry Challenges
- Veterinary nutritionist staffing gaps:Qualified formulators capable of translating metabolic research into species-specific extrusion parameters remain scarce in Polish technical universities.
- Legacy ERP integration with traceability systems:Mid-sized manufacturers struggle to retrofit batch-recording infrastructure that satisfies both EU Regulation 183/2005 and retailer-specific audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Pet Food Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Animal Type: Dogs, Cats, Fish, Birds Distribution Channel: Supermarkets, Pet Stores, E-commerce, Specialty Shops Ingredient Type: Meat-Based, Grain-Free, Organic, Functional |
| Companies Covered | Mars Incorporated, Colgate-Palmolive Company (Hill's Pet Nutrition), Nestlé Purina, Schell & Kampeter (Diamond Pet Foods), VAFO Group, Farmina Pet Foods, Bewital Holding, Jeronimo Martins, Auchan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Pet Food Market Trends and Innovations
Formulation science and distribution logistics are converging around precision nutrition delivery, with technology investments targeting the gap between mass-manufactured extrudates and individualized metabolic requirements.
Cold-pressed dry food production is collapsing the traditional trade-off between manufacturing scale and nutrient bioavailability preservation. Small-batch Polish processors serving boutique veterinary clinics are adopting hydraulic pressing at temperatures below 45°C. This equipment footprint enables regional production closer to end demand while eliminating the vitamin degradation that accompanies conventional extrusion thermal exposure.
EU F-Gas Regulation amendments are forcing refrigeration-dependent wet food distributors toward alternative cooling chemistries and insulated packaging innovations. Polish cold-chain operators serving the Masovian corridor are testing phase-change materials that maintain 4°C stability without mechanical refrigeration during last-mile delivery. This regulatory pressure is compressing wet food distribution economics toward shorter-radius fulfillment networks.
Urban Polish dog owners are fragmenting purchase occasions across multiple channels rather than consolidating supermarket trips. Veterinary clinics capture therapeutic and premium wet food volumes through prescription-integrated dispensing, while specialized e-commerce platforms handle bulk dry food replenishment with predictive algorithms. This channel bifurcation is most pronounced in Warsaw and Kraków metropolitan zones where subscription penetration exceeds national averages.
Poland Pet Food Market Segmentation
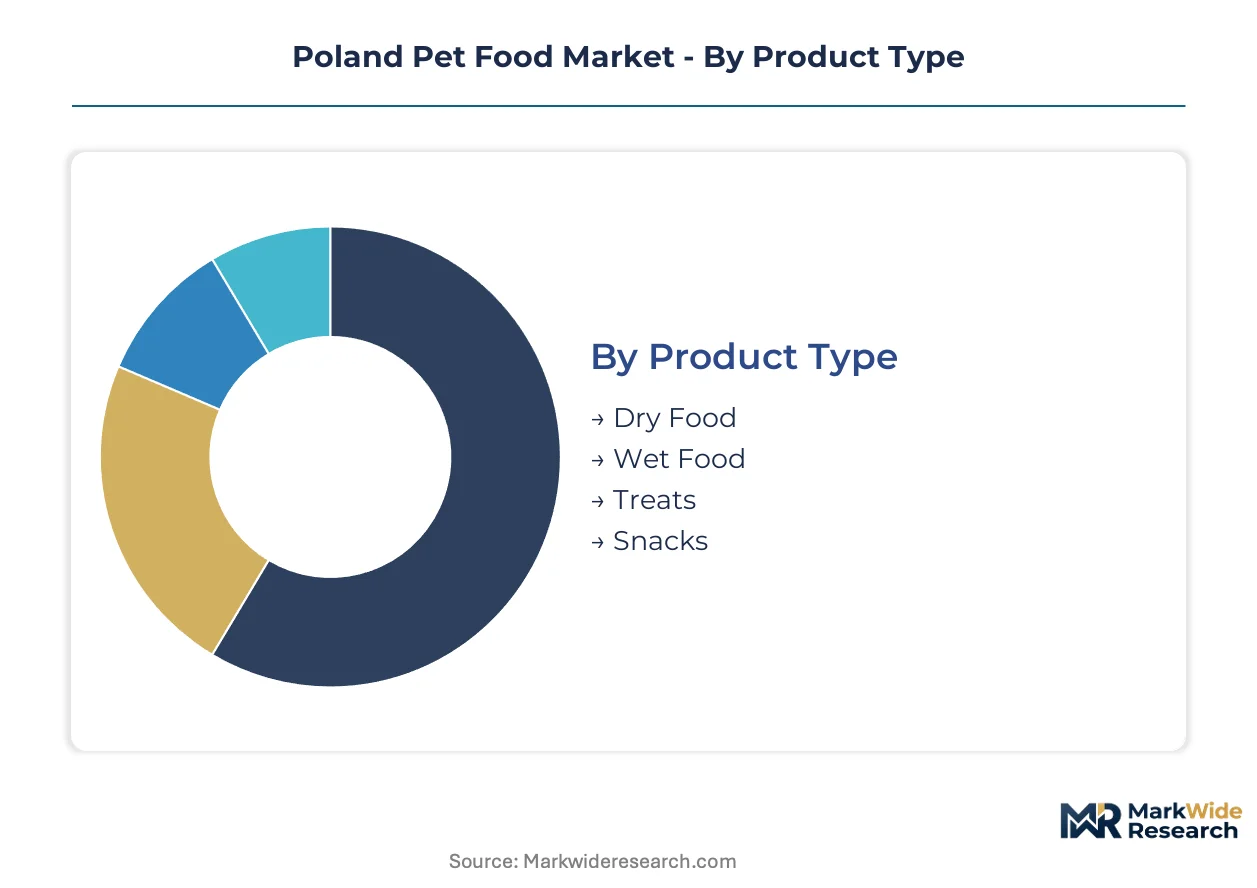
Poland's pet food market fragments across four intersecting dimensions that determine formulation investment, route-to-market control, and margin capture. Manufacturers must calibrate positioning across these categories to align with Masovian Voivodeship urban density and veterinary channel consolidation.
Product Type:
Cost tier differentiation separates mass-market volume plays from premium margin extraction strategies.
- Dry Food:Extruded kibble formulations deliver shelf-stable nutrition at the lowest per-kilogram cost point. Masovian Voivodeship households purchase dry food through supermarket bulk channels, though cold-pressing technology is displacing conventional extrusion among Warsaw's senior pet owners.
- Wet Food:Canned or pouch formats with moisture content exceeding 75% command price premiums through palatability and hydration benefits. Warsaw's urban density justifies dedicated cold-chain infrastructure, while EU F-Gas Regulation refrigerant phase-downs compress distribution economics.
- Treats:High-protein reward formulations with limited caloric density.
- Snacks:Extended shelf-life products positioned between nutritional meals and behavioral reinforcement.
Dry Food holds installed capacity. Wet Food is rotating up the share rankings.
Animal Type:
Application-specific metabolic requirements drive formulation complexity and veterinary channel integration depth.
- Dogs:Canine nutrition spans life-stage formulations from growth to senior maintenance, with large-breed joint support and small-breed dental health representing distinct SKU architectures. Urban Warsaw owners drive premium wet food adoption.
- Cats:Obligate carnivore protein requirements and urinary tract health sensitivities create formulation constraints that favor specialized therapeutic lines. Kraków metropolitan households show elevated prescription diet penetration.
- Fish:Aquarium species with species-specific pellet and flake requirements.
- Birds:Seed and pellet blends calibrated to avian metabolic rates.
Dogs hold installed capacity. Cats is climbing the fastest.
Distribution Channel:
Customer type fragmentation across purchase occasions determines inventory velocity and margin retention.
- Supermarkets:Mass retail chains dominate dry food volume through price-promotion cycles and shelf-space concentration. Subcarpathian and Podlaskie Voivodeships rely heavily on supermarket distribution due to limited specialty retail penetration.
- E-commerce:Digital platforms capture bulk replenishment occasions through predictive algorithms and subscription automation. Warsaw and Kraków metropolitan zones show subscription penetration exceeding national benchmarks.
- Pet Stores:Specialty retail with trained staff and premium brand concentration.
- Specialty Shops:Boutique outlets serving breed-specific and therapeutic formulations.
Supermarkets hold installed capacity. E-commerce is rotating up the share rankings.
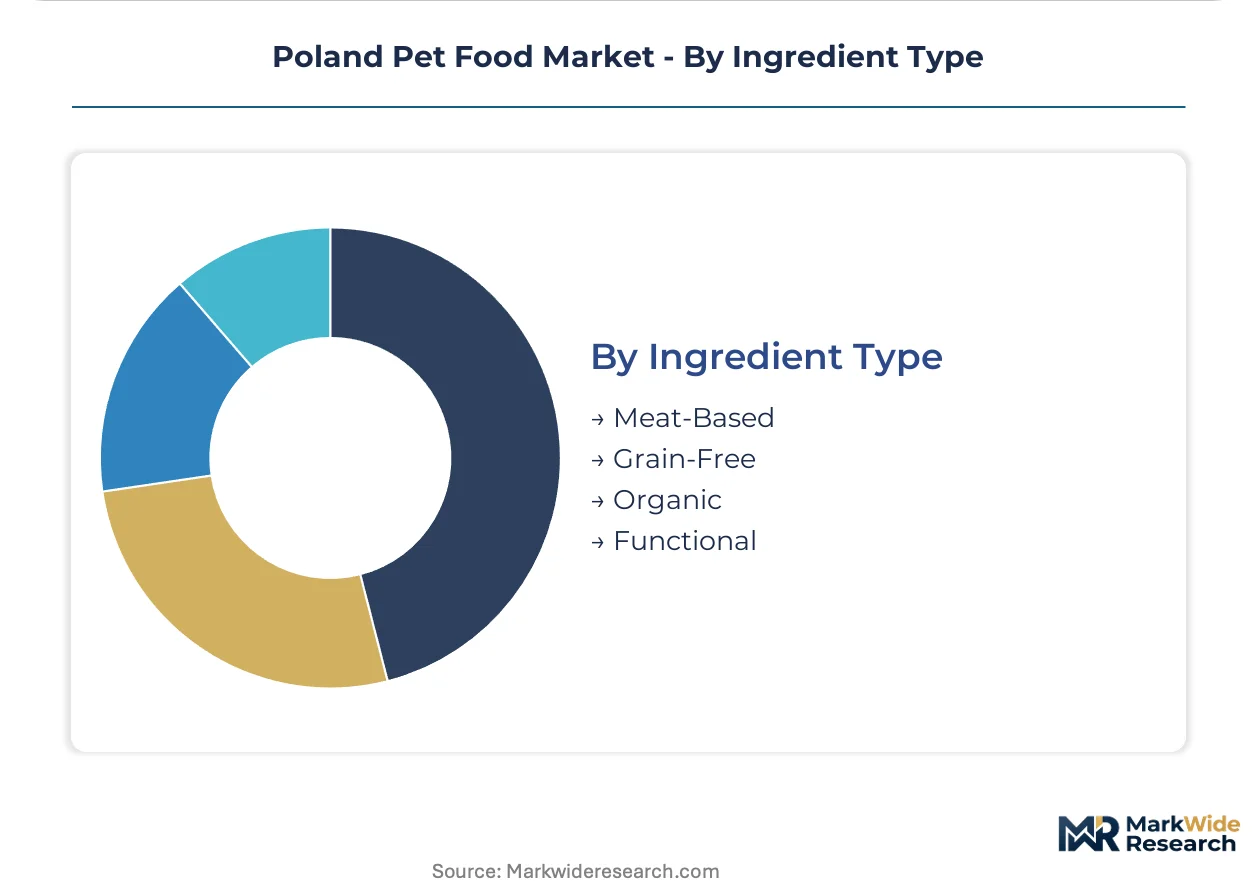
Ingredient Type:
Margin structure and supply concentration differentiate input sourcing strategies.
- Meat-Based:Poultry meal, fish hydrolysates, and fresh meat inclusion levels determine protein digestibility scores. Polish manufacturers depend on imported inputs, exposing margin structures to Black Sea grain corridor disruptions.
- Functional:Digestive enzymes, joint-support glucosamine, and coat-health omega fatty acids represent the steepest expansion trajectory as owners seek measurable health outcomes. Veterinary clinics capture these volumes through prescription-integrated dispensing.
- Grain-Free:Starch alternatives from legumes and tubers for carbohydrate-sensitive animals.
- Organic:Certified inputs with restricted pesticide and synthetic additive profiles.
Meat-Based holds installed capacity. Functional is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish pet owners in rural Subcarpathian Voivodeship exhibit higher price elasticity than Warsaw households, where premium wet food penetration justifies dedicated cold-chain infrastructure and subscription-based replenishment models.
Masovian Voivodeship
Warsaw's concentrated pet-owning households generate sufficient volume to justify premium wet food distribution networks. The Chief Veterinary Officer's regional inspectorate enforces EU Regulation 183/2005 feed hygiene protocols through automated facility audits. Cold-chain operators in the metropolitan corridor are testing phase-change materials to maintain 4°C stability without mechanical refrigeration during last-mile delivery.
Lesser Poland Voivodeship
Kraków metropolitan households show elevated prescription diet penetration for feline urinary tract health formulations. Veterinary channel consolidation under regional inspectorate oversight compresses route-to-market autonomy for imported therapeutic lines. Boutique veterinary clinics in the city center capture premium volumes through prescription-integrated dispensing systems.
Subcarpathian Voivodeship
Rising pet ownership rates in this eastern region encounter limited specialty retail penetration, creating first-mover opportunity for direct-to-veterinary distribution models. Supermarket chains dominate dry food volume through price-promotion cycles in the absence of dedicated pet store networks. Rzeszów-based distributors are building inspection-compliant logistics networks to serve dispersed rural households.
Podlaskie Voivodeship
Agricultural household structures in this northeastern region favor large-breed canine nutrition with cost-efficient dry food formulations. The Białystok veterinary inspectorate handles a disproportionate share of import compliance audits, creating inspection bottlenecks that delay new product market entry. Regional feed mills are retrofitting batch-recording infrastructure to satisfy both EU Regulation 183/2005 and retailer-specific audit protocols.
Greater Poland Voivodeship
Poznań's veterinary inspectorate concentration creates regulatory processing capacity that shapes market access for Central European manufacturers. Cold-pressing technology adoption among regional processors preserves thermolabile vitamins for senior pet formulations. The city's logistics connectivity supports distribution radius expansion into underpenetrated eastern voivodeships.
Poland Pet Food Market Competitive Landscape
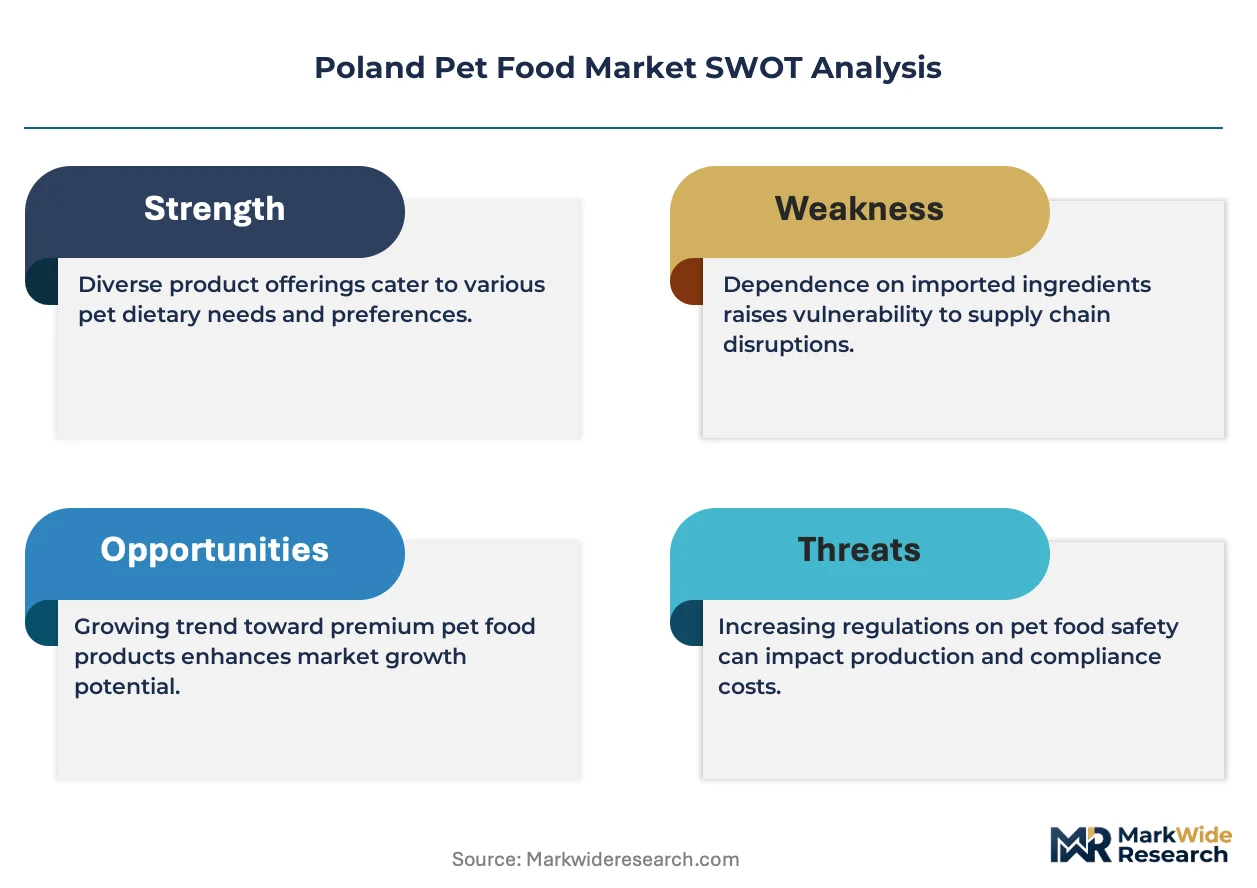
Multinational nutrition conglomerates and Central European private-label specialists split the market between brand equity extraction and manufacturing scale efficiency. The vendor base concentrates around three strategic archetypes: global packaged goods majors with veterinary health networks, regional private-label manufacturers serving retail chains, and specialized therapeutic formulators with prescription channel integration. Dominant competitive moves include veterinary clinic dispensing partnerships and backward integration into captive protein processing to offset Black Sea grain corridor volatility.
Within the multinational tier, Mars Incorporated and Nestlé Purina anchor brand equity through specialized therapeutic formulations and direct-to-consumer engagement platforms. VAFO Group occupies a position as the dominant private-label manufacturer for Polish and Central European retailers, exemplifying the regional scale-driven archetype that supplies supermarket and veterinary channel house brands.
| Leading Market Players |
|---|
| Mars Incorporated |
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| Nestlé Purina |
| Schell & Kampeter (Diamond Pet Foods) |
| VAFO Group |
| Farmina Pet Foods |
| Bewital Holding |
| Jeronimo Martins |
| Auchan |
| Others |
Pricing and Supply Chain Analysis
Black Sea grain corridor freight rate volatility feeds directly into Polish pet food manufacturing economics, compressing margin structures for meat-based formulations while amplifying price differentiation between mass-market dry food and premium cold-pressed alternatives.
Pricing Analysis
Subscription-based diet planning and aftermarket nutritional consulting generate recurring revenue streams that exceed transactional product margins by widening lifetime value capture. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-dispensed therapeutic formulations from supermarket bulk channels. Cost compression in economy tiers stems from imported poultry meal price instability. Rural Subcarpathian households exhibit highest price sensitivity; Warsaw's senior pet owners show lowest elasticity.
Supply Chain Analysis
VAFO Group dominates private-label manufacturing capacity for Central European retailers, anchoring regional production scale. Protein inputs draw from Baltic states and Black Sea origins; grain and starch components source from domestic Polish agriculture. Single-source vulnerability concentrates in fish hydrolysate imports subject to Baltic freight disruption. Distribution runs through veterinary clinic networks for therapeutic lines and supermarket chains for mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified veterinary nutritionists capable of translating metabolic research into species-specific extrusion parameters remain scarce in Polish technical universities, constraining formulation innovation velocity for mid-sized manufacturers.
For Market Incumbents: Entrench inspection-compliant logistics networks around Białystok and Poznań veterinary inspectorates to preempt route-to-market disruption from regulatory consolidation. Deepen backward integration into captive poultry processing to offset Black Sea grain corridor protein input volatility. Mars Incorporated and Nestlé Purina should expand veterinary clinic dispensing partnerships before cold-chain retrofitting costs from EU F-Gas Regulation phase-downs compress wet food distribution economics.
For New Entrants and Emerging Players: Subcarpathian and Podlaskie Voivodeships' rising pet ownership rates with limited specialty retail penetration represent the most penetrable entry point for direct-to-veterinary distribution models. Direct-to-veterinary dispensing of functional ingredient formulations bypasses supermarket price-promotion cycles entirely. Digital platforms integrating veterinary diagnostic data with automated reordering capture recurring revenue streams untapped by mass retail incumbents.
For Investors and Strategic Acquirers: Regional private-label manufacturers with inspection-compliant batch-recording infrastructure and established retailer relationships present acquisition targets with durable route-to-market positioning. Long-term viability hinges on EU packaging sustainability mandate compliance and cold-pressing technology adoption curves. Monitor quarterly veterinary inspectorate audit clearance rates as inflection indicator for market access friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Dispensing Partnership | Prescription-integrated distribution captures premium therapeutic volumes in Warsaw and Kraków metropolitan zones. |
| Cold-Pressing Technology Adoption | Lower-temperature processing preserves thermolabile vitamins for senior pet formulations in boutique veterinary channels. |
| Backward Integration into Protein Processing | In-house poultry meal production insulates margin structures from Black Sea grain corridor freight volatility. |
| Subscription-Based Diet Planning Platform | Automated reordering algorithms capture recurring revenue exceeding supermarket bulk channel economics. |
| EU Packaging Sustainability Compliance | Mono-material flexible packaging investment satisfies pending recycled content mandates before enforcement deadlines. |
Research Methodology
The analysis maps dry food extrusion, wet food canning, cold-pressed production, and functional ingredient formulation segments, each validated through veterinary nutritionists, retail category buyers, cold-chain logistics operators, and Chief Veterinary Officer regional inspectorate officials. Primary interview data triangulates against EU Regulation 183/2005 compliance filings, Polish Central Statistical Office trade records, veterinary pharmaceutical dispensing databases, and retailer-specific audit protocols. Bottom-up facility capacity assessments and top-down household expenditure patterns converge through iterative reconciliation.
Assumptions held fixed include EU F-Gas Regulation refrigerant phase-down timelines and EU packaging sustainability mandate implementation schedules; variables tested include Black Sea grain corridor freight rate scenarios and veterinary inspectorate audit processing capacity. Segmentation dimensions span product type, animal species, distribution channel, and ingredient category across the analysis window. CAGRs derive from expenditure elasticity modeling against urban pet ownership density and premium wet food penetration curves. Forecast inputs incorporate cold-chain infrastructure investment cycles and subscription platform adoption rates.
Macroeconomic conditions sit as an overlay; deviation in Polish zloty exchange rates against euro-denominated protein imports or Baltic freight indices would shift the trajectory. Regulatory enforcement intensity from the Chief Veterinary Officer and EU packaging mandate timing present revision risks. Quarterly review of veterinary inspectorate clearance backlogs and cold-chain fleet retrofitting progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Pet Toys Market
Pet Care Products
Pet Feeder Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Dog Pen Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Dog Harness Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Aquarium and Fish Bowls Market