
 UTI Cat Food Market | 2026-2036
UTI Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
UTI Cat Food Market Analytics
Subscription-based auto-delivery for therapeutic feline nutrition is broadening what manufacturers actually sell, shifting unit economics from single-transaction retail to recurring revenue models. Royal Canin Veterinary Diet leverages its prescription-only channel control to lock in veterinarian loyalty through clinic-exclusive formulations. Hill's Prescription Diet anchors its position with science-backed clinical trials that sustain premium pricing power. Purina Pro Plan competes across both veterinary and retail tiers, extending its reach through dual-brand architecture.
UTI cat food comprises therapeutically formulated diets engineered to modify urinary pH, restrict mineral precursors of struvite and calcium oxalate crystals, and dissolve or prevent urolithiasis in felines. Manufacturing requires precise extrusion or retort processing to preserve heat-sensitive acidifiers and controlled ash content below standard maintenance diets. Wet food formulations command the deepest margin pools due to higher moisture content supporting dilute urine production, while dry food retains volume leadership through storage convenience and lower per-feeding cost. Novel proteins represent the fastest-growing ingredient source as elimination-diet protocols expand beyond allergy into idiopathic cystitis management.
AAFCO nutrient profiles and FDA Center for Veterinary Medicine oversight shape permissible health claims and ingredient safety thresholds for therapeutic pet foods in the United States. State-level veterinary practice acts constrain where prescription diets dispense, creating regulatory friction between telehealth platforms and traditional clinic channels. Stakeholders must monitor evolving telemedicine regulations and pet insurance reimbursement policies as these determine whether UTI diets remain clinic-captive or migrate toward direct-to-consumer accessibility.
Market Dynamics
Prescription diet manufacturers face mounting pressure from telehealth platforms seeking direct-to-consumer distribution channels, forcing incumbents to defend veterinary clinic exclusivity through tighter formulation control and loyalty programs.
Growth Catalysts
- Pet Insurance Expansion:United States insurers now reimburse therapeutic nutrition claims, lowering out-of-pocket costs for chronic UTI management and extending prescription diet adherence.
- AAFCO Nutrient Profile Updates:Revised maximum magnesium and phosphorus thresholds in feline maintenance diets are pushing owners toward purpose-formulated urinary health products.
- Wet Food Manufacturing Scale-Up:Retort processing investments by contract manufacturers are expanding pH-stable canned formulation capacity for moisture-driven urine dilution protocols.
Market Restraints
- Input Cost Volatility:Fish meal and novel protein prices fluctuate with aquaculture harvest cycles and alternative-protein feedstock competition from human food sectors.
- Regulatory Friction:State-level veterinary practice acts in the United States block telehealth platforms from dispensing prescription diets without physical examination requirements.
- Substitution Threat:Over-the-counter urinary health claims on standard maintenance diets confuse owners and erode willingness to pay veterinary markups for therapeutic tiers.
Strategic Opportunities
- Direct-to-Consumer Channels:Subscription auto-delivery platforms can capture recurring revenue if regulatory pathways open for remote veterinary authorization.
- Novel Protein Convergence:Insect and cultivated protein sources combined with precision fermentation are creating elimination-diet options for idiopathic cystitis management.
- Underpenetrated Markets:Japan's aging pet population and high veterinary service utilization present expansion potential for premium therapeutic nutrition.
Industry Challenges
- Formulation Talent Scarcity:Veterinary nutritionists with clinical trial design expertise command premium salaries and limited supply constrains new entrant R&D velocity.
- Retort Capacity Bottlenecks:Wet food sterilization equipment requires 18-24 month lead times, delaying product line extensions and geographic expansion.
- Clinical Trial Duration:FDA Center for Veterinary Medicine substantiation protocols for urinary health claims demand multi-year feline feeding studies that compress margin recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UTI Cat Food Market |
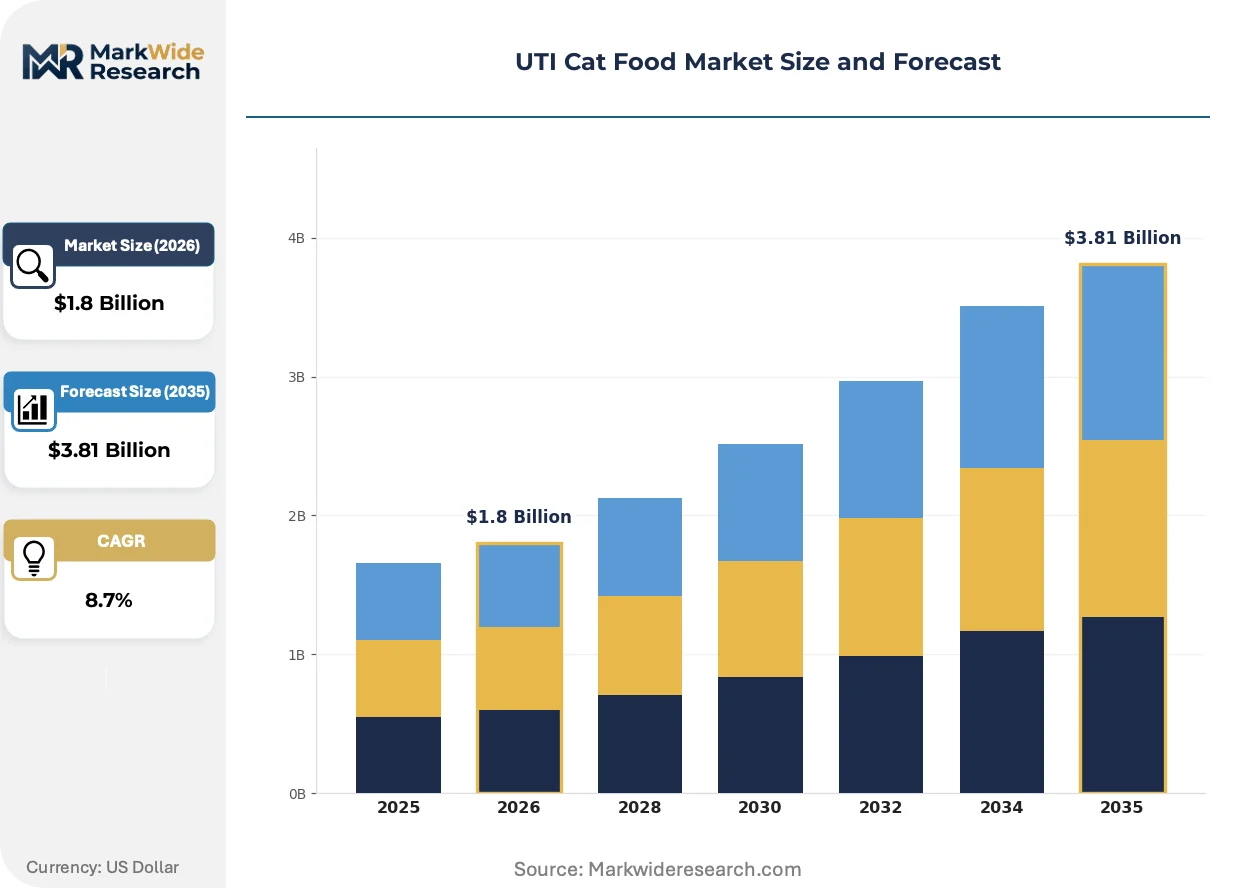
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Food, Dry Food, Treats, Supplements Ingredient Source: Real Meat, Vegetables, Grains, Novel Proteins Pack Size: Single Serve, Family Size, Economy Packs, Sample Packs Benefit Focus: Urinary Health, Weight Management, Digestive Support, Overall Wellness |
| Companies Covered | Royal Canin Veterinary Diet, Farmina VetLife, Hill's Prescription Diet, Hill's Science Diet, Smalls Fresh Cat Food, Purina Pro Plan, Forza10 Nutraceutic, Purina ONE, Iams Proactive Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UTI Cat Food Market Evolving Landscape
Formulation science and distribution control are diverging as manufacturers invest in precision nutrition while channel gatekeepers fight over prescription authority.
Microbiome-targeted prebiotic blends are expanding into urinary health formulations as researchers link gut dysbiosis to feline idiopathic cystitis flare-ups. Specialty veterinary clinics in the United States and Germany are adopting these protocols faster than general practice networks. This ingredient category is expanding into premium positioning that commands 40-60 percent price premiums over standard therapeutic diets.
REACH chemical safety registrations in Europe are tightening contaminant thresholds for heavy metals and mycotoxins in pet food ingredients. Manufacturers sourcing fish meal from non-EU suppliers face additional testing burdens and documentation requirements. Wet food producers with integrated supply chains are responding by certifying captive fisheries and accelerating alternative protein substitution programs.
Veterinary clinic consolidation is compressing buyer concentration as corporate practice groups negotiate national formulary contracts with preferred suppliers. Independent clinics are losing volume leverage and switching to white-label or house-brand urinary diets. This concentration is most visible in the United States, where Mars Veterinary Health and Vetcor operate over 2,500 combined locations dictating shelf space allocation.
UTI Cat Food Market Segmentation
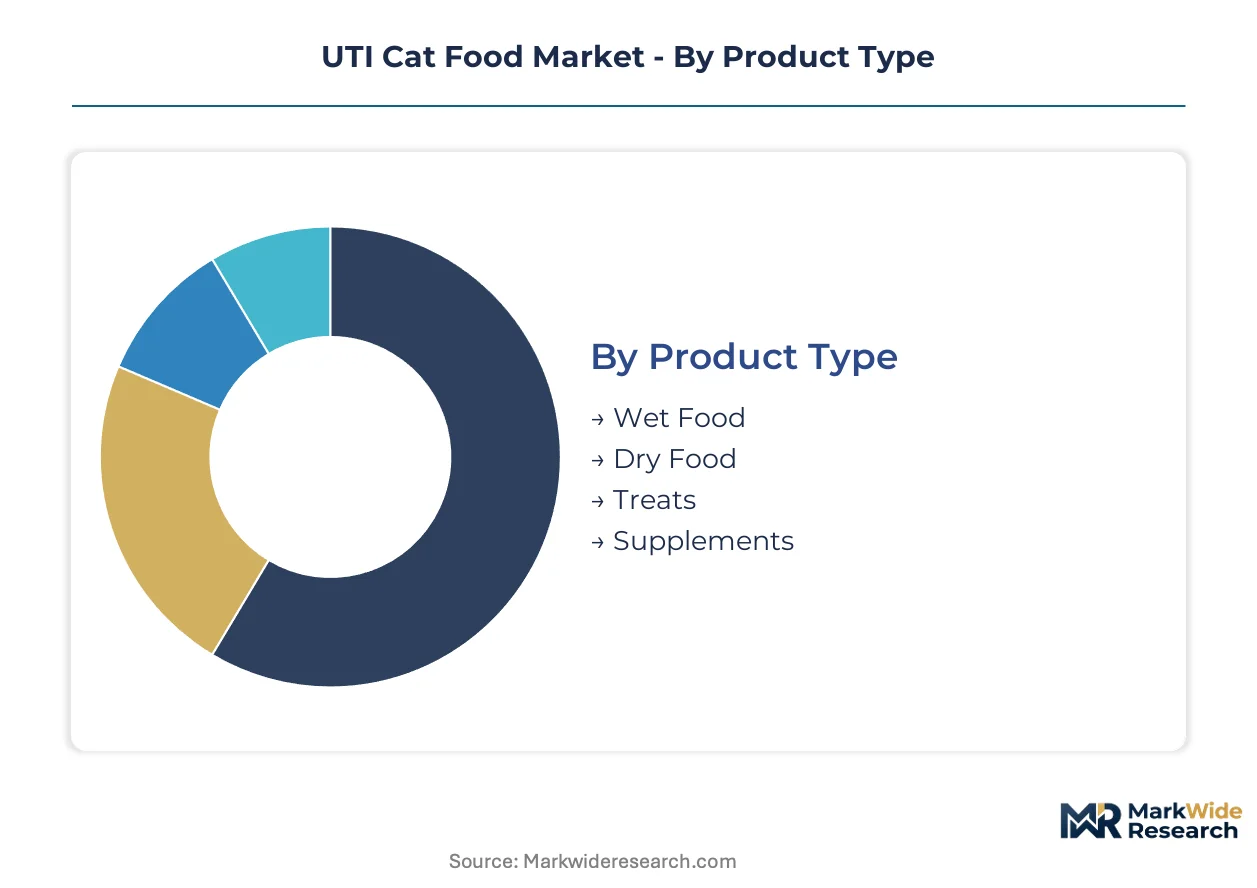
Therapeutic feline nutrition demands precise formulation control across moisture content, mineral restriction, and acidification protocols. Segmentation reveals how manufacturers align production capabilities with veterinary channel requirements and owner compliance patterns.
Product Type:
Upgrade cycles in UTI management follow diagnostic progression from acute crisis intervention to chronic maintenance protocols.
- Wet Food:High-moisture formulations containing 75-85% water content drive urine dilution and reduce specific gravity. Veterinary clinics in the United States prescribe wet diets for struvite dissolution and idiopathic cystitis management, though per-unit logistics costs constrain rural distribution.
- Dry Food:Kibble extrusion with controlled ash content below 6.5% and magnesium restriction to 0.08% dry matter enables storage convenience and lower feeding costs. Pet specialty retailers in suburban United States markets stock these for owner compliance between veterinary visits.
- Treats:pH-balanced formulations with restricted mineral loads support adherence without disrupting therapeutic protocols.
- Supplements:Cranberry extracts and glycosaminoglycan additives target owners seeking adjunctive urinary support outside prescription frameworks.
Volume placements concentrate in Dry Food; the faster expansion belongs to Wet Food.
Ingredient Source:
Cost tier differentiation separates commodity-protein formulations from premium positioning that commands veterinary markup authority.
- Real Meat:Chicken, turkey, and fish meals provide complete amino acid profiles with standardized mineral content for predictable urinary acidification. AAFCO feeding trials in the United States validate these as baseline therapeutic ingredients.
- Novel Proteins:Rabbit, venison, and duck sources support elimination-diet protocols for cats with concurrent food sensitivity and idiopathic cystitis. Specialty veterinary dermatology and internal medicine practices in Germany and the United States are expanding these prescriptions fastest.
- Vegetables:Limited inclusion as fiber sources and acidification carriers in select prescription lines.
- Grains:Corn and rice function as carbohydrate matrices in economy therapeutic tiers with reduced magnesium binding.
Real Meat retains the largest volume share; Novel Proteins are climbing the fastest as elimination-diet protocols broaden.
Pack Size:
Customer type segmentation distinguishes chronic-condition stocking behavior from trial-driven acquisition patterns.
- Single Serve:Individual pouches and cans enable precise portion control for weight-sensitive UTI patients and reduce waste in single-cat households.
- Family Size:Multi-can cases and large kibble bags serve multi-cat households with coordinated therapeutic feeding protocols.
- Economy Packs:Bulk formats lower per-gram costs for long-term struvite prevention in insured populations.
- Sample Packs:Veterinary clinic dispensing tools that reduce financial risk for owners initiating prescription transitions.
Family Size dominates absolute volume; Single Serve formats are gaining share fastest through subscription auto-delivery platforms.
Benefit Focus:
Application segmentation tracks how urinary health positioning converges with adjacent therapeutic categories in retail and clinical channels.
- Urinary Health:pH modification between 6.0-6.5, restricted magnesium and phosphorus, and controlled sodium loads constitute the core therapeutic specification. FDA Center for Veterinary Medicine oversight in the United States restricts health claims to prescription channels with clinical substantiation.
- Weight Management:Reduced-calorie urinary formulations address the comorbidity of obesity and feline lower urinary tract disease in indoor populations. Veterinary practice groups in the United States are expanding these combination protocols.
- Digestive Support:Prebiotic-enhanced urinary diets target gut-urinary axis hypotheses in idiopathic cystitis management.
- Overall Wellness:Maintenance-tier positioning with mild urinary acidification for prevention-focused owners.
Urinary Health commands the deepest prescription loyalty; Digestive Support is expanding most quickly through microbiome-targeted formulation innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
St. Louis anchors therapeutic pet food manufacturing in North America, hosting formulation laboratories and veterinary nutrition research clusters that supply clinic networks across the United States.
United States
Pet insurance reimbursement for therapeutic nutrition now covers 85% of major carriers, driving prescription diet adherence in suburban and urban veterinary markets. FDA Center for Veterinary Medicine oversight restricts urinary health claims to substantiated formulations, creating regulatory barriers for over-the-counter competitors. Mars Veterinary Health and Vetcor operate over 2,500 combined clinic locations, concentrating formulary purchasing power in corporate practice groups.
Germany
Specialty veterinary dermatology and internal medicine practices in Munich and Berlin are expanding novel protein prescriptions for concurrent food sensitivity and idiopathic cystitis cases. EFSA guidelines on pet food contaminants align with REACH chemical safety registrations, tightening heavy metal thresholds for fish meal imports. The Baden-Württemberg region hosts contract manufacturers investing in retort processing capacity for pH-stable canned formulations.
Japan
An aging pet population and high veterinary service utilization create expansion potential for premium therapeutic nutrition in Tokyo and Osaka metropolitan areas. METI standards for pet food safety govern acidifier stability and mineral content labeling. Yokohama-based distributors are building cold-chain infrastructure for wet food logistics to clinic networks.
United Kingdom
Veterinary clinic consolidation in London and Southeast England is compressing buyer concentration for prescription diet procurement. The FSA enforces feed hygiene regulations that exceed baseline EU requirements for therapeutic pet food manufacturing. Manchester and Birmingham distribution hubs are expanding subscription auto-delivery fulfillment for insured pet populations.
Canada
Health Canada and PMRA oversight of veterinary health products creates parallel regulatory pathways for urinary diet authorization in Toronto and Vancouver veterinary markets. Provincial pet insurance penetration lags the United States, constraining premium pricing power for therapeutic tiers. Montreal-area contract manufacturers are retooling extrusion lines for low-ash, magnesium-restricted kibble production.
UTI Cat Food Market Competitive Landscape
Capital-heavy producers with captive manufacturing compete with asset-light brand licensors and contract manufacturers in therapeutic feline nutrition. The market structure concentrates around three multinational veterinary health conglomerates controlling prescription-only distribution channels, while independent and private-label suppliers fragment the over-the-counter urinary health segment. Strategic archetypes include clinic-exclusive prescription formulators, dual-channel premium brands, and novel-protein specialists. Dominant competitive moves encompass veterinary loyalty program expansion and retort capacity investments for wet food manufacturing scale.
Within the prescription-exclusive tier, Royal Canin Veterinary Diet exemplifies clinic-captive distribution control, while Hill's Prescription Diet anchors science-backed clinical trial substantiation. Purina Pro Plan occupies a dual-channel position spanning veterinary authorization and retail accessibility. These three entities represent the dominant competitive anchors shaping formulation investment and channel access patterns across North American and European markets.
| Leading Market Players |
|---|
| Royal Canin Veterinary Diet |
| Farmina VetLife |
| Hill's Prescription Diet |
| Hill's Science Diet |
| Smalls Fresh Cat Food |
| Purina Pro Plan |
| Forza10 Nutraceutic |
| Purina ONE |
| Iams Proactive Health |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up veterinary clinic chains in the United States concentrate formulary purchasing power, compressing supplier margins while enforcing strict pricing discipline through national contract tiers that reward volume commitment with preferential slotting fees.
Pricing Analysis
Outcome-based pricing anchored to clinical efficacy metrics governs prescription diet tiers, with urinary dissolution protocols commanding premium positioning over maintenance formulations. Pricing stratifies across prescription-exclusive, veterinary-authorized retail, and over-the-counter wellness tiers based on clinical substantiation depth and channel control intensity. Cost compression in the retail-accessible segment is intensifying because telehealth platforms erode traditional clinic markups. Price-sensitive owners in uninsured populations gravitate toward maintenance-tier alternatives, while insured chronic-condition households show minimal elasticity for dissolution-phase formulations.
Supply Chain Analysis
Single-source vulnerability sits with Thai and Peruvian fish meal suppliers facing aquaculture harvest volatility and human-food sector competition. Raw material dependencies center on marine proteins, novel protein isolates, and acidifier stabilizers requiring cold-chain integrity. Tariff exposure on imported fish meal concentrates risk in wet food formulations dependent on pH-stable canned processing. Distribution runs through veterinary clinic networks, pet specialty retailers, and emerging subscription auto-delivery platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary clinic consolidation functions as a forced exit mechanism for subscale formulation houses lacking retort capacity or clinical trial substantiation budgets.
For Market Incumbents: Hedge against telehealth disintermediation by tightening prescription-only formulation control and expanding clinic loyalty rebate programs that lock corporate practice groups into exclusive supply agreements. Capacity addition in the Baden-Württemberg region addresses European wet food demand while reducing trans-Atlantic logistics exposure. For New Entrants and Emerging Players: Enter via novel protein convergence targeting idiopathic cystitis protocols in German specialty veterinary practices, where elimination-diet adoption outpaces general practice networks. Direct-to-consumer subscription platforms with remote veterinary authorization partnerships offer the most penetrable channel for circumventing incumbent clinic-captive distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with underutilized retort capacity in North America during periods of input cost volatility. The signal to watch is pet insurance reimbursement expansion into preventive nutrition tiers, which would revalue therapeutic diet assets toward recurring revenue multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Capacity Expansion | Wet food sterilization investments by contract manufacturers unlock pH-stable canned formulation scale for urine dilution protocols. |
| Prescription Channel Lock-In | Clinic-exclusive loyalty programs defend against telehealth platform disintermediation threatening veterinary markup structures. |
| Novel Protein Sourcing | Insect and cultivated protein integration addresses REACH contaminant thresholds while supporting elimination-diet protocol expansion. |
| Subscription Auto-Delivery Launch | Recurring revenue models capture insured household adherence while reducing per-unit customer acquisition costs. |
| Microbiome Formulation R&D | Prebiotic-enhanced urinary diets command 40-60 percent price premiums through gut-urinary axis positioning in specialty clinics. |
Research Methodology
Independent corroboration across veterinary nutritionists, contract manufacturing executives, and pet insurance reimbursement specialists underwrites the qualitative findings. Primary interviews with formulation scientists, clinic procurement managers at corporate practice groups, and specialty retail category buyers combined with secondary validation from FDA Center for Veterinary Medicine substantiation filings, AAFCO nutrient profile updates, and pet insurance claims databases. Bottom-up segment sizing and top-down macro constraint triangulation reconcile volume and value estimates.
Rate-of-change decomposition across product type, ingredient source, benefit focus, and distribution channel dimensions structures the analytical framework. CAGRs derive from segment-level growth trajectory blending with macro constraint elasticity modeling. Forecast inputs incorporate pet insurance penetration curves, retort capacity expansion timelines, and telehealth regulatory pathway evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt telehealth authorization shifts or novel protein feedstock supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
UK Pet Diet Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Dog Harness Market
Pet Care Products
Paw Plunger Market