
 Pet Dental Health Market | 2026-2036
Pet Dental Health Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Dental Health Market Intelligence
Online retail is rewriting how pet dental products reach end users, bypassing traditional veterinary gatekeepers to build direct consumer relationships. Mars Incorporated leverages its multi-brand portfolio to sustain shelf dominance across pet specialty stores and mass retail. Virbac anchors its position through prescription-grade dental diets and professional-only formulations. Nestlé Purina Pet Care competes with science-backed dental chews that carry Veterinary Oral Health Council endorsements.
Pet dental health encompasses preventive and therapeutic interventions for oral hygiene in companion animals, including enzymatic formulations with glucose oxidase or chlorhexidine concentrations calibrated to break plaque biofilm without tissue irritation. The primary purpose spans tartar reduction, gingivitis management, and mitigation of periodontal disease that drives systemic bacterial infection. Dental chews command the largest revenue pool among product types due to daily-use frequency and premium positioning, while oral spray formats represent the fastest-expanding segment driven by ease of administration for resistant pets. Veterinary clinics constitute the highest-margin end-user channel because professional cleanings and anesthetic procedures generate service revenue beyond product sales.
The FDA Center for Veterinary Medicine regulates dental health claims and active ingredient safety for products marketed in the United States, while the EPA governs antimicrobial concentrations in oral rinses. VOHC certification standards shape product credibility and veterinary recommendation patterns. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether non-veterinary pet groomers can perform scaling or polishing services.
Market Dynamics
Veterinary clinic consolidation and the rise of subscription-based pet wellness programs are compressing traditional distribution hierarchies, forcing manufacturers to build direct-to-consumer capabilities alongside professional channel relationships.
Growth Catalysts
- VOHC Certification Standards:The Veterinary Oral Health Council's seal of approval creates a quality threshold that drives veterinary recommendation patterns and consumer willingness to pay premium prices for validated efficacy claims.
- Pet Insurance Expansion:Broadening coverage for dental procedures in the United States reduces cost barriers for professional cleanings, pulling more pets into formal veterinary dental care protocols annually.
- Enzymatic Formulation Advances:Glucose oxidase and calibrated chlorhexidine concentrations now break plaque biofilm without tissue irritation, expanding the addressable population to pets with sensitive oral conditions.
Market Restraints
- Anesthetic Procedure Costs:Professional dental cleanings requiring general anesthesia carry price points that exclude lower-income pet owners from preventive care protocols.
- Veterinarian Concentration:Rural and exurban areas in the United States face shortages of veterinary professionals trained in dental procedures, creating geographic access gaps.
- Antimicrobial Regulatory Friction:EPA oversight of oral rinse concentrations creates formulation constraints that limit product innovation cycles and extend time-to-market for new antimicrobial claims.
Strategic Opportunities
- Telemedicine Integration:Remote veterinary consultation platforms enable preliminary dental assessments that triage pets toward appropriate care levels, expanding reach beyond physical clinic footprints.
- Non-Anesthetic Scaling Services:State-level scope-of-practice expansions allowing certified veterinary technicians to perform scaling without full veterinary supervision create lower-cost entry points for preventive care.
- Personalized Nutrition Convergence:DNA-based dietary recommendations integrating dental health outcomes with metabolic profiles open premium positioning for prescription-grade dental diets tailored to breed-specific predispositions.
Industry Challenges
- Anesthesia Safety Protocols:Veterinary practices must maintain costly monitoring equipment and staff certification to manage risks associated with dental procedures in aging pet populations.
- Cross-Channel Pricing Integrity:Manufacturers struggle to maintain margin structures when identical SKUs appear in veterinary clinics, pet specialty retail, and direct-to-consumer platforms with divergent service bundles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Dental Health Market |
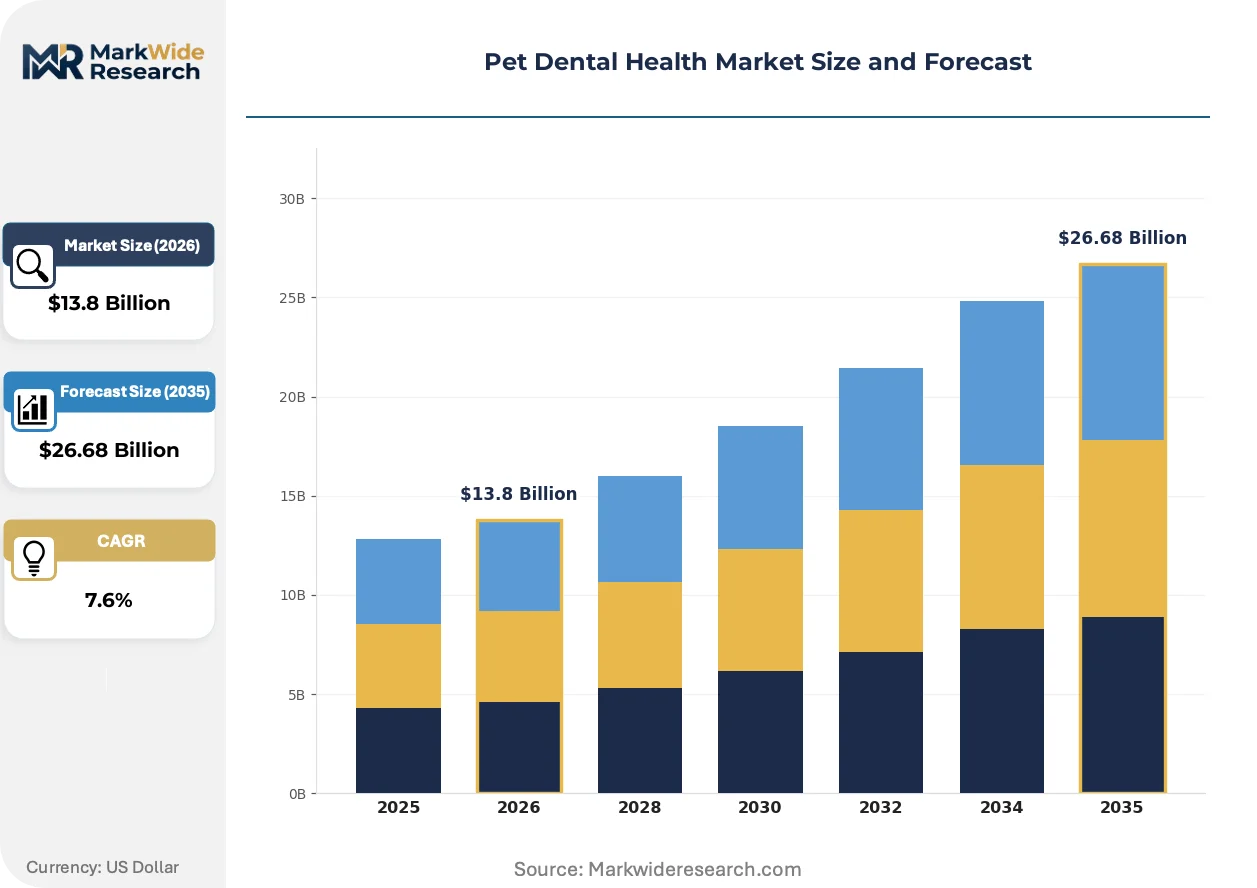
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Chews, Toothpaste, Mouthwash, Oral Spray End User: Pet Owners, Veterinary Clinics, Pet Groomers, Animal Shelters Distribution Channel: Online Retail, Pet Specialty Stores, Veterinary Hospitals, Supermarkets Form: Gel, Powder, Treat, Liquid |
| Companies Covered | Colgate-Palmolive Company, Nestlé Purina Pet Care, Dechra Pharmaceuticals, Virbac, Mars Incorporated, Vetoquinol SA, Central Garden & Pet Company, Midmark Corporation, Zoetis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Dental Health Market Strategic Shifts & Innovations
Digital diagnostic tools and biometric monitoring devices are penetrating the preventive care workflow, enabling earlier intervention and shifting some surveillance burden from clinics to pet owners.
Artificial intelligence-powered image recognition for periodontal assessment is rendering obsolete the traditional visual-only examination protocols that miss subgingival pathology. Large specialty hospital chains in the United States are piloting these systems for intake triage, compressing the diagnostic timeline from days to minutes while building datasets that refine predictive models for disease progression.
The FDA Center for Veterinary Medicine is tightening evidentiary requirements for dental health claims on over-the-counter products, forcing manufacturers to conduct controlled clinical trials. This regulatory elevation is filtering out marginal formulations and concentrating shelf presence among entities with research infrastructure. Dental chew manufacturers with VOHC endorsements are capturing disproportionate veterinary recommendation share as gatekeepers seek liability protection.
Subscription replenishment models for dental chews and enzymatic pastes are displacing episodic purchase patterns in mass retail channels. Millennial and Generation Z pet owners in urban United States markets demonstrate higher loyalty to auto-ship programs that bundle dental products with nutrition and parasite control. This behavioral shift pressures traditional veterinary clinics to launch their own direct fulfillment capabilities or cede recurring revenue to platform competitors.
Pet Dental Health Market Segmentation
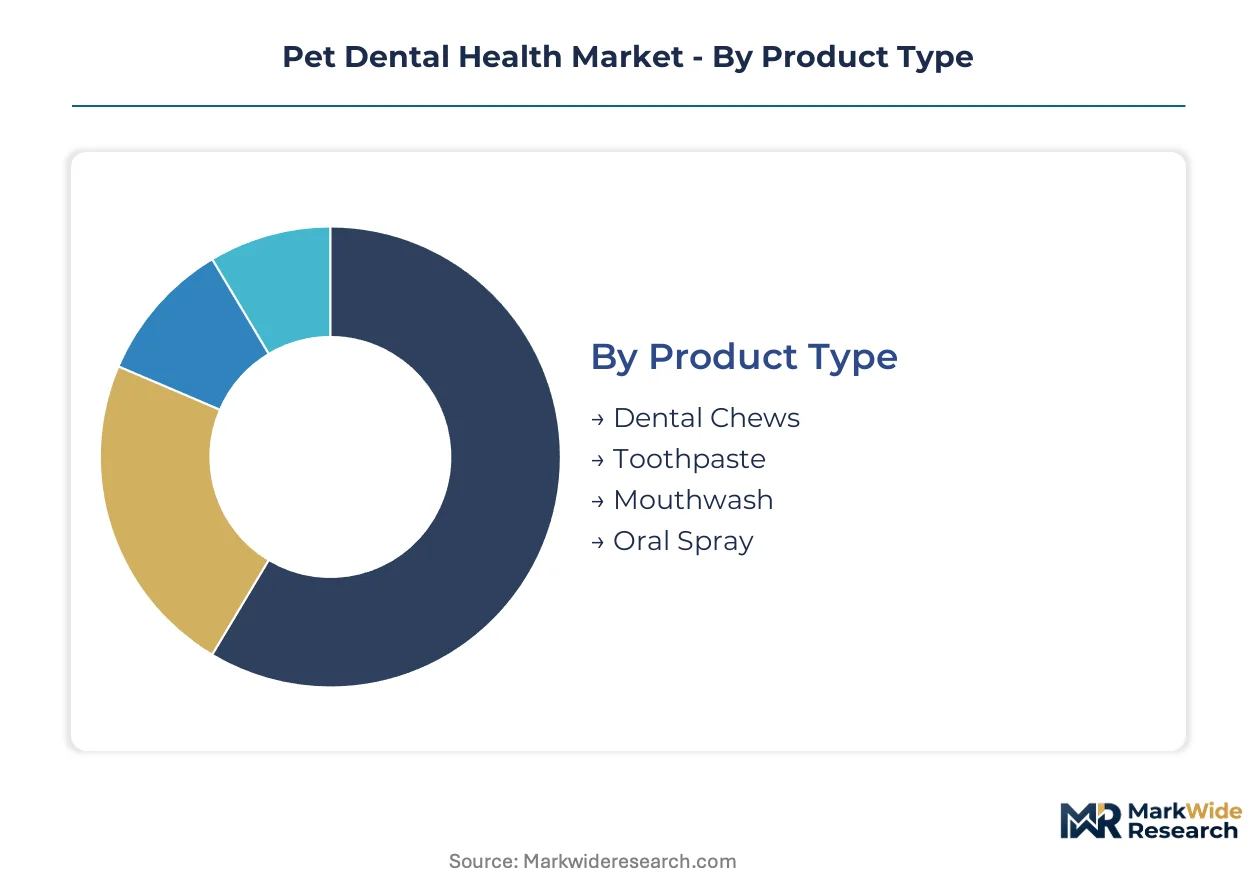
Pet dental health markets fragment across four dimensions that shape pricing power and channel strategy. Product type determines frequency of use and margin structure, while end-user concentration dictates whether manufacturers prioritize professional recommendation or direct consumer marketing.
Product Type:
Use-case spectrum spans daily maintenance routines through acute intervention protocols, with consumption frequency and veterinary involvement varying sharply across formats.
- Dental Chews:Edible formulations combining mechanical abrasion with enzymatic activity, typically incorporating chlorhexidine or glucose oxidase. Demand concentrates in urban United States households seeking compliant administration for resistant pets, driven by VOHC endorsement requirements that filter marginal competitors from veterinary recommendation cycles.
- Toothpaste:Enzymatic pastes calibrated for species-specific pH levels, requiring daily application and owner compliance training. Veterinary clinics in metropolitan United States markets bundle these with initial dental assessments, constrained by anesthetic procedure costs that exclude lower-income pet owners from professional cleaning protocols.
- Mouthwash:Antimicrobial rinses regulated by EPA concentration limits, creating formulation bottlenecks for new entrants.
- Oral Spray:Aerosolized delivery systems penetrating fastest among senior pet populations with periodontal sensitivity.
The dominant share belongs to Dental Chews, while Oral Spray is closing the gap fastest.
End User:
Customer type stratifies by price tolerance, clinical sophistication, and regulatory access to professional-grade formulations.
- Veterinary Clinics:Professional settings generating service revenue through anesthetic cleanings, scaling, and prescription diet recommendations. Concentrated in United States suburban corridors where pet insurance penetration reduces cost barriers and VOHC-certified product endorsement carries liability protection value.
- Pet Owners:Direct purchasers spanning subscription auto-ship loyalty in urban United States markets through episodic mass retail buying in price-sensitive segments, fragmented by digital platform adoption and telemedicine triage familiarity.
- Pet Groomers:Non-veterinary providers whose scope-of-practice permissions for scaling vary by United States state regulation.
- Animal Shelters:Volume purchasers prioritizing cost efficiency over premium positioning for intake protocols.
Veterinary Clinics command the highest margin capture, with Pet Owners expanding most quickly through direct-to-consumer platform migration.
Distribution Channel:
Channel selection determines whether manufacturers retain pricing integrity or surrender margin to platform intermediaries and professional gatekeepers.
- Online Retail:Subscription replenishment platforms displacing episodic purchase patterns, concentrated among Millennial and Generation Z pet owners in United States urban markets who demonstrate higher auto-ship loyalty when dental products bundle with nutrition and parasite control.
- Pet Specialty Stores:Physical retail maintaining shelf presence for impulse purchases and brand discovery, constrained by veterinary clinic consolidation compressing traditional distribution hierarchies.
- Veterinary Hospitals:Professional channel requiring relationship investment with clinic networks and formulary committees.
- Supermarkets:Mass retail capturing price-sensitive volume through promotional cycling.
Online Retail holds the dominant position, while Veterinary Hospitals are gaining share fastest through clinic consolidation and wellness program bundling.
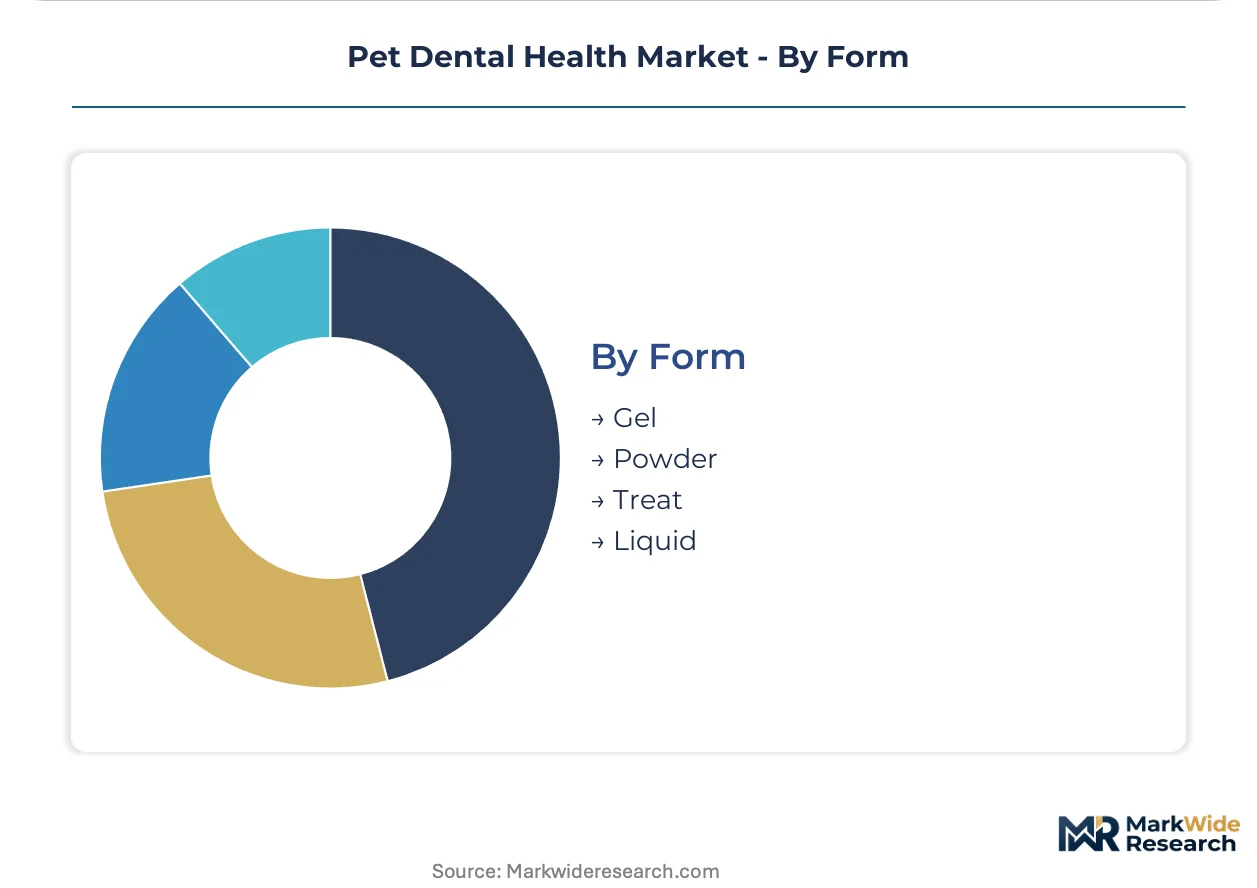
Form:
Physical formulation dictates administration compliance, storage requirements, and cross-category substitution risk.
- Treat:Palatable delivery masking active ingredients in food-motivated animals, dominating daily-use compliance metrics.
- Gel:Viscous formulations adhering to gingival margins for sustained contact time.
- Liquid:Rinse formats requiring EPA antimicrobial concentration compliance.
- Powder:Dry additives integrating with existing feeding routines for low-compliance households.
Treat formats dominate volume, with Gel climbing the fastest as veterinary recommendation shifts toward sustained-contact therapeutic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet dental health pricing power concentrates in the United States while European markets face compressed margins from veterinary reimbursement caps. This asymmetry shapes manufacturer channel strategies and product launch sequencing across developed economies.
United States
Pet insurance expansion and VOHC certification premiums sustain pricing power in suburban veterinary corridors. The FDA Center for Veterinary Medicine regulates dental health claims and antimicrobial concentrations, elevating compliance costs for new entrants. Specialist dental referral networks cluster in California, Texas, and Florida metros where anesthetic procedure volumes support dedicated equipment investments.
Germany
Veterinary dental specialization and mandatory animal welfare insurance create stable demand for professional-grade formulations. EMA and national veterinary pharmaceutical frameworks govern prescription dental diets and oral rinse antimicrobial thresholds. Munich and Stuttgart host concentration of specialty veterinary dental clinics serving high-compliance pet owner segments.
United Kingdom
Post-pandemic pet ownership surges and subscription wellness program adoption drive preventive product uptake in urban households. The Veterinary Medicines Directorate aligns with EU regulatory frameworks for dental health product authorization. Greater London and Manchester veterinary groups are consolidating dental service offerings into standardized care protocols.
Japan
Aging pet demographics and small-breed periodontal predisposition expand therapeutic intervention demand beyond preventive maintenance. PMDA and METI jointly oversee animal health product registration and antimicrobial concentration standards. Tokyo-Osaka veterinary chains are deploying digital dental imaging systems to differentiate service tiers.
Australia
High companion animal ownership rates and geographic veterinary access challenges elevate telemedicine triage for dental assessments. The TGA regulates veterinary oral care products under parallel importation frameworks with US and EU mutual recognition elements. Sydney and Melbourne specialty hospitals are piloting non-anesthetic scaling protocols permitted under state veterinary board scope expansions.
Pet Dental Health Market Key Industry Players
Consumer packaged goods conglomerates and veterinary pharmaceutical specialists split the market between mass retail scale and professional channel depth. Mars Incorporated and Nestlé Purina Pet Care leverage multi-brand portfolios and distribution infrastructure across pet specialty and mass retail channels. Virbac, Dechra Pharmaceuticals, and Zoetis anchor the prescription-grade and professional-only segment through veterinary formulary relationships and clinical trial investment. Competitive moves concentrate on VOHC certification acquisition for liability protection and subscription platform development for recurring revenue capture.
Within the consumer packaged goods tier, Mars Incorporated and Nestlé Purina Pet Care occupy positions defined by shelf presence and brand portfolio breadth. Among veterinary pharmaceutical specialists, Virbac exemplifies the prescription-grade archetype through professional channel anchoring. Colgate-Palmolive Company represents consumer health product lineage extending into companion animal oral care. These entities sit within distinct competitive spaces that rarely overlap in pricing or distribution strategy.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Nestlé Purina Pet Care |
| Dechra Pharmaceuticals |
| Virbac |
| Mars Incorporated |
| Vetoquinol SA |
| Central Garden & Pet Company |
| Midmark Corporation |
| Zoetis |
| Others |
Cost & Logistics Intelligence
Active ingredient manufacturing for chlorhexidine and glucose oxidase concentrates in China and India, feeding formulation facilities in the United States and Europe where VOHC certification and FDA compliance create margin capture for finished goods. This upstream concentration shapes downstream pricing power, with certified manufacturers commanding premium positioning while uncertified competitors face cost compression in mass retail channels.
Pricing Analysis
The customization-premium spread separates prescription-grade dental diets calibrated to metabolic profiles from standard enzymatic chews. Three-tier pricing structure across premium, standard, and economy levels reflects VOHC endorsement status, veterinary channel exclusivity, and after-sales service bundling. Pricing pressure stems from direct-to-consumer platform expansion that disintermediates professional gatekeepers. Price-sensitive mass retail buyers in supermarkets contrast with insurance-backed veterinary clinic clients who absorb premium positioning.
Supply Chain Analysis
Export-control regimes on antimicrobial precursor chemicals constrain formulation flexibility for oral rinse manufacturers seeking EPA-compliant concentrations. Active pharmaceutical ingredient production draws from China, India, and Germany, while enzymatic manufacturing rests on fermentation capacity in the United States and Denmark. Supply chain risk centers on single-source vulnerability for chlorhexidine raw material. Distribution runs through veterinary hospital networks and subscription platforms that bypass traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
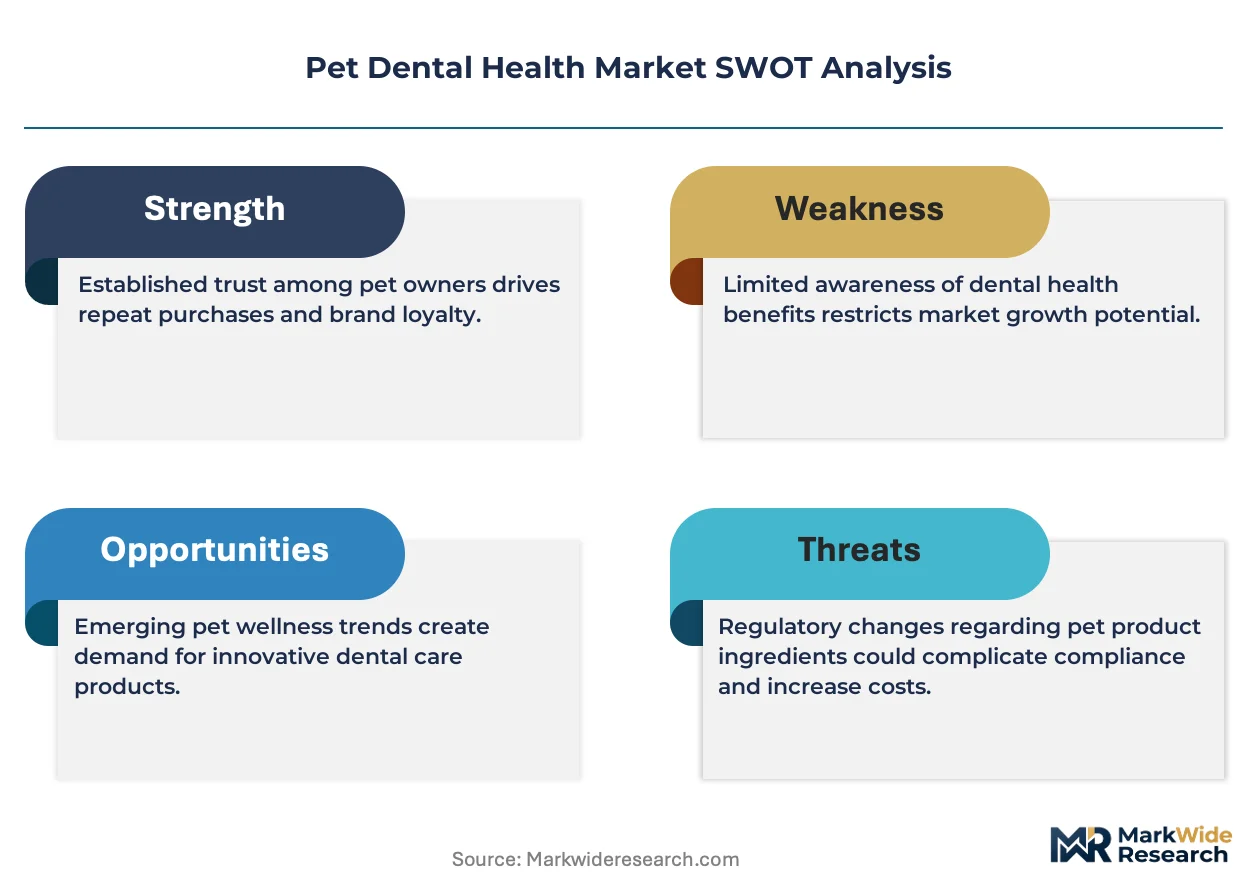
The pet dental health market is reshaping around AI-powered diagnostic tools and tightening FDA evidentiary requirements that filter marginal competitors from shelf presence. This technological-regulatory inflection compresses timelines for product development while elevating capital requirements for sustained participation.
For Market Incumbents: Build certification moats through VOHC endorsement acquisition and clinical trial infrastructure that emerging entrants cannot replicate. Defensive moves center on backward integration into active ingredient manufacturing to secure chlorhexidine supply, plus direct-to-consumer platform development to capture subscription revenue that veterinary clinic consolidation threatens. The threat of telemedicine triage platforms disintermediating professional channels demands channel control investment.
For New Entrants and Emerging Players: Build out white-space positions in oral spray formats for senior pet populations with periodontal sensitivity, and in state-permitted non-anesthetic scaling services where scope-of-practice expansions create access. The most penetrable segment sits in urban United States markets among Millennial and Generation Z owners demonstrating auto-ship loyalty. Go-to-market execution should leverage telemedicine partnerships for preliminary dental assessment triage.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed veterinary clinic consolidators seeking dental service line expansion. Long-term viability over a multi-year horizon hinges on regulatory compliance infrastructure and subscription platform capabilities. Acquisition targets should display VOHC certification pipelines and telemedicine integration readiness. The signal to watch is state-level scope-of-practice legislation permitting certified technician scaling without full veterinary supervision.
| Strategic Initiative | Industry Significance |
|---|---|
| VOHC Certification Acquisition | Endorsement creates veterinary recommendation protection and premium pricing justification. |
| Direct-to-Consumer Platform Launch | Subscription auto-ship captures recurring revenue that clinic consolidation displaces. |
| Telemedicine Integration Partnership | Remote triage expands reach beyond physical clinic footprints into underserved geographies. |
| Enzymatic Formulation R&D Investment | Glucose oxidase advances address sensitive oral conditions and expand addressable populations. |
| Non-Anesthetic Scaling Service Expansion | State scope-of-practice permissions create lower-cost preventive care entry points. |
Research Approach
Desk research of FDA Center for Veterinary Medicine filings, EPA antimicrobial registration databases, and VOHC product approval records preceded structured interviews with veterinary dental specialists, clinic operations directors, pet insurance product managers, and enzymatic formulation scientists. Secondary validation drew from trade customs data, veterinary pharmaceutical distribution records, and pet specialty retail audit sources. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, and distribution channel dimensions.
Assumption sets held pet insurance penetration trajectories and VOHC endorsement timelines within observed regulatory patterns while varying telemedicine adoption rates and state scope-of-practice expansion scenarios. The analytical framework segmented by product format, customer type, channel structure, and physical formulation across the analysis window. CAGRs derived from enrollment curve analysis for subscription platforms and procedure volume trends in consolidated clinic networks. Forecast inputs incorporated enzymatic patent expiration schedules and antimicrobial regulatory threshold adjustments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer platform entrants or rapid state-level scope-of-practice liberalization would shift outcomes. Material shifts in FDA evidentiary requirements for dental health claims or EPA antimicrobial concentration limits would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Dog Clothes Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Pet Grooming Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Organic Pet Food Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Cat Harness Market