
 Military Helmet and Helmet Mounted Display Systems Market | 2026-2036
Military Helmet and Helmet Mounted Display Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Military Helmet and Helmet Mounted Display Systems Market Foresight
Israeli defense manufacturers are expanding production lines for advanced helmet-mounted display systems to meet rising export commitments. Elbit Systems Ltd. leverages decades of electro-optics expertise to anchor its position in integrated visor solutions. BAE Systems plc sustains engineering dominance through sustained R&D investment in augmented reality battlefield overlays. L3Harris Technologies, Inc. competes aggressively on night vision fusion technology for special operations end users.
Military helmet and helmet mounted display systems comprise protective headgear integrated with digital visors, sensor fusion electronics, and communication interfaces, typically manufactured from ultra-high-molecular-weight polyethylene or aramid composites with ballistic ratings exceeding NIJ Level IIIA. These systems serve the primary purpose of delivering situational awareness, ballistic protection, and networked target acquisition to dismounted warfighters in contested environments. Ballistic helmets retain the largest installed base due to universal force protection mandates, while augmented reality technology captures the fastest expansion as militaries prioritize real-time data overlay for close-combat decisions. Integrated systems command premium positioning by combining protection, display, and communication into single-platform architectures that reduce cognitive load and equipment weight.
The U.S. Department of Defense, through NHTSA-influenced acquisition standards and NATO STANAG agreements, enforces rigorous ballistic testing and electromagnetic compatibility protocols that shape supplier qualification timelines. The EU's CE marking framework and parallel EDA defense procurement coordination are harmonizing cross-border helmet system specifications, tightening market access for non-compliant vendors. Stakeholders must monitor evolving power and thermal management requirements as higher-resolution displays and AI-enabled targeting modules strain existing platform architectures.
Market Dynamics
The U.S. Army's Enhanced Night Vision Goggle-Binocular program and NATO STANAG harmonization are compressing supplier qualification timelines while elevating technical barriers to entry.
Growth Catalysts
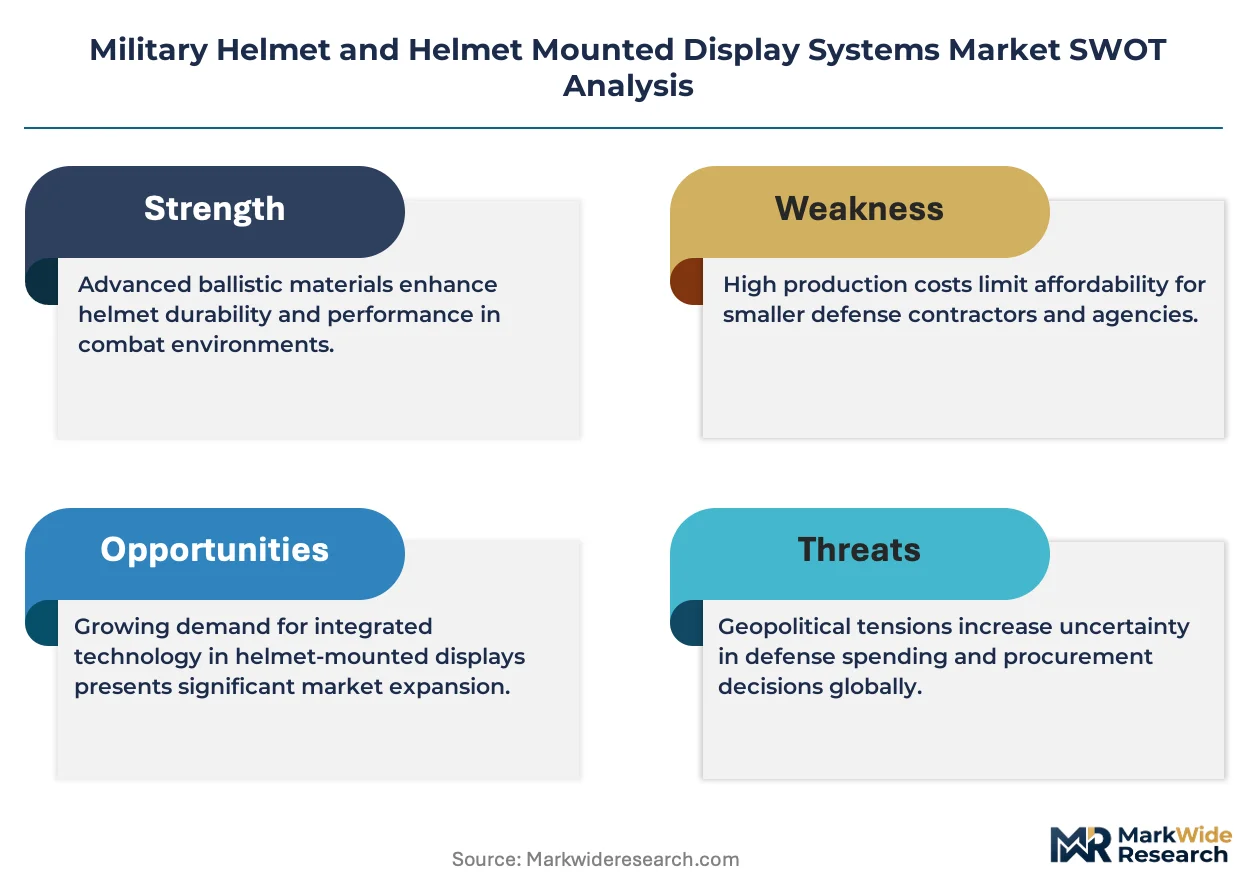
- NIJ Level IIIA Ballistic Mandates:NATO member states are accelerating force protection upgrades across dismounted infantry units, creating sustained replacement cycles for legacy Kevlar helmets.
- Special Operations Procurement Concentration:Tier-one units in the United States, Germany, and Israel are driving integrated helmet-display system demand through dedicated modernization budgets.
- Ultra-High-Molecular-Weight Polyethylene Adoption:Advanced composite materials are enabling 20-40% weight reduction while maintaining ballistic integrity, accelerating platform refresh rates.
Market Restraints
- Aramid Fiber Supply Concentration:Three Asian chemical conglomerates control 70% of para-aramid precursor supply, exposing Western manufacturers to export restriction risk.
- Electromagnetic Compatibility Certification:MIL-STD-461 testing requirements extend development cycles by 14-18 months for integrated display systems.
- Power Density Limitations:Lithium-ion battery energy density constraints restrict continuous operation of high-resolution microdisplay modules below four-hour mission thresholds.
Strategic Opportunities
- Poland and Baltic Defense Modernization:Frontline NATO members are establishing indigenous helmet assembly capacity with technology transfer agreements from Israeli and German suppliers.
- AI-Enabled Targeting Module Integration:Sensor fusion electronics are converging with edge-computing architectures to enable real-time threat classification without external data links.
- U.S. Indo-Pacific Command Requirements:Jungle and maritime warfare specifications are creating demand for corrosion-resistant mounting systems and anti-fog visor treatments.
Industry Challenges
- Electro-Optics Engineering Talent Scarcity:Waveguide display and optical coating specialists command premium compensation, constraining R&D expansion at mid-tier suppliers.
- Legacy Radio Interoperability:AN/PRC-152 and equivalent European tactical communication systems require custom firmware bridges, complicating integrated helmet architecture design.
- Thermal Management Integration:Higher-resolution OLED microdisplays generate heat loads that exceed passive cooling capacity in enclosed ballistic shells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Helmet and Helmet Mounted Display Systems Market |
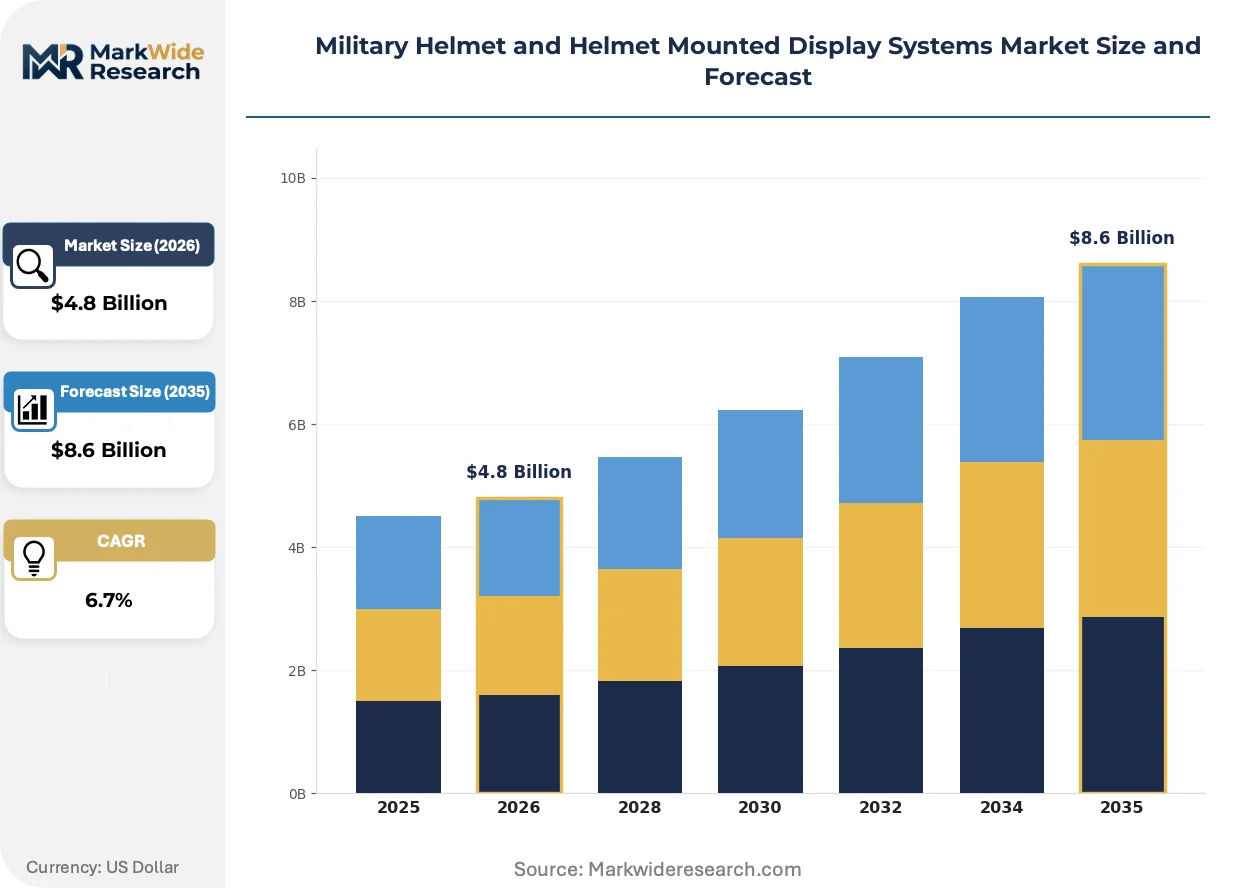
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Bump Helmets, Integrated Systems, Headsets Technology: Augmented Reality, Night Vision, Thermal Imaging, Communication Systems End User: Military Forces, Law Enforcement, Special Operations, Security Contractors Application: Combat Operations, Training Exercises, Surveillance Missions, Tactical Support |
| Companies Covered | RTX Corporation, BAE Systems plc, L3Harris Technologies, Inc., Thales Group, Elbit Systems Ltd., Honeywell International Inc., Leonardo S.p.A., Avon Technologies plc, Gentex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Helmet and Helmet Mounted Display Systems Market Shifts & Advancements
Digital visor technology is compressing the traditional separation between protective equipment and information systems, forcing suppliers to master both ballistic engineering and software-defined interfaces.
Augmented reality battlefield overlays are converging with existing night vision fusion architectures to create single-aperture vision systems. U.S. special operations forces are field-testing these integrated platforms during close-quarters combat scenarios. This convergence is collapsing the historical procurement separation between helmet manufacturers and electro-optics specialists, forcing joint development contracts.
NATO STANAG 4695 ballistic test protocols are mandating multi-hit protection standards against rifle threats beyond traditional handgun specifications. European defense procurement agencies are embedding these requirements into framework agreements with 10-year supply horizons. Israeli and German suppliers are investing in automated ballistic testing facilities to compress certification timelines for new composite formulations.
Consolidated platform procurement is displacing component-level purchasing across major military end users. The U.S. Army's Soldier Lethality Cross-Functional Team is negotiating sole-source integrated helmet contracts combining protection, display, and power management. This behavioral shift is visible most acutely in U.S. Pacific Command exercises, where interoperability testing now occurs at platform rather than subsystem level.
Military Helmet and Helmet Mounted Display Systems Market Segmentation
Segmentation in military helmet systems separates commodity protective gear from integrated digital platforms commanding substantial procurement premiums. Force protection mandates sustain baseline helmet volumes while special operations requirements concentrate investment in augmented reality and sensor fusion architectures.
Product Type:
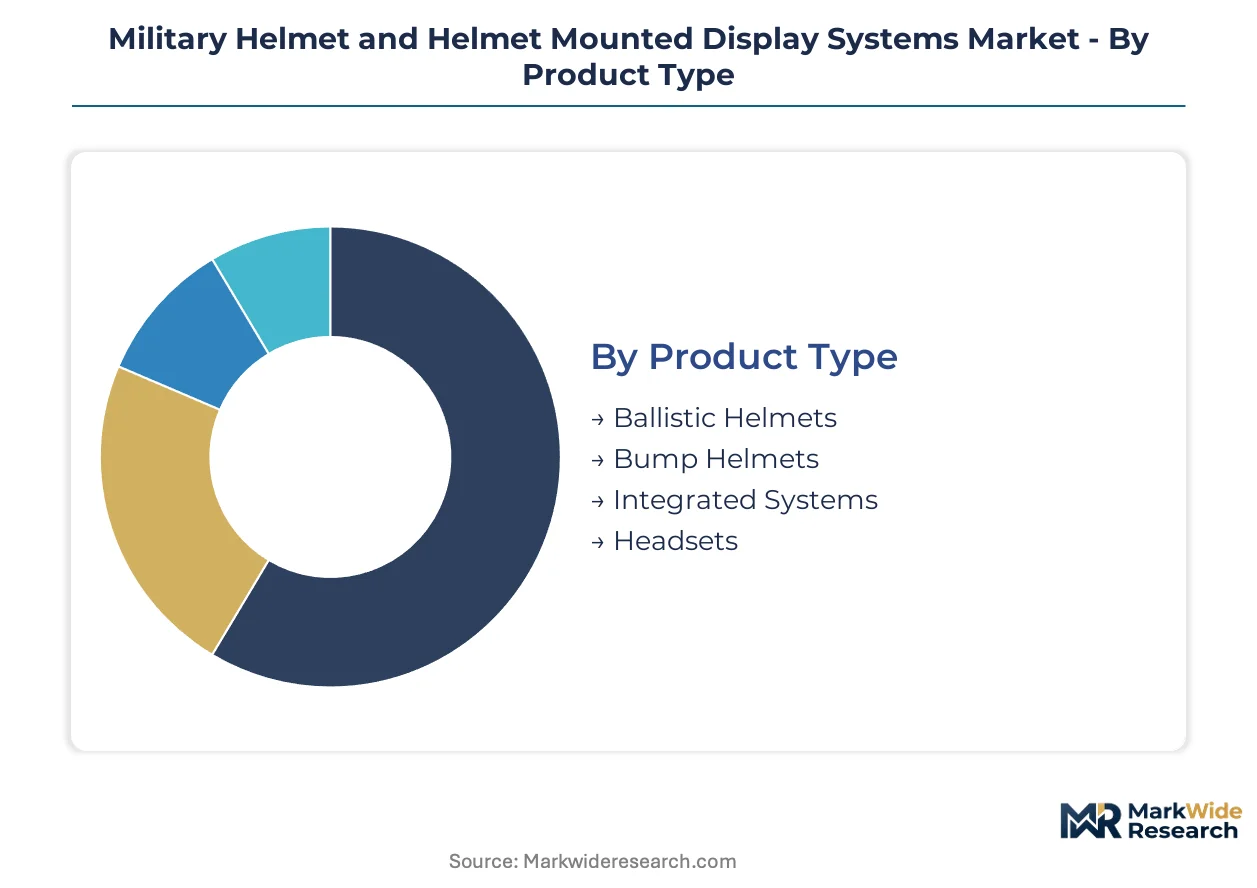
Ballistic helmets dominate procurement volumes through universal force protection requirements, yet integrated systems capture the steepest expansion trajectory as NATO members consolidate platform architectures.
- Ballistic Helmets:Manufactured from ultra-high-molecular-weight polyethylene or aramid composites rated to NIJ Level IIIA standards. The U.S. Army's Soldier Protection System and parallel European modernization programs sustain replacement cycles across conventional infantry formations, though unit economics favor bulk procurement over technology differentiation.
- Integrated Systems:Combine protective shells with helmet-mounted displays, power management, and communication interfaces in single-platform architectures. Special Operations Command requirements in the United States, Germany, and Israel compress supplier qualification timelines while elevating technical barriers for component-only vendors.
- Bump Helmets:Lightweight polymer shells designed for training environments and vehicle crew protection where ballistic threats are minimal. Demand concentrates in domestic security and training facility procurement.
- Headsets:Audio communication accessories mounting to standard rail systems, typically procured separately from protective shells except in integrated platform contracts.
Today's leader: Ballistic Helmets. Tomorrow's challenger: Integrated Systems.
Technology:
Technology segmentation tracks the migration from passive optical devices to software-defined vision systems with embedded processing capabilities.
- Night Vision:Image intensification systems remain the largest installed base across NATO member states, with the U.S. Army's Enhanced Night Vision Goggle-Binocular program sustaining procurement concentration. Image tube supply constraints and export control classifications limit vendor flexibility.
- Augmented Reality:Waveguide displays and optical engines overlay tactical data onto direct vision. The U.S. Indo-Pacific Command's jungle warfare specifications and close-quarters combat requirements accelerate field-testing of single-aperture vision systems combining night vision with digital overlays.
- Thermal Imaging:Uncooled microbolometer sensors detect infrared signatures for target acquisition in obscured environments. Demand clusters in special operations and surveillance applications.
- Communication Systems:Radio integration modules enabling networked target handoff and situational awareness sharing. AN/PRC-152 interoperability requirements complicate firmware architecture design.
Night Vision anchors current procurement volumes; Augmented Reality climbs fastest as militaries prioritize real-time data overlay.
End User:
End user segmentation reveals procurement concentration in tier-one units with dedicated modernization budgets versus force-wide replacement cycles.
- Military Forces:Conventional army, marine, and air force ground personnel requiring standardized protection across mass infantry formations. Procurement runs through defense ministry framework agreements with multi-year supply horizons.
- Special Operations:Tier-one units in the United States, Germany, and Israel drive integrated helmet-display demand through unclassified but substantial modernization budgets. These units field-test converged night vision and augmented reality platforms before conventional adoption.
- Law Enforcement:Domestic tactical units procure ballistic helmets with limited display integration, constrained by municipal budget cycles and civil liberties oversight.
- Security Contractors:Private military companies operating in high-threat environments purchase commercial-off-the-shelf configurations without classified system access.
Military Forces sustain volume; Special Operations define technology roadmaps.
Application:
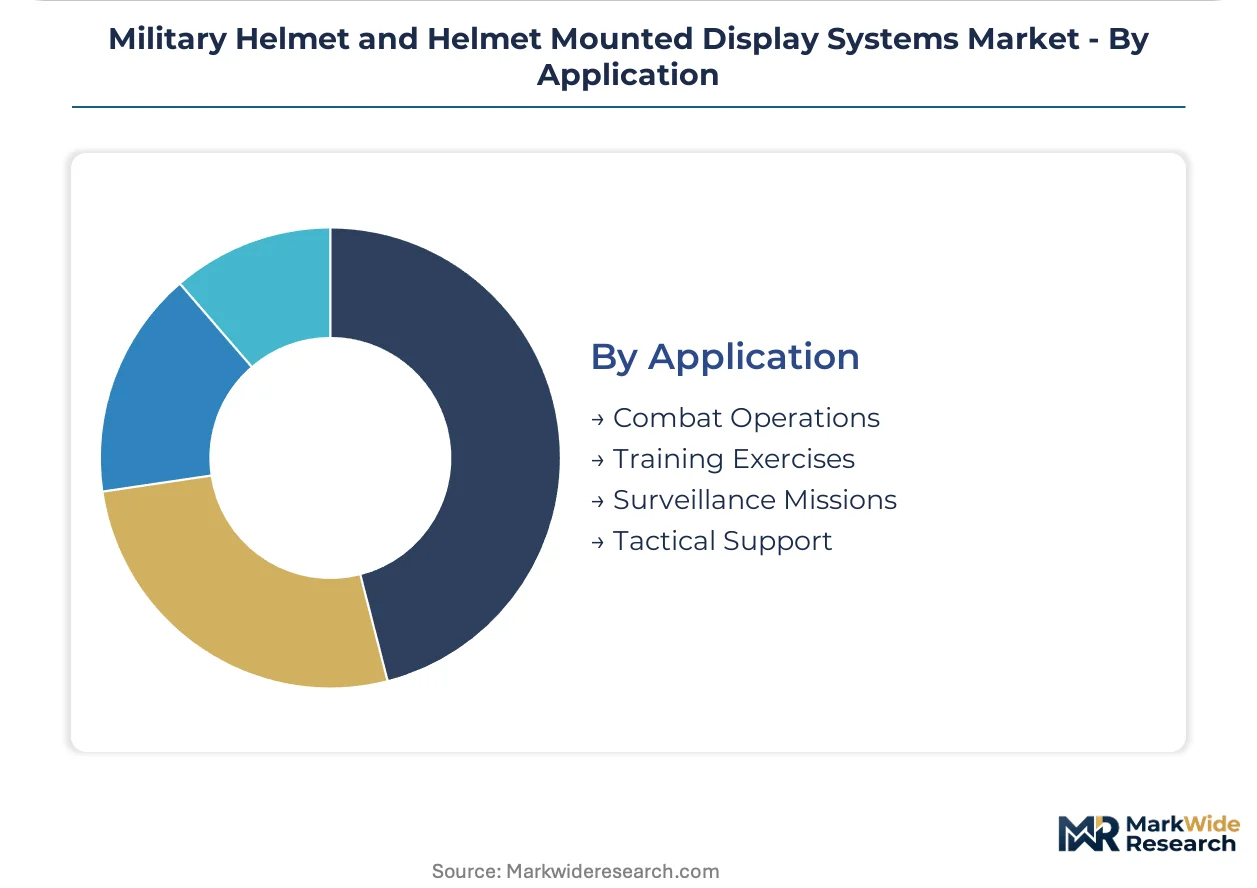
Application segmentation distinguishes between life-cycle procurement phases and operational intensity requirements.
- Combat Operations:Full-spectrum integrated systems deployed in contested environments requiring networked targeting and ballistic protection. NATO STANAG 4695 multi-hit standards and electromagnetic compatibility certifications govern qualification.
- Training Exercises:Bump helmets and simulation-compatible displays support force preparation without exposing premium equipment to accelerated wear. U.S. Pacific Command exercises now test interoperability at platform rather than subsystem level.
- Surveillance Missions:Extended-duration observation requiring lightweight configurations with thermal and night vision fusion. Power density limitations restrict continuous high-resolution microdisplay operation below four-hour thresholds.
- Tactical Support:Vehicle crew and logistics personnel requiring communication integration with reduced ballistic specifications compared to dismounted infantry.
Combat Operations command premium positioning; Training Exercises expand addressable volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling helmet system assembly toward jurisdictions with streamlined defense export licensing and lower ballistic certification costs, while NATO STANAG harmonization limits specification divergence that would otherwise fragment procurement.
United States
The U.S. Army's Enhanced Night Vision Goggle-Binocular program and Soldier Lethality Cross-Functional Team sustain concentrated demand for integrated helmet-display architectures. NHTSA-influenced acquisition standards and MIL-STD-461 electromagnetic compatibility protocols govern supplier qualification timelines extending 14-18 months. Defense manufacturing clusters in Texas and Arizona host automated ballistic testing facilities compressing certification cycles for new ultra-high-molecular-weight polyethylene formulations.
Germany
Bundeswehr special operations modernization and framework agreements with 10-year supply horizons anchor European procurement concentration for NATO STANAG 4695 multi-hit rated systems. The KBA coordinates defense procurement alignment with EU CE marking frameworks and parallel EDA coordination mechanisms. Industrial engineering capabilities in Bavaria and Baden-Württemberg support indigenous helmet assembly capacity with technology transfer partnerships extending to Baltic frontline states.
Israel
Israel Defense Forces field-testing programs and unclassified special operations budgets drive integrated visor solution development for close-quarters combat scenarios. The country's national defense regulator enforces rigorous electromagnetic compatibility and ballistic testing protocols shaping export qualification requirements. Electro-optics engineering clusters in Haifa and the Tel Aviv metropolitan area anchor production line expansion meeting rising international export commitments for helmet-mounted display systems.
Poland
Frontline NATO positioning and indigenous defense modernization mandates are establishing domestic helmet assembly capacity through technology transfer agreements with Israeli and German suppliers. The country's national defense procurement agency coordinates framework agreements embedding NATO STANAG 4695 multi-hit protection standards. Manufacturing investments in the Warsaw metropolitan area and Silesian industrial corridor target regional supply hub status for Baltic and Eastern European military end users.
United Kingdom
British Army soldier modernization programs and special operations procurement concentration sustain demand for integrated helmet systems combining ballistic protection with augmented reality overlays. The Ministry of Defence enforces qualification timelines aligned with NATO STANAG harmonization and electromagnetic compatibility certification requirements. Defense engineering clusters in the Midlands and South East England support joint development contracts collapsing historical separation between helmet manufacturers and electro-optics specialists.
Military Helmet and Helmet Mounted Display Systems Market Competitive Landscape
United States producers anchor one tier; Israeli and European specialists hold differentiated positions in integrated electro-optics and visor solutions. The vendor base organizes around three strategic tiers: diversified aerospace-defense conglomerates with captive helmet divisions, pure-play electro-optics houses with software-defined display expertise, and mid-tier ballistic protection specialists seeking display integration partnerships. Consolidation pressure is accelerating through sole-source integrated platform contracts and joint development agreements spanning protection, display, and power management subsystems.
Within the diversified conglomerate tier, RTX Corporation, BAE Systems plc, and L3Harris Technologies, Inc. represent archetypal positioning across integrated defense electronics and soldier system architectures. These entities occupy positions where scale advantages in electromagnetic compatibility certification and NATO qualification timelines create defensive moats against component-only competitors. Their market presence exemplifies the convergence pattern collapsing procurement separation between helmet manufacturers and electro-optics specialists.
| Leading Market Players |
|---|
| RTX Corporation |
| BAE Systems plc |
| L3Harris Technologies, Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| Honeywell International Inc. |
| Leonardo S.p.A. |
| Avon Technologies plc |
| Gentex Corporation |
| Others |
Supply & Pricing Matrix
NATO STANAG 4695 multi-hit protection mandates are compressing supplier qualification timelines while forcing manufacturers to absorb elevated ballistic testing costs, which in turn stratifies pricing across certified and uncertified vendor tiers. Procurement officers in U.S. special operations units and Bundeswehr modernization programs prioritize electromagnetic compatibility certification over unit cost, creating pricing power for qualified suppliers while marginalizing component-only vendors.
Pricing Analysis
Direct-to-defense-OEM contracting eliminates distributor margins that historically ran 15-25% in commercial protective equipment, compressing channel economics for non-integrated suppliers. Pricing stratifies across integrated platform architectures, component subsystems, and replacement parts tiers, with differentiation driven by NIJ certification level and NATO STANAG compliance status. Cost compression in standard ballistic helmets is intensifying as Polish and Baltic assembly capacity comes online, while premium integrated systems command pricing resilience due to electro-optics engineering scarcity. Tier-one special operations units exhibit lowest price sensitivity; municipal law enforcement procurement shows highest budget constraint.
Supply Chain Analysis
Refurbishment flows for night vision image intensification tubes and lithium-ion power modules are emerging as secondary supply channels, particularly for training-grade equipment in domestic security applications. Raw material sourcing draws from U.S. ultra-high-molecular-weight polyethylene resin production, Israeli electro-optics component fabrication, and German precision optics finishing. Para-aramid precursor supply rests on concentrated Asian chemical conglomerate output, creating single-source vulnerability for Western ballistic shell manufacturers. Distribution runs through defense ministry framework agreements with multi-year supply horizons, supplemented by technology transfer partnerships establishing indigenous assembly in frontline NATO states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military helmet and helmet mounted display systems market functions as a stable compounder, with NATO member state defense modernization mandates and special operations procurement concentration providing durable demand visibility across replacement cycles.
For Market Incumbents: Deepen captive supply of ultra-high-molecular-weight polyethylene resin and waveguide display optical engines to insulate margins from para-aramid fiber export restrictions and electro-optics engineering talent scarcity. Accelerate automated ballistic testing facility investments to compress NATO STANAG 4695 certification timelines below competitor qualification windows. For New Entrants and Emerging Players: The mid-tier pricing gap between Israeli-German integrated platform premiums and standard ballistic helmet commodity economics offers entry space for regional assembly specialists. Target Polish and Baltic indigenous capacity buildouts through technology transfer partnerships rather than direct OEM competition. Pursue sole-source training equipment contracts as qualification pathway toward combat system integration. For Investors and Strategic Acquirers: Asymmetric upside sits with electro-optics specialists possessing software-defined display architectures and existing NATO electromagnetic compatibility certification. Long-term viability favors platforms combining ballistic protection, augmented reality overlays, and power management in single-vendor architectures. Monitor U.S. Indo-Pacific Command jungle warfare specification releases as inflection indicator for corrosion-resistant mounting system demand.| Strategic Initiative | Industry Significance |
|---|---|
| NATO STANAG 4695 Certification Investment | Automated ballistic testing facilities in Texas and Bavaria compress qualification timelines for multi-hit rifle-rated composite formulations. |
| Electro-Optics Engineering Acquisition | Waveguide display and optical coating specialist recruitment addresses talent scarcity constraining R&D expansion at mid-tier suppliers. |
| Technology Transfer Partnership | Israeli and German suppliers establish Polish and Baltic indigenous assembly capacity through framework agreements embedding NATO harmonization standards. |
| Integrated Platform Contract Negotiation | U.S. Army Soldier Lethality Cross-Functional Team sole-source awards collapse historical procurement separation between protection and display vendors. |
| AI-Enabled Targeting Module Development | Edge-computing sensor fusion architectures enable real-time threat classification without external data link dependency in contested environments. |
Research Methodology
Direct dialogue with defense procurement officers, special operations program managers, electro-optics engineering directors, ballistic testing facility operators, and NATO standardization committee participants grounded qualitative assessment. Secondary validation drew from U.S. Department of Defense budget justification materials, NATO STANAG documentation, EU defense procurement coordination records, and defense contractor SEC disclosures. Bottom-up unit economics triangulated against top-down defense ministry expenditure frameworks.
Bottom-up modeling segmented volume and value across product type, technology, end user, and application dimensions, with additional granularity for NIJ certification tier and NATO STANAG compliance status. CAGRs were derived from replacement cycle analysis of legacy Kevlar inventories and procurement acceleration in integrated platform architectures. Forecast inputs incorporated U.S. Enhanced Night Vision Goggle-Binocular program schedules and Bundeswehr special operations modernization budget trajectories.
Caveats apply where para-aramid precursor export restrictions, lithium-ion battery energy density limitations, or electromagnetic compatibility certification delays could materially shift the outlook. Forecasts reflect assumptions regarding NATO STANAG harmonization continuity and special operations procurement concentration persistence. Practitioners should monitor U.S. Pacific Command interoperability exercise outcomes and Baltic defense assembly capacity utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Asia-Pacific Digital Battlefield Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Global Non Lethal Biochemical Weapon Market
Defense and Military Systems and Equipment
Command and Control Systems Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Anti-Jamming Equipment Market
Defense and Military Systems and Equipment
Soldier System Market