
 Shoe Rack Market | 2026-2036
Shoe Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Shoe Rack Market Analysis
Multi-source component sourcing is consolidating among leading shoe rack manufacturers as they seek greater control over material quality and delivery timelines. Inter IKEA Systems B.V. leverages its captive supply chain to maintain cost discipline across flat-pack furniture categories. Godrej Industries Limited anchors its position through in-house metal fabrication capabilities serving Indian households. Williams-Sonoma Inc. differentiates via premium wood finishing and direct-to-consumer channel control in North American markets.
A shoe rack is a freestanding or wall-affixed storage fixture engineered to organize, protect, and display footwear through tiered shelving, enclosed cabinets, or modular stacking systems, typically constructed from engineered wood, powder-coated steel, molded polypropylene, or woven textile composites with load ratings between 15 and 50 kilograms. Floor-standing units dominate residential volume due to their installation flexibility and lower price entry points, while wall-mounted designs command higher margins among urban consumers prioritizing floor space conservation. Metal and wood material segments capture the majority of value pools, with plastic and fabric alternatives occupying economy positioning in mass retail channels.
ISO furniture stability standards, the EU Green Deal sustainable sourcing requirements, and China's GB standards for indoor air quality from composite materials collectively shape product compliance costs and market access conditions for cross-border suppliers. The US EPA guidelines on formaldehyde emissions from pressed wood products directly influence material selection for manufacturers targeting American households. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and Asia that will redefine end-of-life collection obligations and material recovery specifications.
Market Dynamics
Urban densification across metropolitan clusters is compressing residential floor space, forcing storage solution design toward vertical and modular architectures that maximize capacity per square meter.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Certification requirements for recycled metal and FSC-certified wood inputs are accelerating material substitution across European supply chains.
- E-commerce platform penetration in China:Live-streaming commerce and same-day delivery networks are collapsing traditional furniture retail cycles for residential accessories.
- Modular polypropylene stacking systems:Injection-molded interlocking components enable consumer-configurable capacity expansion without tools or permanent installation.
Market Restraints
- Pressed wood formaldehyde compliance costs:US EPA emission standards require CARB Phase 2 or TSCA Title VI certification, adding 8-12% to material procurement expenses for engineered wood suppliers.
- Container freight rate volatility:Asia-to-North America shipping cost swings between 2,400 and 8,600 USD per TEU destabilize landed cost forecasting for flat-pack imports.
- Wall-mounted load-bearing limitations:Rental housing lease restrictions and drywall anchor failure risks cap addressable demand for suspended storage among apartment dwellers.
Strategic Opportunities
- Extended producer responsibility frameworks in Germany and France:Upcoming collection and recycling mandates create first-mover advantage for closed-loop material recovery infrastructure.
- Smart home integration:RFID-tagged inventory tracking and climate-controlled cabinet interiors are converging with residential IoT ecosystems.
- Direct-to-consumer subscription rental:Furniture-as-a-service models targeting transient urban professionals in London and New York bypass retail markup and disposal friction.
Industry Challenges
- Cross-border customs classification complexity:HS code ambiguity between furniture and metal household goods triggers duty disputes and clearance delays at EU and US ports.
- Composite material air quality certification timelines:China's GB standards testing protocols require 28-45 day laboratory queues, compressing product launch windows for seasonal collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoe Rack Market |
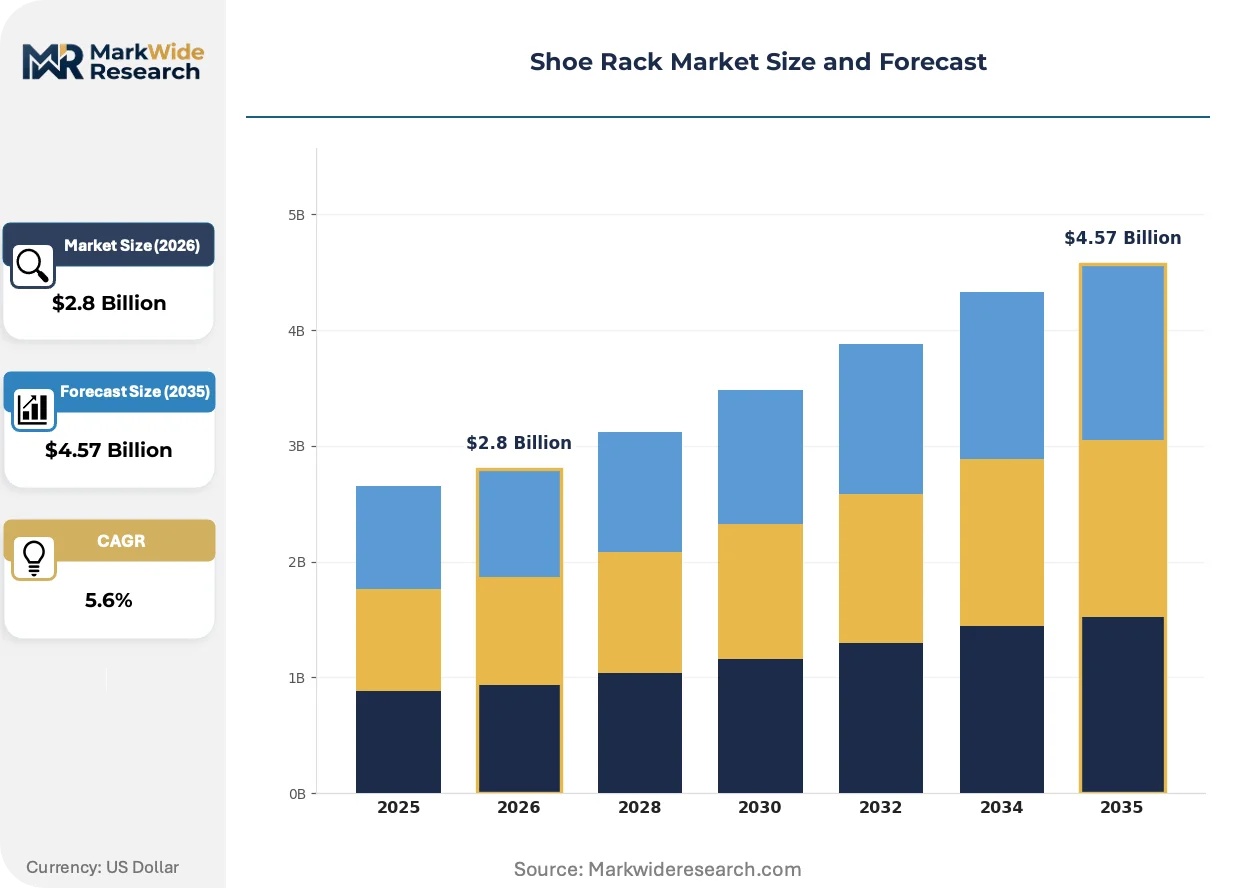
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor-Standing, Wall-Mounted, Stackable, Portable Material: Wood, Metal, Plastic, Fabric End User: Households, Retail Stores, Offices, Shoe Manufacturers Design Style: Modern, Rustic, Minimalist, Traditional |
| Companies Covered | Kartell P.I., Whitmor, Inc., Inter IKEA Systems B.V., honeycando.com, Seville Classics, Inc., Williams-Sonoma Inc., Ethan Allen Global, Inc., TOPMAX, Godrej Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoe Rack Market Emerging Trajectories
Active experimentation with bio-based binders and automated assembly is compressing production lead times while raising performance benchmarks for residential storage hardware.
Bamboo-epoxy composite laminates are converging with traditional hardwood aesthetics at 40% lower carbon intensity. Japanese and Scandinavian manufacturers are adopting these materials for premium tier positioning. The structural consequence is converging with price compression in the mid-market wood segment as supply scales.
REACH SVHC candidate list expansion is forcing substitution of chromium VI in powder-coated steel finishes. Surface treatment suppliers are migrating to zirconium-based pretreatment and polyester TGIC-free formulations. Small-batch metal fabricators in Italy and Poland are absorbing compliance costs through premium positioning rather than volume scaling.
Rental housing operators in Seoul and São Paulo are bundling modular shoe storage into standardized tenant fit-out packages. Property management platforms are displacing individual consumer purchase decisions with bulk procurement contracts. This pattern is most visible in build-to-re residential developments where tenant turnover exceeds 35% annually.
Shoe Rack Market Segmentation
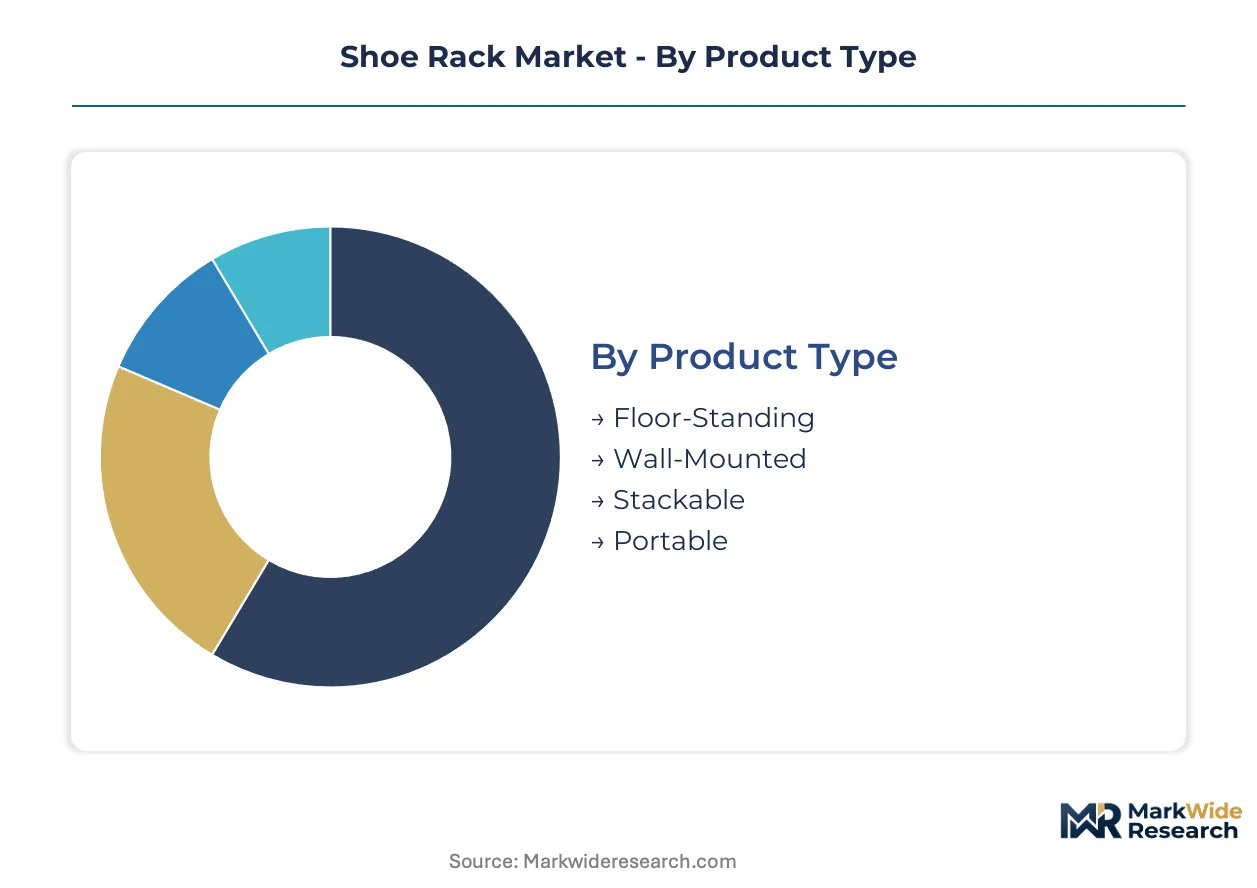
Shoe rack manufacturers configure production lines around distinct material and mounting specifications that determine freight density, assembly complexity, and retail margin structures. Segmentation discipline separates mass-market plastic injection molders from premium wood finishers serving distinct household and commercial procurement channels.
Product Type:
Supply concentration among flat-pack furniture specialists tilts volume toward freestanding formats that minimize last-mile delivery damage and customer assembly friction.
- Floor-Standing:Vertical shelving units with weighted bases and cantilevered tiers accommodate 15-50 kilogram loads without wall anchoring. Chinese e-commerce platforms and Indian urban apartment complexes are driving procurement of these entry-level formats for their installation flexibility and lower price points.
- Wall-Mounted:Suspended systems with concealed brackets and stud-mounting hardware maximize floor space in Tokyo, Seoul, and São Paulo micro-apartments. Rental housing lease restrictions and drywall anchor failure risks constrain addressable demand despite premium positioning.
- Stackable:Interlocking polypropylene modules enable consumer-configurable capacity expansion without tools. Injection molders in Zhejiang and Guangdong dominate component supply for this segment.
- Portable:Collapsible textile and lightweight metal frames target transient professionals in London and New York rental markets. Frequent relocation patterns favor disassembly and flat storage.
Today's leader: Floor-Standing. Tomorrow's challenger: Wall-Mounted.
Material:
Cost tier stratification aligns raw material procurement with certification burdens and end-use durability requirements across residential and commercial applications.
- Wood:Engineered boards with CARB Phase 2 or TSCA Title VI certification dominate North American retail. EU Green Deal FSC requirements and US EPA formaldehyde standards add 8-12% to procurement costs for compliant suppliers.
- Metal:Powder-coated steel with zirconium-based pretreatment replaces chromium VI finishes under REACH SVHC expansion. Italian and Polish fabricators absorb compliance costs through premium positioning rather than volume scaling.
- Plastic:Injection-molded polypropylene serves economy positioning in mass retail channels across India and Southeast Asia. Modular interlocking designs reduce tooling amortization per SKU.
- Fabric:Woven textile composites with aluminum or fiberglass framing occupy portable and temporary storage niches. Lower freight density supports direct-to-consumer shipping economics.
Wood commands current value pools. Metal is climbing the fastest on sustainability certification premiums.
End User:
Volume distribution favors residential procurement, though commercial accounts offer contract stability and standardized specification advantages.
- Households:Individual consumers purchasing through furniture retailers, e-commerce platforms, and home improvement chains. Urban densification in Chinese and Indian metropolitan clusters compresses floor space and elevates vertical storage priority.
- Retail Stores:Footwear merchandising fixtures with integrated lighting and mirror systems. Brand-specific color matching and modular reconfiguration requirements favor captive supplier relationships.
- Offices:Corporate wellness and hot-desking policies generate demand for personal storage in hybrid workplaces. Procurement concentrates through facility management contracts.
- Shoe Manufacturers:Industrial-grade racking for finished goods inventory and quality control staging. Load ratings and fire safety compliance exceed residential specifications.
Households anchor present volume. Retail Stores present the steepest expansion trajectory on experiential merchandising investment.
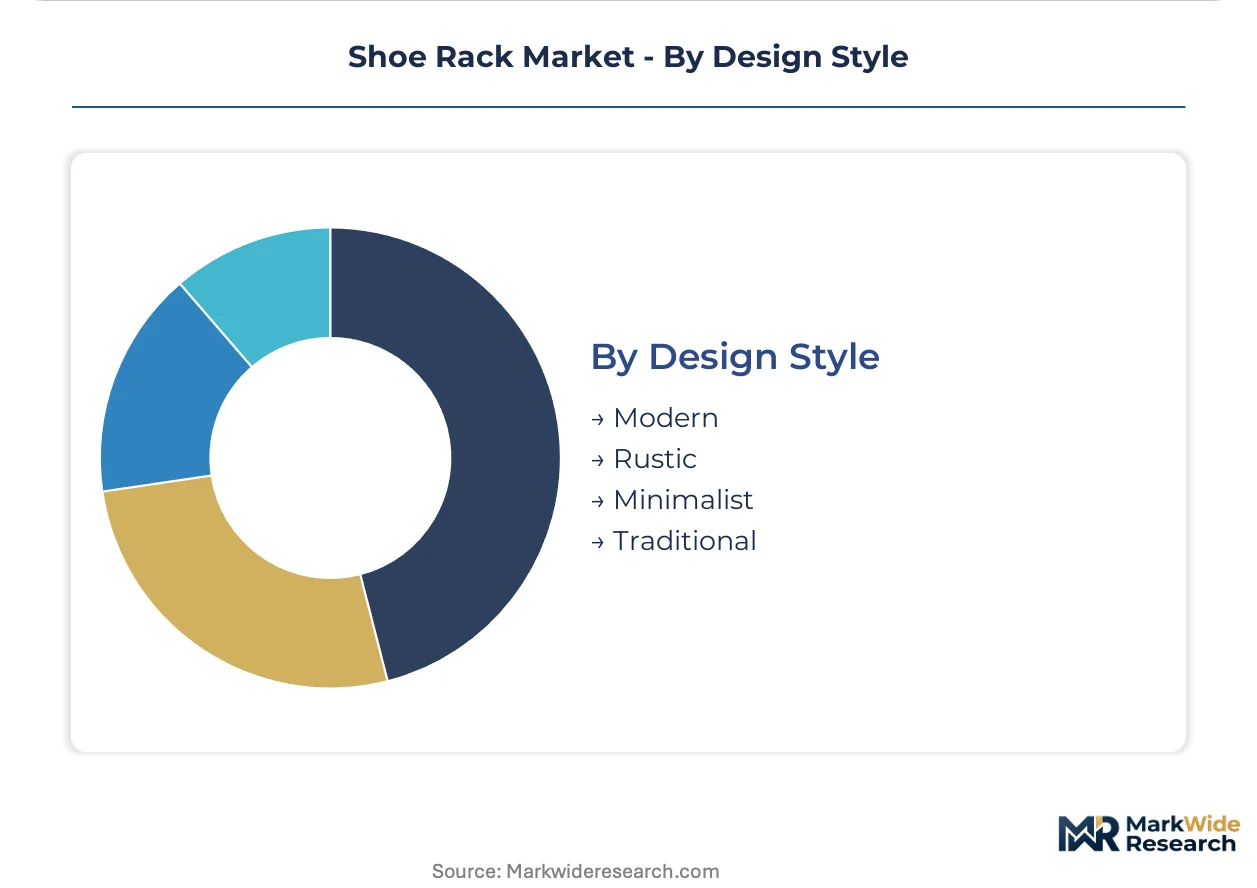
Design Style:
Margin differentiation separates mass-produced standardized finishes from artisan-crafted positioning in premium channels.
- Modern:Clean lines, matte surfaces, and neutral palettes align with Scandinavian and Japanese interior trends. Godrej Industries and Inter IKEA Systems B.V. scale production across this segment.
- Rustic:Distressed wood, wrought iron accents, and farmhouse aesthetics command price premiums in North American specialty retail. Smaller-batch production limits supplier concentration.
- Minimalist:Concealed hardware, floating appearances, and monochromatic schemes target urban professional demographics in Berlin and Copenhagen.
- Traditional:Ornate carving, rich stains, and classical proportions serve heritage home restoration and formal entryways. European and North American custom furniture shops retain share.
Modern styling dominates current production planning. Minimalist is gaining share fastest on apartment-dweller preference for visual lightness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting production flows as manufacturers seek jurisdictions with lower compliance burdens for engineered wood and metal finishing. The EU Green Deal's certification requirements and US EPA formaldehyde standards create cost differentials that reshape sourcing decisions across residential furniture supply chains.
United States
Urban apartment densification in New York and Los Angeles compresses floor space and elevates demand for wall-mounted and modular storage formats. EPA TSCA Title VI certification requirements for pressed wood products add 8-12% to material costs, filtering supplier participation. Manufacturing concentrates in North Carolina and Vietnam-sourced import corridors serving mass retail channels.
China
E-commerce platform penetration through Alibaba and JD.com collapses traditional furniture retail cycles for residential accessories. GB standards for indoor air quality from composite materials impose 28-45 day laboratory testing queues. Production clusters in Zhejiang and Guangdong provinces dominate injection-molded polypropylene component supply for stackable formats.
Germany
Extended producer responsibility frameworks mandate collection and recycling infrastructure for furniture end-of-life recovery. REACH SVHC expansion forces substitution of chromium VI in powder-coated steel finishes. Fabrication concentrates in North Rhine-Westphalia and Bavaria, where small-batch metalworkers absorb compliance costs through premium positioning.
India
Rising middle-class home improvement spending in Mumbai and Bangalore reshapes retail distribution for residential furniture accessories. BIS certification requirements for furniture stability standards filter import competition. Godrej Industries anchors domestic supply through in-house metal fabrication capabilities serving urban households.
Japan
Scandinavian and minimalist interior trends drive demand for concealed-hardware storage systems in Tokyo and Osaka micro-apartments. METI energy efficiency guidelines influence material selection for climate-controlled cabinet interiors. Bamboo-epoxy composite laminates from domestic manufacturers converge with traditional hardwood aesthetics at lower carbon intensity.
Shoe Rack Market Vendor Landscape
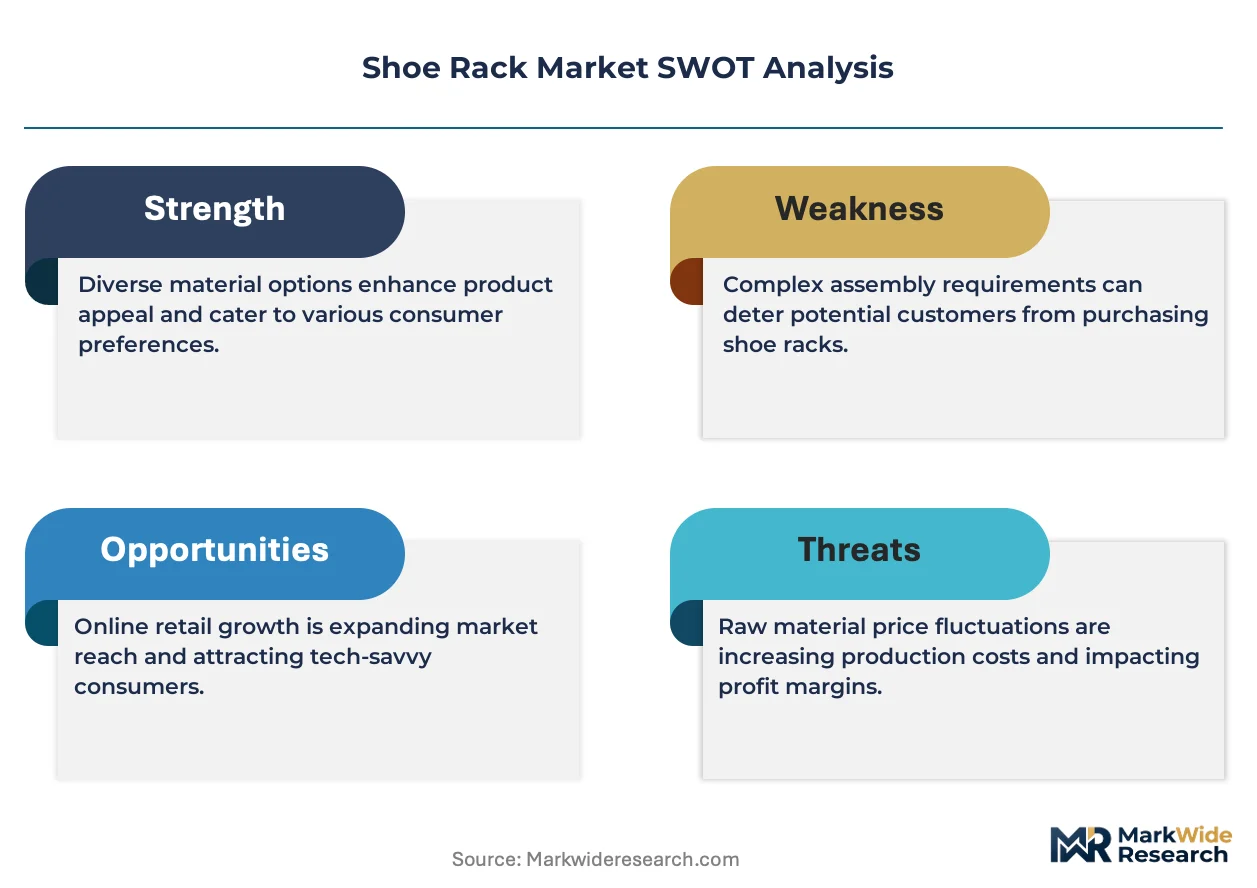
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in smart home integration and subscription rental models. The vendor base separates into three archetypes: flat-pack furniture specialists leveraging captive supply chains, premium wood finishers commanding direct-to-consumer channels, and metal fabricators absorbing regulatory compliance through positioning. Competitive moves concentrate on backward integration into material sourcing and geographic expansion through e-commerce platform partnerships.
Among flat-pack furniture specialists, Inter IKEA Systems B.V. exemplifies scale-driven supply chain control, while Williams-Sonoma Inc. occupies a position within the premium-tier wood finishing segment. Godrej Industries Limited represents the metal fabrication archetype with in-house production capabilities. These three anchors illustrate divergent strategic responses to regulatory cost pressures and channel fragmentation across residential furniture markets.
| Leading Market Players |
|---|
| Kartell P.I. |
| Whitmor, Inc. |
| Inter IKEA Systems B.V. |
| honeycando.com |
| Seville Classics, Inc. |
| Williams-Sonoma Inc. |
| Ethan Allen Global, Inc. |
| TOPMAX |
| Godrej Industries Limited |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between CARB Phase 2 compliant engineered wood and uncertified commodity inputs splits pricing power across North American and European supply chains, with certified suppliers commanding premium positioning while Asian producers absorb margin compression through volume scaling.
Pricing Analysis
Retailer markup layers in North American mass channels absorb 35-45 points of gross margin before reaching household buyers, while direct-to-consumer wood finishers capture full value through owned channels. Three-tier pricing structure across premium, standard, and economy levels aligns with FSC certification status and powder-coat finish durability grades. Cost compression in injection-molded polypropylene intensifies as Zhejiang molders expand capacity. Mass retail procurement teams exhibit highest price sensitivity; boutique interior designers show lowest.
Supply Chain Analysis
Engineered wood supply rests on North Carolina panel producers, Vietnamese CARB-certified export mills, and Baltic birch plywood fabricators serving EU Green Deal requirements. Powder-coated steel inputs draw from Italian and Polish metal finishers migrating to zirconium-based pretreatment. Single-source vulnerability concentrates in container freight corridors linking Zhejiang injection molders to North American distribution hubs. Distribution runs through Alibaba and JD.com platforms in China, IKEA and Williams-Sonoma direct channels in North America, and Godrej's captive retail network in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shoe rack market compounds steadily as urban densification across metropolitan clusters sustains replacement demand for space-efficient storage hardware.
For Market Incumbents: Extend backward integration into FSC-certified wood sourcing and captive metal fabrication to defend against margin erosion from REACH SVHC compliance costs. Anchor channel control through exclusive e-commerce platform partnerships in China and direct-to-consumer finishing capabilities in North America. Investment in automated assembly lines compresses lead times against emerging modular polypropylene specialists. For New Entrants and Emerging Players: Transient urban professionals in London and New York rental markets represent an underserved buyer archetype with low incumbent penetration and high willingness-to-pay for portable, collapsible formats. Subscription rental models bypass retail markup and disposal friction. White-space exists in climate-controlled cabinet interiors for smart home integration. Go-to-market through property management platforms serving build-to-rent developments with standardized tenant fit-out packages. For Investors and Strategic Acquirers: Consolidation pressure builds where small-batch Italian and Polish metal fabricators absorb REACH compliance costs through premium positioning rather than volume scaling. Long-term viability favors suppliers with captive certification infrastructure and direct channel control. Acquisition target archetype: mid-tier wood finishers with CARB Phase 2 compliance and underutilized e-commerce capacity. Watch container freight rate volatility as inflection indicator for import-dependent market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Wood Sourcing | FSC and CARB Phase 2 compliance locks out commodity competitors from premium retail placement. |
| Direct-to-Consumer Channel Expansion | Owned e-commerce platforms capture margin layers previously allocated to mass retail intermediaries. |
| Smart Home Integration Development | RFID inventory tracking and climate control converge shoe storage with residential IoT ecosystems. |
| Subscription Rental Model Launch | Furniture-as-a-service bypasses disposal friction for transient professionals in dense urban markets. |
| Extended Producer Responsibility Infrastructure | German and French collection mandates create first-mover advantage for closed-loop material recovery. |
Methodological Framework
Multiple input streams — primary interviews with furniture procurement managers at mass retail chains, supply chain directors at flat-pack specialists, and sustainability officers at metal fabricators — were reconciled against customs trade data, SEC 10-K filings from listed home furnishings companies, and GB standards laboratory queue records. Bottom-up SKU-level volume estimates and top-down category spend analysis were triangulated to constrain forecast variance.
Historical shipment patterns from North Carolina and Zhejiang production clusters were cross-referenced against panel input from category buyers at Alibaba and JD.com platform operators. Segmentation dimensions modeled include mounting format, material certification tier, design style cluster, and end-user procurement channel. CAGRs were derived from slope-constrained growth curves fitted to urban household formation rates and e-commerce penetration trajectories. Forecast inputs incorporated EU Green Deal implementation timelines and EPA formaldehyde standard enforcement phases.
Inputs from primary fieldwork and secondary regulatory filings were available through the study window; gaps in real-time container freight rate series and seasonal collection sell-through data introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding urban densification continuity and platform commerce adoption curves. A small set of triggers — REACH SVHC list expansion, extended producer responsibility mandate acceleration, and smart home protocol standardization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Shop Shelving Market