
 Janitorial Cleaning Equipment and Supplies Market | 2026-2036
Janitorial Cleaning Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Janitorial Cleaning Equipment and Supplies Market Foresight
The gap between premium autonomous cleaning systems and commodity mop-and-bucket setups is broadening as labor costs and hygiene expectations diverge. Tennant Company specializes in robotic floor scrubbers with LiDAR navigation for large-format retail. Diversey Holdings Ltd. anchors its position through concentrated chemical dispensing systems tied to IoT-enabled dilution control. Ecolab Inc. dominates the healthcare channel with EPA-registered disinfectant chemistries and on-site service auditing.
Janitorial cleaning equipment and supplies encompass mechanized floor maintenance machines, chemical formulations, and disposable tools engineered to remove soil, pathogens, and debris from commercial and institutional hard surfaces and soft flooring, typically operating at pressures from 500 to 4,000 PSI for pressure-based systems and incorporating surfactant blends optimized for specific substrate compatibility. Floor scrubbers lead capital expenditure among product types due to their labor substitution economics in facilities exceeding 50,000 square feet. Healthcare facilities represent the fastest-growing end-user segment as infection control protocols intensify post-pandemic. Disinfection applications command the highest margin pool within the application dimension because of concentrated chemical consumption rates and recurring validation requirements.
The EPA regulates antimicrobial claims through FIFRA registration, compelling reformulation cycles that favor established registrants with toxicology dossiers. OSHA's hazard communication standards and the evolving EU REACH framework for imported chemical substances shape material safety data sheet complexity and cross-border supply chain compliance burdens. Green Seal and ECOLOGO certifications function as de facto market access filters for institutional procurement contracts. Stakeholders must monitor how autonomous equipment interoperability standards and chemical disclosure mandates reshape capital deployment and supplier qualification timelines.
Market Dynamics
The janitorial cleaning equipment and supplies market is bifurcating around labor substitution economics, with autonomous floor scrubbers displacing manual crews in facilities exceeding 50,000 square feet while commodity consumables face margin compression from concentrated buyer power.
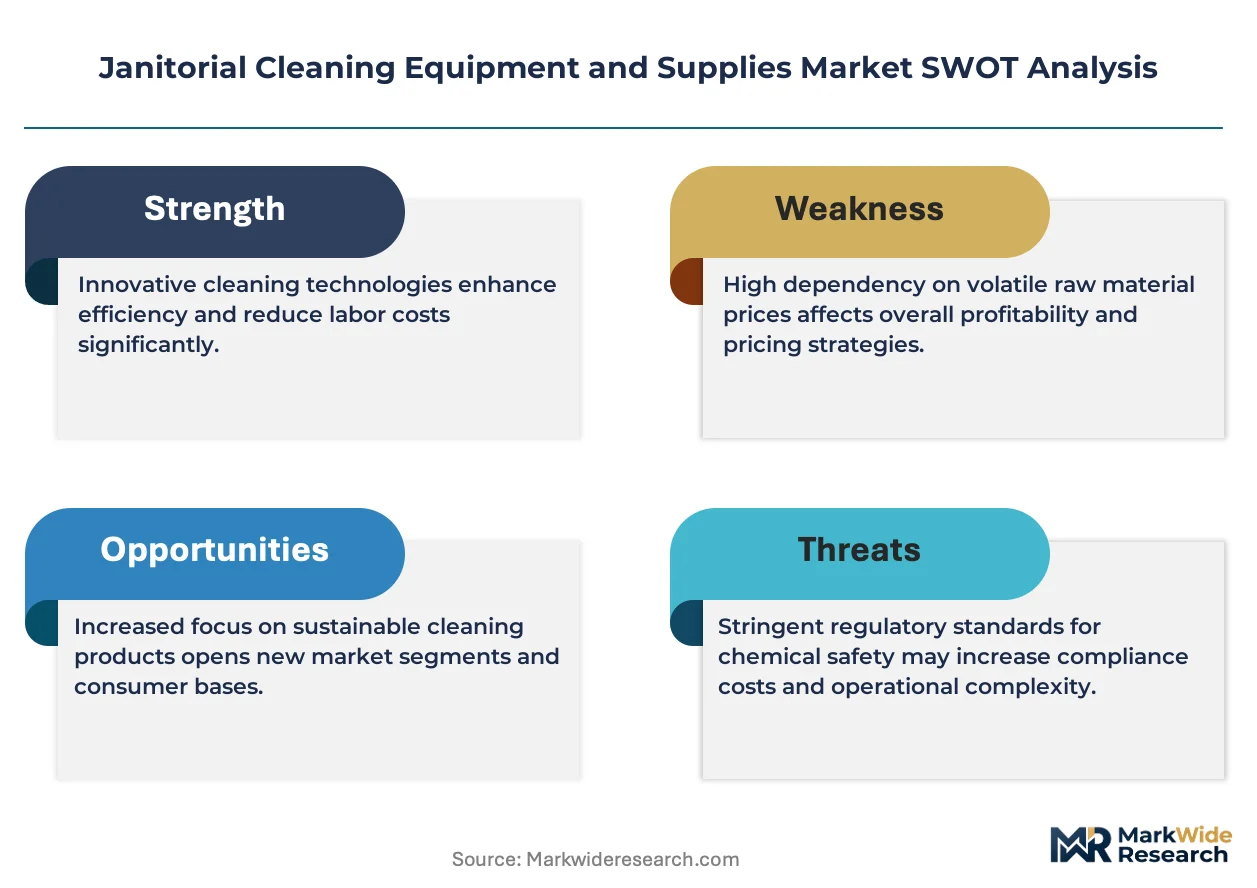
Growth Catalysts
- EPA Safer Choice program:Federal procurement mandates now require verified low-toxicity formulations, accelerating reformulation cycles among institutional chemical suppliers.
- Healthcare infection control protocols:Post-pandemic validation requirements for electrostatic disinfection systems are expanding capital budgets in acute care networks.
- Sun Belt metropolitan construction:Accelerated commercial square footage additions in Phoenix, Dallas, and Miami are concentrating demand for mechanized floor maintenance fleets.
Market Restraints
- LiDAR sensor supply concentration:Autonomous scrubber production depends on a narrow supplier base for navigation hardware, creating procurement bottlenecks.
- EU REACH compliance costs:Cross-border chemical shipments face escalating material safety data sheet complexity and toxicology dossier requirements.
- Manual mop-and-bucket substitution:Low-wage labor availability in smaller facilities undermines the payback calculus for capital equipment.
Strategic Opportunities
- IoT-enabled dilution control:Connected chemical dispensing systems create recurring revenue streams through usage-based consumable replenishment.
- Green Seal certification tailwinds:Institutional procurement contracts increasingly mandate third-party environmental validation, favoring pre-certified suppliers.
- India commercial real estate expansion:Underpenetrated facility management services in Bangalore and Mumbai present equipment leasing opportunities.
Industry Challenges
- Electro-mechanical technician scarcity:Autonomous equipment deployment requires maintenance capabilities that traditional janitorial staffing models lack.
- FIFRA registration timelines:EPA antimicrobial claim approvals extend 18-24 months, delaying new disinfectant chemistry commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Janitorial Cleaning Equipment and Supplies Market |
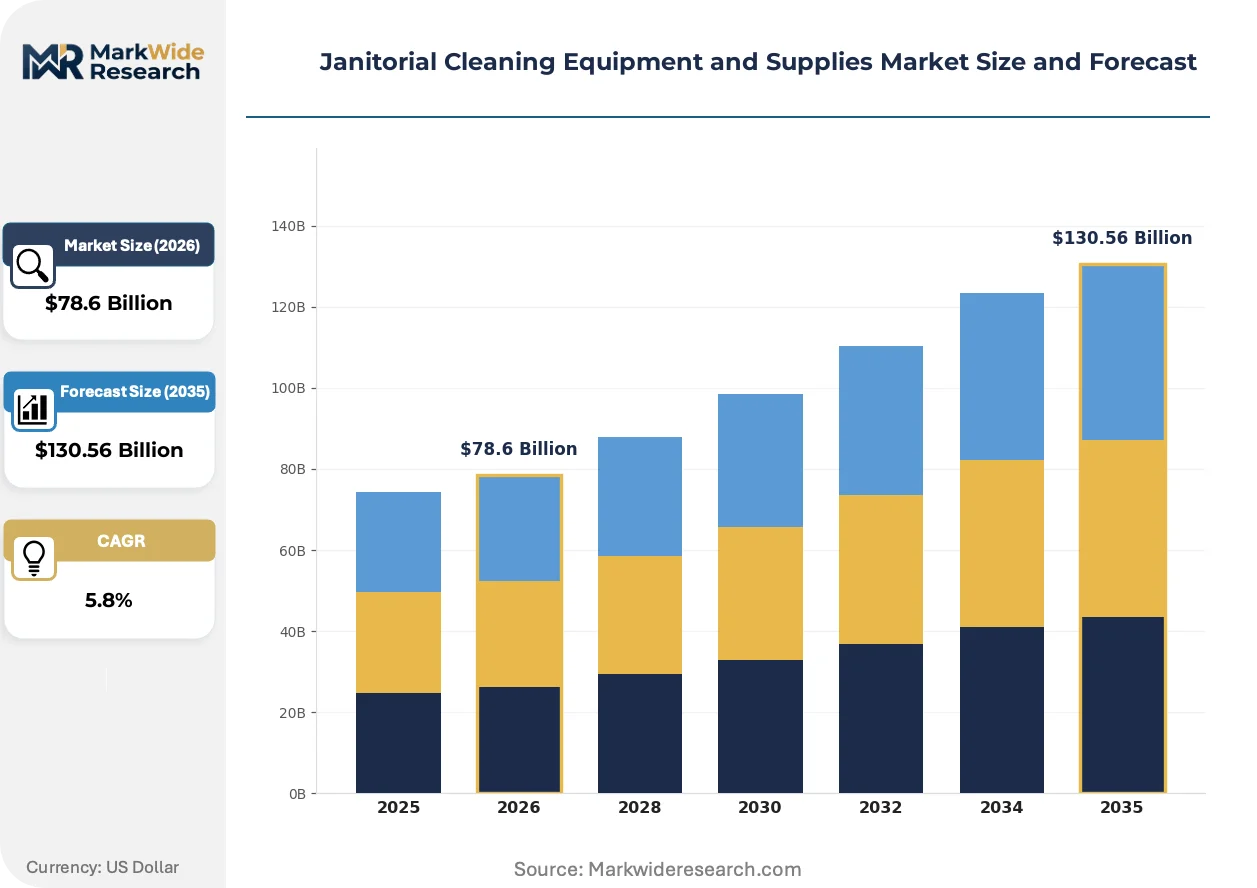
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $130.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Cleaners, Floor Scrubbers, Pressure Washers, Carpet Extractors End User: Commercial Buildings, Healthcare Facilities, Educational Institutions, Industrial Sites Application: Floor Maintenance, Surface Cleaning, Disinfection, Waste Management Service Type: Cleaning Services, Equipment Rental, Maintenance Services, Consultancy |
| Companies Covered | Nilfisk A/S, Diversey Holdings Ltd., Ecolab Inc., Zep Inc., Spartan Chemical Company, Alfred Kärcher SE & Co. KG, Hako GmbH, Betco, Tennant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Janitorial Cleaning Equipment and Supplies Market Shifts & Advancements
Automation and chemical disclosure mandates are converging to reshape competitive positioning, with equipment intelligence and formulation transparency becoming primary purchase criteria rather than ancillary features.
LiDAR-guided autonomous scrubbers are consolidating operational control in large-format retail and logistics facilities. Grocery chains and distribution centers are deploying these systems during off-peak hours to minimize labor overlap. The technology is consolidating vendor relationships as multi-site operators standardize on single-platform fleets to simplify training and parts inventory.
REACH framework amendments are tightening disclosure requirements for imported surfactant blends. Chemical suppliers must now submit extended safety data for downstream use scenarios. Institutional buyers in Germany and France are responding by pre-qualifying registrants with complete toxicology dossiers, compressing the approved vendor pool.
Facility managers are bundling equipment leases with consumable supply contracts to lock in operational expenditure predictability. This model displaces traditional capital purchase cycles in healthcare and education verticals. The shift is most visible in United States metropolitan hospital networks seeking to outsource infection control validation liability.
Janitorial Cleaning Equipment and Supplies Market Segmentation
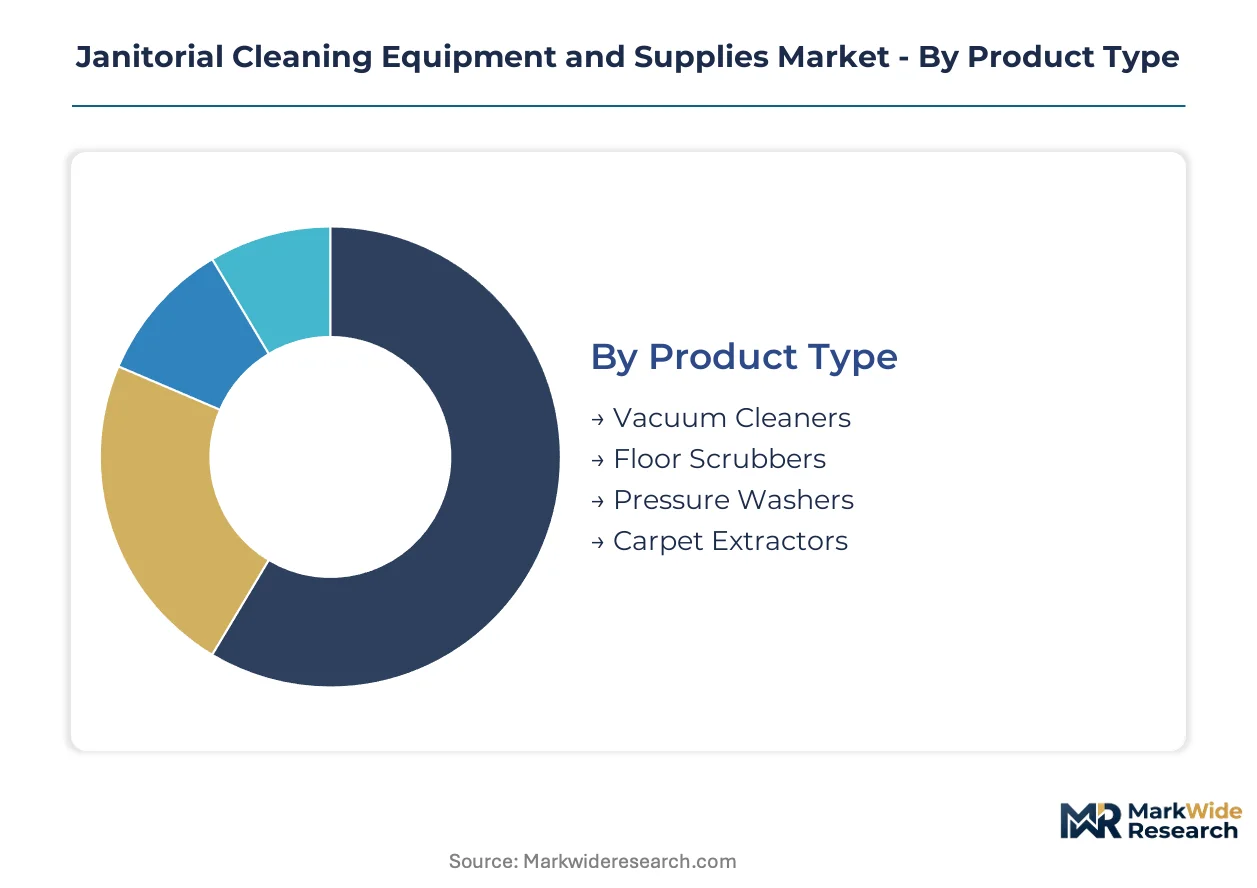
The janitorial cleaning equipment and supplies market fragments across equipment intensity, end-use hygiene requirements, and service delivery models. Each dimension carries distinct procurement patterns, margin profiles, and regulatory exposure that shape supplier positioning.
Product Type:
Capital deployment varies dramatically across this dimension, with autonomous floor scrubbers demanding six-figure upfront investment while portable vacuum cleaners operate at commodity price points.
- Floor Scrubbers:Battery-powered autonomous units with LiDAR navigation and water recovery systems dominate large-format retail deployment. Healthcare networks in the United States are expanding fleets to meet Joint Commission infection control standards while offsetting wage inflation in maintenance crews.
- Pressure Washers:Hot-water and cold-water configurations span 500 to 4,000 PSI operating ranges for concrete, facade, and fleet cleaning. Industrial sites across Texas and Arizona are concentrating demand for heavy-duty gas-powered units tied to construction equipment maintenance contracts.
- Vacuum Cleaners:HEPA-filtered backpack and canister units serve educational institutions with asthma-sensitive occupancy requirements.
- Carpet Extractors:Heated extraction machines with adjustable PSI settings target hospitality and corporate office deep-cleaning schedules.
Floor scrubbers absorb the bulk of installed capital expenditure; pressure washers are expanding most quickly in Sun Belt construction corridors.
End User:
Procurement sophistication diverges sharply across this dimension, with healthcare facilities operating under EPA disinfectant mandates that smaller commercial buildings ignore.
- Healthcare Facilities:Acute care networks require EPA-registered chemistries, electrostatic disinfection validation protocols, and joint equipment-consumable contracts that outsource liability. Post-pandemic capital budgets are prioritizing autonomous scrubbers with pathogen-log reduction documentation.
- Commercial Buildings:Class A office and retail properties in Dallas, Phoenix, and Miami are standardizing on single-platform equipment fleets to simplify technician training and parts inventory across multi-site portfolios.
- Educational Institutions:K-12 districts and universities balance Green Seal certification requirements against constrained maintenance budgets, favoring leased equipment with bundled chemical supply.
- Industrial Sites:Manufacturing and logistics facilities prioritize pressure washing and heavy-duty scrubbing for OSHA compliance around slip hazards and chemical spill containment.
Commercial buildings command the largest equipment installed base; healthcare facilities are climbing the fastest as infection control protocols intensify.
Application:
Margin pools concentrate where recurring chemical consumption intersects with regulatory validation requirements.
- Disinfection:EPA FIFRA-registered chemistries for healthcare and foodservice carry 18-24 month approval timelines that favor established registrants with toxicology dossiers. Electrostatic application systems command premium pricing through validated kill-claim documentation.
- Floor Maintenance:Mechanized scrubbing and polishing in facilities exceeding 50,000 square feet delivers measurable labor substitution economics that justify autonomous equipment investment.
- Surface Cleaning:General-purpose cleaning of walls, fixtures, and furniture spans commodity spray-and-wipe to specialized glass and stainless steel formulations.
- Waste Management:Collection, compaction, and odor control systems serve high-traffic transportation hubs and stadium venues.
Floor maintenance accounts for the largest equipment deployment; disinfection applications are gaining share fastest on recurring chemistry margins.
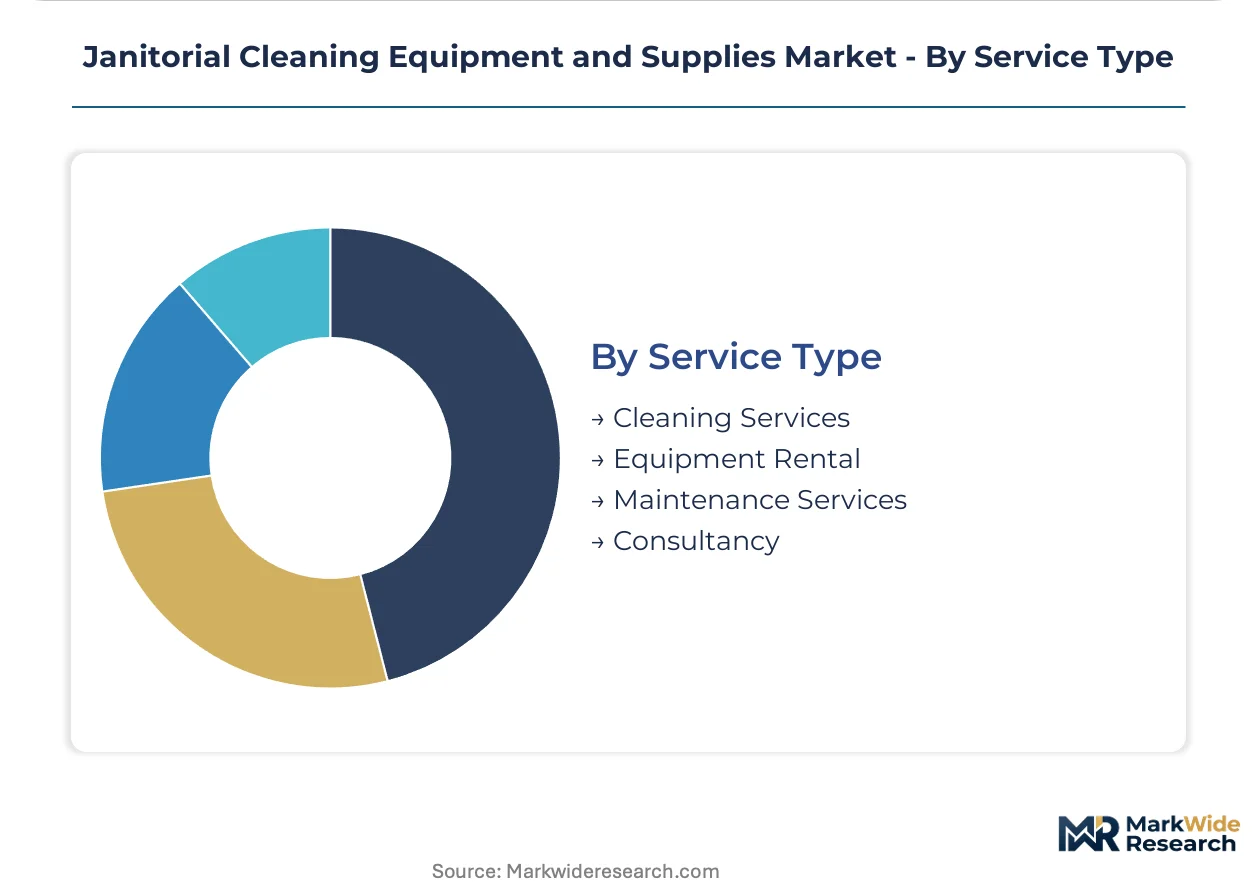
Service Type:
Revenue model innovation is shifting capital ownership risk from end-users to suppliers through bundled service contracts.
- Equipment Rental:Monthly lease structures with bundled maintenance and consumable replenishment are displacing capital purchases in healthcare and education verticals. United States metropolitan hospital networks favor this model for infection control liability transfer.
- Cleaning Services:Third-party facility management providers operate integrated equipment fleets across multi-site contracts, consolidating vendor relationships.
- Maintenance Services:Electromechanical technician networks for autonomous scrubber repair represent a capability gap that OEMs are filling with captive service operations.
- Consultancy:Operational efficiency audits and Green Seal certification pathway guidance serve institutional procurement teams with complex compliance requirements.
Cleaning services deploy the most equipment volume; equipment rental is expanding most quickly as capital budgets tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors the most concentrated demand corridor for mechanized floor maintenance fleets, with Dallas and Miami following as Sun Belt metropolitan construction accelerates commercial square footage additions across the United States.
United States
Healthcare networks in Chicago and Boston are expanding autonomous scrubber procurement to meet Joint Commission infection control standards. The EPA's Safer Choice program mandates verified low-toxicity formulations for federal procurement, accelerating chemical reformulation cycles. Dallas-Fort Worth commercial construction is concentrating demand for battery-powered floor scrubbers in Class A office portfolios.
Germany
Industrial sites across the Ruhr region are prioritizing heavy-duty pressure washing systems for OSHA-equivalent slip hazard compliance. The ECHA REACH framework imposes escalating material safety data sheet complexity on imported surfactant blends. Munich and Stuttgart manufacturing clusters are standardizing on single-platform equipment fleets to simplify technician training.
China
Commercial real estate expansion in Shanghai and Shenzhen is driving equipment leasing opportunities in underpenetrated facility management services. The MIIT oversees industrial equipment safety standards that shape autonomous scrubber certification pathways. The Yangtze River Delta logistics corridor is deploying LiDAR-guided cleaning systems during off-peak warehouse hours.
India
Bangalore and Mumbai commercial real estate expansion presents equipment leasing opportunities as facility management services penetrate underpenetrated markets. The BIS certification requirements for industrial equipment create compliance barriers for imported autonomous systems. The Delhi-NCR corridor is concentrating demand for HEPA-filtered vacuum systems in educational institutions with asthma-sensitive occupancy requirements.
United Kingdom
London metropolitan hospital networks are favoring bundled equipment-consumable contracts to outsource infection control validation liability. The Health and Safety Executive enforces hazard communication standards that parallel OSHA requirements for chemical handling protocols. The Midlands logistics belt is standardizing on autonomous scrubber fleets across multi-site distribution contracts.
Janitorial Cleaning Equipment and Supplies Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent equipment intensity tiers. The market structure consolidates around established registrants with toxicology dossiers and fragmented specialty chemical suppliers facing margin compression. Three archetypes dominate: integrated equipment-chemical platforms, pure-play autonomous hardware specialists, and concentrated dispensing system operators. Competitive moves center on captive service network expansion and IoT-enabled recurring revenue model deployment.
Within the integrated platform tier, Tennant Company and Ecolab Inc. anchor positions through bundled equipment-consumable offerings, while Diversey Holdings Ltd. exemplifies the concentrated chemical dispensing archetype with connected dilution control systems. Nilfisk A/S and Alfred Kärcher SE & Co. KG represent European-origin equipment fabricators with established distribution density in institutional channels.
| Leading Market Players |
|---|
| Nilfisk A/S |
| Diversey Holdings Ltd. |
| Ecolab Inc. |
| Zep Inc. |
| Spartan Chemical Company |
| Alfred Kärcher SE & Co. KG |
| Hako GmbH |
| Betco |
| Tennant Company |
| Others |
Supply & Pricing Matrix
The EPA Safer Choice program gates both qualified chemical supply and premium-tier pricing access, compelling suppliers to absorb reformulation costs while institutional buyers pay certification premiums for verified low-toxicity formulations.
Pricing Analysis
Outcome-based pricing anchored to labor-hour substitution drives autonomous floor scrubber valuations in facilities exceeding 50,000 square feet. Three-tier pricing structure across premium LiDAR-enabled units, standard battery-powered machines, and economy corded models reflects automation sophistication and EPA registration tier of bundled chemistries. Pricing pressure stems from concentrated buyer power among multi-site healthcare networks demanding fleet standardization discounts. Educational institutions exhibit highest price sensitivity due to capital budget constraints, while acute care networks prioritize liability transfer over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific component origins compresses margins on imported LiDAR sensors and battery systems. Manufacturing concentrates in China, Germany, and the United States for autonomous scrubber assembly, with surfactant chemistry production anchored in India and China. Raw material dependencies span lithium-ion cells, precision navigation hardware, and petroleum-derived surfactant feedstocks. Single-source vulnerability in LiDAR sensor supply creates procurement bottlenecks for autonomous equipment OEMs. Distribution runs through authorized dealer networks for capital equipment and chemical distribution cooperatives for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with equipment OEMs pursuing captive chemical dispensing capabilities to lock in recurring consumable revenue streams.
For Market Incumbents: Cement platform stickiness through IoT-enabled dilution control systems that tether consumable replenishment to proprietary hardware. Expand captive service technician networks to address electromechanical scarcity threatening autonomous equipment uptime. Prioritize backward integration into surfactant formulation to capture margin pools from EPA-registered disinfectant chemistry.
For New Entrants and Emerging Players: Autonomous scrubber retrofit kits for existing manual fleets offer a technology-first wedge into mid-size commercial buildings below 50,000 square feet. Target underpenetrated facility management services in Bangalore and Mumbai through equipment leasing partnerships with local real estate developers. Lead with subscription-based validation documentation to differentiate from capital-sale incumbents.
For Investors and Strategic Acquirers: Joint Commission infection control audit failures in United States hospital networks are the leading indicator that liability outsourcing demand is accelerating. Position for 5-10 year holding periods around integrated equipment-chemical platforms with established EPA toxicology dossiers. Monitor FIFRA registration approval timelines as inflection signals for disinfectant chemistry consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Chemistry | Captures EPA FIFRA registration premiums and secures supply continuity for institutional disinfectant lines. |
| IoT-Enabled Dilution Control Deployment | Creates recurring revenue lock-in through usage-based consumable replenishment tied to connected dispensing hardware. |
| Captive Service Technician Network Expansion | Addresses electromechanical maintenance scarcity that threatens autonomous scrubber fleet uptime in healthcare networks. |
| Green Seal Certification Pathway Investment | Unlocks institutional procurement contracts mandating third-party environmental validation for chemical formulations. |
| Equipment Leasing Model Rollout | Transfers capital ownership risk to suppliers while capturing infection control validation liability in metropolitan hospital systems. |
Research Methodology
Multi-period observation of EPA registration timelines, LiDAR sensor procurement bottlenecks, and Sun Belt commercial construction permits anchored the trend analysis, supplemented by interviews with facility maintenance directors, hospital procurement managers, chemical formulation R&D leads, and autonomous equipment service technicians. Secondary validation drew from EPA FIFRA registration databases, OSHA hazard communication filings, Green Seal certification records, and customs trade data for surfactant imports. Bottom-up equipment deployment estimates triangulated against top-down institutional spending surveys.
Segment-weighting approaches modeled product type intensity, end-user hygiene requirements, application margin pools, and service delivery economics across the projection horizon. CAGRs derived from equipment replacement cycles, chemical consumption rates, and regulatory-driven reformulation timelines. Forecast inputs incorporated LiDAR component supply constraints, REACH framework amendment impacts, and healthcare infection control protocol evolution.
Several conditions sit outside the modeled scope, including unscheduled EPA regulatory shifts, autonomous equipment interoperability standard changes, and acute commodity price spikes in lithium or petroleum feedstocks. Forecasts reflect documented assumptions about labor cost trajectories and institutional procurement centralization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Carpet Cleaner Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Household Wipes Market