
 Smart Cleaning and Hygiene Market | 2026-2036
Smart Cleaning and Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cleaning and Hygiene Market Analytics
Subscription-based fleet management software is hardening into the primary revenue layer for equipment vendors, shifting buyer relationships from transactional hardware sales to recurring operational partnerships. iRobot Corporation leverages its proprietary mapping databases to sustain premium pricing in residential channels. Ecovacs Robotics anchors its position through backward integration into brushless motor production, controlling component costs across price tiers. Roborock Technology competes aggressively on LiDAR precision, differentiating its navigation stack against camera-dependent alternatives.
Smart cleaning and hygiene systems integrate autonomous mobile robots, networked environmental sensors, and AI-driven scheduling platforms to execute, validate, and document sanitization protocols with minimal human intervention. These systems typically operate on 2.4 GHz or 5 GHz wireless meshes, process edge-computed contamination signals through machine learning classifiers, and generate audit trails for compliance verification in regulated environments. Robotic Vacuums dominate current shipment volumes but face margin compression as Chinese OEMs saturate entry-level segments. Disinfecting Robots command the steepest unit economics and fastest growth, particularly in Healthcare applications where liability exposure justifies capital-intensive autonomous ultraviolet and electrostatic spray platforms.
The US FDA and EPA jointly govern antimicrobial claims and device safety classifications for autonomous disinfection equipment, while the EU MDR and CE marking frameworks impose clinical validation requirements on healthcare-deployed systems. These regulatory architectures elevate barriers for unvalidated entrants and create procurement preference for certified platforms with documented efficacy data. Stakeholders must monitor evolving interoperability mandates between building management systems and cleaning fleet dashboards, as facility operators increasingly specify API-native equipment that integrates with existing enterprise software stacks.
Market Dynamics
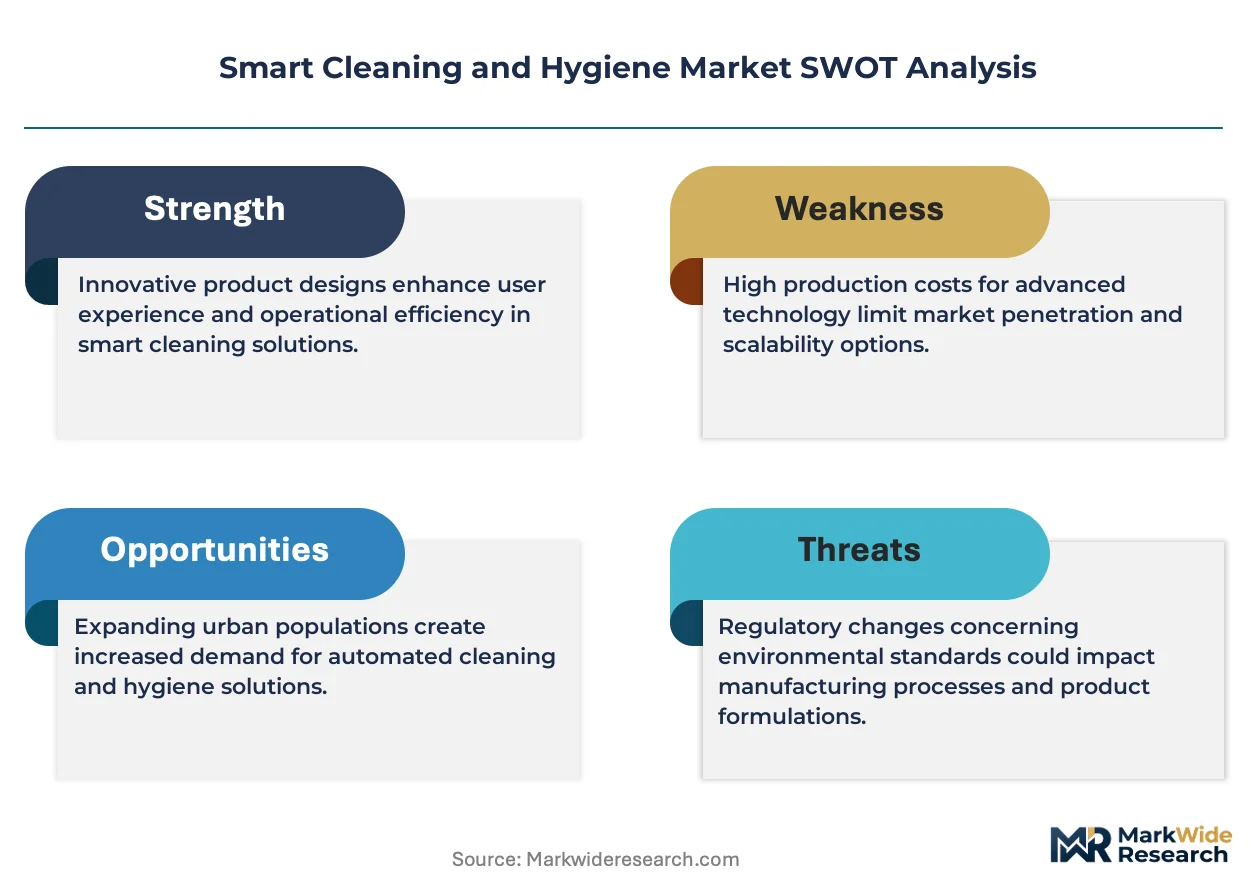
Subscription-based fleet management software is hardening buyer relationships from transactional hardware sales to recurring operational partnerships, while ultraviolet-C LED module miniaturization compresses unit costs and expands autonomous disinfection use cases beyond healthcare into commercial real estate.
Growth Catalysts
- Joint Commission Standards:Healthcare facilities in the United States face tightening infection control protocols that mandate documented sanitization validation. Autonomous disinfection systems with audit trail generation satisfy these compliance requirements.
- Facility Management Association Certification:Germany's hygiene certification requirements accelerate replacement of conventional equipment with connected, sensor-validated cleaning systems across commercial and industrial facilities.
- AI-Powered Navigation:Machine learning classifiers processing edge-computed contamination signals enable real-time path optimization and coverage verification, reducing labor supervision requirements.
Market Restraints
- Ultraviolet-C LED Supply Concentration:Advanced semiconductor substrates for high-output UV-C modules concentrate among specialized foundries in East Asia, creating input cost volatility and procurement lead time uncertainty.
- Interoperability Friction:Building management system API fragmentation forces redundant integration investments, as facility operators specify native connectivity that legacy cleaning equipment cannot satisfy without middleware.
- Electrostatic Spray Limitations:Residual moisture sensitivity restricts autonomous electrostatic disinfection deployment in electronics manufacturing and precision assembly environments.
Strategic Opportunities
- Hospitality Underpenetration:Hotels and conference centers in Spain and Italy lag healthcare and logistics in autonomous cleaning adoption, presenting white space for subscription fleet models targeting seasonal occupancy volatility.
- CSRD Reporting Alignment:The EU Corporate Sustainability Reporting Directive creates procurement preference for equipment vendors offering carbon footprint documentation and circular service arrangements.
- 5G Private Network Convergence:Integration of autonomous mobile robots with millimeter-wave private networks enables sub-10 millisecond latency for collision avoidance and coordinated multi-robot operations.
Industry Challenges
- Embedded Systems Engineering Gap:Shortage of firmware developers with real-time operating system and safety-critical certification experience delays product validation cycles.
- FDA 510(k) Timeline Compression:Autonomous disinfection equipment requiring antimicrobial claims validation faces extended premarket notification review periods that mismatch quarterly capital budgeting cycles.
- Legacy Fleet Integration Complexity:Retrofitting sensor validation and wireless connectivity onto installed base equipment requires hardware redesign that strains aftermarket service margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cleaning and Hygiene Market |
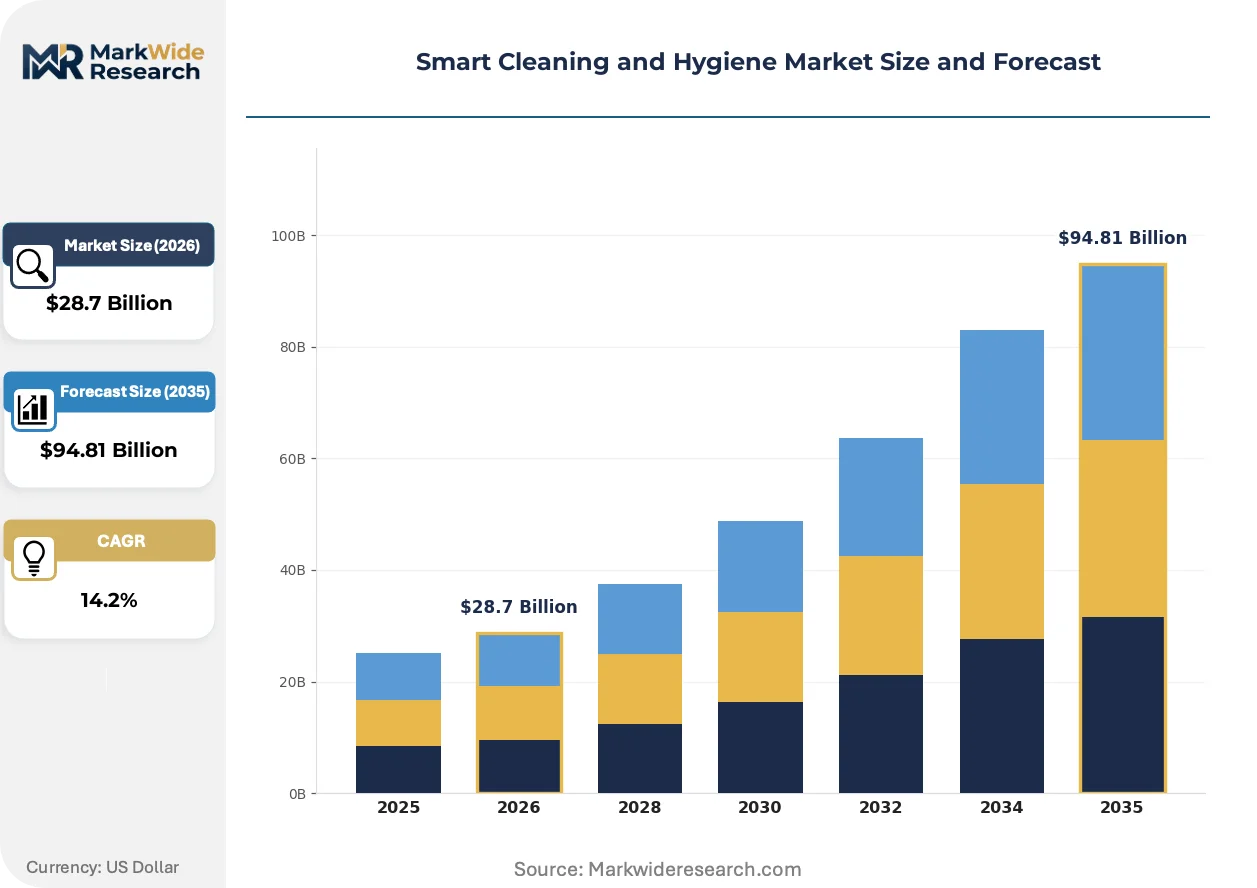
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Vacuums, Smart Mops, Disinfecting Robots, IoT Sensors Application: Residential, Commercial, Healthcare, Industrial Technology: Artificial Intelligence, Wireless Charging, Machine Learning, Automation Customer Type: Homeowners, Facility Managers, Businesses, Cleaning Services |
| Companies Covered | iRobot Corporation, Ecovacs Robotics Co., Ltd., Roborock Technology Co., Ltd., LG Electronics Inc., Samsung Electronics Co., Ltd., SharkNinja Operating LLC, Panasonic Corporation, Neato Robotics, Inc., Kärcher GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cleaning and Hygiene Market Evolving Landscape
Ultraviolet-C LED technology is compressing form factors and energy requirements while expanding autonomous disinfection into transport and education applications previously cost-prohibitive for capital-intensive platforms.
Ultraviolet-C LED arrays with optimized gallium nitride substrates deliver hospital-grade pathogen inactivation at sub-200 watt power draws. Airport operators in Singapore and railway maintenance depots in France pilot these compact modules for overnight cabin and rolling stock sanitization. The technology is expanding into school districts and municipal transit authorities that previously lacked electrical infrastructure for legacy mercury vapor systems.
The EU Medical Device Regulation imposes clinical validation requirements on healthcare-deployed autonomous disinfection platforms, elevating documentation burdens for efficacy claims. Equipment vendors must generate microbiological testing data that satisfies notified body review, creating procurement preference for certified incumbents with established quality management systems. German hospital procurement committees increasingly specify MDR-compliant platforms with peer-reviewed efficacy studies.
Facility operators now bundle cleaning fleet subscriptions with energy management and security services into integrated facility contracts. This consolidation displaces standalone equipment purchasing and shifts vendor relationships toward multi-year performance agreements. Property management firms in the Netherlands and Belgium lead this bundling, specifying outcome-based arrangements where payment ties to validated cleanliness metrics rather than equipment uptime.
Smart Cleaning and Hygiene Market Segmentation
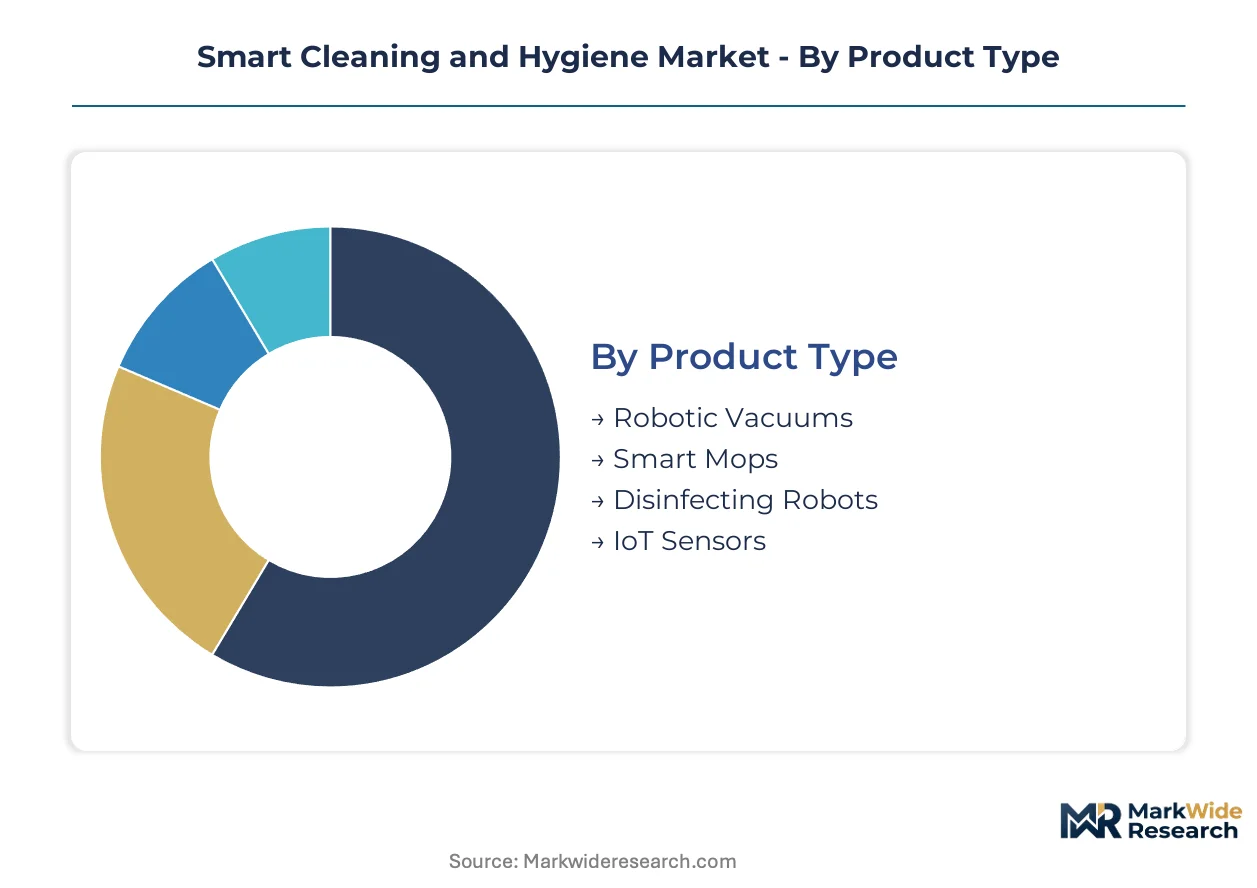
Segmentation in the Smart Cleaning and Hygiene Market reveals distinct procurement patterns across product architectures and buyer sophistication. Equipment vendors calibrate feature depth, connectivity protocols, and service bundling to match operational complexity rather than applying uniform specifications.
Product Type:
Customization intensity spans from mass-produced consumer appliances to engineered-to-order disinfection platforms with site-specific UV-C dosing algorithms.
- Robotic Vacuums:These autonomous floor-cleaning units integrate simultaneous localization and mapping with brushless motor drives for debris extraction across hard surfaces and carpeting. Demand concentrates in German residential complexes and US multifamily housing where property managers deploy fleet subscriptions to reduce turnover cleaning costs. Chinese OEMs dominate entry-tier segments while LiDAR-equipped models command premium positioning.
- Disinfecting Robots:Autonomous platforms combining ultraviolet-C LED arrays with electrostatic spray nozzles for validated pathogen inactivation in regulated environments. Healthcare procurement committees in the United States specify Joint Commission-compliant units with audit trail generation, while French railway operators pilot overnight cabin sanitization systems.
- Smart Mops:Connected floor-scrubbing devices with automated water dispensing and microfiber pad management for commercial hard surface maintenance.
- IoT Sensors:Wireless environmental monitors detecting particulate, volatile organic compound, and biological contamination signals for predictive cleaning dispatch.
Most installed capacity flows through Robotic Vacuums. Expansion is steepest in Disinfecting Robots.
Application:
Operational risk tolerance and regulatory exposure determine automation depth across facility types.
- Healthcare:Hospitals and long-term care facilities deploy autonomous disinfection with FDA 510(k) or EU MDR validation to satisfy infection control mandates and liability mitigation. German hospital procurement increasingly specifies MDR-compliant platforms with peer-reviewed efficacy documentation.
- Commercial:Office complexes, retail centers, and hospitality venues balance labor substitution with visible cleaning presence for occupant reassurance.
- Residential:Single-family and multifamily dwellings drive volume through app-connected vacuum and mop systems with mapping database subscriptions.
- Industrial:Manufacturing floors and logistics warehouses prioritize ruggedized autonomous scrubbers with chemical dispensing for grease and particulate removal.
Healthcare commands the highest unit economics and compliance overhead. Commercial applications are gaining share fastest as facility management contracts consolidate cleaning with energy and security services.
Technology:
Intellectual property concentration varies across the navigation, power, and control layers of system architecture.
- Artificial Intelligence:Neural network-based path planning and contamination classification algorithms process edge-computed sensor inputs for real-time decision autonomy. Navigation stacks differentiate competitive positioning as camera-dependent systems compete with LiDAR-fusion alternatives.
- Machine Learning:Supervised classifiers trained on facility-specific contamination patterns optimize cleaning schedules and resource allocation.
- Automation:Programmable mechanical systems executing repetitive cleaning motions without adaptive intelligence for cost-sensitive deployments.
- Wireless Charging:Inductive power transfer systems enabling continuous operation through automated dock-and-recharge cycles.
AI-enabled systems carry the steepest development investment. Machine learning deployment is climbing fastest as cloud training pipelines mature.
Customer Type:
Buying center structure and total cost of ownership horizon shape vendor relationship models.
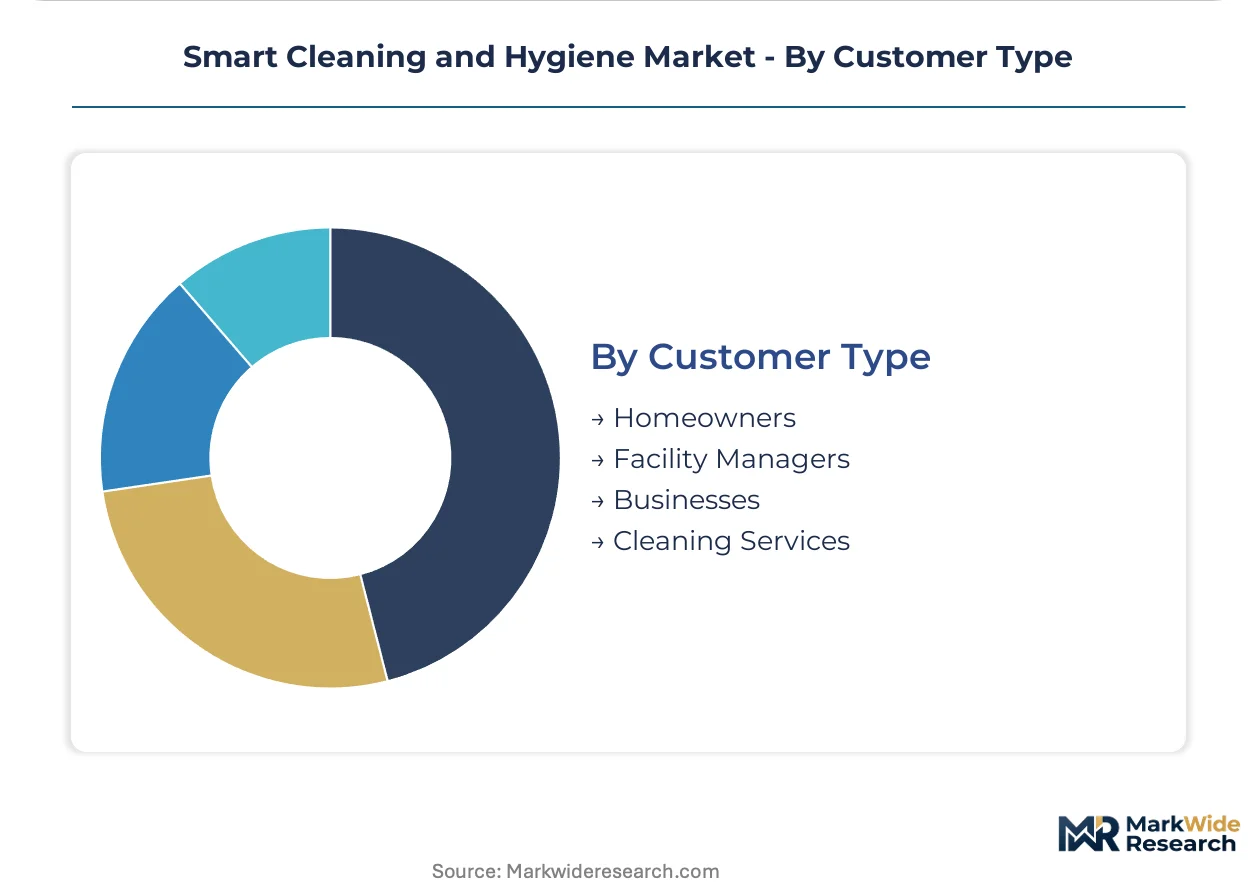
- Facility Managers:Professional operators of commercial and institutional buildings specify API-native equipment integrating with building management systems for consolidated dashboard control. Dutch and Belgian property management firms lead outcome-based contracting tied to validated cleanliness metrics.
- Businesses:Corporate occupiers and retail chains procure cleaning automation through integrated facility services rather than standalone equipment purchases.
- Cleaning Services:Contract cleaning companies adopt fleet subscription models to convert capital expenditure to operational expenditure and differentiate through technology-enabled service level agreements.
- Homeowners:Individual consumers purchase through retail channels with preference for app ecosystems and mapping database continuity.
Facility Managers direct the largest contract values. Cleaning Services represent the fastest-expanding customer type as labor availability constraints accelerate outsourcing conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hygiene certification mandates accelerate equipment replacement faster than US healthcare procurement cycles, while Asian manufacturing clusters concentrate component supply for UV-C LED modules.
United States
Hospital procurement committees expand autonomous disinfection fleets as Joint Commission infection control standards tighten documentation requirements. FDA 510(k) premarket notification timelines extend validation cycles for antimicrobial claim devices. Boston and Minneapolis medical device clusters host pilot deployments of audit trail-generating robotic platforms in tertiary care facilities.
Germany
Facility Management Association hygiene certification rules mandate connected, sensor-validated cleaning systems across commercial and industrial properties. EU MDR frameworks impose clinical validation requirements on healthcare-deployed autonomous platforms. The Rhine-Ruhr industrial corridor leads replacement of conventional equipment with subscription-based fleet management models.
China
Domestic OEMs saturate entry-level robotic vacuum segments through cost-optimized manufacturing and brushless motor supply chain control. MIIT standards govern wireless connectivity protocols for building management system integration. Shenzhen and Dongguan electronics clusters dominate UV-C LED module assembly for export markets.
Japan
Precision manufacturing environments pilot compact autonomous scrubbers for particulate-sensitive cleanroom maintenance. METI efficiency standards drive adoption of wireless charging systems for continuous operation workflows. The Nagoya industrial zone deploys coordinated multi-robot cleaning fleets in automotive component facilities.
Singapore
Airport operators pilot overnight cabin sanitization systems using miniaturized UV-C LED arrays for transport applications. National environmental agency guidelines specify validated pathogen inactivation protocols for public infrastructure. Changi Aviation Hub tests sub-200 watt autonomous disinfection modules for aircraft and terminal maintenance.
Smart Cleaning and Hygiene Market Competitive Landscape
Top-tier vendors anchor premium positioning through proprietary navigation databases and backward integration into critical components, while mid-tier specialists compete on LiDAR precision and regional manufacturing scale. The vendor base stratifies across three archetypes: integrated platform providers controlling motor and sensor supply chains, navigation-stack specialists licensing AI path-planning algorithms, and contract manufacturers serving private-label retail channels. Consolidation pressures intensify as facility management contracts demand API-native equipment with native building management system interoperability.
Among Asia-Pacific headquartered robotics specialists, iRobot Corporation, Ecovacs Robotics Co., Ltd., and Roborock Technology Co., Ltd. occupy distinct competitive positions. iRobot exemplifies the mapping-database archetype sustaining premium residential pricing through proprietary spatial data assets. Ecovacs represents vertical manufacturing control through captive brushless motor production. Roborock anchors LiDAR-precision differentiation against camera-dependent navigation alternatives. These three companies illustrate the strategic divergence between data monetization, component cost control, and sensor-stack specialization reshaping vendor economics.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics Co., Ltd. |
| Roborock Technology Co., Ltd. |
| LG Electronics Inc. |
| Samsung Electronics Co., Ltd. |
| SharkNinja Operating LLC |
| Panasonic Corporation |
| Neato Robotics, Inc. |
| Kärcher GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between MDR-validated healthcare platforms and unvalidated commercial units manifests in both pricing power and sourcing complexity. Premium-tier vendors command subscription multiples through captive UV-C LED supply chains, while commodity robotic vacuums face margin compression as Chinese OEMs consolidate brushless motor production.
Pricing Analysis
Capacity additions in Shenzhen and Dongguan are reshaping price floors for entry-tier robotic vacuums even as MDR-compliant disinfecting robots sustain premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare platforms from CE-marked commercial units and unbranded consumer appliances. Cost compression in residential segments stems from brushless motor oversupply, while pricing pressure in disinfection platforms remains muted due to Joint Commission audit-trail requirements. Facility managers exhibit lowest price sensitivity, whereas residential buyers migrate aggressively toward sub-$200 LiDAR-equipped alternatives.
Supply Chain Analysis
Domestic-content mandates under China's MIIT standards are reshaping sourcing patterns for wireless connectivity modules deployed in building management integrations. Component supply concentrates in China, South Korea, and Taiwan, with gallium nitride substrates for UV-C LED arrays drawing from specialized East Asian foundries. Supply chain risk centers on single-source vulnerability for high-output semiconductor substrates. Distribution runs through OEM direct sales for healthcare platforms, contract cleaning fleet subscriptions for commercial deployments, and retail channels for residential appliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on UV-C LED miniaturization collapsing unit costs while MDR validation sustains premium-tier pricing power against commodity alternatives.
For Market Incumbents: Cement proprietary navigation database advantages through mapping subscription lock-in, while deepening backward integration into brushless motor production to defend against Chinese OEM cost aggression. Prioritize API-native platform development to capture facility management consolidation toward integrated service contracts. For New Entrants and Emerging Players: EU MDR in Germany opens a window for specialized disinfecting robot platforms targeting hospital procurement committees seeking peer-reviewed efficacy documentation. Hospitality underpenetration in Spain and Italy presents accessible white space for subscription fleet models addressing seasonal occupancy volatility. Lead with validated audit-trail generation as the primary go-to-market differentiator against unvalidated commercial alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with navigation-stack specialists licensing AI path-planning algorithms to fragmented mid-tier hardware vendors. Long-term viability favors platforms with demonstrated MDR compliance and established quality management systems over speculative consumer appliance plays. Monitor Joint Commission standard revisions as the critical inflection signal for healthcare procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | Clinical validation documentation satisfies German hospital procurement committee requirements for autonomous disinfection platforms. |
| Backward Integration into UV-C LED Modules | Captive gallium nitride substrate supply insulates margin structure against East Asian foundry concentration risk. |
| API-Native Platform Development | Native building management system interoperability captures Dutch and Belgian facility management contract consolidation. |
| Subscription Fleet Model Launch | Recurring revenue conversion aligns with US multifamily housing property manager cost-reduction mandates. |
| 5G Private Network Integration | Millimeter-wave connectivity enables sub-10 millisecond latency for coordinated multi-robot operations in Japanese automotive facilities. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and Singapore, with primary inputs from each market informing demand calibration. Facility management executives, hospital procurement committee members, biomedical engineers, contract cleaning company operators, and UV-C LED module suppliers contributed structured interviews. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, MIIT wireless connectivity standards, and hospital procurement database records. Bottom-up equipment shipment modeling and top-down facility automation spending estimates were triangulated for convergence.
Granularity-level modeling disaggregated revenue and unit projections across product type, application, technology layer, and customer archetype throughout the forecast period. CAGRs were derived from segmented growth trajectory analysis rather than single-point extrapolation. Forecast inputs incorporated Joint Commission standard revision timelines, EU CSRD reporting mandate adoption curves, and 5G private network deployment schedules in target geographies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA 510(k) review timeline extension or UV-C LED substrate supply disruption scenarios. Projections reflect documented assumptions regarding regulatory enforcement intensity and facility management outsourcing conversion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Canister Vacuum Cleaners Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Global All Purpose Cleanser Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Dry Laundry Detergents Market
Cleaning Equipment
Household Cleaning Tools and Supplies Market
Cleaning Equipment
Bathroom Mirror Wiper Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
North America Smart Commercial Restroom Products Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Contract Cleaning Services Market
Cleaning Equipment
Fabric Care Market
Cleaning Equipment
Floor Cleaning Device Market