
 Cleaning Services Market | 2026-2036
Cleaning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning Services Market Intelligence
Recurring disinfection service revenue is reshaping margin distribution across the cleaning services landscape. ABM Industries leverages its healthcare and aviation facility expertise to capture premium contract renewals. Stratus Building Solutions anchors its competitive position through a franchise network spanning hundreds of local markets. Jan-Pro Cleaning Services differentiates via standardized operating protocols that reduce client churn in commercial office segments.
Cleaning services encompass labor-intensive maintenance activities involving surface treatment, particulate removal, and microbial reduction using EPA-registered formulations, HEPA filtration equipment, and microfiber application systems to preserve asset integrity and occupant health. Commercial cleaning dominates transaction volume through multi-year corporate facility contracts, while specialty cleaning commands superior margins due to confined-space certifications and hazardous material handling requirements. Residential cleaning competes on frequency and trust metrics, with franchise networks capturing recurring homeowner subscriptions through standardized service level agreements.
OSHA workplace safety standards, EPA chemical registration requirements under FIFRA, and the EU REACH framework govern product formulations and worker exposure limits across operational jurisdictions. These regulatory layers elevate compliance costs for independent operators while creating certification barriers that favor scaled providers with dedicated environmental health and safety departments. Stakeholders must monitor evolving state-level green procurement mandates and building electrification timelines that will redefine equipment capital requirements and service bundling strategies.
Market Dynamics
Healthcare facility infection control mandates are compressing service intervals and elevating certification requirements across the cleaning services landscape. EPA Safer Choice formulations and EU REACH chemical restrictions are forcing capital reinvestment in equipment fleets and staff training protocols.
Growth Catalysts
- Healthcare Infection Protocols:Joint Commission accreditation standards and CDC guidelines for hospital-grade disinfection are expanding recurring contract scopes. Long-term care facilities now require daily terminal cleaning with hydrogen peroxide vapor systems.
- EU Green Chemistry Mandates:REACH substance restrictions and the EU Green Deal's building renovation targets are accelerating demand for low-VOC formulations and electrified cleaning equipment. Service providers must certify chemical inventories through ECHA registration portals.
- Aviation Biohazard Standards:IATA health safety protocols for aircraft cabin disinfection are creating specialized service tiers. HEPA-equipped teams now board between flights at major hub airports.
Market Restraints
- Labor Cost Escalation:Minimum wage ordinances in California, New York, and Washington state are compressing margins for janitorial staffing. Independent operators lack scale to absorb payroll tax and benefits loading.
- Input Concentration Risk:Quaternary ammonium compound supply concentrates among three domestic chemical manufacturers. Disinfectant formulation shortages during pandemic waves exposed vulnerability to single-source dependencies.
- Technical Substitution Pressure:Autonomous floor-scrubbing robots from robotics vendors are displacing overnight janitorial shifts in big-box retail and warehouse environments. Human crews retain edge only in irregular surface geometries.
Strategic Opportunities
- Electrification Service Bundling:Building electrification timelines in New York City Local Law 97 and California Title 24 are creating openings for cleaning firms to package HVAC filter maintenance with EV charging station upkeep.
- Confined-Space Certification Gaps:Tank cleaning and silo maintenance for food processing and chemical manufacturing command 40-60% rate premiums. Few regional operators hold OSHA confined-space entry permits.
- Sensor-Enabled Verification:ATP bioluminescence meters and UV-C dosage indicators are virtualizing quality assurance. Clients now demand timestamped compliance dashboards rather than periodic inspections.
Industry Challenges
- Hazmat Handler Pipeline Collapse:OSHA 40-hour HAZWOPER certification programs suffer completion rate declines. Waste handling and bloodborne pathogen training slots remain unfilled across Midwest and Mountain West labor markets.
- Legacy Equipment Stranding:Gas-powered pressure washers and propane burnishers face municipal emissions bans in Denver, Seattle, and Portland. Fleet replacement cycles compress from seven years to four.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning Services Market |
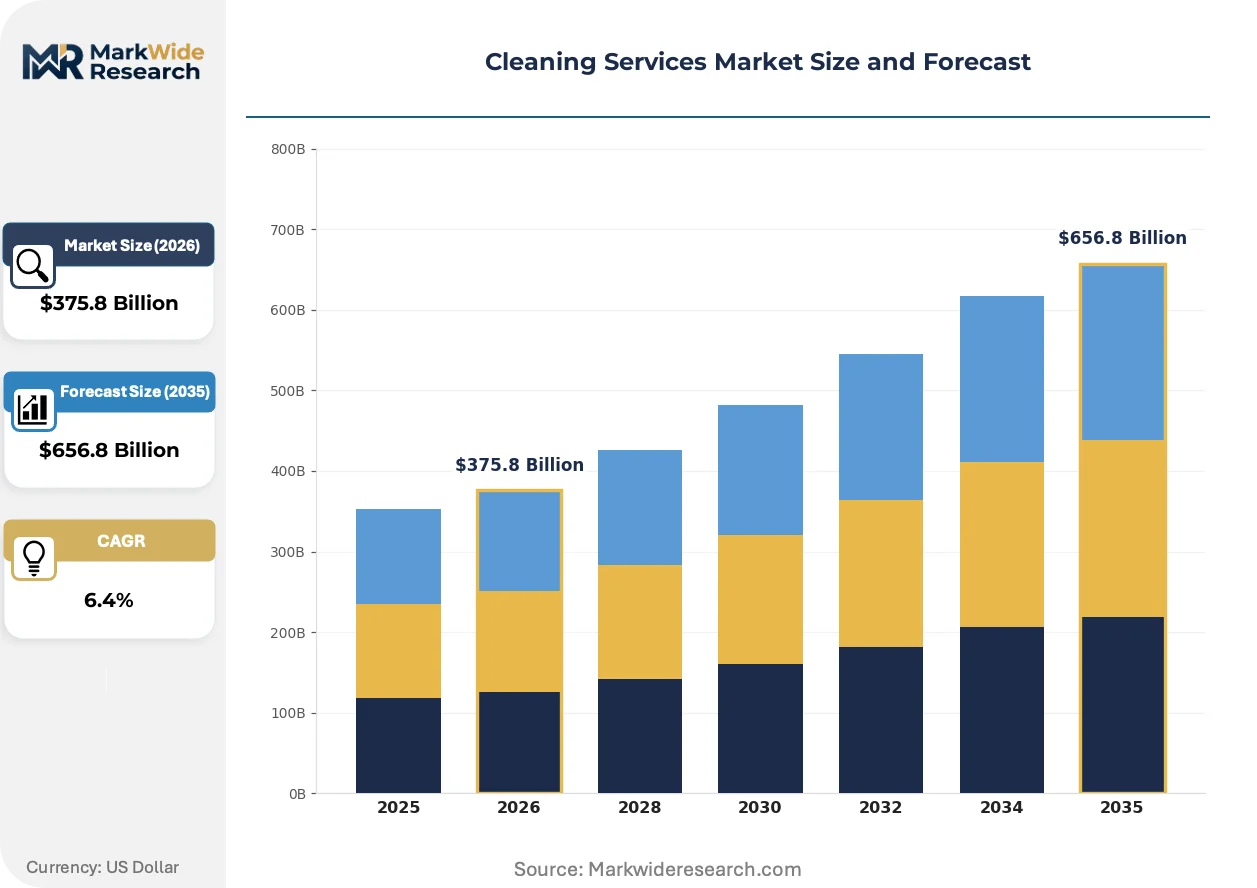
| Market Size in 2026 | $375.8 Billion |
| Market Size in 2035 | $656.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Cleaning, Commercial Cleaning, Industrial Cleaning, Specialty Cleaning, Janitorial Services Customer Type: Homeowners, Corporate Offices, Manufacturing Facilities, Hospitality Establishments, Educational Institutions Distribution Channel: Direct Sales, Online Platforms, Franchise Networks, Third-Party Vendors, Business-to-Business Contracts Application: Floor Care, Window Washing, Carpet Cleaning, Disinfection Services, Waste Management |
| Companies Covered | ABM Industries, Stratus Building Solutions, CleanNet USA, Pritchard Industries, City Wide Facility Solutions, Jan-Pro Cleaning Services, Anago Cleaning Systems, Cleanstar National, ServiceMaster Clean, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning Services Market Strategic Shifts & Innovations
Digital verification systems and electrified equipment platforms are compressing traditional service models while opening premium pricing tiers for data-integrated offerings. Chemical formulation transparency now shapes competitive positioning as procurement teams screen vendors through sustainability scorecards.
Electrostatic sprayer systems are virtualizing surface disinfection protocols. Hospital systems and school districts adopted these units during respiratory virus seasons, then retained them for norovirus containment. The technology is compressing labor hours per square foot while elevating coverage consistency metrics that insurers now reference in liability pricing.
EPA Safer Choice label requirements and California Proposition 65 chemical warnings are forcing formulation transparency across supply chains. Cleaning chemical distributors must now disclose complete ingredient lists and toxicity screening data. Commercial real estate investment trusts in the United States are inserting green procurement clauses into multi-year facility contracts, rejecting vendors with non-compliant product portfolios.
Performance-based service agreements are displacing fixed-scope janitorial contracts. Corporate facility managers now tie vendor payments to infection rate reductions, indoor air quality scores, and occupant satisfaction metrics. This shift concentrates most visibly in Class A office towers in Chicago, Houston, and Atlanta, where landlord competition for credit tenants demands demonstrable wellness outcomes.
Cleaning Services Market Segmentation
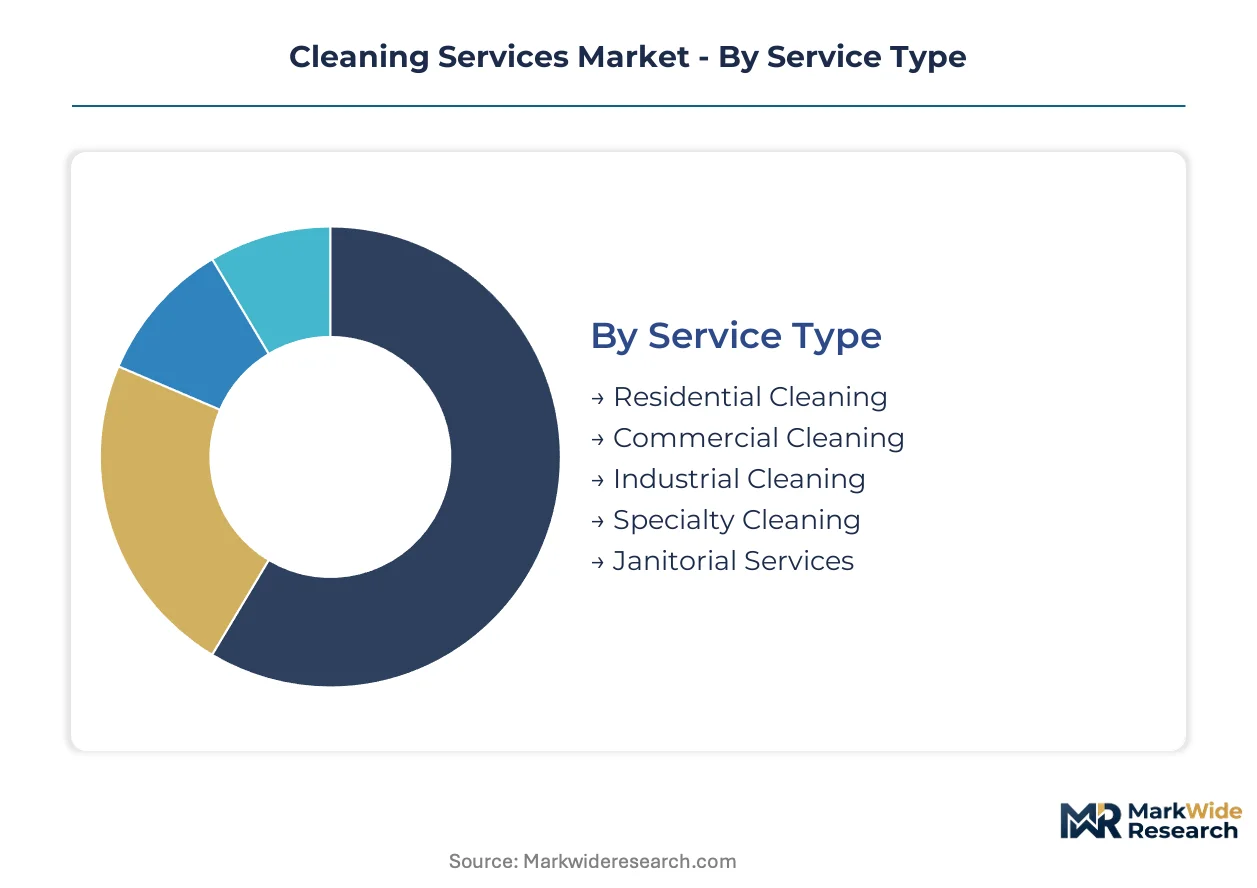
Cleaning services segment along service intensity, regulatory exposure, and contract structure. Each dimension shapes capital requirements, margin profiles, and competitive barriers differently across operational models.
Service Type:
Cost tier stratification separates commoditized labor pools from certified specialty operations with equipment and training premiums.
- Residential Cleaning:Recurring subscription models dominate revenue stability. Homeowners in suburban United States markets prioritize trust metrics and scheduling flexibility over price alone.
- Commercial Cleaning:Multi-year corporate facility contracts anchor transaction volume. Class A office towers in Chicago, Houston, and Atlanta demand performance-based agreements tied to indoor air quality scores.
- Industrial Cleaning:Confined-space certifications and hazardous material handling requirements compress the qualified operator pool. Food processing and chemical manufacturing facilities command rate premiums of 40-60% above standard commercial rates.
- Specialty Cleaning:Aviation biohazard protocols and healthcare terminal cleaning require HEPA-equipped crews and hydrogen peroxide vapor systems. IATA health safety standards create specialized service tiers at major hub airports.
- Janitorial Services:Overnight shift coverage for retail and warehouse environments faces displacement pressure from autonomous floor-scrubbing robotics. Human crews retain competitive edge only in irregular surface geometries.
Commercial cleaning commands the established base. The steepest expansion runs through specialty cleaning.
Customer Type:
Application context determines compliance burden, service frequency, and contract renewal probability across end-use verticals.
- Homeowners:Trust-based selection criteria favor franchise networks with standardized service level agreements. Recurring subscription capture rates correlate with neighborhood density and dual-income household concentration.
- Corporate Offices:Facility management outsourcing deepens across metropolitan commercial corridors. Landlord competition for credit tenants drives wellness outcome metrics into vendor payment structures.
- Manufacturing Facilities:OSHA confined-space entry permits and EPA chemical handling requirements elevate vendor qualification barriers. Tank cleaning and silo maintenance operations concentrate among regional specialists.
- Hospitality Establishments:Turnaround-time pressure between guest checkouts compresses service windows. ATP bioluminescence verification systems now standard for quality assurance documentation.
- Educational Institutions:Electrostatic sprayer adoption accelerated during respiratory virus seasons, then retained for norovirus containment. K-12 districts and university systems represent sticky recurring revenue with annual budget predictability.
Corporate offices anchor contract value concentration. Educational institutions are gaining share fastest through pandemic-retained disinfection protocols.
Distribution Channel:
Channel structure shapes customer acquisition economics, brand control, and geographic expansion velocity.
- Direct Sales:Enterprise facility managers in the United States prefer relationship-based contracting with dedicated account teams. Long sales cycles yield higher lifetime value and customization scope.
- Online Platforms:On-demand scheduling and real-time crew tracking attract residential and small commercial segments. Platform fees compress margins while enabling rapid market entry for independent operators.
- Franchise Networks:Standardized operating protocols reduce client churn through consistent service delivery. Local market penetration scales without corporate capital deployment.
- Third-Party Vendors:Property management companies and facility service integrators aggregate demand across multiple buildings. Vendor consolidation trends favor scaled providers with dedicated environmental health and safety departments.
- Business-to-Business Contracts:Multi-year agreements with commercial real estate investment trusts now incorporate green procurement clauses. EPA Safer Choice compliance screens out non-compliant product portfolios.
Franchise networks dominate residential and light commercial penetration. Business-to-business contracts are expanding most quickly through integrated facility management outsourcing.
Application:
Technical specialization requirements and equipment intensity vary sharply across surface treatment categories.
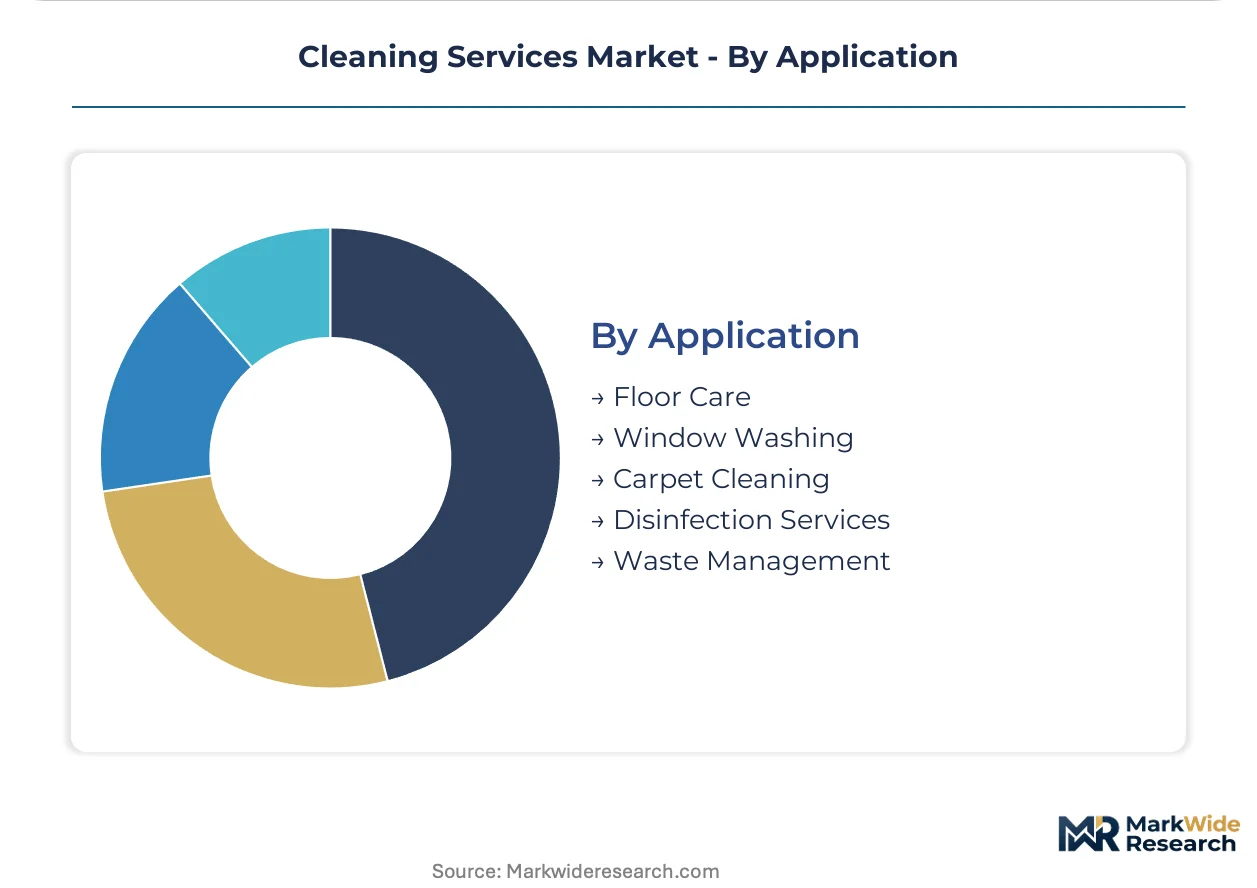
- Floor Care:Electrified equipment platforms face municipal emissions bans in Denver, Seattle, and Portland. Fleet replacement cycles compress from seven years to four for gas-powered pressure washers and propane burnishers.
- Window Washing:High-rise commercial towers demand rope-access certifications and liability coverage tiers that exclude smaller operators. Seasonal demand concentration in northern climates creates capacity utilization challenges.
- Carpet Cleaning:Low-moisture encapsulation methods displace traditional hot-water extraction in commercial settings. Dwell-time reduction aligns with compressed facility access windows.
- Disinfection Services:Healthcare infection control mandates compress service intervals and elevate certification requirements. Joint Commission accreditation standards and CDC guidelines expand recurring contract scopes.
- Waste Management:OSHA 40-hour HAZWOPER certification programs suffer completion rate declines. Waste handling and bloodborne pathogen training slots remain unfilled across Midwest and Mountain West labor markets.
Floor care retains the largest installed equipment base. Disinfection services show the steepest expansion trajectory through retained pandemic-era protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management outsourcing concentrates in metropolitan commercial corridors of the United States, while European markets elevate service standards through green chemistry mandates. Healthcare infection control protocols drive premium contract expansion in Germany and Japan. Emerging demand in India and Brazil centers on aviation and hospitality sectors with compressed service windows.
United States
Corporate facility management outsourcing deepens across Chicago, Houston, and Atlanta commercial corridors. EPA Safer Choice program requirements and California Proposition 65 chemical warnings force formulation transparency. Class A office towers in Manhattan and downtown Los Angeles now tie vendor payments to indoor air quality scores and occupant satisfaction metrics.
Germany
Industrial cleaning for food processing and chemical manufacturing commands rate premiums through confined-space certifications. EU REACH substance restrictions and the EU Green Deal's building renovation targets accelerate demand for low-VOC formulations. The Rhine-Ruhr industrial cluster drives specialized tank cleaning and silo maintenance contracts with 40-60% margins above standard commercial rates.
Japan
Aviation biohazard standards at Narita and Haneda airports create specialized HEPA-equipped service tiers between flights. METI building electrification timelines compress equipment replacement cycles for gas-powered pressure washers. The Kanto region's dense commercial real estate drives performance-based service agreements with sensor-enabled verification systems.
India
Hospitality establishment turnaround-time pressure in Mumbai and Delhi compresses service windows between guest checkouts. BIS standards for cleaning chemical safety elevate procurement screening. The Bangalore and Hyderabad technology corridors drive demand for overnight janitorial coverage in data center and office park environments.
Brazil
São Paulo's commercial real estate investment trusts insert green procurement clauses into multi-year facility contracts. ANVISA health safety protocols for healthcare facilities expand recurring disinfection service scopes. The Rio de Janeiro hospitality sector adopts ATP bioluminescence verification systems for quality assurance documentation.
Cleaning Services Market Key Industry Players
Capability concentration sits with specialty operators holding confined-space and hazardous material certifications; scale advantage sits with franchise networks spanning hundreds of local markets. The market structure fragments across independent operators lacking compliance infrastructure and scaled providers with dedicated environmental health and safety departments. Three archetypes dominate: healthcare-aviation specialists, franchise-based residential-commercial platforms, and industrial hazardous material handlers. Competitive moves concentrate on M&A for certification acquisition and strategic partnerships for electrified equipment fleet transitions.
Among franchise-based operators, Jan-Pro Cleaning Services, Stratus Building Solutions, and Anago Cleaning Systems exemplify the standardized-protocol archetype reducing client churn through consistent service delivery. ABM Industries represents the specialty-tier position leveraging healthcare and aviation facility expertise. These named entities anchor industry commentary without specific claims about individual strategic actions, product portfolios, or financial performance.
| Leading Market Players |
|---|
| ABM Industries |
| Stratus Building Solutions |
| CleanNet USA |
| Pritchard Industries |
| City Wide Facility Solutions |
| Jan-Pro Cleaning Services |
| Anago Cleaning Systems |
| Cleanstar National |
| ServiceMaster Clean |
| Others |
Cost & Logistics Intelligence
Overcapacity in California's janitorial labor pool compresses contractor margins while elevating pricing leverage for chemical manufacturers with EPA-registered formulation portfolios. This utilization asymmetry drives divergent supplier behavior: staffing vendors absorb payroll tax loading while disinfectant producers extend payment terms to capture share.
Pricing Analysis
Multi-year corporate facility contracts dominate pricing structures, with performance-based agreements tying vendor payments to indoor air quality scores and infection rate reductions. Price differentiation rests on certification grade—OSHA confined-space permits and HAZWOPER credentials command 40-60% premiums over standard commercial rates. Pricing pressure stems from minimum wage ordinances in California, New York, and Washington state compressing janitorial margins. Corporate offices show least price sensitivity due to wellness outcome mandates, while independent retail operators in secondary markets resist rate increases.
Supply Chain Analysis
Extended payment terms from quaternary ammonium compound manufacturers in the United States concentrate working capital demands on mid-sized service operators. Supply draws from domestic chemical producers, Mexican equipment assembly facilities, and Chinese microfiber textile mills. Raw material dependencies include EPA-registered disinfectant formulations, HEPA filtration media, and electrified cleaning equipment platforms. Single-source vulnerability runs through three domestic manufacturers controlling quaternary ammonium supply. Distribution runs through franchise networks for residential penetration and direct sales teams for enterprise facility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positions. EPA chemical registration requirements and OSHA certification mandates erect barriers that favor scaled providers with dedicated compliance infrastructure.
For Market Incumbents: Entrench position through captive supply of EPA Safer Choice formulations and backward integration into training academies for HAZWOPER certification pipelines. Autonomous floor-scrubbing robotics threaten overnight janitorial shifts; defend through sensor-enabled verification dashboards that timestamp compliance for liability pricing advantages. Acquire regional specialists holding confined-space permits to capture food processing and chemical manufacturing rate premiums.
For New Entrants and Emerging Players: Pursue electrification service bundling openings created by New York City Local Law 97 and California Title 24 building timelines. The most penetrable white space sits in HVAC filter maintenance packaged with EV charging station upkeep for commercial real estate investment trusts. Target educational institutions in the Midwest and Mountain West where pandemic-retained disinfection protocols created sticky recurring revenue with annual budget predictability. Lead with ATP bioluminescence verification systems as differentiated quality assurance documentation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrified equipment fleets as municipal emissions bans in Denver, Seattle, and Portland compress replacement cycles from seven years to four. Long-term viability favors vertically integrated platforms controlling formulation supply and certification pipelines. Acquisition target archetype: regional specialists with OSHA confined-space entry permits serving food processing clusters. Watch electrification compliance deadlines as inflection indicators for fleet refresh demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | HAZWOPER training academies address Midwest labor shortages while creating captive talent pools. |
| Electrified Fleet Transition | EPA Safer Choice compliance and municipal emissions bans force four-year replacement cycles. |
| Sensor-Enabled Verification Deployment | ATP bioluminescence meters virtualize quality assurance for liability pricing advantages. |
| Confined-Space Permit Acquisition | OSHA certifications unlock 40-60% rate premiums in food processing and chemical manufacturing. |
| Green Procurement Alignment | EU REACH compliance and California Proposition 65 screening filter non-compliant vendor portfolios. |
Research Approach
Cross-validation between facility manager interviews and EPA chemical registration databases anchors the qualitative findings. Primary fieldwork engaged contract administrators at commercial real estate investment trusts, environmental health and safety directors at healthcare systems, procurement leads at educational institutions, and franchise operations managers. Secondary validation drew from OSHA enforcement records, EPA Safer Choice product listings, EU ECHA registration portals, and customs data on cleaning equipment imports. Bottom-up crew deployment models and top-down facility spending estimates were reconciled through triangulation.
Calibration against historical contract renewal rates and equipment replacement cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service intensity tier, regulatory exposure level, contract structure type, and customer vertical. CAGRs were derived from facility management outsourcing penetration curves and retained pandemic-era disinfection protocol adoption. Industry-specific inputs incorporated Joint Commission accreditation standards, IATA aviation biohazard protocols, and building electrification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive electrification fleet moves by franchise networks or autonomous robotics deployment by retail operators would shift outcomes. Macroeconomic deviation in commercial real estate occupancy, regulatory expansion of green procurement mandates, or technological breakthroughs in surface verification systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Household Cleaners Market
Cleaning Equipment
Spin Mops Market
Cleaning Equipment
Furniture Polish Wipes Market
Cleaning Equipment
Carpet Spot Remover Market
Cleaning Equipment
Restroom Cleaning Supplies Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Household Wipes Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Carpet Cleaning Products Market
Cleaning Equipment
Stain Remover Products Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Household Cleaning Products Market
Cleaning Equipment
Carpet Extraction Cleaner Market