
 Cleaning and Hygiene Products Market | 2026-2036
Cleaning and Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cleaning and Hygiene Products Market Analytics
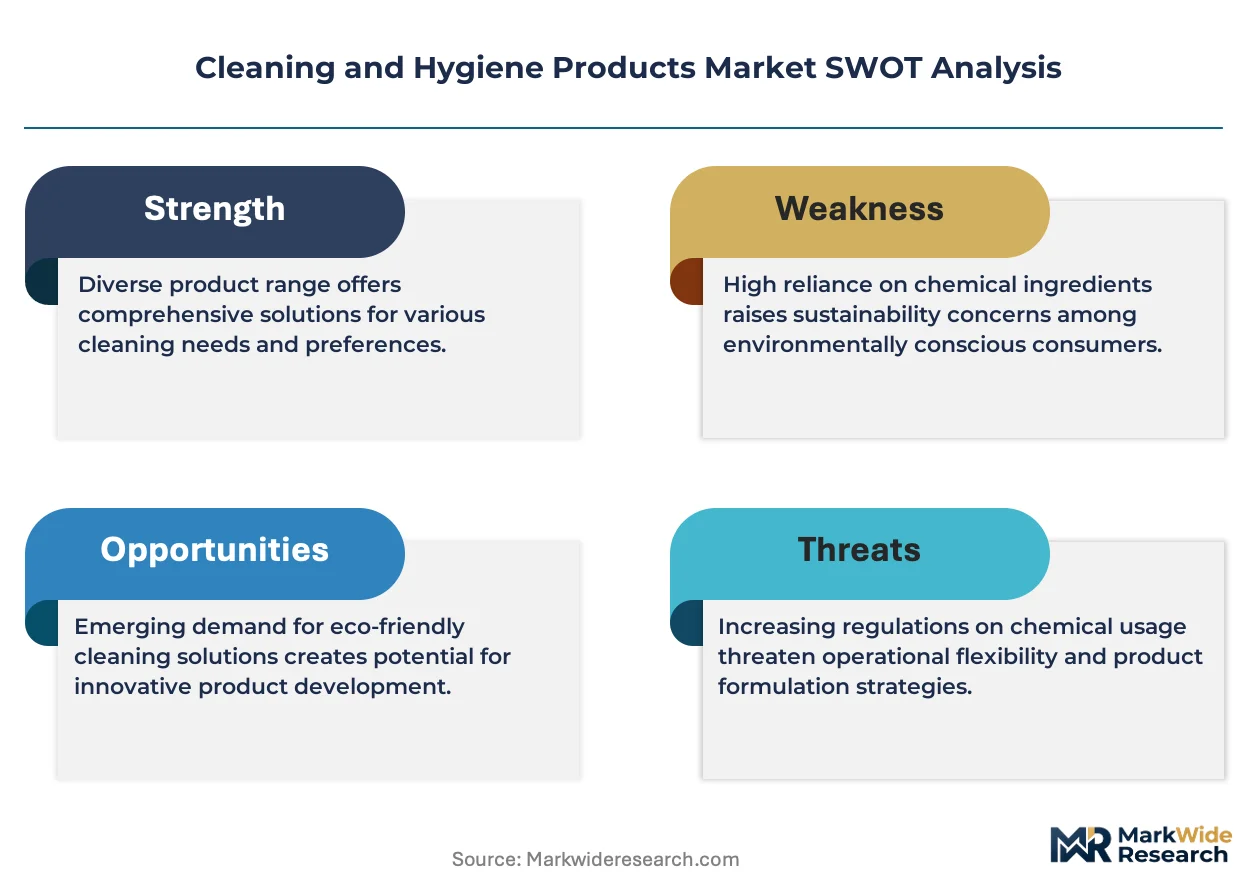
EPA Safer Choice certification is redrawing competitive boundaries for surface cleaner suppliers seeking institutional contracts. Procter & Gamble leverages its scale to secure shelf dominance across retail channels in North America. Unilever sustains growth through concentrated formats that reduce plastic intensity and shipping costs. Ecolab dominates the commercial and industrial segments with service-integrated dispensing systems that lock in recurring revenue.
Cleaning and hygiene products encompass formulated chemical solutions, emulsions, and ready-to-use preparations designed to remove soil, destroy pathogens, or maintain sanitary conditions on surfaces, skin, and equipment, typically containing active ingredients such as quaternary ammonium compounds, hydrogen peroxide, or plant-derived surfactants at specified concentrations for efficacy against target microorganisms. These products serve essential functions in preventing disease transmission, complying with health codes, and preserving asset longevity across residential, commercial, and industrial environments. The application dimension shows institutional buyers in healthcare and food service driving premiumization as they prioritize validated kill-claims and audit-ready documentation, while household demand gravitates toward multi-surface sprays and convenient wipe formats that trade raw efficacy for ease of use. Product type segmentation reveals disinfectants capturing disproportionate margin pools as pandemic-era hygiene awareness persists, though surface cleaners maintain larger volume throughput across less regulated settings.
The EPA regulates antimicrobial claims through FIFRA registration requirements that mandate substantiated efficacy data before products can legally advertise pathogen-specific performance. OSHA's bloodborne pathogen standards and the FDA's food code provisions compel end users in healthcare and food service to specify validated cleaning protocols, creating downstream demand for compliant product lines. REACH restrictions in Europe and state-level disclosure laws such as California's Cleaning Product Right to Know Act are forcing reformulation investments that favor suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor how fragmented chemical disclosure requirements across multiple jurisdictions will reshape sourcing strategies and whether biobased active ingredients can achieve cost parity with petrochemical alternatives at commercial scale.
Market Dynamics
Hospital-grade disinfectant procurement is consolidating around EPA Safer Choice-certified suppliers as infection-control mandates tighten across healthcare systems, forcing smaller formulators to absorb compliance costs or exit institutional channels entirely.
Growth Catalysts
- EPA FIFRA Registration Requirements:Healthcare facilities now mandate validated kill-claims documentation, creating captive demand for registered antimicrobial formulations that smaller competitors cannot legally supply.
- Concentrated Format Chemistry:Water-reduced concentrates slash plastic intensity and freight costs, allowing suppliers to capture margin expansion while meeting corporate sustainability targets.
- Food Service Audit Protocols:FDA food code compliance requirements are compelling restaurant chains to specify documented cleaning protocols, driving recurring revenue through protocol-integrated dispensing systems.
Market Restraints
- Quaternary Ammonium Compound Feedstock Volatility:Petrochemical-derived active ingredient costs fluctuate with crude oil benchmarks, compressing margins for mid-tier formulators lacking long-term supply contracts.
- Regulatory Fragmentation:California's Cleaning Product Right to Know Act and REACH disclosure requirements in Europe impose divergent labeling mandates, forcing redundant reformulation runs for multi-jurisdiction suppliers.
- Biobased Active Cost Parity Gap:Plant-derived surfactants and hydrogen peroxide alternatives remain 15-40% above petrochemical equivalents at commercial scale, limiting mass-market penetration.
Strategic Opportunities
- Service-Integrated Dispensing Hardware:IoT-enabled dilution control systems lock in recurring chemical revenue while generating usage data that suppliers leverage for contract renewal negotiations.
- Green Chemistry Certification Tailwinds:EPA Safer Choice and EU Ecolabel preferences are opening procurement doors at institutional buyers with explicit sustainable sourcing mandates.
- Multi-Surface Wipe Format Expansion:Convenience-oriented household segments show willingness to trade raw efficacy for ease-of-use formats, creating white space beyond traditional spray-and-wipe applications.
Industry Challenges
- Regulatory Affairs Talent Scarcity:FIFRA registration and state-level disclosure compliance require specialized expertise that smaller formulators struggle to recruit and retain.
- Legacy Equipment Compatibility:New concentrated and biobased formulations often degrade existing dispensing infrastructure, forcing costly retrofitting or customer education cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleaning and Hygiene Products Market |
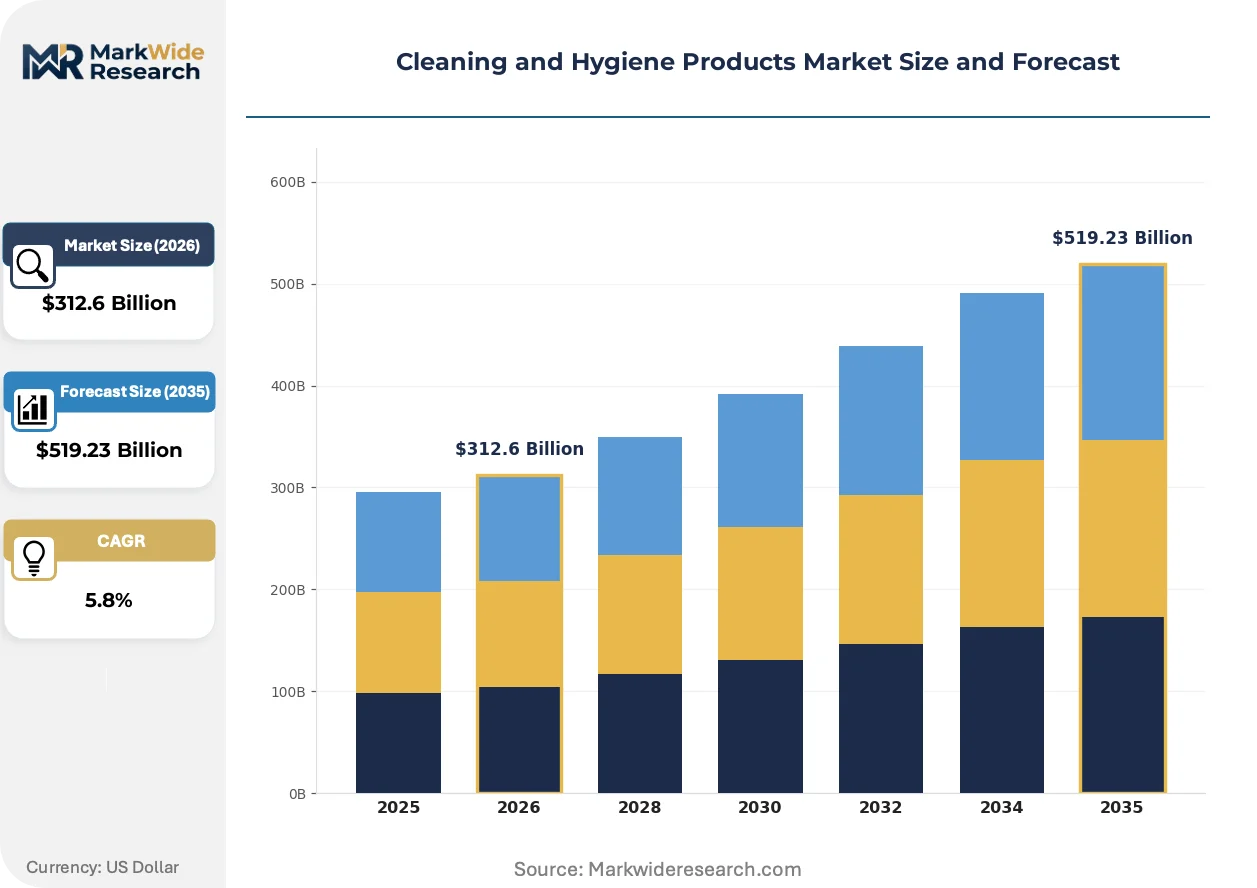
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Disinfectants, Hand Sanitizers, Bathroom Cleaners Application: Household, Commercial, Industrial, Institutional Form: Liquid, Spray, Wipe, Powder End User: Retail, Healthcare, Food Service, Hospitality |
| Companies Covered | Procter & Gamble, Unilever, Henkel, Reckitt Benckiser, The Clorox Company, Ecolab, Colgate-Palmolive Company, Diversey Holdings Ltd., Alfred Kärcher SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleaning and Hygiene Products Market Evolving Landscape
Formulation chemistry and delivery mechanisms are converging around sustainability verification and connected hardware, reshaping how suppliers capture value beyond commodity chemical sales.
Electrochemical activation systems generate hypochlorous acid and other sanitizers on-site from salt water and electricity, eliminating transportation of hazardous concentrates. Large food processors and hospital systems are piloting these units to reduce storage liability and supply chain exposure. This distributed generation model is supplanting traditional bulk chemical delivery contracts in facilities with predictable high-volume demand.
REACH authorization restrictions on persistent organic pollutants and endocrine-disrupting compounds are forcing reformulation of legacy disinfectant actives. European suppliers face compressed timelines to substitute quaternary ammonium alternatives that maintain efficacy against enveloped viruses. The industrial and institutional segment bears the heaviest compliance burden, with many buyers accelerating vendor consolidation around established regulatory affairs capabilities.
Consolidated procurement through group purchasing organizations now dominates hospital and long-term care facility buying, compressing supplier margins while demanding extended payment terms and audit-ready documentation. Direct sales relationships with environmental services directors are yielding to contract negotiations with centralized supply chain offices. This concentration is most pronounced in the United States, where health system mergers have reduced the number of independent purchasing decision-makers by over half since 2010.
Cleaning and Hygiene Products Market Segmentation
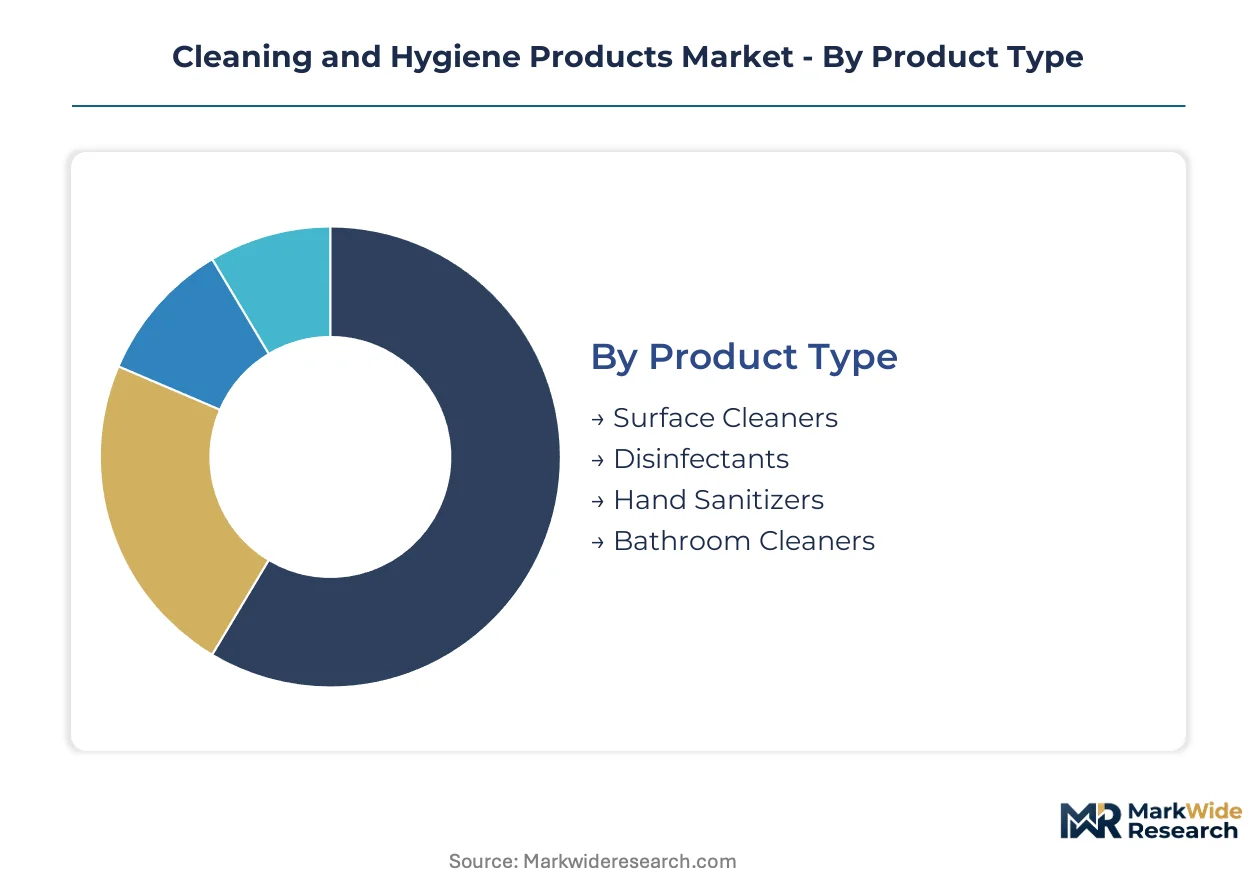
Segmentation in cleaning and hygiene products determines formulation priorities, regulatory pathways, and channel economics. Product chemistry and application context dictate whether suppliers pursue EPA FIFRA registration or fast-moving consumer goods distribution strategies.
Product Type:
Geographic concentration varies sharply across product types, with hospital-grade disinfectants dominated by domestic EPA-registered suppliers while surface cleaners flow through global retail networks.
- Surface Cleaners:Formulated emulsions and surfactant-based solutions designed for soil removal without antimicrobial claims. Household demand in the United States concentrates in multi-surface spray formats, though concentrated refills are gaining shelf space at mass retailers pursuing plastic reduction targets.
- Disinfectants:EPA-registered formulations containing quaternary ammonium compounds, hydrogen peroxide, or sodium hypochlorite at specified concentrations for validated pathogen kill. Healthcare procurement in the United States is consolidating around Safer Choice-certified suppliers as infection-control mandates tighten across hospital systems.
- Hand Sanitizers:Alcohol-based or benzalkonium chloride formulations for skin antisepsis, regulated by FDA as over-the-counter drugs.
- Bathroom Cleaners:Acidic or bleach-based formulations targeting soap scum, hard water deposits, and mold in high-moisture environments.
Surface cleaners hold the largest share; momentum sits with disinfectants as pandemic-era hygiene awareness persists in institutional channels.
Application:
Cost tier differentiation separates premium validated formulations for regulated environments from commodity chemistry in price-sensitive segments.
- Household:Consumer-facing products sold through retail channels, where convenience formats and fragrance profiles drive purchase decisions over raw efficacy specifications.
- Commercial:Office buildings, retail spaces, and facility management contracts demanding documented cleaning protocols and bulk dispensing economics.
- Industrial:Heavy-duty formulations for manufacturing equipment, food processing machinery, and asset preservation in high-soil environments.
- Institutional:Healthcare, education, and government facilities requiring audit-ready documentation, validated kill-claims, and compliance with OSHA bloodborne pathogen standards.
Commercial applications dominate volume throughput; institutional segments command the steepest expansion trajectory as regulatory compliance requirements deepen.
Form:
Customer type shapes form factor preference, with institutional buyers favoring concentrated liquids for dilution control while households gravitate toward single-use convenience.
- Liquid:Bulk concentrates and ready-to-use solutions enabling precise dilution control in commercial dispensing systems. Food service chains in the United States are standardizing on closed-loop dilution hardware to reduce chemical waste and ensure compliance consistency across locations.
- Spray:Aerosol and trigger-spray formats dominating household and light commercial applications where immediate application without dilution steps matters.
- Wipe:Pre-saturated substrates in canister or flow-pack formats, capturing premium pricing in healthcare and hospitality for point-of-use convenience.
- Powder:Dry concentrates for industrial carpet cleaning, warewashing, and applications where water weight in shipping creates cost disadvantages.
Liquid forms retain the largest installed base; wipes are climbing the fastest as healthcare and hospitality segments prioritize infection control workflow efficiency.
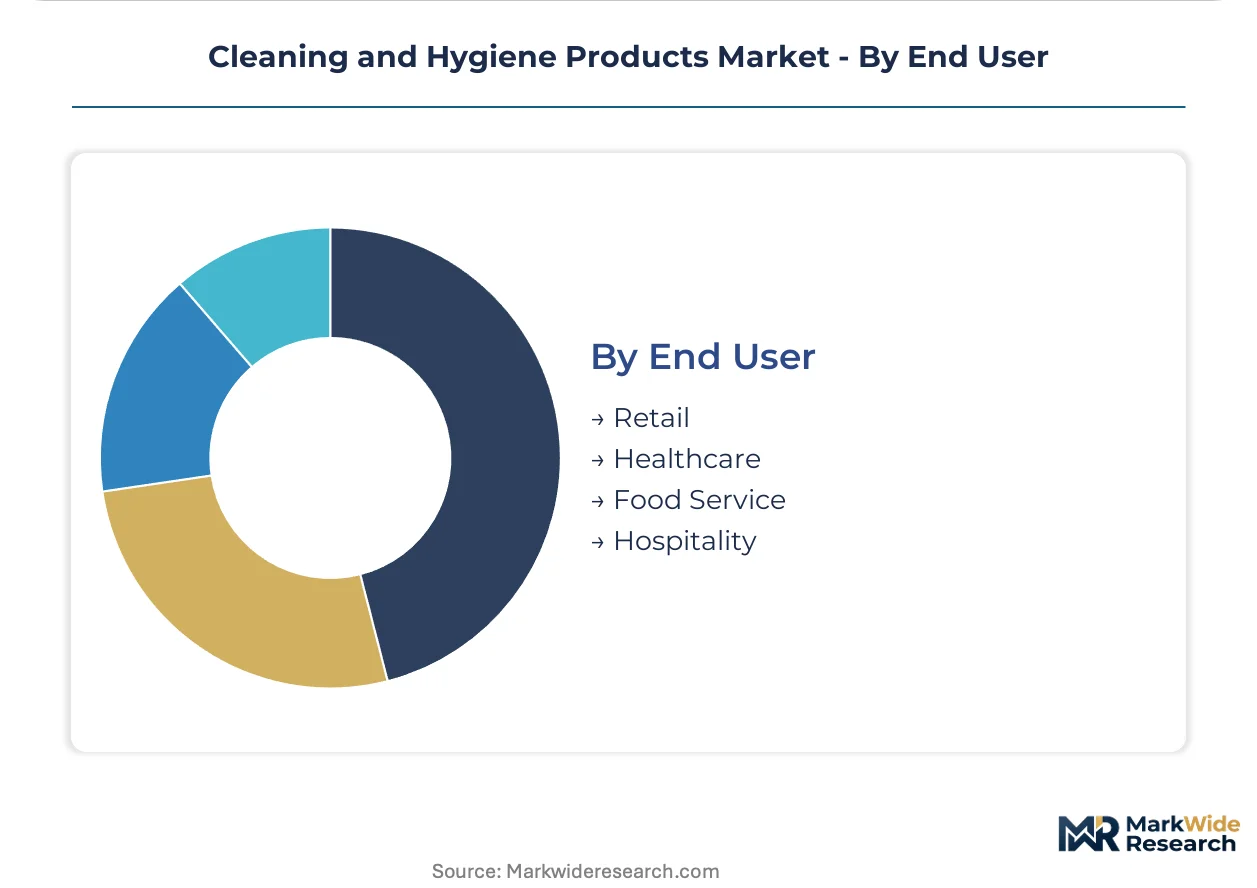
End User:
Supply concentration in retail channel control separates mass-market penetration from specialized institutional distribution.
- Retail:Supermarkets, mass merchants, and e-commerce platforms where shelf placement fees and promotional spending determine visibility. United States retail consolidation around Walmart, Target, and Amazon has compressed supplier margins while demanding exclusive formulations and packaging sizes.
- Healthcare:Hospitals, long-term care facilities, and outpatient clinics requiring EPA-registered disinfectants with documented efficacy against healthcare-associated pathogens. Group purchasing organizations now dominate procurement, reducing direct supplier relationships with environmental services directors.
- Food Service:Restaurant chains and food processing facilities governed by FDA food code compliance requirements.
- Hospitality:Hotels, cruise lines, and event venues balancing guest-facing aesthetics with back-of-house sanitation protocols.
Retail channels generate the highest unit volumes; healthcare represents the most concentrated profit pool as compliance barriers limit competitive entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safer Choice certification is redrawing procurement criteria for institutional buyers across multiple jurisdictions. Healthcare systems in developed economies are consolidating vendor relationships around verified sustainable supply chains. Formulation requirements are diverging as regional regulators impose distinct chemical disclosure mandates.
United States
Hospital-grade disinfectant procurement is concentrating around EPA-registered suppliers as infection-control mandates tighten across healthcare systems. California's Cleaning Product Right to Know Act imposes disclosure requirements that exceed federal standards. The Midwest manufacturing corridor hosts concentrated production of quaternary ammonium compounds for institutional channels.
Germany
REACH authorization restrictions are forcing reformulation of legacy disinfectant actives across industrial and institutional segments. ECHA's evolving standards on endocrine-disrupting compounds compress timelines for substituting quaternary ammonium alternatives. The Rhine-Ruhr industrial cluster anchors European production of hydrogen peroxide-based formulations.
China
Food processing facilities are expanding adoption of electrochemical activation systems to reduce storage liability and supply chain exposure. SAMR's national standards for disinfectant efficacy are converging with international benchmarks. The Yangtze River Delta hosts pilot deployments of on-site hypochlorous acid generation for large-scale sanitation operations.
Japan
Commercial facility managers are standardizing on closed-loop dilution hardware to ensure compliance consistency across location portfolios. METI's guidance on green procurement is influencing corporate sustainability targets for cleaning chemical sourcing. The Kanto region around Tokyo concentrates demand for IoT-enabled dispensing systems in hospitality and healthcare.
Brazil
Food service chains are accelerating vendor consolidation around suppliers with documented regulatory affairs capabilities. ANVISA's antimicrobial registration requirements create compliance barriers for imported formulations. São Paulo's industrial belt hosts growing production of concentrated surface cleaners for Latin American distribution.
Cleaning and Hygiene Products Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and service integration depth. The market structure tiers around scale-driven multinationals, regional formulators with niche certifications, and hardware-integrated service providers. Three archetypes dominate: retail shelf-space controllers, institutional protocol integrators, and electrochemical system pioneers. Competitive moves concentrate on M&A for regulatory expertise and strategic partnerships for dispensing hardware deployment.
Within the scale-driven tier, Procter & Gamble and Unilever occupy positions reflecting retail channel dominance across North American and European mass markets. Ecolab exemplifies the service-integrated archetype through its commercial and industrial segment focus. These three entities anchor competitive dynamics by representing distinct pathways to value capture: consumer packaged goods velocity, institutional recurring revenue lock-in, and sustainability-certified procurement access.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel |
| Reckitt Benckiser |
| The Clorox Company |
| Ecolab |
| Colgate-Palmolive Company |
| Diversey Holdings Ltd. |
| Alfred Kärcher SE & Co. KG |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day raw material lead times for quaternary ammonium compound feedstocks concentrate pricing power with integrated petrochemical producers in the United States and Germany, while smaller formulators absorb margin compression from crude oil benchmark volatility. This inventory exposure forces mid-tier suppliers toward long-term offtake contracts or exit from institutional channels entirely.
Pricing Analysis
Certification level creates the primary spread between EPA Safer Choice-certified institutional formulations and commodity surface cleaners lacking validated kill-claims. Three-tier pricing structure separates premium hospital-grade disinfectants from standard commercial concentrates and economy household sprays, with brand premium and volume scale as secondary differentiators. Pricing pressure stems from group purchasing organization consolidation in United States healthcare systems. Household retail segments exhibit highest price sensitivity; institutional buyers with compliance mandates show lowest.
Supply Chain Analysis
The United States anchors production of quaternary ammonium compounds for institutional disinfectants, while Germany's Rhine-Ruhr cluster specializes in hydrogen peroxide-based formulations and China dominates surfactant intermediate manufacturing. Supply chains draw from petrochemical feedstocks, specialized active ingredient synthesis, and blow-molded packaging components. Single-source vulnerability concentrates in quaternary ammonium compound supply where three domestic producers control majority share. Distribution runs through institutional group purchasing organizations, mass retail chains, and direct service-integrated dispensing hardware deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare capital expenditure cycles and infection-control mandate tightening position this market for cyclical recovery as deferred facility upgrades accelerate procurement of validated formulations.
For Market Incumbents: Fortify regulatory affairs capabilities to defend EPA FIFRA registration moats against emerging biobased formulators seeking Safer Choice certification. Deepen backward integration into quaternary ammonium compound production to offset petrochemical feedstock volatility. Prioritize IoT-enabled dispensing hardware deployment to lock in recurring chemical revenue and generate usage data for contract renewal leverage. For New Entrants and Emerging Players: Service-layer gaps in small-to-mid-sized food service chains lacking documented FDA food code compliance protocols present immediate white-space opportunity. Target Latin American markets where ANVISA registration requirements create compliance barriers for unestablished suppliers. Pursue electrochemical activation system partnerships to bypass traditional chemical distribution entirely and capture facility-level sanitation contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial chemical divisions lacking dedicated regulatory affairs infrastructure for institutional healthcare channels. Long-term viability favors suppliers with verified sustainable supply chains as procurement mandates harden across developed economies. Watch EPA Safer Choice program expansion into additional product categories as inflection signal for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Production | Captive quaternary ammonium compound supply insulates margins from crude oil benchmark swings. |
| EPA Safer Choice Certification Investment | Verified sustainable formulation unlocks group purchasing organization procurement doors at United States health systems. |
| IoT-Enabled Dispensing Hardware Deployment | Connected dilution control systems generate usage data that strengthens contract renewal negotiations. |
| Electrochemical Activation System Partnership | On-site hypochlorous acid generation eliminates transportation liability for large food processors. |
| Concentrated Format Chemistry Expansion | Water-reduced formulations reduce plastic intensity while meeting corporate sustainability targets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs directors, environmental services managers at hospital systems, food service procurement leads, and chemical distribution channel partners; and secondary validation through EPA FIFRA registration databases, FDA food code compliance records, customs trade data on surfactant imports, and SEC 10-K filings from listed chemical suppliers. Bottom-up product-level volume estimates triangulated against top-down category spending data from institutional procurement databases.
Across the analysis window, the forecasting framework modeled demand trajectories by product chemistry tier, application context, form factor, and end-user channel, with regional regulatory cluster as an additional segmentation dimension. CAGRs derived from regression analysis of historical procurement patterns against infection-control mandate intensity and sustainability certification adoption curves. Industry-specific inputs included hospital bed capacity expansion plans and food service chain location growth targets.
Underlying assumptions cover sustained enforcement of EPA FIFRA registration requirements and REACH authorization timelines in Europe, with deviation risk concentrated in biobased active ingredient cost parity achievement and electrochemical activation system commercialization pace. Recalibration cycles align with material shifts in healthcare infection-control mandates and green chemistry certification program expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Car Wash Detergents and Soaps Market
Cleaning Equipment
Laundry Sanitizer Market
Cleaning Equipment
Carpet Steamers Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Vacuum Cleaner Filter Market
Cleaning Equipment
Cleaning Appliance Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market
Cleaning Equipment
Dishwashing Detergent Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Commercial Vacuum Cleaners Market
Cleaning Equipment
Brush Cleaner Market
Cleaning Equipment
Fabric Freshener Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
US Cleaning Products Market